
 Asia-Pacific Liner Hanger System Market | 2026-2036
Asia-Pacific Liner Hanger System Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Liner Hanger System Market Outlook
Maintenance and aftermarket service contracts is consolidating as the primary revenue layer in Asia-Pacific liner hanger system sales, shifting capital expenditure models toward lifecycle-based agreements. Halliburton Company leverages its regional service infrastructure to anchor long-term contracts across Indonesian deepwater fields. Baker Hughes Company competes through differentiated metallurgical testing protocols that extend equipment duty cycles in corrosive environments. Schlumberger Limited dominates digital diagnostics integration, positioning remote monitoring as a bundled service feature.
A liner hanger system is a mechanical or hydraulic downhole tool that suspends casing or liner strings within a wellbore, typically rated for pressure thresholds exceeding 10,000 psi and temperatures above 150°C, designed to isolate formations and enable zonal isolation during completion and production operations. Mechanical systems retain the largest installed base across mature onshore basins in India and Thailand, though hydraulic variants capture expanding margin pools in subsea installations where remote setting capability eliminates intervention costs. The offshore installation category outpaces onshore growth as frontier drilling moves into the South China Sea and Bay of Bengal, while exploration companies as an end-user segment concentrate procurement through integrated drilling contracts that bundle hanger systems with directional services.
China's MIIT enforces GB standards for downhole equipment metallurgy, compelling manufacturers to certify creep-resistant alloys for high-pressure high-temperature wells. Australia's NOPSEMA and Malaysia's PETRONAS technical standards jointly shape regional product specifications for offshore safety-critical components. Japan's METI guidelines on methane emissions monitoring further tighten equipment sealing requirements. Stakeholders must monitor how divergent national certification regimes affect cross-border equipment mobility and service deployment economics.
Market Dynamics
Deepwater exploration in Southeast Asia is compressing intervention windows and forcing liner hanger systems toward remote-actuation architectures that eliminate rig-time exposure. Operators now bundle hanger procurement with integrated drilling contracts, reshaping vendor economics toward lifecycle service accountability rather than discrete equipment sales.
Growth Catalysts
- MIIT Metallurgical Mandates:China's GB standards for creep-resistant alloys are accelerating alloy certification programs across domestic manufacturing bases, pulling investment into high-temperature capable hanger systems.
- Bay of Bengal Deepwater Activity:Frontier drilling campaigns off Myanmar and Bangladesh are creating pull-through demand for hydraulic setting mechanisms rated beyond 15,000 psi.
- PETRONAS Technical Standards:Malaysia's offshore safety specifications for subsea components are standardizing regional procurement specifications, reducing vendor qualification friction across Southeast Asian tender processes.
Market Restraints
- Nickel Alloy Input Volatility:Superalloy price swings for Inconel and Incoloy grades are compressing fabrication margins on HPHT-rated hanger assemblies.
- Subsea Component Supply Concentration:Specialized forging capacity for high-pressure housings clusters in Japan and South Korea, creating single-source vulnerability for regional project timelines.
- Mechanical System Obsolescence Risk:Mature onshore basins in India retain substantial installed bases of slip-and-cone mechanical hangers that face replacement inertia against hydraulic alternatives.
Strategic Opportunities
- Vietnam Unexplored Shelf:The Cuu Long and Nam Con Son basins remain underpenetrated by premium subsea hanger technology, offering first-mover positioning as licensing rounds accelerate.
- Remote Monitoring Convergence:Integration of fiber-optic pressure sensing with hanger sealing elements is opening predictive maintenance service contracts as a recurring revenue layer.
- Australia NOPSEMA Digital Submission Pathways:Streamlined electronic certification processes for well barrier equipment are compressing vendor approval timelines and lowering market entry barriers for qualified suppliers.
Industry Challenges
- HPHT Systems Engineering Talent Scarcity:Finite pools of completion engineers capable of integrating 20,000 psi-rated hangers with intelligent wellhead systems are constraining project execution velocity.
- Cross-Border Certification Fragmentation:Divergent pressure-testing protocols between China's MIIT, Australia's NOPSEMA, and Malaysia's PETRONAS are forcing redundant validation cycles on identical equipment specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Liner Hanger System Market |
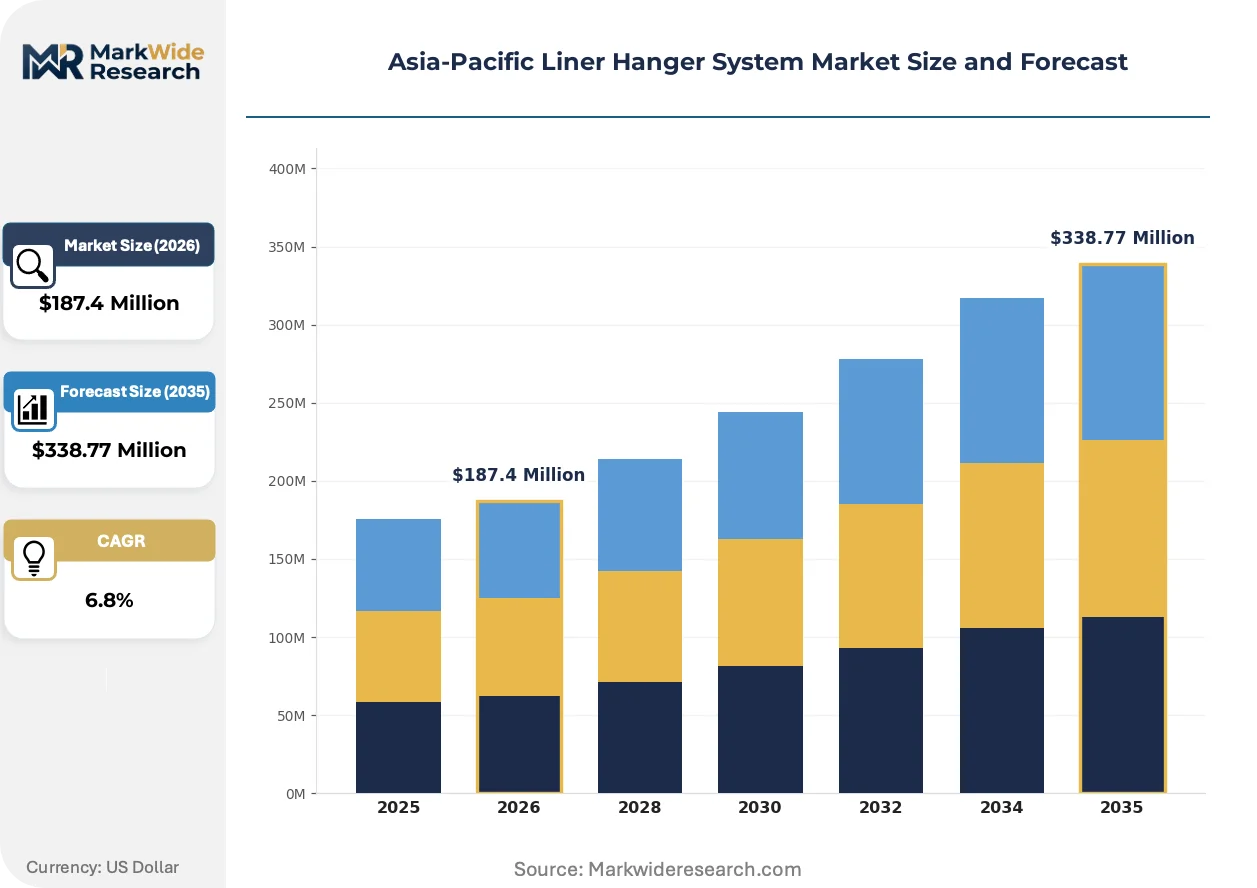
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mechanical, Hydraulic, Dual-Type, Adjustable Application: Oil & Gas, Water Wells, Geothermal, Mining Installation Type: Onshore, Offshore, Subsea, Surface End User: Exploration Companies, Drilling Contractors, Service Providers, Operators |
| Companies Covered | Weatherford International plc, Aker Solutions ASA, Halliburton Company, ONGC, China Oilfield Services Limited, Schlumberger Limited, NOV Inc., TAQA Group, Baker Hughes Company, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Liner Hanger System Market Strategic Shifts
Digital integration is collapsing the traditional separation between downhole hardware and surface diagnostics, creating new competitive battlegrounds around data ownership and predictive analytics capabilities. Vendors now compete on telemetry integration depth rather than pressure rating alone.
Modular hanger architectures with field-reconfigurable sealing elements are decentralizing inventory deployment across Asia-Pacific. Indonesian drilling contractors are adopting these systems to reduce offshore logistics complexity. The shift is compressing working capital requirements and enabling faster response to emergent wellbore conditions without shore-base reconfiguration.
Australia's NOPSEMA has tightened well barrier integrity documentation requirements, mandating digital twin records for all subsea hanger installations. Operators must now submit real-time pressure test data through approved electronic platforms. The regulation is accelerating cloud-based compliance tool adoption among service companies active on the Northwest Shelf.
Integrated drilling contractors are consolidating procurement authority and unbundling after-sales service from original equipment manufacturers. National oil companies in Thailand and Indonesia now negotiate hanger supply through bundled drilling contracts that specify performance guarantees rather than component specifications. The model is visible most acutely in PETRONAS-managed deepwater campaigns where single-point accountability has displaced multi-vendor sourcing.
Asia-Pacific Liner Hanger System Market Segmentation
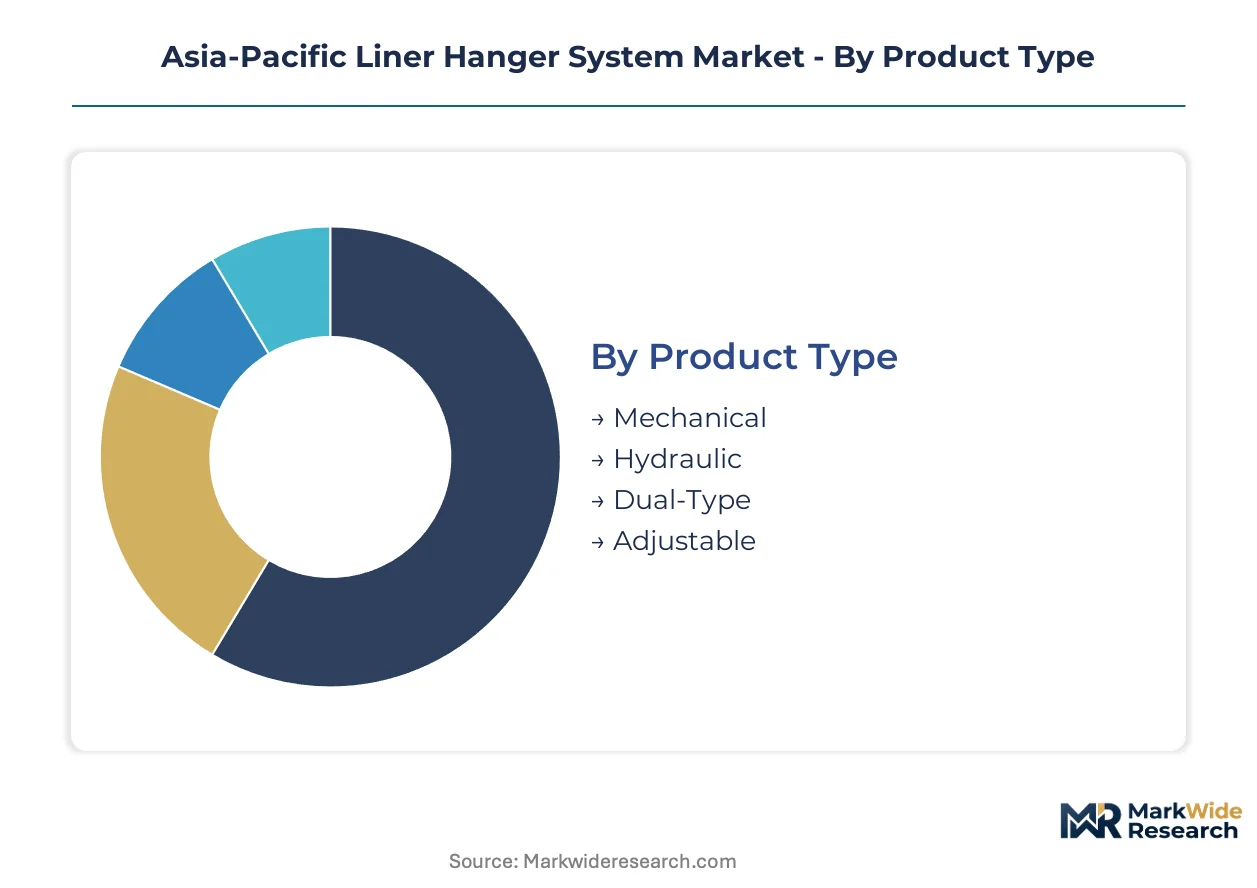
Segmentation in the Asia-Pacific liner hanger system market reveals how procurement authority, technical specifications, and installation environments fragment vendor economics. Understanding these divisions exposes where margin pools concentrate and where standardization pressures erode pricing power.
Product Type:
Supply concentration for high-pressure housings clusters around forging capacity in Japan and South Korea, creating chokepoints that favor vendors with captive metallurgy capabilities.
- Mechanical:Slip-and-cone assemblies using wedge mechanisms to anchor casing through axial load transfer. India's mature onshore basins retain substantial installed bases, though replacement inertia slows hydraulic conversion.
- Hydraulic:Pressure-actuated setting systems rated beyond 15,000 psi for remote deployment without pipe rotation. Southeast Asian deepwater fields in the South China Sea and Bay of Bengal drive specification escalation here.
- Dual-Type:Hybrid architectures combining mechanical backup with hydraulic primary activation.
- Adjustable:Field-reconfigurable sealing elements enabling diameter adaptation without inventory duplication.
Today's leader: Mechanical. Tomorrow's challenger: Hydraulic.
Application:
Cost tier differentiation separates premium HPHT-rated systems from standard onshore equipment, with certification grade determining pricing bands more than raw material content.
- Oil & Gas:Conventional and unconventional hydrocarbon extraction requiring zonal isolation above 150°C and 10,000 psi. Australia's Northwest Shelf projects and Indonesia's deepwater campaigns concentrate procurement volume.
- Geothermal:High-temperature deployment exceeding 200°C in volcanic formations. Japan's Kyushu installations and Philippines' Leyte fields pull specialized alloy specifications.
- Water Wells:Municipal and agricultural groundwater extraction with lower pressure thresholds.
- Mining:Dewatering and ventilation shaft applications in coal and mineral operations.
Upstream hydrocarbon extraction commands pricing premiums; geothermal applications are climbing the fastest as energy transition capital reallocates.
Installation Type:
Volume concentration favors onshore deployment, though margin accretion follows subsea complexity where intervention costs amplify equipment value.
- Offshore:Platform-deployed systems in 50-500 meter water depths. Malaysia's PETRONAS technical standards shape regional specifications, compressing vendor qualification cycles.
- Subsea:Seabed-installed hangers with remote actuation eliminating riser intervention. Myanmar and Bangladesh frontier drilling creates specification pull-through for 20,000 psi-rated assemblies.
- Onshore:Conventional land-based deployment across established sedimentary basins.
- Surface:Wellhead-integrated hangers for conductor casing suspension.
Offshore installations anchor current revenue; subsea systems are gaining share fastest as exploration depth records advance.
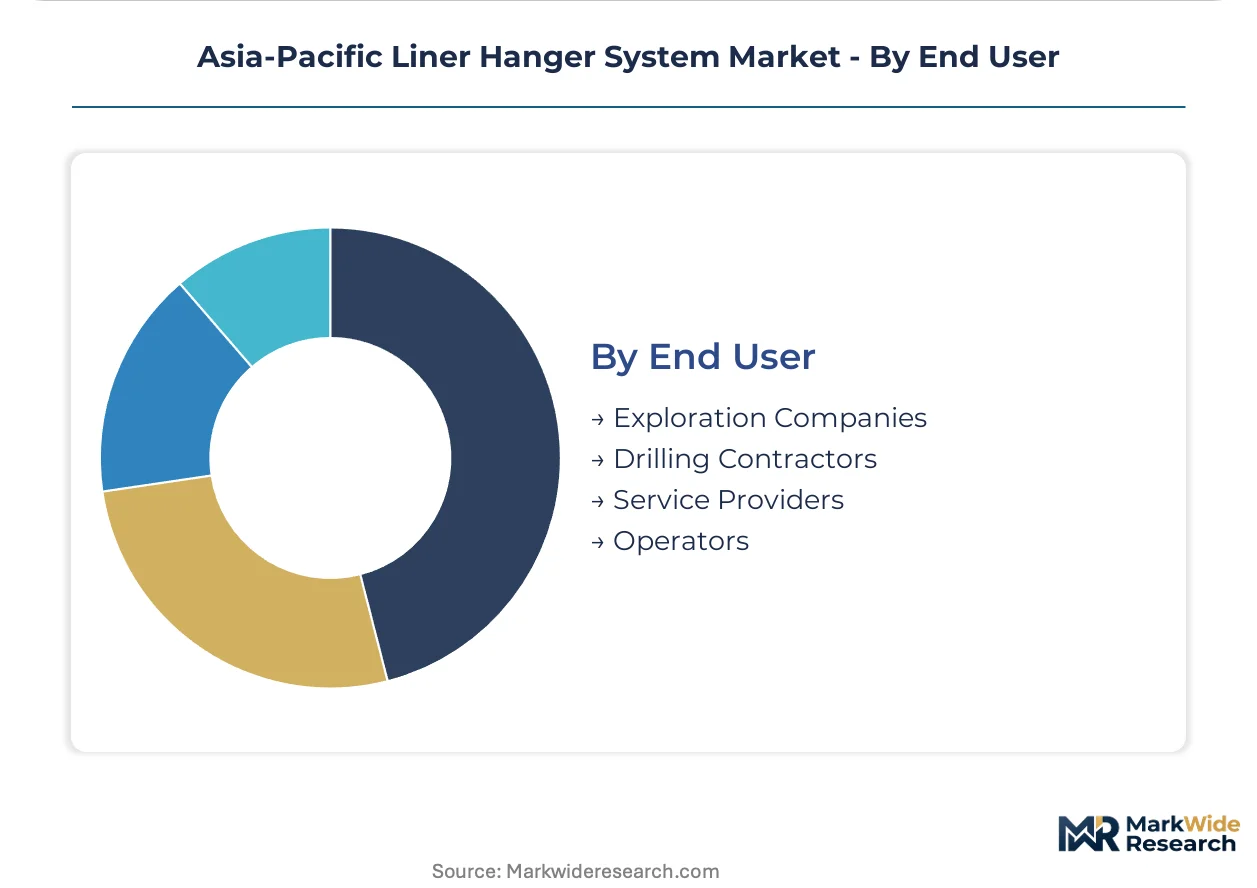
End User:
Customer type fragmentation shows integrated drilling contractors consolidating procurement authority while national oil companies unbundle after-sales service from original equipment supply.
- Exploration Companies:Independent operators licensing frontier blocks. They concentrate procurement through bundled drilling contracts specifying performance guarantees rather than component specifications.
- Drilling Contractors:Integrated service providers managing rig operations. Indonesian contractors adopt modular hanger architectures to reduce offshore logistics complexity and working capital requirements.
- Service Providers:Specialized completion and intervention companies.
- Operators:Asset-owning production companies with lifecycle accountability.
Drilling contractors currently dominate procurement volume; exploration companies are expanding most quickly as licensing rounds accelerate across Vietnam's unexplored shelf.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China commands the largest procurement volume for liner hanger systems in Asia-Pacific, while Australia's project specifications set the premium-tier technical bar that regional vendors must meet to compete in deepwater segments.
China
Domestic drilling contractors drive demand through unconventional gas campaigns in Sichuan and shale basins in Xinjiang. MIIT enforces GB standards for creep-resistant alloys that compel manufacturers to certify high-temperature capable hanger systems. Manufacturing clusters in Shandong and Jiangsu provinces house forging capacity that supplies pressure housings across Southeast Asian projects.
Australia
Northwest Shelf developments anchor regional demand for subsea-rated hydraulic systems rated beyond 15,000 psi. NOPSEMA mandates digital twin documentation for all well barrier equipment installations, accelerating cloud-based compliance adoption. Perth serves as the procurement coordination hub for integrated drilling contracts spanning the Timor Sea and Browse Basin.
Indonesia
Deepwater exploration in the South China Sea and Makassar Strait creates specification pull-through for remote-actuation architectures. PETRONAS technical standards shape vendor qualification cycles for contractors operating across shared maritime boundaries. Batam Island hosts service infrastructure that supports hanger deployment logistics for campaigns off East Kalimantan.
Malaysia
PETRONAS-managed deepwater campaigns concentrate procurement through single-point accountability contracts that displace multi-vendor sourcing. The national oil company's technical standards for subsea safety-critical components standardize regional tender specifications. Port Klang functions as the primary logistics node for hanger system staging across Southeast Asian offshore installations.
Vietnam
The Cuu Long and Nam Con Son basins remain underpenetrated by premium subsea hanger technology as licensing rounds accelerate. Domestic regulators align equipment certification requirements with ASEAN harmonization protocols to reduce cross-border friction. Ho Chi Minh City anchors the commercial infrastructure for exploration companies licensing frontier blocks in the Mekong Delta offshore.
Asia-Pacific Liner Hanger System Market Competitive Environment
Top-tier vendors anchor premium subsea and HPHT segments, while mid-tier fabricators compete on mechanical system replacements and onshore standard-pressure applications. The vendor base stratifies across three archetypes: integrated oilfield service conglomerates with captive metallurgy capabilities, specialized completion tool manufacturers with modular product architectures, and national oil company affiliates with domestic market preference. Consolidation pressure operates through integrated drilling contract bundling and lifecycle service accountability models that disadvantage pure equipment sellers.
Among integrated service providers, Halliburton Company and Schlumberger Limited exemplify the premium-tier archetype through bundled offerings that combine hanger supply with directional drilling and digital diagnostics. Baker Hughes Company occupies a parallel position emphasizing metallurgical testing differentiation for corrosive environment duty cycles. Weatherford International plc represents the specialized manufacturer vector with modular architectures that reduce offshore logistics complexity for Indonesian drilling contractors. These three anchors demonstrate how competitive positioning now depends on service integration depth rather than pressure rating specifications alone.
| Leading Market Players |
|---|
| Weatherford International plc |
| Aker Solutions ASA |
| Halliburton Company |
| ONGC |
| China Oilfield Services Limited |
| Schlumberger Limited |
| NOV Inc. |
| TAQA Group |
| Baker Hughes Company |
| Others |
Value Chain & Pricing Dynamics
Completion engineer scarcity in Southeast Asia's deepwater hubs widens pricing spreads between premium hydraulic systems and standard mechanical alternatives, as labor-cost differentials between Singapore and Batam Island compress margins on mid-tier equipment.
Pricing Analysis
Capacity additions in China's Shandong forging corridor are reshaping price floors for high-pressure housings, forcing Japanese and South Korean suppliers to defend premium positioning through extended metallurgical testing protocols. Three-tier pricing structure across premium, standard, and economy levels separates HPHT-certified subsea assemblies from onshore mechanical systems, with certification grade outweighing raw material content as the primary differentiation driver. Pricing pressure stems from nickel alloy input volatility for Inconel grades, compressing fabrication margins on 20,000 psi-rated assemblies. National oil companies in Thailand and Indonesia exhibit highest price sensitivity through bundled drilling contract procurement, while Australia's Northwest Shelf operators prioritize performance guarantees over unit cost.
Supply Chain Analysis
Superalloy forging capacity rests on specialized producers in Japan and South Korea, with Chinese manufacturers in Jiangsu province expanding creep-resistant alloy certification programs under MIIT mandates. Critical inputs include Inconel 718 forgings, fiber-optic pressure sensors, and hydraulic activation modules. Single-source vulnerability concentrates in high-pressure housing production, where limited qualified forging capacity creates project timeline risk for Myanmar and Bangladesh frontier drilling. Distribution runs through integrated drilling contractors consolidating procurement authority, with Port Klang and Singapore anchoring logistics staging for Southeast Asian offshore campaigns.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
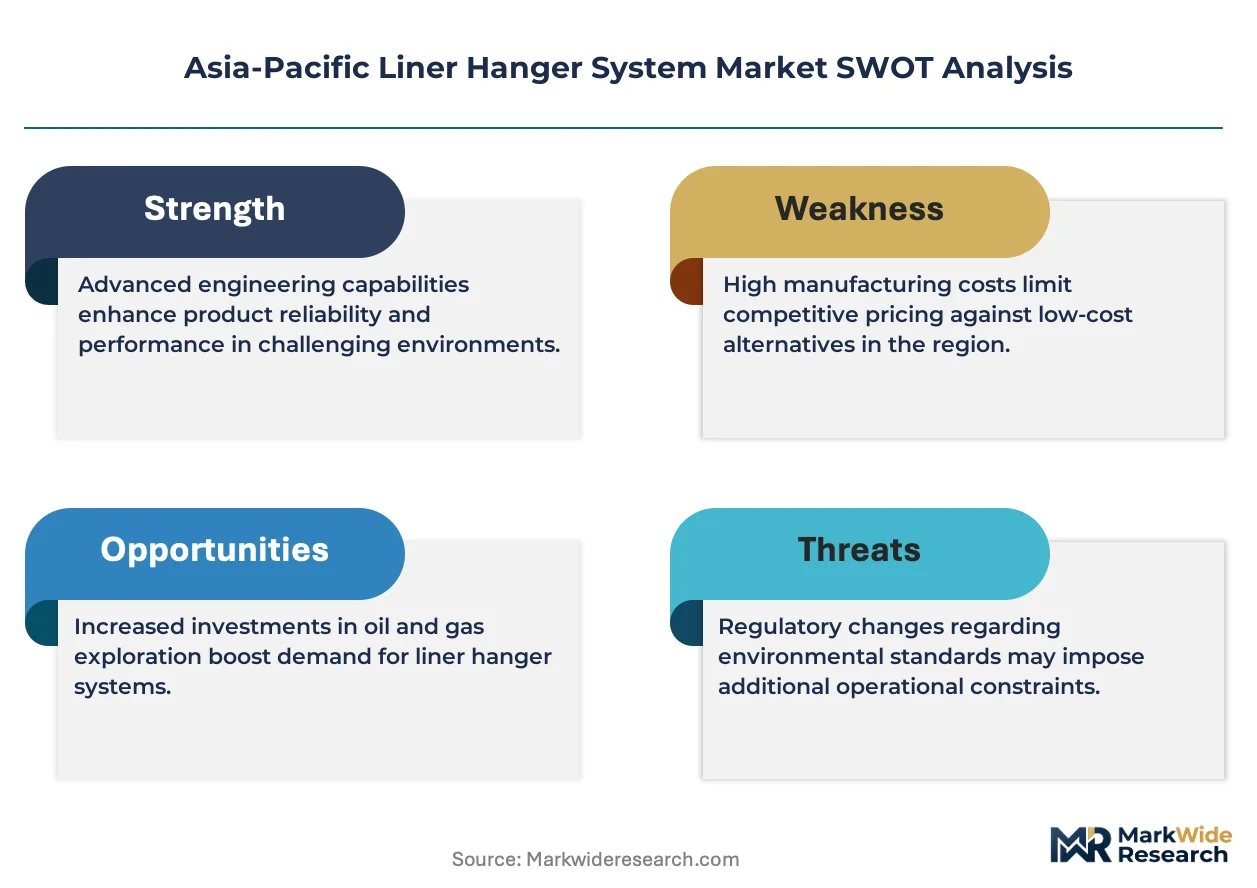
This market functions as a geographic-arbitrage play between Australia's premium-tier certification requirements and Vietnam's emerging licensing rounds, where regulatory alignment with ASEAN protocols reduces cross-border equipment mobility friction.
For Market Incumbents: Cement dominance in subsea HPHT segments by deepening captive metallurgy capabilities against Chinese forging expansion, while locking long-term service contracts with Indonesian drilling contractors adopting modular architectures. Halliburton's regional infrastructure and Schlumberger's digital diagnostics integration represent the consolidation benchmark threatening pure equipment vendors. For New Entrants and Emerging Players: Remote-actuation telemetry with fiber-optic pressure sensing offers entry into Vietnam's underpenetrated Cuu Long and Nam Con Son basins, where first-mover positioning in premium subsea technology precedes licensing round acceleration. Target exploration companies negotiating performance-guarantee contracts rather than component-specification tenders, leveraging Australia's streamlined NOPSEMA digital submission pathways to compress vendor approval timelines. For Investors and Strategic Acquirers: Integrated drilling contractors are the most active acquirer in this space, consolidating hanger supply with directional services to capture lifecycle accountability contracts displacing multi-vendor sourcing. Long-term viability hinges on predictive maintenance service revenue layers, with fiber-optic sensing integration and cloud-based compliance tools as the acquisition target archetype. Watch PETRONAS technical standard harmonization across ASEAN as the inflection signal for cross-border equipment mobility economics.| Strategic Initiative | Industry Significance |
|---|---|
| Metallurgical Certification Investment | MIIT GB standards for creep-resistant alloys compel domestic Chinese manufacturers to upgrade alloy testing protocols. |
| Remote Monitoring Platform Integration | NOPSEMA digital twin mandates for well barrier equipment accelerate cloud-based compliance tool adoption among service companies. |
| Modular Architecture Deployment | Indonesian drilling contractors adopt field-reconfigurable sealing elements to reduce offshore logistics complexity. |
| Lifecycle Service Contract Bundling | PETRONAS-managed deepwater campaigns consolidate procurement through single-point accountability displacing multi-vendor sourcing. |
| ASEAN Harmonization Alignment | Vietnam's domestic regulators align equipment certification with regional protocols to reduce cross-border qualification friction. |
Study Parameters
Direct dialogue with completion engineers at integrated drilling contractors, procurement leads at national oil companies, metallurgical testing directors at forging facilities, and aftermarket service heads at regional equipment depots grounded qualitative findings, validated against customs trade data for superalloy imports, MIIT certification registries, NOPSEMA well barrier documentation submissions, and PETRONAS tender specifications. Bottom-up equipment shipment tracking and top-down drilling contract value analysis provided triangulation across primary and secondary sources.
Segment-level projections across mechanical, hydraulic, dual-type, and adjustable product architectures, spanning offshore, subsea, onshore, and surface installation categories, calibrated against exploration company procurement patterns and drilling contractor fleet deployment schedules throughout the forecast period. CAGRs derived from equipment replacement cycles in mature basins and specification escalation curves in frontier deepwater fields, with nickel alloy price trajectories and regional certification timeline assumptions as key model inputs.
The model holds under stable ASEAN regulatory harmonization and continued deepwater exploration licensing; deviation in nickel superalloy supply disruption or cross-border certification fragmentation would shift equipment mobility economics and vendor margin structures. A small set of triggers—MIIT standard tightening, NOPSEMA digital submission pathway expansion, and PETRONAS technical standard regional adoption—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
North America Drilling Completion Fluids Market
Oil & Gas
Drilling Bits Market
Oil & Gas
Asia-Pacific Digital Oilfield Market
Oil & Gas
Downhole Tractor Market
Oil & Gas
Global Carbon Steel Tubing in Oil and Gas Lift Applications Market
Oil & Gas
Kazakhstan Oil and Gas Downstream Market
Oil & Gas
North America Artificial Lift Systems Market
Oil & Gas
Open Hole Logging Services Market
Oil & Gas
Wellhead Equipment Market
Oil & Gas
Africa Drilling and Completion Fluids Market
Oil & Gas
North America Oil Storage Market
Oil & Gas
Canada LNG Bunkering Market
Oil & Gas
Reservoir Analysis Market
Oil & Gas
Tricone Bits Market
Oil & Gas
Oil and Gas Data Management Market
Oil & Gas
Blowout Preventers (BOP) Market