
 Gulf of Mexico Oil and Gas Midstream Market | 2026-2036
Gulf of Mexico Oil and Gas Midstream Market Size, Share, and Industry Trends Forecast 2026-2036
Gulf of Mexico Oil and Gas Midstream Market Foresight
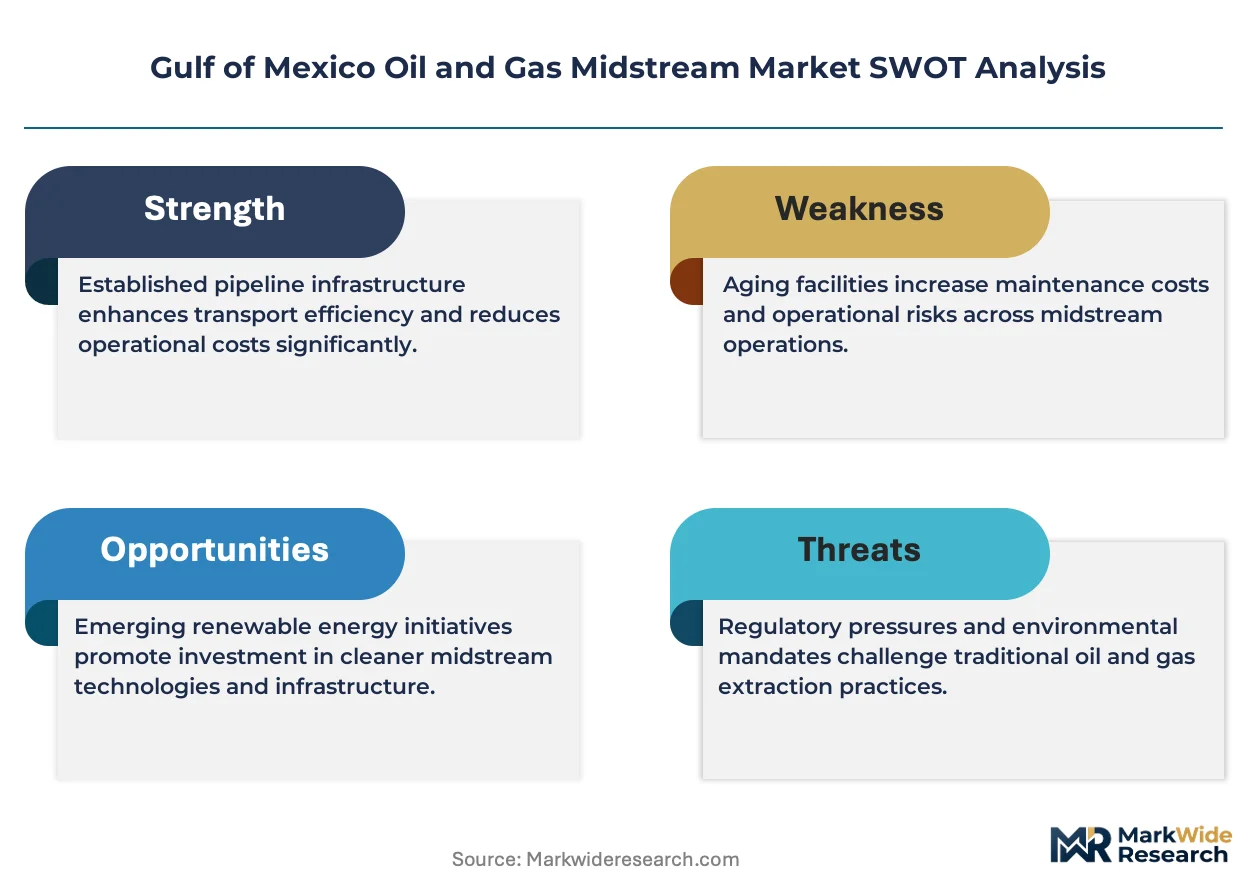
Deepwater pipeline operators in the Gulf of Mexico is pivoting toward higher-pressure steel designs for ultra-deepwater tiebacks. Williams Companies Inc leverages its Transco system to anchor natural gas gathering across the western Gulf. Chevron Corporation dominates deepwater trunkline routing from its Anchor and Mad Dog platform complexes. DCP Midstream LLC specializes in NGL fractionation and export terminal connectivity along the Texas Gulf Coast.
Gulf of Mexico oil and gas midstream encompasses the transportation, storage, processing, and distribution infrastructure bridging offshore production to onshore refining and export markets, operating at pressures exceeding 10,000 psi and depths surpassing 1,500 meters. Pipeline systems constitute the backbone infrastructure, with subsea flowlines and export lines commanding the largest capital deployment and longest project lead times. Processing services represent the fastest-expanding segment as associated gas handling and NGL extraction requirements intensify with deeper, more complex reservoir developments. Terminal and platform infrastructure maintains mature utilization profiles, though brownfield expansions at existing hub locations capture disproportionate margin pools due to lower permitting burdens.
The Pipeline and Hazardous Materials Safety Administration enforces construction and integrity management standards for interstate pipelines, while the Bureau of Safety and Environmental Oversight regulates offshore platform and subsea system integrity through mandatory third-party certification requirements. The Coast Guard oversees marine terminal security and vessel traffic management for LNG and crude export facilities. Stakeholders must monitor evolving decommissioning liability frameworks and methane intensity benchmarks as these regulatory dimensions increasingly determine project financing terms and insurance pricing.
Market Dynamics
Deepwater tieback economics are restructuring capital allocation across the Gulf of Mexico midstream sector, as operators prioritize brownfield platform expansions over greenfield trunkline construction to de-risk project returns against volatile commodity price environments.
Growth Catalysts
- Ultra-deepwater production:Reservoir developments below 1,500 meters require high-pressure pipeline infrastructure, pulling investment toward specialized steel metallurgy and subsea installation capabilities.
- PHMSA integrity mandates:Tighter construction and inspection protocols for interstate pipelines are accelerating replacement cycles for aging shallow-water gathering systems along the Louisiana coastline.
- NGL fractionation demand:Associated gas from deepwater oil fields is expanding processing requirements for natural gas liquids extraction and export terminal connectivity.
Market Restraints
- Specialized steel supply concentration:High-yield pipeline-grade steel production concentrates among a limited set of domestic and international mills, creating input cost volatility and lead time uncertainty.
- Decommissioning liability frameworks:Evolving federal standards for platform removal and site restoration are extending project financing timelines and elevating insurance pricing for aging infrastructure.
- Permitting bottlenecks:BSEE third-party certification requirements and Coast Guard marine terminal security reviews compress development schedules for new export capacity.
Strategic Opportunities
- Electrification of offshore platforms:Subsea power cable tie-ins to onshore grids are reducing carbon intensity and opening carbon credit monetization pathways for deepwater operators.
- Hydrogen blending infrastructure:Existing natural gas pipeline corridors offer repurposing potential for hydrogen transport, contingent on metallurgical compatibility testing and BSEE safety protocol updates.
- Methane intensity benchmarking:Emerging federal methane performance standards are creating first-mover advantages for operators with leak detection and repair automation deployed across their gathering networks.
Industry Challenges
- Subsea welding technician scarcity:Deepwater pipeline installation requires certified hyperbaric welders, and training program throughput lags project demand by approximately eighteen months.
- Legacy platform integration:Brownfield expansions must interface with decades-old control systems and structural designs, elevating engineering complexity and commissioning risk.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gulf of Mexico Oil and Gas Midstream Market |
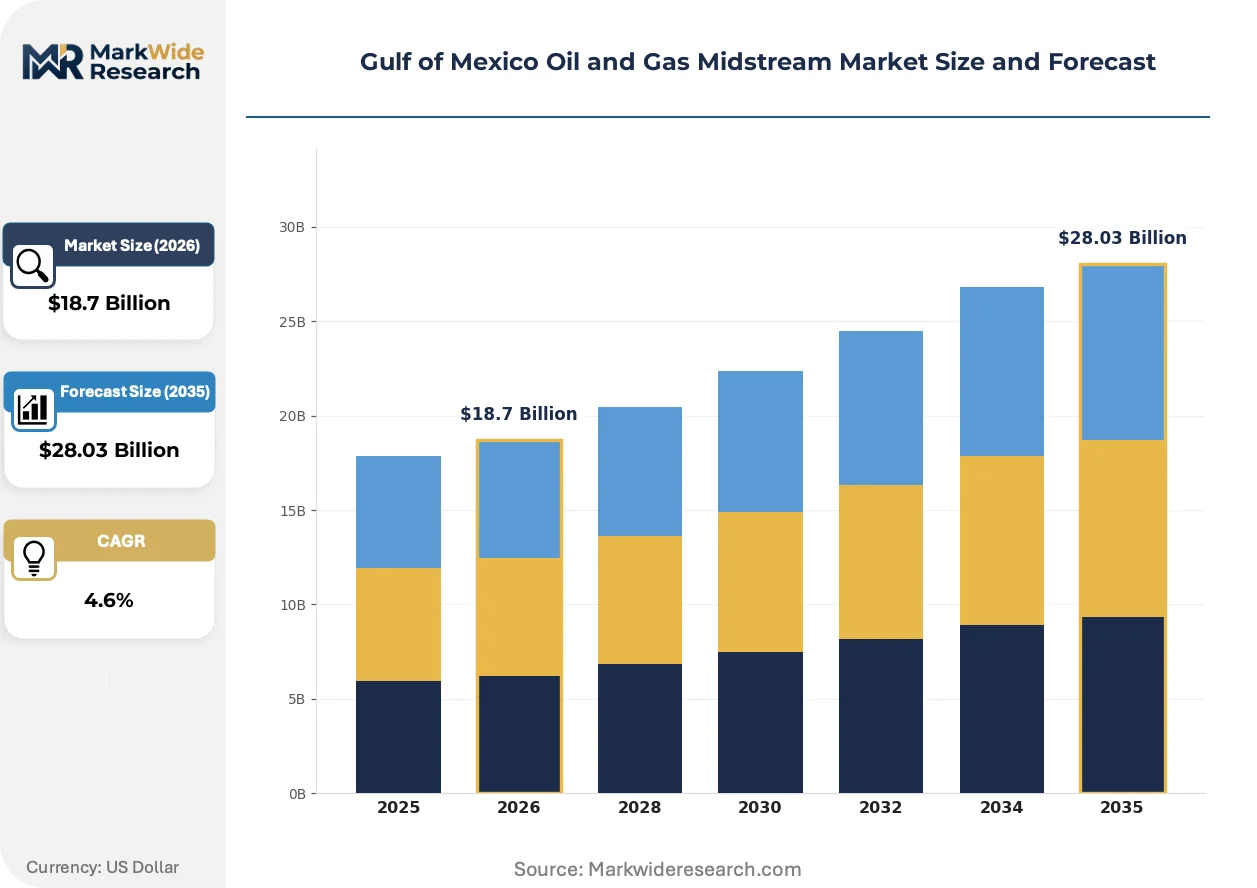
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.03 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Transportation, Storage, Processing, Distribution Infrastructure Type: Pipelines, Terminals, Platforms, Compression Stations Product Type: Natural Gas, Crude Oil, Liquefied Natural Gas, Refined Products End User: Industrial Users, Power Generators, Refiners, Traders |
| Companies Covered | Williams Companies Inc, Exxon Mobil Corporation, Occidental Petroleum Corporation, Royal Vopak NV, Enagás SA, Chevron Corporation, DCP Midstream LLC, PSI Midstream Partners LP, Crimson Midstream LLC, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gulf of Mexico Oil and Gas Midstream Market Shifts & Advancements
Digital twin technology and autonomous inspection systems are compressing operational decision cycles across Gulf of Mexico pipeline networks, while metallurgical advances enable deeper, higher-pressure reservoir access.
Corrosion-resistant alloy cladding is expanding into ultra-deepwater flowline applications as operators push tieback distances beyond fifty miles from host platforms. Major trunkline developers are specifying clad pipe for high-CO2 reservoir service to eliminate inhibition chemical logistics. This metallurgical shift is expanding into standard procurement specifications for new Outer Continental Shelf developments.
BSEE mandatory third-party certification requirements for subsea safety systems are tightening documentation standards and extending engineering review timelines. The regulation forces operators to front-load validation testing during design phases rather than addressing compliance gaps during installation. Deepwater project teams are responding by embedding certification specialists within engineering contractor organizations.
Buyer consolidation among supermajor operators is compressing vendor qualification cycles and elevating performance guarantees in midstream service contracts. Smaller independents are losing procurement access to preferred installation contractor schedules, forcing reliance on spot-market vessel availability. This concentration is most visible in the western Gulf, where Chevron and Shell control the majority of deepwater production tieback commitments.
Gulf of Mexico Oil and Gas Midstream Market Segmentation
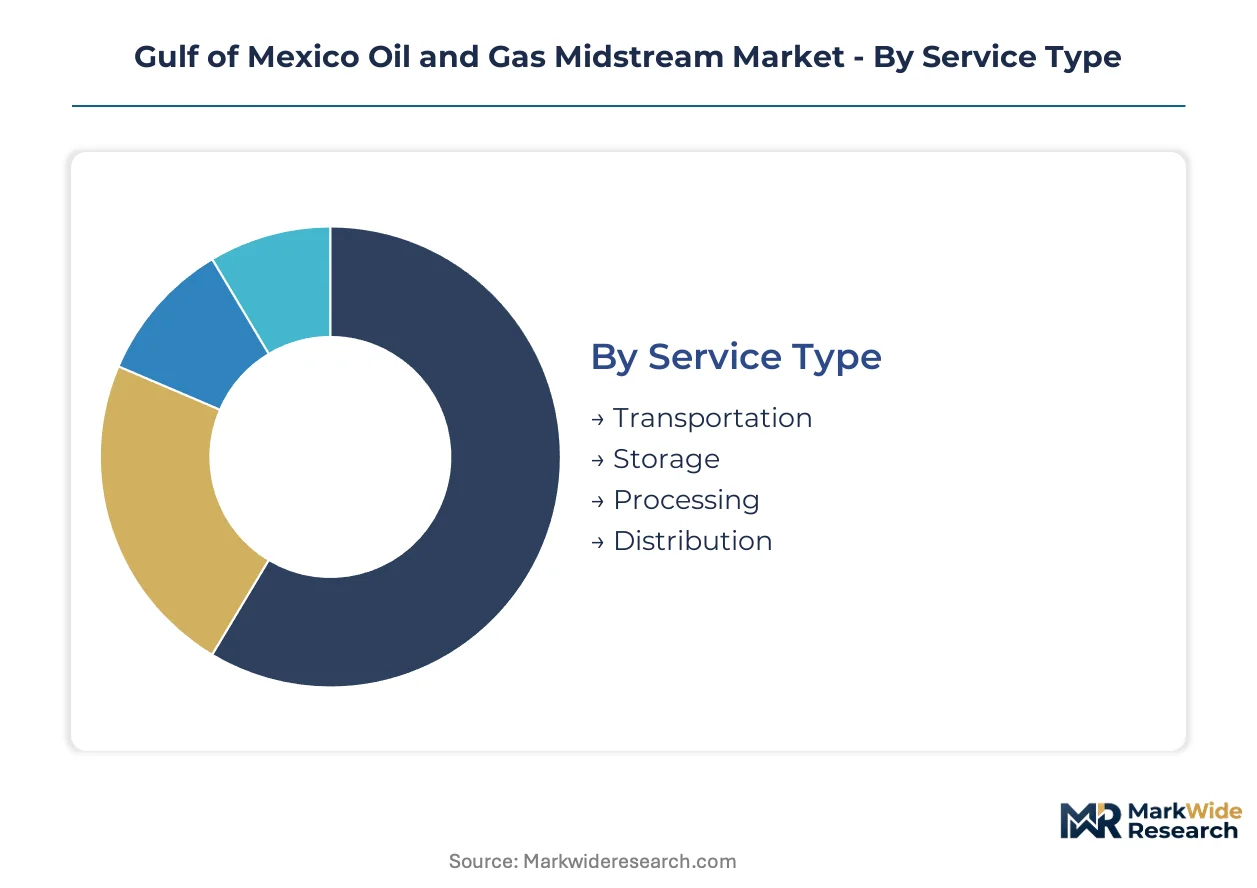
Midstream operators in the Gulf of Mexico configure service portfolios around reservoir depth, pressure specifications, and tieback distance to existing infrastructure. Segmentation discipline separates brownfield expansion opportunities from greenfield development risks across the Louisiana and Texas offshore corridors.
Service Type:
Capital allocation priorities differ sharply by service category, with processing margins expanding fastest while transportation commands the largest absolute deployment.
- Transportation:Subsea flowlines and export trunklines operating above 10,000 psi constitute the foundational revenue layer. Operators prioritize brownfield tiebacks to existing platform complexes in the western Gulf to de-risk returns against commodity volatility.
- Processing:Associated gas handling and NGL extraction infrastructure is expanding most quickly as deepwater oil fields yield higher gas-to-oil ratios. PHMSA integrity mandates are accelerating replacement demand for legacy shallow-water gathering systems.
- Storage:Subsalt caverns and floating storage units buffer production volatility from hurricane disruptions. Louisiana salt dome capacity maintains the highest utilization rates due to proximity to refining clusters.
- Distribution:Last-mile connectivity to onshore fractionation facilities and marine export terminals completes the value chain. Texas Gulf Coast NGL fractionation demand is pulling investment toward specialized terminal infrastructure.
Transportation leads on scale; Processing leads on momentum.
Infrastructure Type:
Project economics vary by asset vintage, with newbuild pipelines requiring decade-long payback periods against brownfield platform expansions capturing faster returns.
- Pipelines:High-pressure steel trunklines and corrosion-resistant alloy flowlines dominate capital deployment. Ultra-deepwater tiebacks beyond fifty miles from host platforms are specifying clad pipe for high-CO2 reservoir service.
- Terminals:Marine loading facilities for crude and LNG exports face Coast Guard security reviews that compress development schedules. Brownfield expansions at existing hub locations capture disproportionate margin pools due to lower permitting burdens.
- Platforms:Fixed-leg structures in shallow water and floating production systems in deepwater serve as gathering hubs. Electrification tie-ins to onshore grids are reducing carbon intensity and opening carbon credit pathways.
- Compression Stations:Subsea and platform-based gas compression maintains flow assurance across extended tieback distances. BSEE third-party certification requirements are extending engineering review timelines for safety system validation.
Pipelines anchor capital deployment; Terminals face the tightest permitting constraints.
Product Type:
Product mix determines metallurgical specifications and regulatory jurisdiction, with natural gas infrastructure falling under FERC interstate authority and crude systems subject to PHMSA construction mandates.
- Natural Gas:Dry gas and associated gas from oil reservoirs flow through gathering networks to processing facilities. Williams Companies leverages its Transco system to anchor natural gas gathering across the western Gulf.
- Crude Oil:Heavy sour and light sweet grades require segregated pipeline infrastructure to preserve blending specifications. Chevron dominates deepwater trunkline routing from its Anchor and Mad Dog platform complexes.
- Liquefied Natural Gas:Cryogenic export terminals connect Gulf production to international markets through marine loading facilities. Specialized insulation and boil-off management systems command premium engineering margins.
- Refined Products:Diesel, gasoline, and jet fuel movements through product pipelines serve coastal refining corridors. Demand concentrates around Houston and New Orleans refining clusters with marine terminal access.
Natural Gas commands the largest infrastructure footprint; LNG export capacity is climbing the fastest.
End User:
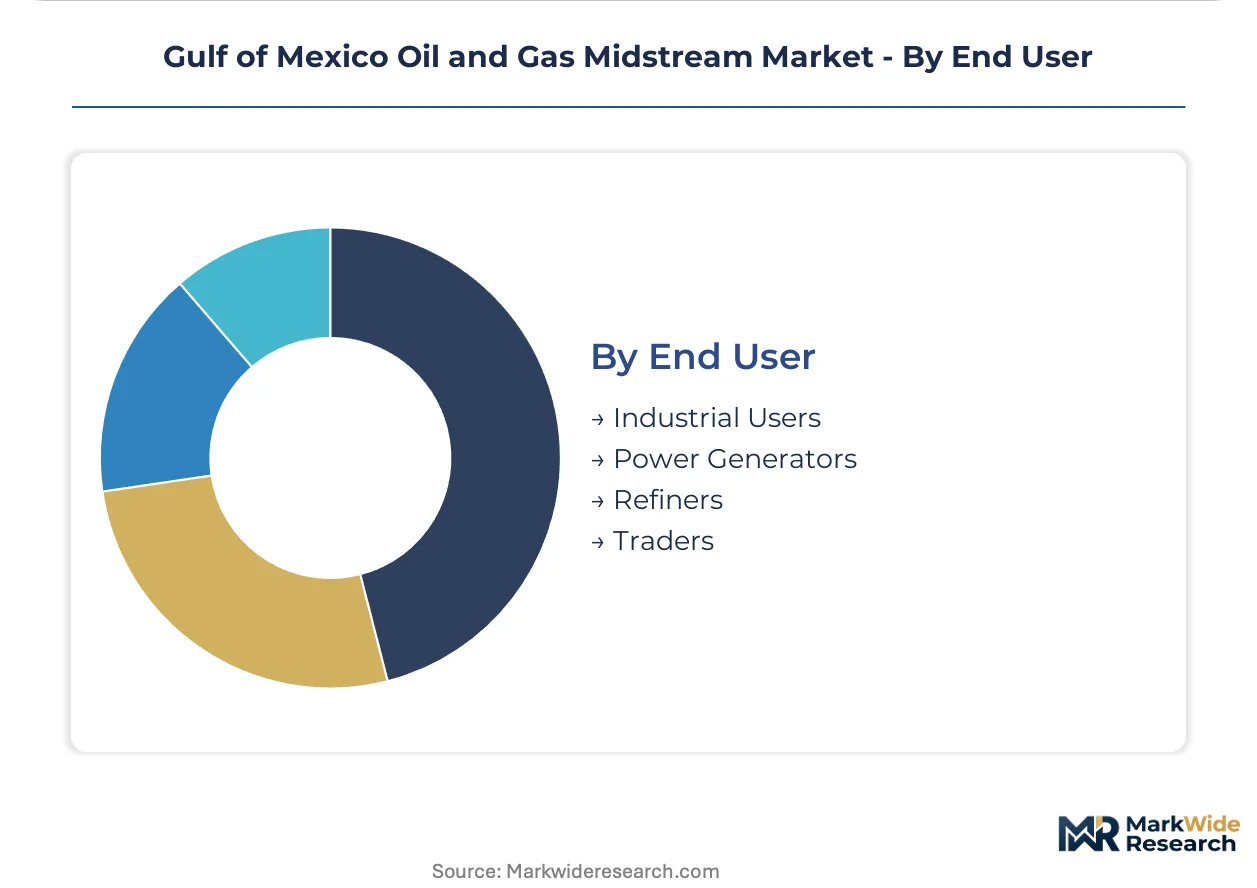
Buyer concentration among supermajor operators is compressing vendor qualification cycles and elevating performance guarantees in midstream service contracts.
- Industrial Users:Petrochemical complexes and manufacturing facilities along the Texas and Louisiana coasts consume pipeline-delivered feedstocks. Methane intensity benchmarking is creating first-mover advantages for operators with automated leak detection.
- Power Generators:Combined-cycle gas turbines and peaking plants depend on firm transportation capacity for supply security. Electrification of offshore platforms is reducing generator fuel demand at production facilities.
- Refiners:Complex coking and hydrocracking units on the Gulf Coast process heavy crude delivered via marine and pipeline receipts. DCP Midstream specializes in NGL fractionation connectivity for refining feedstock supply.
- Traders:Merchant intermediaries arbitrage price differentials between offshore production and onshore market hubs. Floating storage and regasification units enable rapid cargo repositioning during price volatility.
Refiners anchor volume commitments; Traders drive flexibility premiums in contract structuring.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States Gulf Coast infrastructure outpaces Mexican offshore development by a factor of ten in active pipeline mileage, though both jurisdictions face tightening decommissioning liability frameworks that compress project financing timelines.
Louisiana
Deepwater tiebacks from the Outer Continental Shelf drive subsea flowline demand, with brownfield expansions at existing platform complexes capturing faster returns than greenfield trunkline construction. PHMSA integrity mandates accelerate replacement cycles for aging shallow-water gathering systems. The Port Fourchon marine terminal cluster anchors crude export capacity, while Lake Charles processing facilities expand NGL fractionation throughput.
Texas
Associated gas from Permian-linked offshore fields expands natural gas liquids extraction requirements along the Gulf Coast corridor. FERC interstate pipeline authority shapes rate structures for cross-border capacity into Mexico. The Houston Ship Channel refining cluster concentrates demand for high-pressure trunkline connectivity, with Texas City petrochemical complexes consuming pipeline-delivered feedstocks at scale.
Mississippi
Shallow-water platform infrastructure maintains mature utilization profiles, with electrification tie-ins to onshore grids reducing carbon intensity at production facilities. BSEE third-party certification requirements extend engineering review timelines for safety system validation. The Pascagoula refining corridor processes heavy crude receipts via marine and pipeline supply modes.
Alabama
Subsalt cavern storage capacity buffers production volatility from hurricane disruptions, with Mobile Bay offshore fields requiring specialized compression infrastructure for extended tieback distances. Coast Guard marine terminal security reviews compress development schedules for new export capacity. The Theodore industrial complex anchors last-mile connectivity to onshore fractionation facilities.
Florida
Eastern Gulf exploration moratoria limit pipeline construction activity, though existing infrastructure serves as a strategic reserve corridor for supply security planning. EPA water quality standards shape coastal construction permitting timelines. The Tampa Bay logistics cluster maintains floating storage utilization for rapid cargo repositioning during price volatility events.
Gulf of Mexico Oil and Gas Midstream Market Competitive Landscape
Gulf Coast integrated operators anchor one tier; specialized midstream partnerships hold contracted positions around supermajor production commitments. Market structure concentrates around three dominant archetypes: trunkline developers with anchor platform relationships, processing specialists with fractionation and terminal connectivity, and independent gatherers serving shallow-water independents. Competitive moves center on brownfield platform expansions to de-risk returns and strategic compression infrastructure to maintain flow assurance across extended tieback distances.
Within the integrated operator tier, Williams Companies Inc and Chevron Corporation exemplify divergent strategic positions. Williams leverages its Transco system footprint across the western Gulf, while Chevron dominates deepwater trunkline routing from its Anchor and Mad Dog platform complexes. DCP Midstream LLC occupies a specialized position in NGL fractionation and export terminal connectivity along the Texas Gulf Coast.
| Leading Market Players |
|---|
| Williams Companies Inc |
| Exxon Mobil Corporation |
| Occidental Petroleum Corporation |
| Royal Vopak NV |
| Enagás SA |
| Chevron Corporation |
| DCP Midstream LLC |
| PSI Midstream Partners LP |
| Crimson Midstream LLC |
| Others |
Supply & Pricing Matrix
BSEE methane intensity benchmarks gate qualified supply access and premium-tier pricing for deepwater pipeline contractors serving supermajor operators. Contractors meeting automated leak detection standards command rate premiums on brownfield expansion contracts while non-compliant vendors face exclusion from preferred bidder lists.
Pricing Analysis
Capacity additions along the Texas Gulf Coast are reshaping price floors for NGL fractionation services as DCP Midstream and competing processors expand terminal connectivity. Contract pricing stratifies across premium, standard, and economy tiers based on BSEE certification status and guaranteed throughput commitments. Cost compression in shallow-water gathering systems is intensifying because PHMSA integrity mandates accelerate replacement demand. Independent operators exhibit highest price sensitivity due to spot-market vessel reliance, while Chevron and Shell anchor long-term offtake agreements at premium rates.
Supply Chain Analysis
Direct-to-platform procurement channels handle supermajor demand for high-yield pipeline-grade steel and corrosion-resistant alloy cladding. Manufacturing concentrates in Japan, South Korea, and domestic US mills producing specialized metallurgy for ultra-deepwater service. Raw material feeds draw from nickel, chromium, and molybdenum suppliers facing commodity price volatility from energy transition demand shifts. Distribution runs through integrated EPC contractors with embedded certification specialists to satisfy BSEE third-party validation requirements. Single-source vulnerability concentrates in hyperbaric welding technician training programs lagging project demand by eighteen months.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Deepwater tieback economics present margin expansion pathways through brownfield platform electrification and carbon credit monetization. Cost-down drivers center on automated inspection systems compressing operational decision cycles across pipeline networks.
For Market Incumbents: Deploy digital twin technology across legacy platform infrastructure to reduce commissioning risk on brownfield expansions. Backward integration into specialized steel procurement mitigates input cost volatility from concentrated mill supply. Williams Companies and Chevron Corporation anchor positions through Transco system dominance and Anchor-Mad Dog trunkline control respectively.
For New Entrants and Emerging Players: Subsea power cable installation services represent the most penetrable white-space target as electrification mandates spread across the Outer Continental Shelf. Target shallow-water independent operators losing procurement access to preferred contractor schedules. Pursue BSEE certification pre-investment to qualify for supermajor vendor lists before capacity shortages peak.
For Investors and Strategic Acquirers: Roll-up economics work for NGL fractionation specialists because Texas Gulf Coast export terminal connectivity faces permitting bottlenecks that protect incumbent positions. Long-term viability hinges on hydrogen blending infrastructure repurposing potential. Monitor BSEE safety protocol updates for metallurgical compatibility testing as the inflection signal for stranded asset risk.
| Strategic Initiative | Industry Significance |
|---|---|
| Brownfield Platform Electrification | Subsea power cable tie-ins to onshore grids reduce carbon intensity and unlock carbon credit revenue streams. |
| Corrosion-Resistant Alloy Cladding Expansion | Clad pipe specifications for high-CO2 reservoirs eliminate chemical inhibition logistics across extended tiebacks. |
| Automated Leak Detection Deployment | Methane intensity benchmarking creates first-mover advantages for operators with sensor networks across gathering infrastructure. |
| Hyperbaric Welder Training Program Investment | Certified technician pipeline expansion addresses eighteen-month supply lag constraining deepwater installation capacity. |
| Hydrogen Blending Infrastructure Testing | Existing natural gas corridor repurposing potential depends on BSEE metallurgical compatibility protocol updates. |
Research Methodology
Direct dialogue with pipeline integrity engineers, subsea project managers, PHMSA regulatory specialists, and EPC procurement directors grounded qualitative assessment of brownfield expansion economics. Secondary validation drew from BSEE safety filings, FERC interstate rate case dockets, Coast Guard marine terminal security reviews, and EIA Gulf production statistics. Bottom-up project pipeline tracking and top-down infrastructure capacity modeling enabled triangulation across data sources.
Segmentation outputs across service type, infrastructure vintage, product category, and end-user concentration were generated across the projection horizon. CAGRs were derived from capacity utilization trends, replacement cycle timing, and regulatory compliance cost trajectories. Forecast inputs incorporated PHMSA integrity mandate implementation schedules and supermajor capital commitment patterns.
Commodity price volatility, permitting timeline extensions, and decommissioning liability framework evolution are the dominant revision risks for Gulf of Mexico midstream projections. Forecasts reflect documented assumptions regarding brownfield expansion preference persistence and electrification subsidy continuity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Small Scale LNG (SSLNG) Market
Oil & Gas
Iran Oil and Gas Market
Oil & Gas
Saudi Arabia Oil and Gas Midstream Market
Oil & Gas
North America Oil and Gas Line Pipe Market
Oil & Gas
North America Artificial Lift Systems Market
Oil & Gas
Electric Fracking Market
Oil & Gas
Subsea Well Access and BOP System Market
Oil & Gas
Coiled Tubing System Market
Oil & Gas
Canada LNG Bunkering Market
Oil & Gas
GCC and North Africa Coiled Tubing Market
Oil & Gas
Sidetracking Market
Oil & Gas
Geothermal Drill Bits Market
Oil & Gas
Oil and Gas Pipeline Coatings Market
Oil & Gas
Oil and Gas Security Services Market
Oil & Gas
Oil and Gas Accumulators Market
Oil & Gas
Libya Oil and Gas Midstream Market