
 Smart Oilfield Market | 2026-2036
Smart Oilfield Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Oilfield Market Analysis
API Q2 certification for service suppliers is bifurcating the vendor landscape between qualified integrators and commodity hardware providers. Schlumberger Limited leverages its digital subsurface platform to anchor high-margin software subscriptions across Middle Eastern NOCs. Halliburton Company sustains drilling optimization leadership through real-time telemetry networks deployed in Permian Basin operations. Baker Hughes Company differentiates via its combined hardware-software stack for predictive maintenance of subsea production systems.
Smart oilfield denotes an upstream hydrocarbon production environment instrumented with networked sensors, edge computing nodes, and cloud-based analytics to optimize reservoir recovery rates and minimize unplanned downtime. Functional parameters include sub-second latency for wellhead pressure telemetry and machine learning models trained on historical decline curves to forecast production bottlenecks. IoT Sensors and Remote Monitoring Systems represent the most mature revenue pools, while Data Analytics Software captures expanding margin as operators shift from capex-heavy hardware to recurring software licenses. Machine Learning within the technology stack is displacing rule-based diagnostics for reservoir characterization, though Cloud Computing infrastructure remains concentrated among hyperscale providers with energy-sector compliance attestations.
EPA methane emissions standards under the Clean Air Act and BSEE well control regulations govern offshore system reliability requirements in US waters, while Saudi Aramco's supplier qualification programs impose parallel cybersecurity and data sovereignty conditions on foreign technology vendors. API standards for equipment integrity and emerging SEC climate disclosure rules are reshaping procurement criteria toward verifiable emissions monitoring capabilities. Stakeholders must weigh the capital intensity of full-stack platform builds against modular partnerships as operator budgets oscillate with commodity price volatility.
Market Dynamics
Digital twin deployment is compressing capital allocation cycles across upstream portfolios as operators demand real-time reservoir simulation fidelity before sanctioning new field developments.
Growth Catalysts
- API Q2 Certification Mandates:North American service suppliers face tightening qualification standards that favor integrated platform providers over commodity hardware vendors.
- Edge Computing Architecture:Sub-second latency requirements for wellhead pressure telemetry are pulling capital toward distributed computing nodes at the wellsite.
- Saudi Aramco Supplier Programs:Cybersecurity and data sovereignty conditions imposed on foreign technology vendors are accelerating localization partnerships.
Market Restraints
- Hyperscale Cloud Concentration:Energy-sector compliance attestations remain concentrated among a narrow set of infrastructure providers with specialized certifications.
- Silicon Supply Volatility:Edge computing hardware faces input cost pressure from semiconductor fabrication capacity constraints.
- SEC Climate Disclosure Rules:Emerging emissions monitoring requirements are creating procurement friction for operators with legacy telemetry architectures.
Strategic Opportunities
- Machine Learning Convergence:Reservoir characterization workflows combining physics-based simulation with neural network pattern recognition are opening new service revenue pools.
- Permian Basin Telemetry Networks:Real-time drilling optimization infrastructure remains underpenetrated across independent producers operating fractured acreage positions.
- BSEE Well Control Incentives:Offshore reliability regulations are creating preferential procurement pathways for predictive maintenance system vendors.
Industry Challenges
- Petroleum Data Science Talent Scarcity:Reservoir engineers with machine learning deployment experience command premium compensation that strains operator opex budgets.
- Subsea Integration Complexity:Predictive maintenance platforms for subsea production systems require extensive retrofit engineering on brownfield installations.
- API Equipment Integrity Timelines:Certification cycles for sensor hardware extend procurement lead times beyond traditional drilling schedule windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Oilfield Market |
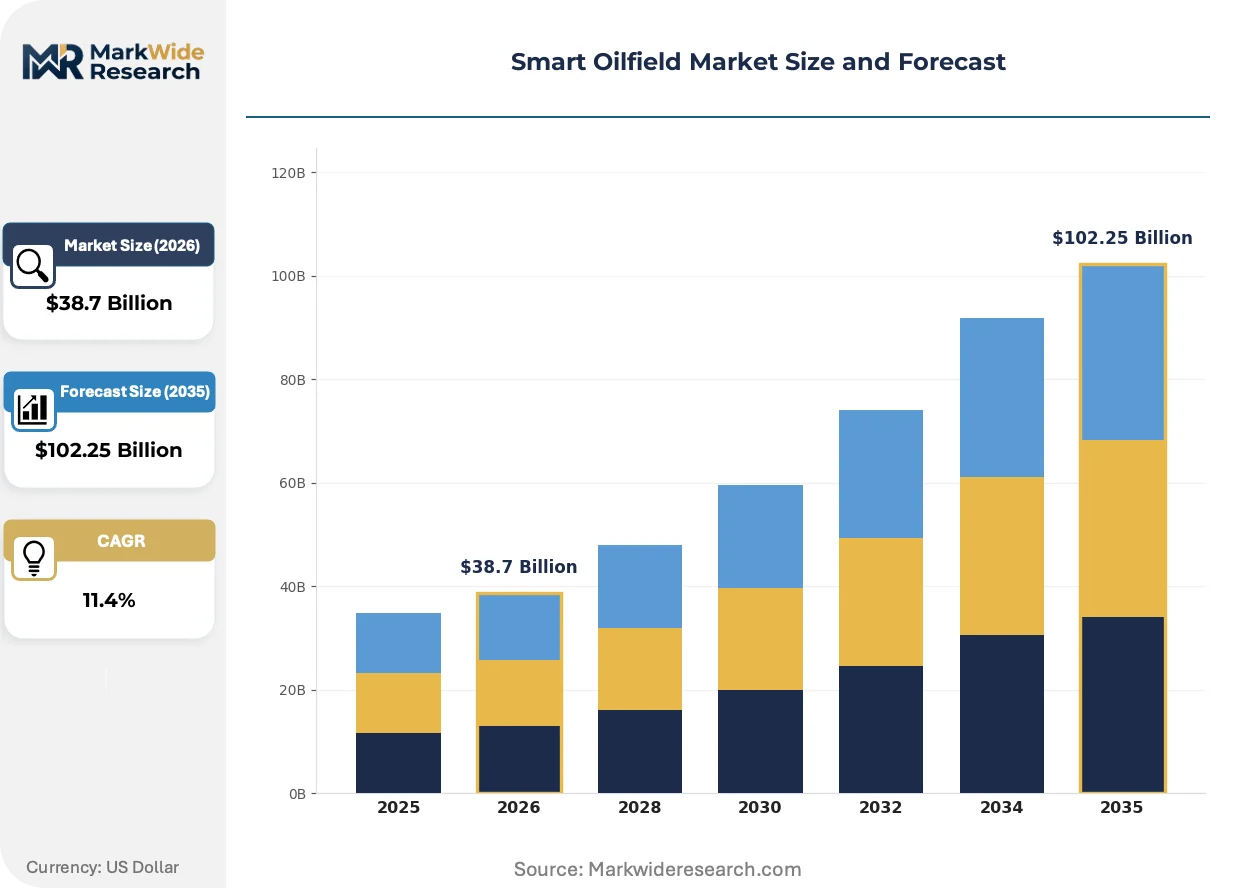
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $102.25 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: IoT Sensors, Data Analytics Software, Automation Solutions, Remote Monitoring Systems Application: Exploration, Drilling Optimization, Production Monitoring, Asset Management Technology: Machine Learning, Cloud Computing, Big Data Analytics, Real-time Data Processing End User: Oil Producers, Service Companies, Equipment Manufacturers, Asset Managers |
| Companies Covered | Schlumberger Limited, Halliburton Company, Baker Hughes Company, Weatherford International, NOV Inc., Honeywell International Inc., Rockwell Automation, China National Petroleum Company, Pason Systems Corp., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Oilfield Market Emerging Trajectories
Upstream technology investment is pivoting from hardware-intensive wellsite instrumentation toward software-defined reservoir management systems that compress decision latency.
Downhole fiber-optic sensing is miniaturizing. Distributed acoustic sensing cables now deliver temperature and strain measurements along the entire wellbore with single-fiber deployments. Supermajor operators in the Gulf of Mexico are retrofitting existing completions with slimline fiber packages. This miniaturizing form factor is collapsing the capital cost differential between greenfield instrumentation and brownfield upgrades.
EPA methane emissions standards under the Clean Air Act are tightening fugitive detection thresholds. Continuous monitoring systems are displacing periodic optical gas imaging surveys across onshore shale basins. Permian Basin operators are deploying aerial LiDAR networks to satisfy quarterly reporting obligations.
Subscription licensing is displacing perpetual software sales across reservoir simulation platforms. National oil companies in the Middle East are negotiating enterprise-wide seat agreements that bundle training and model maintenance. This procurement evolution is most visible in Saudi Arabia's onshore developments, where multi-year commitments anchor vendor cash flow visibility.
Smart Oilfield Market Segmentation
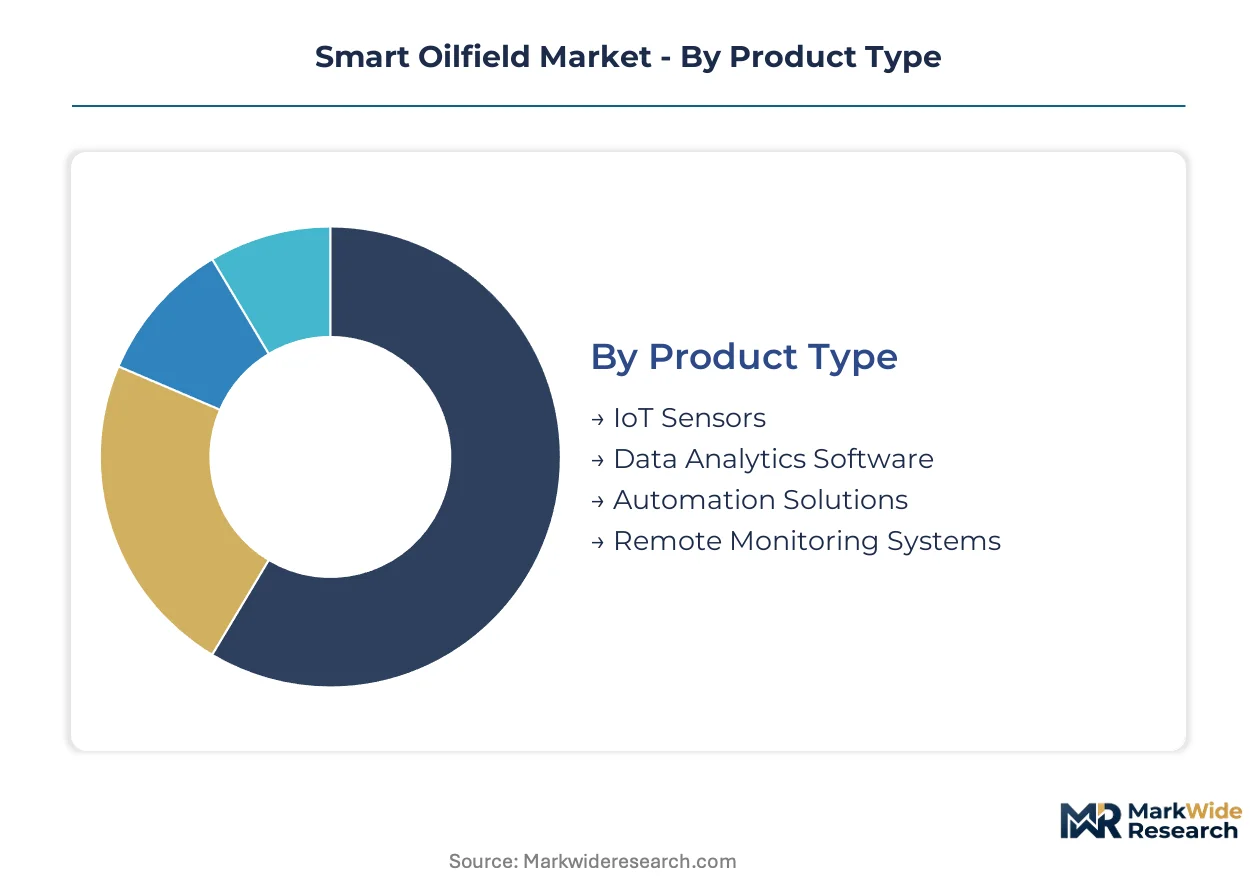
Smart oilfield procurement patterns diverge sharply between integrated operators seeking full-stack platforms and independent producers buying modular point solutions. Segment boundaries are blurring as vendors bundle hardware with recurring software licenses, forcing buyers to evaluate total cost of ownership across mixed deployment models.
Product Type:
IoT Sensors and Remote Monitoring Systems dominate domestic procurement in Saudi Arabia's onshore developments, while Data Analytics Software exports concentrate among Middle Eastern national oil companies negotiating enterprise-wide subscriptions.
- IoT Sensors:Pressure, temperature, and flow measurement devices with sub-second telemetry latency. Demand concentrates in Permian Basin drilling operations where real-time wellhead monitoring reduces non-productive time. Edge computing nodes at the wellsite are pulling capital toward distributed architectures that bypass hyperscale cloud dependencies.
- Data Analytics Software:Reservoir simulation platforms combining physics-based modeling with neural network pattern recognition. Saudi Aramco's supplier qualification programs are accelerating localization partnerships for foreign vendors seeking multi-year enterprise commitments. Subscription licensing is displacing perpetual sales across Middle Eastern NOCs.
- Automation Solutions:Closed-loop control systems for artificial lift and surface facility optimization.
- Remote Monitoring Systems:Integrated telemetry networks spanning wellhead-to-cloud data pipelines.
IoT Sensors holds the largest share; momentum sits with Data Analytics Software.
Application:
Production Monitoring commands premium pricing from operators with mature field portfolios, while Drilling Optimization spreads across cost-sensitive independent producers in fractured acreage positions.
- Production Monitoring:Continuous surveillance of artificial lift performance, separator efficiency, and pipeline integrity. Gulf of Mexico supermajors are retrofitting brownfield completions with downhole fiber-optic sensing to collapse capital cost differentials against greenfield instrumentation. Distributed acoustic sensing cables now deliver temperature and strain measurements along entire wellbores.
- Drilling Optimization:Real-time telemetry networks guiding directional drilling decisions and rate-of-penetration tuning. Permian Basin independents remain underpenetrated for integrated optimization infrastructure despite proven returns on automated mud weight management. Halliburton sustains leadership through deployed networks across West Texas operations.
- Exploration:Seismic processing and subsurface imaging workflows for prospect generation.
- Asset Management:Predictive maintenance platforms for surface equipment and subsea production systems.
Production Monitoring captures the highest margins; Drilling Optimization is expanding most quickly among independents.
Technology:
Machine Learning deployments cluster with national oil companies possessing historical decline curve archives, while Cloud Computing infrastructure concentrates among hyperscale providers with energy-sector compliance attestations.
- Machine Learning:Neural network models trained on reservoir characterization data to forecast production bottlenecks and optimize recovery factors. Physics-based simulation convergence is opening new service revenue pools for vendors combining empirical pattern recognition with first-principles modeling. Talent scarcity for petroleum data scientists strains operator opex budgets.
- Cloud Computing:Hyperscale infrastructure hosting reservoir simulation workloads and enterprise data lakes. Saudi Aramco's data sovereignty conditions are forcing foreign vendors toward localized edge deployments or in-country facility partnerships. EPA methane emissions standards are tightening procurement criteria toward verifiable monitoring capabilities.
- Big Data Analytics:Historical production database mining for decline curve analysis and infill drilling targeting.
- Real-time Data Processing:Sub-second latency architectures for wellhead pressure telemetry and emergency shutdown triggering.
Machine Learning shows the steepest expansion trajectory; Cloud Computing remains concentrated among narrow infrastructure provider sets.
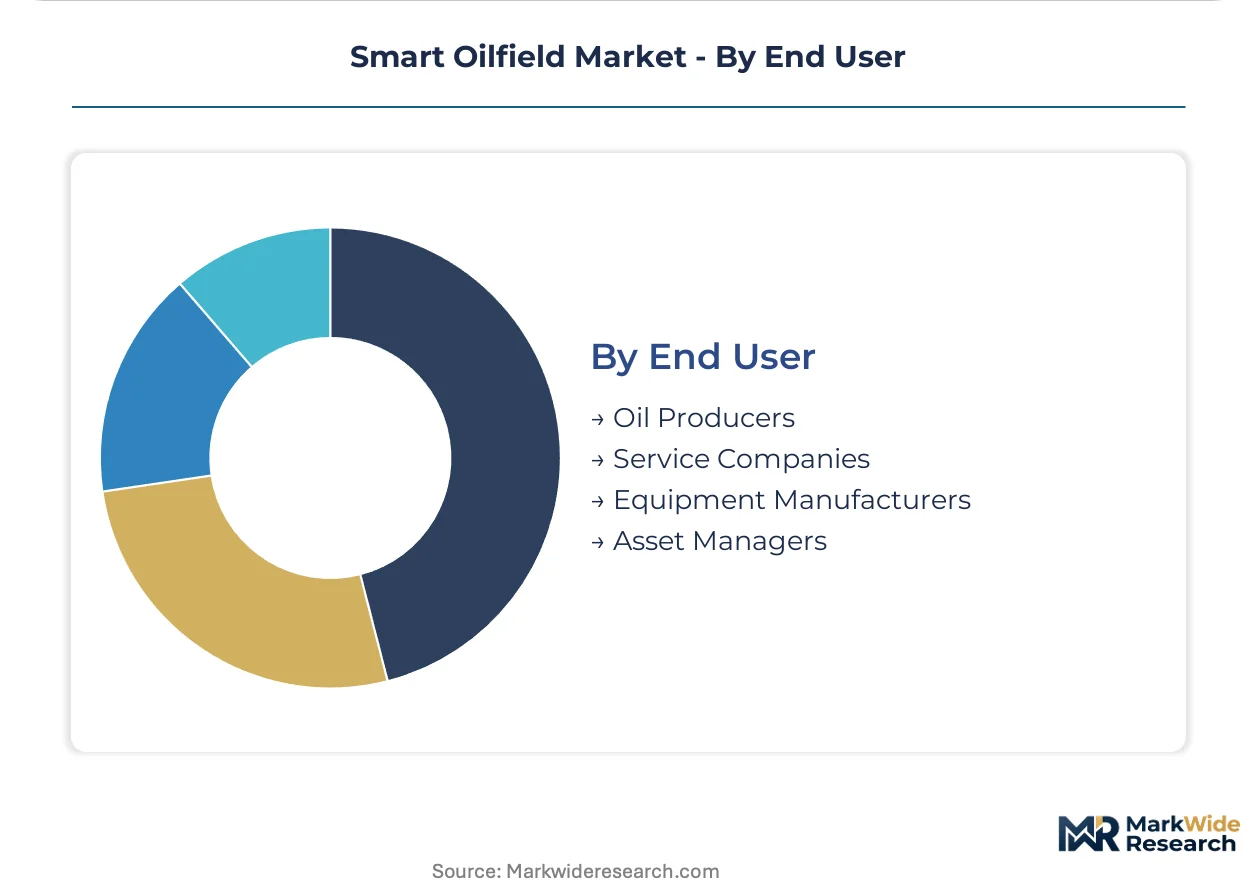
End User:
Oil Producers drive integrated platform procurement with multi-year capital commitments, while Service Companies fragment across specialized point solution vendors seeking API Q2 qualification.
- Oil Producers:Integrated operators and national oil companies with captive engineering organizations deploying full-stack smart field architectures. Saudi Arabia's onshore developments anchor vendor cash flow visibility through enterprise-wide seat agreements bundling training and model maintenance. Schlumberger leverages its digital subsurface platform to anchor high-margin subscriptions.
- Service Companies:Drilling contractors and well intervention specialists buying modular telemetry and optimization modules. API Q2 certification mandates are bifurcating the vendor landscape between qualified integrators and commodity hardware providers. Tighter qualification standards favor integrated platform providers.
- Equipment Manufacturers:Original equipment suppliers embedding sensor packages into pumps, compressors, and subsea trees.
- Asset Managers:Financial operators optimizing portfolio-level production economics through outsourced analytics services.
Oil Producers command the largest procurement volumes; Service Companies are gaining share fastest as drilling activity accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Integrated operators anchor procurement volumes in Saudi Arabia, while independent producers fragment demand across the Permian Basin. National oil companies in the Middle East negotiate enterprise-wide software subscriptions. North American shale operators prioritize modular point solutions over full-stack platforms.
United States
Permian Basin independents drive drilling optimization demand through real-time telemetry networks. EPA methane emissions standards under the Clean Air Act tighten fugitive detection thresholds across onshore shale basins. West Texas operators deploy aerial LiDAR networks to satisfy quarterly reporting obligations.
Saudi Arabia
Saudi Aramco's onshore developments concentrate demand for IoT sensors and data analytics software. The company's supplier qualification programs impose cybersecurity and data sovereignty conditions on foreign technology vendors. Eastern Province field developments anchor vendor cash flow visibility through multi-year enterprise commitments.
United Arab Emirates
ADNOC's digital transformation programs accelerate adoption of digital twin platforms across offshore production assets. MOHAP and national cybersecurity frameworks govern data localization requirements for foreign vendors. Abu Dhabi clusters host localization partnerships between international service companies and domestic technology providers.
Norway
Equinor's integrated operations center drives predictive maintenance demand for subsea production systems. Petroleum Safety Authority regulations govern offshore system reliability requirements in North Sea waters. Stavanger-based engineering clusters specialize in brownfield retrofit engineering for fiber-optic sensing deployments.
China
China National Petroleum Company expands smart field architectures across domestic tight oil developments. MIIT standards and GB certification requirements shape procurement criteria for edge computing hardware. Sichuan-Chongqing shale gas basins concentrate pilot deployments of machine learning-based reservoir characterization workflows.
Smart Oilfield Market Vendor Landscape
Player mix skews toward integrated oilfield service conglomerates with captive software platforms. Market structure concentrates around three global providers controlling digital subsurface and drilling optimization segments. Strategic archetypes include full-stack platform builders, modular hardware specialists, and hyperscale cloud infrastructure partners. Competitive moves center on enterprise subscription anchoring and localization joint ventures in Middle Eastern markets.
Within the integrated service tier, Schlumberger Limited, Halliburton Company, and Baker Hughes Company exemplify platform-centric positioning. Schlumberger represents the digital subsurface archetype anchoring high-margin software subscriptions. Halliburton occupies the drilling optimization vector through deployed telemetry networks. Baker Hughes sits within the combined hardware-software stack segment for predictive maintenance applications.
| Leading Market Players |
|---|
| Schlumberger Limited |
| Halliburton Company |
| Baker Hughes Company |
| Weatherford International |
| NOV Inc. |
| Honeywell International Inc. |
| Rockwell Automation |
| China National Petroleum Company |
| Pason Systems Corp. |
| Others |
Supply Flow & Price Mechanics
Subscription licensing displacing perpetual software sales simultaneously redistributes supply geography toward Middle Eastern data centers and compresses pricing power for hardware-centric vendors. Saudi Aramco's enterprise-wide seat agreements bundle training and model maintenance, forcing foreign technology providers toward localized partnerships that alter cost structures.
Pricing Analysis
Cost-plus contracts with API Q2 certification indexation dominate service supplier agreements across North American shale operations. Three-tier pricing structure across premium integrators, qualified mid-tier vendors, and commodity hardware providers separates API-certified platforms from uncertified equipment. Pricing pressure stems from silicon supply volatility in edge computing hardware procurement. Independent producers in the Permian Basin exhibit highest price sensitivity, while Saudi Aramco's national oil company procurement demonstrates lowest sensitivity due to multi-year capital commitments.
Supply Chain Analysis
China and Taiwan anchor semiconductor fabrication for edge computing nodes deployed at wellsite locations. Downhole fiber-optic sensing draws from Japanese photonics suppliers and German precision manufacturing for distributed acoustic sensing cables. Single-source vulnerability concentrates in hyperscale cloud infrastructure with energy-sector compliance attestations. Distribution runs through integrated oilfield service conglomerates with captive software platforms rather than independent hardware distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Smart oilfield economics pivot toward platform-centric vendor structures as interoperability standards for reservoir simulation data reshape competitive boundaries. Schlumberger's digital subsurface platform exemplifies how enterprise subscription anchoring captures recurring revenue pools.
For Market Incumbents: Consolidate API Q2 certification advantages through deeper integration of hardware-software stacks, particularly for predictive maintenance applications in subsea production systems. Edge computing architecture investments at the wellsite defend against hyperscale cloud concentration risks. Acquire petroleum data science talent pools to offset capability scarcity strains on operator opex budgets. For New Entrants and Emerging Players: Differentiate on machine learning convergence workflows combining physics-based simulation with neural network pattern recognition for reservoir characterization. Target underpenetrated Permian Basin independents with modular telemetry solutions rather than full-stack platforms. Pursue localization joint ventures in Saudi Arabia to satisfy data sovereignty conditions for foreign technology vendors. For Investors and Strategic Acquirers: EPA methane emissions standards under the Clean Air Act reshape the acquisition landscape toward verifiable emissions monitoring capabilities. Long-term viability centers on vendors with recurring software license architectures rather than capex-heavy hardware models. Target acquisition archetypes include edge computing specialists with sub-second latency architectures. Watch SEC climate disclosure rule enforcement intensity as inflection indicator for procurement criteria shifts.| Strategic Initiative | Industry Significance |
|---|---|
| API Q2 Certification Investment | Qualification mandates bifurcate vendor landscape between integrated platforms and commodity hardware providers. |
| Localization Joint Venture | Saudi Aramco's data sovereignty conditions force foreign vendors toward in-country facility partnerships. |
| Machine Learning Platform Integration | Physics-neural convergence opens service revenue pools for reservoir characterization workflows. |
| Edge Computing Capacity Buildout | Distributed architectures at wellsite bypass hyperscale cloud dependencies for sub-second telemetry. |
| Predictive Maintenance Technology Licensing | BSEE well control regulations create preferential procurement pathways for subsea reliability systems. |
Methodological Framework
Cross-validation between primary interviews with reservoir engineers, drilling optimization specialists, and national oil company procurement directors and secondary validation through API standards documentation, EPA regulatory filings, and SEC climate disclosure submissions anchors the qualitative findings. Field interviews with edge computing hardware suppliers and hyperscale cloud infrastructure providers with energy-sector compliance attestations complement bottom-up and top-down triangulation across the analysis window.
Sensitivity analysis across product type, application, technology, and end user segmentation dimensions shapes the analytical framework throughout the forecast period. CAGRs derive from modeled adoption curves for digital twin platforms and machine learning deployment rates. Reservoir simulation workload migration patterns and Saudi Aramco supplier qualification program expansion serve as industry-specific forecast inputs.
Material uncertainties — commodity price volatility, semiconductor fabrication capacity constraints, and regulatory enforcement intensity for methane emissions standards — sit outside the modeled envelope. Forecasts reflect assumptions about operator capital allocation cycles and vendor localization partnership timelines. Recalibration cycles align with material shifts in API certification mandates and Middle Eastern data sovereignty requirements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Downhole Drilling Tools Market
Oil & Gas
Asia-Pacific Small-Scale LNG Market
Oil & Gas
India LNG Bunkering Market
Oil & Gas
Nigeria Upstream Oil Sector Market
Oil & Gas
Digital Oil Field Technology Market
Oil & Gas
Mexico Oil and Gas Market
Oil & Gas
Crude Oil Carriers Market
Oil & Gas
Oil and Gas Data Management Market
Oil & Gas
South America LNG Bunkering Market
Oil & Gas
Downhole Equipment Market
Oil & Gas
Mud Logging Unit Market
Oil & Gas
Digital Oilfield Solutions Market
Oil & Gas
Flow Computer Oil Gas Market
Oil & Gas
Shale Gas Hydraulic Fracturing Market
Oil & Gas
Hydraulic Workover Units Market
Oil & Gas
Latin America Coiled Tubing Market