
 Nigeria Oil and Gas Market | 2026-2036
Nigeria Oil and Gas Market Size, Share, and Industry Trends Forecast 2026-2036
Nigeria Oil and Gas Market Outlook
The capital-intensity divergence between integrated majors and indigenous operators is reorganizing competitive dynamics across Nigeria's petroleum sector. NNPC leverages its pipeline infrastructure and joint-venture equity positions to sustain upstream dominance in onshore and shallow-water blocks. Seplat Energy specializes in acquiring mature assets from international divestitures and extending production life through infill drilling and gas monetization. Dangote Petroleum Refinery anchors downstream transformation with its integrated refining and petrochemical complex near Lagos.
Nigeria oil and gas encompasses the exploration, production, refining, and distribution of hydrocarbon resources including Bonny Light crude with API gravity of 37.3° and associated natural gas reserves exceeding non-associated formations in volume. The sector serves power generation, industrial feedstock, export revenue, and domestic energy security objectives for Africa's largest economy. Upstream exploration and production commands the largest revenue pool despite maturity in onshore fields, while downstream refining represents the fastest-growing segment as Dangote's complex reduces import dependency. Midstream transportation infrastructure remains structurally constrained, creating margin capture opportunities for pipeline and storage operators serving the Niger Delta-to-Lagos corridor.
The Petroleum Industry Act, administered by the Nigerian Upstream Petroleum Regulatory Commission and Nigerian Midstream and Downstream Petroleum Regulatory Authority, is reshaping fiscal terms, licensing rounds, and host-community development obligations. NNPC's commercial transformation under the Act separates regulatory and commercial functions, altering market access for new entrants and joint-venture partners. Environmental standards from the Department of Petroleum Resources govern flaring reduction and remediation liabilities across producing regions. Stakeholders must monitor regulatory implementation timelines, divestment completion by international majors, and gas infrastructure investment decisions that determine Nigeria's transition positioning between hydrocarbon export and domestic industrialization pathways.
Market Dynamics
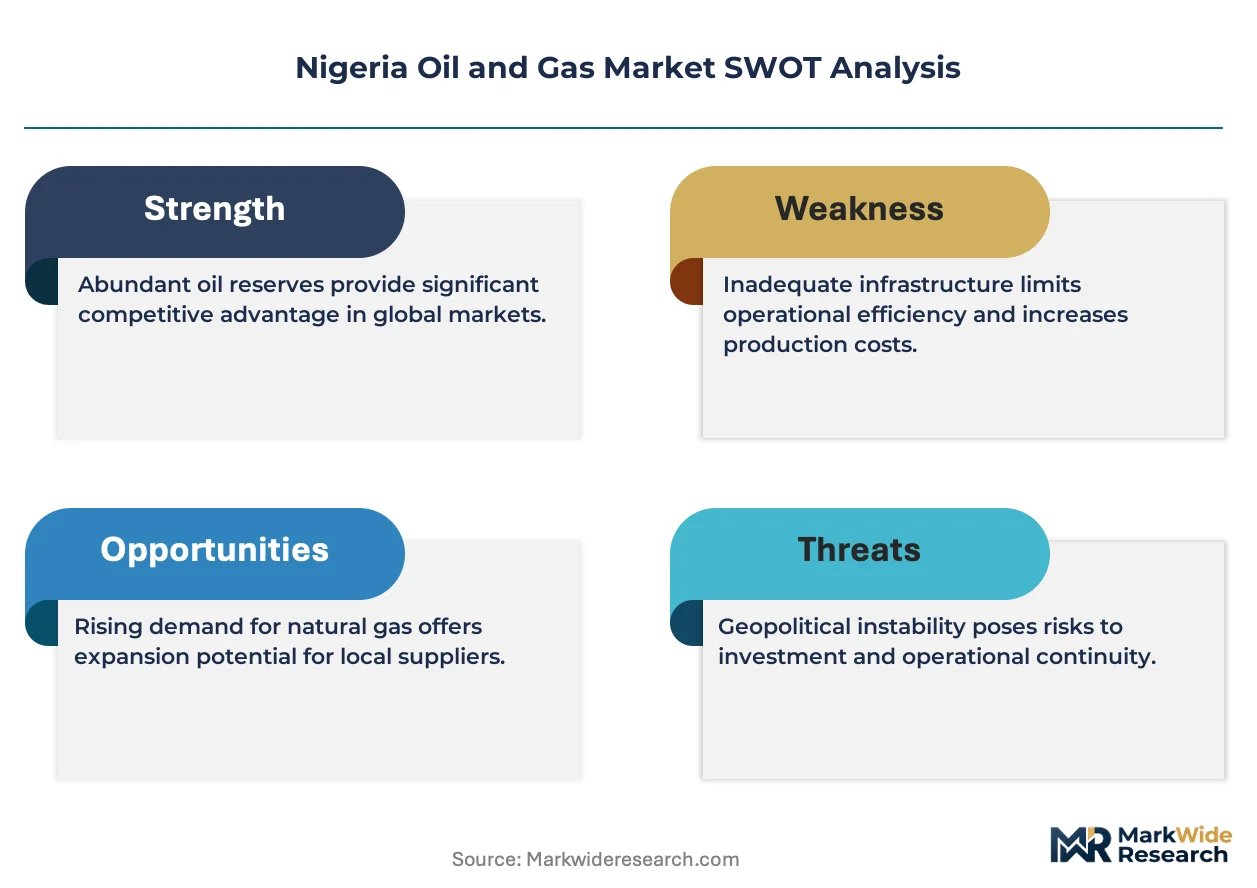
The Petroleum Industry Act is restructuring Nigeria's petroleum governance by separating NNPC's commercial and regulatory functions, while international majors accelerate asset divestitures that indigenous operators are acquiring to extend field life.
Growth Catalysts
- Gas-fired power expansion:Federal power generation utilities are procuring combined-cycle turbines to bridge grid deficits, creating anchor demand for domestic gas offtake.
- Host Community Development Trust:The Petroleum Industry Act mandates operator-funded trusts for producing regions, reducing vandalism risk and stabilizing Niger Delta operations.
- Floating LNG modularization:Small-scale liquefaction units are enabling stranded gas monetization from marginal fields previously uneconomic for pipeline export.
Market Restraints
- Crude theft and pipeline sabotage:Organized bunkering operations in the Niger Delta force operators into costly security expenditures and production deferments.
- Joint-venture funding gaps:NNPC's cash-call arrears to international partners have delayed greenfield developments and infill drilling programs.
- Refined product import dependency:Subsidy-distorted pricing and aging state refineries perpetuate forex drain and supply volatility.
Strategic Opportunities
- Deepwater exploration frontiers:Underexplored blocks in the Bight of Benin and outer Niger Delta offer material reserve additions beyond mature onshore basins.
- Petrochemical feedstock integration:Dangote's aromatics and polypropylene units are creating captive demand for refinery off-gases and naphtha streams.
- Carbon capture utilization:Associated CO2 from gas processing can supply enhanced oil recovery operations in depleted onshore reservoirs.
Industry Challenges
- Specialized subsea engineering scarcity:Deepwater project execution depends on expatriate expertise and Nigerian Content Act localization timelines.
- Legacy infrastructure integrity:Decades-old trunk lines and flow stations require rehabilitation investment that competes with production growth capex.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nigeria Oil and Gas Market |
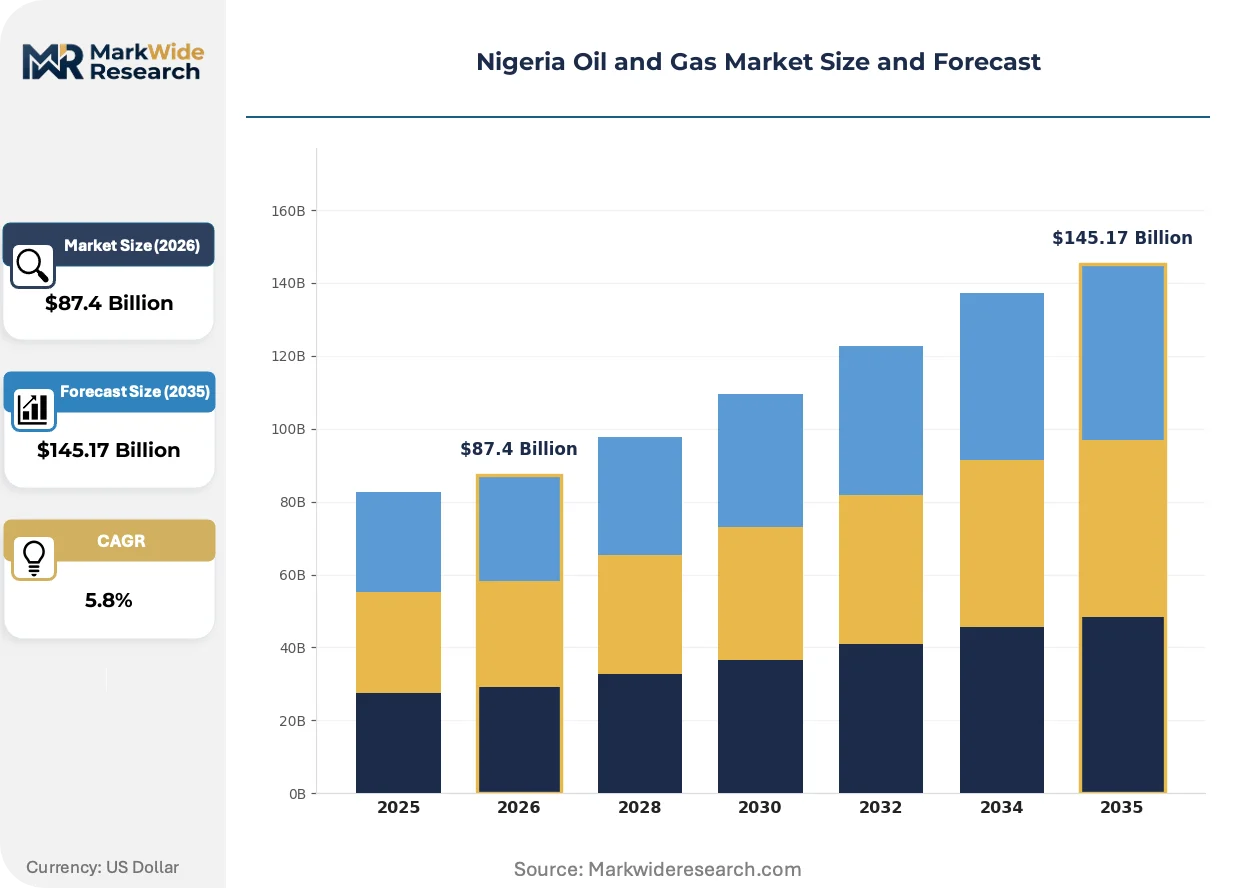
| Market Size in 2026 | $87.4 Billion |
| Market Size in 2035 | $145.17 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Exploration, Production, Refining, Transportation Technology: Upstream, Midstream, Downstream, Renewable End User: Power Plants, Industrial Users, Export Markets, Domestic Consumers Product Type: Cruude Oil, Natural Gas, LPG, Petrochemicals |
| Companies Covered | Exxon Mobil Corporation, Seplat Energy, Nigerian National Petroleum Corporation (NNPC), Dangote Petroleum Refinery, Oando, Shell Petroleum Development Company of Nigeria, TotalEnergies SE, Conoil, Chevron Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nigeria Oil and Gas Market Strategic Shifts
Digitalization and modular processing architectures are compressing development timelines, while regulatory restructuring forces operators to rebuild community relations frameworks and commercial contracting models.
Subsea tieback systems with standardized manifolds and wet gas compression are bifurcating deepwater development economics. International operators with stranded discoveries are deploying these configurations to fast-track production without fixed-platform capex. The technology is enabling marginal field clusters to achieve commerciality at sub-$40/breakeven thresholds.
The Nigerian Upstream Petroleum Regulatory Commission is enforcing flare gas commercialization regulations with metering and penalty structures. Operators must submit gas utilization plans or face production curtailment. Deepwater and offshore developments face the strictest compliance timelines due to higher associated gas ratios.
Power sector offtake agreements are shifting from take-or-pay to indexed spark-spread structures. Industrial buyers in Lagos and Port Harcourt corridors are negotiating tolling arrangements that transfer commodity risk. This restructuring is most advanced among cement and fertilizer manufacturers with captive power plants.
Nigeria Oil and Gas Market Segmentation
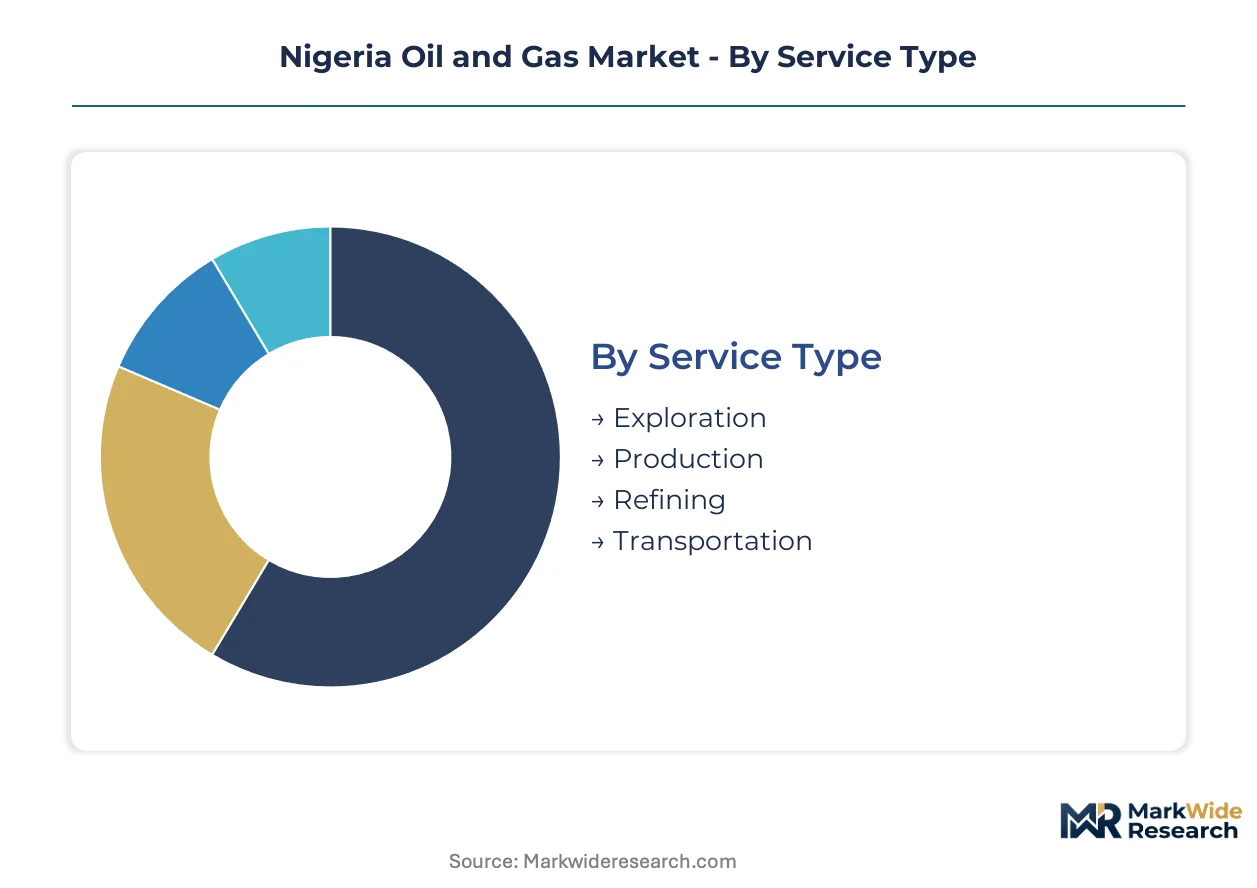
Segmentation in Nigeria's petroleum sector reveals how capital flows, regulatory obligations, and infrastructure constraints fragment opportunity across distinct operational layers. Each dimension—service delivery, technology application, end-use destination, and product specification—channels revenue through different risk-return profiles and partnership structures.
Service Type:
Exploration contracts flow through joint-venture frameworks with NNPC, while production services concentrate with indigenous operators acquiring divested assets. Refining and transportation segments channel through offtake agreements and pipeline tariffs respectively.
- Exploration:Seismic surveying, wildcat drilling, and reserve certification activities target underexplored deepwater blocks in the Bight of Benin. Demand clusters around international majors seeking material discoveries beyond mature Niger Delta basins, constrained by specialized subsea engineering scarcity and Nigerian Content Act localization timelines.
- Production:Reservoir management, artificial lift systems, and well intervention services extend field life in onshore and shallow-water assets. Indigenous operators like Seplat Energy concentrate acquisition and infill drilling here, capitalizing on international divestitures and lower breakeven thresholds at sub-$40/barrel.
- Refining:Crude processing into transportation fuels and distillates occurs at Dangote's integrated complex near Lagos and aging state facilities requiring rehabilitation. This segment channels through wholesale offtake contracts to petroleum product marketers.
- Transportation:Pipeline trunk systems, storage terminals, and marine logistics move hydrocarbons from Niger Delta production corridors to Lagos industrial clusters. Margins capture opportunities exist for operators serving structurally constrained midstream infrastructure.
Production dominates installed base. Refining is where expansion concentrates.
Technology:
Technology segmentation tracks where capital deployment meets regulatory compliance and resource quality—upstream commands revenue depth, downstream offers transformation velocity, while renewable integration remains nascent.
- Upstream:Exploration and production technologies encompass subsea tieback systems, standardized manifolds, and wet gas compression enabling marginal field commerciality. Applications concentrate in deepwater developments where floating production configurations reduce fixed-platform capital intensity.
- Midstream:Pipeline integrity management, metering systems, and gas processing facilities handle associated and non-associated gas streams. The Nigerian Midstream and Downstream Petroleum Regulatory Authority governs tariff structures and flare gas commercialization compliance.
- Downstream:Refining catalysts, hydrocracking units, and aromatics production support Dangote's petrochemical integration. Demand from cement and fertilizer manufacturers drives captive power and feedstock offtake negotiations.
- Renewable:Solar-hybrid installations and carbon capture utilization from gas processing feed enhanced oil recovery operations. Deployment remains limited by competing hydrocarbon investment returns and policy clarity on energy transition timelines.
Upstream technology anchors revenue generation. Downstream processing is climbing the fastest.
End User:
End-user segmentation distributes petroleum value across domestic energy security priorities and export revenue imperatives, with pricing structures varying by offtake certainty and foreign exchange exposure.
- Power Plants:Federal and state generation utilities procure natural gas under evolving contract structures—shifting from take-or-pay to indexed spark-spread arrangements. Combined-cycle turbine expansion creates anchor demand for domestic gas offtake from Niger Delta processing facilities.
- Industrial Users:Cement, fertilizer, and steel manufacturers in Lagos and Port Harcourt corridors negotiate tolling agreements transferring commodity price risk. Captive power plant investments by Dangote and BUA Group concentrate demand for reliable fuel supply.
- Export Markets:Bonny Light crude cargoes and LNG shipments generate foreign exchange for federation account allocation. European and Asian refiners prize the low-sulfur, high-API gravity specification.
- Domestic Consumers:LPG for cooking fuels and retail petroleum products serve household energy needs through subsidized pricing channels. Supply volatility persists due to import dependency and forex constraints.
Export markets dominate revenue contribution. Industrial users are gaining share fastest.
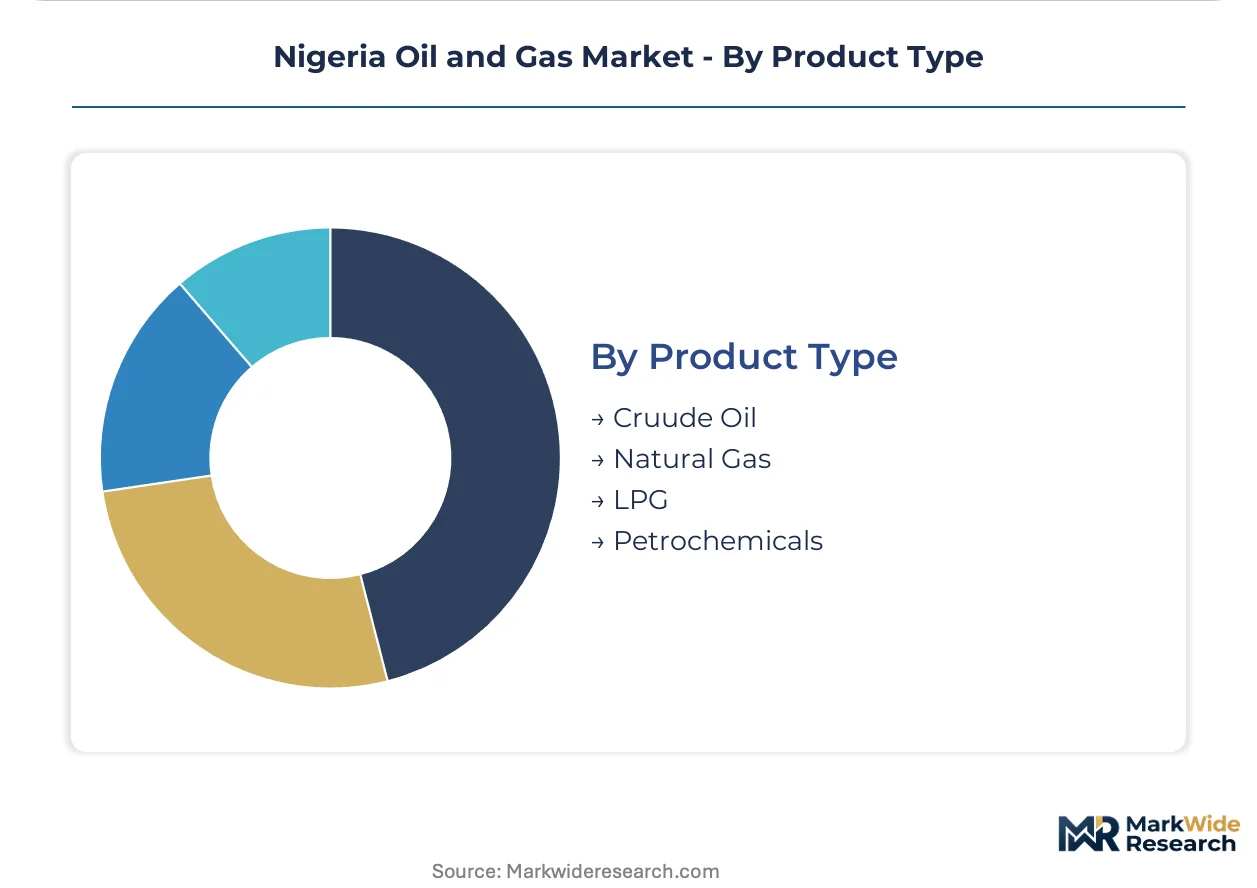
Product Type:
Product segmentation separates commodity flows by processing complexity and margin structure—crude and raw gas upstream, refined and derivative products downstream.
- Crude Oil:Bonny Light and related grades with API gravity of 37.3° and low sulfur content command premium pricing in Atlantic Basin markets. Production concentrates in Niger Delta onshore and shallow-water blocks with established evacuation infrastructure.
- Natural Gas:Associated gas from oil production and non-associated reserves from dedicated gas fields supply power generation and industrial feedstock. The Nigerian Upstream Petroleum Regulatory Commission enforces flare gas commercialization regulations with metering and penalty structures.
- LPG:Liquefied petroleum gas for domestic cooking and light industrial applications distributes through bottling plants and retail networks. Demand growth tracks urban household energy transition from biomass and kerosene.
- Petrochemicals:Aromatics, polypropylene, and refinery off-gas derivatives from Dangote's complex create captive integration opportunities. Feedstock supply agreements anchor downstream chemical manufacturing investments.
Crude oil dominates export volumes. Petrochemicals represent the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Nigeria commands pricing power over West African crude benchmarks while Ghana and Senegal struggle to match evacuation infrastructure scale, creating a regional asymmetry that concentrates export revenue in Lagos-anchored trading operations.
Niger Delta Production Corridor
Rivers and Bayelsa states host the bulk of onshore and shallow-water output, with Bonny Light crude loading at the Bonny Terminal. The Petroleum Industry Act mandates Host Community Development Trusts funded by operators, reducing vandalism risk in this historically volatile zone. Warri and Port Harcourt serve as logistics hubs for joint-venture operations between NNPC and international partners.
Lagos Industrial Cluster
Dangote Petroleum Refinery near Lekki Free Zone anchors downstream transformation, consuming crude feedstock for domestic fuel supply and petrochemical derivatives. The Nigerian Midstream and Downstream Petroleum Regulatory Authority oversees tariff structures for products moving via coastal tanker routes. Ibeju-Lekki's special economic zone status attracts gas-to-power investments from cement and fertilizer manufacturers.
Deepwater Bight of Benin
Offshore blocks beyond 200-meter depths hold underexplored reserves requiring subsea tieback configurations and floating production systems. The Nigerian Upstream Petroleum Regulatory Commission licenses these acreages under stricter flare gas commercialization timelines due to higher associated gas ratios. Expatriate engineering dependence complicates project execution despite Nigerian Content Act localization mandates.
North-Central Gas Processing Belt
Non-associated gas fields in Benue and Nasarawa states supply feedstock for power generation utilities expanding combined-cycle capacity. The Federal Ministry of Petroleum Resources coordinates domestic gas obligation frameworks linking upstream producers to grid-connected plants. Abuja's regulatory concentration shapes contracting standards for gas transmission pipelines serving industrial corridors southward.
South-East LPG Distribution Network
Enugu and Anambra states represent emerging demand centers for liquefied petroleum gas transitioning urban households from biomass cooking. Bottling plants and retail networks expand along Aba-Onitsha manufacturing corridors. State governments implement LPG penetration programs aligned with federal clean cooking initiatives, though supply volatility persists due to import dependency and forex constraints.
Nigeria Oil and Gas Market Competitive Environment
Concentration sits with state-affiliated and integrated majors controlling pipeline infrastructure and refining capacity, while indigenous operators fragment across marginal field production and downstream marketing tiers. International majors accelerate asset divestitures, transferring mature onshore blocks to local acquirers with lower cost structures. Two archetypes dominate: infrastructure-anchored national champions and acquisition-driven indigenous independents. Competitive moves center on portfolio rationalization through divestiture completion and downstream integration into petrochemical value chains.
Within the infrastructure-anchored tier, Nigerian National Petroleum Corporation represents state-commercial hybrid positioning following Petroleum Industry Act restructuring, while Dangote Petroleum Refinery anchors private downstream transformation. Among acquisition-driven independents, Seplat Energy exemplifies the indigenous operator archetype consolidating mature assets from international divestitures. These three entities occupy positions that concentrate strategic control across upstream joint ventures, midstream evacuation systems, and downstream refining capacity respectively.
| Leading Market Players |
|---|
| Exxon Mobil Corporation |
| Seplat Energy |
| Nigerian National Petroleum Corporation (NNPC) |
| Dangote Petroleum Refinery |
| Oando |
| Shell Petroleum Development Company of Nigeria |
| TotalEnergies SE |
| Conoil |
| Chevron Corporation |
| Others |
Value Chain & Pricing Dynamics
Sixty-to-ninety-day crude cargo lead times from wellhead to refinery gate concentrate pricing power with NNPC and integrated traders controlling storage and terminal access across the Niger Delta-to-Lagos corridor. Inventory positioning at Bonny Terminal and Dangote's Lekki complex shapes spot differentials against Brent benchmarks.
Pricing Analysis
The customization-premium spread between term-contract Bonny Light cargoes and spot-market distressed barrels runs wide. Long-term offtake agreements dominate, with price differentiation driven by API gravity certification and guaranteed delivery windows to European refiners. Cost compression in spot trading is intensifying because indigenous operators lack credit-backed trading lines. State refineries and small-scale marketers show highest price sensitivity; integrated majors with captive offtake show least.
Supply Chain Analysis
Nigeria and the United States anchor Bonny Light crude supply, with associated gas streams feeding domestic power plants. The supply chain draws from subsea wellheads, floating production units, and aging trunk pipelines. Single-source vulnerability concentrates in the Trans-Forcados and Trans-Niger pipeline systems. Distribution runs through coastal tanker routes to Lagos storage terminals and export loading buoys.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized subsea engineering capacity sits below deepwater project demand, creating persistent execution bottlenecks that favor operators with captive technical partnerships or training pipelines.
For Market Incumbents: Secure pipeline integrity management contracts before rehabilitation capex cycles peak. Lock in gas processing tolling agreements with Dangote's petrochemical complex to anchor downstream offtake. Threat: International majors accelerating divestitures transfer marginal fields to lower-cost indigenous competitors. Lever: Backward integration into gas-fired power generation through IPP structures. For New Entrants and Emerging Players: Differentiate on flare gas commercialization compliance and carbon capture integration to meet Nigerian Upstream Petroleum Regulatory Commission mandates. White-space targets: stranded gas fields in Nasarawa and Benue states requiring modular processing solutions. Most penetrable segment: LPG bottling and retail distribution in South-East urban corridors. Go-to-market angle: Partner with cement manufacturers for captive power fuel supply. For Investors and Strategic Acquirers: Carve-out targets emerge from international majors divesting mature onshore blocks with established reserves but high security overhead. Long-term viability hinges on operators' ability to transition from crude export dependence to domestic gas monetization and petrochemical feedstock supply. Acquisition archetype: Indigenous operators with proven community relations frameworks and sub-$40/barrel breakeven structures. Signal to watch: Completion timelines for Dangote refinery aromatics units as demand anchor for associated gas streams.| Strategic Initiative | Industry Significance |
|---|---|
| Host Community Development Trust Formation | Petroleum Industry Act mandates reduce vandalism risk and stabilize Niger Delta production corridors. |
| Flare Gas Commercialization Infrastructure | Nigerian Upstream Petroleum Regulatory Commission metering requirements force capital deployment toward gas processing. |
| Deepwater Subsea Tieback Deployment | Floating production configurations enable marginal field clusters at reduced capital intensity. |
| Petrochemical Feedstock Integration | Dangote's aromatics units create captive demand for refinery off-gases and naphtha streams. |
| Gas-to-Power Tolling Arrangements | Industrial buyers in Lagos and Port Har corridors negotiate spark-spread indexed contracts transferring commodity risk. |
Study Parameters
A standing panel of upstream petroleum engineers, midstream logistics coordinators, NNPC joint-venture managers, and power utility procurement officers provided ongoing calibration against field realities. Primary interview data combined with secondary validation from Nigerian Upstream Petroleum Regulatory Commission licensing records, Department of Petroleum Resources environmental compliance filings, and Nigerian National Petroleum Corporation annual activity reports. Bottom-up field-level production estimates triangulated against top-down federation account revenue allocations.
Consistency checks against external benchmarks validated volume and value outputs across the analysis window. Segmentation modeling incorporated service type, technology application, end-user category, and product specification dimensions. CAGRs derived from production decline curves, greenfield development timelines, and refining capacity absorption rates. Forecast inputs included international divestiture completion schedules and Dangote refinery utilization ramp assumptions.
Material uncertainties — regulatory implementation delays, pipeline sabotage frequency, and joint-venture cash-call resolution — sit outside the modeled envelope. Forecasts reflect assumptions about Petroleum Industry Act enforcement timelines and host community trust operationalization. Recalibration cycles align with material shifts in divestiture completion rates and domestic gas obligation fulfillment.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Open Hole Logging Services Market
Oil & Gas
Middle-East Oilfield Services Market
Oil & Gas
Operational Digital Oilfield Solution Market
Oil & Gas
Pumpjack Market
Oil & Gas
Oil and Gas Pipeline Management Software Market
Oil & Gas
Global Shale Gas Market
Oil & Gas
Kuwait Oil and Gas Market
Oil & Gas
Southeast Asia Oil and Gas Upstream Market
Oil & Gas
Middle-East and Africa Liner Hanger System Market
Oil & Gas
North America Completion Equipment and Services Market
Oil & Gas
Well Completion Equipment Service Market
Oil & Gas
Coiled Tubing Services Market
Oil & Gas
Perforating Gun Market
Oil & Gas
South Korea Oil and Gas Market
Oil & Gas
United States Liner Hanger System Market
Oil & Gas
Europe Well Intervention Market