
 Geothermal Drill Bits Market | 2026-2036
Geothermal Drill Bits Market Size, Share, and Industry Trends Forecast 2026-2036
Geothermal Drill Bits Market Analysis
Indonesia's Java-Bali corridor is fragmenting as national energy targets drive new drilling capacity. Schlumberger Limited leverages its integrated drilling services to anchor geothermal contracts across Southeast Asian volcanic basins. Halliburton Company sustains manufacturing scale through dedicated geothermal product lines. Baker Hughes Company differentiates via high-temperature directional drilling systems for supercritical resource zones.
Geothermal drill bits are purpose-engineered cutting tools manufactured from tungsten carbide substrates, synthetic diamond matrices, and hardened steel bodies, designed to penetrate igneous and metamorphic formations at temperatures exceeding 300°C while maintaining structural integrity under high-torsional loads. Their primary purpose is to create boreholes that enable steam or hot water extraction for electricity generation and direct-use thermal applications. PDC bits command margin pools in deep basalt drilling where thermal stability determines tool life, while roller cone bits retain dominance in fractured volcanic formations where impact resistance governs selection. Diamond bits occupy the fastest-growing tier in ultra-deep exploration targeting supercritical geothermal resources.
The EPA regulates geothermal drilling fluid disposal and induced seismicity monitoring under the Underground Injection Control program, while the EU Green Deal channels public finance toward projects meeting CE-marked equipment standards. Indonesia's national energy regulator mandates local content requirements for drilling contractors, reshaping procurement patterns for foreign bit suppliers. Stakeholders must monitor evolving certification thresholds for high-temperature tool performance as resource targets deepen.
Market Dynamics
Supercritical geothermal resource targeting below 4,000 meters is forcing bit manufacturers to re-engineer thermal stability specifications, as Indonesia's utility-scale operators and Kenya's Rift Valley developers race to access 400°C-plus reservoirs.
Growth Catalysts
- EU Green Deal financing:Public capital deployment under tightened F-Gas Regulation standards is accelerating procurement of CE-marked high-temperature drilling equipment across European volcanic zones.
- Basalt formation drilling:Polycrystalline diamond compact bit thermal stability advances are extending tool life in deep igneous penetration, reducing trip frequency for Indonesian steam-field developers.
- Kenya's Rift Valley corridor:Exploratory drilling intensity for steam-field development is concentrating demand for impact-resistant roller cone configurations in fractured volcanic formations.
Market Restraints
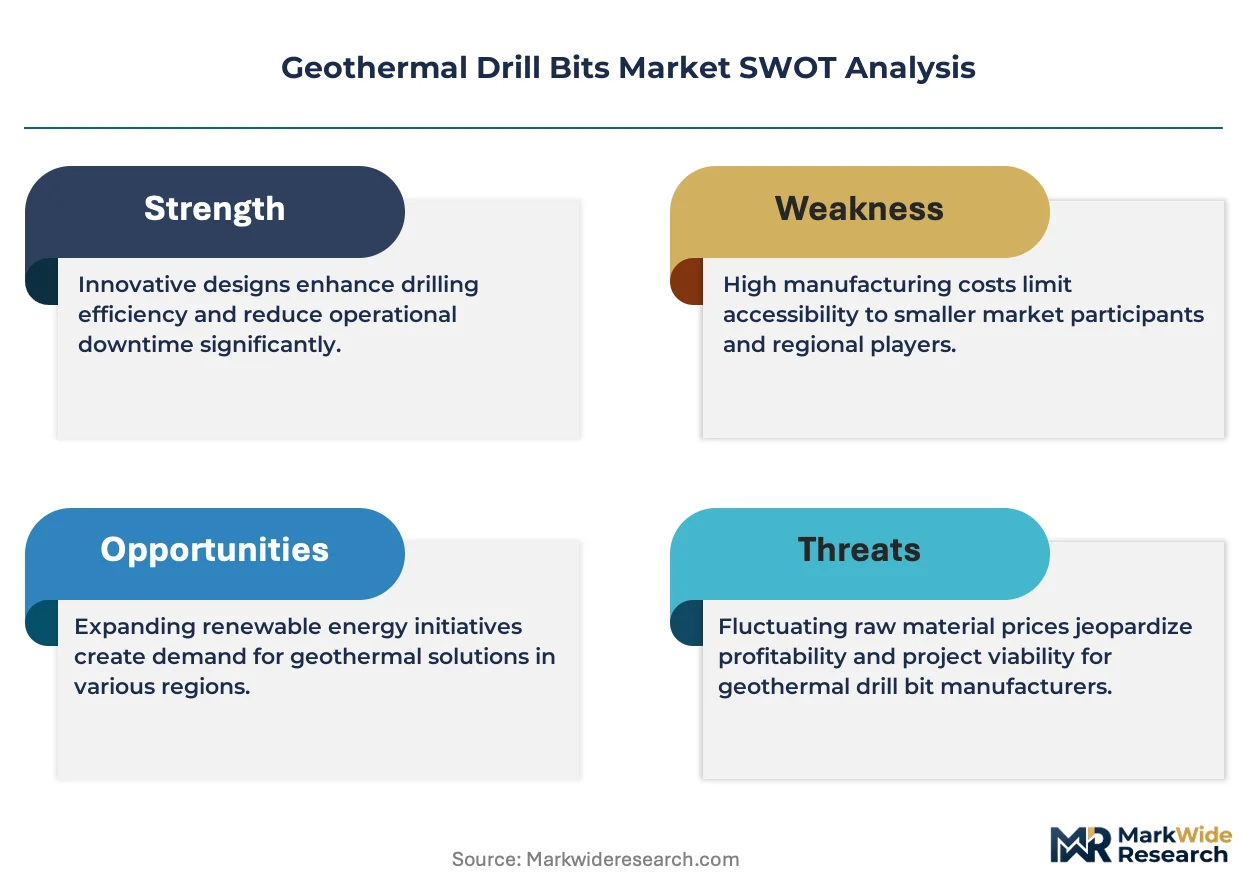
- Tungsten carbide supply concentration:Sintered substrate sourcing from limited metallurgical suppliers creates input cost volatility and delivery timeline risk for bit fabricators.
- Induced seismicity monitoring mandates:EPA Underground Injection Control program compliance adds procedural friction and extended permitting cycles for US-based drilling operations.
- Directional drilling complexity:Supercritical zone navigation requires high-temperature telemetry systems that remain technically immature above 350°C, constraining reachable resource depth.
Strategic Opportunities
- Ultra-deep exploration:Diamond-impregnated bit deployment for supercritical resource zones represents unclaimed white space as developers target 500°C reservoirs below 5,000 meters.
- Indonesian local content mandates:National energy regulator requirements for domestic drilling contractor participation are creating partnership pathways for foreign bit suppliers to establish in-country fabrication.
- Digital twin convergence:Real-time wear modeling fused with predictive analytics is enabling outcome-based bit performance contracts that shift revenue from unit sales to meters-drilled guarantees.
Industry Challenges
- High-temperature materials science talent:Synthetic diamond matrix bonding expertise and thermal degradation modeling capability scarcity constrains product development velocity.
- CE certification timelines:Extended validation cycles for equipment meeting EU Green Deal performance thresholds delay market entry for next-generation bit designs.
- Legacy rig compatibility:Advanced bit torque specifications often exceed older drill string capacity, forcing capital-intensive rig upgrades or limiting addressable installed base.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Geothermal Drill Bits Market |
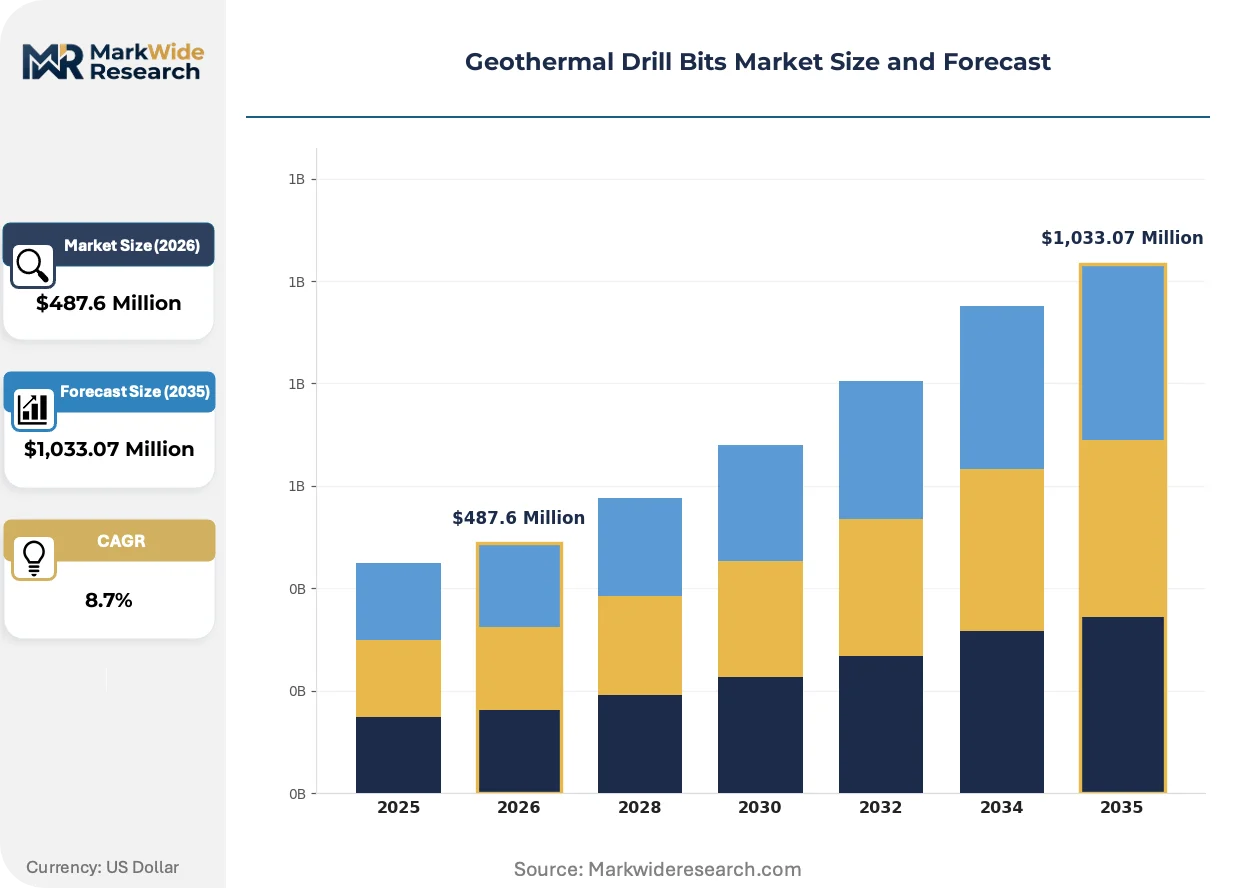
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,033.07 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diamond Bits, Roller Cone Bits, PDC Bits, Core Bits Application: Power Generation, District Heating, Exploration, Environmental End User: Energy Companies, Drilling Contractors, Mining Operators, Government Agencies Technology: Conventional Drilling, Advanced Drilling, Directional Drilling, Hot Dry Rock |
| Companies Covered | Schlumberger Limited, Halliburton Company, Baker Hughes Company, NOV Inc., Epiroc AB, Atlas Copco AB, Varel International Energy Services, Weatherford International plc, America West Drilling Supply Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Geothermal Drill Bits Market Emerging Trajectories
Digital instrumentation embedded at the cutting face is virtualizing how operators monitor bit condition, compressing decision cycles from days to hours and enabling predictive rather than reactive tool management.
Real-time downhole sensor arrays are virtualizing formation evaluation by transmitting temperature, vibration, and wear data continuously rather than relying on post-trip inspection. Indonesian utility operators are deploying these systems in Java-Bali corridor basalt drilling. This capability is virtualizing maintenance scheduling, shifting from fixed-hour replacement to condition-based intervention that extends average bit runs by eliminating premature pulls.
The EU F-Gas Regulation is tightening equipment standards for geothermal projects by mandating leak-proof cooling systems and phased hydrofluorocarbon reduction in drilling fluid temperature management. European manufacturers are redesigning bit body cooling channels to accommodate alternative refrigerants. Supercritical exploration programs in Italy's Tuscany fields and Iceland's Reykjanes peninsula are experiencing the steepest compliance cost adjustments.
Integrated drilling service bundling is displacing standalone bit procurement as Indonesian national energy targets fragment the Java-Bali contractor landscape. Operators now specify performance-based contracts where Schlumberger and Halliburton retain tool selection authority rather than purchasing bits separately. Kenya's Rift Valley independent developers remain the exception, continuing discrete procurement for smaller exploratory programs where capital constraints prevent full-service contracting.
Geothermal Drill Bits Market Segmentation
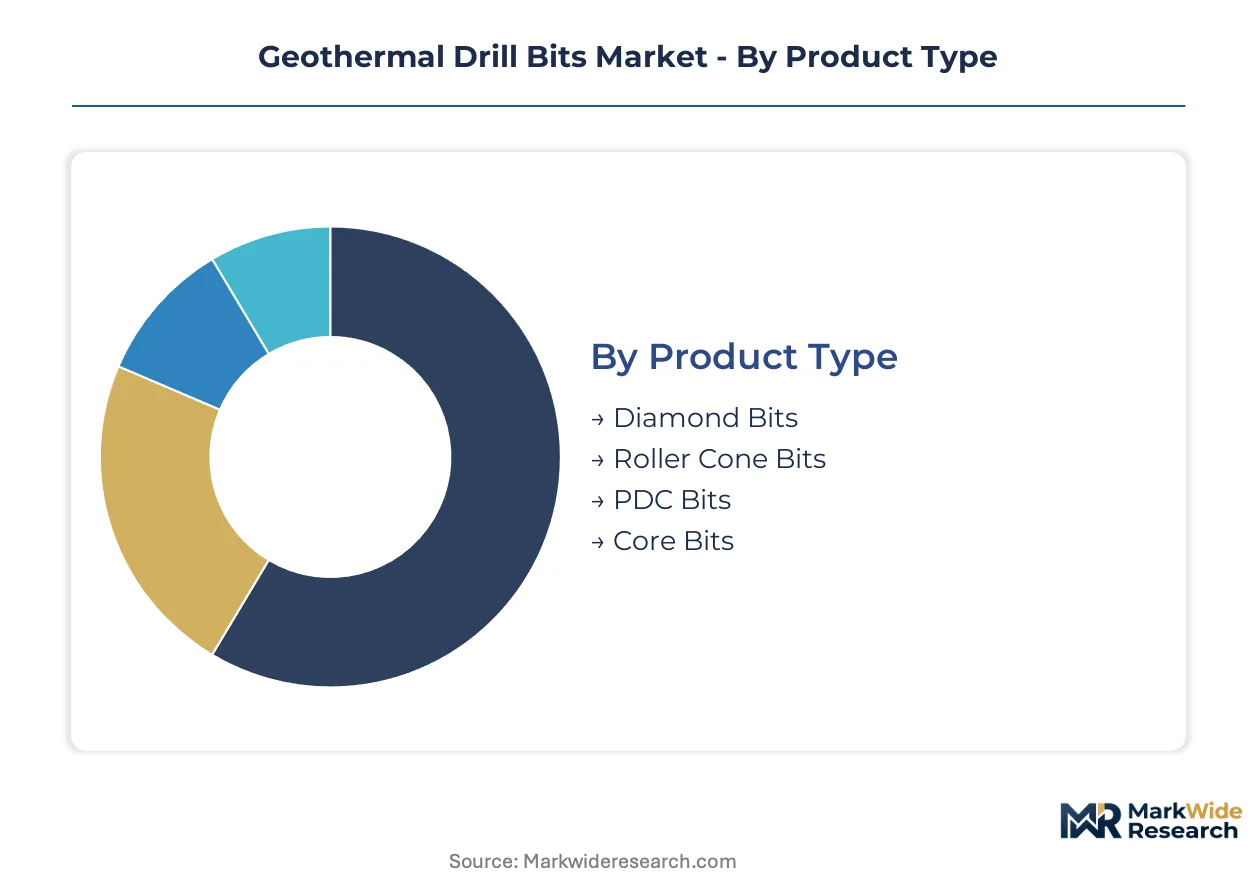
Geothermal drill bit procurement patterns diverge sharply across product configurations and deployment contexts. After-sales service intensity varies by segment, with advanced directional systems demanding continuous telemetry support while conventional roller cone bits require minimal field engineering.
Product Type:
After-sales service intensity peaks with diamond-impregnated and PDC configurations, where thermal degradation monitoring and cutter replacement scheduling generate recurring revenue streams for suppliers.
- Diamond Bits:Synthetic diamond matrices bonded to tungsten carbide substrates penetrate ultra-hard igneous formations at temperatures exceeding 400°C. Demand concentrates in Iceland's Reykjanes peninsula and Italy's Tuscany fields where supercritical exploration targets 500°C reservoirs below 5,000 meters, though thermal stability validation cycles extend CE certification timelines.
- Roller Cone Bits:Hardened steel cones with tungsten carbide inserts deliver impact resistance in fractured volcanic formations. Procurement clusters in Kenya's Rift Valley corridor where exploratory drilling for steam-field development favors three-cone configurations in highly fractured basalt, with bit life governed by bearing seal integrity under high-torsional loads.
- PDC Bits:Polycrystalline diamond cutters on tungsten carbide substrates dominate deep basalt penetration where thermal stability determines tool life.
- Core Bits:Annular diamond-impregnated designs retrieve continuous formation samples for reservoir characterization.
Roller cone bits hold the largest share; momentum sits with diamond bits.
Application:
Cost tier stratification separates utility-scale power generation from exploratory programs, with the former absorbing premium pricing for guaranteed performance contracts.
- Power Generation:Utility-scale operators in Indonesia's Java-Bali corridor deploy advanced PDC and diamond configurations for production well drilling where trip frequency directly impacts plant commissioning schedules. Procurement runs through integrated service contracts with Schlumberger and Halliburton retaining tool selection authority rather than discrete bit purchases.
- District Heating:Shallow resource development in European volcanic zones—particularly Iceland and Turkey—employs roller cone bits for doublet well completion where capital constraints favor proven technology over experimental supercritical targeting.
- Exploration:Wildcat drilling programs prioritize durability over cutting efficiency given uncertain reservoir conditions.
- Environmental:Ground-source heat pump boreholes utilize small-diameter core bits in sedimentary overburden.
Power generation commands the deepest wallet share; exploration is climbing the fastest.
End User:
Customer type determines procurement sophistication, with integrated energy companies leveraging performance-based contracting while independent contractors optimize unit economics.
- Energy Companies:State-owned utilities in Indonesia and Kenya specify outcome-based contracts where suppliers guarantee meters drilled rather than delivering tools alone. Pertamina Geothermal Energy and KenGen anchor volume, bundling bit procurement within integrated drilling services that shift technical risk to contractors.
- Drilling Contractors:Independent operators in Kenya's Rift Valley maintain discrete procurement relationships for exploratory programs where capital constraints prevent full-service contracting, favoring roller cone bits with predictable wear patterns.
- Mining Operators:Diversified resource companies repurpose hard-rock drilling expertise for geothermal co-production.
- Government Agencies:Public research institutions in Iceland and Japan fund supercritical demonstration projects.
Energy companies dominate absolute spend; drilling contractors represent the steepest expansion trajectory.
Technology:
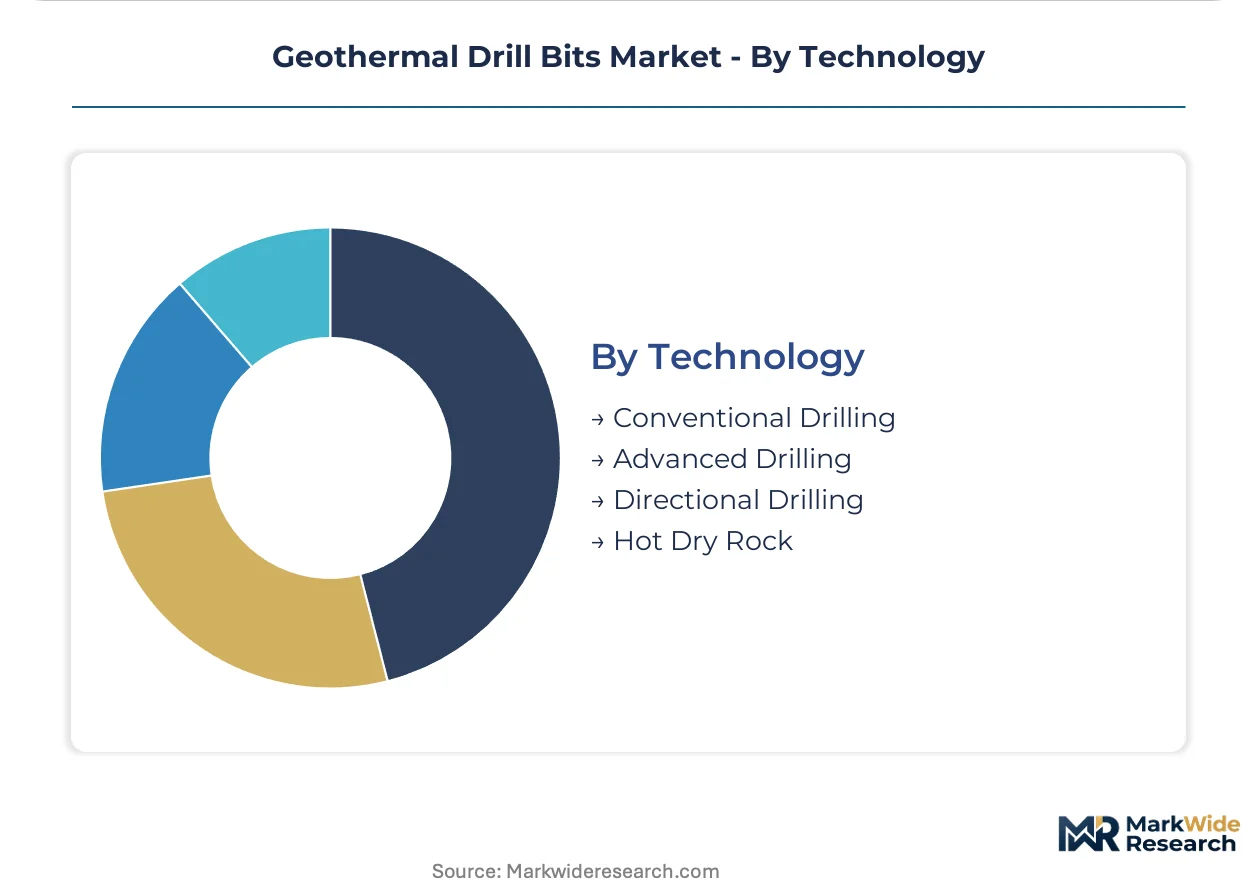
Technology maturity curves separate proven conventional methods from experimental supercritical targeting, with directional drilling occupying the commercial sweet spot.
- Directional Drilling:High-temperature telemetry systems enable navigation of deviated wellbores in Indonesia's fractured volcanic reservoirs, though sensor reliability degrades above 350°C constraining reachable depth. Baker Hughes differentiates via proprietary high-temperature directional systems for supercritical zones.
- Hot Dry Rock:Engineered geothermal systems requiring artificial reservoir stimulation deploy specialized bits for crystalline basement penetration, with pilot programs in Japan's Hijiori field and France's Soultz-sous-Forêts testing thermal shock resistance.
- Conventional Drilling:Vertical well completion in shallow sedimentary basins employs standard roller cone configurations.
- Advanced Drilling:Hybrid bit designs combining PDC and diamond elements target transitional formations.
Conventional drilling retains the widest installed base; hot dry rock is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indonesia's national energy regulator anchors procurement patterns across Southeast Asian volcanic basins, while Kenya's Rift Valley corridor concentrates exploratory drilling intensity. The EU Green Deal channels public finance toward European geothermal zones, reshaping equipment standards from Iceland to Italy.
Indonesia
Utility-scale operators in the Java-Bali corridor are expanding procurement of advanced PDC and diamond configurations. The national energy regulator mandates local content requirements for drilling contractors, forcing foreign suppliers toward in-country partnerships. Pertamina Geothermal Energy anchors volume in the volcanic arc stretching from Sumatra to Sulawesi.
Kenya
KenGen and independent developers are intensifying exploratory drilling across the Rift Valley corridor for steam-field expansion. Impact-resistant roller cone bits dominate procurement in fractured volcanic formations where bearing seal integrity governs selection. The Olkaria and Menengai fields concentrate operational deployment.
United States
The EPA Underground Injection Control program regulates drilling fluid disposal and induced seismicity monitoring, adding procedural friction to permitting cycles. Geothermal development clusters in Nevada's Great Basin and California's Imperial Valley, where supercritical exploration targets deep basalt formations below 4,000 meters.
Iceland
The EU F-Gas Regulation mandates leak-proof cooling systems and hydrofluorocarbon reduction in drilling fluid temperature management. The Reykjanes peninsula hosts supercritical demonstration projects testing diamond-impregnated bits for 500°C reservoirs. CE certification timelines for high-temperature equipment extend market entry for next-generation designs.
Italy
Public finance under tightened EU Green Deal standards accelerates procurement of CE-marked high-temperature drilling equipment. Tuscany's Larderello-Travale field represents Europe's oldest geothermal district, now targeting ultra-deep exploration below 5,000 meters. Manufacturers are redesigning bit body cooling channels to accommodate alternative refrigerants.
Geothermal Drill Bits Market Vendor Landscape
Integrated energy service providers and specialized bit fabricators split the market along the bundling-versus-specialization axis. The vendor base concentrates around three strategic archetypes: full-service drilling contractors retaining tool selection authority, dedicated geothermal product line manufacturers, and directional drilling system specialists. Dominant competitive moves include integrated service bundling displacing standalone procurement and in-country fabrication partnerships satisfying local content mandates.
Among Houston-based energy service conglomerates, Schlumberger Limited, Halliburton Company, and Baker Hughes Company exemplify the full-service archetype. These entities anchor geothermal contracts across Southeast Asian volcanic basins through performance-based agreements where technical risk shifts to contractors. Baker Hughes occupies a differentiated position within this tier via proprietary high-temperature directional systems targeting supercritical zones. The trio collectively represents the procurement pathway that Indonesian utility-scale operators now specify, displacing discrete bit purchases with meters-drilled guarantees.
| Leading Market Players |
|---|
| Schlumberger Limited |
| Halliburton Company |
| Baker Hughes Company |
| NOV Inc. |
| Epiroc AB |
| Atlas Copco AB |
| Varel International Energy Services |
| Weatherford International plc |
| America West Drilling Supply Inc. |
| Others |
Supply Flow & Price Mechanics
Houston's energy service corridor anchors global bit fabrication capacity, concentrating thermal stability engineering expertise that translates directly into pricing power for supercritical-grade configurations. Tungsten carbide substrate sourcing from limited metallurgical suppliers creates input cost volatility that propagates downstream, compressing margins for standard roller cone tiers while insulating premium diamond-impregnated lines.
Pricing Analysis
Price spreads between CE-certified supercritical bits and conventional roller cone configurations widen as EU Green Deal compliance costs accumulate. Three-tier pricing structure across premium diamond-impregnated, standard PDC, and economy roller cone levels reflects certification grade and thermal stability specifications. Cost compression in economy tiers is intensifying because Indonesian local content mandates force foreign suppliers toward partnership structures that erode margin capture. Independent drilling contractors in Kenya's Rift Valley exhibit highest price sensitivity, while Indonesian state utilities absorb premium positioning through integrated service contracts.
Supply Chain Analysis
Export controls on synthetic diamond matrix bonding technology limit flow of supercritical-grade fabrication equipment from US and European suppliers to Asian manufacturing partners. Sintered tungsten carbide substrates draw from concentrated metallurgical capacity in Germany, China, and the United States. Single-source vulnerability sits with synthetic diamond grit suppliers, where De Beers-alternative sourcing remains technically immature for 400°C-plus thermal specifications. Distribution runs through integrated drilling service bundling that displaces standalone bit procurement, particularly across Indonesian utility-scale contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Supercritical geothermal targeting below 5,000 meters is forcing a capability disruption that rewards thermal stability engineering investments and penalizes commodity-grade positioning. The EU F-Gas Regulation and Indonesian local content mandates together compress timeline and sourcing flexibility for unprepared participants.
For Market Incumbents: Harden thermal stability validation capabilities to extend CE certification lead times into competitive moats against emerging Asian fabricators. Deepen backward integration into synthetic diamond matrix production to offset tungsten carbide supply concentration. Anchor integrated service contracts across Indonesian utility-scale operators before local partnership requirements fragment procurement pathways. For New Entrants and Emerging Players: Establish a beachhead in Kenya's Rift Valley independent drilling contractor segment, where discrete procurement persists and capital constraints prevent full-service contracting adoption. Target roller cone refurbishment and bearing seal replacement services as entry vectors before advancing to PDC thermal stability engineering. Leverage digital twin predictive analytics as differentiated service bundling against incumbent unit-sales models. For Investors and Strategic Acquirers: Long-term, this sits as a materials-science scarcity play because synthetic diamond matrix bonding expertise and thermal degradation modeling capability constrain product development velocity across the vendor base. Acquisition targets should display captive tungsten carbide sourcing or established CE certification pipelines. Watch supercritical demonstration project commissioning rates in Iceland's Reykjanes peninsula as inflection signal for diamond-impregnated bit demand scaling.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Synthetic Diamond Production | Captive matrix bonding capability insulates margin compression from tungsten carbide volatility. |
| CE Certification Pipeline Investment | Accelerated validation cycles capture EU Green Deal financing deployment in Tuscany and Reykjanes fields. |
| Indonesian In-Country Fabrication Partnership | Local content mandate compliance secures utility-scale procurement access across Java-Bali corridor. |
| Digital Twin Performance Contracting | Meters-drilled guarantees shift revenue model from unit sales to outcome-based recurring streams. |
| Supercritical Telemetry System Development | 350°C-plus sensor reliability unlocks 5,000-meter reservoir targeting in Indonesia and Kenya. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of regulatory filings, trade customs data, and project development databases to construct bottom-up bit procurement estimates and top-down market sizing. Primary interviews engaged drilling contractors, geothermal utility procurement officers, EPC project managers, and bit manufacturer product line directors across Indonesia, Kenya, Iceland, and Italy. Secondary validation drew from EPA Underground Injection Control program disclosures, EU F-Gas Regulation implementation guidance, and Indonesian national energy regulator local content mandates.
Forecast inputs incorporate drilling intensity projections by reservoir type, technology substitution curves between roller cone and diamond configurations, and regulatory compliance cost trajectories. Segmentation modeling spans product type, application tier, end-user procurement sophistication, and technology maturity across the projection horizon. CAGRs derive from weighted average of bottom-up unit demand and top-down value capture, with supercritical exploration program announcements and CE certification timeline data as industry-specific demand signals.
Stress conditions across tungsten carbide price volatility, Indonesian local content enforcement intensity, and supercritical telemetry technical maturity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding EU Green Deal financing continuity and EPA regulatory stability. Material shifts in export control regimes for synthetic diamond matrix technology or breakthroughs in 400°C-plus sensor reliability would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Russian Federation Oil and Gas Midstream Market
Oil & Gas
Canada Oil and Gas Pipeline Services Market
Oil & Gas
Romania Oil and Gas Upstream Market
Oil & Gas
Middle-East Enhanced Oil Recovery Market
Oil & Gas
Operational Digital Oilfield Solution Market
Oil & Gas
Dry Natural Gas Market
Oil & Gas
Australia Oil and Gas Upstream Market
Oil & Gas
GCC Oil and Gas Separation Market
Oil & Gas
Gulf of Mexico Oil and Gas Midstream Market
Oil & Gas
Qatar Oilfield Chemicals Market
Oil & Gas
Drilling Mud Desander and Desilter Market
Oil & Gas
Frac Tree Market
Oil & Gas
Oil and Gas Infrastructure Market
Oil & Gas
Digital Oilfield Market
Oil & Gas
Underwater Monitoring System for Oil and Gas Market
Oil & Gas
Europe Oilfield Equipment Rental Services Market