
 Rigless Intervention Systems Sales Market | 2026-2036
Rigless Intervention Systems Sales Market Size, Share, and Industry Trends Forecast 2026-2036
Rigless Intervention Systems Sales Market Insights
Buyer concentration among supermajor oil and gas operators is expanding as portfolio rationalization leaves fewer but larger procurement entities negotiating framework contracts for rigless services. Baker Hughes Company leverages its integrated coiled tubing and wireline portfolio to anchor long-term master service agreements with these consolidated buyers. Schlumberger Limited competes through technology leadership in intelligent completion interventions, while Halliburton sustains geographic dominance across North American land and offshore markets with its hydraulic workover capabilities.
Rigless Intervention Systems encompass surface-deployed equipment enabling wellbore access, stimulation, and remediation without removing the production tree or mobilizing a drilling rig, typically operating at pressures up to 15,000 psi through snubbing or coiled tubing conveyance. Their primary purpose is restoring or enhancing hydrocarbon flow from live wells at substantially lower cost and operational footprint than rig-based alternatives. Coiled tubing equipment occupies the largest installed base due to versatility across milling, logging, and nitrogen lift applications, while automated technology segments are recording the fastest growth as remote-operated systems reduce personnel exposure in high-pressure environments. Well remediation services generate the most recurring revenue, though stimulation demand fluctuates with commodity price cycles.
The US Bureau of Safety and Environmental Enforcement mandates mechanical integrity testing schedules that directly increase intervention frequency on Gulf of Mexico platforms, while the EPA's offshore discharge regulations shape chemical selection for stimulation and remediation fluids. API RP 17G and ISO 13628-7 provide equipment qualification standards that create compliance barriers for new entrants but assure buyer confidence in subsea intervention tool reliability. Stakeholders must monitor how electrification of intervention systems interacts with evolving offshore power infrastructure and carbon intensity accounting frameworks.
Market Dynamics
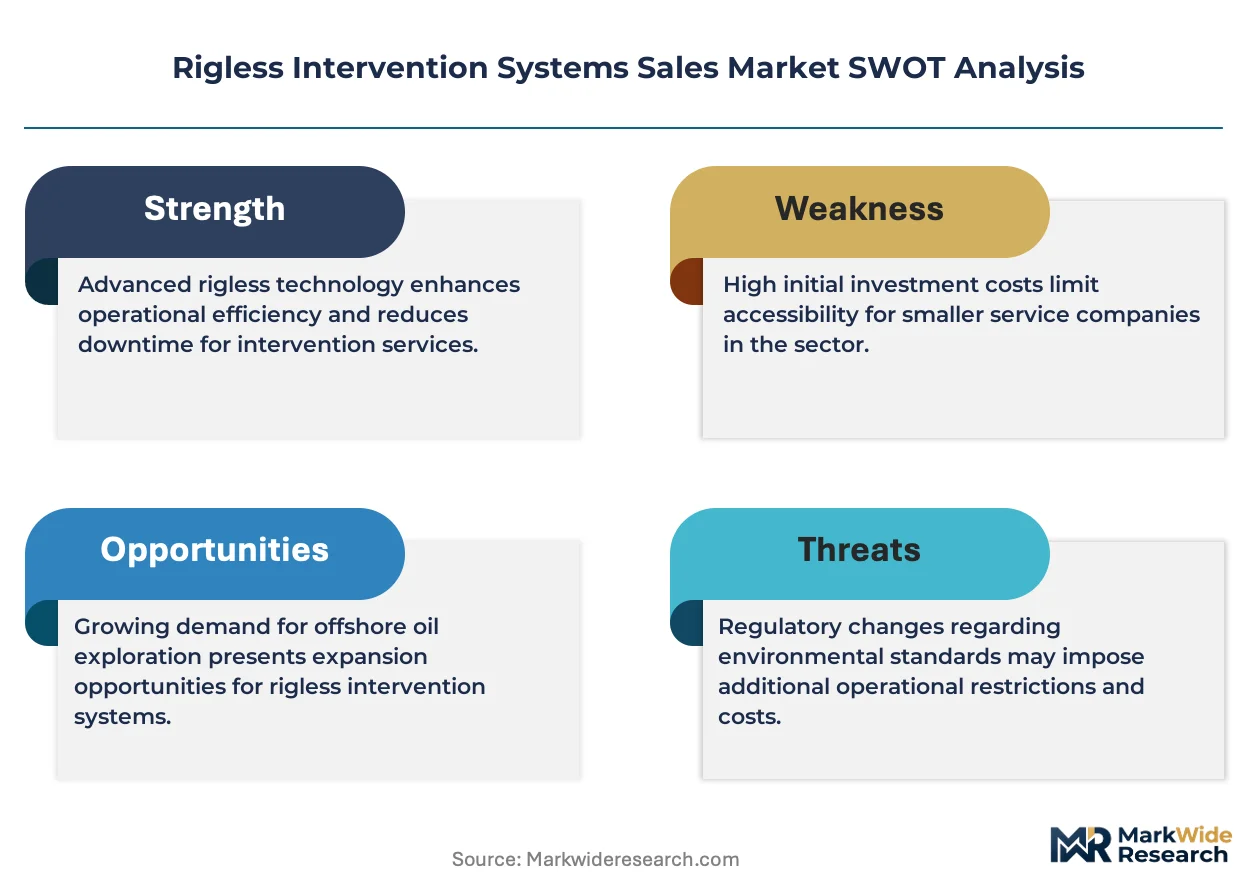
Supermajor procurement consolidation is compressing vendor margins while elevating technical qualification barriers, as fewer buyers negotiate multi-year framework contracts demanding integrated service capabilities across coiled tubing, wireline, and hydraulic workover disciplines.
Growth Catalysts
- US Bureau of Safety and Environmental Enforcement integrity mandates:Mechanical testing schedules for Gulf of Mexico platforms directly expand intervention frequency, creating recurring demand for through-tubing verification services.
- Offshore brownfield decommissioning deferral:North Sea and Gulf of Mexico operators deploy rigless systems to extend platform life and delay multi-billion dollar abandonment liabilities.
- Automated remote intervention systems:Robotics and remote-operated tooling reduce personnel exposure in 15,000 psi environments, accelerating adoption across high-pressure subsea applications.
Market Restraints
- Specialized alloy supply concentration:High-grade chromium steel for coiled tubing strings concentrates among a limited set of European and Japanese metallurgical suppliers, creating input cost volatility.
- API RP 17G compliance barriers:Subsea intervention tool qualification standards require extensive third-party verification, extending new entrant time-to-market by 18-24 months.
- Rig-based workover substitution in shallow water:Low day-rate jackup rigs in mature basins like the US Gulf shelf undercut rigless economics for simple recompletion operations.
Strategic Opportunities
- CCUS well intervention emergence:Carbon storage site operators require rigless abandonment and monitoring services, opening a new service category with limited incumbent competition.
- Electrification convergence with offshore power infrastructure:Battery-powered intervention systems align with platform electrification trends and carbon intensity accounting frameworks in the North Sea.
- West Africa deepwater expansion:Pre-salt developments off Angola and Nigeria lack mature rigless service infrastructure, creating first-mover positioning for integrated providers.
Industry Challenges
- High-pressure snubbing technician scarcity:Specialized live-well handling skills require years of apprenticeship, constraining fleet expansion despite equipment availability.
- Legacy subsea tree interface incompatibility:Decades-old hardware across the Gulf of Mexico lacks standardized intervention access points, forcing costly custom tool development per installation.
- ISO 13628-7 recertification timelines:Equipment requalification cycles disrupt deployment scheduling and tie up capital in non-revenue testing phases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rigless Intervention Systems Sales Market |
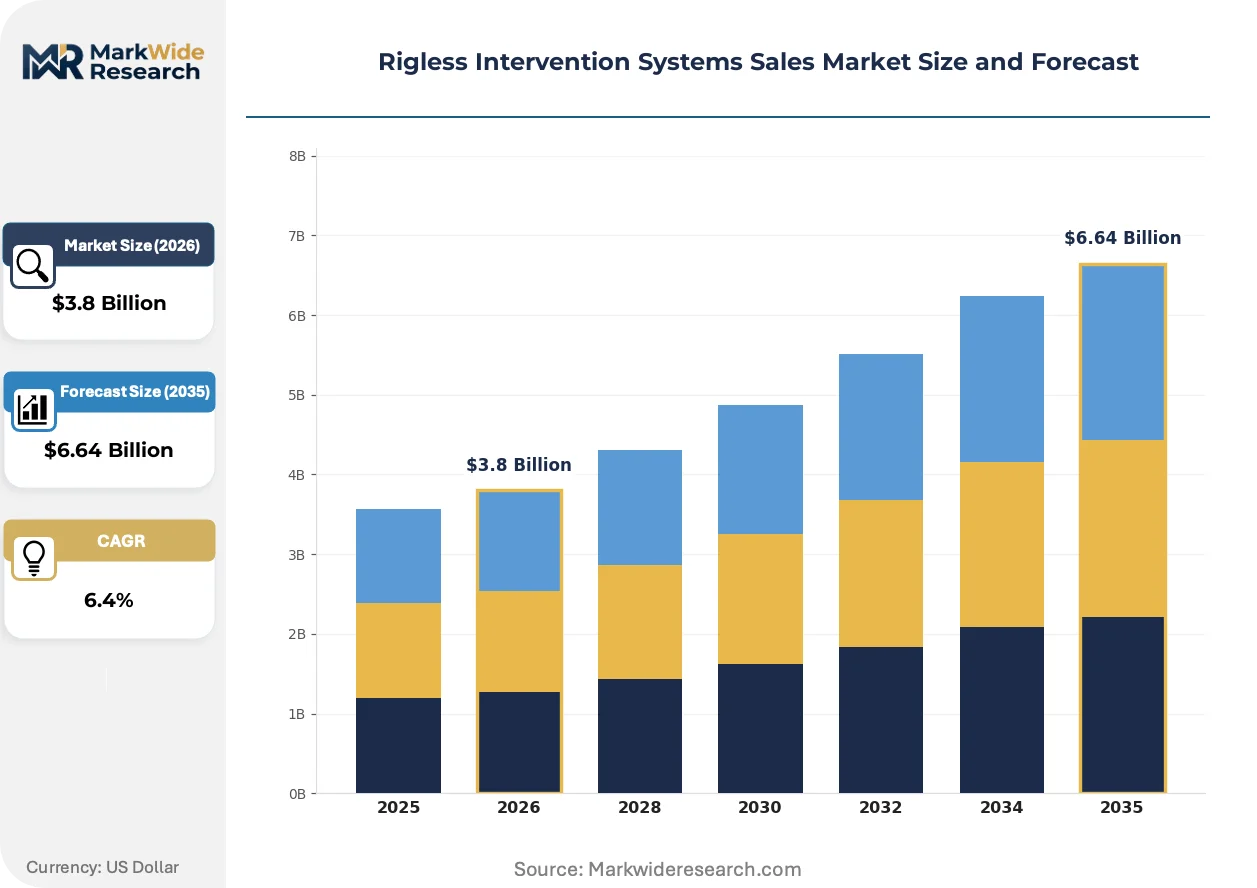
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
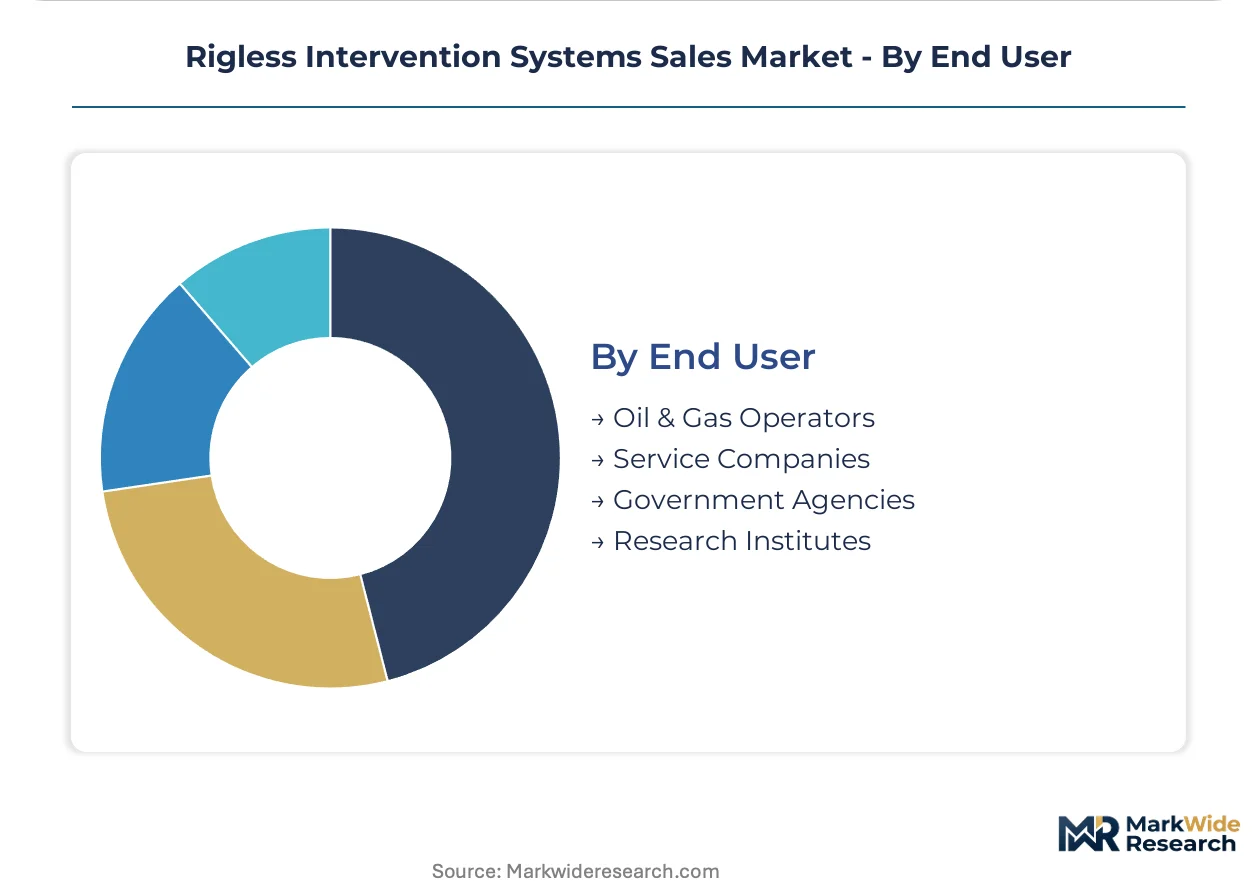
| Segmentation | Equipment Type: Coiled Tubing, Wireline, Snubbing, Hydraulic Workover Technology: Mechanical, Electrical, Hybrid, Automated Service Type: Well Remediation, Stimulation, Maintenance, Inspection End User: Oil & Gas Operators, Service Companies, Government Agencies, Research Institutes |
| Companies Covered | Baker Hughes Company, Schlumberger Limited, Weatherford, Halliburton, Oceaneering International, Inc., EFC Group Ltd, Expro Group Holdings N.V., Acteon Group Ltd., Aker Solutions, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rigless Intervention Systems Sales Market Trends and Innovations
Digitalization of intervention planning and execution is compressing operational timelines while remote capabilities reduce offshore headcount requirements. These shifts are redefining competitive advantage around data integration rather than equipment scale alone.
Intelligent coiled tubing with embedded fiber-optic sensing is absorbing real-time downhole monitoring functions previously requiring separate wireline runs. Offshore operators in the Gulf of Mexico and North Sea are deploying these strings for continuous pressure and temperature profiling during stimulation operations. The technology is absorbing discrete service line revenues into unified intervention packages, pressuring pure-play wireline providers.
The US Bureau of Safety and Environmental Enforcement has tightened incident reporting thresholds for well control events, forcing operators to upgrade blowout preventer testing protocols. This regulatory pressure accelerates replacement of conventional snubbing stacks with closed-loop systems featuring redundant shear capabilities. Gulf of Mexico platform operators now prioritize intervention packages with pre-certified BOP configurations to minimize regulatory downtime.
Framework contracting with integrated service providers is displacing single-tool callout arrangements among supermajor buyers. Procurement teams negotiate multi-year master service agreements bundling coiled tubing, wireline, and hydraulic workover capacity with guaranteed utilization floors. This consolidation concentrates in the US Gulf Coast and North Sea, where portfolio rationalization has left fewer but larger decision-making entities.
Rigless Intervention Systems Sales Market Segmentation

Equipment configuration and service bundling decisions in rigless intervention directly determine project economics and regulatory compliance across offshore and onshore deployments. Technology selection shapes workforce requirements, while end-user procurement consolidation is compressing vendor specialization into integrated service portfolios.
Equipment Type:
Replacement cycles for high-pressure intervention equipment accelerate where US Bureau of Safety and Environmental Enforcement integrity mandates tighten mechanical testing schedules.
- Coiled Tubing:Continuous steel or composite tubing strings enable milling, logging, and nitrogen lift operations through live wellbores at pressures up to 15,000 psi. Gulf of Mexico operators deploy these systems for through-tubing verification services where platform decommissioning deferral drives intervention frequency.
- Wireline:Electric cable conveyance systems deliver downhole logging, perforating, and plug-setting functions with minimal surface footprint. North Sea brownfield operators favor wireline for subsea tree interventions where remote-operated deployment reduces personnel exposure.
- Snubbing:Live-well pipe handling using surface-mounted stripping assemblies enables tubing installation against well pressure.
- Hydraulic Workover:Rigless pulling and running of tubulars using hydraulic jacks addresses heavier completion strings beyond coiled tubing capacity.
Volume placements concentrate in Coiled Tubing; the faster expansion belongs to Hydraulic Workover.
Technology:
Cost tier differentiation separates basic mechanical systems from premium automated packages where labor substitution justifies capital intensity.
- Mechanical:Conventional hydraulically-actuated intervention tools rely on surface pump pressure and manual valve operation without electronic control systems. Mature basins with simple recompletion economics favor these configurations where low day-rate alternatives compete.
- Automated:Remote-operated robotics and closed-loop control systems execute intervention sequences from onshore control centers, eliminating offshore personnel in 15,000 psi environments. Gulf of Mexico supermajors prioritize these packages following tightened well control incident reporting thresholds.
- Electrical:Battery-powered and electrically-actuated tooling aligns with platform electrification and carbon intensity accounting frameworks.
- Hybrid:Combined mechanical-electrical architectures balance reliability with selective automation for mid-pressure applications.
Customer procurement concentrates in Mechanical systems; the steepest expansion trajectory belongs to Automated.
Service Type:
Application maturity varies sharply between recurring integrity verification and cyclical stimulation demand tied to commodity price volatility.
- Well Remediation:Restoration of hydrocarbon flow through scale removal, sand cleanout, and mechanical repair generates recurring revenue streams. US Gulf Coast operators contract these services under multi-year master service agreements with guaranteed utilization floors.
- Stimulation:Acidizing, fracturing, and nitrogen lift operations enhance reservoir permeability but fluctuate with oil price cycles and capital allocation priorities.
- Maintenance:Scheduled mechanical integrity testing and tree valve exercising prevents unplanned shutdowns on producing platforms.
- Inspection:Downhole diagnostic logging and corrosion monitoring satisfies regulatory verification requirements without production interruption.
Revenue concentration sits with Well Remediation; Inspection services are gaining share fastest.
End User:
Customer type determines contract structure, technical specification depth, and qualification barriers for equipment suppliers.
- Oil & Gas Operators:Supermajor and independent producers negotiate framework contracts bundling multiple intervention disciplines, consolidating vendor relationships. These buyers drive API RP 17G compliance requirements and pre-certified BOP configuration demands.
- Service Companies:Specialist contractors and integrated providers procure intervention equipment for fleet expansion and technology refresh programs.
- Government Agencies:State-owned petroleum enterprises and regulatory bodies acquire intervention capacity for strategic reserve management and enforcement verification.
- Research Institutes:Academic and national laboratory facilities source specialized equipment for CCUS well intervention methodology development.
Procurement volume concentrates among Oil & Gas Operators; Research Institutes represent the fastest-climbing customer category.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Supermajor procurement consolidation concentrates rigless intervention demand in the Gulf of Mexico, where aging subsea infrastructure and regulatory mandates drive through-tubing service frequency.
United States
The Gulf of Mexico hosts the world's densest concentration of subsea intervention demand, with brownfield operators deploying rigless systems to defer platform decommissioning costs. The US Bureau of Safety and Environmental Enforcement mandates mechanical integrity testing schedules that expand intervention frequency across offshore platforms. Houston anchors the service provider ecosystem, with integrated contractors maintaining coiled tubing and hydraulic workover fleets for Gulf Coast deployment.
Norway
North Sea platform electrification trends accelerate battery-powered intervention system adoption as operators align with carbon intensity accounting frameworks. The Norwegian Petroleum Directorate enforces strict well integrity verification requirements that favor remote-operated through-tubing solutions. Stavanger and Bergen host specialist engineering clusters developing automated snubbing systems for high-pressure subsea applications.
United Kingdom
Mature North Sea fields generate sustained demand for well remediation and abandonment services as operators face statutory decommissioning timelines. The Health and Safety Executive regulates live-well intervention protocols, pushing adoption of closed-loop blowout preventer configurations. Aberdeen maintains Europe's largest concentration of rigless service technical expertise and equipment staging capacity.
Brazil
Pre-salt deepwater developments off the Santos Basin lack mature rigless service infrastructure, creating first-mover positioning opportunities for integrated providers. The National Petroleum Agency oversees well intervention safety standards that increasingly reference API RP 17G equipment qualification protocols. Rio de Janeiro serves as the operational hub for international service companies establishing Brazilian offshore intervention capabilities.
Saudi Arabia
Offshore field redevelopment programs in the Arabian Gulf expand demand for through-tubing stimulation and remediation services on aging platforms. The Ministry of Energy mandates adherence to ISO 13628-7 subsea intervention tool standards for all offshore contractors. Dhahran anchors the kingdom's petroleum engineering cluster, with state-owned operators negotiating framework contracts for integrated rigless service packages.
Rigless Intervention Systems Sales Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue electrification and automation vectors. The vendor base stratifies between integrated energy service conglomerates and specialist intervention equipment fabricators. Three archetypes dominate: full-service providers bundling multiple intervention disciplines, pure-play coiled tubing specialists, and subsea robotics innovators. Competitive moves concentrate on multi-year master service agreement negotiations and automated system development programs.
Among integrated service providers, Baker Hughes Company, Schlumberger Limited, and Halliburton exemplify the full-service archetype, anchoring long-term procurement relationships with consolidated supermajor buyers. These entities represent the scale-driven tier where coiled tubing, wireline, and hydraulic workover capabilities converge under unified contracting structures.
| Leading Market Players |
|---|
| Baker Hughes Company |
| Schlumberger Limited |
| Weatherford |
| Halliburton |
| Oceaneering International, Inc. |
| EFC Group Ltd |
| Expro Group Holdings N.V. |
| Acteon Group Ltd. |
| Aker Solutions |
| Others |
Pricing and Supply Chain Analysis
High-pressure snubbing technician scarcity in the Gulf of Mexico and North Sea creates labor-cost differentials that widen pricing-tier spreads between automated remote systems and conventional mechanical configurations.
Pricing Analysis
Volume placements concentrate in mechanical coiled tubing systems where commodity-grade specifications dominate fleet procurement, while margins accrue to automated packages certified for 15,000 psi subsea environments. Price differentiation separates API RP 17G-qualified systems with pre-certified BOP configurations from standard mechanical stacks lacking redundant shear capabilities. Cost compression in the mechanical tier is intensifying because supermajor framework contracting consolidates procurement leverage across multi-year master service agreements. Independent operators in mature Gulf of Mexico shelf fields exhibit the highest price sensitivity, whereas supermajors negotiating bundled intervention packages prioritize technical qualification over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with European and Japanese metallurgical suppliers of high-grade chromium steel for coiled tubing strings. Manufacturing concentration centers on Germany, Japan, and the United States for precision-engineered intervention components, while specialty alloy feedstock draws from South African chromium and Turkish ferroalloy sources. Supply chain risk manifests in extended API RP 17G third-party verification timelines that extend new entrant equipment qualification by 18-24 months. Distribution runs through Houston, Stavanger, and Aberdeen service hubs that stage equipment for rapid Gulf of Mexico and North Sea deployment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a cost-of-compliance story where the US Bureau of Safety and Environmental Enforcement's tightened well integrity verification requirements create a regulatory moat favoring incumbents with pre-certified intervention packages.
For Market Incumbents: Anticipate margin compression from supermajor procurement consolidation by anchoring multi-year framework contracts with guaranteed utilization floors. Invest in backward integration into high-grade chromium steel sourcing to offset European and Japanese supplier concentration. Certification investment in ISO 13628-7 and API RP 17G compliance creates switching costs that defend against emerging automated robotics specialists.
For New Entrants and Emerging Players: Digital-channel routes through remote-operated intervention system platforms offer lower customer acquisition costs than traditional field sales networks. Target West Africa pre-salt developments off Angola and Nigeria where rigless service infrastructure remains underdeveloped. Position through CCUS well intervention methodology partnerships with research institutes building carbon storage monitoring capabilities.
For Investors and Strategic Acquirers: The window for entry favors automated subsea robotics innovators with proprietary closed-loop control systems. Long-term viability hinges on electrification convergence with offshore platform power infrastructure and carbon intensity accounting frameworks. Monitor the US Bureau of Safety and Environmental Enforcement's incident reporting threshold adjustments as the inflection signal for BOP replacement cycle acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Automated System Development | Remote-operated robotics eliminate personnel exposure in 15,000 psi Gulf of Mexico environments. |
| Electrification Convergence | Battery-powered intervention systems align with North Sea platform electrification and carbon accounting frameworks. |
| CCUS Service Expansion | Carbon storage site operators require rigless abandonment and monitoring services with limited incumbent competition. |
| Framework Contract Anchoring | Multi-year master service agreements with supermajors bundle coiled tubing, wireline, and hydraulic workover capacity. |
| High-Grade Alloy Backward Integration | Captive chromium steel supply mitigates European and Japanese metallurgical supplier concentration risk. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with high-pressure snubbing technicians, offshore platform operations managers, supermajor procurement leads, and subsea intervention equipment engineers validated equipment deployment patterns and contracting structures. Secondary sources included US Bureau of Safety and Environmental Enforcement mechanical integrity testing records, API RP 17G certification databases, and ISO 13628-7 equipment qualification registries. Bottom-up fleet capacity estimates triangulated against top-down supermajor framework contract value disclosures.
Segmentation-level modeling tracked equipment type, technology tier, service category, and end-user archetype across the projection horizon. Coiled tubing, wireline, snubbing, and hydraulic workover configurations were modeled separately with intervention pressure rating as an industry-specific dimension. CAGRs were derived from historical deployment frequency correlations with regulatory mandate timelines and brownfield decommissioning deferral economics. Forecast inputs incorporated Gulf of Mexico platform age distributions and North Sea statutory abandonment timelines.
Inputs from regulatory certification bodies and supermajor procurement disclosures were available through the study window; gaps in privately negotiated framework contract pricing introduce uncertainty bands around vendor margin estimates. Forecasts reflect assumptions regarding US Bureau of Safety and Environmental Enforcement enforcement consistency and European metallurgical supply stability. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Global Deep-Well Disposal Services Market
Oil & Gas
Gulf of Mexico Oil and Gas Midstream Market
Oil & Gas
Subsea Multiphase Flowmeter Market
Oil & Gas
Injection Well Market
Oil & Gas
Europe Natural Gas Market
Oil & Gas
North America Frac Sand Market
Oil & Gas
LAMEA Oilfield Auxiliary Rental Equipment Market
Oil & Gas
Peru Oil and Gas Downstream Market
Oil & Gas
Crude Oil Desalter and Electrostatic Dehydrator Market
Oil & Gas
Europe Oilfield Services Market
Oil & Gas
North America Directional Drilling Services Market
Oil & Gas
Vietnam Oil and Gas Market
Oil & Gas
Small Scale LNG (SSLNG) Market
Oil & Gas
Middle East and Africa Early Production Facility Market
Oil & Gas
Subsea Manifolds Market
Oil & Gas
Downhole Equipment Market