
 Europe Natural Gas Market | 2026-2036
Europe Natural Gas Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Natural Gas Market Analysis
Utility procurement is consolidating around a smaller set of large integrated buyers with long-term offtake agreements. Shell PLC leverages its global LNG portfolio to secure supply flexibility for European power generators. TotalEnergies SE anchors downstream positions through integrated trading and regasification infrastructure. Equinor competes on pipeline proximity, sustaining cost advantages into Northwest European markets.
Europe natural gas consists primarily of methane with energy content typically ranging from 35 to 45 megajoules per cubic meter, delivered via pipeline networks or liquefied for marine transport to serve heating, industrial process, and electricity generation needs. Pipeline supply retains volume leadership across the continent, though LNG is gaining share as import diversification accelerates under REPowerEU targets. Within usage sectors, power generation commands premium margins as utilities value dispatchable low-carbon bridging capacity, while residential heating remains structurally mature with limited growth upside.
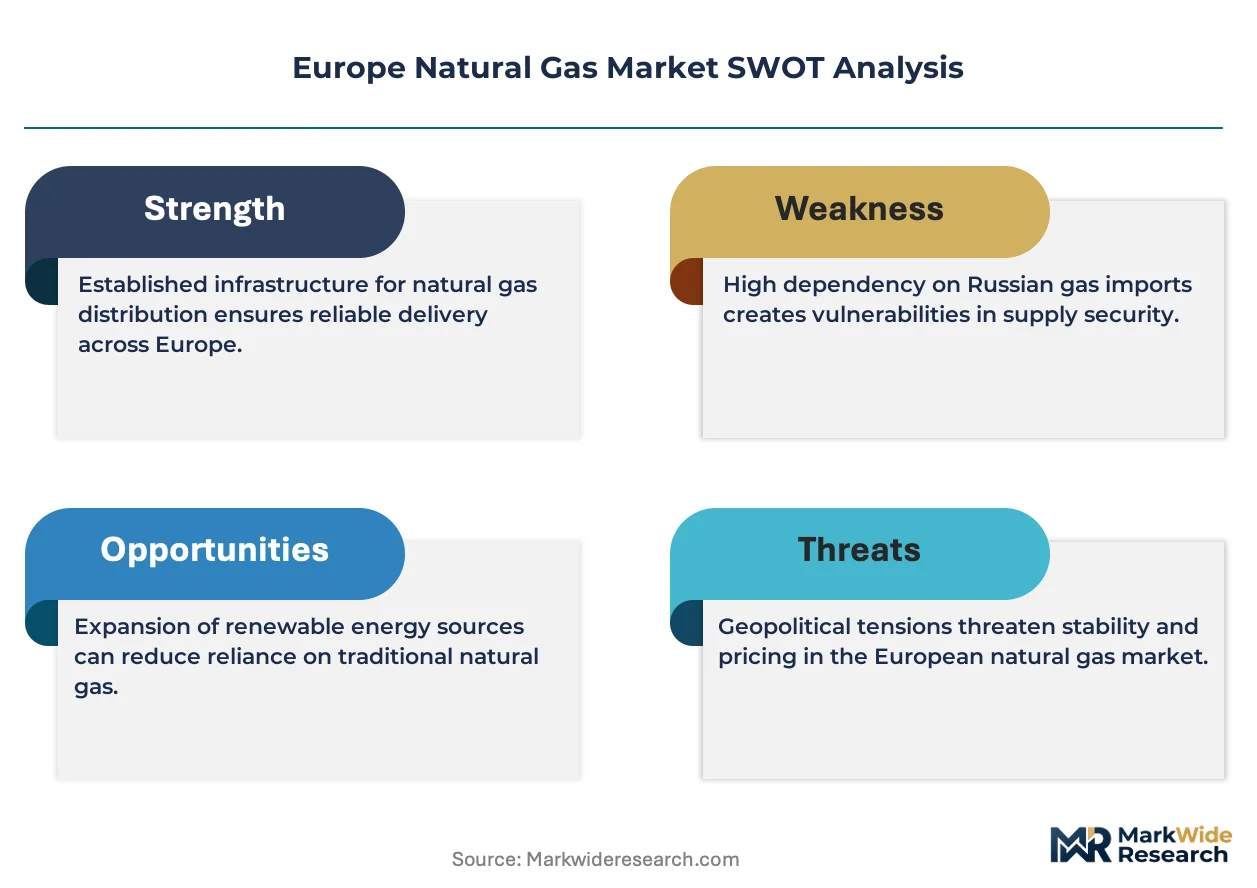
EU Green Deal carbon pricing through the Emissions Trading System and REPowerEU infrastructure mandates reshape procurement standards and market access conditions for suppliers. ECHA chemical safety protocols and national regulators in Germany and Italy enforce methane leak detection and network integrity requirements that elevate operational compliance costs. Stakeholders must monitor hydrogen blending mandates and biomethane injection quotas that could redefine pipeline gas specifications and asset valuations.
Market Dynamics
REPowerEU infrastructure mandates are forcing a wholesale reconfiguration of European import capacity, with LNG terminal expansions competing against pipeline rehabilitation for capital allocation across Germany, Italy, and the Netherlands.
Growth Catalysts
- EU Green Deal carbon pricing:The Emissions Trading System elevates gas-fired generation economics relative to coal across German power markets, sustaining dispatchable demand through the energy transition.
- Power generation utilities:Baseload transition requirements in Italy are expanding combined-cycle capacity, anchoring long-term offtake commitments for pipeline and LNG suppliers.
- REPowerEU diversification targets:Infrastructure investment is concentrating in Northwest European trading hubs, particularly the Netherlands and Germany, reducing single-source dependency risks.
Market Restraints
- Pipeline supply concentration:Norwegian and Algerian pipeline volumes retain volume leadership, constraining price discovery flexibility when LNG spot markets swing.
- Carbon border adjustment friction:CBAM implementation on imported industrial goods elevates compliance complexity for energy-intensive German chemical processors.
- Electrification substitution:Heat pump deployment in Dutch residential heating is compressing structural gas demand growth in the mature household segment.
Strategic Opportunities
- Hydrogen blending mandates:EU hydrogen backbone development is creating injection infrastructure opportunities for biomethane and synthetic gas producers.
- Italian industrial clusters:Underpenetrated LNG bunkering at Adriatic ports offers marine fuel switching potential as IMO sulfur regulations tighten.
- Network digitalization:Smart meter deployment across France and Spain is enabling demand-response aggregation for grid balancing services.
Industry Challenges
- Methane leak detection certification:ECHA chemical safety protocols and German network integrity rules are extending compliance timelines for legacy pipeline assets.
- Asset stranding risk:Hydrogen readiness specifications for new German compressor stations are elevating capex intensity without guaranteed utilization paths.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Natural Gas Market |
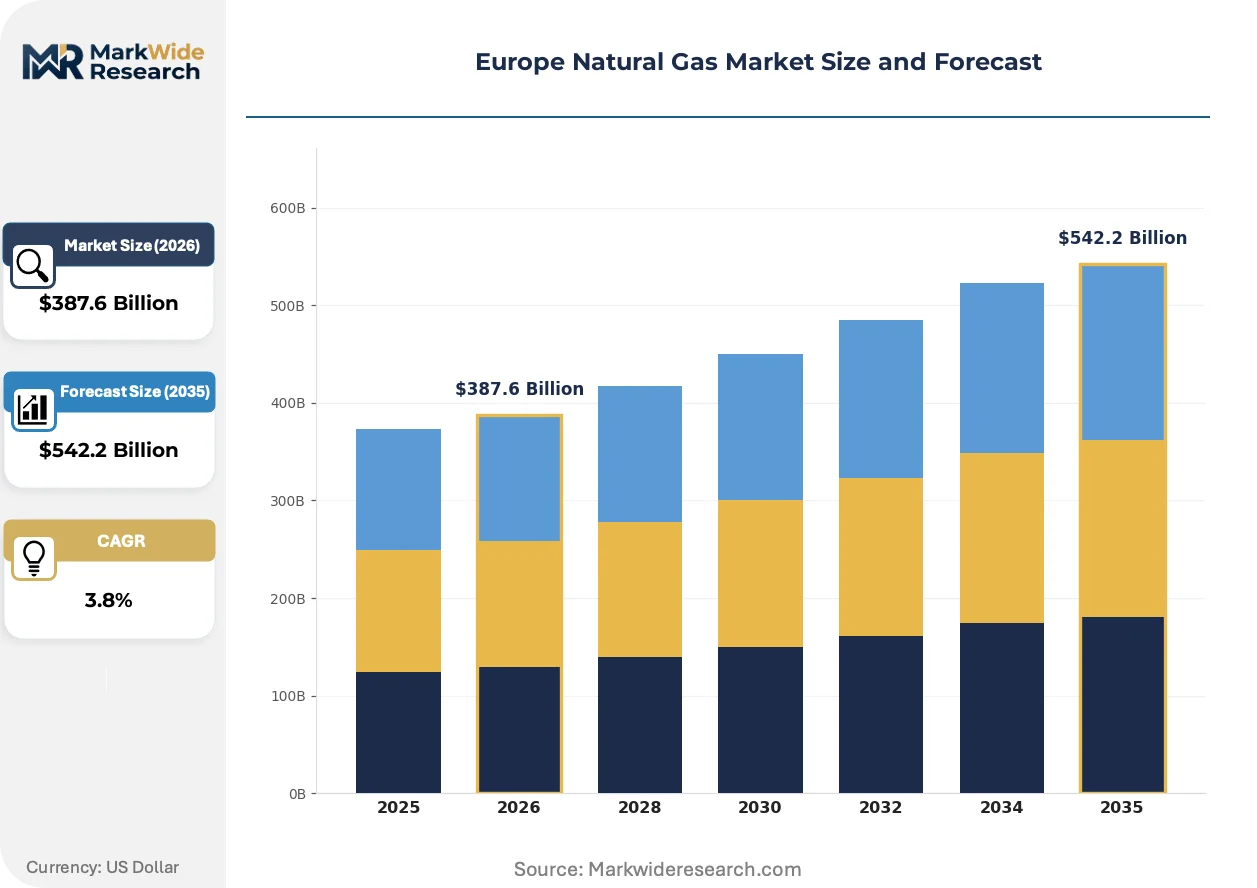
| Market Size in 2026 | $387.6 Billion |
| Market Size in 2035 | $542.2 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Supply Type: Pipeline, LNG, CNG, Storage Usage Sector: Residential, Industrial, Power Generation, Agriculture Distribution Channel: Direct Sales, Wholesale, Retail, Online Application Type: Heating, Transportation, Electricity Generation, Others |
| Companies Covered | TotalEnergies SE, Shell PLC, BP PLC, Eni S.p.A., Equinor, Uniper SE, E.ON SE, Chevron Corporation, Exxon Mobil Corporation, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Natural Gas Market Emerging Trajectories
Distributed production models and regulatory chemistry are compressing traditional hub-and-spoke supply architectures across European gas markets.
Small-scale LNG bunkering infrastructure is decentralizing marine fuel supply chains. Port authorities at Rotterdam and Hamburg are installing shore-side liquefaction and regasification units, enabling direct vessel refueling without terminal queuing. This compression of the supply chain is decentralizing volume flows away from large-scale import terminals toward consumption-adjacent distribution nodes.
EU methane emissions regulation is mandating measurement, reporting, and verification protocols for all gas imports exceeding specified thresholds. German transmission system operators must deploy continuous monitoring across compressor stations and storage facilities by specified deadlines. This enforcement architecture is elevating operational compliance costs most acutely for pipeline suppliers serving Central European industrial clusters.
Utility procurement is consolidating around integrated trading desks with balance-sheet capacity to manage volumetric and price volatility. Large German power generators are bypassing traditional wholesale intermediaries, negotiating direct bilateral contracts with Norwegian and Qatari suppliers. This disintermediation is most visible in the Netherlands, where TTF-linked pricing is giving way to hub-agnostic indexation for baseload power purchase agreements.
Europe Natural Gas Market Segmentation
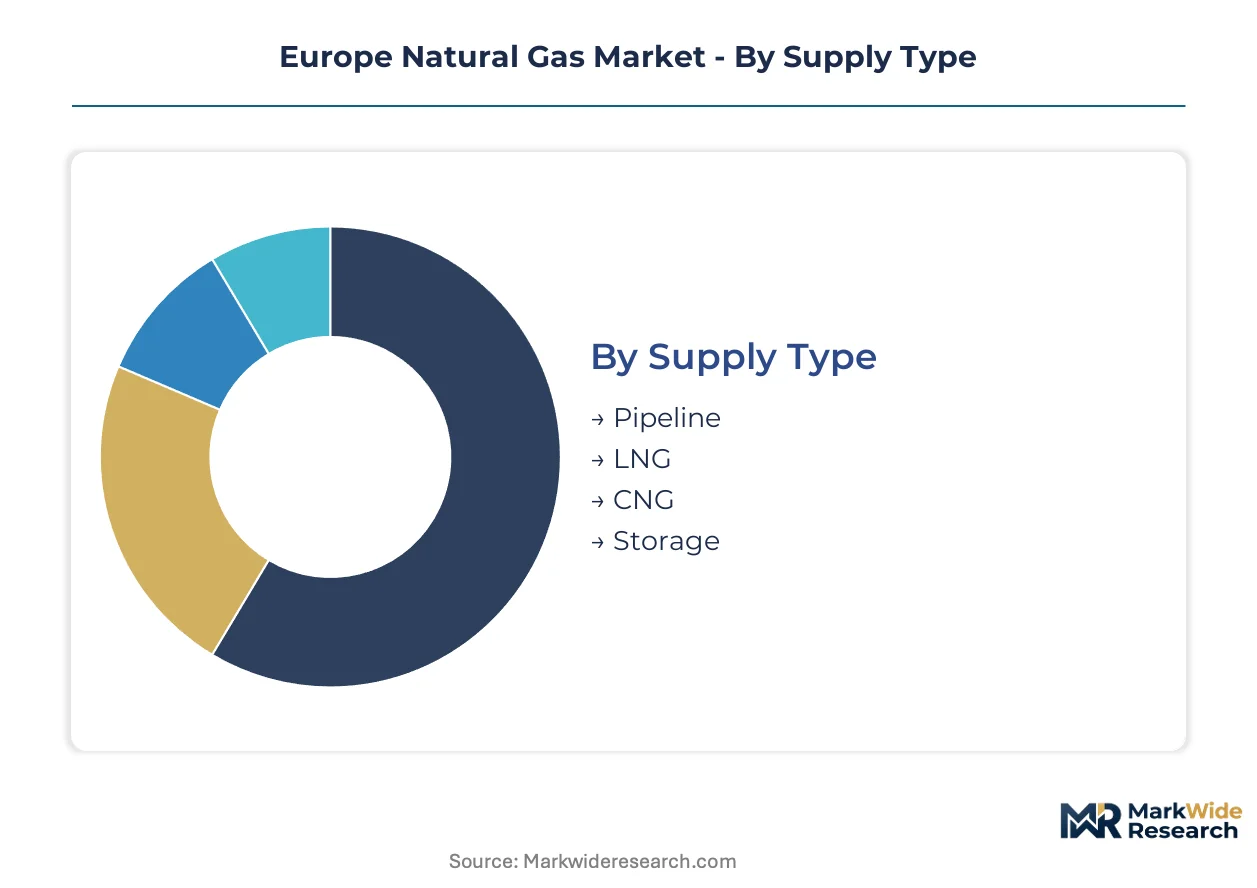
Segmentation across supply routes and consumption endpoints reveals how infrastructure investment priorities diverge between baseload power commitments and residential efficiency mandates. Procurement patterns in this market track regulatory deadlines for hydrogen blending and methane intensity certification rather than pure cost optimization.
Supply Type:
Pipeline rehabilitation cycles and LNG terminal commissioning schedules are driving capital allocation decisions across Northwest European infrastructure planners.
- Pipeline:Continental pipeline networks deliver methane at 35-45 MJ per cubic meter through high-pressure transmission systems. German utilities anchor long-term offtake agreements on Norwegian and Algerian corridor volumes to secure baseload power generation feedstock.
- LNG:Liquefied natural gas arrives via marine transport to regasification terminals in the Netherlands, Germany, and Italy. REPowerEU diversification mandates are accelerating import capacity expansion at Rotterdam and Wilhelmshaven to displace single-source dependencies.
- CNG:Compressed natural gas serves fleet vehicle refueling through daughter station networks. Italian transport operators deploy CNG for urban bus and light commercial applications under national decarbonization procurement rules.
- Storage:Underground salt cavern and depleted field facilities balance seasonal demand swings. German transmission system operators maintain strategic reserves to buffer heating load peaks and supply disruption scenarios.
Pipeline sits at the top of the volume ranking, with LNG climbing the fastest.
Usage Sector:
Margin concentration follows carbon price exposure and dispatchable capacity valuation across EU Emissions Trading System compliance obligations.
- Residential:Mature heating demand in Dutch and German housing stock faces structural compression from heat pump electrification mandates. Network operators defend revenue through smart meter deployment and demand-response tariff restructuring.
- Industrial:German chemical processors and Italian ceramics manufacturers consume pipeline gas for process heat under Carbon Border Adjustment Mechanism compliance pressure. Methane leak detection certification now gates market access for energy-intensive importers.
- Power Generation:Combined-cycle turbines in Italy and Germany dispatch as baseload transition capacity under EU Green Deal carbon pricing. Utilities pay premium hub-agnostic indexation to secure firm supply for renewable backup obligations.
- Agriculture:Greenhouse heating and biomethane feedstock production concentrate in Netherlands and Spain. Biogas upgrading facilities inject renewable gas into distribution networks under national biomethane quota schemes.
Power Generation commands the steepest expansion trajectory, with Agriculture gaining share fastest on renewable gas integration.
Distribution Channel:
Customer scale and balance-sheet capacity determine whether procurement flows through intermediaries or direct bilateral contracting.
- Direct Sales:Large German power generators negotiate term contracts directly with Norwegian and Qatari suppliers. This disintermediation compresses trading margins for traditional wholesale intermediaries at TTF-linked hubs.
- Wholesale:Trading desks at Rotterdam and Amsterdam manage volumetric and price volatility for mid-sized industrial offtakers. Liquidity concentration in Netherlands-based hubs sustains benchmark price discovery for continental contracts.
- Retail:Regulated suppliers serve residential and small commercial accounts through standardized tariff structures. French and Spanish network codes mandate supplier-of-last-resort obligations that cap margin extraction.
- Online:Digital platforms aggregate switching behavior for price-sensitive household consumers. Comparison tools accelerate churn in liberalized markets where German and British retail competition has intensified.
Direct Sales leads volume concentration, with Online expanding most quickly on platform-enabled customer acquisition.
Application Type:
Technology substitution risk varies by end-use, with heating applications facing steeper electrification pressure than industrial process loads.
- Heating:Residential and commercial building thermal demand dominates winter consumption profiles. Dutch heat pump deployment targets explicitly compress structural gas demand growth in the household segment.
- Transportation:Marine bunkering at Adriatic ports and heavy-duty road fleets drive LNG and CNG adoption. IMO sulfur regulations tighten compliance requirements for Italian coastal shipping routes.
- Electricity Generation:Combined-cycle gas turbines provide dispatchable low-carbon bridging capacity for renewable intermittency. German utilities value firm capacity payments alongside energy market revenues.
- Others:Feedstock applications in chemical synthesis and hydrogen production represent emerging demand categories. EU hydrogen backbone development creates injection infrastructure for synthetic gas producers.
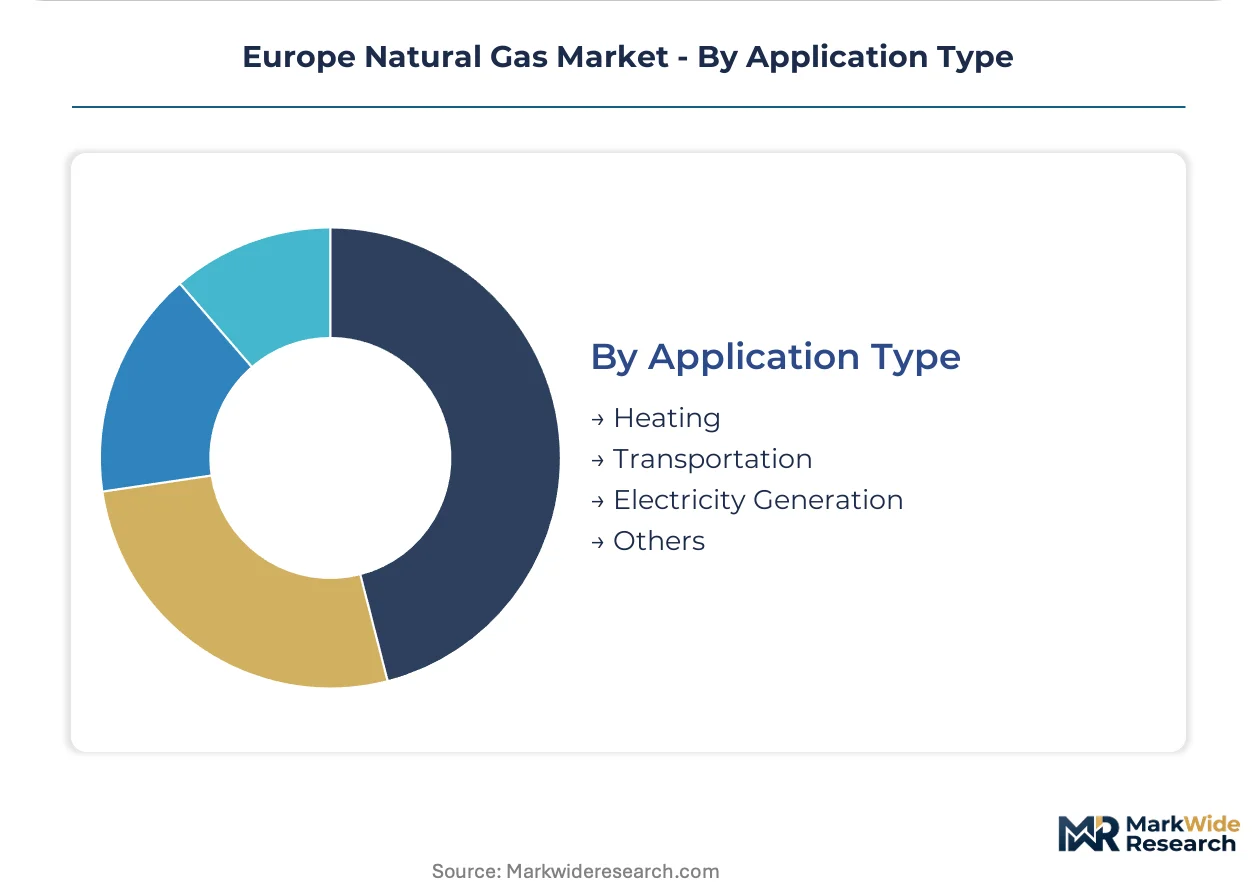
Heating retains volume leadership, with Transportation gaining momentum fastest on marine fuel switching.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Engineering talent clusters in German industrial regions and Dutch trading hubs anchor European natural gas infrastructure development. Technical workforce concentrations in Norway's energy corridor and Italian manufacturing zones sustain operational expertise across the value chain. These human capital foundations shape where capital investment flows and regulatory innovation takes root.
Germany
Power generation utilities and chemical processors drive baseload gas demand across the Ruhr and Rhine industrial corridors. The EU Green Deal carbon pricing through the Emissions Trading System elevates gas-fired generation economics relative to coal. Wilhelmshaven and Brunsbüttel host accelerating LNG terminal construction to displace single-source pipeline dependencies.
Netherlands
Rotterdam trading desks and TTF-linked price discovery mechanisms concentrate liquidity for continental contract benchmarking. REPowerEU infrastructure mandates accelerate regasification capacity expansion at port facilities. The Randstad logistics cluster enables small-scale LNG bunkering infrastructure deployment for marine fuel switching.
Italy
Combined-cycle turbine operators in Lombardy and Veneto anchor long-term offtake commitments for baseload transition capacity. National decarbonization procurement rules mandate CNG deployment for urban bus and light commercial fleets. Adriatic port authorities at Ravenna and Venice are installing shore-side liquefaction units for direct vessel refueling.
Norway
Pipeline proximity advantages sustain cost competitiveness into Northwest European markets through North Sea corridor infrastructure. Equinor and transmission system operators deploy continuous methane monitoring across compressor stations under tightening EU emissions regulation. The Stavanger energy cluster maintains subsea engineering expertise for offshore production and carbon capture integration.
United Kingdom
North Sea production decline and domestic storage depletion reshape import dependency toward LNG and Norwegian interconnectors. The country's national energy regulator enforces network integrity standards for aging transmission infrastructure. Grangemouth and Teesside industrial clusters pursue hydrogen readiness specifications for downstream process heat applications.
Europe Natural Gas Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across procurement, trading, and infrastructure verticals. The vendor base concentrates around integrated majors with balance-sheet capacity to manage volumetric volatility alongside national champions with pipeline proximity advantages. Three archetypes dominate: global LNG portfolio traders, pipeline-anchored national suppliers, and utility-affiliated procurement desks. Competitive moves center on direct bilateral contracting disintermediation and hydrogen-ready infrastructure pre-positioning.
Among integrated energy majors, TotalEnergies SE, Shell PLC, and BP PLC exemplify the global trading archetype with diversified supply origination and regasification downstream positions. These London- and Paris-based entities anchor liquidity provision at Northwest European hubs while negotiating hub-agnostic indexation for baseload power purchase agreements. Their scale enables balance-sheet absorption of price volatility that fragments procurement access for mid-sized industrial offtakers.
| Leading Market Players |
|---|
| TotalEnergies SE |
| Shell PLC |
| BP PLC |
| Eni S.p.A. |
| Equinor |
| Uniper SE |
| E.ON SE |
| Chevron Corporation |
| Exxon Mobil Corporation |
| Others |
Supply Flow & Price Mechanics
Backward integration into regasification infrastructure anchors pricing power for integrated majors serving Northwest European utilities. German power generators and Dutch trading desks leverage captive terminal capacity to bypass hub intermediaries and secure hub-agnostic indexation for baseload offtake.
Pricing Analysis
Capacity additions in the Netherlands and Germany are reshaping price floors for LNG deliveries to Northwest European markets. Contract-based long-term offtake dominates procurement, with price differentiation resting on volume scale and methane intensity certification under EU emissions regulation. Cost compression in spot-indexed supply is intensifying because Norwegian pipeline volumes retain baseload preference. Mid-sized industrial offtakers exhibit highest price sensitivity, while power generation utilities value dispatchable capacity premiums above absolute cost.
Supply Chain Analysis
Single-source vulnerability sits with Norwegian and Algerian pipeline corridors serving Central European industrial clusters. Geographic supply concentration centers on Norway, Qatar, and the United States for LNG feedstock. Raw material dependencies include liquefaction capacity, specialized vessel fleets, and subsea pipeline infrastructure. Tariff exposure from Carbon Border Adjustment Mechanism implementation elevates compliance costs for German chemical processors. Distribution runs through Rotterdam and Amsterdam trading hubs for continental price benchmarking.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe natural gas market reads as a late-cycle quality story where methane intensity certification and hydrogen-ready specifications command procurement preference. Demand is shifting toward premium specifications as EU Green Deal compliance gates market access.
For Market Incumbents: Anchor baseload positions through direct bilateral contracting with Qatari and Norwegian suppliers to disintermediate TTF-linked trading margins. Invest in hydrogen-ready compressor stations at Wilhelmshaven and Brunsbüttel before regulatory deadlines harden. Electrification substitution in Dutch residential heating threatens structural demand compression.
For New Entrants and Emerging Players: Begin with biomethane upgrading facilities in Netherlands and Spain where national quota schemes guarantee offtake. Target Adriatic LNG bunkering infrastructure at Ravenna and Venice as IMO sulfur regulations tighten compliance requirements. Partner with Italian port authorities for shore-side liquefaction deployment.
For Investors and Strategic Acquirers: Consolidation pressure builds where balance-sheet capacity to manage volumetric volatility fragments procurement access for mid-sized offtakers. Long-term viability favors integrated majors with regasification downstream positions and global LNG portfolio origination. Watch TTF liquidity concentration versus hub-agnostic indexation adoption as the inflection signal for pricing power migration.
| Strategic Initiative | Industry Significance |
|---|---|
| Regasification Capacity Buildout | Wilhelmshaven and Brunsbüttel terminals displace single-source pipeline dependencies under REPowerEU mandates. |
| Hydrogen Backbone Integration | German transmission operators prepare pipeline assets for biomethane and synthetic gas injection quotas. |
| Methane Intensity Certification | ECHA protocols and EU emissions regulation gate market access for pipeline suppliers serving industrial clusters. |
| Direct Bilateral Contracting | Large German utilities bypass TTF intermediaries to negotiate hub-agnostic indexation with Norwegian suppliers. |
| Small-Scale LNG Bunkering | Rotterdam and Hamburg port authorities enable marine fuel switching without large-terminal queuing delays. |
Methodological Framework
Direct dialogue with utility procurement officers, LNG trading desk heads, EPC contractors, and German transmission system operators grounded the qualitative assessment. Secondary validation drew from EIA data, IEA market reports, FERC filings, and project development databases tracking European regasification capacity. Bottom-up and top-down triangulation cross-checked volume assumptions against infrastructure commissioning schedules.
Segmented outputs across supply type, usage sector, distribution channel, and application type fed into the analytical framework over the projection horizon. CAGRs were derived from capacity expansion trajectories, regulatory deadline impacts, and demand elasticity modeling for heating electrification substitution. Forecast inputs included REPowerEU infrastructure mandate compliance timelines and EU Green Deal carbon price pathway assumptions.
Several conditions sit outside the modeled scope, including geopolitical supply disruptions, accelerated hydrogen blending mandate revisions, and breakthrough storage technology commercialization. Forecasts reflect documented assumptions about infrastructure completion schedules and regulatory enforcement intensity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Mud Balance Market
Oil & Gas
Well Casing Market
Oil & Gas
Global LNG Liquefaction Terminals Market
Oil & Gas
China Oil and Gas Midstream Market
Oil & Gas
Latin America AI in Oil and Gas Market
Oil & Gas
Kuwait Oil and Gas Upstream Market
Oil & Gas
Canada LNG Bunkering Market
Oil & Gas
Hydrocracking Market
Oil & Gas
South Korea Oil and Gas Market
Oil & Gas
CO2 EOR Market
Oil & Gas
United States Wireline Logging Services Market
Oil & Gas
Digital Oilfield Solutions Market
Oil & Gas
Intelligent Pigging Services Market
Oil & Gas
Italy Oil and Gas Upstream Market
Oil & Gas
Pumpjack Market
Oil & Gas
Malaysia Oil and Gas Market