
 Ultrasound Probe Disinfection Market | 2026-2036
Ultrasound Probe Disinfection Market Size, Share, and Industry Trends Forecast 2026-2036
Ultrasound Probe Disinfection Market Intelligence
A preference for single-source procurement from integrated system providers is hardening hospital purchasing decisions. Nanosonics specializes in automated trophon systems, creating a distinct technology-led position. STERIS leverages its broad portfolio of infection prevention products to offer bundled solutions to large hospital networks. Meanwhile, Tristel plc competes on the strength of its proprietary chlorine dioxide chemistry for manual disinfection processes.
Ultrasound probe disinfection involves processes that eliminate or inactivate microorganisms on semi-critical and critical medical devices used in sonography. These methods must achieve high-level disinfection (HLD) to prevent patient-to-patient transmission of pathogens, particularly for intracavitary probes. While chemical disinfectants remain a large segment, automated systems using technologies like hydrogen peroxide vapor represent the fastest-growing product category. Within applications, gynecology and cardiology have the most stringent disinfection requirements, driving adoption in surgical facilities and large diagnostic centers.
Regulatory frameworks from the US Food and Drug Administration (FDA) and requirements for CE marking under Europe's Medical Device Regulation (MDR) mandate validated disinfection processes. These standards enforce strict efficacy and material compatibility testing for all disinfection products and systems before they can be marketed. The key decision for healthcare facilities centers on balancing the upfront capital cost of automated systems against the long-term operational and compliance benefits.
Market Dynamics
The central dynamic shaping the market is the accelerating replacement of manual, chemistry-based disinfection with automated systems. This shift is driven by regulatory pressure for validated, auditable processes to mitigate the risk of healthcare-associated infections from semi-critical ultrasound probes.
Growth Catalysts
- Stringent Regulations:Mandates for high-level disinfection from bodies like the US FDA and requirements for CE marking under Europe's MDR for semi-critical devices compel facilities to adopt validated processes.
- Cardiology Department Demand:Escalating use of transesophageal echocardiography (TEE) probes, which require meticulous disinfection between patients, drives adoption of reliable and fast-turnaround systems in cardiac units.
- Process Standardization:Automated systems using hydrogen peroxide vapor offer repeatable, user-independent cycles that help hospitals standardize infection control protocols and simplify compliance documentation.
Market Restraints
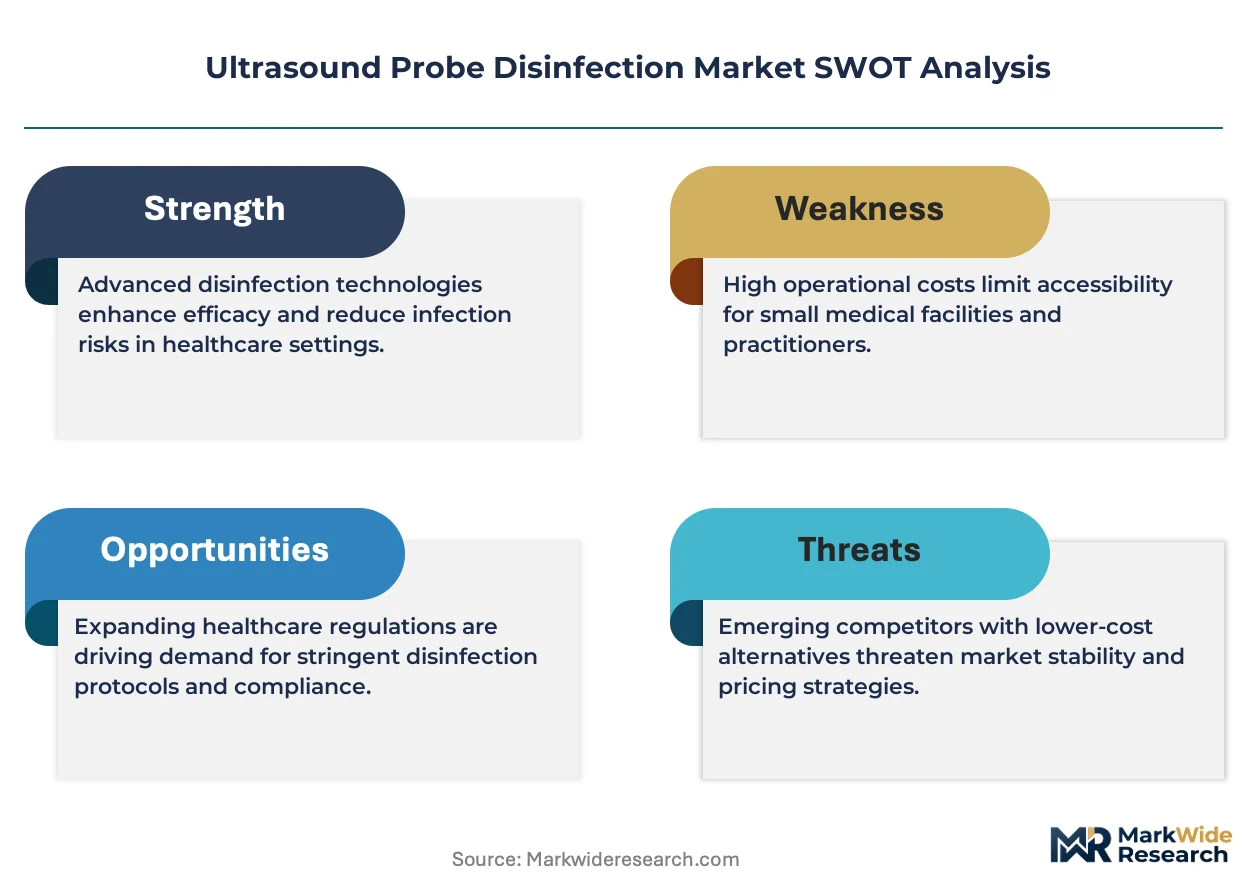
- High Capital Outlay:The significant upfront investment required for automated disinfection systems presents a major barrier for smaller clinics, private practices, and hospitals with constrained capital budgets.
- Material Compatibility Issues:Certain older or specialized ultrasound probes may not be compatible with the aggressive chemicals or processes used in some disinfection systems, limiting technology adoption.
- Lengthy Validation Cycles:New disinfection products and systems face extensive and time-consuming efficacy and material compatibility testing to gain clearance from regulators like the FDA or achieve CE marking.
Strategic Opportunities
- Emerging Market Penetration:Healthcare systems in Latin America and Southeast Asia are upgrading infection control standards, creating new demand for cost-effective and validated ultrasound probe disinfection solutions.
- IT and Data Integration:Developing systems that integrate with hospital electronic health records and asset management platforms to automate tracking and compliance reporting offers a significant value-add.
- Expansion to Adjacent Devices:Adapting disinfection technologies for other semi-critical endocavity devices used in urology, gastroenterology, and other specialties opens new revenue streams beyond sonography.
Industry Challenges
- User Training and Adherence:Ensuring consistent and correct use of disinfection protocols, whether manual or automated, requires continuous staff training and monitoring, which is a persistent operational burden for healthcare facilities.
- Workflow Integration Complexity:Retrofitting older healthcare facilities to accommodate the physical footprint, utility requirements, and workflow changes of new automated disinfection systems is a significant logistical challenge.
- Lack of Global Standardization:Divergent disinfection guidelines and standards across different countries and regions create complexity for manufacturers in product development, marketing, and regulatory submissions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ultrasound Probe Disinfection Market |
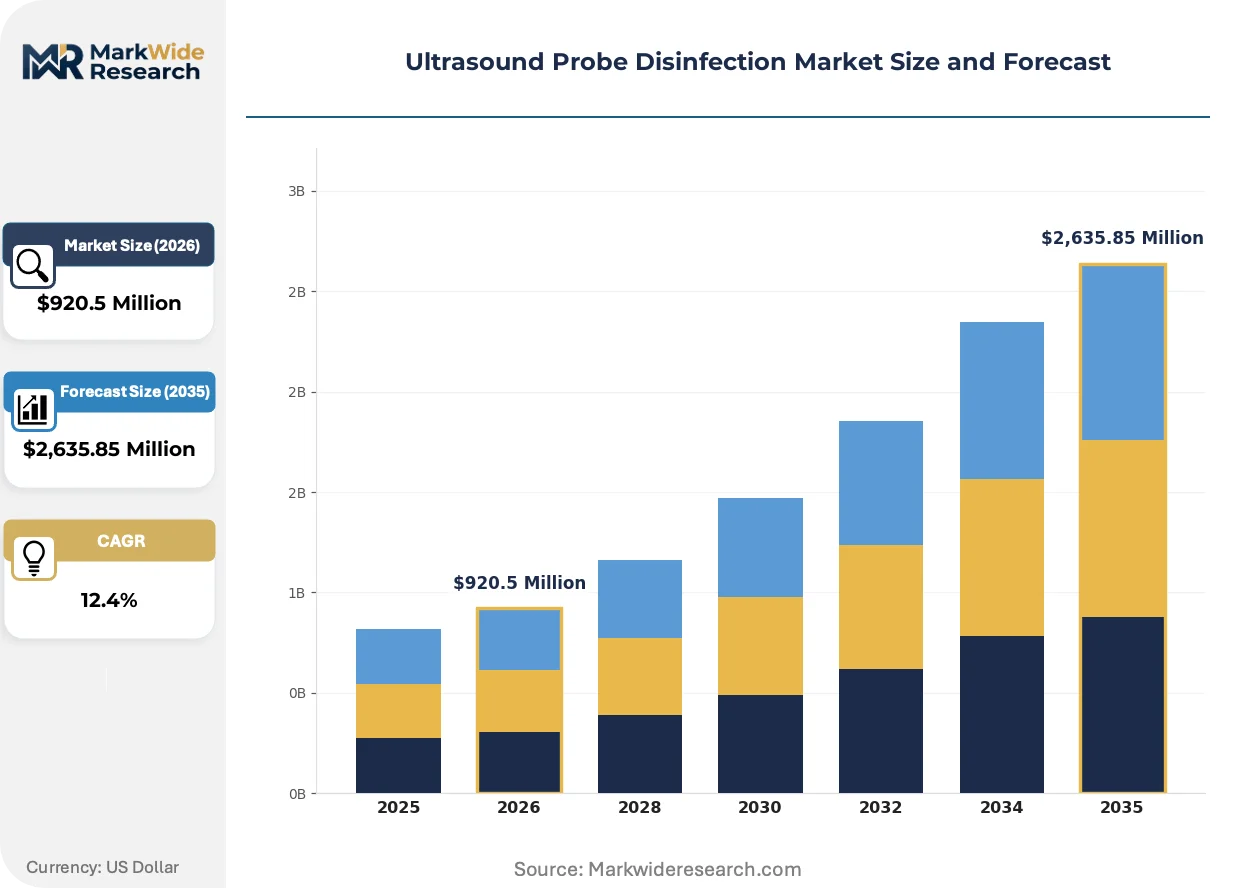
| Market Size in 2026 | $920.5 Million |
| Market Size in 2035 | $2,635.85 Million |
| CAGR (2026 – 2036) | 12.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chemical Disinfectants, Ultraviolet Disinfection, Automated Systems, Wipe-Based Solutions Application: Gynecology, Cardiology, Emergency Medicine, Urology, Anesthesiology End User: Diagnostic Centers, Surgical Facilities, Outpatient Clinics, Diagnostic Imaging Centers Technology: Hydrogen Peroxide Vapor, Ozone-Based, Enzymatic Cleaners, Electrolyzed Water Systems |
| Companies Covered | Ecolab Inc., STERIS plc, Nanosonics, Siemens Healthineers AG, GE HealthCare Technologies Inc., CIVCO Medical Solutions, Germitec, CS Medical LLC, Tristel plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ultrasound Probe Disinfection Market Strategic Shifts & Innovations
The market's evolution is defined by the convergence of automation, advanced chemistries, and data connectivity. This is creating a new paradigm where disinfection is not just a cleaning step but an integrated, auditable component of patient safety protocols.
Automated systems using vaporized hydrogen peroxide or ultraviolet (UV-C) light deliver validated, low-temperature disinfection cycles. Large hospitals and specialized diagnostic centers are adopting these technologies to minimize human error and improve turnaround times for critical probes. This technological shift from manual soaking methods is rewriting the standards for infection control efficacy and operational workflow in modern sonography departments.
Europe's Medical Device Regulation (MDR) imposes significantly stricter requirements for clinical evidence, material compatibility data, and post-market surveillance for disinfection systems. This regulatory pressure is forcing manufacturers to invest heavily in validation testing for specific probe models to obtain or maintain CE marking. The automated systems segment is most impacted, as vendors must now provide a higher level of proof to substantiate their performance claims.
A clear behavioral change in hospital purchasing is the move toward single-source procurement for bundled infection prevention solutions. This model is displacing discrete, transactional purchases of disinfectants with long-term contracts from integrated suppliers that cover systems, consumables, and service. This trend is most prominent within large, multi-site hospital networks in the United States, where it helps standardize care and simplify supply chain logistics.
Ultrasound Probe Disinfection Market Segmentation
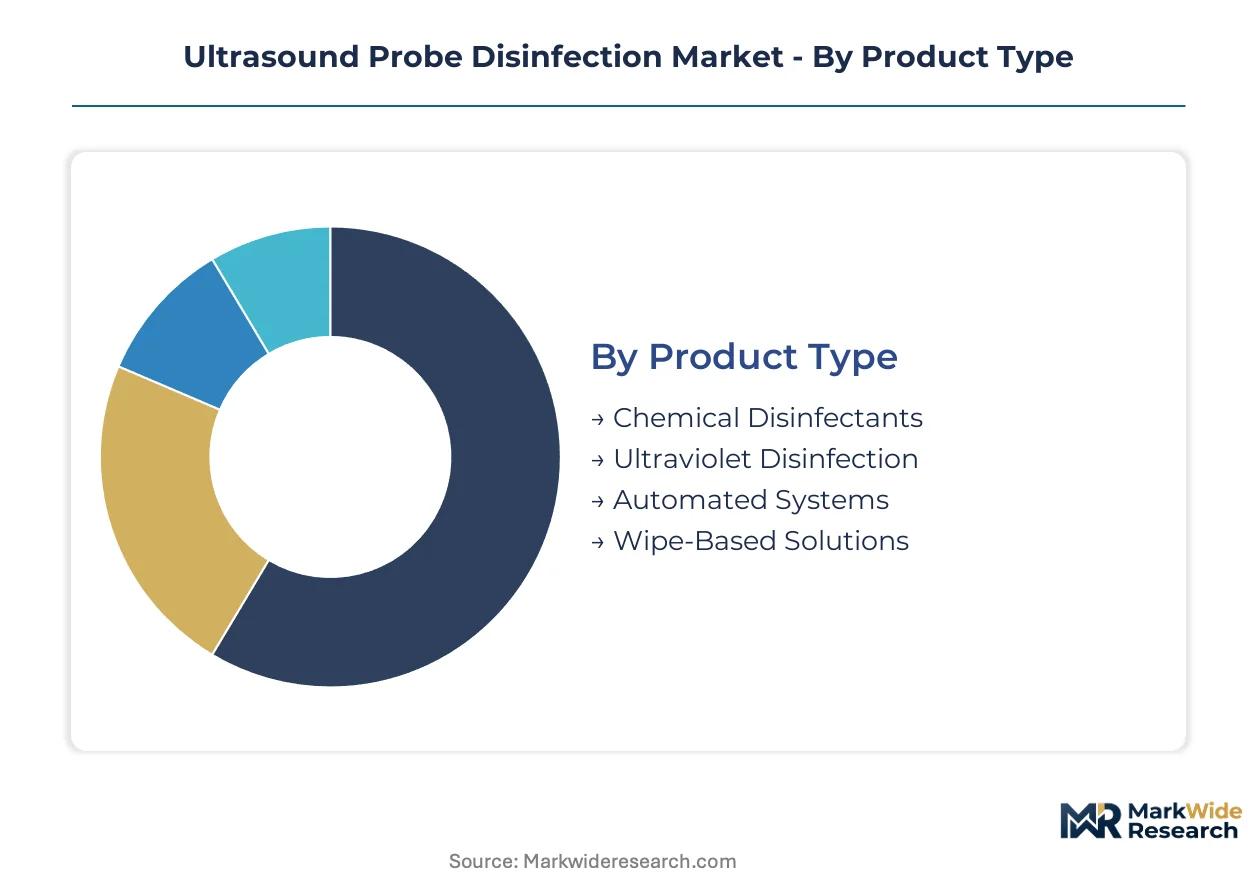
The Ultrasound Probe Disinfection Market segments based on product type, application, end user, and technology, reflecting the diverse needs of healthcare facilities for patient safety. Understanding these segments helps manufacturers tailor solutions to specific clinical workflows and regulatory demands.
Product Type:
Buyers in the ultrasound probe disinfection market differentiate their choices based on the level of automation and chemical efficacy required for various clinical settings.
- Automated Systems:These advanced devices utilize technologies like hydrogen peroxide vapor or UV-C light to provide validated, user-independent disinfection cycles for semi-critical probes. Demand concentrates within large hospitals and diagnostic centers in the United States, driven by stringent infection control guidelines and the need for process standardization.
- Chemical Disinfectants:This category encompasses liquid high-level disinfectants, often glutaraldehyde or OPA-based, requiring manual soaking procedures for probe reprocessing. This segment remains a large market component, particularly in smaller clinics where capital outlay for automated systems poses a significant barrier.
- Ultraviolet Disinfection:UV-C light systems offer a chemical-free disinfection method, primarily for non-critical or semi-critical probes, sterilizing surfaces through germicidal irradiation. These systems find utility in settings where chemical exposure is a concern, providing an alternative to traditional liquid disinfectants.
- Wipe-Based Solutions:Pre-saturated wipes containing disinfectants provide a convenient, rapid method for low-level disinfection of external probe surfaces or as a pre-cleaning step. Outpatient clinics and emergency medical services often use these for quick turnaround needs.
Volume sits with Chemical Disinfectants; growth tilts toward Automated Systems.
Application:
The specific medical application dictates the level of disinfection required and the probe types used, influencing technology adoption and product selection.
- Cardiology:This segment involves transesophageal echocardiography (TEE) probes, which are semi-critical devices requiring high-level disinfection due to direct patient contact. Cardiology departments prioritize rapid turnaround and validated processes, especially in large cardiac units.
- Gynecology:Endocavitary probes used in gynecological examinations necessitate high-level disinfection to prevent patient-to-patient transmission of pathogens. Surgical facilities and women's health centers drive demand for effective and material-compatible disinfection solutions.
- Emergency Medicine:Ultrasound probes in emergency departments often require rapid disinfection between patients, frequently involving portable devices and less stringent HLD requirements for non-invasive scans. Speed and ease of use are critical factors for emergency medical teams.
- Urology:Procedures involving transrectal or transurethral probes require high-level disinfection, focusing on devices for prostate examinations and bladder imaging. Urological clinics and diagnostic centers seek efficient and reliable disinfection protocols.
- Anesthesiology:Peripheral nerve blocks and vascular access procedures frequently utilize ultrasound guidance, requiring disinfection of probes that contact intact skin. Anesthesiology departments prioritize solutions that integrate seamlessly into their procedural workflows.
The segment with the most rigorous requirements is Cardiology; Emergency Medicine shows the broadest patient exposure.
End User:
The operational scale and patient throughput of healthcare facilities significantly influence their procurement decisions for disinfection solutions.
- Diagnostic Centers:These specialized facilities perform a high volume of ultrasound examinations across various specialties, requiring efficient and compliant disinfection protocols. Large diagnostic centers often invest in automated systems to manage throughput and standardize processes.
- Surgical Facilities:Hospitals and ambulatory surgical centers utilize ultrasound for guidance during procedures, necessitating high-level disinfection for intracavitary and semi-critical probes. Stringent infection control standards in surgical environments drive demand for validated solutions.
- Outpatient Clinics:Smaller clinics and private practices perform routine ultrasound examinations, often prioritizing cost-effective and easy-to-use disinfection methods. Manual chemical disinfection or wipe-based solutions remain prevalent in these settings.
- Diagnostic Imaging Centers:These centers focus exclusively on imaging services, including ultrasound, and require robust disinfection solutions for a wide array of probes. Efficiency and regulatory compliance are paramount for maintaining patient schedules.
Large-scale facilities drive demand for automated solutions; smaller clinics prioritize cost-effectiveness and ease of use.
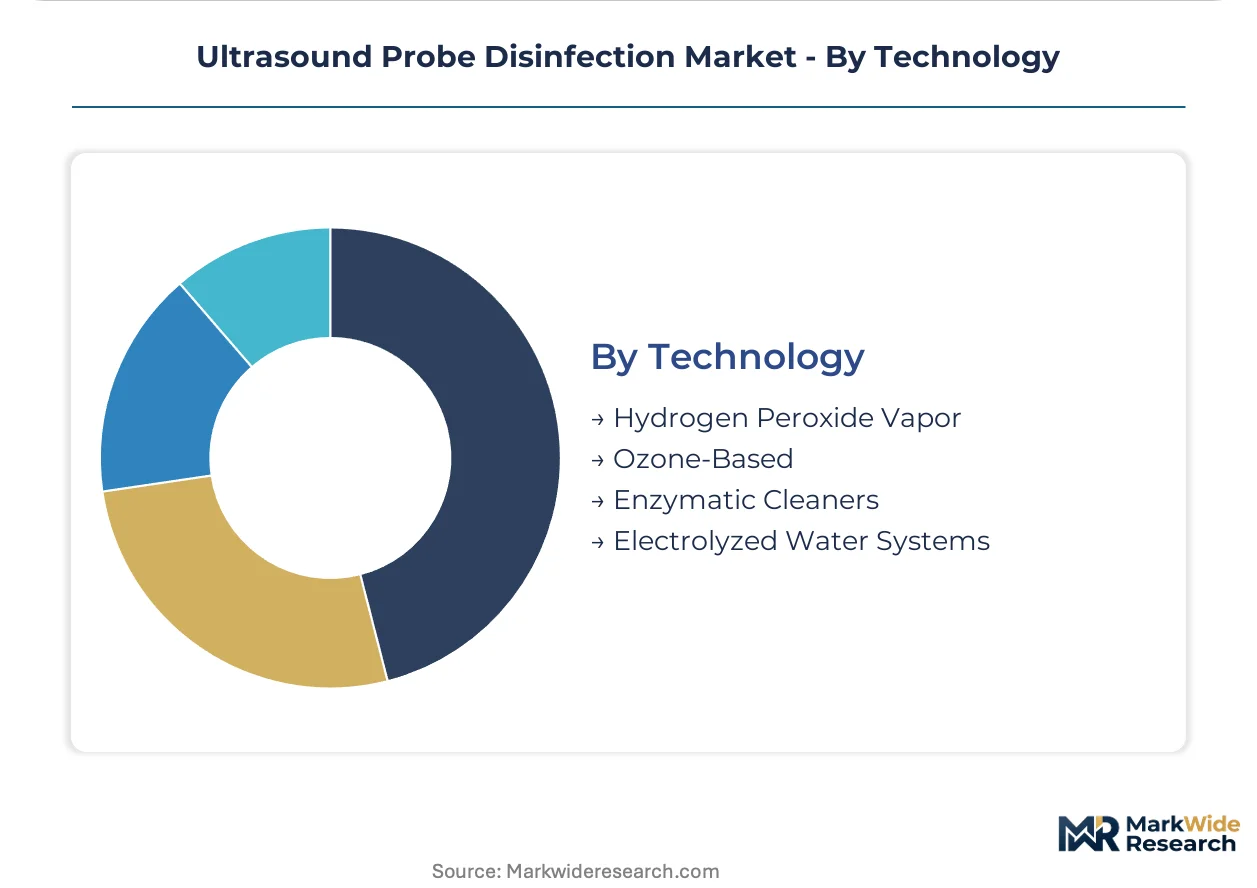
Technology:
Technological advancements in disinfection methods offer varied efficacy profiles and operational benefits for healthcare providers, influencing adoption rates.
- Hydrogen Peroxide Vapor:This technology uses vaporized hydrogen peroxide to achieve high-level disinfection in automated systems, offering broad-spectrum efficacy and material compatibility. It is widely adopted in the United States for TEE and other semi-critical probes due to its validated, standardized cycles.
- Ozone-Based:Ozone-based disinfection systems utilize ozone gas for microbial inactivation, providing an alternative to chemical-intensive methods for certain medical devices. These systems appeal to facilities seeking environmentally friendlier disinfection options.
- Enzymatic Cleaners:These solutions use enzymes to break down organic matter on probes, serving as a crucial pre-cleaning step before high-level disinfection. Enzymatic cleaners are essential for effective reprocessing, preventing biofilm formation.
- Electrolyzed Water Systems:Such systems generate disinfectant solutions from water and salt, offering an on-demand, non-toxic alternative for certain disinfection applications. They are gaining traction for their safety profile and reduced environmental impact.
Hydrogen Peroxide Vapor technology commands significant investment due to its proven efficacy; Electrolyzed Water Systems offer a cost-effective alternative for certain applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States anchors demand for ultrasound probe disinfection solutions, driven by stringent infection control guidelines and a high volume of advanced medical procedures. This market's regional dynamics reflect varied healthcare infrastructures, regulatory landscapes, and investment capacities across different economies.
United States
Demand for high-level disinfection of transesophageal echocardiography (TEE) probes is particularly strong in the United States. The US Food and Drug Administration (FDA) mandates validated reprocessing protocols for semi-critical medical devices. Major medical hubs like Boston and Houston are early adopters of automated disinfection systems, standardizing processes in large hospital networks.
Germany
Germany's advanced healthcare system drives consistent demand for sophisticated disinfection technologies. Compliance with Europe's Medical Device Regulation (MDR) ensures rigorous material compatibility and efficacy testing. Key medical technology clusters in Bavaria and North Rhine-Westphalia focus on integrating automated solutions into surgical facilities and diagnostic centers.
Japan
Japan's aging population and emphasis on preventative care increase the volume of ultrasound examinations, necessitating effective disinfection. The Pharmaceuticals and Medical Devices Agency (PMDA) oversees strict guidelines for medical device reprocessing. Tokyo and Osaka's large university hospitals are investing in automated systems to enhance patient safety and operational efficiency.
China
China's expanding healthcare infrastructure and growing awareness of healthcare-associated infections accelerate the adoption of disinfection solutions. The National Medical Products Administration (NMPA) is tightening regulations on medical device reprocessing. Major urban centers such as Shanghai and Beijing are seeing increased investment in automated disinfection technologies for large diagnostic centers.
Australia
Australia exhibits a strong commitment to infection control, with the Therapeutic Goods Administration (TGA) setting high standards for medical device disinfection. Nanosonics, an Australian company, holds a significant position with its automated trophon systems. Sydney and Melbourne's leading hospitals prioritize advanced disinfection methods for semi-critical probes.
Ultrasound Probe Disinfection Market Key Industry Players
Portfolio diversification dominates the current landscape, as companies seek to offer comprehensive infection prevention solutions. The market structure is tiered, with specialized technology providers competing alongside broad-portfolio medical device manufacturers. Strategic partnerships and technology leadership are key competitive moves shaping market share.
Nanosonics exemplifies the technology-led archetype, specializing in automated trophon systems for high-level disinfection. STERIS plc occupies a position as a broad portfolio provider, leveraging its extensive range of infection prevention products to offer bundled solutions to large healthcare networks. Meanwhile, Tristel plc anchors the segment focused on proprietary chemical solutions, competing on the strength of its chlorine dioxide chemistry for manual disinfection processes.
| Leading Market Players |
|---|
| Ecolab Inc. |
| STERIS plc |
| Nanosonics |
| Siemens Healthineers AG |
| GE HealthCare Technologies Inc. |
| CIVCO Medical Solutions |
| Germitec |
| CS Medical LLC |
| Tristel plc |
| Others |
Cost & Logistics Intelligence
Specialty chemical feedstock costs directly influence the production expenses of disinfectants, shaping the final pricing tiers for automated systems and chemical solutions. These upstream fluctuations cascade through the supply chain, impacting procurement decisions for healthcare facilities.
Pricing Analysis
Warranty and service agreements bundled with automated systems significantly influence their overall cost, differentiating premium offerings from basic transactional purchases. The dominant pricing structure for advanced solutions leans towards long-term contracts, integrating consumables and maintenance. Price differentiation stems from regulatory compliance certifications and the level of automation provided. Smaller outpatient clinics exhibit higher price sensitivity compared to large diagnostic centers investing in automated systems.
Supply Chain Analysis
Logistics and freight costs impact the final delivery price of disinfection systems and consumables, particularly for specialized equipment. Manufacturing of automated systems and chemical disinfectants concentrates in the United States, Germany, and Australia. Key raw material dependencies include high-purity hydrogen peroxide and specialized polymers for probe compatibility. Distribution runs through direct sales teams to large hospital networks and third-party distributors for outpatient clinics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The ultrasound probe disinfection market is evolving into a vertical-integration race, as providers pursue comprehensive bundled solutions to control the entire infection prevention workflow. This strategy aims to capture greater value by offering systems, consumables, and services under a single contract.
For Market Incumbents: Anchor existing market share by expanding bundled solutions that integrate automated systems, consumables, and service contracts for large hospital networks. Invest in R&D to develop next-generation automated technologies, such as advanced hydrogen peroxide vapor systems, to counter the persistent use of manual chemical methods. Prioritize CE marking and FDA clearances for new probe models to ensure broad compatibility and maintain a regulatory advantage against new entrants.
For New Entrants and Emerging Players: Begin with targeting underpenetrated segments like smaller outpatient clinics or facilities in emerging markets seeking cost-effective, validated solutions. Focus on developing chemical-free disinfection technologies, such as enhanced UV-C systems, to offer a distinct value proposition. The most penetrable segment remains outpatient clinics due to their lower capital outlay capacity. A go-to-market angle should emphasize ease of use, rapid turnaround, and robust regulatory compliance for specific probe types.
For Investors and Strategic Acquirers: Distressed-cycle entries favor specialized technology providers in Europe, particularly those with strong CE marking credentials, for long-term viability. The market's long-term viability is underpinned by continuous regulatory mandates for patient safety and the accelerating shift towards automated systems. Acquire companies offering proprietary chemical solutions or advanced data integration capabilities for compliance reporting. A key signal to watch is the increasing stringency of infection control guidelines in Southeast Asian healthcare systems.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration for Automated Systems | Consolidates disparate disinfection processes, improving workflow efficiency for diagnostic centers. |
| CE Marking Pathway Acceleration | Ensures compliance with Europe's MDR, allowing market access for advanced disinfection technologies. |
| Hospital System Partnership Expansion | Secures long-term contracts and standardizes infection control protocols across large networks. |
| Software Companion Development | Automates compliance reporting and asset tracking, adding value for end-users. |
| Green Manufacturing Transition | Reduces environmental impact of chemical disinfectants, appealing to eco-conscious facilities. |
Research Approach
Independent corroboration across primary interviews with biomedical engineers, hospital procurement managers, and infection control officers underwrites the qualitative findings. This approach combines insights from industry stakeholders with secondary validation from FDA clearances, CE marking databases, and company annual reports. Bottom-up and top-down triangulation ensures data accuracy and comprehensive market understanding.
The forecast window was anchored to historical reference periods, establishing a robust baseline for projecting market trajectories across the analysis window. An analytical framework modeled segmentation dimensions including product type, application, end user, and technology. Compound Annual Growth Rates were derived from historical performance and anticipated shifts in healthcare capital expenditure trends. Ultrasound procedure volumes and infection control guideline updates served as key forecast inputs.
Underlying measurement precision varies by segment; automated systems and cardiology applications carry tighter precision than others. Forecasts reflect assumptions regarding technological adoption rates and regulatory enforcement, though unforeseen global supply chain disruptions could revise these projections. Stakeholders should weigh assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Infection Control
Sterility Indicators Market
Infection Control
Ear Infection Treatment Market
Infection Control
Global Disease Control and Prevention Vaccine Market
Infection Control
Perianal Infection Treatment Market
Infection Control
Salivary Gland Infection Market
Infection Control
South Africa Antibacterial Soap Market
Infection Control
Sterilization Tunnel Market
Infection Control
Global Disinfection Robots Market
Infection Control
Hand Hygiene Products Market
Infection Control
Medical Disinfectant Wipes Market
Infection Control
Healthcare Associated Infections (HAI) Treatment Market
Infection Control
Asia-Pacific Hand Sanitizer Market
Infection Control
Pertussis Infection Testing Market
Infection Control
Air Sanitizer Market
Infection Control
Global Hospital Disinfectant Products and Services Market
Infection Control
Hand Hygiene Market