
 South Africa Antibacterial Soap Market | 2026-2036
South Africa Antibacterial Soap Market Size, Share, and Industry Trends Forecast 2026-2036
South Africa Antibacterial Soap Market Insights
Retail shelf-space allocation is reconfiguring margin pools from conventional bar formats toward liquid and foam dispensers in South African supermarkets and pharmacies. Unilever leverages its brand architecture across multiple price tiers in mass-market channels. Procter & Gamble sustains manufacturing scale through regional supply hubs serving Southern African markets. Reckitt Benckiser differentiates through healthcare-certified formulations targeting hospital and clinical procurement tenders.
South Africa antibacterial soap comprises surfactant-based cleansing agents incorporating antimicrobial actives such as benzalkonium chloride or chloroxylenol, formulated to reduce bacterial load on skin surfaces during washing. These products serve both domestic hygiene routines and institutional infection prevention protocols in clinical and food-service environments. Liquid soap holds the dominant retail position in urban South African supermarkets, while foam formats capture expanding share in workplace and hospital dispenser installations. Bar soap retains volume in lower-income household segments and rural distribution networks where unit economics favor solid formats. The natural ingredients formulation segment attracts premium positioning among environmentally conscious consumers in Cape Town and Johannesburg metropolitan markets.
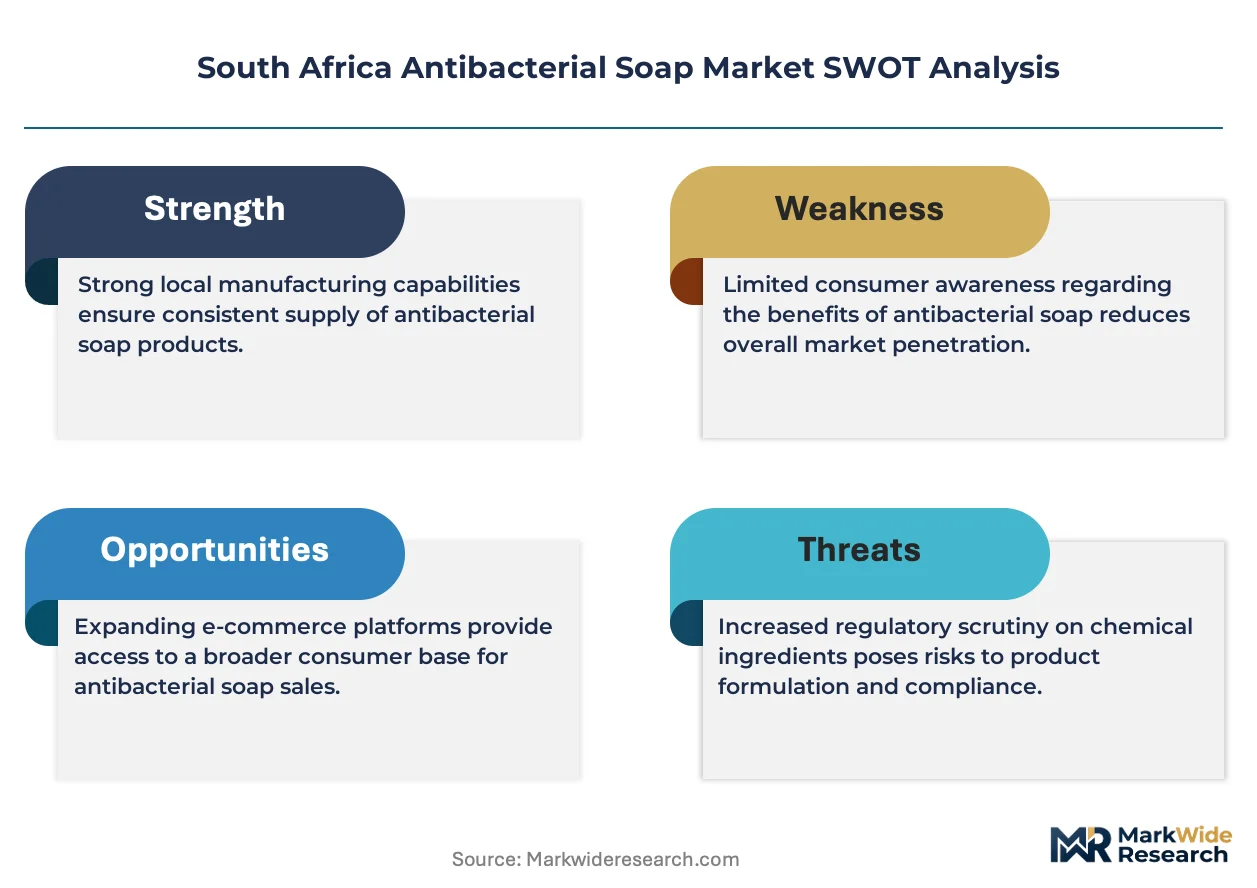
South Africa's National Regulator for Compulsory Specifications mandates compliance with SANS 1828 for antimicrobial soaps, while the Department of Health enforces infection control standards in public healthcare facilities that specify approved active ingredients. The South African Health Products Regulatory Authority monitors therapeutic claims that cross into pharmaceutical classification, creating compliance boundaries between cosmetic and drug-grade products. Stakeholders must track pending amendments to antibacterial active ingredient schedules and align R&D pipelines with shifting regulatory tolerances for chemical versus natural antimicrobial systems.
Market Dynamics
South Africa's National Regulator for Compulsory Specifications is compressing formulation freedom through mandatory SANS 1828 compliance, forcing manufacturers to abandon legacy chemistries and rebuild supply chains around approved actives. This regulatory compression acts as the dominant structural force reshaping competitive positioning and R&D allocation across the value chain.
Growth Catalysts
- Hospital infection control mandates:The Department of Health enforces stricter hand-hygiene protocols in Gauteng and Western Cape public facilities, expanding institutional procurement volumes for certified antimicrobial formulations.
- Triclosan phase-out regulations:SANS 1828 amendments prohibit specific actives, creating replacement demand for benzalkonium chloride and chloroxylenol alternatives that comply with revised safety thresholds.
- Urban household hygiene elevation:Johannesburg and Cape Town metropolitan consumers demonstrate elevated willingness-to-pay for liquid and foam dispenser formats in supermarket and pharmacy channels.
Market Restraints
- Active ingredient supply concentration:Specialty chemical suppliers in India and China control upstream benzalkonium chloride production, exposing South African formulators to import cost volatility and currency fluctuation risk.
- Natural ingredient cost premiums:Plant-derived antimicrobial actives command 40-60% higher input costs versus synthetic alternatives, compressing margins for premium-positioned domestic brands targeting environmentally conscious segments.
- Rural distribution infrastructure gaps:Bar soap dominates lower-income and rural networks where cold-chain and dispenser infrastructure limitations prevent liquid format penetration, fragmenting addressable market geometry.
Strategic Opportunities
- KwaZulu-Natal institutional expansion:Durban metropolitan hospital clusters and food-service processing zones present underpenetrated demand for bulk dispenser installations and clinical-grade certification.
- Biodegradable surfactant convergence:Formulators combining antimicrobial efficacy with compostable base chemistries capture premium shelf positioning in Cape Town's sustainability-focused retail channels.
- E-commerce direct-to-household channels:Subscription refill models bypass traditional wholesale distribution, enabling margin recovery and customer data capture in middle-income urban segments.
Industry Challenges
- Formulation chemist talent scarcity:South African universities produce limited graduates with combined surfactant chemistry and regulatory compliance expertise, extending product development timelines for SANS 1828-aligned launches.
- Dual certification complexity:Products crossing cosmetic-therapeutic boundaries require parallel South African Health Products Regulatory Authority and National Regulator for Compulsory Specifications approvals, creating procedural bottlenecks.
- Legacy equipment retooling costs:Bar-dominant manufacturing assets require capital-intensive conversion to liquid and foam production lines, straining mid-tier manufacturer balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Africa Antibacterial Soap Market |
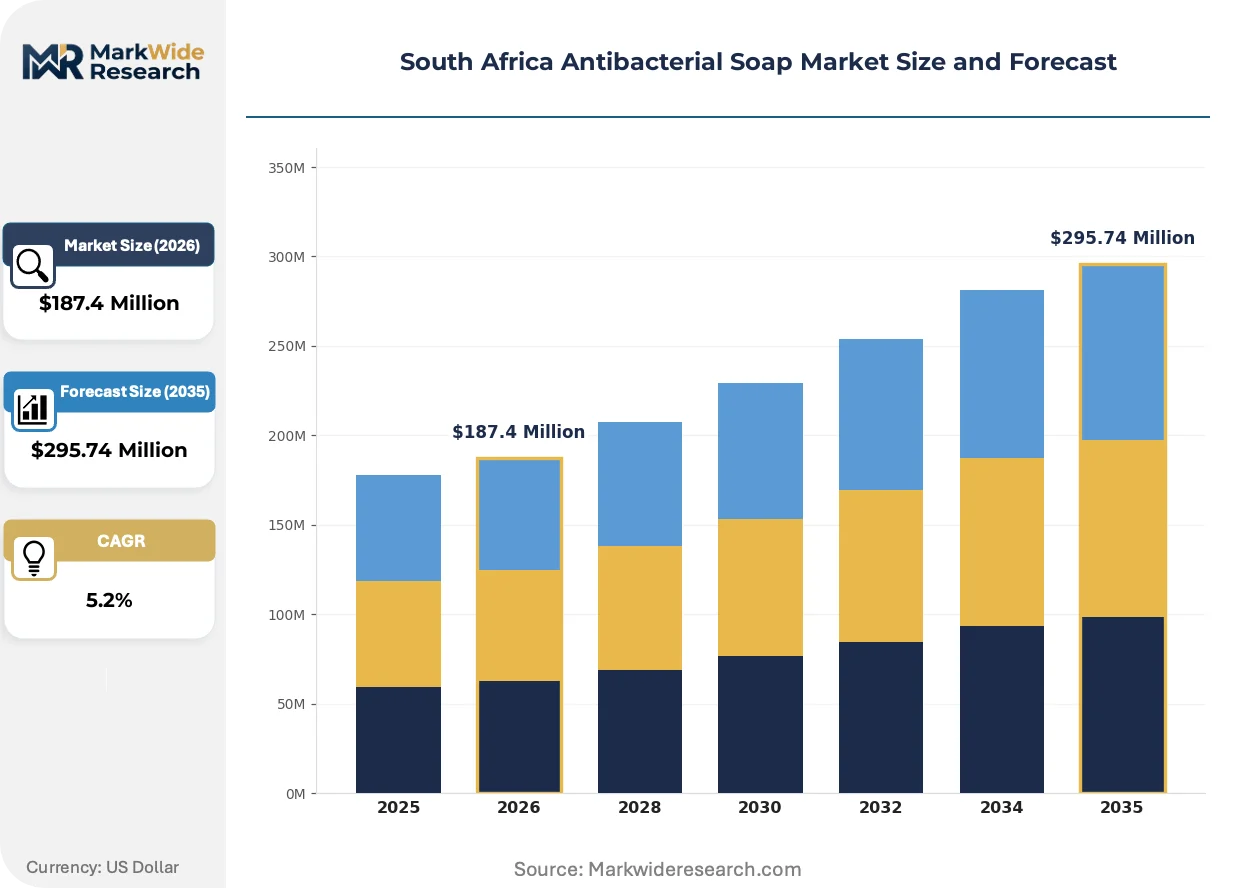
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $295.74 Million |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Soap, Bar Soap, Foam Soap, Gel Soap Distribution Channel: Online Retail, Supermarkets, Pharmacies, Convenience Stores Customer Type: Households, Hospitals, Schools, Workplaces Formulation: Natural Ingredients, Chemical Compound, Organic, Conventional |
| Companies Covered | Beiersdorf, GOJO Industries, Unilever, Ecolab, Henkel, Procter & Gamble, SC Johnson Professional, Kimberly-Clark Professional, Reckitt Benckiser, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Africa Antibacterial Soap Market Trends and Innovations
Antimicrobial soap chemistry is undergoing forced migration away from legacy actives, while distribution architecture reconfigures around dispenser-centric consumption models. These intersecting shifts are compressing traditional format advantages and rewarding regulatory agility.
Triclosan-based formulations, once standard across mass-market antibacterial soaps, are migrating from South African retail and institutional channels under SANS 1828 prohibition. Hospital procurement officers in Johannesburg and Cape Town metropolitan corridors are accelerating adoption of chloroxylenol and benzalkonium chloride alternatives to maintain compliance with Department of Health tender specifications. This chemistry transition is compressing market share for legacy inventory holders while opening formulation partnerships between domestic manufacturers and specialty chemical suppliers.
South Africa's National Regulator for Compulsory Specifications is tightening labeling disclosure requirements for antimicrobial efficacy claims, forcing manufacturers to substantiate bacterial load reduction percentages through standardized testing protocols. The industrial consequence is a bifurcation between cosmetic-grade products restricted to general hygiene positioning and pharmaceutical-grade formulations eligible for clinical procurement channels. Hospital and clinical segments are responding by consolidating supplier lists around manufacturers with dual certification capability, squeezing out uncertified competitors from institutional tenders.
Urban South African households are abandoning single-use bar soap purchases in favor of refillable liquid and foam dispenser systems, particularly in middle-income Johannesburg and Cape Town suburbs. Supermarket and pharmacy channels are reallocating shelf space toward concentrate refill pouches and automatic dispenser hardware, displacing traditional wrapped bar formats from premium retail positioning. This consumption-pattern shift is most visible in metropolitan corridors where water-scarcity awareness and convenience preferences converge to favor measured-dose dispensing over conventional bar usage.
South Africa Antibacterial Soap Market Segmentation
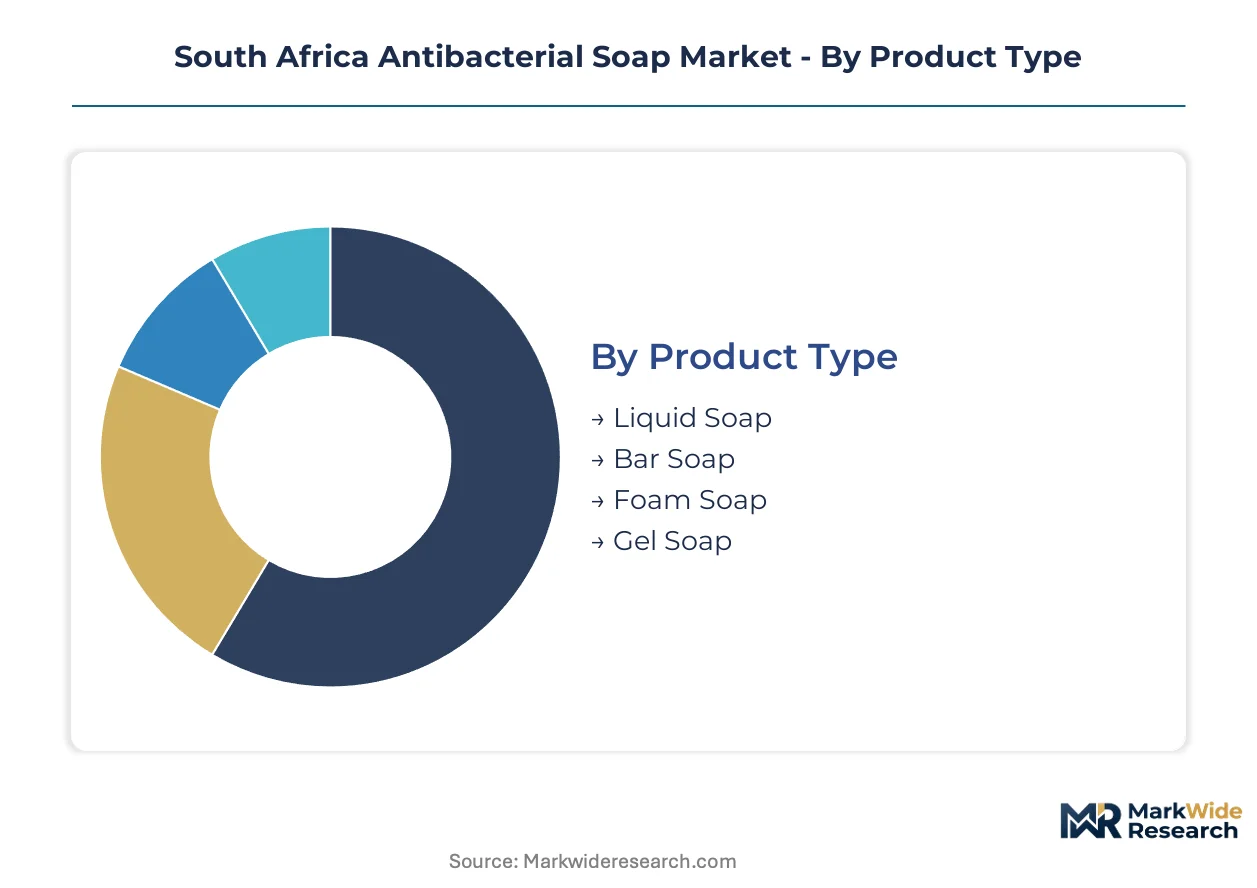
Antibacterial soap manufacturers in South Africa configure service networks and technical support intensity around product format complexity and institutional certification requirements. Liquid and foam dispenser systems demand installation maintenance and refill logistics that bar formats never required.
Product Type:
After-sales-service intensity varies dramatically across formats, with dispenser-dependent systems requiring ongoing technical support and bulk supply contracts that reshape manufacturer-customer relationships.
- Liquid Soap:Surfactant-based formulations packaged in pump dispensers or refill pouches dominate urban retail channels. Johannesburg and Cape Town supermarkets allocate expanding shelf space to concentrate refill systems as metropolitan households abandon single-use packaging. Demand concentrates in middle-income suburbs where convenience and measured dosing outweigh unit cost premiums.
- Bar Soap:Solid alkali-fat formulations retain cost advantages in lower-income segments and rural distribution networks lacking cold-chain infrastructure. KwaZulu-Natal and Eastern Cape provinces maintain volume concentration where unit economics favor wrapped bars over liquid logistics.
- Foam Soap:Air-infused dispensers reduce water consumption and extend product yield per unit, attracting workplace and hospital procurement tenders in Gauteng and Western Cape metropolitan corridors.
- Gel Soap:Thickened aqueous formulations target premium positioning in pharmacy channels and hospitality installations requiring visual differentiation and controlled viscosity.
Liquid soap holds the largest share; momentum sits with foam formats in institutional channels.
Distribution Channel:
Channel selection determines margin capture and customer data access, with direct digital routes offering subscription economics that wholesale intermediaries cannot match.
- Online Retail:E-commerce platforms and direct-to-consumer subscription models enable recurring revenue capture and usage data harvesting in urban middle-income segments. Cape Town and Johannesburg households demonstrate highest adoption of auto-replenishment services for dispenser refills.
- Supermarkets:Mass-market retail chains control volume placement and private-label development, compressing branded manufacturer margins through slotting fee structures and promotional calendar demands.
- Pharmacies:Healthcare-certified formulations and therapeutic-grade positioning command premium pricing in retail pharmacy networks serving clinical-adjacent consumers.
- Convenience Stores:Impulse-oriented small-format retail captures emergency replenishment and travel-size purchases in transport hubs and fuel station networks.
Supermarkets retain volume leadership; online retail climbs fastest among urban professional households.
Customer Type:
Procurement sophistication separates institutional buyers with tender compliance requirements from household consumers driven by brand familiarity and shelf availability.
- Households:Domestic consumers in metropolitan corridors drive liquid and foam format adoption, while rural households sustain bar soap demand through price-sensitive purchasing patterns.
- Hospitals:Public and private healthcare facilities in Gauteng and Western Cape enforce SANS 1828-compliant procurement specifications, consolidating supplier lists around dual-certified manufacturers with clinical-grade production capacity.
- Schools:Educational institutions represent fragmented demand with varying compliance enforcement, creating opportunities for basic certified formulations in bulk dispenser installations.
- Workplaces:Corporate offices and food-service processing facilities in Durban and Johannesburg metropolitan areas adopt measured-dose systems to satisfy occupational health protocols and water conservation targets.
Hospitals generate the highest per-unit value; households provide the broadest volume base.
Formulation:
Regulatory pressure on active ingredient safety profiles is fragmenting R&D investment between synthetic chemistry optimization and botanical antimicrobial development.
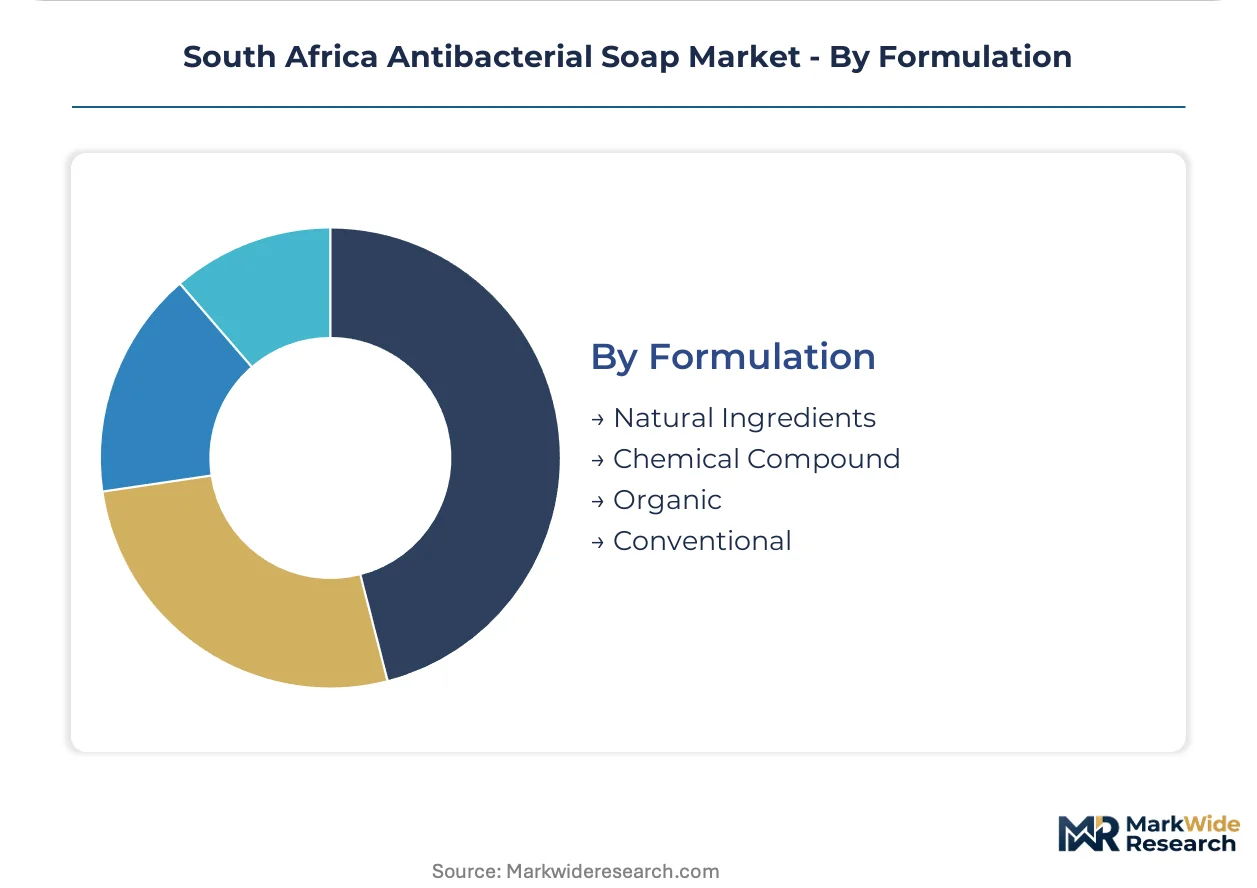
- Natural Ingredients:Plant-derived antimicrobial actives such as tea tree oil and eucalyptus extracts attract premium positioning among environmentally conscious consumers in Cape Town's sustainability-focused retail channels, though input cost premiums compress margins.
- Chemical Compound:Benzalkonium chloride and chloroxylenol formulations dominate institutional procurement following triclosan prohibition under SANS 1828 amendments, with supply concentration in Indian and Chinese specialty chemical producers.
- Organic:Certified organic surfactant bases command niche positioning in premium pharmacy and health-food retail segments with limited volume scale.
- Conventional:Standard synthetic formulations without specialized certification serve price-competitive mass-market channels where regulatory compliance remains the primary differentiator.
Chemical compound formulations retain institutional dominance; natural ingredients gain fastest in metropolitan premium channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Gauteng and Western Cape provinces consume liquid and foam dispenser formats at rates double those of rural Eastern Cape and Limpopo, where bar soap retains cost-driven dominance. Metropolitan infrastructure gaps fragment distribution geometry across South Africa's nine provinces.
Gauteng
Johannesburg hospital clusters and corporate headquarters drive institutional procurement of SANS 1828-certified foam dispensers. The Department of Health enforces hand-hygiene protocols in public facilities across the province. Tshwane metropolitan area hosts manufacturing plants serving Southern African export markets.
Western Cape
Cape Town's sustainability-conscious households command premium positioning for natural-ingredient liquid refills in pharmacy and supermarket channels. The National Regulator for Compulsory Specifications mandates labeling compliance for all antimicrobial products sold in provincial retail networks. Stellenbosch food-processing zones adopt measured-dose workplace systems.
KwaZulu-Natal
Durban metropolitan hospital procurement tenders present underpenetrated demand for clinical-grade bulk installations. Provincial health department specifications align with national infection control standards. Richards Bay industrial corridors require occupational hygiene protocols in manufacturing facilities.
Eastern Cape
Rural distribution networks sustain wrapped bar soap volume through price-sensitive purchasing patterns in lower-income segments. Cold-chain infrastructure limitations prevent liquid format penetration outside Port Elizabeth metropolitan area. Mthatha and Butterworth retail clusters rely on traditional wholesale channels.
South Africa Antibacterial Soap Market Competitive Landscape
Capability concentration sits with multinational manufacturers holding dual certification capacity; scale advantage sits with domestic distributors controlling rural wholesale networks. The market structures around three tiers: global FMCG conglomerates with regional supply hubs, institutional specialists with healthcare certification, and local formulators serving price-competitive bar soap segments. Dominant competitive moves include portfolio diversification across liquid-foam-bar formats and strategic partnerships with specialty chemical suppliers for SANS 1828-compliant actives.
Within the multinational tier, Unilever and Procter & Gamble occupy positions anchored by mass-market brand architecture across multiple price levels. Reckitt Benckiser exemplifies the institutional-specialist archetype through healthcare-certified formulations targeting hospital procurement channels. These three companies represent divergent strategic postures: Unilever leverages retail shelf-space allocation, Procter & Gamble sustains manufacturing scale through regional hubs, and Reckitt Benckiser concentrates on clinical-grade certification boundaries.
| Leading Market Players |
|---|
| Beiersdorf |
| GOJO Industries |
| Unilever |
| Ecolab |
| Henkel |
| Procter & Gamble |
| SC Johnson Professional |
| Kimberly-Clark Professional |
| Reckitt Benckiser |
| Others |
Pricing and Supply Chain Analysis
The Durban-Johannesburg freight corridor's fuel surcharge volatility transmits directly into landed cost spreads for benzalkonium chloride shipments, compressing margin pools for domestic formulators while amplifying price differentiation between synthetic and natural antimicrobial tiers.
Pricing Analysis
Long-term offtake contracts dominate institutional procurement in Gauteng hospital systems, while spot purchasing governs rural wholesale channels. Pricing stratifies across clinical-grade, standard-certified, and economy tiers based on SANS 1828 compliance depth and dispenser installation bundling. Cost compression in natural ingredient formulations is intensifying because tea tree oil and eucalyptus extract premiums run 40-60% above synthetic alternatives. Rural bar soap buyers exhibit highest price sensitivity; certified foam dispenser contracts show lowest.
Supply Chain Analysis
Extended payment terms from Indian and Chinese specialty chemical suppliers strain working capital for South African formulators sourcing benzalkonium chloride and chloroxylenol actives. Upstream concentration rests on Gujarat and Jiangsu province manufacturers for antimicrobial inputs, while surfactant bases draw from Malaysian palm derivative processors. Single-source vulnerability runs through the benzalkonium chloride import channel. Distribution runs through Johannesburg-based wholesale networks serving metropolitan retail and institutional clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory fragmentation around SANS 1828 compliance tiers and natural ingredient certification is carving out distinct competitive niches that reward specialized positioning over scale dominance.
For Market Incumbents: Harden dual certification capacity at existing production facilities to defend against uncertified competitors losing hospital tender access. Deepen backward integration into surfactant chemistry through captive supply partnerships with Malaysian base material processors, insulating margin pools from currency fluctuation.
For New Entrants and Emerging Players: Build out biodegradable surfactant-antimicrobial convergence formulations targeting Cape Town's sustainability-focused pharmacy channels. KwaZulu-Natal hospital clusters present the most penetrable institutional geography given current supplier list consolidation gaps. Pursue direct-to-household subscription models bypassing wholesale intermediaries.
For Investors and Strategic Acquirers: Healthcare-certified domestic formulators with SANS 1828 alignment and existing Gauteng production footprint represent the most defensible acquisition archetype. Long-term viability hinges on regulatory agility across the 5-10 year chemical-to-natural formulation transition. Watch for National Regulator for Compulsory Specifications amendments to active ingredient schedules as the critical inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical-Grade Certification Investment | SANS 1828 dual certification unlocks Gauteng hospital procurement tenders. |
| Backward Integration into Surfactant Supply | Captive Malaysian palm derivative sourcing insulates margins from rand volatility. |
| Direct-to-Consumer Subscription Launch | Auto-replenishment models capture Johannesburg middle-income household data. |
| Biodegradable Formulation Development | Compostable base chemistry commands premium shelf positioning in Cape Town. |
| KwaZulu-Natal Distribution Expansion | Durban hospital cluster penetration addresses underexploited institutional demand. |
Research Methodology
Cross-validation between primary interviews with procurement officers at Gauteng public hospitals and secondary analysis of National Regulator for Compulsory Specifications filing records anchors the qualitative findings. Conversations with surfactant chemistry formulators, retail category buyers at Johannesburg supermarket chains, and specialty chemical import distributors informed supply chain dynamics. Secondary sources include SANS 1828 compliance databases, South African Health Products Regulatory Authority therapeutic claim registers, and customs import records for benzalkonium chloride shipments. Bottom-up channel volume estimates and top-down macroeconomic scaling were triangulated for consistency.
Calibration against historical format adoption curves and regulatory phase-out timelines shaped the projection framework across the analysis window. Segmentation dimensions modeled include product format (liquid, foam, bar, gel), distribution channel, customer type, and formulation chemistry. CAGRs were derived from trend extrapolation of urban household dispenser adoption and institutional procurement growth. Forecast inputs incorporated SANS 1828 amendment probability and natural ingredient cost trajectory assumptions.
Practitioners should monitor National Regulator for Compulsory Specifications enforcement intensity and specialty chemical import tariff adjustments for early signals. Forecasts reflect documented assumptions about regulatory stability and currency band movement. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Infection Control
Point of Care Infection Control Market
Infection Control
Global Viral Clearance Services Market
Infection Control
Global Wall Mounted Ozone Disinfection Machine Market
Infection Control
Global High Level Disinfection Services Market
Infection Control
Australia Healthcare Surface Disinfectant Wipes Market
Infection Control
Dental Infection Treatment Market
Infection Control
Medical Washer Disinfector Market
Infection Control
UV Disinfection Equipment Market
Infection Control
Blood Stream Infection Testing Market
Infection Control
United States Hand Sanitizer Market
Infection Control
Global Sepsis Therapeutics Market
Infection Control
Intra Abdominal Infection Market
Infection Control
Infection Control Supplies Market
Infection Control
Healthcare Protective Masks Market
Infection Control
Europe Ultrasound Probe Disinfection Market
Infection Control
Global Hospital Acquired Infection Control Market