
 Pertussis Infection Testing Market | 2026-2036
Pertussis Infection Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Pertussis Infection Testing Market Analytics
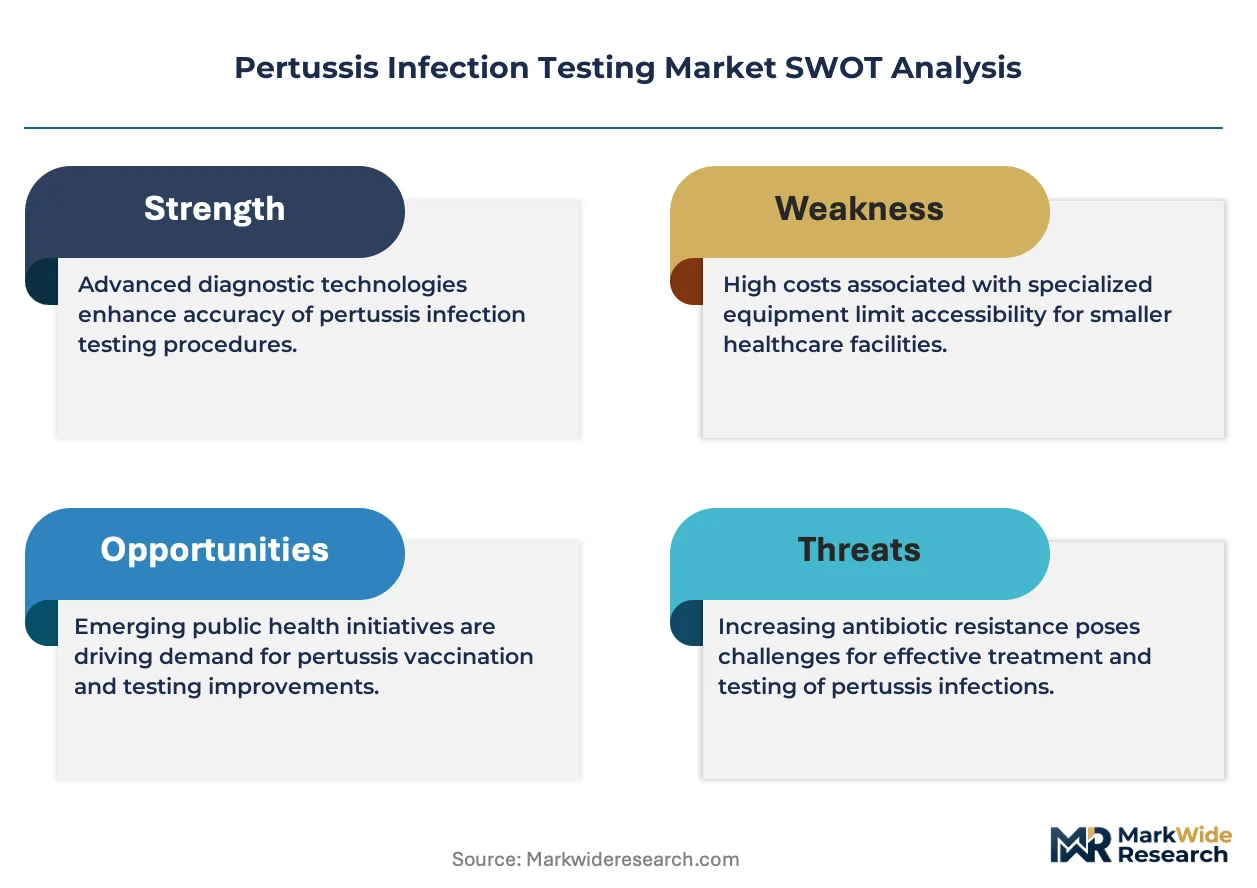
The capital-intensity divergence between automated molecular platform suppliers and conventional immunoassay providers is redrawing competitive boundaries in pertussis diagnostics. Cepheid leverages its GeneXpert cartridge infrastructure to dominate near-patient respiratory testing workflows. Thermo Fisher Scientific sustains broad reagent and instrument portfolios that anchor high-throughput laboratory contracts. BioMérieux SA differentiates through integrated microbiology platforms that span culture confirmation to molecular identification.
Pertussis infection testing encompasses laboratory methods for detecting Bordetella pertussis nucleic acid or antibodies, primarily through nucleic acid amplification tests run on thermal cyclers with probe-based detection chemistries and cycling parameters typically spanning 45-60 minutes. These assays serve outbreak surveillance, pediatric differential diagnosis, and vaccine efficacy monitoring in public health and clinical settings. PCR-based technology occupies the premium tier of this market due to superior sensitivity during the paroxysmal phase when bacterial loads decline below culture detection thresholds. Test kits and reagents generate recurring revenue streams that outpace instrument placements in margin contribution. Application demand tilts toward hospital laboratories managing emergency department throughput for undifferentiated cough illness.
The FDA regulates in vitro diagnostic platforms through premarket notification and emergency use authorization pathways that shape product development timelines for pertussis assays. CDC laboratory recommendations and CLIA complexity classifications determine where specific test formats deploy across hospital, reference, and point-of-care settings. Stakeholders must monitor evolving WHO prequalification criteria and multiplex respiratory panel reimbursement decisions that will determine platform economics.
Market Dynamics
The transition from culture-based confirmation to molecular diagnostics is compressing turnaround times and redistributing testing volume toward hospital laboratories with thermal cycler infrastructure.
Growth Catalysts
- CDC Surveillance Mandates:United States public health reporting requirements for pertussis cases sustain consistent test demand across hospital and reference laboratory networks.
- Multiplex Respiratory Panels:Laboratory investment in syndromic testing platforms expands Bordetella pertussis inclusion alongside influenza and RSV detection.
- WHO Laboratory Strengthening:Capacity-building initiatives in low- and middle-income countries broaden access to nucleic acid amplification testing for outbreak response.
Market Restraints
- Reagent Cost Concentration:Probe-based detection chemistries and master mix formulations tie laboratory budgets to volatile polymerase supply chains.
- CLIA Complexity Barriers:Moderate and high-complexity test classifications restrict molecular assay deployment to certified hospital laboratories, excluding primary care clinics.
- Serological Cross-Reactivity:Enzyme immunoassays for pertussis antibodies generate false positives from Bordetella parapertussis and other respiratory pathogens, limiting clinical utility.
Strategic Opportunities
- Point-of-Care Molecular Miniaturization:Cartridge-based platforms with 30-minute turnaround times address emergency department triage workflows for undifferentiated cough illness.
- India Diagnostic Expansion:CDSCO streamlined approval pathways and government immunization surveillance programs create entry points for automated platform suppliers.
- Vaccine Efficacy Monitoring:Post-market surveillance of acellular pertussis vaccines generates recurring contract revenue for reference laboratories with validated PCR protocols.
Industry Challenges
- Multiplex Validation Burden:Laboratory-developed tests combining pertussis with respiratory targets require extensive analytical and clinical validation against FDA-cleared comparators.
- Specimen Collection Standardization:Nasopharyngeal swab technique variability and transport medium compatibility issues degrade nucleic acid yield in clinical practice.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pertussis Infection Testing Market |
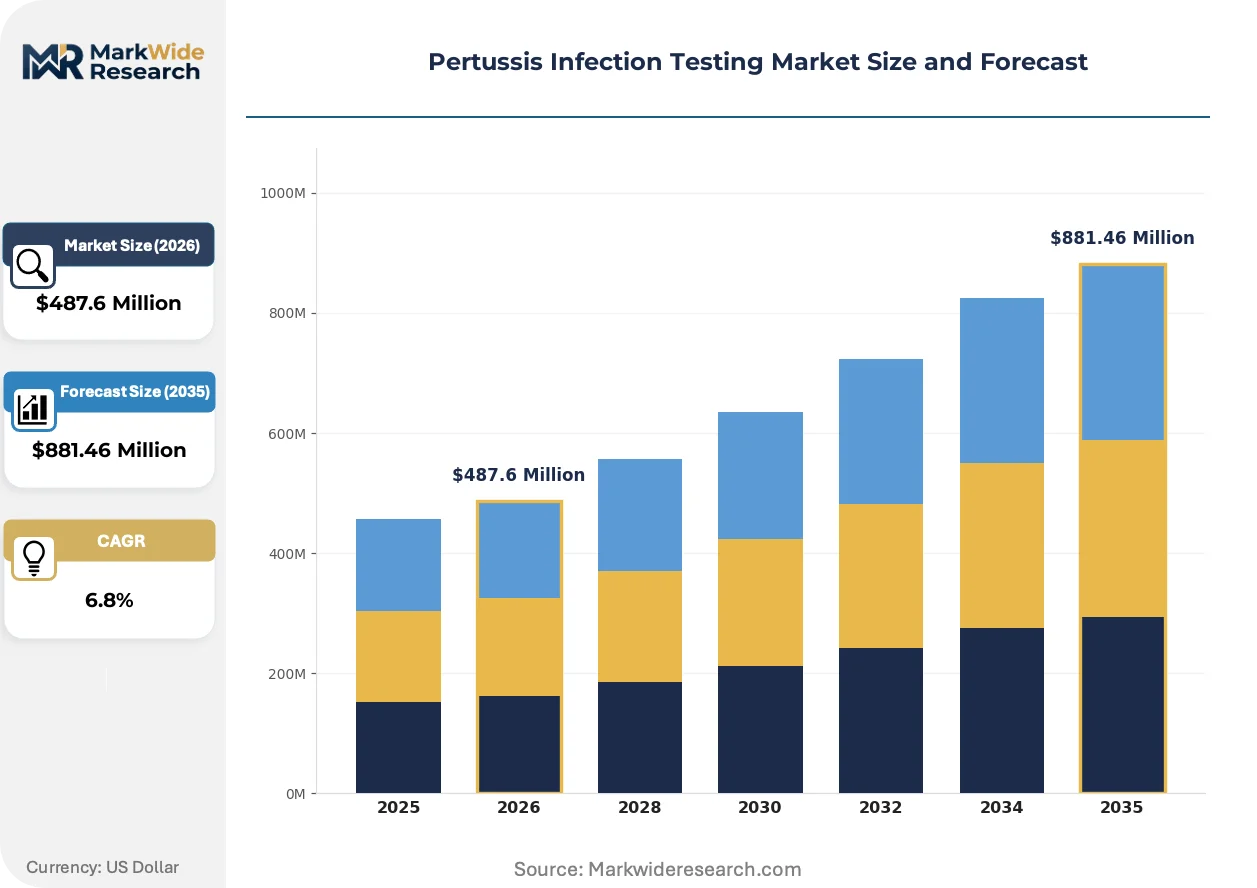
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Test Kits, Reagents, Instruments, Software Application: Laboratories, Hospitals, Clinics, Research Centers End User: Healthcare Professionals, Patients, Diagnostic Centers, Pharmacists Technology: ELISA, PCR, LAMP, Immunofluorescence |
| Companies Covered | Cepheid, Quidel Corporation, Thermo Fisher Scientific, Inc., Becton, Dickinson and Company, Meridian Bioscience, Inc., BioMérieux SA, Hologic, Inc., Roche Diagnostics, Abbott Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pertussis Infection Testing Market Evolving Landscape
Digital PCR and CRISPR-based detection chemistries are advancing sensitivity thresholds while cloud-connected instrument platforms enable real-time surveillance data transmission to health authorities.
Loop-mediated isothermal amplification (LAMP) is supplanting conventional thermal cycling in near-patient settings where infrastructure constraints limit real-time PCR deployment. Community health centers and urgent care networks in rural United States counties are adopting battery-powered LAMP devices with visual readout. This shift is compressing the addressable market for central laboratory molecular testing in geographies with dispersed populations.
FDA's emergency use authorization pathway for respiratory multiplex panels has accelerated assay development timelines while tightening post-authorization performance monitoring requirements. Manufacturers must now submit real-world analytical data within 12 months of commercial launch. High-throughput hospital laboratories in the United States are responding by consolidating vendor relationships with suppliers possessing validated EUA portfolios.
Hospital procurement committees now bundle respiratory pathogen testing contracts across virology and bacteriology menus, displacing standalone pertussis assay purchasing. Integrated delivery networks in the United States negotiate multi-year reagent supply agreements that lock in platform exclusivity. This concentration is visible most acutely in pediatric hospital systems managing seasonal cough illness surges.
Pertussis Infection Testing Market Segmentation
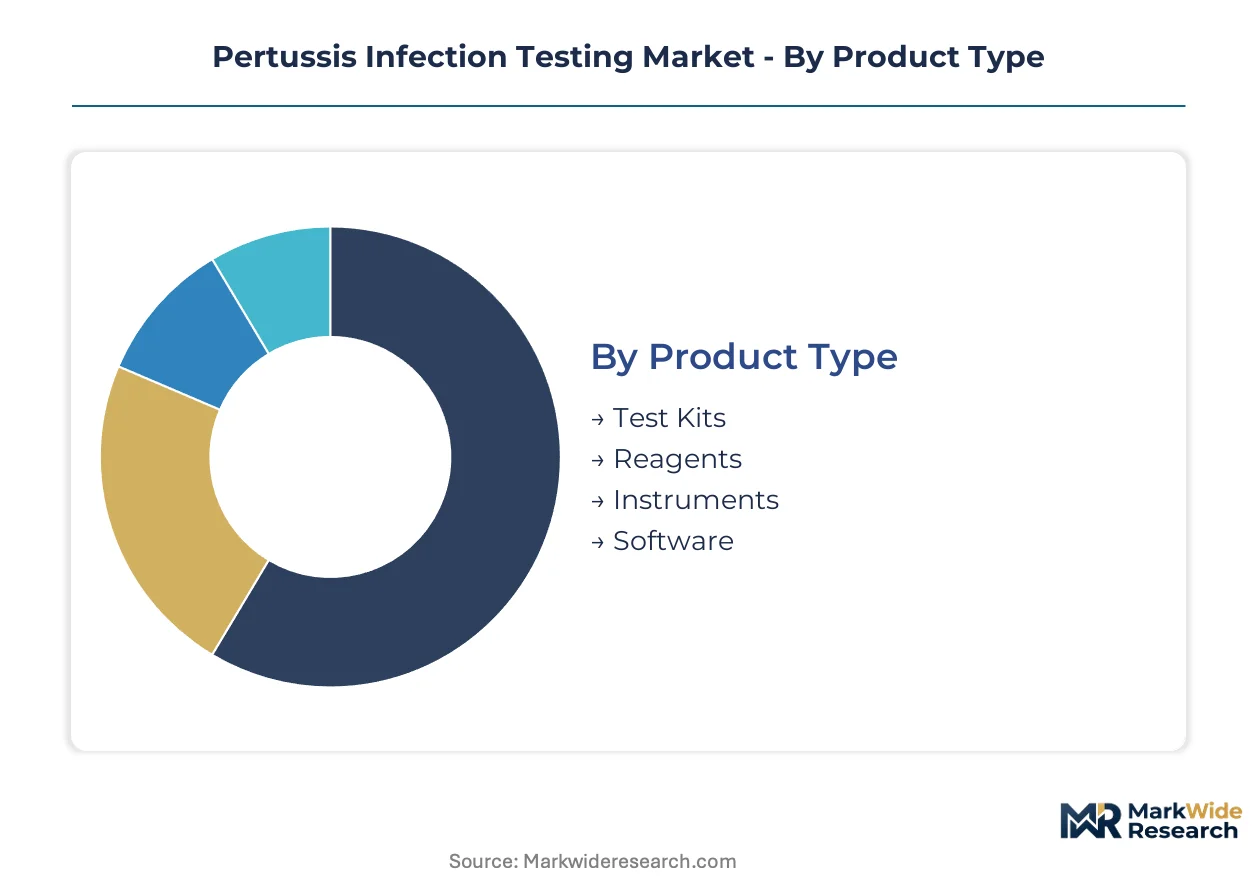
Pertussis testing markets fragment across four dimensions that determine procurement patterns and margin capture. Product type dictates recurring revenue potential. Application and end-user concentration shape platform selection. Technology choice locks laboratories into specific workflow investments.
Product Type:
Reagent and consumable margins substantially outpace capital equipment returns across installed instrument bases.
- Test Kits:Pre-formulated PCR panels and single-plex pertussis assays ship in lyophilized or liquid formats with probe-based detection chemistries. Hospital laboratories in the United States prioritize FDA-cleared kits for CLIA compliance, particularly during seasonal respiratory surge periods.
- Reagents:Master mixes, extraction buffers, and positive controls generate recurring revenue streams that anchor long-term supplier relationships. Multiplex respiratory panel expansion in diagnostic laboratories drives master mix volume concentration.
- Instruments:Thermal cyclers, real-time PCR platforms, and automated nucleic acid extraction systems require capital approval cycles spanning 12-18 months. Reference laboratories prioritize throughput scalability over point-of-care portability.
- Software:Laboratory information system modules and cloud-based surveillance reporting tools integrate with public health databases. CDC reporting mandates in the United States sustain demand for automated case notification functionality.
The dominant share belongs to Reagents, while Test Kits are closing the gap fastest.
Application:
Testing volume concentrates where emergency department throughput demands rapid pathogen identification.
- Laboratories:Hospital core laboratories and reference facilities process high-complexity molecular assays with 4-6 hour turnaround times. CLIA certification requirements concentrate pertussis PCR in these settings.
- Hospitals:Emergency departments and pediatric wards drive stat testing demand for undifferentiated cough illness triage. Infection control protocols mandate rapid Bordetella pertussis exclusion.
- Clinics:Primary care and urgent care settings increasingly adopt waived or moderate-complexity assays. LAMP-based platforms address infrastructure constraints in rural United States counties.
- Research Centers:Vaccine efficacy studies and outbreak genomic surveillance require validated PCR protocols with sequencing confirmation capabilities.
Hospitals command the largest application share, though Clinics are expanding most quickly through point-of-care miniaturization.
End User:
Professional versus patient-directed testing splits procurement authority and reimbursement pathways.
- Healthcare Professionals:Physicians and nurse practitioners order laboratory-based PCR through electronic health record integration. CDC surveillance reporting flows through these clinical decision-makers.
- Patients:Direct-access testing in some United States jurisdictions permits self-ordered serology, though molecular diagnostics remain prescription-controlled.
- Diagnostic Centers:Independent reference laboratories compete on turnaround time and panel breadth. Multiplex respiratory contracts determine vendor selection.
- Pharmacists:Retail clinic expansion positions pharmacists for point-of-care respiratory testing in certain state jurisdictions.
Healthcare Professionals retain dominant ordering authority, while Diagnostic Centers are gaining share fastest through integrated delivery network contracting.
Technology:
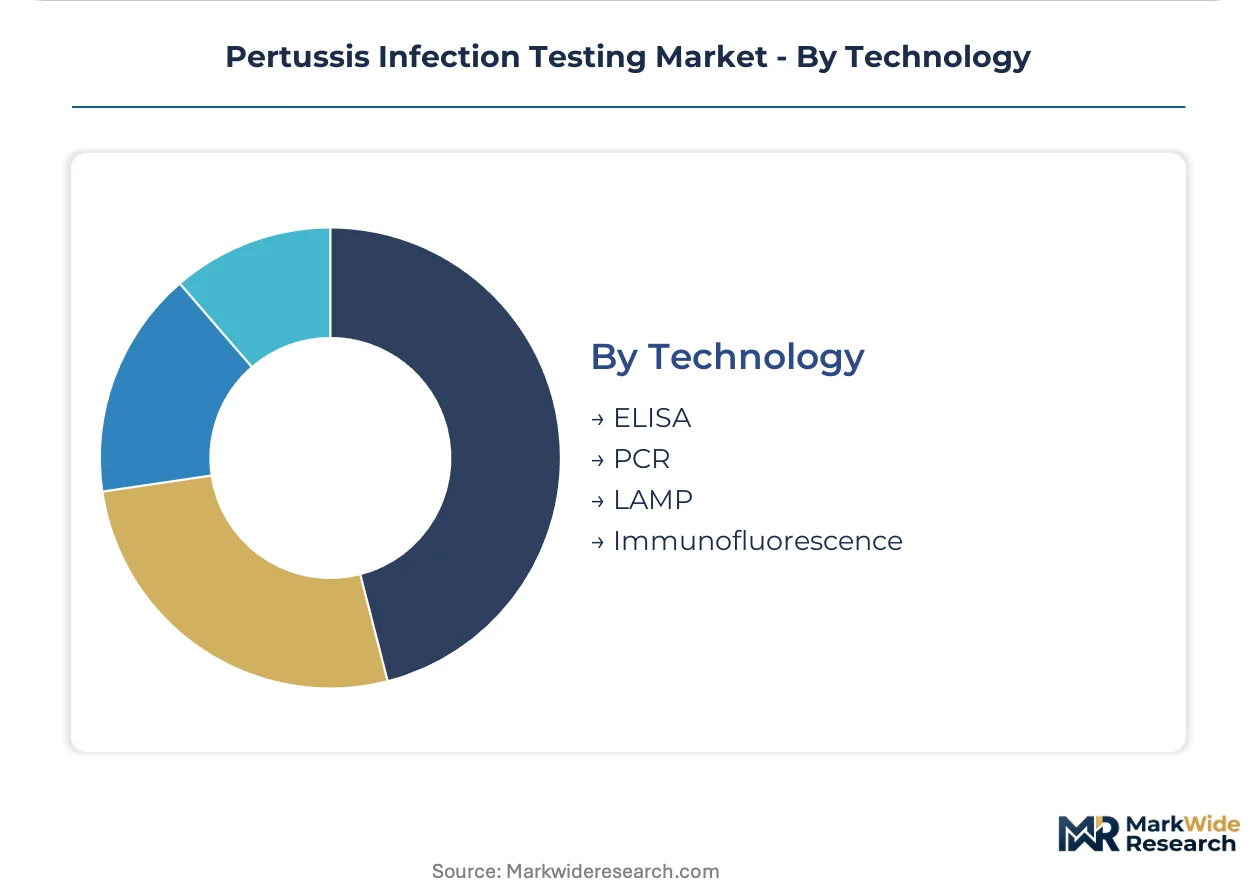
Sensitivity thresholds and infrastructure requirements partition the addressable market by setting type.
- PCR:Real-time thermal cycling with probe-based detection delivers superior analytical sensitivity during paroxysmal phase when bacterial loads decline. Hospital laboratories with existing thermal cycler infrastructure standardize on this platform.
- LAMP:Isothermal amplification operates without thermal cycling equipment, enabling battery-powered deployment in near-patient settings. Community health centers adopt visual readout formats where laboratory infrastructure is absent.
- ELISA:Enzyme immunoassays for pertussis antibodies offer lower cost but suffer cross-reactivity with Bordetella parapertussis. Serological confirmation sees declining clinical utility.
- Immunofluorescence:Direct fluorescent antibody testing provides rapid results but requires skilled microscopy interpretation. Reference laboratories retain this capability for culture confirmation.
PCR holds the dominant technology position, while LAMP is climbing the fastest through point-of-care expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across geographies. Hospital laboratories in the United States absorb premium PCR reagent costs through bundled reimbursement, while diagnostic centers in India prioritize platform economics over sensitivity thresholds. European reference laboratories occupy a middle position, balancing WHO prequalification requirements against national health technology assessment constraints.
United States
Emergency departments in pediatric hospital systems drive stat testing demand for undifferentiated cough illness triage. CDC surveillance mandates require mandatory pertussis case reporting through the National Notifiable Diseases Surveillance System. The Boston-Cambridge biotechnology corridor anchors molecular diagnostic platform development, with hospital networks consolidating vendor contracts across respiratory pathogen menus.
Germany
Reference laboratories serving the statutory health insurance system process high-complexity molecular assays with stringent turnaround requirements. The In-Vitro Diagnostics Regulation (IVDR) compliance deadlines reshape assay validation protocols for Bordetella pertussis detection. The Rhine-Main metropolitan region concentrates diagnostic platform manufacturing and reagent formulation capacity for Central European distribution.
India
Government immunization surveillance programs generate demand for affordable nucleic acid amplification testing in district hospital networks. CDSCO streamlined approval pathways for automated diagnostic platforms accelerate market entry timelines. The Hyderabad-Bengaluru pharmaceutical corridor hosts contract research organizations validating PCR protocols for vaccine efficacy monitoring contracts.
Japan
Pediatric infectious disease specialists in university hospitals prioritize analytical sensitivity during paroxysmal phase diagnosis. PMDA regulatory consultations for multiplex respiratory panels determine product development sequencing for domestic manufacturers. The Kansai region's medical device cluster specializes in miniaturized thermal cycler components for near-patient deployment.
Brazil
Public health laboratories in São Paulo and Rio de Janeiro manage outbreak response capacity for pertussis surveillance in densely populated urban centers. ANVISA post-market surveillance requirements for in vitro diagnostics shape quality management system investments. The São Paulo state health secretariat operates the largest reference laboratory network in Latin America, processing syndromic respiratory panels for the national health system.
Pertussis Infection Testing Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in pertussis diagnostics. The upper tier combines automated molecular platform manufacturing with broad reagent portfolios that anchor multi-year hospital contracts. Specialist competitors concentrate on single-plex assays or regional distribution advantages. Three archetypes predominate: integrated life science conglomerates with thermal cycler infrastructure, dedicated diagnostic platform specialists with cartridge-based workflows, and reference laboratory service providers with validated PCR protocols. Competitive moves center on multiplex respiratory panel bundling and point-of-care miniaturization to capture emergency department triage workflows.
Among integrated diagnostic conglomerates, Thermo Fisher Scientific and Roche Diagnostics exemplify the scale-driven archetype with broad reagent and instrument portfolios spanning high-throughput laboratory contracts. Cepheid occupies a distinct position within the near-patient specialist tier, leveraging cartridge infrastructure for rapid turnaround applications. These three companies represent contrasting strategic postures: one emphasizing comprehensive laboratory workflow integration, another prioritizing syndromic panel breadth, and the third focusing on decentralized molecular testing accessibility.
| Leading Market Players |
|---|
| Cepheid |
| Quidel Corporation |
| Thermo Fisher Scientific, Inc. |
| Becton, Dickinson and Company |
| Meridian Bioscience, Inc. |
| BioMérieux SA |
| Hologic, Inc. |
| Roche Diagnostics |
| Abbott Laboratories |
| Others |
Value Network & Pricing Analysis
Forty-five to sixty-day reagent lead times concentrate pricing power with master mix formulators who anchor hospital laboratory budgets to polymerase supply chains. This inventory exposure redistributes margin capture toward consumable suppliers while instrument manufacturers absorb capital approval cycle risk.
Pricing Analysis
After-sales reagent revenue streams drive lifetime value for thermal cycler platform suppliers. Three-tier pricing structure across premium probe-based detection, standard master mix formulations, and economy-grade extraction buffers segments buyer archetypes. Cost compression in standard-tier reagents intensifies because reference laboratories negotiate multi-year supply agreements. Pediatric hospital systems exhibit highest price sensitivity due to seasonal volume volatility, while CDC-mandated surveillance programs demonstrate lowest sensitivity.
Supply Chain Analysis
The United States and Germany anchor thermal cycler manufacturing and lyophilized assay formulation for North American and European distribution. Master mix production draws from polymerase enzyme suppliers in Switzerland and Austria, with probe synthesis concentrated in California and Massachusetts. Single-source vulnerability in modified nucleotide supply creates exposure to fermentation capacity constraints. Distribution runs through integrated delivery network procurement committees that bundle respiratory pathogen contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hospital laboratory consolidation into integrated delivery networks shifts procurement leverage toward buyers who negotiate multi-year platform exclusivity. This concentration fragments vendor access and elevates contract scale thresholds.
For Market Incumbents: Fortify installed base retention through cartridge infrastructure lock-in and CLIA-waived assay menu expansion. Emerging LAMP-based entrants threaten near-patient molecular market share. Backward integration into polymerase formulation secures reagent margin capture against supply volatility. For New Entrants and Emerging Players: Lead with point-of-care miniaturization targeting rural United States urgent care networks where laboratory infrastructure is absent. India's CDSCO streamlined pathways offer the most penetrable regulatory entry point for automated platform suppliers. Reimbursement strategy alignment with CDC surveillance mandates accelerates hospital adoption velocity. For Investors and Strategic Acquirers: Long-term, this sits as a recurring revenue infrastructure play because consumable pull-through economics dominate capital equipment cyclicality. Acquisition targets with validated multiplex respiratory panels and EUA portfolios command strategic premiums. The signal to watch is WHO prequalification criteria evolution for low- and middle-income country laboratory strengthening contracts.| Strategic Initiative | Industry Significance |
|---|---|
| Multiplex Respiratory Panel Expansion | CDC surveillance mandates sustain Bordetella pertussis inclusion alongside influenza and RSV targets. |
| Point-of-Care Miniaturization | Cartridge-based platforms address emergency department triage workflows for undifferentiated cough illness. |
| Laboratory Information System Integration | Automated case notification functionality aligns with National Notifiable Diseases Surveillance System requirements. |
| Reagent Supply Agreement Consolidation | Integrated delivery networks lock in multi-year exclusivity across virology and bacteriology menus. |
| Vaccine Efficacy Monitoring Contracting | Post-market surveillance of acellular pertussis vaccines generates recurring reference laboratory revenue. |
Research Methodology
Cross-validation between primary interviews with hospital laboratory directors and secondary validation through FDA 510(k) filings anchors the qualitative findings. Conversations with GPO contracts managers, biomedical engineers, and CLIA compliance officers combined with CDC surveillance data, hospital procurement databases, and CMS Medicare reimbursement schedules enable bottom-up and top-down triangulation.
Sensitivity analysis across technology adoption curves, regulatory pathway timelines, and reimbursement policy shifts frames the analytical approach. Segmentation dimensions modeled include product type, application setting, end-user category, and technology platform across the projection horizon. CAGRs derive from instrument placement trajectories, reagent pull-through coefficients, and multiplex panel expansion rates calibrated against historical surveillance volume patterns.
The analysis sits within stated boundaries; outcomes outside sustained CDC funding levels or CLIA complexity reclassification would require recalibration. Forecasts reflect assumptions regarding thermal cycler infrastructure penetration and WHO laboratory strengthening commitment continuity. Recalibration cycles align with material shifts in EUA pathway requirements and integrated delivery network consolidation velocity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Infection Control
Global Hospital Disinfectant Products and Services Market
Infection Control
Surgical Site Infection Control Market
Infection Control
Global Viral Clearance Services Market
Infection Control
Infection Control Surveillance Solutions Market
Infection Control
United States Hand Sanitizer Market
Infection Control
Biological and Chemical Indicators Market
Infection Control
Salivary Gland Infection Treatment Market
Infection Control
Global Disinfection Robots Market
Infection Control
Blood Stream Infection Testing Market
Infection Control
Ultraviolet Germicidal Irradiation Market
Infection Control
Global Skin Antiseptic Products Market
Infection Control
Medical Disinfectant Wipes Market
Infection Control
Hospital Acquired Infections Therapeutic Market
Infection Control
Global Biofilms Treatment Market
Infection Control
New Zealand Healthcare Surface Disinfectant Wipes Market
Infection Control
Global Prophylactic Human Vaccine Market