
 Women's Health App Market | 2026-2036
Women's Health App Market Size, Share, and Industry Trends Forecast 2026-2036
Women's Health App Market Intelligence
A shortage of trained reproductive health data scientists is redrawing competitive boundaries for platform developers. Flo Health, Inc. leverages proprietary cycle prediction algorithms to sustain user retention across 100-plus countries. Clue anchors its position through Berlin-based R&D intensity and open-science partnerships with academic medical centers. Apple Inc. competes via HealthKit integration that controls hardware-software distribution across iPhone and Apple Watch ecosystems.
Women's health apps are digital platforms that collect biometric, behavioral, and self-reported data to deliver personalized reproductive, hormonal, and wellness guidance through machine learning-driven insights and clinical validation protocols. Their primary commercial purpose is to convert episodic healthcare interactions into continuous, data-rich relationships between users and preventive care systems. Period tracking dominates product type revenue due to high daily engagement frequency and low customer acquisition costs. Telehealth integration within the technology segment is expanding fastest as synchronous provider access commands premium subscription tiers. Freemium revenue models capture the widest user bases while subscription conversions concentrate margin pools among perimenopausal and fertility-focused cohorts.
FDA software-as-a-medical-device frameworks and HIPAA privacy mandates shape product architecture and liability exposure for US-based developers. The EU AI Act and GDPR impose additional algorithmic transparency and cross-border data transfer constraints on European deployments. Stakeholders must monitor how reproductive data protection legislation in individual US states alters permissible data monetization and third-party sharing architectures.
Market Dynamics
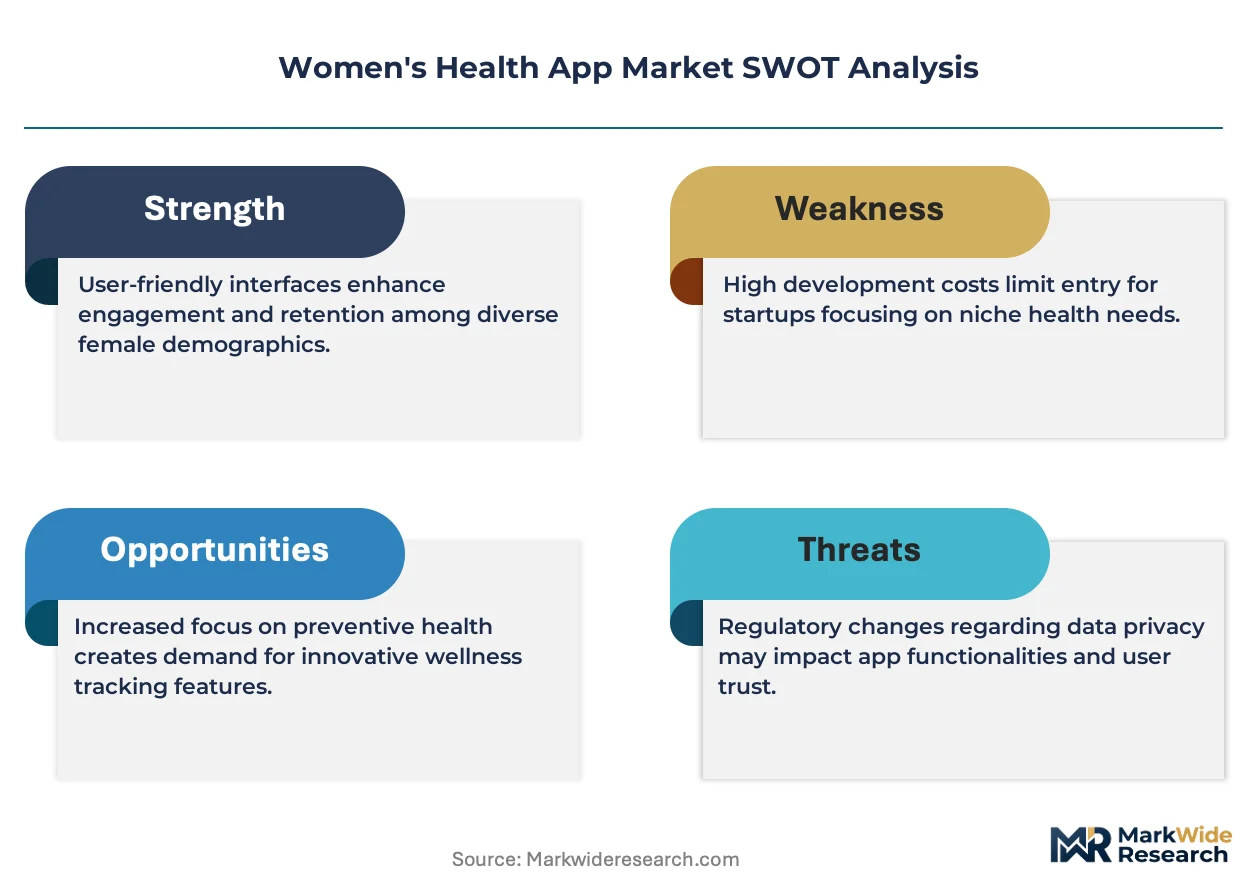
The FDA's software-as-a-medical-device framework is fragmenting product roadmaps as developers must bifurcate US and non-US feature sets, creating parallel compliance tracks that reshape resource allocation and release velocity.
Growth Catalysts
- Employer benefit expansion:Large US employers are adding fertility and maternity coverage as retention tools, creating direct-to-enterprise sales channels for app developers.
- EU AI Act transparency mandates:Algorithmic explainability requirements are accelerating clinical validation partnerships between platforms and academic medical centers.
- Telehealth integration:Synchronous provider access commands premium subscription tiers and extends average revenue per user through medical consultation fees.
Market Restraints
- Reproductive data protection fragmentation:US state-level legislation creates incompatible data architecture requirements that limit cross-border user portability.
- Trained data scientist scarcity:Shortage of reproductive health machine learning specialists concentrates hiring power among well-capitalized incumbents.
- Hardware dependency:Apple HealthKit integration dominance creates platform risk for standalone apps lacking wearable ecosystem control.
Strategic Opportunities
- Perimenopausal cohorts:Hormonal transition management represents underserved white space with high willingness-to-pay for symptom tracking and HRT coordination.
- HIPAA-compliant API ecosystems:Third-party developer platforms enable health system integrations that convert apps into clinical workflow infrastructure.
- GDPR-certified data trusts:European user bases reward privacy-first architectures with higher subscription conversion rates than ad-supported models.
Industry Challenges
- Clinical validation timelines:FDA 510(k) clearance for cycle prediction algorithms extends development cycles and burns runway for pre-revenue platforms.
- Legacy EHR integration:Hospital system procurement committees demand Epic and Cerner compatibility that smaller developers cannot resource.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Women's Health App Market |
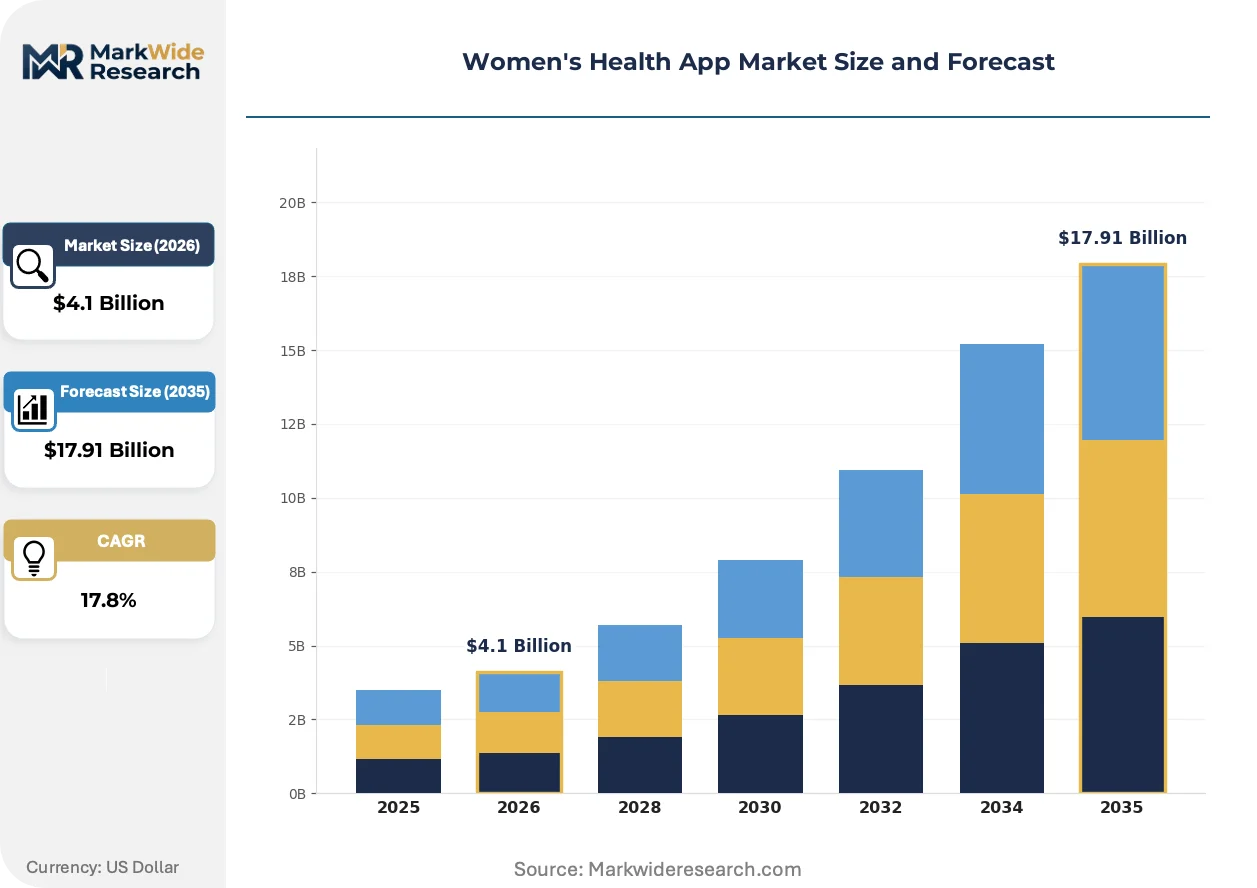
| Market Size in 2026 | $4.1 Billion |
| Market Size in 2035 | $17.91 Billion |
| CAGR (2026 – 2036) | 17.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Period Tracking, Nutrition Guidance, Fitness Coaching, Mental Health End User: Individuals, Healthcare Professionals, Clinics, Gynecologists Technology: Mobile, Web-Based, Wearable Integration, Telehealth Revenue Model: Subscription, One-Time Purchase, Freemium, Advertising |
| Companies Covered | Flo Health, Inc., Clue, Glow, Inc., Apple Inc., Natural Cycles, Ava, Wildflower Health, Ovia Health, Maven Clinic, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Women's Health App Market Strategic Shifts & Innovations
Machine learning architectures are being unbundled into modular components that separate training from inference, enabling faster regulatory iteration and reducing validation surface area for new features.
Federated learning for menstrual cycle prediction is decomposing the centralized data model that previously required massive user pools. Mid-size platforms with 500,000-2 million active users are adopting edge-computing inference to match prediction accuracy of larger competitors without cross-border data transfers. This compression of scale economies is fragmenting market concentration and enabling regional specialists to defend niche positions.
REACH chemical safety extensions into digital therapeutics are forcing EU-based developers to document algorithmic training data provenance with the same rigor as pharmaceutical supply chains. The European Medicines Agency's emerging guidance on software validation is compressing release cycles as teams front-load documentation. Fertility-focused apps face the steepest compliance burden due to their classification as higher-risk devices under evolving MDR interpretations.
Subscription fatigue among fertility-tracking users is shortening average customer lifetime as buyers rotate between platforms seeking novel features. Direct-to-consumer marketing spend is displacing employer channel investments for apps targeting perimenopausal demographics. Germany and France show the highest switching velocity as GDPR data portability rights reduce friction for user migration.
Women's Health App Market Segmentation
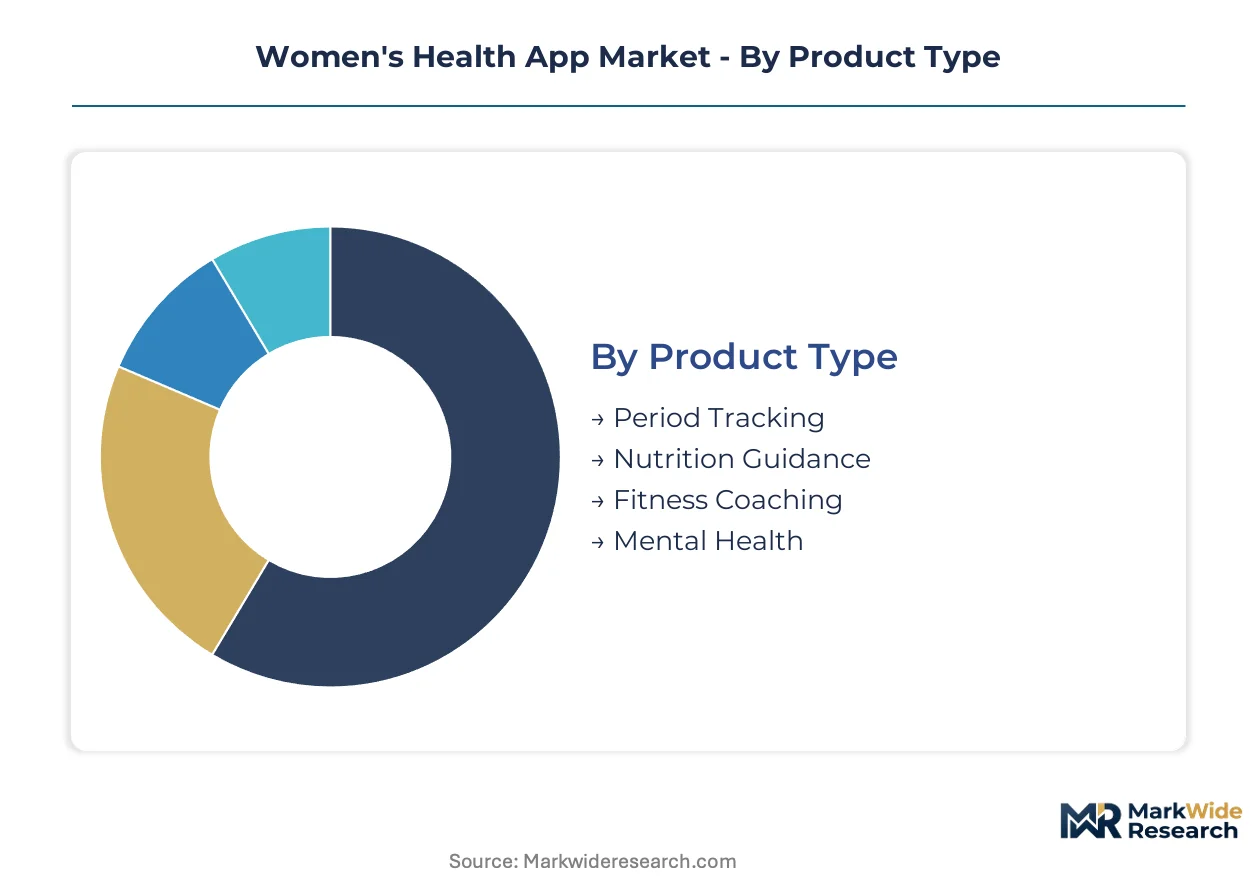
Segmentation in women's health apps determines which features command premium pricing and which channels deliver sustainable unit economics. Product architecture, user interface design, and compliance requirements diverge sharply across these dimensions, forcing developers to prioritize rather than serve all segments equally.
Product Type:
Channel-mix patterns show period tracking and nutrition guidance flowing primarily through direct-to-consumer app stores, while fitness coaching and mental health modules increasingly embed within employer-sponsored wellness platforms and health system patient portals.
- Period Tracking:Core functionality centers on menstrual cycle logging, ovulation prediction, and symptom correlation through proprietary algorithms. Daily engagement frequency in the United States and Germany sustains freemium-to-subscription conversion funnels with minimal customer acquisition spend.
- Nutrition Guidance:Meal logging and micronutrient tracking tailored to hormonal phases requires integration with third-party food databases. Corporate wellness programs in France and the United Kingdom are bundling these modules into fertility benefit packages, expanding B2B revenue streams beyond individual subscriptions.
- Fitness Coaching:Cycle-synced workout programming adapts intensity to luteal and follicular phases. Wearable ecosystem partnerships with Apple and Samsung hardware dominate distribution.
- Mental Health:Mood tracking, cognitive behavioral therapy tools, and anxiety management for PMDD and perimenopause. Telehealth platforms in Canada are white-labeling these capabilities for gynecology practices.
By volume, Period Tracking leads. By growth pace, Mental Health is ahead.
End User:
Cost-tier stratification separates individual subscribers paying out-of-pocket from institutional procurement committees demanding Epic and Cerner compatibility, with healthcare professionals occupying a mid-tier requiring standalone clinical decision support without full EHR integration.
- Individuals:Direct consumers seeking fertility optimization, pregnancy planning, or menopause symptom management. Privacy-conscious users in California and Massachusetts are migrating toward HIPAA-compliant platforms that restrict third-party data monetization.
- Healthcare Professionals:Nurse practitioners and primary care physicians using apps for patient education and remote monitoring. Reimbursement coding complexity in the United States limits widespread clinical adoption despite FDA 510(k) clearances for specific diagnostic features.
- Clinics:Fertility and family planning centers deploying white-labeled patient engagement platforms. Germany's statutory health insurance system is piloting app prescriptions through digital health application pathways.
- Gynecologists:Specialist practices requiring menstrual history visualization and anomaly flagging for endometriosis and PCOS screening. France's HAS evaluation process is creating preferred vendor lists that concentrate procurement among validated platforms.
Individuals generate the highest absolute revenue. Healthcare Professionals are climbing the fastest as prescribing workflows mature.
Technology:
Application intensity varies by deployment context—mobile-first architectures dominate consumer markets while wearable integration and telehealth capabilities concentrate among fertility-focused platforms commanding premium subscription tiers.
- Mobile:Native iOS and Android applications with offline data storage and push notification systems. India's expanding smartphone penetration is creating price-sensitive demand for lightweight APK-optimized versions.
- Web-Based:Browser-accessible dashboards for clinical review and multi-device synchronization. Larger screen real estate supports detailed cycle visualization for provider consultations.
- Wearable Integration:Continuous temperature, heart rate variability, and sleep stage monitoring through Apple Watch, Oura Ring, and Garmin devices. Basal body temperature correlation algorithms in the United Kingdom are achieving clinical-grade precision for natural family planning.
- Telehealth:Synchronous video consultation and asynchronous messaging with reproductive endocrinologists and mental health specialists. Premium pricing in the United States reflects reimbursement parity with in-person visits in select states.
Mobile leads by installed base. Wearable Integration is gaining share fastest as hardware ecosystems consolidate.
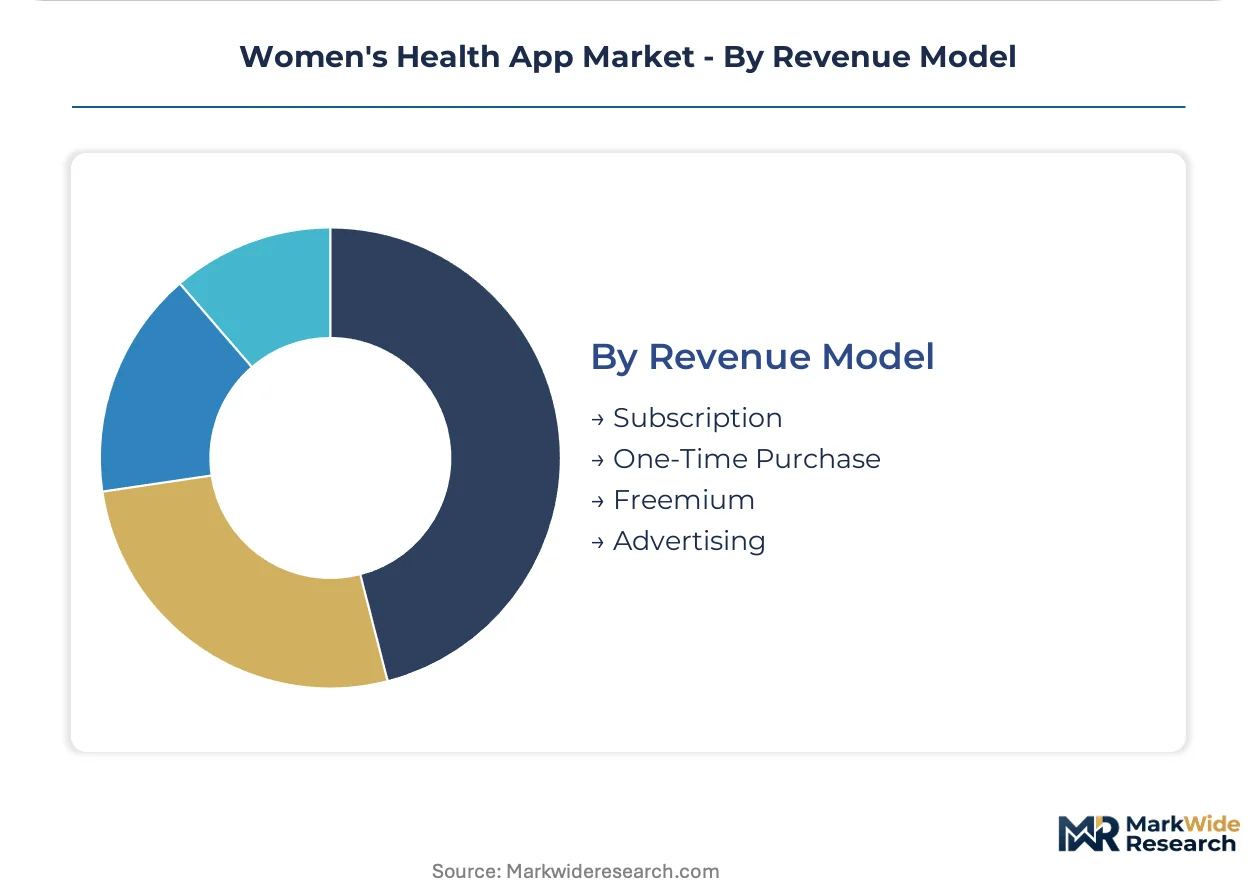
Revenue Model:
Margin profiles diverge dramatically—subscription cohorts in perimenopausal and fertility-focused segments show 3-4x lifetime value versus ad-supported users, while one-time purchases concentrate among pregnancy tracking apps with naturally bounded usage windows.
- Subscription:Recurring monthly or annual fees unlocking premium predictions, telehealth access, and advanced analytics. Annual billing preferences in Germany and Switzerland reduce churn versus monthly plans.
- One-Time Purchase:Single payment for pregnancy-specific tracking with postpartum feature expiration. Natural customer lifecycle limits expansion revenue but eliminates ongoing support costs.
- Freemium:Basic cycle logging with paywalled advanced features and data export capabilities. The dominant acquisition channel in Brazil and Mexico where credit card penetration constrains upfront payment.
- Advertising:Targeted display and sponsored content based on cycle phase and self-reported symptoms. GDPR consent frameworks in the European Union are compressing addressable audiences and CPM rates.
Subscription leads by revenue per user. Freemium is expanding most quickly in emerging markets with payment infrastructure constraints.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Employer-sponsored wellness programs in the United States drive recurring subscription revenue through fertility benefit expansion, while European users prioritize GDPR-certified privacy architectures that restrict data monetization models prevalent elsewhere.
United States
Large employers in California and Massachusetts extend fertility coverage as retention tools, creating direct-to-enterprise sales channels for app developers. FDA software-as-a-medical-device frameworks fragment product roadmaps into parallel US and non-US compliance tracks. Boston's digital health cluster concentrates clinical validation partnerships between platforms and academic medical centers.
Germany
Statutory health insurance pilots prescribe apps through digital health application pathways, expanding reimbursement-coded revenue streams. The EU AI Act imposes algorithmic transparency mandates that accelerate open-science partnerships with Berlin-based R&D institutions. Munich and Hamburg host concentrated fertility-focused platform development for MDR compliance.
United Kingdom
Basal body temperature correlation algorithms achieve clinical-grade precision for natural family planning, commanding premium subscription tiers. MHRA oversight of software-as-a-medical-device creates alignment pressure with FDA frameworks for developers seeking dual-market clearance. London's telehealth infrastructure enables synchronous provider access bundled into employer wellness programs.
France
HAS evaluation processes create preferred vendor lists that concentrate procurement among validated platforms for gynecology practices. GDPR-certified data trusts reward privacy-first architectures with higher subscription conversion rates than ad-supported alternatives. Paris anchors national deployment of white-labeled patient engagement platforms for fertility clinics.
India
Expanding smartphone penetration creates price-sensitive demand for lightweight APK-optimized period tracking applications. CDSCO emerging oversight of wellness apps shapes local data localization requirements for biometric collection. Bangalore's health-tech cluster incubates freemium platforms targeting credit-card-constrained user acquisition in tier-2 cities.
Women's Health App Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, with hardware-software ecosystem control separating scaled platforms from standalone applications. The upper tier commands distribution through wearable integration and employer channel access, while mid-size competitors defend regional positions through federated learning and edge-computing inference. Three archetypes dominate: ecosystem-integrated technology platforms, clinically validated fertility specialists, and privacy-first European developers. Competitive moves concentrate on telehealth capability acquisition and HIPAA-compliant API ecosystem construction for health system integration.
Within the clinically validated tier, Flo Health, Inc. and Clue occupy positions anchored by proprietary cycle prediction algorithms and Berlin-based R&D intensity respectively. Apple Inc. represents ecosystem-integrated competition through HealthKit distribution control across iPhone and Apple Watch hardware. These three exemplify the strategic divergence between algorithmic specialization, open-science academic partnerships, and vertical hardware-software integration that defines competitive positioning in this market.
| Leading Market Players |
|---|
| Flo Health, Inc. |
| Clue |
| Glow, Inc. |
| Apple Inc. |
| Natural Cycles |
| Ava |
| Wildflower Health |
| Ovia Health |
| Maven Clinic |
| Others |
Cost & Logistics Intelligence
Capacity reservation agreements with cloud infrastructure providers lock in compute access and cost predictability for women's health app developers navigating FDA software-as-a-medical-device validation cycles. These multi-year contracts anchor unit economics while algorithmic training costs concentrate margin pressure among mid-size platforms lacking scale.
Pricing Analysis
Subscription-based recurring revenue dominates the women's health app landscape, with annual billing in Germany and Switzerland reducing churn versus monthly plans. Price differentiation hinges on FDA 510(k) certification tier and telehealth integration depth, with premium tiers commanding three-to-four-fold lifetime value over ad-supported alternatives. Pricing pressure stems from subscription fatigue among fertility-tracking users rotating between platforms. Individual consumers in emerging markets show highest price sensitivity, while employer-sponsored wellness programs demonstrate lowest sensitivity due to bundled procurement.
Supply Chain Analysis
Inventory lead times for biometric sensor hardware from Taiwan and South Korea extend platform development cycles, particularly for basal body temperature correlation devices. Cloud compute and third-party food databases from the United States and India feed algorithmic training pipelines. Single-source vulnerability concentrates in Apple HealthKit ecosystem control, creating platform risk for standalone applications. Distribution runs through direct-to-consumer app stores and employer benefit administrators, with health system procurement committees demanding Epic and Cerner compatibility.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Women's health apps face a platform-economics inflection as HealthKit integration and federated learning architectures reshape competitive boundaries. Interoperability mandates from the EU AI Act and HIPAA-compliant API ecosystems are redefining value capture mechanisms.
For Market Incumbents: Shield proprietary algorithmic moats through accelerated clinical validation partnerships with Boston and Berlin academic medical centers. Deepen backward integration into wearable hardware ecosystems to reduce Apple HealthKit dependency. Prioritize HIPAA-compliant API construction for health system workflow embedding.
For New Entrants and Emerging Players: Differentiate on perimenopausal hormonal transition management, the most penetrable white space with underserved symptom tracking demand. Target India's tier-2 cities through APK-optimized freemium acquisition. Pursue white-label telehealth platform partnerships with Canadian gynecology practices.
For Investors and Strategic Acquirers: Capital is best deployed toward privacy-first European developers with GDPR-certified data trusts and MDR compliance pathways. Long-term viability favors platforms with federated learning architectures that compress scale economies. Watch MHRA-FDA dual-market clearance velocity as inflection indicator for clinical validation tier separation.
| Strategic Initiative | Industry Significance |
|---|---|
| Telehealth Capability Acquisition | Synchronous provider access commands premium subscription tiers through reimbursement parity in select US states. |
| HIPAA-Compliant API Ecosystem Construction | Third-party developer platforms convert apps into clinical workflow infrastructure for Epic and Cerner integration. |
| Federated Learning Architecture Deployment | Edge-computing inference enables mid-size platforms to match prediction accuracy without cross-border data transfers. |
| MDR Compliance Pathway Investment | European Medicines Agency software validation guidance compresses release cycles for fertility-focused higher-risk devices. |
| Perimenopausal Cohort Product Expansion | Hormonal transition management modules address white space with high willingness-to-pay for HRT coordination. |
Research Approach
Two parallel data streams informed the analysis: structured primary interviews with reproductive health data scientists, digital health product managers, employer benefits administrators, and FDA regulatory consultants; and secondary validation through SEC filings, App Annie mobile intelligence, FDA 510(k) clearance databases, and hospital procurement records. Bottom-up user cohort modeling and top-down market sizing triangulated volume and value estimates across the projection horizon.
Forecasts spanning the analysis window applied segmentation dimensions including product type, end user archetype, technology deployment, and revenue model. CAGRs derived from algorithmic adoption curves, employer benefit expansion velocity, and telehealth reimbursement policy trajectories. Fertility benefit penetration rates and wearable ecosystem integration timelines served as industry-specific forecast inputs.
The analysis sits within stated boundaries; outcomes outside sustained employer sponsorship growth or FDA regulatory stability would require recalibration. Forecasts reflect documented assumptions regarding data scientist labor market tightness and reproductive data protection legislation fragmentation. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Women's Health
Maternal Health Market
Women's Health
North America Womens Health Diagnostics Market
Women's Health
Dysmenorrhea Treatment Market
Women's Health
Postmenopausal Vaginal Atrophy Treatment and Drug Market
Women's Health
Women Health Software Market
Women's Health
Menstrual Health Apps Market
Women's Health
Dysfunctional Uterine Bleeding Market
Women's Health
US Womens Health Market
Women's Health
Menstrual Cup Foam Wash Market
Women's Health
Women Health Devices Market
Women's Health
Women Health Care Market
Women's Health
Menopause Market
Women's Health
Women Health Disease Diagnosis and Treatment Market
Women's Health
Global Menopausal Hot Flashes Market
Women's Health
Workplace Menstrual Health Benefits Platform Market
Women's Health
Women's Digital Health Market