
 Healthcare Associated Infections (HAI) Treatment Market | 2026-2036
Healthcare Associated Infections (HAI) Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Healthcare Associated Infections (HAI) Treatment Market Foresight
Silver nanoparticle coatings in central venous catheters is decoupling device-related infection economics from traditional antiseptic protocols. Pfizer Inc. leverages its cephalosporin manufacturing scale to supply hospital formularies across North America and Europe. Merck & Co., Inc. anchors its position through carbapenem R&D pipelines targeting multidrug-resistant gram-negative organisms. Johnson & Johnson Services, Inc. competes in surgical site infection prevention through antimicrobial sutures and wound closure systems.
Healthcare Associated Infections (HAI) Treatment encompasses pharmacological and non-pharmacological interventions designed to eliminate or suppress pathogenic microorganisms acquired during medical care, typically involving minimum inhibitory concentration thresholds of 0.5–32 mg/L for gram-positive isolates and combination therapy indices for resistant gram-negative strains. The primary purpose is reducing morbidity, mortality, and excess length of stay in acute and post-acute care settings. Antibiotics occupy the largest revenue pool within product type segmentation, driven by prolonged IV courses for bloodstream and postoperative infections, while antifungals represent the fastest-growing category as Candida auris outbreaks strain hospital capacity. Injectable and intravenous delivery modes dominate inpatient revenue, though oral step-down protocols are gaining traction in outpatient clinics and skilled nursing transitions.
FDA breakpoints, EMA antimicrobial resistance guidance, and CDC NHSN reporting mandates collectively tighten the evidentiary threshold for new HAI therapeutics seeking formulary access. These frameworks shape demand by penalizing hospitals with elevated standardized infection ratios and restricting reimbursement for preventable events. Stakeholders must monitor how CMS quality metrics and EU MDR post-market surveillance requirements will reshape clinical trial endpoints and commercialization timelines for next-generation agents.
Market Dynamics
Medicare reimbursement penalties for preventable infections now dominate hospital procurement calculus, forcing integrated delivery networks to prioritize agents with proven resistance profiles over legacy broad-spectrum antibiotics.
Growth Catalysts
- Antimicrobial Stewardship Mandates:CMS Hospital-Acquired Condition Reduction Program penalties compel formulary committees to stock novel antipseudomonal agents. Hospital systems expand dedicated stewardship teams to optimize therapy selection.
- Catheter-Coating Innovation:Silver nanoparticle and chlorhexidine-impregnated central line materials reduce bloodstream infection incidence. Device manufacturers partner with coating specialists to differentiate vascular access portfolios.
- United States:Medicare's nonpayment policy for catheter-associated urinary tract infections and surgical site infections after certain procedures redirects capital toward preventive therapeutics and preoperative decolonization protocols.
Market Restraints
- Carbapenem Manufacturing Concentration:Active pharmaceutical ingredient production for last-resist gram-negative antibiotics clusters in specific Asian manufacturing zones, exposing formularies to single-source disruption risks.
- FDA Breakpoint Stringency:Updated susceptibility testing thresholds for resistant Enterobacterales reclassify formerly effective agents, forcing sponsors to generate new clinical data for retained indications.
- Oral Step-Down Substitution:Bioequivalent oral fluoroquinolones and oxazolidinones compress inpatient IV revenue cycles for uncomplicated skin and soft tissue infections, limiting duration-based pricing power.
Strategic Opportunities
- Post-Acute and Long-Term Care:Skilled nursing facilities face rising Candida auris colonization rates with limited on-site diagnostic capacity, creating demand for empiric echinocandin protocols and environmental decontamination services.
- EMA Adaptive Pathways:Conditional approval frameworks for limited-population antibacterial drugs accelerate market access for pathogens with documented resistance gaps, rewarding sponsors with priority review incentives.
- Pharmacokinetic-Pharmacodynamic Modeling:Dose optimization software converges with real-time therapeutic drug monitoring to enable precision dosing in critically ill patients with augmented renal clearance or extracorporeal circuits.
Industry Challenges
- ID Physician Workforce Constraints:Fellowship-trained infectious disease specialists remain scarce relative to expanding stewardship program mandates, stretching clinical decision support implementation timelines.
- Legacy EHR Integration:Antibiotic alert systems require costly interface engineering with entrenched hospital information systems, delaying real-time susceptibility reporting and automated de-escalation prompts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Healthcare Associated Infections (HAI) Treatment Market |
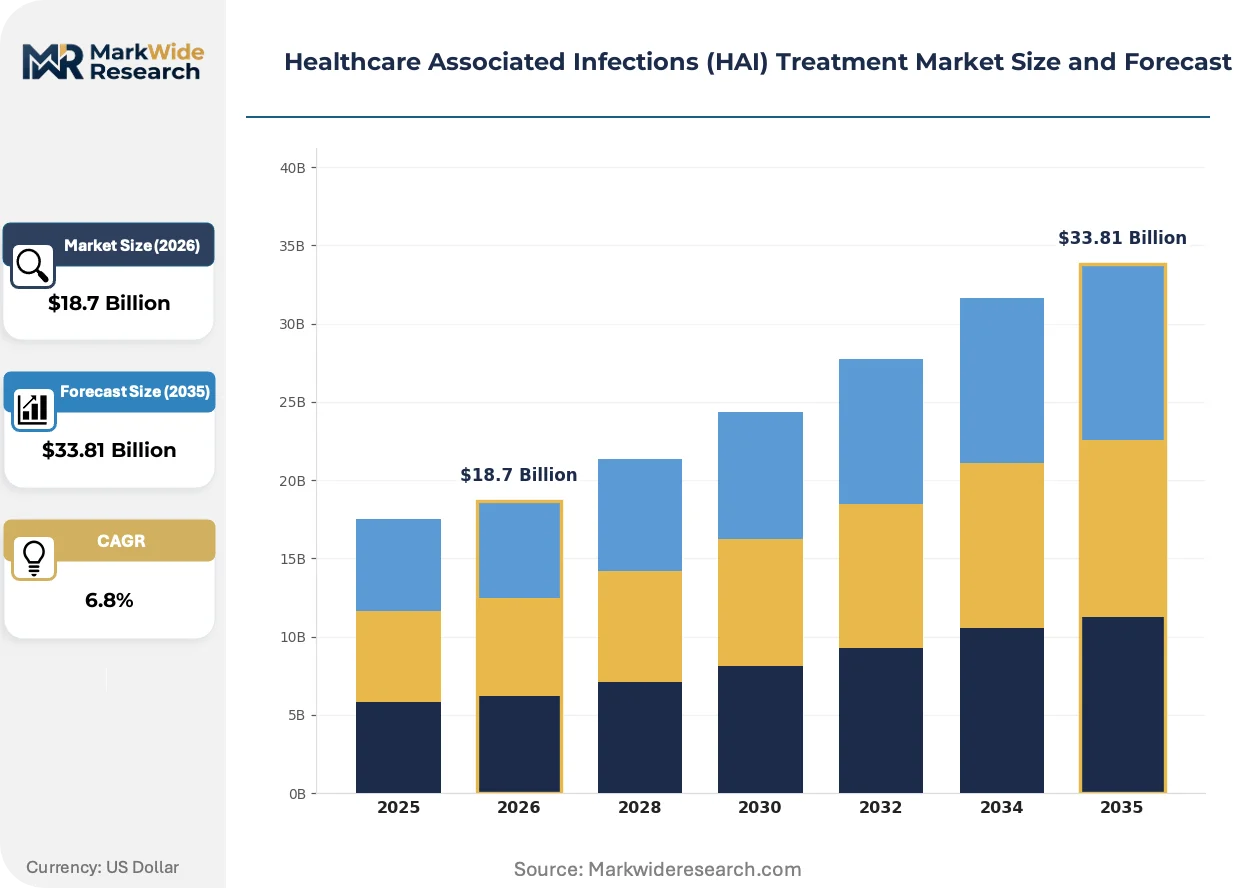
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antibiotics, Antiseptics, Disinfectants, Antifungals End User: Hospitals, Outpatient Clinics, Nursing Facilities, Home Healthcare Delivery Mode: Injectable, Oral, Topical, Intravenous Application: Postoperative Infections, Urinary Tract Infections, Pneumonia, Bloodstream Infections |
| Companies Covered | Pfizer Inc., Merck & Co., Inc., Johnson & Johnson Services, Inc., Sanofi S.A., AstraZeneca plc, Bayer AG, GlaxoSmithKline plc, F. Hoffmann-La Roche Ltd, BD, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Healthcare Associated Infections (HAI) Treatment Market Shifts & Advancements
Resistance surveillance networks and rapid molecular diagnostics are compressing the interval between pathogen identification and targeted therapy initiation, reshaping how hospitals value speed versus spectrum in antimicrobial selection.
Bacteriophage therapy adjuncts for recalcitrant Pseudomonas aeruginosa biofilms is unifying salvage treatment protocols in cystic fibrosis and chronic wound centers. Specialized compounding pharmacies and academic medical centers coordinate phage sourcing and host-range matching. This convergence is compressing the historical binary between approved antibiotics and experimental access programs.
EMA's revised clinical trial guidance for hospital-acquired bacterial pneumonia now requires all-cause mortality endpoints rather than composite clinical cure measures. Sponsors must enroll larger patient populations and extend follow-up windows. This standard is reshaping Phase III investment decisions for gram-negative development programs targeting ventilator-associated indications.
Hospital supply chains now bundle device and drug procurement through integrated vendor contracts, displacing traditional pharmaceutical distributor relationships. Catheter manufacturers partner with antibiotic suppliers to offer infection-rate guarantees. This consolidation is most visible in United States IDN central contracting offices seeking single-source accountability for device-related infection outcomes.
Healthcare Associated Infections (HAI) Treatment Market Segmentation
Hospital procurement committees segment HAI therapeutics by resistance profile, delivery feasibility, and reimbursement alignment. Formulary decisions increasingly weight pharmacokinetic data against CMS penalty exposure. Manufacturers must map pipeline assets across these dimensions to secure integrated delivery network contracts.
Product Type:
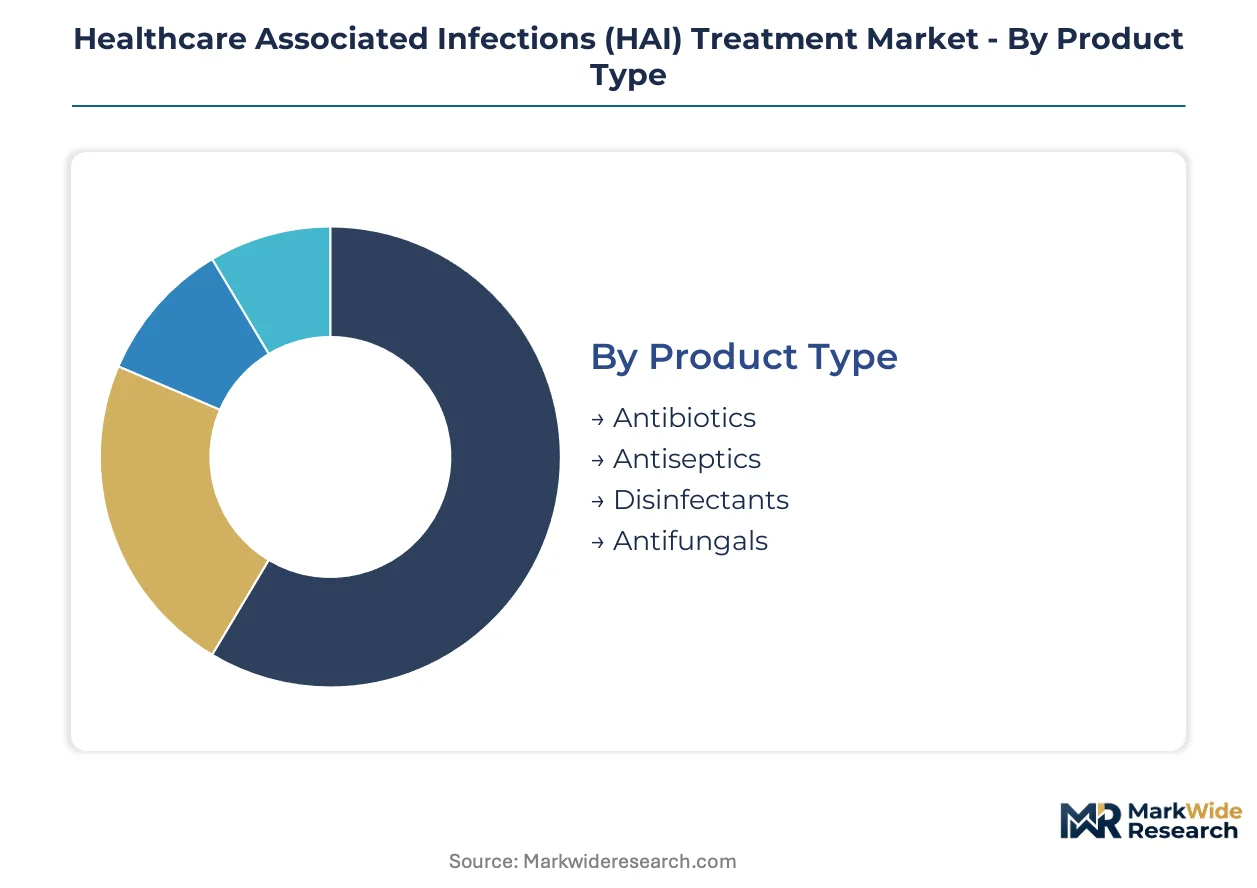
Replacement cycles for legacy antipseudomonal agents accelerate as FDA breakpoint revisions invalidate historical susceptibility claims. Stewardship programs demand newer agents with preserved activity against resistant Enterobacterales.
- Antibiotics:Beta-lactam combinations, carbapenems, and novel aminoglycosides constitute the core inpatient arsenal for bloodstream and surgical site infections. United States Medicare nonpayment policies for preventable events concentrate demand in agents with documented resistance profiles. Hospital systems prioritize IV formulations with therapeutic drug monitoring protocols.
- Antifungals:Echinocandins and azoles target Candida auris and Aspergillus colonization in immunocompromised patients. Skilled nursing facilities drive empiric protocol adoption where diagnostic capacity lags colonization rates. Environmental decontamination services increasingly bundle with antifungal procurement.
- Antiseptics:Chlorhexidine and iodine-based preparations for preoperative skin decolonization and catheter site care.
- Disinfectants:Sporicidal agents for terminal cleaning of Candida auris-contaminated patient rooms and equipment.
Antibiotics sit at the top of the volume ranking, with antifungals climbing the fastest.
End User:
Cost tier stratification separates academic medical centers with dedicated stewardship teams from resource-constrained post-acute facilities. Reimbursement penalties apply unevenly across settings, shaping procurement sophistication.
- Hospitals:Acute care facilities with 24-hour pharmacy and microbiology laboratory capacity drive IV antibiotic consumption. CMS Hospital-Acquired Condition Reduction Program penalties compel formulary committees to stock novel agents with proven resistance profiles. Antimicrobial stewardship teams optimize therapy selection through real-time susceptibility reporting.
- Nursing Facilities:Long-term care and skilled nursing environments face rising multidrug-resistant organism colonization with limited on-site diagnostic resources. Empiric protocols and environmental decontamination services address Candida auris outbreaks straining hospital capacity. Staffing constraints complicate infection control implementation.
- Outpatient Clinics:Ambulatory settings managing uncomplicated skin and soft tissue infections with oral step-down protocols.
- Home Healthcare:Infusion services delivering prolonged IV courses for osteomyelitis and endocarditis in residential settings.
Hospitals command the largest procurement budgets, though nursing facilities present the steepest expansion trajectory as post-acute infection penalties tighten.
Delivery Mode:
Application context determines route selection, with critically ill patients requiring immediate bioavailability and stable patients shifting to oral alternatives.
- Intravenous:Direct bloodstream administration ensures rapid peak concentrations in sepsis and ventilator-associated pneumonia. United States intensive care units prioritize IV formulations for patients with hemodynamic instability or impaired gastrointestinal absorption. Continuous infusion protocols optimize time-dependent killing for beta-lactams.
- Oral:Bioequivalent fluoroquinolones and oxazolidinones enable discharge and skilled nursing transitions. Outpatient parenteral antimicrobial therapy programs compress inpatient length of stay. Step-down protocols face pressure from oral bioavailability advances.
- Injectable:Intramuscular depot formulations for adherence-challenged populations in outpatient and home settings.
- Topical:Surface applications for surgical site prophylaxis and localized wound infections with limited systemic exposure.
Intravenous dominates acute care revenue, while oral delivery gains share fastest through step-down protocol expansion.
Application:
Geographic variation in procedure mix and device utilization patterns shapes infection type prevalence across hospital systems.
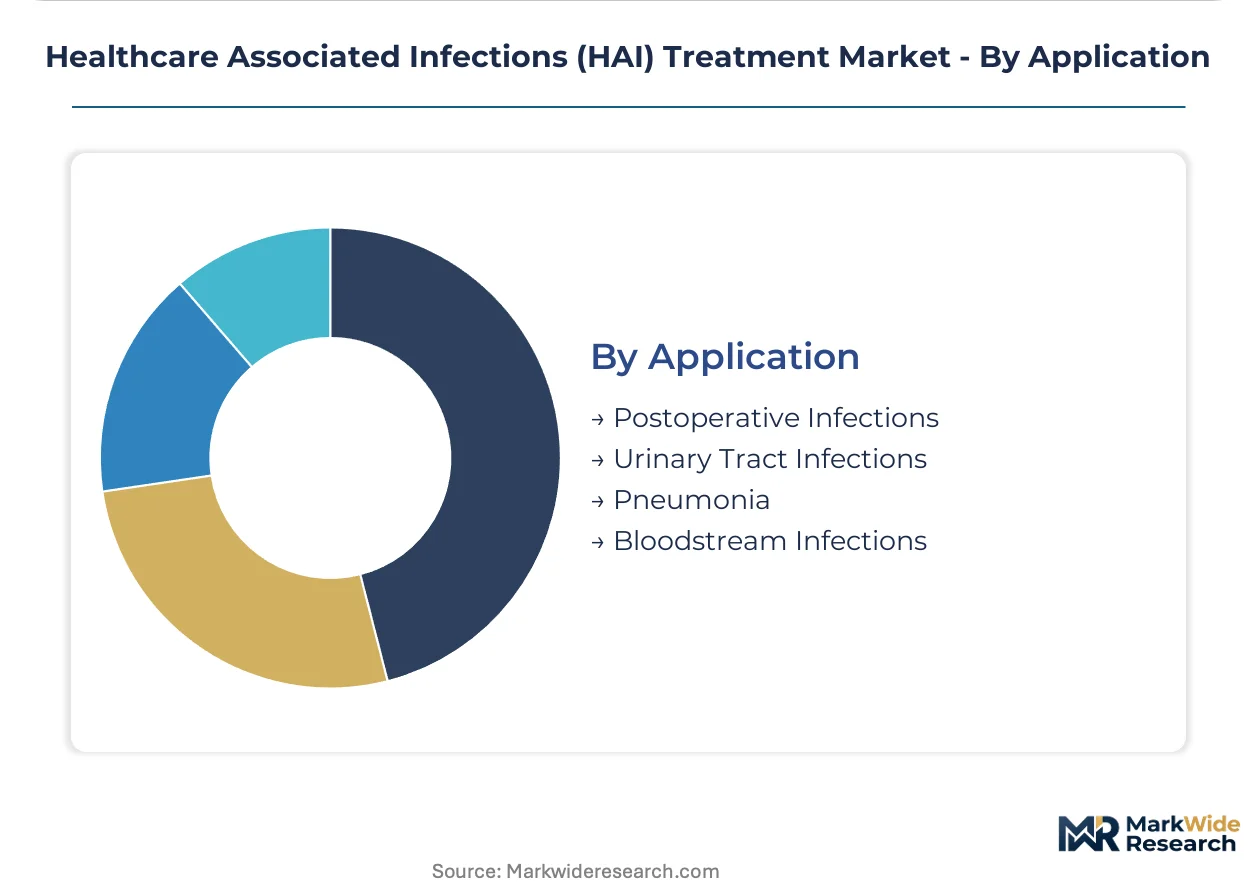
- Bloodstream Infections:Central line-associated bacteremia drives prolonged broad-spectrum IV courses and therapeutic drug monitoring. United States academic medical centers invest in rapid molecular diagnostics to compress pathogen identification intervals. Catheter-coating innovations with silver nanoparticles aim to decouple device economics from antiseptic protocols.
- Postoperative Infections:Surgical site infections after cardiac, orthopedic, and gastrointestinal procedures trigger CMS nonpayment penalties. Preoperative decolonization with chlorhexidine and mupirocin reduces Staphylococcus aureus burden. Antimicrobial sutures and wound closure systems compete for formulary inclusion.
- Pneumonia:Ventilator-associated and hospital-acquired bacterial pneumonia require antipseudomonal coverage with EMA-mandated all-cause mortality endpoints for approval.
- Urinary Tract Infections:Catheter-associated events face Medicare reimbursement restrictions, redirecting capital toward prevention and silver-alloy catheter procurement.
Bloodstream infections generate the highest per-case therapeutic costs, with postoperative infections expanding most quickly as surgical volume recovers and penalty enforcement intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Boston's Longwood Medical Area anchors the world's densest concentration of antimicrobial research hospitals. The United States commands procurement volume through Medicare penalty structures. European regulators accelerate novel agent approvals through adaptive pathways.
United States
Integrated delivery networks in the Northeast and California prioritize novel antipseudomonal agents to avoid CMS Hospital-Acquired Condition Reduction Program penalties. The FDA's tightened susceptibility breakpoints for resistant Enterobacterales force formulary committees toward newer beta-lactam combinations. Texas Medical Center hospitals in Houston deploy therapeutic drug monitoring protocols for critically ill patients on continuous infusion carbapenems.
Germany
University hospitals in Baden-Württemberg and Bavaria drive demand for precision-dosed antifungals against Candida auris colonization. The EMA's conditional approval framework for limited-population antibacterial drugs accelerates market access for sponsors targeting documented resistance gaps. Berlin's Charité hospital network partners with device manufacturers on silver nanoparticle catheter trials.
Japan
Metropolitan Tokyo hospitals face rising multidrug-resistant gram-negative bloodstream infections in aging surgical populations. PMDA post-market surveillance requirements align with EU MDR standards for antimicrobial-coated devices. Osaka's Kansai medical corridor concentrates carbapenem stewardship program implementation across private and public hospital systems.
United Kingdom
NHS England's procurement frameworks penalize trusts with elevated standardized infection ratios, redirecting capital toward preoperative decolonization protocols. The MHRA's adoption of FDA-aligned breakpoint revisions reclassifies formerly effective legacy agents. London's Imperial College Healthcare NHS Trust leads rapid molecular diagnostic adoption to compress pathogen identification intervals.
India
Corporate hospital chains in Maharashtra and Karnataka expand ICU capacity without proportional infectious disease specialist growth, stretching empiric protocol reliance. CDSCO accelerated approval pathways for critical care antibiotics address carbapenem-resistant Enterobacterales prevalence. Chennai's Apollo Hospitals network invests in environmental decontamination services for Candida auris outbreak containment.
Healthcare Associated Infections (HAI) Treatment Market Competitive Landscape
Global majors compete with regional champions across resistance-profile specialization and formulary access depth. The market structures around three tiers: diversified pharmaceutical conglomerates with cephalosporin manufacturing scale, mid-cap antibacterial specialists with carbapenem R&D pipelines, and device-drug bundling vendors with coating technology partnerships. Dominant competitive moves include backward integration into active pharmaceutical ingredient production and strategic alliances between catheter manufacturers and antibiotic suppliers for infection-rate guarantees.
Within the diversified pharmaceutical tier, Pfizer Inc. and Merck & Co., Inc. exemplify scale-driven positions anchored in beta-lactam and carbapenem supply security. Johnson & Johnson Services, Inc. occupies a distinct archetype bridging device and drug domains through antimicrobial suture portfolios. These three entities represent the primary competitive anchors against which regional champions and mid-cap specialists position their resistance-targeted development programs.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Merck & Co., Inc. |
| Johnson & Johnson Services, Inc. |
| Sanofi S.A. |
| AstraZeneca plc |
| Bayer AG |
| GlaxoSmithKline plc |
| F. Hoffmann-La Roche Ltd |
| BD |
| Others |
Supply & Pricing Matrix
Private-equity-rolled-up antimicrobial coating specialists now control catheter manufacturing capacity across North American hospital supply chains, linking supply discipline directly to formulary pricing power for device-drug bundles. This ownership pattern concentrates procurement leverage within integrated delivery networks that negotiate infection-rate guarantees against volume commitments.
Pricing Analysis
Active pharmaceutical ingredient cost pass-through from Asian carbapenem manufacturing zones shapes tiered pricing structures across beta-lactam and novel aminoglycoside portfolios. Three-tier pricing structure across premium, standard, and economy levels separates FDA breakpoint-validated agents from legacy broad-spectrum alternatives, with certification tier and volume scale as primary differentiation drivers. Cost compression in standard-tier IV antibiotics intensifies because oral step-down protocols compress inpatient revenue cycles. Post-acute nursing facilities exhibit highest price sensitivity due to limited reimbursement pools, while academic medical centers with stewardship mandates prioritize resistance-profile premiums over acquisition cost.
Supply Chain Analysis
Reverse-logistics networks for recalled or expired antimicrobial-coated devices remain underdeveloped, creating stranded inventory risks for hospital systems holding silver nanoparticle catheter stockpiles against outbreak contingencies. Active pharmaceutical ingredient production for last-resort gram-negative antibiotics concentrates in India, China, and South Korea, drawing from fermentation-derived beta-lactam intermediates and synthetic carbapenem precursors. Single-source vulnerability in carbapenem manufacturing exposes formularies to disruption when environmental inspections shutter specific Asian facilities. Distribution runs through pharmaceutical distributor relationships that device manufacturers increasingly displace through integrated vendor contracts bundling catheters with antibiotic procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where Medicare penalty structures and FDA breakpoint stringency concentrate procurement budgets toward premium agents with validated resistance profiles against multidrug-resistant gram-negative organisms.
For Market Incumbents: Lock in formulary access through backward integration into active pharmaceutical ingredient production, securing carbapenem supply continuity against Asian manufacturing concentration risks. Expand therapeutic drug monitoring service offerings to differentiate IV antibiotic portfolios from oral step-down substitutes that threaten inpatient revenue cycles. Prioritize stewardship program partnerships that embed clinical decision support within hospital information systems. For New Entrants and Emerging Players: Telehealth-integrated outpatient parenteral antimicrobial therapy programs offer the lowest barrier to entry, enabling skilled nursing facility penetration without competing for acute care formulary slots against entrenched cephalosporin and carbapenem suppliers. Target post-acute Candida auris empiric protocol adoption where diagnostic capacity lags colonization rates. Pursue environmental decontamination service bundling as the primary go-to-market angle. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-cap antibacterial specialists with carbapenem R&D pipelines targeting documented resistance gaps but lacking integrated delivery network contract scale. Long-term viability hinges on conditional approval pathway navigation through EMA adaptive frameworks and FDA limited-population antibacterial drug designations. Monitor CMS quality metric expansion into post-acute settings as the inflection signal for skilled nursing facility procurement sophistication.| Strategic Initiative | Industry Significance |
|---|---|
| Antimicrobial Stewardship Program Partnership | Embedding clinical decision support within Epic and Cerner installations secures formulary lock-in against generic substitution. |
| Silver Nanoparticle Coating Scale-Up | Catheter manufacturers partnering with coating specialists differentiate vascular access portfolios through infection-rate guarantees. |
| EMA Adaptive Pathway Navigation | Conditional approval frameworks for limited-population antibacterial drugs accelerate market access for resistance-gap agents. |
| Therapeutic Drug Monitoring Integration | Real-time dosing software convergence with hospital laboratory systems optimizes beta-lactam exposure in critically ill patients. |
| Post-Acute Distribution Channel Expansion | Skilled nursing facility empiric protocol adoption addresses Candida auris outbreaks with limited on-site diagnostic capacity. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with infectious disease specialists, hospital formulary directors, antimicrobial stewardship team leads, and GPO contracts managers with secondary validation against FDA breakpoint revisions, EMA submission filings, CMS Medicare penalty schedules, and hospital procurement database extracts. Bottom-up therapeutic category sizing and top-down macro constraint triangulation anchored volume and value estimates.
Comparable-period anchoring tied projection horizons to historical reference windows spanning pre-pandemic baseline, acute disruption, and recovery-normalization phases across the analysis window. Segmentation modeling incorporated product type, end user facility tier, delivery mode, and application-specific resistance profile dimensions. CAGRs derived from fitted growth curves calibrated against antimicrobial resistance surveillance trendlines and regulatory approval velocity benchmarks.
The model assumes a particular technology adoption path; alternative pathways for bacteriophage therapy adjuncts would alter the outlook if salvage treatment protocols displace traditional antipseudomonal agents in cystic fibrosis and chronic wound centers. Forecasts reflect assumptions about FDA breakpoint stability and CMS penalty enforcement continuity. Practitioners should monitor EMA all-cause mortality endpoint requirements and ID physician workforce growth rates for early signals of clinical trial enrollment capacity constraints.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Infection Control
Point of Care Infection Control Market
Infection Control
Veterinary Disinfectant for Pets and Farms Market
Infection Control
Hygiene Stations Market
Infection Control
Ultraviolet Germicidal Irradiation Market
Infection Control
Salivary Gland Infection Market
Infection Control
Healthcare Protective Masks Market
Infection Control
Global Disease Control and Prevention Vaccine Market
Infection Control
Infection Control Surveillance Solutions Market
Infection Control
Peptide-Based Infection Therapeutics Market
Infection Control
Preventable Vaccines Market
Infection Control
Infection Control Market
Infection Control
Virus Filtration Market
Infection Control
Medical Washer Disinfector Market
Infection Control
Ultraviolet Disinfection Equipment Market
Infection Control
Infection Control Supplies Market
Infection Control
Catheter-Related Bloodstream Infections (Crbsis) Market