
 Ear Infection Treatment Market | 2026-2036
Ear Infection Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Ear Infection Treatment Market Intelligence
The development of targeted topical therapies for otitis externa is rewriting the margin structure previously dominated by generic oral antibiotics. Pfizer plc leverages its extensive antibiotic portfolio and R&D capabilities to address emerging resistant pathogens. Novartis AG competes through its focus on specialized pediatric formulations and novel delivery mechanisms. GlaxoSmithKline plc sustains its market presence with a broad range of both prescription and over-the-counter pain relievers associated with ear infections.
Ear infection treatment encompasses pharmacological interventions designed to resolve inflammation of the middle ear (otitis media), outer ear canal (otitis externa), or inner ear. These therapies primarily target bacterial or viral pathogens to alleviate symptoms like pain and hearing impairment, and prevent complications. Antibiotics remain the cornerstone product type, particularly for bacterial infections, though pain relievers hold significant volume. The pediatrics end-user segment commands the largest share, driven by the high incidence of otitis media in young children.
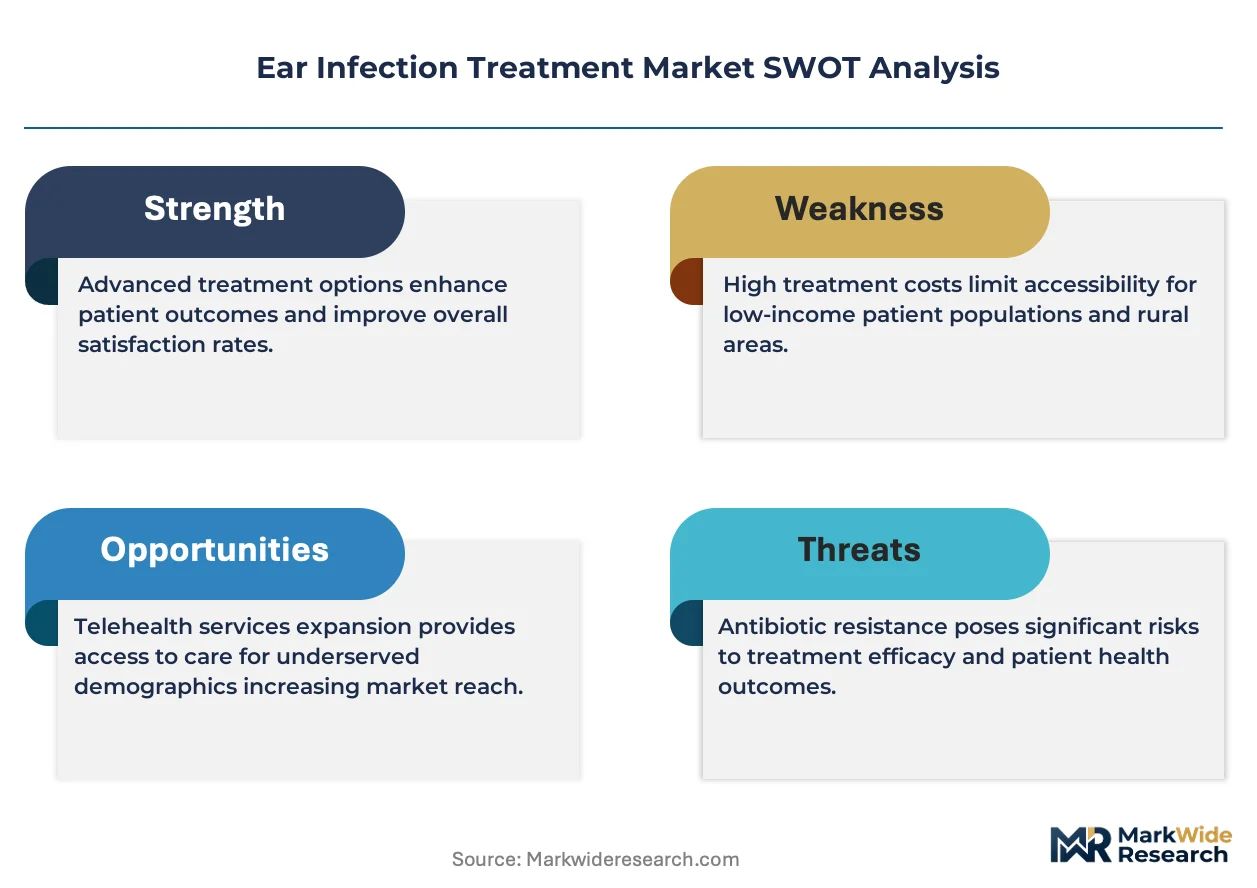
Market access is governed by stringent regulatory approvals from bodies like the U.S. FDA and the European Medicines Agency (EMA). These agencies mandate rigorous clinical trials to prove the safety and efficacy of new antibiotics and combination therapies, influencing R&D timelines. Stakeholders must now navigate the challenge of developing economically viable treatments for antibiotic-resistant infections while meeting evolving payer reimbursement criteria.
Market Dynamics
The central structural force shaping the ear infection treatment market is the escalating pressure from antibiotic-resistant pathogens. This creates a critical tension between the high-volume use of established generic antibiotics and the urgent need for novel therapeutic innovation.
Growth Catalysts
- Targeted Drug Delivery:Advances in topical formulations, including hydrogels and bio-adhesive polymers, enable direct and sustained delivery of active agents to the ear canal, improving efficacy for otitis externa and reducing systemic side effects.
- Pediatric Disease Burden:The persistently high incidence of acute otitis media among young children, particularly in developed nations like the United States and Germany, ensures a large and consistent patient volume for both antibiotics and adjunctive therapies.
- Regulatory Incentives:Programs such as the FDA's Qualified Infectious Disease Product (QIDP) designation provide incentives, including extended market exclusivity, for the development of new antibiotics targeting serious or life-threatening infections, stimulating R&D pipelines.
Market Restraints
- Generic Price Erosion:The widespread availability and low cost of generic oral antibiotics, such as amoxicillin, create significant pricing pressure and a high barrier to entry for more expensive, newly developed treatments, especially in primary care settings.
- Clinical Trial Hurdles:Stringent and lengthy clinical trial requirements mandated by regulatory bodies like the European Medicines Agency (EMA) for new anti-infective agents result in high development costs and extended timelines to market.
- Therapeutic Substitution:The adoption of "watchful waiting" guidelines by pediatric associations in several countries for non-severe otitis media encourages delayed or non-use of antibiotics, acting as a direct substitute and reducing overall prescription volume.
Strategic Opportunities
- Geographic Expansion:Improving healthcare infrastructure and rising disposable incomes in countries like Brazil and Mexico present an opportunity for market entry with both established and novel ear infection treatments, addressing a large, underserved patient population.
- Non-Antibiotic Formulations:There is a significant white-space opportunity in developing and commercializing non-antibiotic therapies, such as biofilm disruptors or anti-inflammatory agents, which can circumvent resistance issues and serve as standalone or adjunctive treatments.
- Specialized Patient Segments:Focusing product development on the needs of specific populations, such as elderly or immunocompromised patients who are more susceptible to severe or complicated ear infections, offers a pathway for specialized, high-value therapeutics.
Industry Challenges
- Reimbursement Fragmentation:Navigating the disparate and often complex reimbursement criteria set by national and regional payers across the European Union presents a substantial operational challenge, complicating commercial strategy and market access for new therapies.
- Antibiotic Discovery Void:The scientific difficulty and high failure rate associated with discovering truly novel classes of antibiotics pose a fundamental challenge to replenishing the R&D pipeline and effectively combating emerging superbugs.
- API Supply Chain Risk:Heavy reliance on a concentrated number of API manufacturers in China and India for key antibiotic starting materials creates potential supply chain vulnerabilities and exposes the market to geopolitical and logistical disruptions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ear Infection Treatment Market |
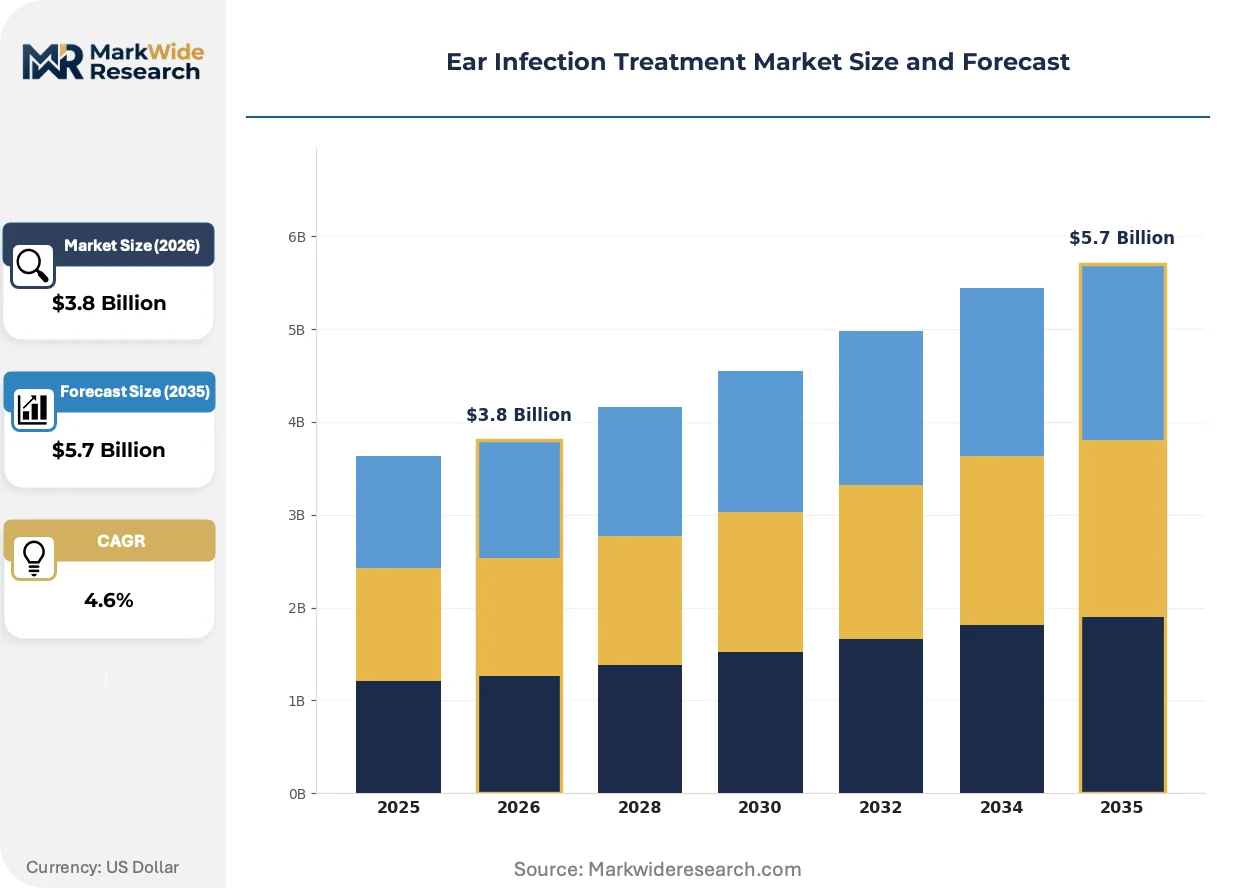
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antibiotics, Antihistamines, Pain Relievers, Steroids Delivery Mode: Oral, Topical, Injectable, Nasal End User: Pediatrics, Adults, Geriatrics, Home Care Distribution Channel: Retail Pharmacies, Online Stores, Hospital Pharmacies, Clinics |
| Companies Covered | Pfizer plc, Olympus Corporation, Novartis AG, GlaxoSmithKline plc, Sanofi SA, Johnson & Johnson, Medtronic, American Diagnostic Corporation, Grace Medical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ear Infection Treatment Market Strategic Shifts & Innovations
A fundamental shift from systemic, broad-spectrum interventions toward precise, localized therapies is defining the market's evolution. This movement is a direct response to the dual pressures of antimicrobial resistance and a deeper understanding of ear infection pathology.
Biofilm-disrupting agents incorporated into topical formulations represent a significant product evolution. These agents work by breaking down the protective matrix that shields bacterial colonies from antibiotics. Otolaryngologists are increasingly adopting this approach for patients with chronic or recurrent otitis externa. This technology is collapsing the prolonged treatment cycles previously required for persistent infections, which often involved multiple courses of less effective systemic drugs.
Regulatory frameworks are adapting to stimulate antimicrobial research. The European Medicines Agency's (EMA) PRIME scheme offers enhanced scientific and regulatory support to developers of medicines targeting unmet needs. This initiative accelerates the assessment timeline for promising new antibiotics intended for resistant pathogens. The segment most affected is the R&D-focused biopharmaceutical sector, which is now more incentivized to invest in challenging clinical programs for novel otic therapies.
Prescribing behavior is changing in response to value-based healthcare initiatives. Clinicians are moving away from empirical treatment with broad-spectrum antibiotics, instead favoring therapies selected based on results from rapid diagnostic tests that identify the specific causative pathogen. This disruption is most visible in integrated health systems in the United States and Sweden, where outcome tracking and antimicrobial stewardship are rigorously enforced.
Ear Infection Treatment Market Segmentation
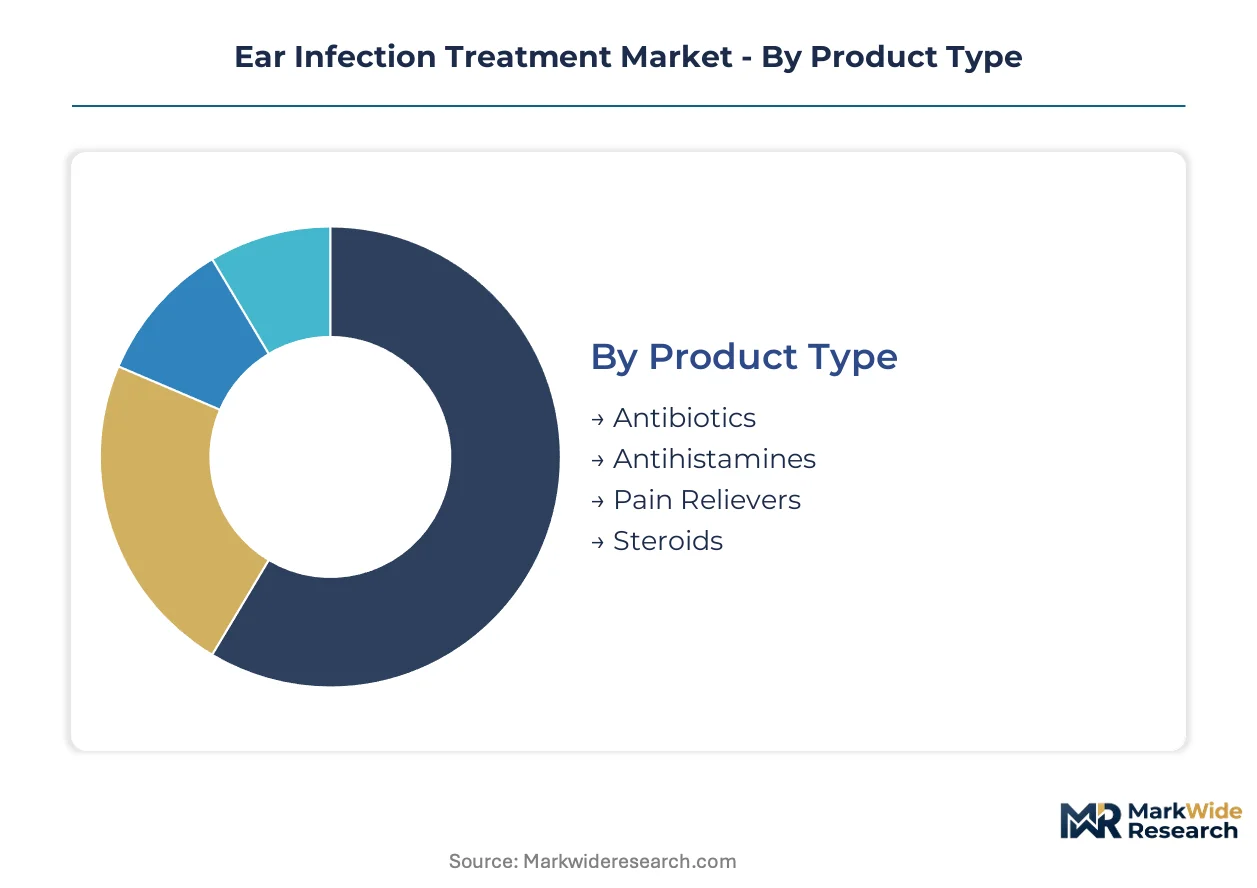
The ear infection treatment market is diverse, characterized by various product types, delivery methods, end-user demographics, and distribution channels. Understanding these segments is crucial for stakeholders to identify areas of unmet need and emerging therapeutic opportunities.
Product Type:
The product type dimension categorizes treatments based on their primary active ingredients and therapeutic mechanisms.
- Antibiotics:Antibiotics represent the foundational treatment for bacterial ear infections, targeting pathogens directly. Demand remains high in pediatric care, particularly in regions with high acute otitis media incidence like the United States.
- Pain Relievers:Pain relievers, including NSAIDs and acetaminophen, manage symptoms like pain and inflammation associated with ear infections. Their volume is substantial across over-the-counter and prescription channels for all age groups.
- Antihistamines:Antihistamines address allergic components contributing to ear congestion and fluid buildup, particularly in cases of serous otitis media. These are often used as adjunctive therapies.
- Steroids:Steroids are prescribed to reduce inflammation and swelling in the ear canal or middle ear, often used in combination with antibiotics or for specific inflammatory conditions.
Antibiotics commands the established base. The steepest expansion runs through Pain Relievers.
Delivery Mode:
Application methods for ear infection treatments vary significantly, influencing patient compliance and therapeutic efficacy.
- Oral:Oral medications, primarily antibiotics, offer systemic treatment for various ear infection types. Their widespread use is driven by convenience and established prescribing habits in primary care settings.
- Topical:Topical formulations, including drops and sprays, deliver localized treatment directly to the ear canal. This mode is gaining traction for otitis externa due to reduced systemic side effects and targeted action.
- Injectable:Injectable treatments are typically reserved for severe, complicated, or resistant ear infections requiring rapid systemic delivery. These are administered in clinical settings, often for inpatient care.
- Nasal:Nasal sprays and drops can alleviate congestion and inflammation in the nasal passages, indirectly improving Eustachian tube function and relieving middle ear pressure.
Oral delivery maintains broad market penetration. Topical applications are rapidly gaining share for localized conditions.
End User:
Customer types define distinct therapeutic requirements and disease prevalence patterns within the ear infection treatment market.
- Pediatrics:The pediatrics segment encompasses infants and young children, experiencing the highest incidence of otitis media. This demographic drives substantial demand for palatable formulations and effective, safe treatments.
- Adults:Adult patients represent a significant end-user group, often seeking treatment for otitis externa and less frequent otitis media. Demand here spans both prescription and over-the-counter remedies.
- Geriatrics:Elderly patients may present with unique challenges, including comorbidities and polypharmacy, influencing treatment selection for ear infections. This segment requires careful consideration of drug interactions.
- Home Care:The home care segment includes patients managing chronic ear conditions or recovering from acute infections outside traditional clinical settings. This area emphasizes ease of administration and patient education.
Pediatrics consistently generates the largest patient volume. The home care segment is showing notable expansion.
Distribution Channel:
Volume flow for ear infection treatments navigates diverse channels, impacting accessibility and pricing structures.
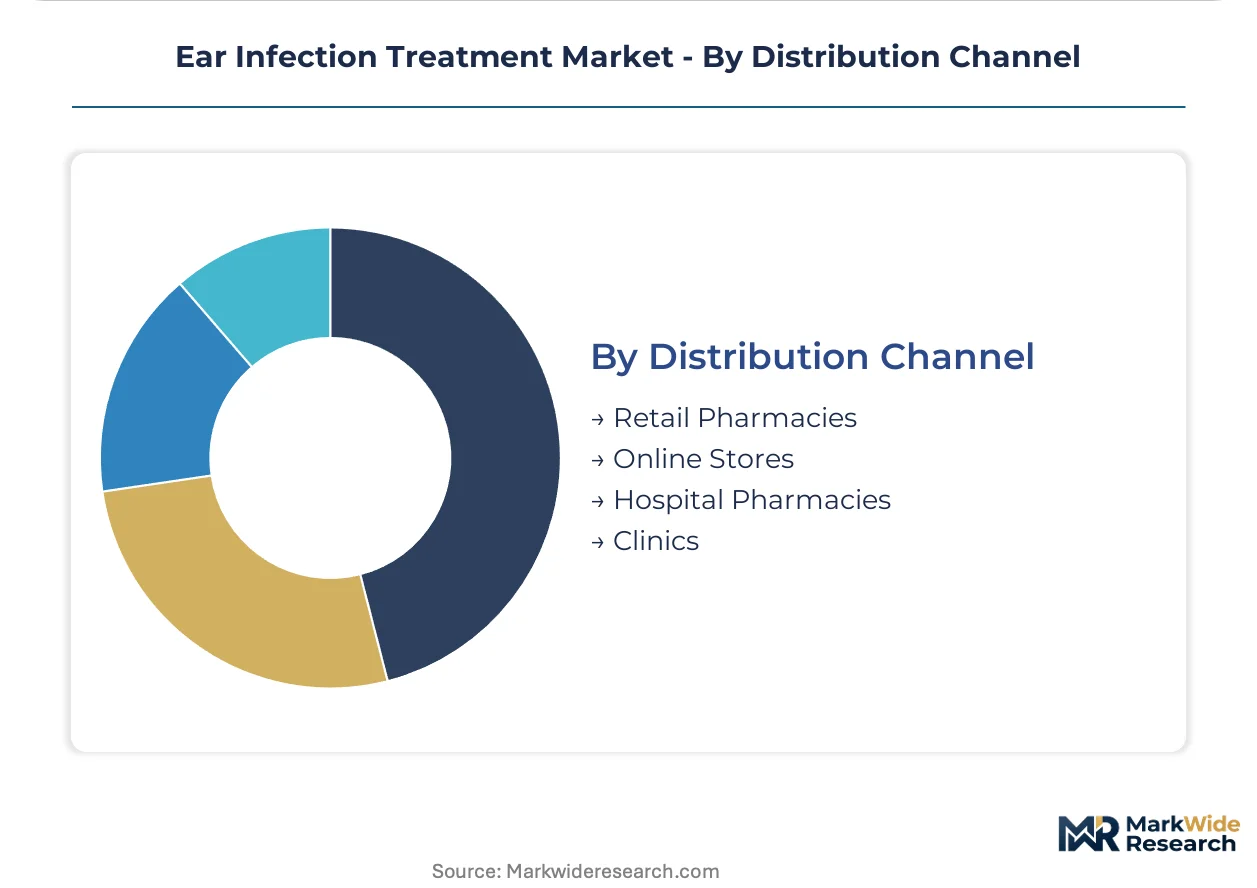
- Retail Pharmacies:Retail pharmacies serve as the primary point of access for both prescription and over-the-counter ear infection medications. Their extensive network ensures broad availability for consumers across urban and rural areas.
- Hospital Pharmacies:Hospital pharmacies dispense specialized or injectable treatments, often for severe or complicated ear infections requiring inpatient care. They also manage procurement for hospital-based clinics and emergency departments.
- Online Stores:Online stores provide a convenient platform for purchasing over-the-counter ear infection remedies and, increasingly, prescription medications through telehealth services. This channel offers competitive pricing and discreet delivery.
- Clinics:Clinics, including general practitioner offices and specialized ENT clinics, directly dispense certain medications or provide samples during patient visits. They play a crucial role in initial diagnosis and prescription.
Retail Pharmacies remain the dominant channel for patient access. Online Stores exhibit the most dynamic growth trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
While the United States emphasizes advanced therapeutic adoption, other regions like India and Brazil focus on broader access to essential antibiotics. The global ear infection treatment market exhibits diverse consumption patterns influenced by healthcare infrastructure, disease burden, and regulatory landscapes. This geographic variation shapes market dynamics for both novel and established therapies.
United States
High prevalence rates of otitis media in children and a strong focus on advanced therapies drive demand for innovative treatments. The U.S. FDA offers Qualified Infectious Disease Product (QIDP) designation to incentivize novel antibiotic development. Major pharmaceutical research clusters in Boston and San Francisco actively pursue next-generation ear infection solutions.
Germany
A robust healthcare system and a significant pediatric population contribute to consistent demand for ear infection treatments. The European Medicines Agency (EMA) ensures rigorous safety and efficacy standards for all new pharmaceutical products. Bavaria and North Rhine-Westphalia host numerous pharmaceutical companies engaged in research and manufacturing of anti-infectives.
India
A large patient base and improving healthcare access fuel demand for both generic and branded ear infection medications. The Central Drugs Standard Control Organization (CDSCO) regulates drug approvals, balancing innovation with affordability. Hyderabad and Mumbai serve as key hubs for generic drug manufacturing and pharmaceutical R&D.
Brazil
Rising disposable incomes and expanding healthcare infrastructure increase the market for ear infection treatments, particularly in urban centers. ANVISA, the national health surveillance agency, plays a critical role in approving and monitoring pharmaceutical products. São Paulo's biomedical cluster is seeing increased investment in localized drug development and distribution.
Japan
An aging population and a focus on high-quality medical care sustain demand for effective ear infection therapies. The Pharmaceuticals and Medical Devices Agency (PMDA) maintains strict regulatory oversight for pharmaceutical products. Tokyo's extensive medical research institutions contribute to advancements in otic drug delivery systems.
Ear Infection Treatment Market Key Industry Players
Capability concentration sits with one tier; scale advantage sits with another within the ear infection treatment market. The market structure is tiered, featuring global pharmaceutical giants alongside specialized biotech firms and regional generic manufacturers. Strategic archetypes include diversified healthcare conglomerates and focused anti-infective developers. Dominant competitive moves involve continuous R&D investment and portfolio diversification to address emerging resistance.
Global pharmaceutical leaders like Pfizer plc and Novartis AG exemplify the diversified healthcare conglomerate archetype, leveraging extensive R&D capabilities and broad market reach. GlaxoSmithKline plc occupies a similar position, utilizing its established portfolio of both prescription and over-the-counter remedies. These companies anchor the premium segment by focusing on novel formulations and specialized pediatric treatments, addressing complex therapeutic needs.
| Leading Market Players |
|---|
| Pfizer plc |
| Olympus Corporation |
| Novartis AG |
| GlaxoSmithKline plc |
| Sanofi SA |
| Johnson & Johnson |
| Medtronic |
| American Diagnostic Corporation |
| Grace Medical |
| Others |
Cost & Logistics Intelligence
Reliance on API manufacturers in China and India for key antibiotic starting materials influences pricing power for generic oral antibiotics. This concentration impacts margin structures across the ear infection treatment market.
Pricing Analysis
Contract-based long-term offtake agreements often govern bulk antibiotic procurement for national health systems. Per-unit transactional pricing dominates over-the-counter pain relievers. Brand premium for novel topical formulations and specific certifications from bodies like the U.S. FDA drive price differentiation. Volume scale also impacts pricing for generic oral antibiotics. Pricing pressure stems from the widespread availability of low-cost generic oral antibiotics. This creates a high barrier to entry for more expensive, newly developed treatments. Pediatric associations' "watchful waiting" guidelines reflect high price sensitivity among primary care providers for non-severe cases. Specialized clinics for recurrent otitis externa show lower price sensitivity for targeted topical therapies.
Supply Chain Analysis
Export restrictions on specific chemical precursors, while not directly targeting ear infection treatments, can indirectly limit the global supply of essential antibiotic APIs from concentrated manufacturing hubs. API manufacturing for essential antibiotics concentrates in China and India. Specialized active ingredients for novel otic therapies increasingly source from European and U.S. biopharmaceutical clusters. The market depends on key chemical precursors for antibiotic synthesis and specialized excipients for advanced topical delivery systems. Glass vials and sterile packaging components also form critical dependencies. Geopolitical disruptions and logistical chokepoints in Asia pose a structural risk to the global supply of generic antibiotics. Regulatory restrictions on certain chemical imports can also impact production timelines. Downstream distribution primarily runs through a network of pharmaceutical wholesalers and retail pharmacies globally. Hospital pharmacies manage specialized and injectable ear infection treatments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The ear infection treatment market presents a significant service-attach opportunity, with rapid diagnostic testing and antimicrobial stewardship programs expanding faster than core pharmaceutical sales. This shift emphasizes outcome-based care and reduces empirical antibiotic use.
For Market Incumbents: Harden existing market positions by investing in R&D for novel, non-antibiotic formulations to counter the threat of antibiotic resistance. Diversify portfolios to include biofilm disruptors and targeted topical therapies, especially for recurrent otitis externa. Control key distribution channels, particularly retail pharmacies, to maintain broad patient access for both prescription and over-the-counter pain relievers. This mitigates pricing pressure from generic oral antibiotics.
For New Entrants and Emerging Players: Pursue white-space opportunities in non-antibiotic therapies, such as anti-inflammatory agents or novel delivery mechanisms for existing compounds, to circumvent resistance issues. The pediatric segment for innovative, palatable formulations remains highly penetrable due to high incidence rates. A go-to-market angle focusing on clinical efficacy for specific patient populations, like immunocompromised individuals, offers a pathway for differentiation. Prioritize regions with improving healthcare infrastructure, such as Brazil and Mexico.
For Investors and Strategic Acquirers: Capital is best deployed toward specialized biopharmaceutical firms developing targeted anti-infectives and advanced drug delivery systems for a long-term viability in the market. These firms often possess strong R&D pipelines addressing unmet needs in antibiotic resistance. An acquisition target archetype would be mid-cap companies with promising Phase II/III clinical assets in otic indications or proprietary topical formulation technologies. The signal to watch for inflection is successful clinical trial completion for novel non-antibiotic agents.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Accelerate development of novel non-antibiotic therapies to address emerging resistance mechanisms. |
| Regulatory Approval Pathway | Expedite market access for promising anti-infectives via programs like the EMA's PRIME scheme. |
| Manufacturing Scale-Up | Increase production capacity for advanced topical formulations to meet growing demand in otitis externa. |
| Strategic Partnership | Collaborate with diagnostic companies to integrate rapid pathogen identification into treatment protocols. |
| Portfolio Diversification | Expand offerings to include adjunctive therapies like biofilm disruptors for chronic ear infections. |
Research Approach
Two parallel data streams informed the analysis: primary interviews with industry stakeholders and secondary validation from published sources. Primary fieldwork involved discussions with drug development executives, regulatory affairs leads, and hospital procurement managers across the U.S. and Europe. Secondary data was drawn from U.S. FDA filings, EMA submissions, and pharmaceutical company annual reports. This approach ensured bottom-up market sizing triangulated with top-down industry insights.
Forecast inputs considered disease prevalence rates, treatment adoption patterns, and regulatory landscape changes across the analysis window. The analytical framework segmented the market by product type, delivery mode, end-user demographics, and regional therapeutic preferences. Compound annual growth rates were derived from historical data trends and projected shifts in medical practice. Key forecast inputs included the incidence of acute otitis media and the pace of antibiotic resistance development.
Macroeconomic conditions sit as an overlay; deviation in global healthcare spending or pharmaceutical R&D investment would shift the trajectory. Forecasts reflect current assumptions regarding regulatory approvals and market access policies. Material shifts in antimicrobial resistance patterns or major public health crises would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Infection Control
Sterility Indicators Market
Infection Control
Antimicrobial Wipes Market
Infection Control
Disinfection Cupboard Market
Infection Control
Alcohol Wipes Market
Infection Control
Hospital Acquired Infections Therapeutic Market
Infection Control
Australia Hand Sanitizer Market
Infection Control
Disinfection Equipment Market
Infection Control
Australia Healthcare Surface Disinfectant Wipes Market
Infection Control
North America Bloodstream Infection Testing Market
Infection Control
Antimicrobial Catheters Market
Infection Control
Healthcare Associated Infections (HAI) Treatment Market
Infection Control
Global Infection Prevention Devices Market
Infection Control
New Zealand Healthcare Surface Disinfectant Wipes Market
Infection Control
Sterilization Tunnel Market
Infection Control
Point of Care Infection Control Market
Infection Control
Hygiene Stations Market