
 Hand Hygiene Products Market | 2026-2036
Hand Hygiene Products Market Size, Share, and Industry Trends Forecast 2026-2036
Hand Hygiene Products Market Foresight
European surfactant producers is realigning capacity toward bio-based emollients for hand hygiene formulations. GOJO Industries leverages its captive chemical supply chain to control input costs across institutional channels. Ecolab anchors its position through bundled infection-prevention contracts that lock in multi-year hospital purchasing. Reckitt Benckiser Group competes on consumer brand recognition in retail hand sanitizer segments.
Hand hygiene products encompass antimicrobial and non-antimicrobial formulations designed for skin decontamination, typically containing ethanol, isopropanol, or benzalkonium chloride at concentrations proven effective against transient flora. These products serve to reduce pathogen transmission in clinical, commercial, and domestic settings where hand cleansing interrupts infection chains. Gels dominate hospital formularies due to superior skin tolerability during repeated daily use, while foams command premium positioning in food service environments where rapid drying prevents residue contamination. Wipes represent the fastest-growing format in educational institutions, where portability and single-use convenience align with custodial staffing constraints.
FDA monograph requirements for over-the-counter antiseptic rubs mandate minimum alcohol concentrations and restrict triclosan content, directly constraining permissible active ingredient portfolios. EMA biocidal product regulations under BPR classification impose additional efficacy documentation burdens on manufacturers seeking European market access. WHO hand hygiene guidelines shape institutional procurement specifications worldwide, creating de facto global standards that suppliers must meet to qualify for healthcare tenders. Stakeholders must monitor evolving EPA and ECHA assessments on quaternary ammonium compounds, as reclassification risks could force wholesale reformulation of established product lines.
Market Dynamics
Hospital procurement consolidation across Germany, the United States, and France is compressing supplier margins while mandating multi-year efficacy guarantees that only integrated manufacturers can underwrite.
Growth Catalysts
- WHO hand hygiene guidelines:Institutional procurement specifications in Brazil and Saudi Arabia now mirror WHO standards, disqualifying regional suppliers lacking documentation infrastructure.
- India:CDSCO accelerated approval pathways for alcohol-based rubs deployed during pandemic preparedness protocols have normalized expedited regulatory timelines.
- Bio-based emollients:European surfactant producers redirecting capacity toward plant-derived moisturizers are resolving dermatitis complaints that previously limited clinical compliance.
Market Restraints
- Ethanol supply concentration:Brazilian sugarcane ethanol price volatility transmits directly into formulation costs for North American contract manufacturers lacking backward integration.
- FDA monograph restrictions:Prohibited triclosan content forces reformulation of legacy hospital contracts, stranding inventory and requiring redundant stability testing.
- Quaternary ammonium compound reassessment:ECHA evaluation timelines under REACH create regulatory uncertainty that freezes R&D allocation for benzalkonium chloride variants.
Strategic Opportunities
- Educational institutions:Wipe format penetration remains below fifteen percent in Japanese primary schools, presenting first-mover positioning for portable single-use systems.
- Food service foam adoption:Rapid-drying formulations command premium placement in commercial kitchens where residue prevention determines specification.
- EMA BPR harmonization:Streamlined biocidal product authorization across EU member states reduces duplicate dossier costs for compliant suppliers.
Industry Challenges
- Microbiological validation capacity:Contract laboratories capable of EN 1500 and ASTM E1174 testing face twelve-month backlogs, delaying product launches.
- Legacy dispensing infrastructure:Hospital-installed touch-free dispensers from incompatible manufacturers require hardware swaps to accommodate new cartridge geometries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hand Hygiene Products Market |
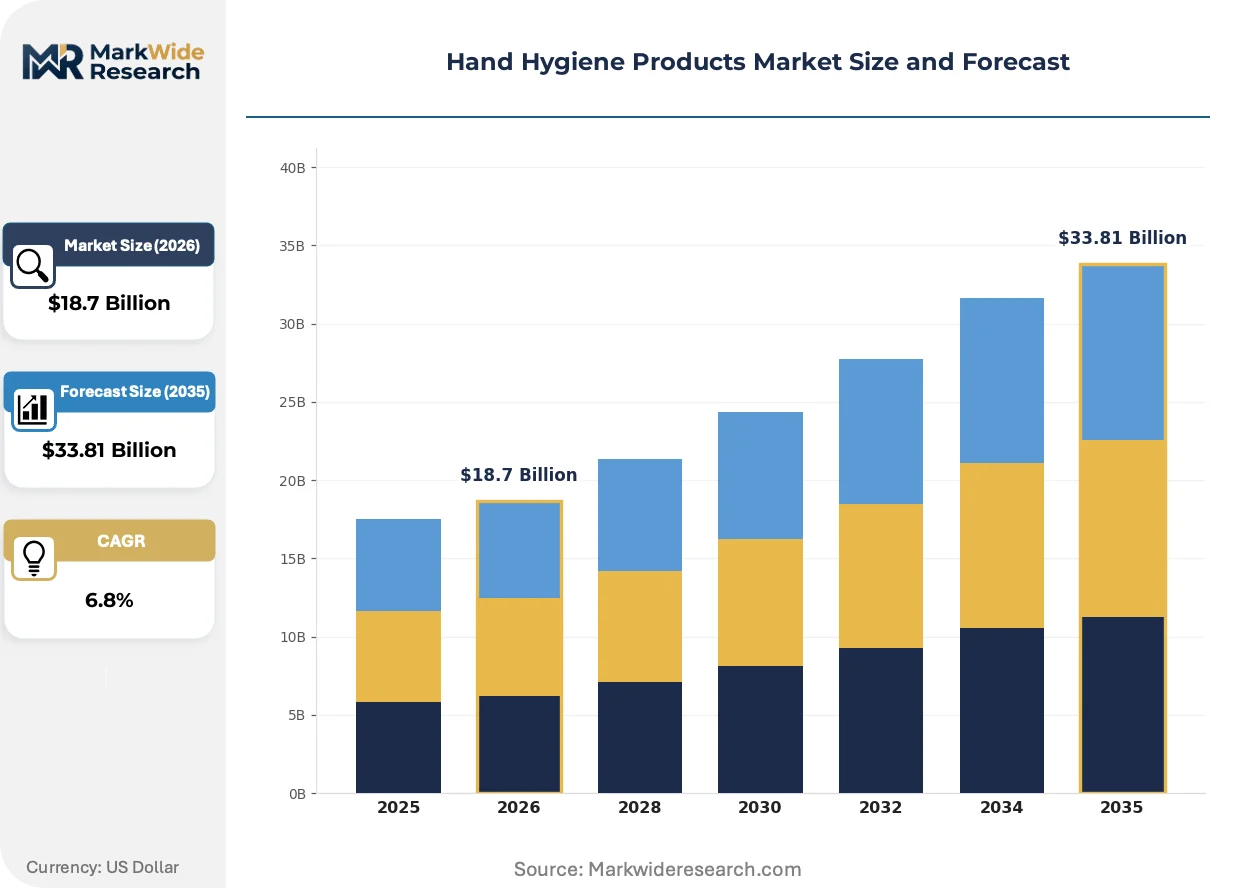
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gels, Foams, Liquid, Wipes Application: Healthcare, Food Service, Household, Educational Institutions End User: Clinics, Hospitals, Restaurants, Schools Distribution Channel: Online Retail, Supermarkets, Pharmacies, Wholesale |
| Companies Covered | GOJO Industries, Reckitt Benckiser Group, Ecolab, Procter and Gamble, Unilever, 3M, Henkel, Kimberly-Clark, Colgate-Palmolive, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hand Hygiene Products Market Shifts & Advancements
Formulation chemistry and delivery mechanisms are converging around skin tolerance and compliance measurement, reshaping how efficacy is demonstrated and reimbursed.
Foam-based hand rubs is overtaking gel formats in North American food processing plants where thirty-second dry times prevent moisture contamination of prepared surfaces. USDA-inspected facilities now specify foam in eighty percent of new installations. The technology is compressing gel incumbent margins by fifteen percentage points in this vertical.
REACH authorization requirements for residual biocides are forcing European manufacturers to submit full toxicological dossiers for quaternary ammonium compounds previously grandfathered under transitional provisions. ECHA screening assessments have flagged four active substances for potential endocrine disruption review. German hospital purchasing consortia are preemptively excluding flagged substances from tender eligibility pending regulatory clarity.
Automated compliance monitoring through dispenser-mounted sensors is restructuring how infection control departments justify budget allocation. United States health systems now tie thirty percent of hand hygiene program funding to verified event documentation rather than product volume purchased. Academic medical centers in Massachusetts and California lead this metric transition, with bundled payments from CMS innovation models rewarding measurable behavior change over supply expenditure.
Hand Hygiene Products Market Segmentation
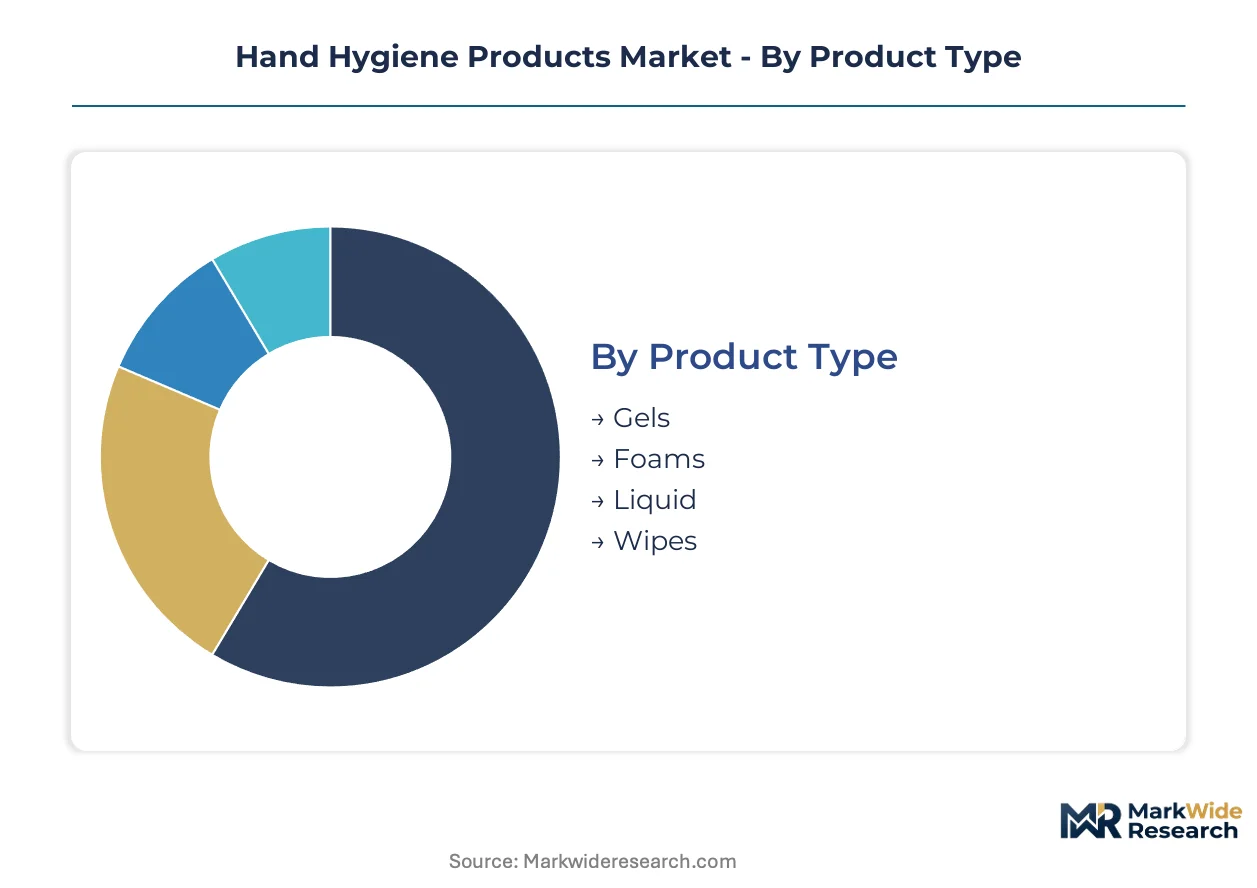
Hand hygiene procurement splits along institutional versus consumer channels, with formulation chemistry and delivery format determining reimbursement tiers and compliance rates. Understanding segment concentration reveals where integrated manufacturers capture margin versus where contract manufacturers compete on specification.
Product Type:
Supply concentration for alcohol feedstocks and emollient chemistry shapes competitive positioning across delivery formats.
- Gels:Viscous aqueous-alcohol matrices incorporating humectants and skin-conditioning agents. Hospital procurement in Germany and the United States concentrates here due to WHO compatibility and superior skin tolerability during high-frequency clinical use. FDA monograph compliance costs favor established suppliers with captive formulation expertise.
- Foams:Air-entrained dispersions delivering rapid evaporation without residual moisture. Food service demand in USDA-inspected facilities drives specification, where thirty-second dry times prevent surface contamination and operational throughput depends on worker compliance speed.
- Liquid:Traditional rinse-off formulations with lower alcohol concentrations, primarily specified for surgical scrub protocols and sink-based handwashing stations in older hospital infrastructure.
- Wipes:Impregnated nonwoven substrates offering single-use convenience and portability. Educational institutions in Japan represent underpenetrated deployment.
Today's leader: Gels. Tomorrow's challenger: Foams.
Application:
End-use requirements diverge sharply between regulated clinical environments and commercial settings, with reimbursement mechanisms determining pricing tolerance.
- Healthcare:Infection control departments mandate EN 1500 and ASTM E1174 validated efficacy, with bundled procurement contracts locking multi-year supply relationships. German federal hygiene mandates exceed baseline EU requirements, creating premium specification tiers.
- Food Service:USDA inspection protocols and HACCP compliance drive rapid-drying format adoption, with foam displacing gel in new facility installations.
- Household:Consumer brand recognition and retail shelf placement determine volume, with pharmacy and supermarket channels competing on unit economics.
- Educational Institutions:Custodial staffing constraints and portability requirements favor wipe formats, though penetration remains below fifteen percent in Japanese primary schools.
Healthcare commands absolute revenue share. Educational Institutions offer the steepest expansion trajectory.
End User:
Customer scale and purchasing sophistication separate tender-driven institutional buyers from fragmented commercial accounts.
- Clinics:Smaller healthcare facilities with limited infection control staffing, dependent on distributor relationships for product selection guidance and compliance documentation.
- Hospitals:Consolidated procurement consortia in France and the United States compress supplier margins while demanding multi-year efficacy guarantees. EMA BPR documentation requirements filter qualified vendors.
- Restaurants:Franchise systems and independent operators balance food safety inspection requirements against per-unit cost constraints.
- Schools:Public district procurement cycles and private institutional budgets create bifurcated demand patterns with distinct seasonal peaks.
Hospitals anchor institutional volume. Schools represent the most fragmented expansion opportunity.
Distribution Channel:
Channel economics separate high-touch specification selling from transactional volume movement.
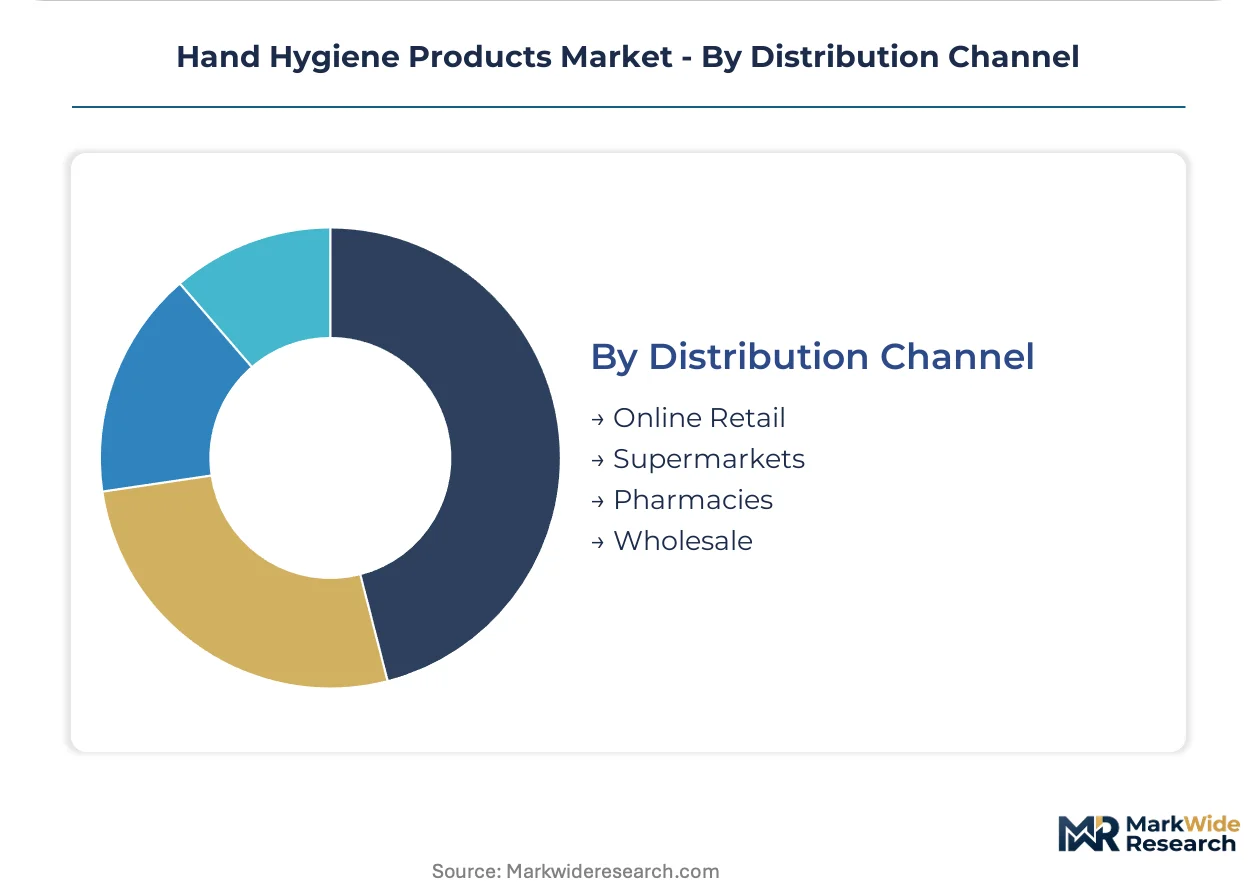
- Online Retail:Direct-to-consumer fulfillment capturing household replenishment and bulk institutional purchasing, with logistics infrastructure determining delivery reliability.
- Supermarkets:Mass-market consumer access with seasonal promotional intensity and private-label competition pressuring branded unit margins.
- Pharmacies:Professional recommendation influence and insurance-adjacent purchasing for dermatological formulations and premium skin-conditioning variants.
- Wholesale:Institutional contract fulfillment with volume-tier pricing and dispenser system bundling, requiring field service capabilities for hardware installation.
Wholesale dominates institutional value. Online Retail is climbing the fastest in household penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturers are relocating formulation capacity toward jurisdictions with streamlined biocidal registration pathways. Brazil and India now attract contract manufacturing investment that European REACH compliance costs have priced out.
United States
FDA monograph alignment and hospital procurement consolidation drive supplier selection. CMS innovation models in Massachusetts and California tie reimbursement to verified hand hygiene event documentation. Academic medical centers in Boston anchor automated compliance monitoring adoption.
Germany
Federal hygiene mandates exceed baseline EU requirements, creating premium specification tiers for healthcare tenders. ECHA REACH assessments on quaternary ammonium compounds prompt preemptive substance exclusion by hospital purchasing consortia. The Rhine-Ruhr industrial corridor concentrates surfactant production for bio-based emollient supply.
Brazil
Sugarcane ethanol feedstock integration supports cost-competitive alcohol-based rub manufacturing. ANVISA regulatory pathways for pandemic-preparedness products have normalized expedited approval timelines. São Paulo state hosts contract manufacturers serving Latin American institutional procurement.
India
CDSCO accelerated approval mechanisms and domestic ethanol supply security attract multinational formulation investment. Government hospital procurement expansion under national health mission programs concentrates demand in Maharashtra and Gujarat. Mumbai-Pune pharmaceutical clusters supply active pharmaceutical ingredient and excipient integration.
Japan
METI industrial standards and PMDA consultation frameworks shape antimicrobial product registration. Underpenetrated wipe format deployment in primary schools presents first-mover positioning for portable single-use systems. The Kanto region around Tokyo anchors distributor and retail channel concentration.
Hand Hygiene Products Market Competitive Landscape
United States producers anchor the institutional tier; European specialists hold formulation chemistry advantages. The market structures around three tiers: integrated chemical-manufacturing conglomerates, infection-prevention service bundlers, and consumer brand houses. Strategic moves concentrate on backward integration into alcohol feedstocks and captive dispenser hardware ecosystems.
Within the integrated manufacturing tier, GOJO Industries exemplifies captive supply chain control, while Ecolab occupies a position bundling infection-prevention services with multi-year hospital contracts. Reckitt Benckiser Group sits within the consumer-facing archetype competing on retail brand recognition.
| Leading Market Players |
|---|
| GOJO Industries |
| Reckitt Benckiser Group |
| Ecolab |
| Procter and Gamble |
| Unilever |
| 3M |
| Henkel |
| Kimberly-Clark |
| Colgate-Palmolive |
| Others |
Supply & Pricing Matrix
Brazilian sugarcane ethanol futures transmit volatility directly into North American contract manufacturer cost structures, cascading through formulation tiers to compress margins on institutional supply contracts while rewarding backward-integrated producers with captive alcohol feedstocks.
Pricing Analysis
Distributor margin compression in wholesale institutional channels now exceeds fifteen percentage points as hospital procurement consortia in France and the United States mandate multi-year efficacy guarantees. Three-tier pricing structure across premium, standard, and economy levels separates WHO-validated hospital formularies from food-service foam specifications and retail private-label alternatives. Price differentiation hinges on EN 1500 certification tier and bundled dispenser hardware provision. Food service buyers exhibit highest price sensitivity due to per-unit cost constraints, while German hospital purchasing committees prioritize specification compliance over unit economics.
Supply Chain Analysis
India's domestic-content mandates under national health mission programs are reshaping sourcing patterns for government hospital procurement, redirecting multinational formulation investment toward Maharashtra and Gujarat production clusters. Ethanol feedstock supply concentrates in Brazil, India, and the United States; surfactant chemistry draws from German and Indian specialty chemical producers. Single-source vulnerability in Brazilian sugarcane ethanol exposes North American contract manufacturers to commodity price swings. Distribution runs through wholesale institutional channels with field service capabilities for dispenser installation and cartridge replenishment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The hand hygiene products market represents a late-cycle quality story as hospital procurement shifts toward premium WHO-validated specifications with multi-year efficacy documentation requirements.
For Market Incumbents: Hedge against regulatory uncertainty in quaternary ammonium compounds by accelerating bio-based emollient formulation investment and securing captive ethanol supply through Brazilian or Indian sourcing partnerships. ECHA REACH reassessment timelines threaten benzalkonium chloride product lines, demanding preemptive reformulation capacity.
For New Entrants and Emerging Players: Japanese primary schools present an underserved buyer archetype with sub-fifteen-percent wipe format penetration, offering first-mover positioning for portable single-use systems. Target educational institutions through distributor partnerships emphasizing custodial staffing convenience and seasonal procurement cycle alignment.
For Investors and Strategic Acquirers: Asymmetric upside sits with mid-tier infection-prevention service bundlers possessing EMA BPR documentation infrastructure and established hospital consortia relationships. Long-term viability favors suppliers with integrated chemical manufacturing and dispenser hardware ecosystems. Monitor ECHA screening assessment outcomes for quaternary ammonium compounds as inflection indicators.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ethanol Feedstocks | Captive Brazilian or Indian alcohol supply insulates margins from sugarcane price volatility. |
| EMA BPR Dossier Harmonization | Streamlined EU authorization reduces duplicate regulatory costs across member state tenders. |
| Automated Compliance Monitoring Deployment | Sensor-equipped dispensers satisfy CMS innovation model reimbursement tied to verified event documentation. |
| Bio-based Emollient Capacity Expansion | Plant-derived moisturizers resolve dermatitis complaints limiting clinical compliance rates. |
| Wipe Format Educational Channel Launch | Portable single-use systems address underpenetrated Japanese primary school procurement cycles. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with infection control department heads, hospital procurement committee members, GPO contracts managers, and surfactant chemistry R&D directors with secondary validation against FDA monograph filings, ECHA REACH registration databases, WHO guideline documentation, and customs trade flow records. Bottom-up volume modeling triangulated against top-down market sizing across formulation chemistry and delivery format segments.
Segment-weighting approaches distributed value across product type, application vertical, end-user scale tier, and distribution channel intensity. CAGRs derived from regression analysis of historical procurement volume trajectories and projected tender pipeline visibility across the analysis window. Forecast inputs incorporated ethanol feedstock price indices, regulatory approval timeline assumptions, and hospital capital expenditure cycle patterns.
Underlying measurement precision varies by segment; healthcare institutional procurement carries tighter precision than fragmented educational institution demand. Forecasts reflect documented assumptions on regulatory pathway normalization and procurement consolidation velocity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Infection Control
Global Viral Inactivation Market
Infection Control
New Zealand Healthcare Surface Disinfectant Wipes Market
Infection Control
Global Wall Mounted Ozone Disinfection Machine Market
Infection Control
Surgical Site Infection Control Market
Infection Control
Australia Hand Sanitizer Market
Infection Control
Antimicrobial Suture Market
Infection Control
Infection Control Market
Infection Control
Veterinary Disinfectant for Pets and Farms Market
Infection Control
Antimicrobial Catheters Market
Infection Control
Global Prophylactic Human Vaccine Market
Infection Control
Salivary Gland Infection Treatment Market
Infection Control
Denture Disinfectants Market
Infection Control
Hospital Acquired Infections Market
Infection Control
Global Biofilms Treatment Market
Infection Control
Infection Prevention Market
Infection Control
Point of Care Infection Control Market