
 Hand Hygiene Market | 2026-2036
Hand Hygiene Market Size, Share, and Industry Trends Forecast 2026-2036
Hand Hygiene Market Outlook
Alcohol-based formulations is pivoting toward benzalkonium chloride alternatives in pediatric and sensitive-skin product lines. GOJO Industries leverages captive supply chains for sanitizer dispensers in healthcare corridors. Reckitt Benckiser Group sustains brand recognition through Lysol's retail shelf presence across mass-market channels. Ecolab dominates institutional contracts with bundled hygiene programs for hospital networks.
Hand hygiene encompasses antiseptic and disinfectant preparations designed to reduce microbial load on intact skin, typically incorporating ethanol, isopropanol, or quaternary ammonium compounds at concentrations validated by suspension and carrier testing protocols. The primary commercial purpose centers on interrupting pathogen transmission vectors in clinical, food-handling, and congregate settings. Gels and foams anchor the product-type mix due to dosing precision and reduced drip rates in high-throughput environments. Alcohol-based formulations command the formulation segment through rapid dry times and broad-spectrum efficacy against enveloped viruses. Institutional sales channels capture margin pools through multi-year service contracts integrating product supply with compliance monitoring.
FDA monograph requirements govern over-the-counter antiseptic active ingredients and labeling claims in the United States, while EPA regulates surface disinfectants with residual antimicrobial claims under FIFRA. The EU Green Deal and REACH frameworks restrict certain biocidal actives, compelling reformulation investments for exporters serving European healthcare procurement. WHO hand-hygiene guidelines shape hospital purchasing specifications across member states through formal recommendations embedded in accreditation standards. Stakeholders must monitor evolving regulatory thresholds for emerging actives and sustainability-linked procurement criteria in institutional tenders.
Market Dynamics
Joint Commission accreditation mandates are compressing purchasing cycles across acute-care networks, forcing suppliers to bundle compliance monitoring with product supply or lose multi-year contracts to integrated service providers.
Growth Catalysts
- Hospital-acquired infection protocols:CMS reimbursement penalties for preventable infections are accelerating procurement of touch-free dispensing systems in US acute-care facilities.
- REACH biocidal restrictions:EU Green Deal frameworks are compelling manufacturers to reformulate with sustainable actives, creating first-mover advantages for compliant exporters.
- Ethanol supply concentration:Corn-belt processing clusters in the US Midwest are securing captive feedstock for domestic sanitizer production at scale.
Market Restraints
- Isopropanol price volatility:Propylene feedstock swings tied to petrochemical cycles are squeezing margin structures for mid-tier contract manufacturers.
- FDA monograph uncertainty:Pending final rules on benzalkonium chloride efficacy thresholds are freezing R&D pipelines for alternative actives.
- Surface disinfectant substitution:UV-C and hydrogen peroxide vapor systems are capturing high-risk procedure budgets in surgical suites.
Strategic Opportunities
- Indian outpatient expansion:Ayushman Bharat health coverage is extending hygiene protocols to tier-2 and tier-3 clinic networks previously underserved by institutional suppliers.
- IoT-enabled compliance tracking:Sensor-integrated dispensers are converging with building management systems to capture real-time hand-hygiene adherence data.
- Saudi healthcare privatization:SFDA localization requirements are opening tender opportunities for joint-venture manufacturing within the Kingdom.
Industry Challenges
- Microbiologist talent scarcity:Suspension testing and carrier-method validation expertise is concentrating at contract labs, extending new product registration timelines.
- Legacy dispenser retrofit costs:Healthcare facilities face capital burdens replacing mechanical units with connected systems to meet digital compliance mandates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hand Hygiene Market |
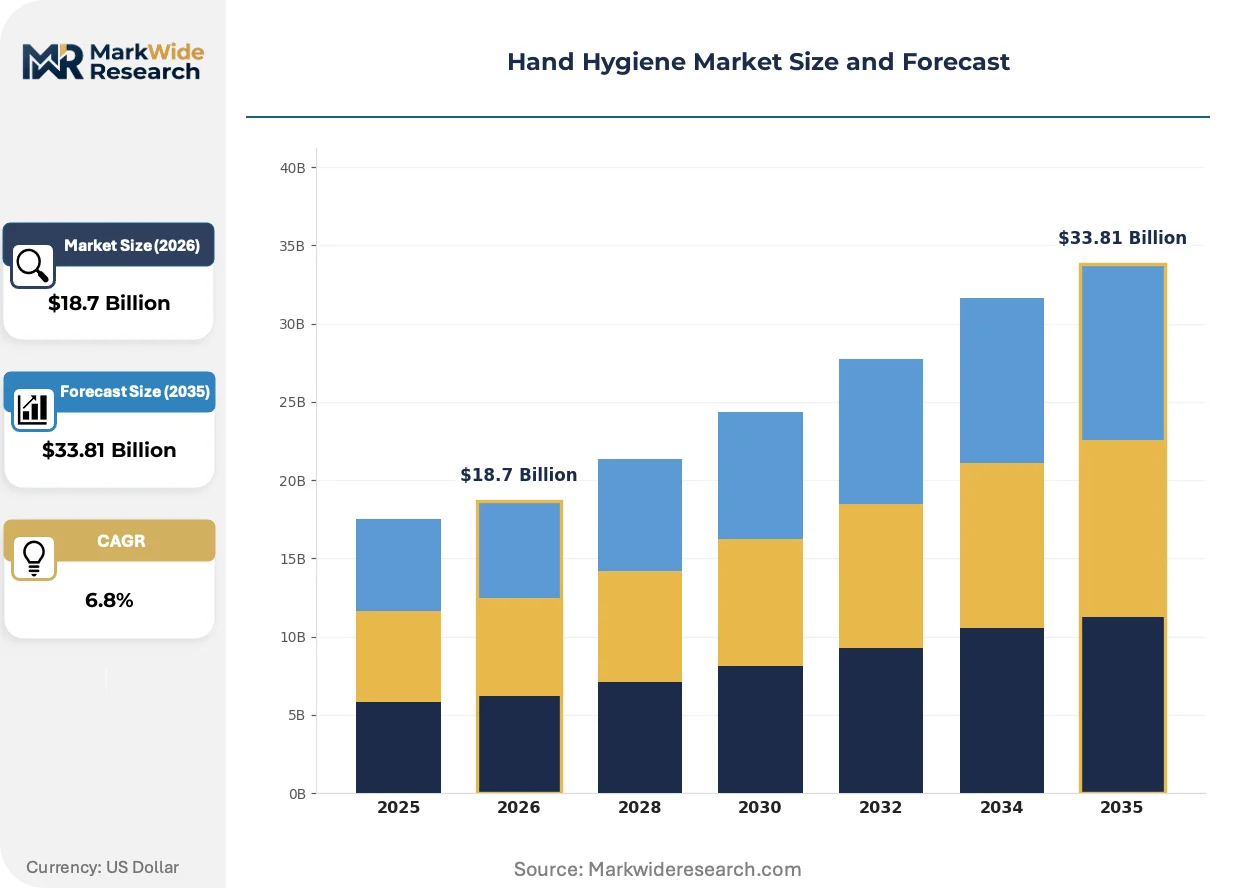
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gels, Foams, Wipes, Sprays End User: Healthcare Facilities, Educational Institutions, Food Service, Residential Formulation: Alcohol-Based, Non-Alcohol-Based, Antiseptic, Disinfectant Distribution Channel: Offline Retail, Online Retail, Direct Sales, Institutional Sales |
| Companies Covered | GOJO Industries, Reckitt Benckiser Group, The Procter & Gamble Company, 3M Company, Henkel, Unilever, Vi-Jon Laboratories, The Clorox Company, Ecolab, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hand Hygiene Market Strategic Shifts
Formulation science and connected hardware are converging to redefine value capture, shifting competition from commodity alcohol supplies toward data-integrated hygiene programs that lock in long-term institutional relationships.
Hypochlorous acid formulations are expanding into pediatric and neonatal care units where skin sensitivity excludes traditional alcohol bases. Children's hospitals in the US and EU are piloting these alternatives for incubator-side protocols. The technology is expanding into premium product tiers previously dominated by legacy quaternary ammonium compounds.
EPA's emerging viral pathogen claim framework is tightening efficacy demonstration requirements for disinfectants targeting enveloped viruses. Manufacturers must now submit quantitative suspension data against surrogate organisms rather than relying on label extensions. Surface wipe producers serving US long-term care facilities are restructuring testing budgets to accommodate accelerated submission cycles.
Consolidated purchasing through group purchasing organizations is compressing vendor rosters and unbundling after-sales service from product supply. Independent acute-care hospitals are losing leverage as regional health systems centralize procurement decisions. The shift is most visible in US Midwest networks where Catholic health systems and for-profit chains dominate bed capacity.
Hand Hygiene Market Segmentation
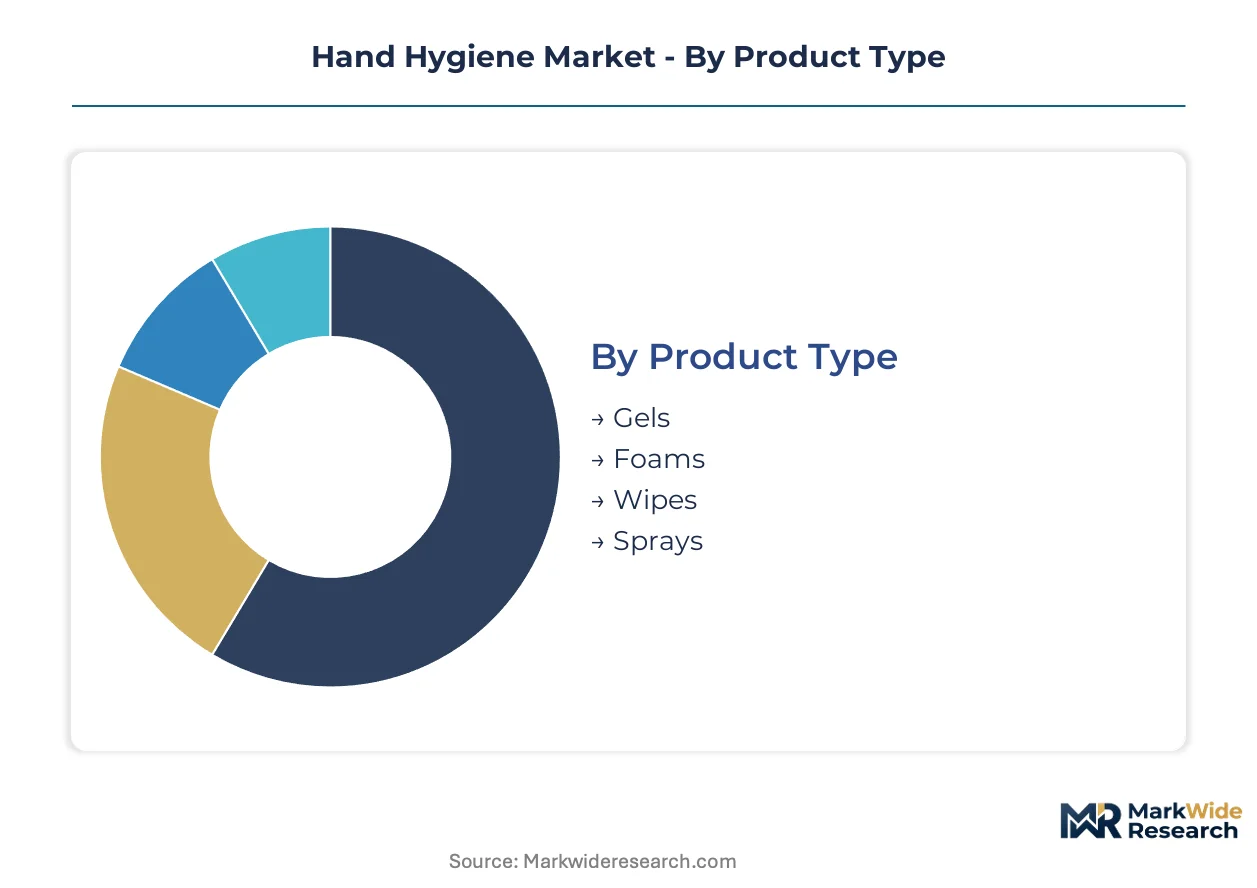
Hand hygiene procurement splits sharply between standardized commodity formats and customized compliance-integrated programs. Segment boundaries determine margin capture, with institutional channels and alcohol-based formulations commanding premium pricing against mass-market alternatives.
Product Type:
Customization concentrates in dosing mechanisms and viscosity engineering, while standardization dominates volume manufacturing for retail channels.
- Gels:Viscosity-controlled formulations enable precise volume dosing through pump dispensers in high-throughput hospital corridors. Demand clusters in North American acute-care settings where Joint Commission mandates specify touch-free dispensing compatibility.
- Foams:Air-entrainment technology reduces per-use volume by 30-40% versus gels, lowering total cost of ownership for budget-constrained facilities. European healthcare networks prioritize foams for sustainability-linked procurement tenders under EU Green Deal frameworks.
- Wipes:Saturated substrate formats serve food-service and educational settings requiring surface disinfection alongside hand hygiene.
- Sprays:Aerosol and trigger-spray delivery systems capture niche demand in residential and industrial safety applications.
Most installed capacity flows through Gels. Expansion is steepest in Foams.
End User:
Cost tier separation runs from capital-intensive integrated programs at the top to price-sensitive individual purchasing at the bottom.
- Healthcare Facilities:CMS reimbursement penalties for hospital-acquired infections drive procurement of sensor-integrated dispensing systems with real-time compliance monitoring. US acute-care networks bundle multi-year service contracts covering product supply, dispenser maintenance, and adherence analytics.
- Food Service:FDA Food Code compliance mandates hand-wash stations alongside hand-sanitizer placement in commercial kitchens. Quick-service chains standardize on alcohol-based foams to minimize fire hazards near cooking surfaces.
- Educational Institutions:K-12 districts and universities prioritize benzalkonium chloride alternatives for pediatric safety, with procurement centralized through state cooperative purchasing agreements.
- Residential:Mass-market retail channels dominate, with brand recognition and shelf placement determining purchase decisions over formulation specifications.
Revenue concentration sits with Healthcare Facilities. Volume expansion is climbing the fastest in Educational Institutions.
Formulation:
Application requirements dictate active ingredient selection, with clinical efficacy thresholds separating regulated antiseptics from general-use sanitizers.
- Alcohol-Based:Ethanol and isopropanol formulations at 60-95% concentration deliver rapid kill kinetics against enveloped viruses. FDA monograph compliance and WHO formulation guidelines anchor procurement specifications across US and European healthcare systems.
- Non-Alcohol-Based:Benzalkonium chloride and hypochlorous acid alternatives serve pediatric, neonatal, and sensitive-skin applications where alcohol irritation risks exclude standard formulations. REACH biocidal restrictions are accelerating reformulation investments for EU market access.
- Antiseptic:Surgical hand-scrub preparations with persistent antimicrobial activity meet operating-room protocols for extended procedures.
- Disinfectant:EPA-registered surface formulations with residual claims capture environmental hygiene budgets in long-term care and veterinary settings.
Technology leadership resides with Alcohol-Based formulations. Regulatory pressure is expanding Non-Alcohol-Based most quickly.
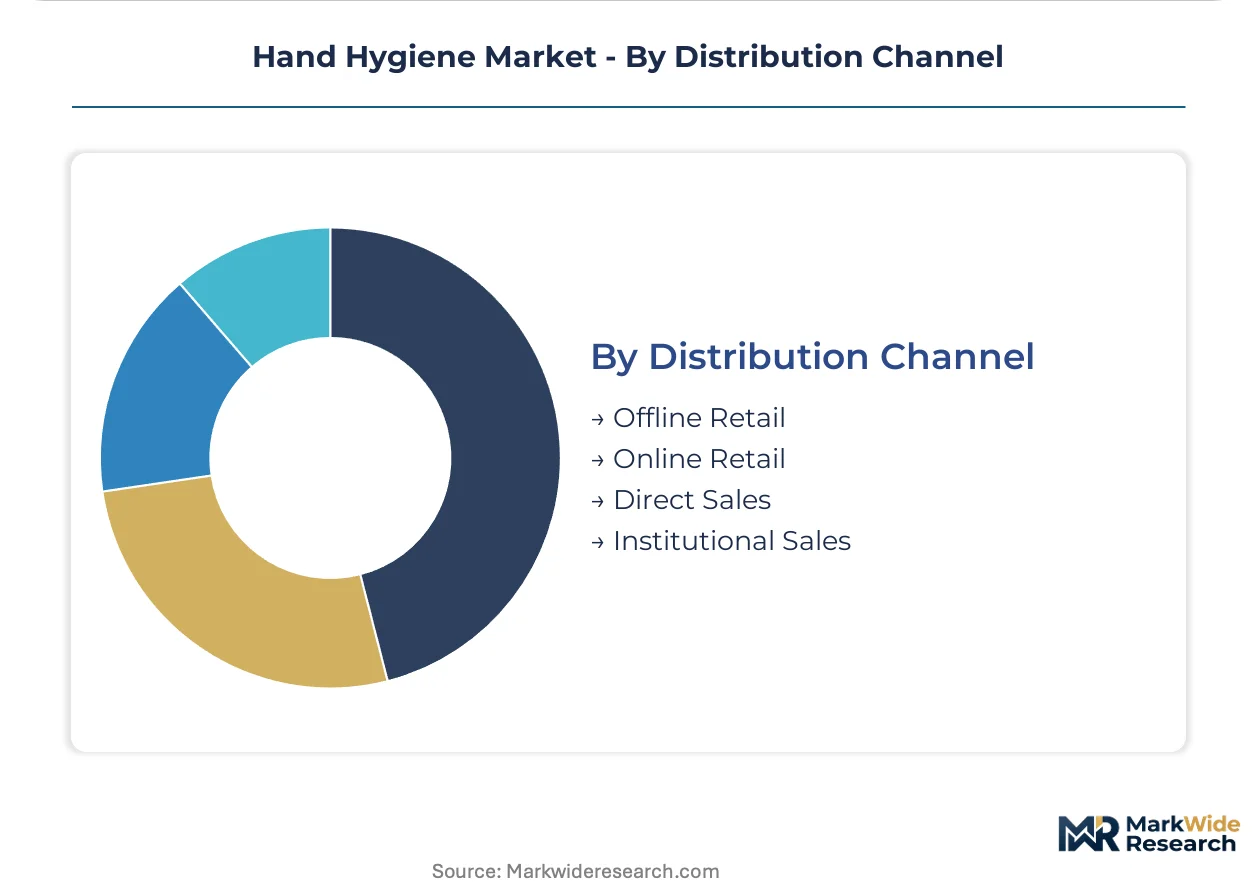
Distribution Channel:
Customer type and purchase scale determine channel selection, with institutional buyers bypassing retail intermediaries entirely.
- Institutional Sales:Direct contracting with group purchasing organizations and integrated delivery networks captures multi-year agreements bundling product supply with compliance infrastructure. Ecolab and GOJO Industries dominate through captive dispenser ecosystems and service technician deployment.
- Direct Sales:Manufacturer field forces serve mid-sized healthcare systems and regional food-service chains requiring customized formulation or private-label programs.
- Offline Retail:Mass-market gels and foams move through pharmacy, grocery, and club channels where shelf placement fees and promotional spending determine visibility.
- Online Retail:E-commerce penetration concentrates in bulk purchasing for small businesses and subscription replenishment for residential users, with Amazon and specialized medical supply platforms capturing traffic.
Margin pools concentrate in Institutional Sales. Digital migration is gaining share fastest in Online Retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Midwestern ethanol processing clusters anchor North American supply security for alcohol-based formulations, while regulatory divergence across major economies is fragmenting formulation standards and reshaping export compliance investments.
United States
CMS reimbursement penalties for hospital-acquired infections accelerate procurement of sensor-integrated dispensing systems across acute-care networks. FDA monograph requirements govern over-the-counter antiseptic active ingredients and labeling claims for all domestic manufacturers. Corn-belt processing facilities in Iowa and Illinois secure captive ethanol feedstock for domestic sanitizer production at scale.
Germany
REACH biocidal restrictions and EU Green Deal frameworks compel manufacturers to reformulate with sustainable actives, creating first-mover advantages for compliant exporters. ECHA regulatory thresholds for emerging actives require accelerated testing budgets and extended registration timelines. Industrial chemical clusters along the Rhine-Ruhr corridor concentrate reformulation R&D investments for European healthcare procurement.
India
Ayushman Bharat health coverage extends hygiene protocols to tier-2 and tier-3 clinic networks previously underserved by institutional suppliers. CDSCO and BIS standards govern antiseptic quality specifications for domestic and imported products. Pharmaceutical manufacturing zones in Maharashtra and Gujarat attract joint-venture investments for localized sanitizer production serving South Asian markets.
Saudi Arabia
Healthcare privatization under Vision 2030 opens tender opportunities for joint-venture manufacturing within the Kingdom. SFDA localization requirements mandate domestic production partnerships for institutional procurement eligibility. Medical city developments in Riyadh and the Eastern Province anchor demand concentration for compliance-integrated hygiene programs.
Japan
Aging demographics and infection control protocols in long-term care facilities sustain premium demand for skin-sensitive formulations. PMDA and METI frameworks regulate antiseptic efficacy claims and medical device classifications for automated dispensers. Osaka-based chemical specialists supply quaternary ammonium compounds for neonatal and pediatric product lines.
Hand Hygiene Market Competitive Environment
Capacity expansion dominates the current landscape as manufacturers retrofit lines for benzalkonium chloride and hypochlorous acid alternatives. The vendor base separates into three tiers: multinational chemical conglomerates with captive raw material positions, specialized hygiene service providers bundling hardware with compliance analytics, and regional contract manufacturers competing on ethanol conversion economics. Strategic archetypes include integrated program vendors, commodity alcohol suppliers, and pediatric formulation specialists. Vertical integration into dispenser hardware and geographic expansion through joint-venture localization represent the dominant competitive moves.
Within the integrated service tier, Ecolab and GOJO Industries exemplify archetypes combining product supply with compliance infrastructure deployment. Reckitt Benckiser Group occupies a position representing mass-market brand leverage through retail shelf presence. These three anchors demonstrate how competitive positioning stratifies between institutional contract bundling, consumer brand recognition, and specialized formulation expertise.
| Leading Market Players |
|---|
| GOJO Industries |
| Reckitt Benckiser Group |
| The Procter & Gamble Company |
| 3M Company |
| Henkel |
| Unilever |
| Vi-Jon Laboratories |
| The Clorox Company |
| Ecolab |
| Others |
Value Chain & Pricing Dynamics
Joint Commission compliance mandates for touch-free dispensing systems are compressing procurement cycles across US acute-care networks, forcing suppliers to absorb hardware retrofit costs into long-term service contracts and compressing margins on commodity alcohol formulations.
Pricing Analysis
Ethanol and isopropanol feedstock swings pass through to finished-product pricing within one to two quarters, with corn-belt ethanol processors capturing margin during propylene volatility. Three-tier pricing structure across premium compliance-integrated programs, standard institutional contracts, and economy retail SKUs reflects bundling depth and certification grade. Price differentiation hinges on EPA registration tier and real-time monitoring capability. Cost compression in mid-tier contract manufacturing is intensifying because propylene feedstock instability squeezes isopropanol-dependent producers. Quick-service food chains and tier-3 clinic networks exhibit highest price sensitivity, while integrated delivery networks prioritize total cost of ownership over unit pricing.
Supply Chain Analysis
FDA monograph compliance and EPA registration requirements gate supplier eligibility for institutional procurement, extending qualification timelines and concentrating approved vendor pools. Manufacturing capacity clusters in the United States, Germany, and India, with corn-belt ethanol processing anchoring North American feedstock security. Formulation draws from ethanol, isopropanol, and quaternary ammonium compound inputs, with benzalkonium chloride sourcing increasingly tethered to Indian pharmaceutical chemical specialists. Single-source vulnerability runs through Midwest ethanol processing clusters exposed to agricultural yield variability. Distribution runs through group purchasing organization contracts that bypass retail intermediaries for healthcare and food-service accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Divergent regulatory timelines between FDA monograph finalization and EU REACH biocidal restrictions create geographic-arbitrage opportunities for manufacturers with dual-registration capabilities, as compliance investments in one jurisdiction yield protected pricing power in the other.
For Market Incumbents: Anchor market position through captive dispenser hardware ecosystems and backward integration into ethanol processing. UV-C and hydrogen peroxide vapor systems threaten high-risk procedure budgets in surgical suites, demanding defensive R&D into sensor-integrated compliance platforms. Capacity addition in Maharashtra and Gujarat pharmaceutical zones secures cost advantages for South Asian market penetration.
For New Entrants and Emerging Players: Begin with tier-2 and tier-3 clinic networks under India's Ayushman Bharat coverage expansion, where institutional supplier penetration remains shallow. Pediatric and neonatal care units in US children's hospitals offer white-space demand for hypochlorous acid alternatives. Direct contracting with regional food-service chains bypasses GPO vendor roster compression.
For Investors and Strategic Acquirers: Asymmetric upside sits with specialized hygiene service providers bundling IoT-enabled compliance analytics with product supply. Long-term viability favors vendors with integrated program architectures over commodity alcohol converters. Watch for FDA benzalkonium chloride monograph finalization as inflection signal for alternative active investments.
| Strategic Initiative | Industry Significance |
|---|---|
| IoT-Enabled Compliance Platform Development | Sensor-integrated dispensers capture real-time adherence data for Joint Commission reporting requirements. |
| Joint Venture Localization | SFDA manufacturing partnerships unlock tender eligibility for Saudi healthcare privatization projects. |
| Sustainable Active Reformulation | REACH-compliant biocidal alternatives secure EU Green Deal procurement preference in German hospital networks. |
| Backward Integration into Ethanol Processing | Corn-belt captive feedstock insulates margin structures from isopropanol price volatility cycles. |
| Pediatric Formulation Specialization | Hypochlorous acid products penetrate neonatal care units where alcohol bases face sensitivity exclusions. |
Study Parameters
Multiple input streams — regulatory filing databases, hospital procurement contract records, and chemical manufacturing capacity registries — were reconciled through structured primary interviews with infection control officers, GPO contracts managers, formulation R&D directors, and ethanol processing plant operators, validated against FDA monograph dockets, EPA registration databases, ECHA biocidal substance inventories, and customs trade flow data, with bottom-up facility-level capacity assessments triangulated against top-down demand modeling.
Data-stream reconciliation across product type, formulation chemistry, end-user vertical, and distribution channel dimensions supported CAGR derivation through trend extrapolation and elasticity-adjusted scenario weighting, with ethanol feedstock cost curves and REACH regulatory compliance timelines incorporated as industry-specific forecast inputs across the projection horizon.
Caveats apply where FDA benzalkonium chloride efficacy rule finalization or EU biocidal active substance approval delays could materially shift the outlook, as forecasts reflect assumptions on regulatory timeline adherence and feedstock cost stability. Deviation in propylene-ethanol price spreads or Joint Commission digital compliance mandate acceleration would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Infection Control
Community Acquired Pneumonia (CAP) Market
Infection Control
Infection Control Surveillance Solutions Market
Infection Control
Ear Infection Treatment Market
Infection Control
Air Sanitizer Market
Infection Control
Antiseptic Bathing Market
Infection Control
Blood Stream Infection Testing Market
Infection Control
Catheter-Related Bloodstream Infections (Crbsis) Market
Infection Control
Disinfection Equipment Market
Infection Control
Sterility Indicators Market
Infection Control
Global Sepsis Therapeutics Market
Infection Control
Healthcare Protective Masks Market
Infection Control
Global Wall Mounted Ozone Disinfection Machine Market
Infection Control
Salivary Gland Infection Market
Infection Control
Surgical Site Infections Market
Infection Control
Asia-Pacific Hand Sanitizer Market
Infection Control
Hospital Acquired Infections Market