
 Air Sanitizer Market | 2026-2036
Air Sanitizer Market Size, Share, and Industry Trends Forecast 2026-2036
Air Sanitizer Market Analytics
Specialized HVAC engineering talent is redrawing competitive boundaries across the air sanitizer industry. Daikin Industries leverages captive compressor and filtration R&D to sustain integrated product pipelines. Sharp Corporation anchors East Asian supply through proprietary plasma cluster ion technology. Dyson competes on design-led consumer positioning in premium residential channels.
Air sanitizers are electromechanical devices that reduce airborne pathogens and particulate matter through filtration, ultraviolet germicidal irradiation, or ionization, typically achieving CADR ratings between 100-400 cubic feet per minute for residential units. HEPA filtration dominates commercial and healthcare procurement due to established efficacy documentation and lower ozone emission profiles. Photocatalytic oxidation is gaining traction in educational settings where continuous operation without occupancy restrictions matters. Residential demand flows primarily through online retail, though specialty stores retain margin advantages in premium segments.
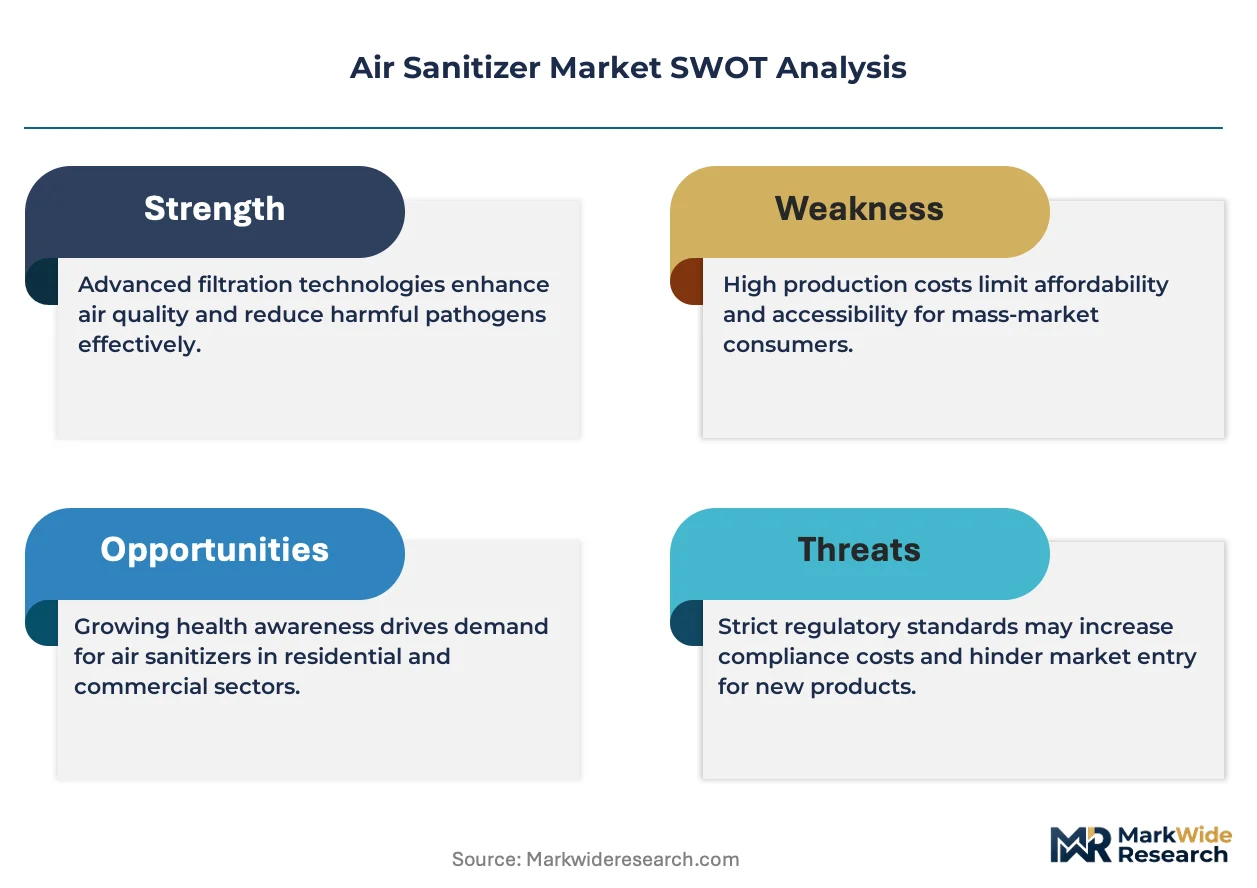
FDA device classification for UV-based medical air sanitizers and EPA registration requirements for antimicrobial claims constrain market entry timelines and compliance costs. California Air Resources Board ozone emission limits and EU CE marking under the MDR framework further shape product design specifications. Stakeholders must monitor evolving state-level ventilation mandates and building code integrations that could accelerate replacement cycles or create specification lock-ins.
Market Dynamics
Healthcare procurement consolidation is compressing vendor margins while accelerating specification standardization around UV-C and HEPA performance thresholds. FDA device classification timelines and EPA antimicrobial claim registrations now function as de facto market gates, favoring incumbents with established compliance infrastructure over new entrants.
Growth Catalysts
- Updated FDA indoor air quality guidance:Healthcare facilities in the United States are expanding capital budgets for certified UV-C systems under revised medical device protocols.
- Photocatalytic oxidation:Educational institutions are specifying continuous-operation systems that function without occupancy restrictions, bypassing traditional ozone emission constraints.
- South Korean manufacturing clusters:Concentrated compressor and filtration R&D capacity near Seoul enables rapid prototype-to-production cycles for integrated HVAC-sanitizer units.
Market Restraints
- California Air Resources Board ozone limits:Stringent emission caps force redesign of ionization-based products, extending development timelines by 12-18 months for non-compliant architectures.
- East Asian supply concentration:Sharp Corporation and Daikin Industries control proprietary plasma cluster and captive compressor technologies, creating input dependency for second-tier assemblers.
- HEPA filtration substitution pressure:Lower-cost MERV-13 alternatives are capturing specification share in commercial retrofits where absolute pathogen elimination is not mandated.
Strategic Opportunities
- EU CE marking under MDR framework:Medical-grade air sanitizer certification creates premium positioning for systems that bridge healthcare and high-end residential channels.
- Online retail channel expansion:Direct-to-consumer platforms are disintermediating specialty stores in residential segments, enabling margin capture previously lost to distributor networks.
- Convergence of IoT sensors and UV-C dosing:Real-time air quality feedback loops enable dynamic irradiation intensity, reducing energy consumption while maintaining efficacy documentation.
Industry Challenges
- Specialized HVAC engineering scarcity:Integrated system design requires rare cross-functional expertise spanning fluid dynamics, microbiology, and electromechanical controls.
- Legacy building infrastructure incompatibility:Retrofit installations face ductwork modification costs and electrical capacity constraints in structures predating 1990 construction codes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Air Sanitizer Market |
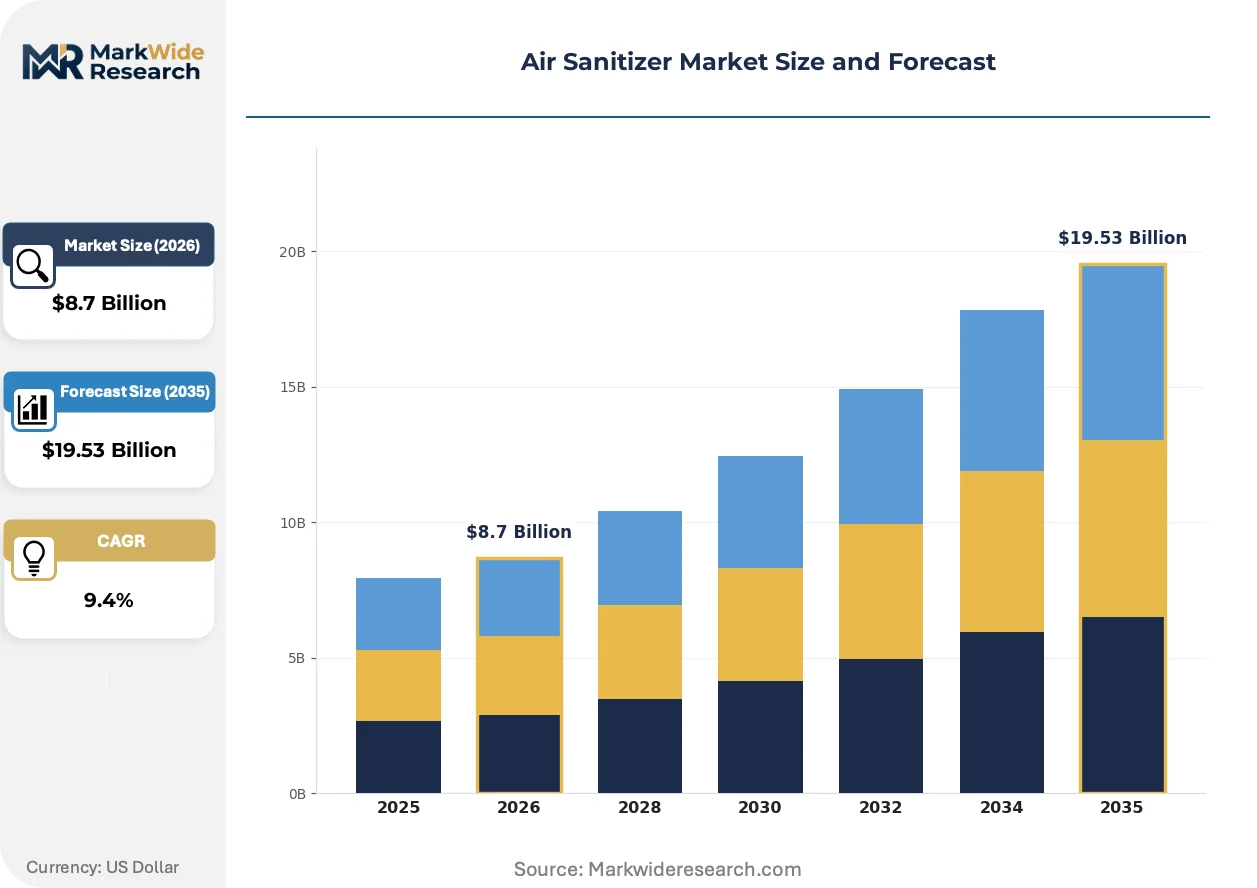
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: UV Light, Ionizers, HEPA Filters, Activated Carbon End User: Residential, Commercial, Healthcare, Educational Technology: Photocatalytic Oxidation, Ozone Generators, Electrostatic Precipitators, Chemical Disinfectants Distribution Channel: Online Retail, Direct Sales, Wholesalers, Specialty Stores |
| Companies Covered | Honeywell International Inc., 3M Company, Philips Electronics, Dyson, Blueair, Coway, Daikin Industries Ltd., Sharp Corporation, Pure Environments, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Air Sanitizer Market Evolving Landscape
Photocatalytic oxidation architectures are reshaping competitive positioning by enabling continuous operation without occupancy-based safety interlocks. Three distinct vectors are compressing traditional technology lifecycles and redrawing procurement criteria across end-use verticals.
Photocatalytic oxidation systems utilizing titanium dioxide-coated substrates activated by UV-A LEDs are supplanting mercury-vapor UV-C lamps in educational and hospitality deployments. School districts in the United States specify these systems for 24/7 corridor operation where mercury breakage protocols complicate maintenance. The technology is compressing total cost-of-ownership calculations by eliminating lamp replacement cycles and enabling simpler fixture integration.
REACH chemical substance restrictions and EU F-Gas Regulation phase-down schedules are forcing refrigerant-dependent integrated HVAC-sanitizer systems toward hydrofluoroolefin alternatives. Equipment manufacturers serving European commercial markets are redesigning heat pump coils and compressor packages to accommodate lower-global-warming-potential working fluids. Medical-grade installations face additional MDR documentation burdens that extend certification timelines but create defensible specification lock-in for compliant suppliers.
Building operators are consolidating facility-wide air quality contracts under single-source performance agreements rather than equipment ownership models. Corporate real estate departments in Japan and Germany favor subscription-based maintenance and efficacy guarantees over capital purchase decisions. This pattern is most pronounced in multi-site healthcare networks and university campus systems where standardization across disparate building vintages reduces operational complexity.
Air Sanitizer Market Segmentation
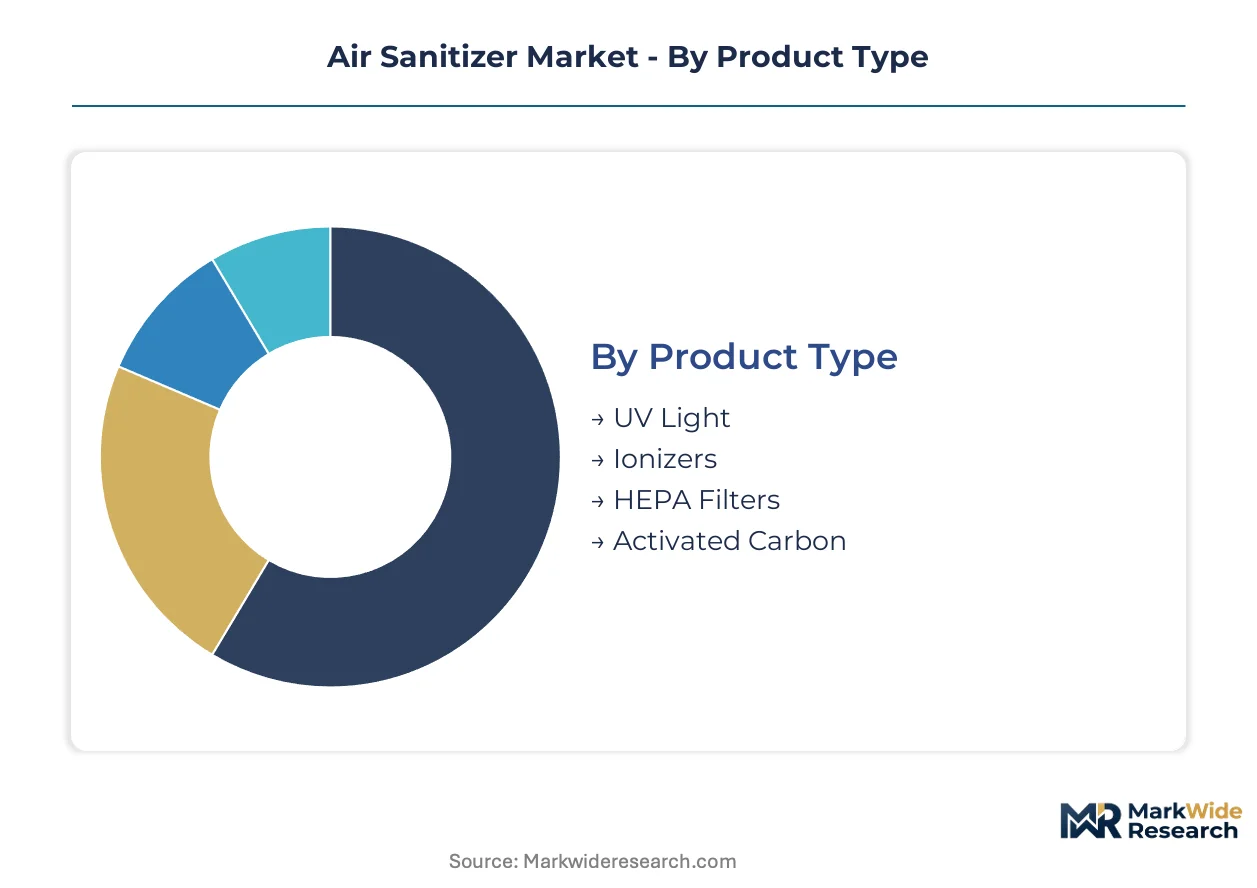
Air sanitizer procurement patterns diverge sharply across product architectures and end-use environments. FDA device classifications for UV-based medical systems and EPA antimicrobial claim registrations create distinct compliance tiers that reshape vendor strategies and margin structures across each segment boundary.
Product Type:
FDA and EPA regulatory frameworks impose divergent certification burdens on each product architecture, compressing timelines for compliant entrants while locking in specification advantages for incumbents with established testing infrastructure.
- HEPA Filters:Mechanical filtration media rated H13-H14 under EN 1822 standards capture 99.95% of 0.3-micron particles. United States healthcare procurement under FDA enforcement discretion letters concentrates demand here, though California Air Resources Board ozone limits further reinforce HEPA preference over ionization alternatives in commercial retrofits.
- UV Light:Germicidal irradiation at 254 nanometers disrupts pathogen DNA. FDA 510(k) clearance requirements for medical device classification extend development cycles but create defensible positioning in hospital surgical suites and pharmaceutical cleanrooms where efficacy documentation is mandatory.
- Ionizers:Bipolar ionization systems face CARB emission caps that force architectural redesigns.
- Activated Carbon:Adsorption-based VOC removal serves hospitality and residential odor control applications.
HEPA Filters handle the majority of throughput; UV Light is expanding most quickly on share as medical-grade certification requirements harden.
End User:
Cost tier differentiation separates capital-intensive healthcare installations from price-sensitive residential purchases, with commercial and educational segments occupying intermediate positions on specification flexibility and contract duration.
- Healthcare:Acute care facilities and outpatient surgical centers demand continuous air changes per hour with documented pathogen reduction. United States hospital procurement under Joint Commission standards favors UV-C and HEPA systems with FDA 510(k) or EPA establishment registration, locking out uncertified alternatives regardless of price positioning.
- Commercial:Corporate real estate and retail chains prioritize total cost of ownership over upfront capital expenditure. Japanese and German facility managers increasingly specify subscription-based performance contracts rather than equipment ownership, consolidating vendor relationships under single-source agreements.
- Residential:Online retail channels dominate volume, with CADR-per-dollar metrics driving purchase decisions.
- Educational:K-12 districts and university systems specify photocatalytic oxidation for corridor operation without occupancy restrictions.
Healthcare commands the highest specification bar; Educational is climbing the fastest as federal infrastructure funding reaches district ventilation upgrades.
Technology:
Volume concentration favors established electromechanical approaches, while emerging photocatalytic architectures displace legacy mercury-vapor systems in continuous-operation environments.
- Photocatalytic Oxidation:Titanium dioxide-coated substrates activated by UV-A LEDs enable 24/7 operation without mercury breakage protocols. United States school districts specify these systems for hallway and common area deployment, compressing maintenance costs and eliminating lamp replacement cycles that complicate facility staffing.
- Ozone Generators:High-concentration systems face regulatory headwinds from CARB and EPA indoor air quality guidance, restricting deployment to unoccupied industrial sanitization.
- Electrostatic Precipitators:Collection plate designs serve commercial kitchen and manufacturing environments with high particulate loads.
- Chemical Disinfectants:Vapor-phase hydrogen peroxide and chlorine dioxide systems occupy niche medical sterilization applications.
Photocatalytic Oxidation is the fastest mover on share; Electrostatic Precipitators retain volume concentration in heavy-industrial exhaust treatment.
Distribution Channel:
Margin structure separates direct contractual relationships in healthcare from high-volume, low-touch residential e-commerce, with specialty retail retaining positioning power in premium consumer segments.
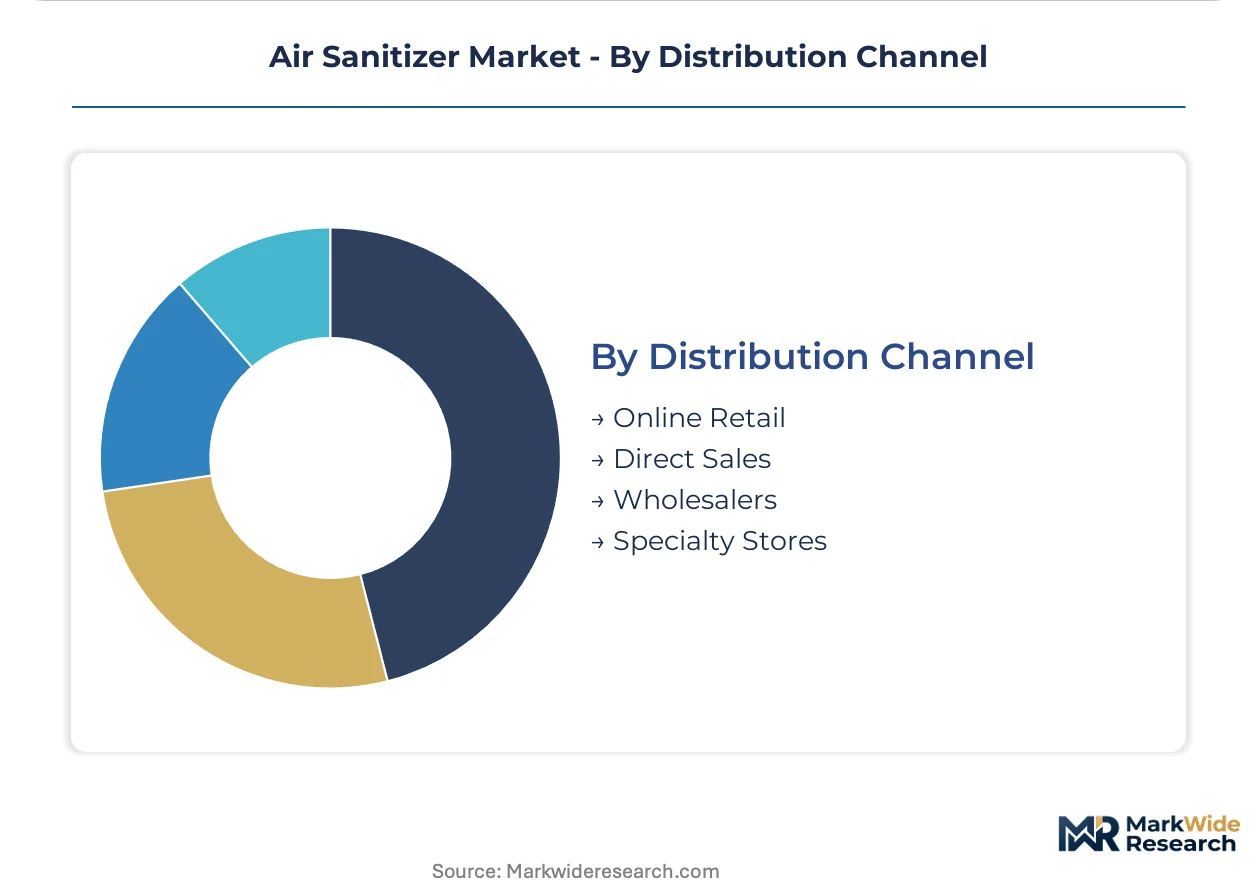
- Direct Sales:Healthcare networks and corporate real estate departments negotiate multi-site performance agreements with efficacy guarantees. Japanese university systems and German hospital chains favor this channel for standardization across disparate building vintages, consolidating maintenance under single-source vendor relationships.
- Online Retail:Amazon and direct-to-consumer platforms disintermediate distributor networks in residential segments, enabling margin capture previously lost to specialty store markups.
- Specialty Stores:Premium positioning persists in affluent residential markets where in-person demonstration drives purchase decisions.
- Wholesalers:HVAC contractor channels serve commercial retrofit markets with integrated system specifications.
Direct Sales handles the majority of healthcare and commercial throughput; Online Retail is expanding most quickly as residential purchase behavior shifts permanently to e-commerce.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Japanese and German manufacturing clusters where captive R&D infrastructure commands premium positioning, while Chinese and Mexican assembly operations compete on compressed margins for standardized filtration components.
United States
Healthcare procurement under FDA enforcement discretion letters drives UV-C and HEPA specification upgrades in acute care facilities. EPA antimicrobial claim registrations function as de facto market gates for commercial entrants. The Boston-Cambridge corridor anchors medical-grade device development, with Massachusetts General Hospital procurement standards diffusing across New England hospital networks.
Germany
Corporate real estate departments favor subscription-based performance contracts over equipment ownership, consolidating vendor relationships under single-source agreements. EU F-Gas Regulation phase-down schedules force refrigerant-dependent integrated HVAC-sanitizer systems toward hydrofluoroolefin alternatives. The Rhine-Ruhr industrial belt concentrates engineering talent for building automation integration.
Japan
Daikin Industries and Sharp Corporation maintain concentrated production capacity for proprietary plasma cluster and captive compressor technologies. METI efficiency standards for commercial buildings accelerate replacement cycles in Tokyo and Osaka metropolitan areas. The Nagoya-Chubu corridor hosts integrated system manufacturing for export markets.
South Korea
Seoul Capital Area manufacturing clusters enable rapid prototype-to-production cycles for integrated HVAC-sanitizer units. MFDS medical device classification creates compliance infrastructure advantages for domestic suppliers serving hospital procurement. Busan-Ulsan shipbuilding and petrochemical complexes drive industrial air treatment demand.
China
Domestic online retail channels dominate residential volume, with CADR-per-dollar metrics driving purchase decisions on Alibaba and JD.com platforms. NMPA medical device registration timelines extend for foreign manufacturers, favoring local assembly operations. The Yangtze River Delta concentrates contract manufacturing for export-bound HEPA filtration media.
Air Sanitizer Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the air sanitizer industry. The market structure fragments across three tiers: integrated HVAC conglomerates with captive R&D, specialized filtration engineering houses, and consumer-facing appliance brands. Two strategic archetypes dominate competitive positioning: electromechanical systems specialists and design-led consumer positioning firms. Capacity expansion in East Asian manufacturing clusters and technology licensing agreements for photocatalytic oxidation architectures represent the dominant competitive moves reshaping supply-side dynamics.
Among diversified industrial conglomerates, Honeywell International Inc. and 3M Company exemplify the integrated systems archetype, while Daikin Industries Ltd. and Sharp Corporation anchor East Asian supply concentration through proprietary technology positions. Dyson occupies a position within the design-premium consumer tier, competing on residential channel positioning rather than healthcare certification infrastructure.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| 3M Company |
| Philips Electronics |
| Dyson |
| Blueair |
| Coway |
| Daikin Industries Ltd. |
| Sharp Corporation |
| Pure Environments |
| Others |
Value Network & Pricing Analysis
Sixty-to-ninety-day lead times for HEPA filtration media and UV-C lamp assemblies concentrate pricing power with Japanese and South Korean suppliers who maintain captive compressor and plasma cluster ion R&D infrastructure. Inventory buffers at Daikin Industries and Sharp Corporation facilities insulate premium-tier pricing from spot-market volatility, while second-tier assemblers absorb margin compression from California Air Resources Board compliance redesigns.
Pricing Analysis
Japanese-manufactured UV-C medical systems command 40-60% premiums over Chinese-assembled residential units due to FDA 510(k) certification documentation and METI efficiency compliance. Three-tier pricing structure across premium certified-medical, standard commercial, and economy residential levels separates procurement budgets. Cost compression in the residential tier intensifies because Alibaba and JD.com platforms transparentize CADR-per-dollar comparisons. Healthcare networks exhibit lowest price sensitivity due to Joint Commission mandates, while K-12 districts face acute budget constraints.
Supply Chain Analysis
Just-in-time inventory strategies dominate HEPA media procurement, whereas UV-C LED chip sourcing requires strategic stockpiling against semiconductor foundry allocation cycles. Manufacturing concentrates in Japan, South Korea, and China, with the Nagoya-Chubu corridor and Seoul Capital Area anchoring integrated HVAC-sanitizer assembly. Raw material flows draw from titanium dioxide substrate suppliers in the Yangtze River Delta, mercury-vapor lamp foundries in Guangdong, and rare-earth phosphor processors in Jiangxi. Single-source vulnerability concentrates in plasma cluster ion generator modules controlled by Sharp Corporation. Distribution runs through direct sales for healthcare networks, online retail for residential volume, and HVAC contractor channels for commercial retrofits.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cross-functional expertise spanning fluid dynamics, microbiology, and electromechanical controls remains scarcer than production capacity, constraining integrated system design and locking incumbents into talent-retention bidding wars.
For Market Incumbents: Fortify compliance infrastructure against EPA antimicrobial claim registration backlogs that favor established testing protocols. Deepen backward integration into titanium dioxide substrate production to bypass REACH chemical substance restriction delays. Capture channel control through subscription-based performance contracts that displace equipment ownership models in German and Japanese corporate real estate departments. For New Entrants and Emerging Players: FDA 510(k) fast-track pathways for UV-C medical devices open white-space positioning in outpatient surgical centers underserved by Honeywell and 3M healthcare divisions. Target educational institution procurement where photocatalytic oxidation specifications bypass mercury breakage protocol complications. Pursue go-to-market partnerships with HVAC contractors in the US commercial retrofit segment where legacy building infrastructure creates installation-service bundling opportunities. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-capture play because FDA and EPA certification timelines function as de facto market gates that compound incumbent advantages across replacement cycles. Acquisition focus centers on specialized filtration engineering houses with established 510(k) submission track records and captive relationships with Massachusetts General Hospital-tier procurement committees. Monitor state-level ventilation mandate adoption as the inflection signal—accelerated building code integration would compress replacement cycles and expand addressable market boundaries.| Strategic Initiative | Industry Significance |
|---|---|
| Photocatalytic Oxidation Technology Licensing | Enables 24/7 corridor operation without mercury breakage protocols in US school districts. |
| CE Marking Pathway Under MDR Framework | Creates premium positioning bridging healthcare and high-end residential channels in EU markets. |
| Hospital System Partnership | Locks in multi-site standardization under Joint Commission-compliant performance agreements. |
| IoT Sensor Integration Development | Supports dynamic UV-C dosing with real-time air quality feedback loops for energy reduction. |
| Backward Integration into HEPA Media Production | Secures supply against EN 1822 certification bottlenecks and CARB ozone limit redesign cycles. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA 510(k) clearance databases, EPA establishment registration records, and EU MDR technical documentation files. Interviews with hospital procurement managers, biomedical engineers, HVAC contractor operations heads, and GPO contracts managers informed demand-side segmentation. Bottom-up unit shipment estimates triangulated against top-down healthcare capital expenditure flows and residential e-commerce transaction data from Alibaba and JD.com platform disclosures.
Segmentation dimensions modeled include product architecture, end-use environment, technology type, and distribution channel across the projection horizon. CAGRs derived from regression analysis of historical procurement cycles correlated with regulatory milestone dates and infrastructure funding disbursement patterns. Forecast inputs incorporate Joint Commission standard revision schedules, EU F-Gas Regulation phase-down compliance timelines, and METI commercial building efficiency mandate adoption curves.
Underlying assumptions cover continued FDA enforcement discretion for UV-C medical device classification, with deviation risk concentrated in California Air Resources Board ozone emission limit tightening or NMPA medical device registration timeline extensions for foreign manufacturers. Revision becomes warranted when federal infrastructure funding for K-12 ventilation upgrades crosses appropriation thresholds that accelerate educational segment procurement velocity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Infection Control
Healthcare Protective Masks Market
Infection Control
Global Skin Antiseptic Products Market
Infection Control
Antiseptic Bathing Market
Infection Control
Biological and Chemical Indicators Market
Infection Control
North America Hand Sanitizer Market
Infection Control
Antimicrobial Catheters Market
Infection Control
Ultraviolet Germicidal Irradiation Market
Infection Control
Global Prophylactic Human Vaccine Market
Infection Control
Healthcare Associated Infections (HAI) Treatment Market
Infection Control
Salivary Gland Infection Market
Infection Control
Sterilization Monitoring Market
Infection Control
Disinfection Equipment Market
Infection Control
Preventable Vaccines Market
Infection Control
Global Wall Mounted Ozone Disinfection Machine Market
Infection Control
Global Disease Control and Prevention Vaccine Market
Infection Control
Global Viral Clearance Services Market