
 Global Disinfection Robots Market | 2026-2036
Global Disinfection Robots Market Size, Share, and Industry Trends Forecast 2026-2036
Global Disinfection Robots Market Foresight
CE marking under the EU Medical Device Regulation is bifurcating vendor access across European healthcare procurement channels. Blue Ocean Robotics leverages its extensive UVD Robots installation base to anchor large hospital contracts in Scandinavia and Central Europe. Xenex Disinfection Services differentiates through pulsed xenon UV technology that sustains premium positioning in U.S. academic medical centers. TMiRob Technology competes on manufacturing scale from its Shenzhen operations, extending cost advantages across Asia-Pacific public hospital tenders.
Disinfection robots are mobile or stationary automated systems engineered to deliver antimicrobial agents—UV-C irradiation, hydrogen peroxide vapor, or electrostatically charged disinfectants—onto surfaces and airborne environments with programmable dose control and spatial mapping. These systems execute pathogen reduction cycles in settings where manual cleaning introduces human error, inconsistency, or occupational exposure risk. UV light robots occupy the dominant product category due to faster cycle completion and lower consumable dependency versus vapor-based alternatives. Autonomous deployment mode is attracting the fastest growth as LiDAR navigation and AI-driven obstacle recognition reduce supervision labor in hospital corridors and food processing lines. Electrostatic sprayers retain niche strength in commercial offices where rapid turnaround between occupancy periods governs operational economics.
FDA 510(k) clearance timelines and EPA establishment registration requirements shape U.S. market entry pathways for disinfection robot vendors, while EMA notified body oversight under MDR governs European commercialization. China's NMPA medical device classification and GB standard compliance for electromagnetic safety add further gating layers for foreign manufacturers seeking hospital procurement eligibility. Stakeholders must monitor how evolving ISO 13485 quality management expectations and country-specific infection control procurement mandates reshape competitive qualification thresholds and capital deployment priorities across target geographies.
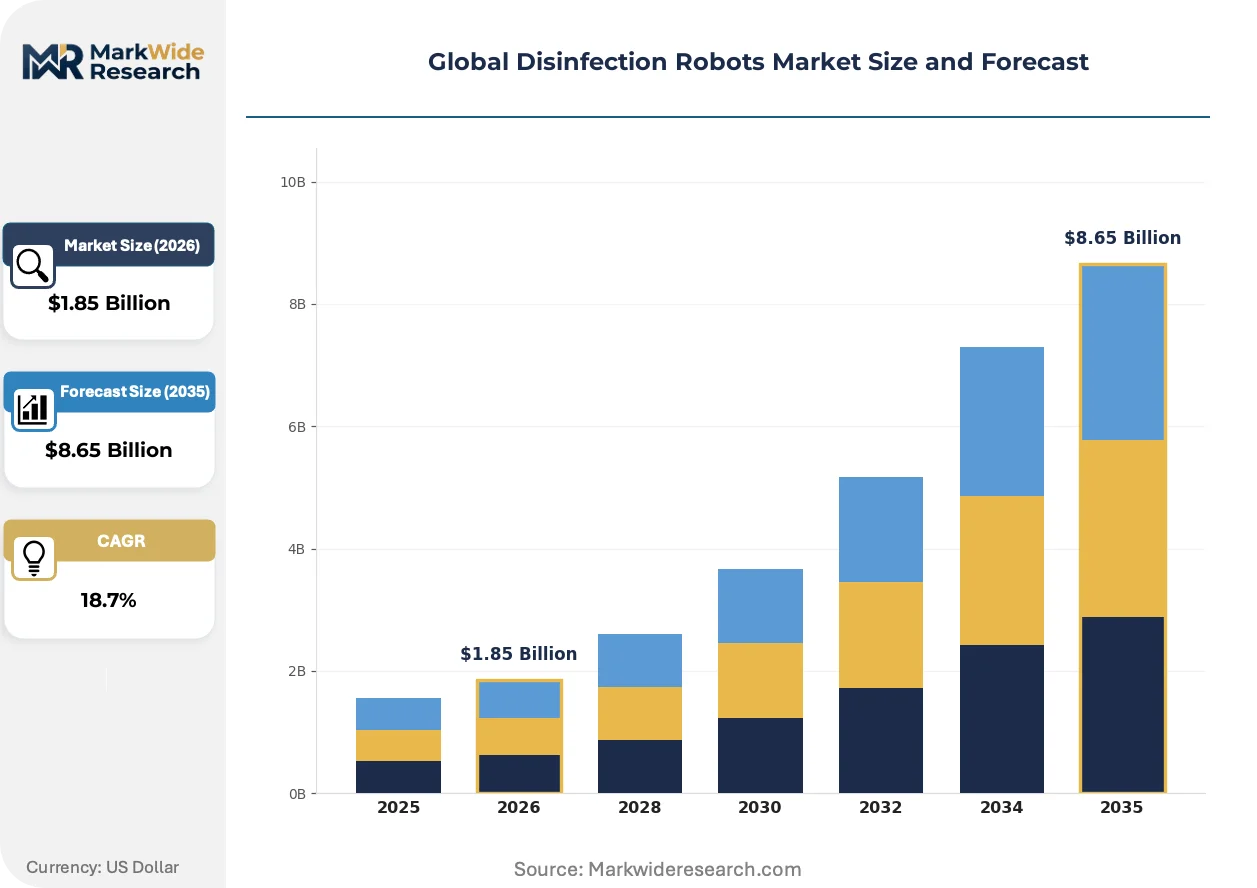
Market Dynamics
Autonomous navigation capabilities are compressing deployment labor requirements and redefing competitive differentiation among disinfection robot vendors as hospitals prioritize unsupervised corridor operation.
Growth Catalysts
- Hospital-acquired infection mandates:CMS reimbursement penalties for preventable infections are accelerating autonomous UV-C adoption in U.S. acute care facilities.
- EU Medical Device Regulation:CE marking under MDR is creating procurement qualification barriers that favor established vendors with notified body relationships.
- LiDAR sensor cost curves:Cheaper solid-state navigation modules are enabling mid-tier hospital systems to access autonomous disinfection previously limited to academic medical centers.
Market Restraints
- Xenon lamp supply concentration:Pulsed UV source manufacturing clusters in Germany and Japan create single-source vulnerability for premium robot configurations.
- FDA 510(k) timeline extension:Enhanced FDA scrutiny of UV-C dose validation protocols is stretching U.S. market entry cycles to 18-24 months.
- Manual cleaning labor arbitrage:Low-wage janitorial contracts in emerging market hospitals sustain cost advantages over capital-intensive robotic systems.
Strategic Opportunities
- Food processing integration:USDA-inspected meat and poultry plants represent an underpenetrated vertical where overnight robotic cycles align with sanitation windows.
- India hospital infrastructure:National health mission procurement tenders under Ayushman Bharat are embedding robotic disinfection into new facility construction standards.
- Electrostatic-AI convergence:Machine learning pathogen mapping combined with charged droplet delivery is opening commercial office contracts previously served by UV-only systems.
Industry Challenges
- UV-C dosimetry expertise scarcity:Hospital infection control departments lack personnel trained to validate microbial kill rates against surface geometry variations.
- Legacy building infrastructure:Older healthcare facilities with narrow corridors and non-standard door widths require costly facility modifications for robot passage.
- Multi-jurisdiction certification stacking:Vendors must sequence FDA, CE, and NMPA approvals with incompatible electromagnetic safety test protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Disinfection Robots Market |
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $8.65 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: UV Light Robots, Hydrogen Peroxide Vapor Robots, Electrostatic Sprayers, Thermal Fogging Machines, Ozone Generators Application: Hospital Sanitization, Food Processing Plants, Public Transportation, Commercial Offices, Educational Institutions End User: Healthcare Facilities, Food Manufacturers, Transit Authorities, Corporate Enterprises, Academic Campuses Deployment Mode: Autonomous, Teleoperated, Semi-Autonomous, Manual, Hybrid Systems |
| Companies Covered | Blue Ocean Robotics, Xenex Disinfection Services, Finsen Technologies, Skytron, Tru-D SmartUVC, TMiRob Technology, Bioquell, Akara Robotics, Mediland Enterprise Corp., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Disinfection Robots Market Shifts & Advancements
Disinfection robotics is experiencing a platform shift from stationary emitters to mobile autonomous systems with real-time environmental sensing and adaptive dosing algorithms.
Far-UVC technology emitting at 222 nanometers is displacing conventional 254-nanometer mercury lamp systems in occupied-space applications. Semiconductor foundries and pharmaceutical cleanrooms in Japan and South Korea are piloting these installations for continuous airborne pathogen suppression. The shorter wavelength enables human presence during operation, collapsing the throughput penalty of evacuation protocols.
EMA notified body oversight under the EU AI Act is imposing algorithmic transparency requirements on pathogen detection modules. Robot vendors must now document training data provenance and decision logic for AI-driven contamination mapping. German hospital procurement consortia are demanding these disclosures as contract prerequisites, pressuring software-centric entrants to restructure quality management systems.
Long-term service agreements bundling hardware, consumables, and outcome guarantees are replacing capital purchase models in Nordic healthcare systems. Danish and Swedish regional health authorities now specify cost-per-disinfection-cycle metrics rather than upfront equipment pricing. This restructures vendor cash flows toward recurring revenue and tightens customer retention through embedded workflow integration.
Global Disinfection Robots Market Segmentation
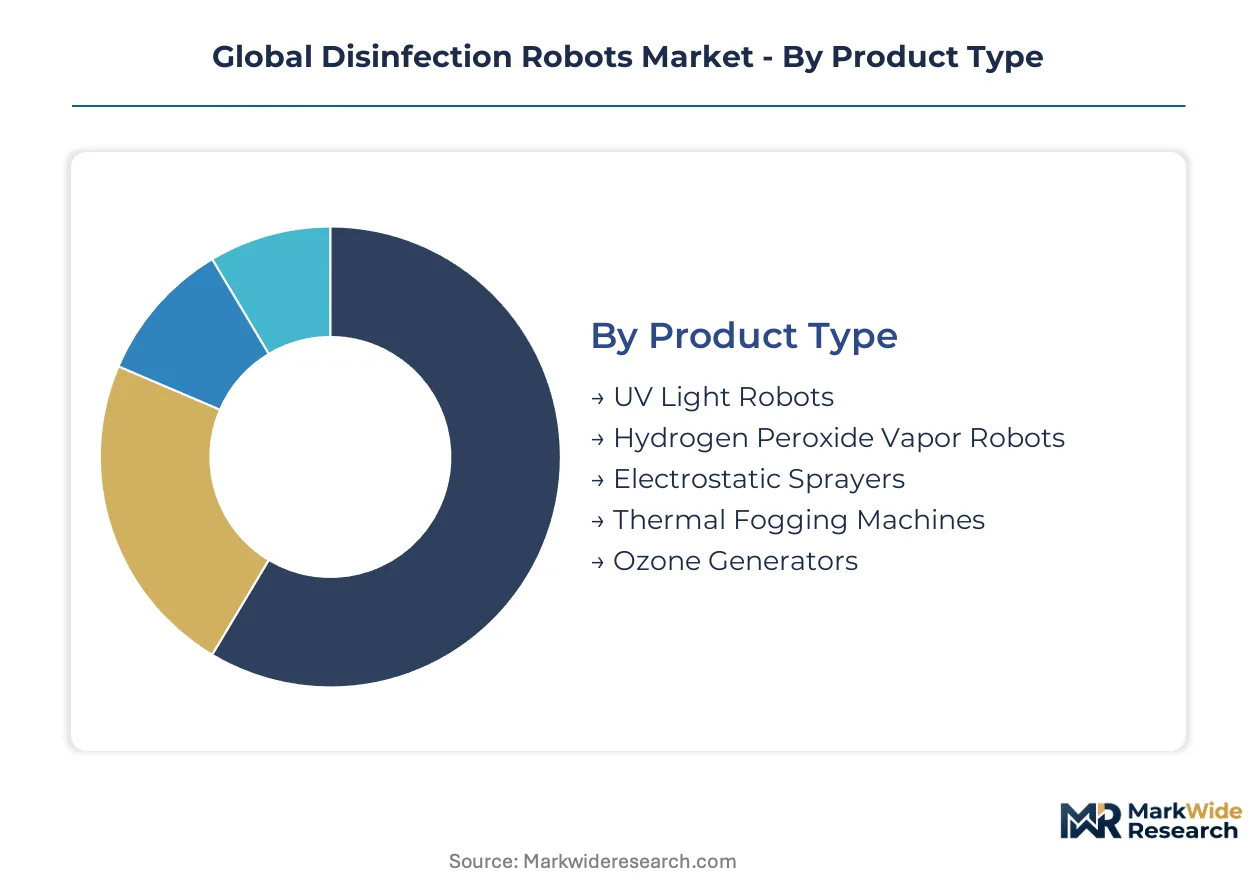
Segmentation in disinfection robotics reveals divergent technology economics across deployment settings. UV-C systems dominate hospital corridors while electrostatic platforms capture commercial office turnover demands. Procurement channel selection—direct vendor relationships versus distributor networks—varies sharply by end-user sophistication and regulatory compliance burden.
Product Type:
Channel economics favor capital-intensive UV systems through direct sales to large health systems, while lower-cost electrostatic units flow through janitorial supply distributors to commercial accounts.
- UV Light Robots:Mercury vapor or LED-based UV-C emitters delivering calibrated 254-nanometer irradiation with programmable exposure timers and shadow-mapping algorithms. German hospital procurement consortia specify these for operating theater sterilization cycles, driven by EMA MDR compliance requirements for validated microbial kill documentation.
- Hydrogen Peroxide Vapor Robots:Closed-loop vapor generation systems achieving 6-log sporicidal reduction in sealed environments through controlled humidity and concentration cycling. Pharmaceutical cleanrooms in Japan and South Korea deploy these for isolator and pass-through chamber decontamination, constrained by lengthy aeration periods that compress operational throughput.
- Electrostatic Sprayers:Charged droplet delivery systems wrapping complex geometries with disinfectant film. Commercial real estate operators in US metropolitan markets favor rapid deployment models.
- Thermal Fogging Machines:Heated aerosol generators producing sub-20-micron disinfectant particles for large-volume space treatment. Agricultural processing facilities represent primary demand clusters.
- Ozone Generators:Corona discharge or UV-photolysis systems producing triatomic oxygen for unoccupied space treatment. Water treatment and cold storage applications sustain niche adoption.
By volume, UV Light Robots lead. By growth pace, Electrostatic Sprayers are expanding most quickly.
Application:
Cost tier stratification separates premium autonomous systems in acute care from economy teleoperated units in transit maintenance depots.
- Hospital Sanitization:High-frequency terminal cleaning of patient rooms, operating suites, and intensive care units with EPA-registered sporicidal validation. US academic medical centers anchor demand, compelled by CMS reimbursement penalties for preventable healthcare-associated infections.
- Food Processing Plants:USDA-inspected sanitation of meat, poultry, and ready-to-eat production lines during mandated overnight shutdown windows. Midwest US protein processing clusters concentrate procurement volume.
- Public Transportation:Rapid-cycle disinfection of rail cars, buses, and station environments between service intervals. European transit authorities specify autonomous corridor operation.
- Commercial Offices:Post-occupancy turnover cleaning of meeting rooms and common areas. Asian-Pacific corporate campuses drive specifications for aesthetic-integrated designs.
- Educational Institutions:Seasonal deep cleaning of dormitories and athletic facilities. K-12 districts in North America represent price-sensitive volume demand.
Hospital Sanitization commands the highest unit economics. Food Processing Plants show the steepest expansion trajectory as USDA inspection protocols tighten.
End User:
Customer type determines service model attachment—healthcare demands outcome guarantees while transit authorities prioritize capital expenditure minimization.
- Healthcare Facilities:Acute care hospitals, ambulatory surgery centers, and long-term care institutions with infection control committees and capital equipment committees. Nordic regional health authorities now contract on cost-per-cycle metrics rather than equipment purchase.
- Food Manufacturers:Protein processors, dairy operations, and packaged goods producers subject to HACCP and FSMA preventive controls. Third-party sanitation contractors intermediate much of this demand.
- Transit Authorities:Municipal and regional rail and bus operators with overnight maintenance windows. Procurement flows through public tender processes with extended vendor qualification timelines.
- Corporate Enterprises:Multi-site office portfolios and facility management companies. Leasing arrangements with bundled maintenance gain traction.
- Academic Campuses:University housing and research facilities with seasonal utilization patterns. Budget cycles constrain refresh rates.
Healthcare Facilities represent the dominant revenue pool. Food Manufacturers are gaining share fastest as protein processing automation expands.
Deployment Mode:
Maturity gradients separate proven autonomous navigation from emerging hybrid architectures combining human oversight with robotic execution.
- Autonomous:LiDAR and vision-guided systems with SLAM-based mapping, obstacle avoidance, and elevator integration for unsupervised multi-floor operation. Solid-state sensor cost reductions are extending reach to mid-tier US hospital systems previously limited to academic medical centers.
- Teleoperated:Remote human control via tablet or dedicated console with real-time video feedback. Emerging market hospitals with low-wage labor arbitrage sustain this segment despite throughput limitations.
- Semi-Autonomous:Pre-mapped route execution with human-triggered cycle initiation and completion verification. European nursing homes favor this liability-mitigating intermediate.
- Manual:Human-pushed or human-carried emitters with automated dosing control. Small clinic and veterinary applications preserve this category.
- Hybrid Systems:Modular architectures permitting autonomous, teleoperated, or manual mode selection per task requirements. Japanese hospital consortia are piloting these for flexible ward configurations.
Autonomous systems lead by installed base value. Hybrid Systems are climbing the fastest as vendor platforms pursue configurability differentiation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital infrastructure modernization programs across major economies are embedding robotic disinfection into mandatory procurement specifications. National health ministries in China, Germany, Japan, the United States, and India are driving volume concentration through post-pandemic facility standards and infection control mandates.
United States
CMS reimbursement penalties for preventable healthcare-associated infections compel academic medical centers toward autonomous UV-C systems. FDA 510(k) clearance timelines now stretch to 18-24 months under enhanced dose validation scrutiny. The Midwest protein processing corridor anchors food plant sanitation demand as USDA inspection protocols tighten.
Germany
EMA notified body oversight under MDR creates procurement qualification barriers favoring established vendors with CE marking relationships. German hospital procurement consortia now specify cost-per-disinfection-cycle metrics rather than capital purchase pricing. Bavarian and Baden-Württemberg medical device clusters concentrate notified body expertise and vendor qualification infrastructure.
China
NMPA medical device classification and GB electromagnetic safety standards govern hospital procurement eligibility for foreign and domestic manufacturers alike. National health mission infrastructure spending embeds robotic disinfection into new facility construction standards. Shenzhen manufacturing scale advantages extend across Asia-Pacific public hospital tenders.
Japan
PMDA oversight and METI industrial standards shape pharmaceutical cleanroom and semiconductor foundry adoption of Far-UVC systems for continuous airborne suppression. Kansai and Kyushu industrial zones pilot 222-nanometer installations enabling human presence during operation. JIS standards compliance remains a gating factor for procurement eligibility.
India
Ayushman Bharat national health mission procurement tenders are embedding robotic disinfection into new hospital construction standards. CDSCO medical device registration requirements add compliance layers for foreign manufacturers. Maharashtra and Karnataka state health infrastructure programs concentrate initial deployment volume in western and southern hospital networks.
Global Disinfection Robots Market Competitive Landscape
Player mix skews toward technology-integrated specialists with established regulatory relationships across multiple jurisdictions. Market structure concentrates around vendors with notified body partnerships and validated microbial kill documentation. Two strategic archetypes dominate: autonomous navigation platform developers and UV source technology specialists. Competitive moves center on M&A for regulatory qualification assets and strategic partnerships for hospital system workflow integration.
Within the autonomous navigation tier, Blue Ocean Robotics and TMiRob Technology exemplify scale-driven positioning through extensive installed bases and manufacturing cost structures. Xenex Disinfection Services occupies a premium technology position through pulsed xenon UV differentiation. These three anchors represent divergent competitive vectors: Nordic direct-sales hospital contracting, Asia-Pacific public tender cost leadership, and U.S. academic medical center premium positioning.
| Leading Market Players |
|---|
| Blue Ocean Robotics |
| Xenex Disinfection Services |
| Finsen Technologies |
| Skytron |
| Tru-D SmartUVC |
| TMiRob Technology |
| Bioquell |
| Akara Robotics |
| Mediland Enterprise Corp. |
| Others |
Supply & Pricing Matrix
Eighteen-month FDA 510(k) clearance timelines compress vendor cash conversion cycles and amplify pricing power for established players with validated microbial kill documentation, while LiDAR sensor cost curves below two hundred dollars enable mid-tier hospital systems to access autonomous navigation previously confined to academic medical centers.
Pricing Analysis
Certification level (FDA 510(k)/CE MDR/NMPA Class II) creates the primary spread between premium autonomous systems and economy teleoperated units, with subscription-based service agreements bundling hardware, consumables, and outcome guarantees displacing capital purchase models in Nordic healthcare procurement. Price differentiation stems from electromagnetic safety testing breadth and after-sales validation support, with cost-per-disinfection-cycle contracting intensifying margin pressure on vendors lacking installed base scale. Food processing plants exhibit highest price sensitivity due to third-party sanitation contractor intermediation, while U.S. academic medical centers absorb premium positioning for pulsed xenon UV differentiation.
Supply Chain Analysis
Xenon lamp manufacturing concentration in Germany and Japan creates single-source vulnerability for premium robot configurations, with solid-state LiDAR modules drawing from Taiwanese semiconductor foundries and South Korean sensor packaging operations. Mercury vapor UV tubes and hydrogen peroxide vapor generators rest on Chinese component sourcing for cost-competitive electrostatic platforms, exposing vendors to tariff exposure on navigation electronics and optical subassemblies. Distribution runs through direct vendor relationships with large health systems for autonomous platforms, while janitorial supply distributors intermediate commercial office electrostatic sprayer flows.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense against manual cleaning labor arbitrage in emerging market hospitals, where low-wage janitorial contracts sustain cost advantages over capital-intensive robotic systems despite throughput and consistency deficits.
For Market Incumbents: Fortify regulatory qualification moats by deepening notified body relationships across FDA, EMA, and NMPA jurisdictions to compress competitor entry timelines, while anchoring recurring revenue through embedded workflow integration that raises customer switching costs. Pulsed xenon UV technology specialists must defend against Far-UVC semiconductor displacement by accelerating occupied-space validation studies. For New Entrants and Emerging Players: Anchor in USDA-inspected meat and poultry processing corridors where overnight robotic cycles align with mandated sanitation windows and incumbent penetration remains limited, targeting Midwest protein processing clusters with autonomous vapor systems. Food manufacturing integration offers the most penetrable vertical, with go-to-market leverage through third-party sanitation contractors seeking differentiation. For Investors and Strategic Acquirers: Long-term, this sits as a recurring-revenue infrastructure play because Nordic cost-per-cycle contracting models and Asian-Pacific public hospital tender structures restructure vendor cash flows toward service annuity streams. Acquisition targets should display multi-jurisdiction certification stacking capability and hospital system workflow integration depth. The signal to watch is Far-UVC semiconductor foundry adoption rates in Japan and South Korea as inflection indicator for technology platform displacement.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EMA MDR notified body relationships unlock German hospital procurement consortia contracting. |
| Hospital System Partnership | Danish and Swedish regional health authorities specify cost-per-cycle metrics requiring embedded workflow integration. |
| FDA Submission | Enhanced UV-C dose validation scrutiny stretches clearance timelines to eighteen-plus months for new entrants. |
| Software Companion Development | AI-driven pathogen detection modules face EU AI Act algorithmic transparency documentation requirements. |
| Reimbursement Strategy | CMS penalty structures for preventable infections compel U.S. academic medical center autonomous UV-C adoption. |
Research Methodology
Desk research of FDA 510(k) filings, EMA notified body guidance documents, and hospital procurement database records preceded structured interviews with infection control committee chairs, biomedical engineering directors, GPO contracts managers, and robotic systems integration specialists. Secondary validation drew from CMS reimbursement rulemaking, USDA inspection protocol amendments, and GB electromagnetic safety standard revisions. Bottom-up unit economics modeling and top-down national health mission infrastructure spending estimates were triangulated against vendor shipment disclosures and regional procurement tender awards.
Variance decomposition across product type, deployment mode, end-user sophistication tier, and geographic regulatory cluster shaped analytical framework construction throughout the projection horizon. CAGRs were derived from installed base expansion rates, replacement cycle assumptions, and pricing trajectory modeling for subscription versus capital purchase contract mix. Far-UVC semiconductor adoption curves in Japanese pharmaceutical cleanrooms and South Korean foundry environments informed technology displacement scenario weighting.
Decision-makers should treat outputs as directional under assumptions of sustained FDA scrutiny intensity and stable LiDAR cost curves; material deviation in regulatory timeline compression or solid-state sensor pricing would warrant model refresh. Practitioners should keep alternative scenarios live as EU AI Act algorithmic transparency enforcement and NMPA medical device classification evolution reshape competitive qualification thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Infection Control
Intra-Abdominal Infection Treatment Market
Infection Control
Global Skin Antiseptic Products Market
Infection Control
Dental Infection Treatment Market
Infection Control
Salivary Gland Infection Treatment Market
Infection Control
Virus Filtration Market
Infection Control
Global Sepsis Therapeutics Market
Infection Control
Ultraviolet Disinfection Equipment Market
Infection Control
Global Wall Mounted Ozone Disinfection Machine Market
Infection Control
Antiseptic Bathing Market
Infection Control
Peptide-Based Infection Therapeutics Market
Infection Control
Infection Prevention Market
Infection Control
Disinfection Cupboard Market
Infection Control
Alcohol Wipes Market
Infection Control
Europe Ultrasound Probe Disinfection Market
Infection Control
Hand Hygiene Market
Infection Control
Preventable Vaccines Market