
 Global Disease Control and Prevention Vaccine Market | 2026-2036
Global Disease Control and Prevention Vaccine Market Size, Share, and Industry Trends Forecast 2026-2036
Global Disease Control and Prevention Vaccine Market Foresight
The vaccine supply base is pivoting between premium mRNA platforms and commodity-grade inactivated formulations as procurement budgets diverge across buyer tiers. Pfizer Inc leverages its mRNA manufacturing network to sustain premium positioning in high-income contracts. Serum Institute of India Pvt Ltd anchors volume supply through large-scale inactivated and conjugate production for government tenders. GSK plc differentiates via its adjuvant technology leadership and established presence in pediatric combination vaccines.
Disease control and prevention vaccines are biologic preparations containing antigenic substances—live attenuated pathogens, inactivated virions, purified subunits, or nucleic acid constructs—that stimulate adaptive immune responses without causing disease; mRNA formulations encode spike protein antigens synthesized in vivo, while conjugate vaccines link polysaccharide coats to protein carriers to enhance immunogenicity in infant populations. The primary commercial purpose is population-level prophylaxis against infectious disease morbidity and mortality, with manufacturing governed by sterility assurance, cold chain integrity, and potency consistency standards. Live attenuated and conjugate vaccine categories occupy mature margin pools in pediatric routine immunization, while DNA and mRNA segments attract R&D concentration due to rapid reformulation capability against emerging variants. Public health agencies and government programs dominate procurement volume, though hospital pharmacies are gaining share in adult booster and travel vaccine segments as delivery decentralizes.
FDA breakthrough therapy designation and EMA conditional marketing authorization frameworks compress clinical development timelines for priority pathogens, while WHO prequalification standards govern access to procurement by international organizations and low-income country programs. India's CDSCO and BIS enforce local manufacturing quality benchmarks that shape export eligibility for domestic producers. Stakeholders must monitor regulatory convergence between FDA, EMA, and WHO on post-approval variant-adapted vaccine change protocols, as harmonized standards will determine speed-to-market for next-generation formulations.
Market Dynamics
mRNA platform standardization is compressing development cycles while fragmenting manufacturing investment across modular facilities and legacy bulk antigen plants. Regulatory convergence on variant-adapted protocols is accelerating approval velocity for reformulated candidates.
Growth Catalysts
- FDA Breakthrough Therapy Pathway:Compressed clinical timelines for priority pathogens enable faster commercialization of novel antigens against emerging variants.
- Government Immunization Infrastructure:Brazil, India, and the United States are scaling cold chain networks and procurement budgets for routine adult and pediatric programs.
- Adjuvant Technology Maturation:Next-generation formulations enhance immunogenicity in infant populations, expanding addressable cohorts for conjugate vaccines.
Market Restraints
- Lipid Nanoparticle Input Concentration:Ionizable lipid supply concentrates among specialized chemical manufacturers, creating single-source vulnerability for mRNA production.
- Cold Chain Infrastructure Gaps:Ultra-low temperature requirements for mRNA formulations exclude distribution to rural clinics in low-income regions lacking freezer capacity.
- WHO Prequalification Timelines:Stringent stability and sterility documentation requirements delay market access for manufacturers targeting international procurement pools.
Strategic Opportunities
- Travel Medicine Channel Expansion:Hospital pharmacies and private clinic networks in Germany and Australia are capturing adult booster demand outside government tender systems.
- Thermostable Formulation Development:Freeze-dried and ambient-stable platforms eliminate cold chain dependency, opening procurement in tropical climates with infrastructure constraints.
- Combination Vaccine Pipelines:Pentavalent and hexavalent candidates reduce injection burden, aligning with national immunization program efficiency mandates in Indonesia and Nigeria.
Industry Challenges
- Fill-Finish Capacity Bottlenecks:Aseptic manufacturing and vial filling operations require specialized cleanroom infrastructure that cannot scale rapidly to match antigen production.
- Cross-Contamination Protocol Complexity:Multi-product facilities face extended changeover validation requirements under EMA and FDA current good manufacturing practice standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Disease Control and Prevention Vaccine Market |
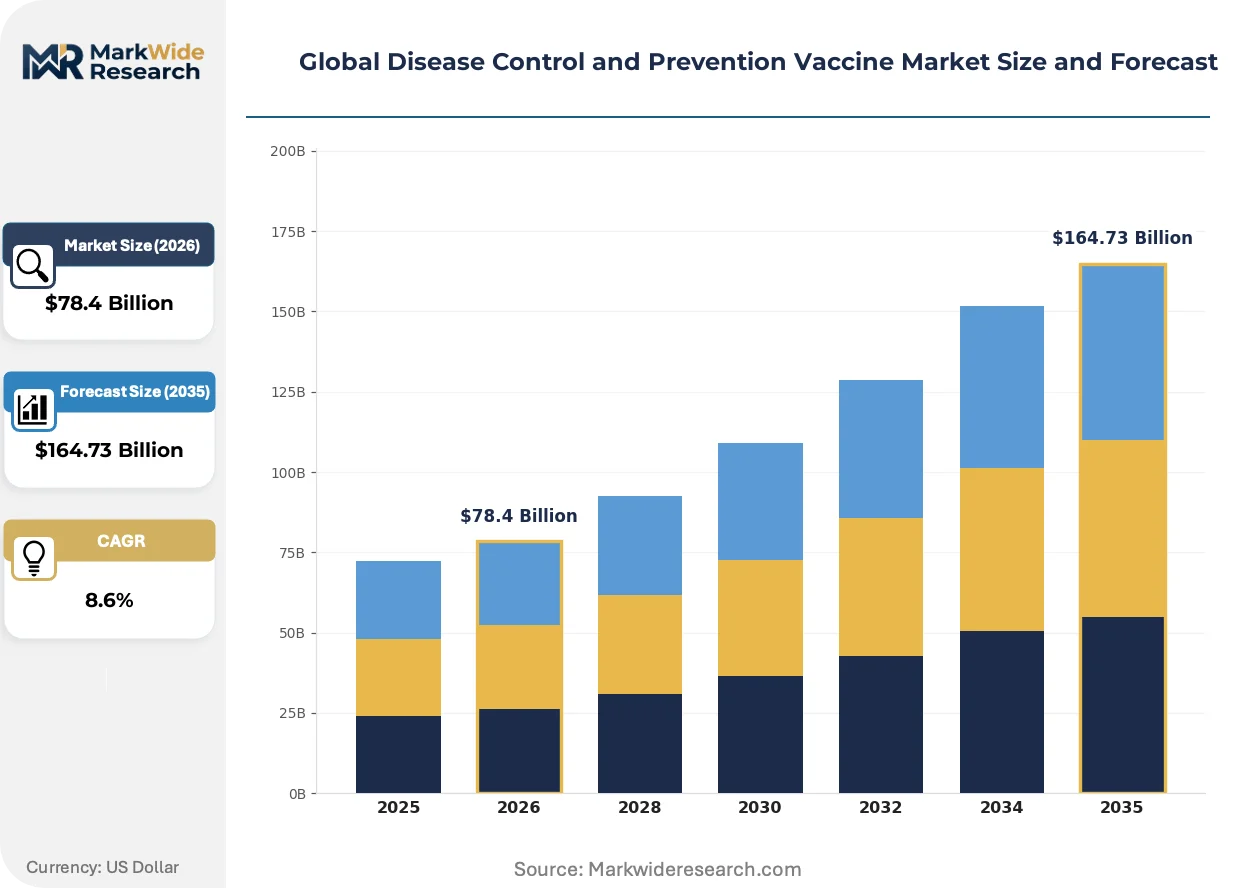
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $164.73 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vaccine Type: Live Attenuated, Inactivated, Subunit, Toxoid, Conjugate, DNA Target Disease: Influenza, Measles, Hepatitis B, Rabies, Polio, Diphtheria End User: Public Health Agencies, Research Centers, Diagnostic Laboratories, Immunization Clinics Distribution Channel: Hospital Pharmacies, Government Programs, Private Clinics, International Organizations |
| Companies Covered | Pfizer Inc, Merck & Co Inc, GSK plc, Sanofi, Moderna Inc, AstraZeneca, Serum Institute of India Pvt Ltd, CSL, BioNTech SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Disease Control and Prevention Vaccine Market Shifts & Advancements
Platform diversification is splitting manufacturing investment between flexible mRNA facilities and high-volume inactivated antigen plants. Regulatory agencies are harmonizing post-approval change protocols, compressing timelines for variant-adapted formulations.
Self-amplifying RNA constructs encode replicase enzymes that multiply antigen expression from minimal dose inputs. Large-scale government tenders in Southeast Asia are evaluating these platforms for pandemic stockpile applications. The technology is modularizing manufacturing footprints, enabling smaller batch facilities to achieve outputs previously requiring bulk fermentation infrastructure.
EMA conditional marketing authorization frameworks now permit rolling review of immunogenicity data prior to completion of large-scale efficacy trials. This regulatory evolution compresses development timelines by eight to fourteen months for priority pathogen candidates. Pediatric combination vaccine segments are responding fastest, leveraging established safety databases to accelerate label expansions.
Hospital pharmacies in France and Japan are disintermediating traditional distributor channels, contracting directly with manufacturers for adult travel and occupational vaccines. This channel shift fragments procurement concentration, enabling price differentiation between tender and retail segments. Brazil's private clinic networks demonstrate the most advanced direct-purchasing models, capturing premium positioning for non-scheduled immunizations.
Global Disease Control and Prevention Vaccine Market Segmentation
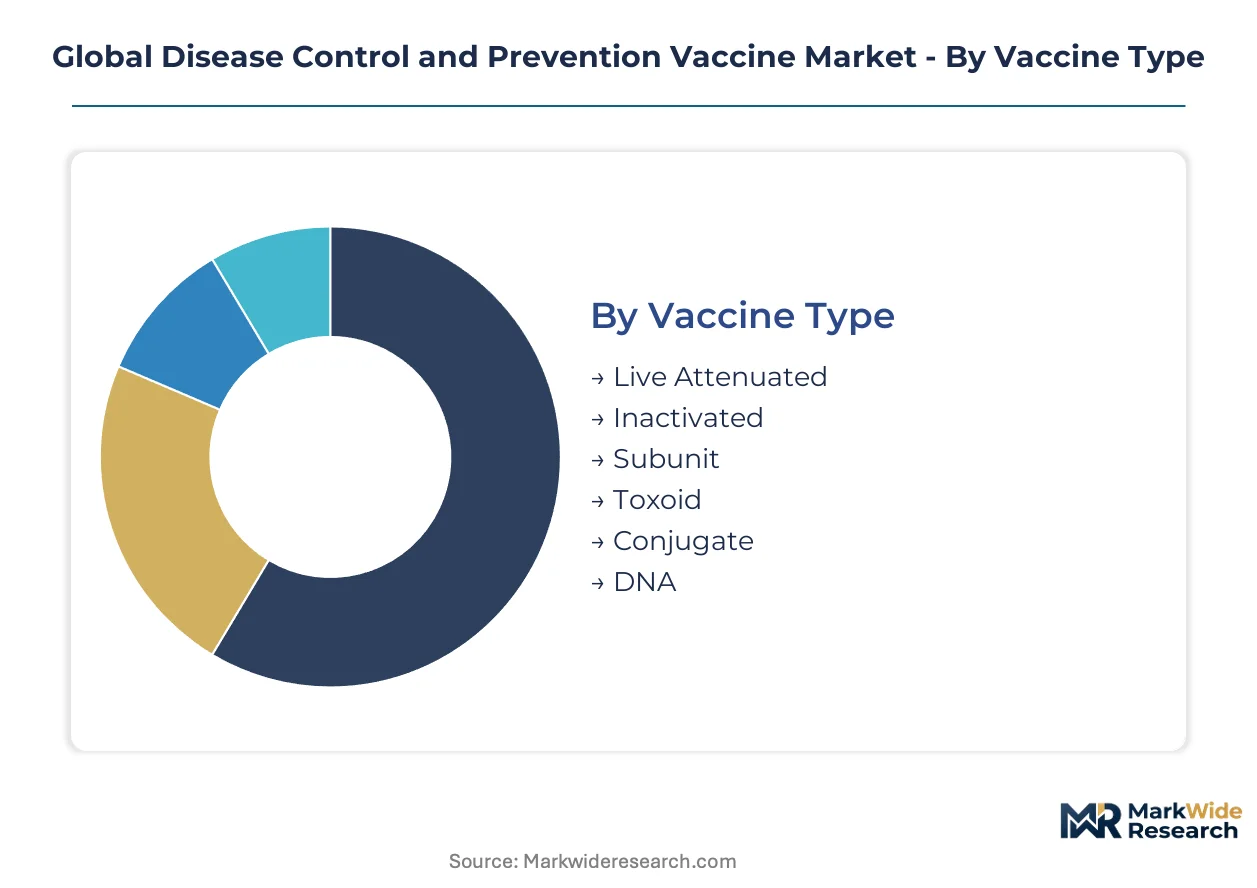
Vaccine market segmentation reveals divergent capital requirements and margin profiles across technology platforms. Procurement channel structure and cold chain infrastructure demands create distinct competitive arenas within each category.
Vaccine Type:
Capital intensity varies sharply across platforms, with mRNA and live attenuated production requiring the most sophisticated biomanufacturing infrastructure.
- Live Attenuated:Formulations contain weakened pathogens that replicate minimally in vivo to stimulate durable cellular immunity. Pediatric routine immunization programs in Brazil and Nigeria concentrate demand for measles and polio variants, constrained by ultra-cold storage requirements and short shelf lives.
- Inactivated:Virions destroyed by heat or chemical treatment retain immunogenic surface antigens without replication risk. India's government tenders absorb the largest procurement volumes for hepatitis B and polio coverage, driven by established safety profiles in infant populations.
- Subunit:Purified protein or polysaccharide antigens eliminate whole-pathogen handling risks.
- Toxoid:Bacterial exotoxins inactivated by formalin retain immunogenicity against diphtheria and tetanus.
- Conjugate:Polysaccharide coats chemically linked to protein carriers enhance T-cell dependent responses in infants.
- DNA:Plasmid vectors encoding target antigens offer thermal stability advantages over RNA platforms.
Inactivated platforms absorb the bulk of installed capacity; DNA formulations are expanding most quickly on thermostability advantages.
Target Disease:
Procurement volume clusters around diseases with established national immunization mandates and donor-funded eradication commitments.
- Influenza:Seasonal reformulation requirements drive annual manufacturing cycles with strain-matched updates. Hospital pharmacies in Germany and Japan capture adult booster demand outside government tender systems, pressured by abbreviated development windows for variant-adapted candidates.
- Measles:Live attenuated formulations dominate routine pediatric schedules with two-dose coverage targets. Sub-Saharan African programs through Gavi partnerships concentrate procurement volume, constrained by cold chain gaps in rural distribution.
- Hepatitis B:Recombinant subunit production at scale serves birth-dose and adolescent catch-up campaigns.
- Rabies:Post-exposure prophylaxis demand concentrates in veterinary and occupational health channels.
- Polio:Inactivated and oral formulations coexist in eradication-phase transition markets.
- Diphtheria:Toxoid components in combination vaccines anchor pediatric combination pipelines.
Influenza claims the steepest expansion trajectory on pandemic preparedness investments; measles retains the largest addressable population base.
End User:
Customer type determines pricing power, with public tenders squeezing margins while research channels accept premium positioning.
- Public Health Agencies:National immunization programs and supranational procurement bodies govern volume contracting through multi-year supply agreements. India's Universal Immunization Programme and Brazil's Ministry of Health anchor demand for inactivated and conjugate platforms, subject to stringent WHO prequalification requirements.
- Research Centers:Academic and government laboratories purchase investigational lots for clinical trial supply and immunogenicity studies.
- Diagnostic Laboratories:Serology and quality control reference materials support manufacturing release testing.
- Immunization Clinics:Private delivery networks in France and Australia capture travel and occupational vaccine demand outside tender systems.
Public Health Agencies command the dominant procurement share; Immunization Clinics are gaining price differentiation leverage through direct manufacturer contracts.
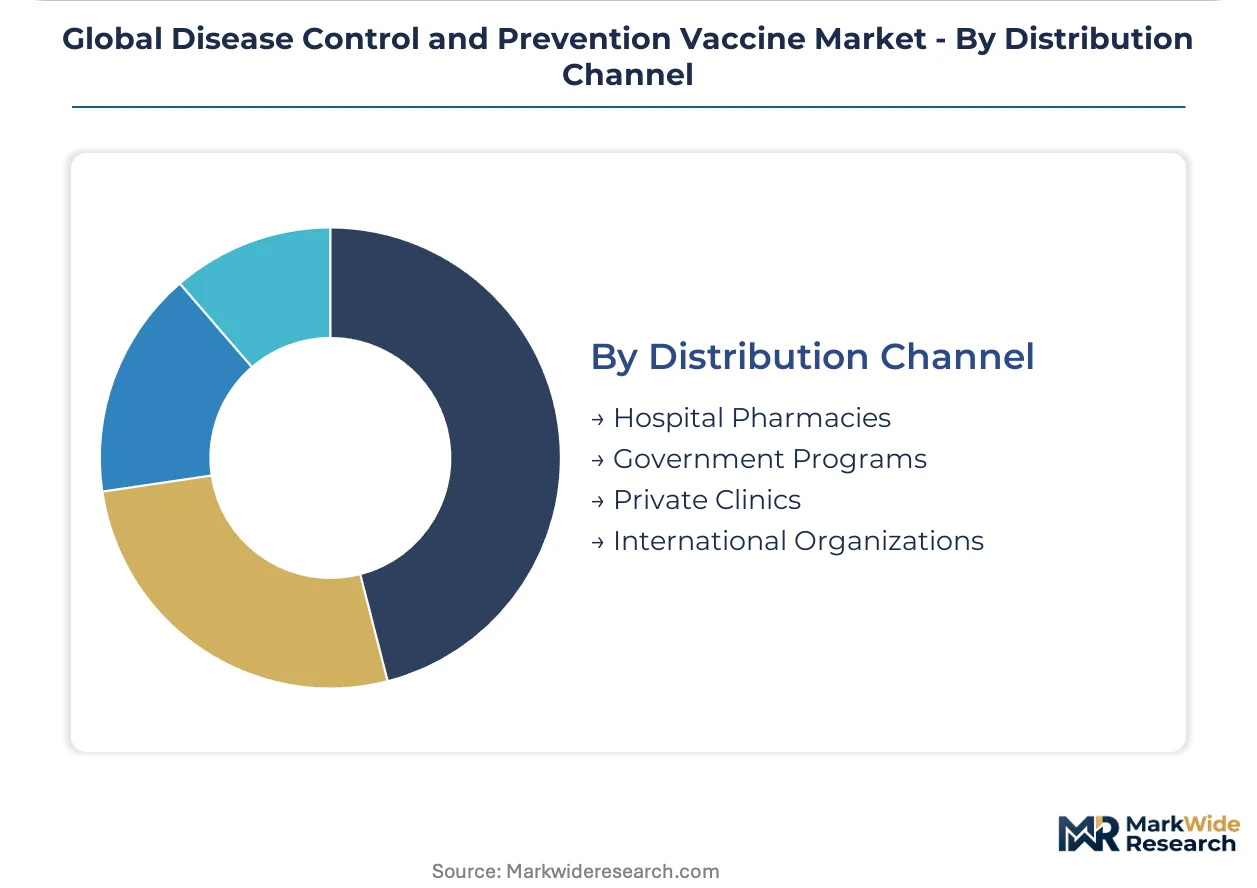
Distribution Channel:
Channel structure fragments between centralized tender systems and decentralized retail procurement, enabling tiered pricing strategies.
- Hospital Pharmacies:Institutional buyers in Japan and Germany contract directly for adult travel and booster segments. Cold chain custody transfers at hospital loading docks reduce distributor markups while requiring validated storage infrastructure.
- Government Programs:National immunization schedules and emergency stockpiles concentrate volume in Brazil, India, and the United States. FDA and CDSCO regulatory convergence on stability standards shapes eligibility for multi-source tender awards.
- Private Clinics:Occupational health and travel medicine providers in Australia capture premium positioning for non-scheduled immunizations.
- International Organizations:UNICEF and PAHO pooled procurement governs access to low-income country programs.
Government Programs dominate volume throughput; Hospital Pharmacies are climbing fastest on channel disintermediation trends.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Boston anchors North American vaccine R&D concentration through clustered biotech research corridors and proximity to FDA headquarters. Manufacturing scale concentrates across three distinct national markets with divergent procurement structures.
United States
Adult booster and pandemic stockpile programs drive procurement volume through CDC and BARDA contracting. FDA breakthrough therapy designation compresses clinical timelines for mRNA reformulations. Maryland and Massachusetts host fill-finish infrastructure serving government tender awards.
Germany
Hospital pharmacy direct contracting fragments procurement concentration for travel and occupational vaccines. EMA conditional marketing authorization frameworks accelerate variant-adapted approvals. BioNTech's manufacturing presence in Marburg exemplifies mRNA platform scale-up.
India
Universal Immunization Programme tenders absorb inactivated and conjugate vaccine volumes for hepatitis B and polio coverage. CDSCO and BIS quality benchmarks shape export eligibility for domestic producers. Pune and Hyderabad anchor bulk antigen manufacturing clusters.
Brazil
Ministry of Health scaling of cold chain networks enables mRNA distribution beyond metropolitan centers. ANVISA convergence with FDA stability standards facilitates multi-source tender eligibility. São Paulo's private clinic networks demonstrate advanced direct-purchasing models for non-scheduled immunizations.
Japan
Hospital pharmacy channel disintermediation captures adult travel vaccine demand outside distributor markups. PMDA rolling review frameworks compress development timelines for pediatric combination label expansions. Kanto region institutional buyers contract directly for booster segments.
Global Disease Control and Prevention Vaccine Market Competitive Landscape
Premium-margin players sit above commodity-margin players across technology platform differentiation and cold chain infrastructure requirements. The supplier base organizes into three tiers: mRNA platform specialists commanding research premiums, high-volume inactivated producers serving government tenders, and adjuvant technology leaders capturing pediatric combination margins. Strategic moves concentrate on modular manufacturing partnerships and thermostable formulation licensing.
Among US-based pharmaceutical conglomerates, Pfizer Inc and Merck & Co Inc exemplify divergent platform strategies—one anchored in mRNA network scale, the other in established pediatric franchise maintenance. GSK plc represents European adjuvant technology leadership. Serum Institute of India Pvt Ltd occupies the volume-production archetype for emerging market tenders. These three anchors—American, British, Indian—illustrate how geographic manufacturing specialization maps to procurement channel access.
| Leading Market Players |
|---|
| Pfizer Inc |
| Merck & Co Inc |
| GSK plc |
| Sanofi |
| Moderna Inc |
| AstraZeneca |
| Serum Institute of India Pvt Ltd |
| CSL |
| BioNTech SE |
| Others |
Supply & Pricing Matrix
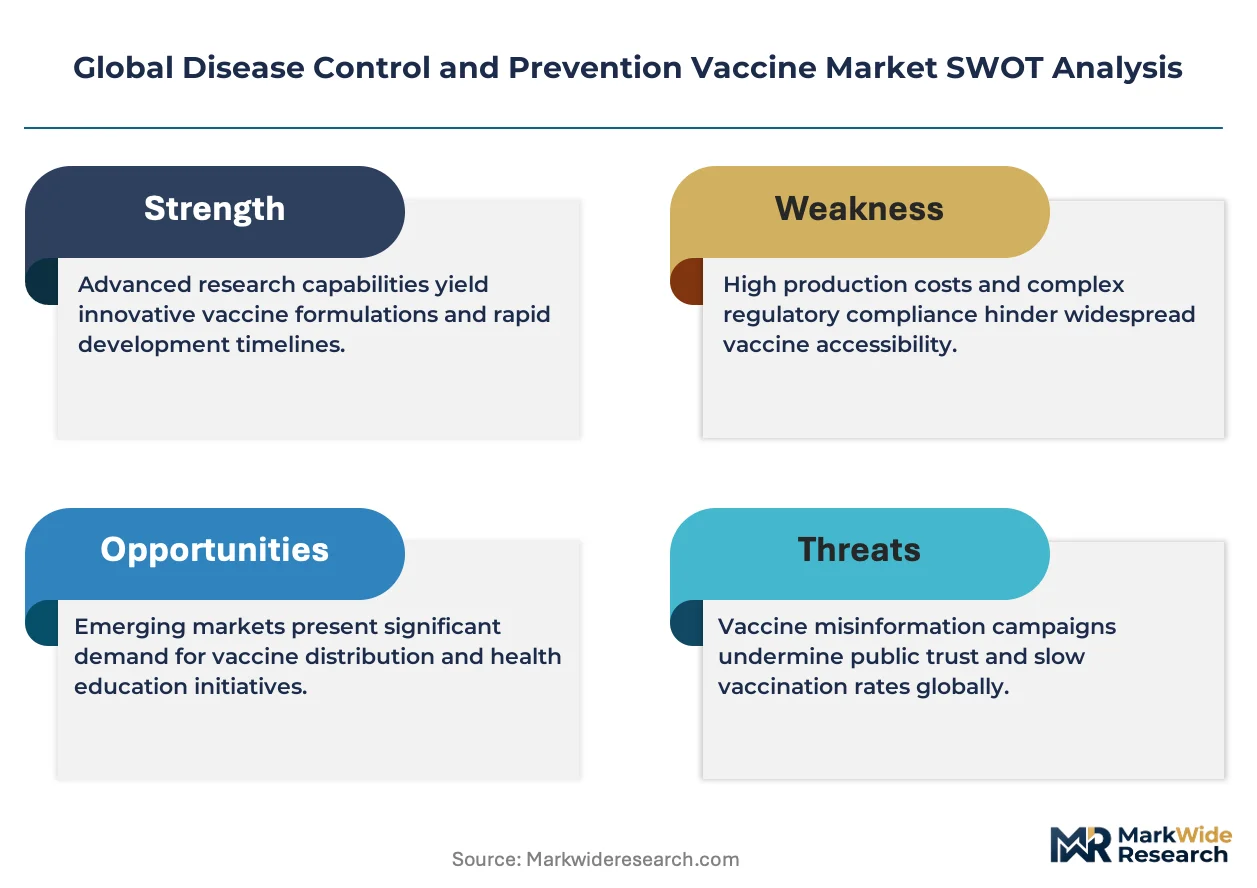
Captive ionizable lipid production anchors both supply security and premium pricing power for mRNA platform operators, while outsourced bulk antigen manufacturing constrains margin recovery for inactivated vaccine suppliers serving government tenders. This integration divergence stratifies the supplier base between technology-locked premium tiers and commodity-exposed volume segments.
Pricing Analysis
Yield-linked pricing models dominate mRNA contracts, with dose commitments tied to antigen expression efficiency and cold chain custody performance. Three-tier pricing structure across premium, standard, and economy levels reflects technology platform differentiation, WHO prequalification status, and volume scale. Cost compression in standard-tier inactivated vaccines is intensifying because Indian and Brazilian tender authorities consolidate multi-source awards. Public health agencies exhibit highest price sensitivity; private immunization clinics in Japan and Germany accept premium positioning for travel and occupational segments.
Supply Chain Analysis
WHO prequalification and FDA stability certification gate access to pooled procurement channels, filtering supplier eligibility before commercial negotiations commence. Ionizable lipid supply concentrates in specialized chemical manufacturers across the United States and Germany, while bulk antigen production clusters in India and Brazil. Fill-finish capacity bottlenecks in aseptic manufacturing create single-source vulnerability for vial filling operations. Distribution runs through government cold chain networks for routine immunization, with hospital pharmacies in France and Japan capturing direct manufacturer contracts for adult boosters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fill-finish cleanroom scarcity props pricing across all technology tiers, constraining volume expansion regardless of antigen production capacity. This supply bottleneck sustains margin pools for qualified manufacturers while excluding marginal entrants from tender eligibility.
For Market Incumbents: Cement fill-finish capacity advantages through captive facility expansion in Maryland and Maharashtra regulatory clusters. Lock in multi-year ionizable lipid supply agreements before specialty chemical competitors scale alternative lipid formulations. Adjuvant technology leaders must defend pediatric combination positions against self-amplifying RNA platform entrants targeting hexavalent label expansions.
For New Entrants and Emerging Players: FDA breakthrough therapy designation in the United States opens a window for thermostable formulation specialists to bypass cold chain infrastructure gaps that exclude mRNA incumbents from tropical procurement. Target WHO prequalification pathways for freeze-dried platforms serving Gavi partnerships in sub-Saharan Africa. Lead with ambient-stable stability data to differentiate from ultra-cold dependent competitors in rural distribution tenders.
For Investors and Strategic Acquirers: Exit pathways concentrate in platform-technology licensing to government stockpile authorities seeking pandemic surge capacity. Five-to-ten year viability favors adjuvant technology holders with established pediatric safety databases over unproven DNA platform operators. Watch EMA-FDA convergence on post-approval variant-adapted change protocols as the signal for accelerated reformulation approval velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | Modular mRNA facility deployment in Marburg and Pune expands surge capacity for government stockpile awards. |
| Regulatory Approval Pathway | Rolling review frameworks at EMA and PMDA compress development timelines for pediatric combination label expansions. |
| Backward Integration | In-house ionizable lipid synthesis eliminates single-source dependency for mRNA platform operators. |
| Licensing Agreement | Thermostable formulation partnerships with Serum Institute unlock tropical procurement eligibility for freeze-dried platforms. |
| Pipeline Diversification | Pentavalent and hexavalent candidates align with Indonesia and Nigeria national immunization efficiency mandates. |
Research Methodology
FDA filings, EMA conditional marketing authorization submissions, and WHO prequalification databases formed the secondary backbone for platform technology and regulatory pathway mapping. Primary interviews with vaccine development executives, regulatory affairs leads at CDSCO and ANVISA, hospital procurement managers in Germany and Japan, and formulary directors at UNICEF pooled procurement validated demand assumptions. Bottom-up antigen production capacity modeling triangulated against top-down government tender award analysis across the analysis window.
Historical trendline analysis of multi-year supply agreement volumes established baseline procurement patterns across public health agencies and private clinic networks. Segmentation modeling incorporated vaccine type platform characteristics, target disease immunization schedule positioning, end-user procurement channel structure, and regional regulatory cluster alignment. CAGRs derived from weighted average of government budget growth trajectories and technology platform substitution curves, with pandemic stockpile replenishment cycles and variant-adapted reformulation frequency as key forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for self-amplifying RNA would alter the outlook if thermostability and dose-sparing advantages accelerate platform substitution. Forecasts reflect assumptions on regulatory convergence timelines, fill-finish capacity expansion rates, and cold chain infrastructure investment levels in priority geographies. A model refresh is warranted upon material change in FDA-EMA harmonization protocols for post-approval variant-adapted vaccine modifications.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Infection Control
Middle East and Africa Hand Sanitizer Market
Infection Control
Global Hospital Acquired Infection Control Market
Infection Control
Point of Care Infection Control Market
Infection Control
Germicidal UV Lamp Market
Infection Control
Multi-Surface Disinfection Booster Systems with Low QAC Load Market
Infection Control
Sterilization Monitoring Market
Infection Control
Alcohol Wipes Market
Infection Control
Virus Filtration Market
Infection Control
Denture Disinfectants Market
Infection Control
Ultraviolet Disinfection Equipment Market
Infection Control
Global Disinfection Robots Market
Infection Control
Hygiene Stations Market
Infection Control
Dental Infection Treatment Market
Infection Control
Ear Infection Treatment Market
Infection Control
Sterilization Market
Infection Control
Infection Control Market