
 Global Hospital Disinfectant Products and Services Market | 2026-2036
Global Hospital Disinfectant Products and Services Market Size, Share, and Industry Trends Forecast 2026-2036
Global Hospital Disinfectant Products and Services Market Foresight
EU MDR is pivoting the cost-of-entry calculus for hospital disinfectant suppliers by reclassifying certain high-level disinfectants as medical devices requiring notified body certification. Ecolab Inc. leverages its integrated service model to bundle chemical supply with compliance documentation, reducing procurement friction for European hospitals. STERIS plc anchors its position through captive manufacturing of both hydrogen peroxide vapor equipment and consumable refills. Diversey Holdings, Ltd. competes on formulation breadth, sustaining R&D pipelines across quaternary ammonium, peracetic acid, and accelerated hydrogen peroxide chemistries.
Hospital disinfectant products and services encompass chemical formulations, physical sterilization systems, and contracted environmental hygiene programs engineered to achieve defined log-reduction thresholds against bacterial spores, mycobacteria, enveloped viruses, and prions on critical and semi-critical surfaces. Terminal cleaning protocols typically demand ≥6-log reduction of Geobacillus stearothermophilus spores for steam sterilization and ≥5-log reduction for high-level liquid chemical disinfectants used on flexible endoscopes. Surface disinfectants command the largest revenue pool given their daily deployment across all hospital zones, while UV disinfectants represent the fastest-expanding technology segment as facilities seek non-contact terminal disinfection for C. difficile and MRSA containment. Operating rooms generate premium pricing per square meter due to terminal cleaning validation requirements and the direct link between surgical site infections and reimbursement penalties.
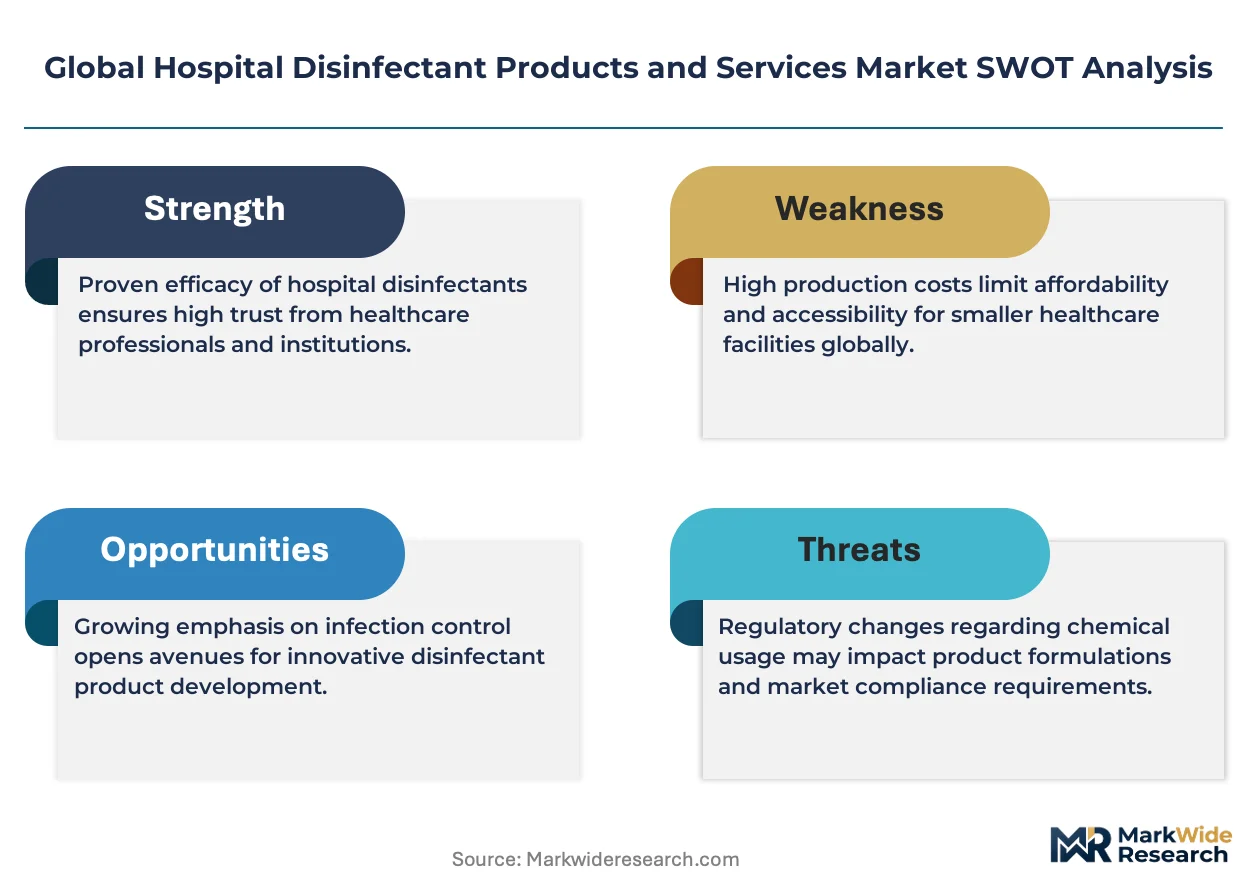
FDA regulates liquid chemical sterilants and high-level disinfectants through the 510(k) pathway, while EPA governs hospital-use disinfectants under FIFRA with emerging pathogen and List N designations driving pandemic-era procurement. EMA's MDR framework and ISO 15883 standards for washer-disinfectors collectively shape product development roadmaps and market access timelines across OECD healthcare systems. Stakeholders must monitor regulatory divergence between EPA's data requirements for sporicidal claims and EMA's medical device technical documentation, as this friction determines which formulation platforms achieve transatlantic commercial viability.
Market Dynamics
EU MDR reclassification of high-level disinfectants as medical devices is forcing suppliers to absorb notified body certification costs and extend validation timelines, fundamentally altering competitive economics for liquid chemical sterilants across European healthcare procurement.
Growth Catalysts
- EPA Emerging Pathogen Protocol:US hospitals accelerate sporicidal disinfectant stockpiling to maintain List N compliance, expanding hydrogen peroxide and peracetic acid formulation demand.
- German Operating Room Mandates:Hospital accreditation standards now require hydrogen peroxide vapor terminal cleaning, creating captive equipment-consumable bundling opportunities.
- UV-C Robotics Diffusion:Autonomous no-touch disinfection systems reduce C. difficile transmission in isolation units, displacing manual terminal cleaning protocols in high-acuity wards.
Market Restraints
- Quaternary Ammonium Supply Concentration:China controls 60-70% of benzalkonium chloride precursor manufacturing, exposing European and North American formulators to input volatility and tariff exposure.
- EMA MDR Technical Documentation Burden:High-level disinfectant reclassification demands clinical evidence packages that extend time-to-market by 18-24 months for novel chemistries.
- Glutaraldehyde Substitution Pressure:Occupational exposure limits and respiratory toxicity concerns are compressing demand for aldehyde-based high-level disinfectants in endoscope reprocessing.
Strategic Opportunities
- India Hospital Accreditation Expansion:NABH standards adoption in tier-2 and tier-3 cities creates first-mover positioning for automated washer-disinfector and chemical monitoring system suppliers.
- Peracetic Acid-Hydrogen Peroxide Convergence:Synergistic formulations achieving sporicidal efficacy at reduced contact times are penetrating flexible endoscope reprocessing workflows.
- Environmental Hygiene Service Unbundling:Third-party terminal cleaning validation and ATP bioluminescence auditing are emerging as standalone procurement categories separate from chemical supply contracts.
Industry Challenges
- Reprocessing Technician Certification Gaps:ISO 15883-compliant washer-disinfector operation and chemical indicator interpretation require specialized training that outpaces workforce pipeline development.
- Legacy Steam Sterilizer Integration:Hydrogen peroxide vapor systems demand facility infrastructure modifications including HVAC isolation and humidity control that complicate retrofit deployment in older hospital wings.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Hospital Disinfectant Products and Services Market |
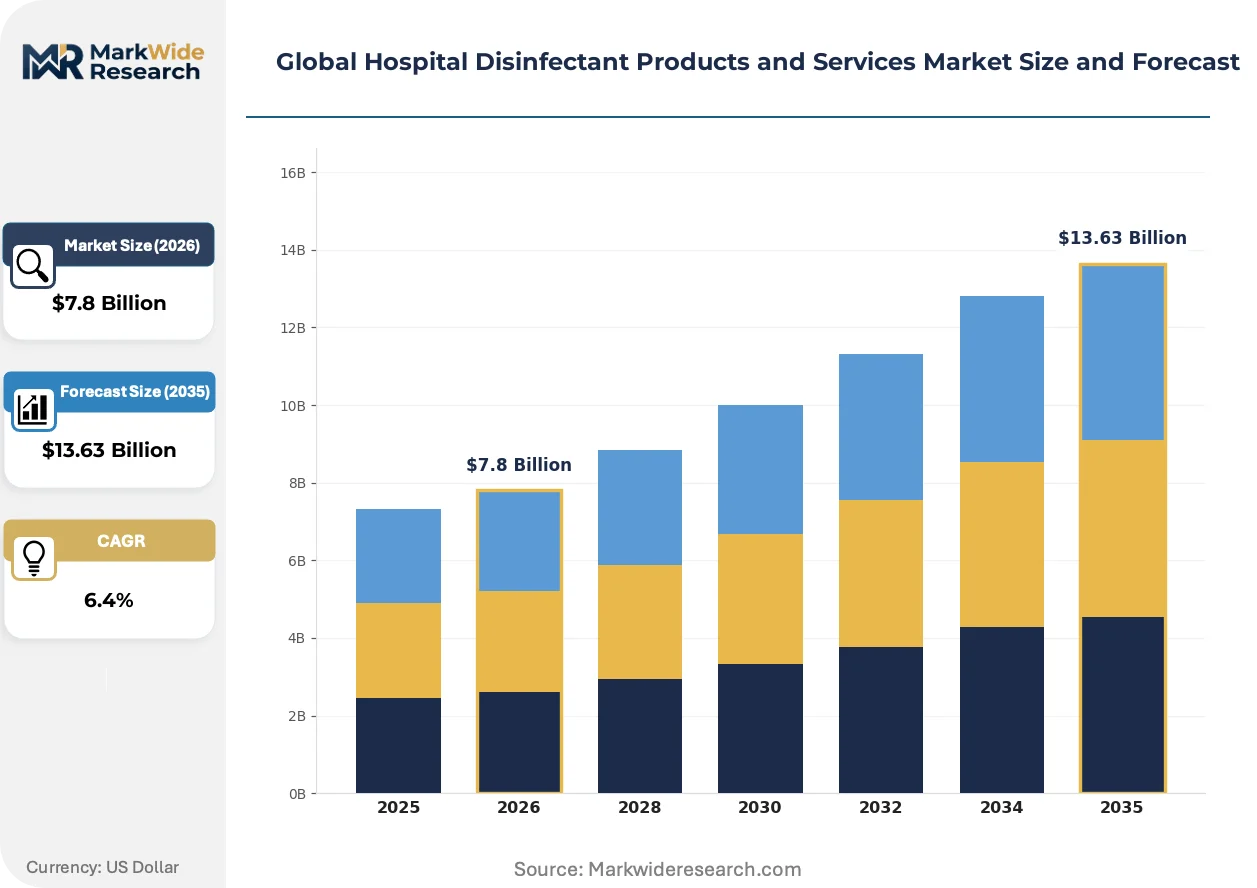
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $13.63 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Surface Disinfectants, Instrument Disinfectants, Hand Sanitizers, UV Disinfectants, Thermal Disinfectants, Fogging Agents Technology: Chemical-Based, Ozone-Based, Ultraviolet, Hydrogen Peroxide Vapor, Electrolyzed Water, Steam Sterilization Application: Operating Rooms, Patient Rooms, Laboratories, Sterile Processing, Emergency Wards, Isolation Units End User: Hospitals, Ambulatory Surgical Centers, Diagnostic Centers, Long-Term Care Facilities, Rehabilitation Clinics, Nursing Homes |
| Companies Covered | Ecolab Inc., Reckitt Benckiser Group plc, STERIS plc, 3M Company, Diversey Holdings, Ltd., Johnson & Johnson Company, The Clorox Company, Colgate-Palmolive Company, Kimberly-Clark Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Hospital Disinfectant Products and Services Market Shifts & Advancements
Terminal disinfection protocols are converging around automated, data-validated systems that replace subjective manual cleaning assessments with quantifiable log-reduction documentation for infection control compliance.
Far-ultraviolet (222nm) excimer lamp technology is electrifying operating room and intensive care unit disinfection by enabling continuous pathogen suppression during occupied periods without photobiological safety constraints. German university hospitals are piloting ceiling-mounted installations for intraoperative air and surface decontamination. This capability is compressing the boundary between terminal and maintenance cleaning cycles, enabling more frequent intervention without workflow disruption.
REACH authorization requirements for biocidal active substances are forcing reformulation of legacy quaternary ammonium and phenolic disinfectants across EU member states. The industrial consequence is a consolidation of approved substance lists that favors large-scale manufacturers with dedicated regulatory affairs capabilities. High-level disinfectant suppliers are responding by accelerating peracetic acid and hydrogen peroxide platform development to preempt authorization uncertainty.
Subscription-based environmental hygiene service models are displacing transactional chemical procurement in US health systems pursuing standardized infection rate outcomes. Kaiser Permanente and similar integrated delivery networks are bundling surface disinfectant supply with UV equipment deployment and compliance reporting under per-bed-day pricing. This shift is most visible in California and Massachusetts markets where Medicaid reimbursement penalties for hospital-acquired infections are most severe.
Global Hospital Disinfectant Products and Services Market Segmentation
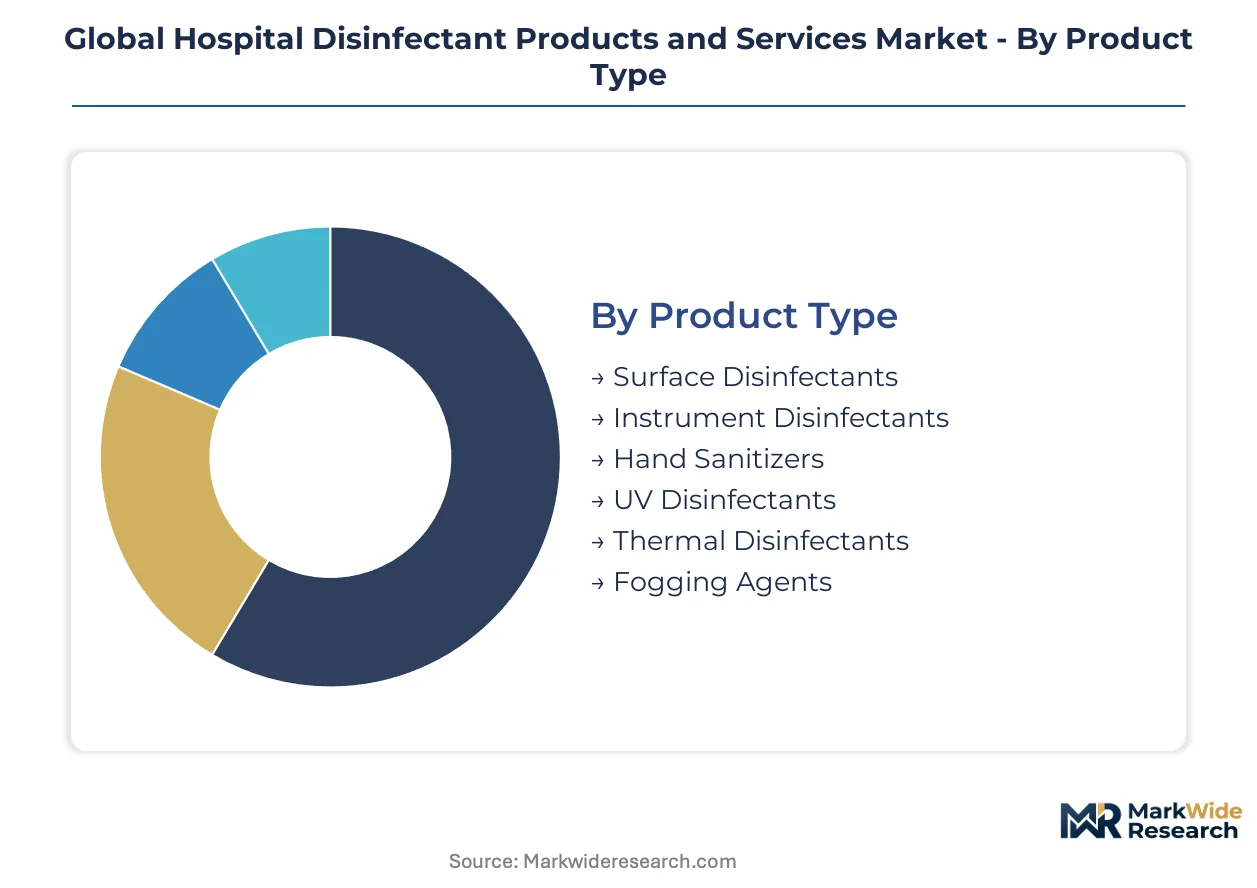
Hospital disinfectant procurement follows parallel upgrade cycles: equipment replacement drives capital expenditure in UV and vapor systems, while consumable formulations turn over faster as regulations shift. Understanding where these cycles intersect reveals which segments command pricing power versus volume scale.
Product Type:
Replacement cycles vary dramatically by product physics — liquid formulations turn over in 12-18 months as claims evolve, while capital equipment stretches 7-10 years with consumable lock-in.
- Surface Disinfectants:Quaternary ammonium, peracetic acid, and accelerated hydrogen peroxide formulations dominate daily environmental hygiene across all hospital zones. Demand concentrates in US acute care facilities where EPA List N compliance and Medicaid reimbursement penalties for hospital-acquired infections drive quarterly procurement reviews.
- UV Disinfectants:Mobile and ceiling-mounted systems deploying 254nm mercury vapor or 222nm far-UVC excimer lamps achieve ≥4-log reduction of C. difficile spores without contact time limitations. German university hospitals are piloting continuous intraoperative disinfection, compressing terminal cleaning windows.
- Instrument Disinfectants:High-level liquid chemical sterilants for flexible endoscope reprocessing face EMA MDR reclassification burdens.
- Hand Sanitizers:Alcohol-based and chlorhexidine formulations sustain baseline consumption across all clinical entry points.
- Thermal Disinfectants:Washer-disinfector chemistries complement automated reprocessing hardware.
- Fogging Agents:Hydrogen peroxide and peracetic acid aerosol systems target terminal disinfection in outbreak containment scenarios.
Surface disinfectants sit at the top of the volume ranking, with UV disinfectants climbing the fastest.
Technology:
Technology selection tracks facility infrastructure age — older buildings favor chemical flexibility while new construction integrates fixed UV and vapor systems.
- Chemical-Based:Quaternary ammonium, phenolic, and halogen-based formulations retain cost advantage for low-acuity surface disinfection. REACH authorization pressures in Europe are forcing consolidation toward peracetic acid and hydrogen peroxide platforms with clearer regulatory pathways.
- Hydrogen Peroxide Vapor:Automated room decontamination systems achieve ≥6-log spore reduction in sealed environments. German operating room mandates now require terminal cleaning validation via vapor systems, creating captive equipment-consumable bundling.
- Ultraviolet:Mercury vapor and excimer lamp architectures compete on photobiological safety and continuous-operation capability.
- Ozone-Based:Limited penetration due to material compatibility constraints and ventilation requirements.
- Electrolyzed Water:On-site generation systems reduce transport costs for large-scale laundry and floor cleaning operations.
- Steam Sterilization:Saturated steam under pressure remains the gold standard for critical instrument terminal sterilization.
Chemical-based platforms retain the widest installed base, though hydrogen peroxide vapor systems are expanding most quickly in new construction.
Application:
Application segmentation maps directly to reimbursement risk — surgical site infections trigger penalties, while laboratory contamination risks research integrity rather than payment.
- Operating Rooms:Terminal cleaning protocols demand validated ≥5-log reduction documentation with direct linkage to surgical site infection rates. Premium pricing per square meter reflects accreditation audit intensity and HVAC isolation requirements for vapor system deployment.
- Isolation Units:C. difficile and MRSA containment drives no-touch UV disinfection adoption. US facilities in California and Massachusetts markets lead autonomous robot deployment where Medicaid penalties are most severe.
- Patient Rooms:High-frequency surface disinfection sustains quaternary ammonium and hydrogen peroxide wipe consumption.
- Laboratories:Biosafety level considerations determine sterilization tier requirements.
- Sterile Processing:Centralized reprocessing departments concentrate instrument disinfectant and washer-disinfector demand.
- Emergency Wards:Rapid turnover protocols favor fast-acting surface disinfectants with broad-spectrum claims.
Operating rooms command the highest pricing intensity, with isolation units gaining share fastest on infection control investment.
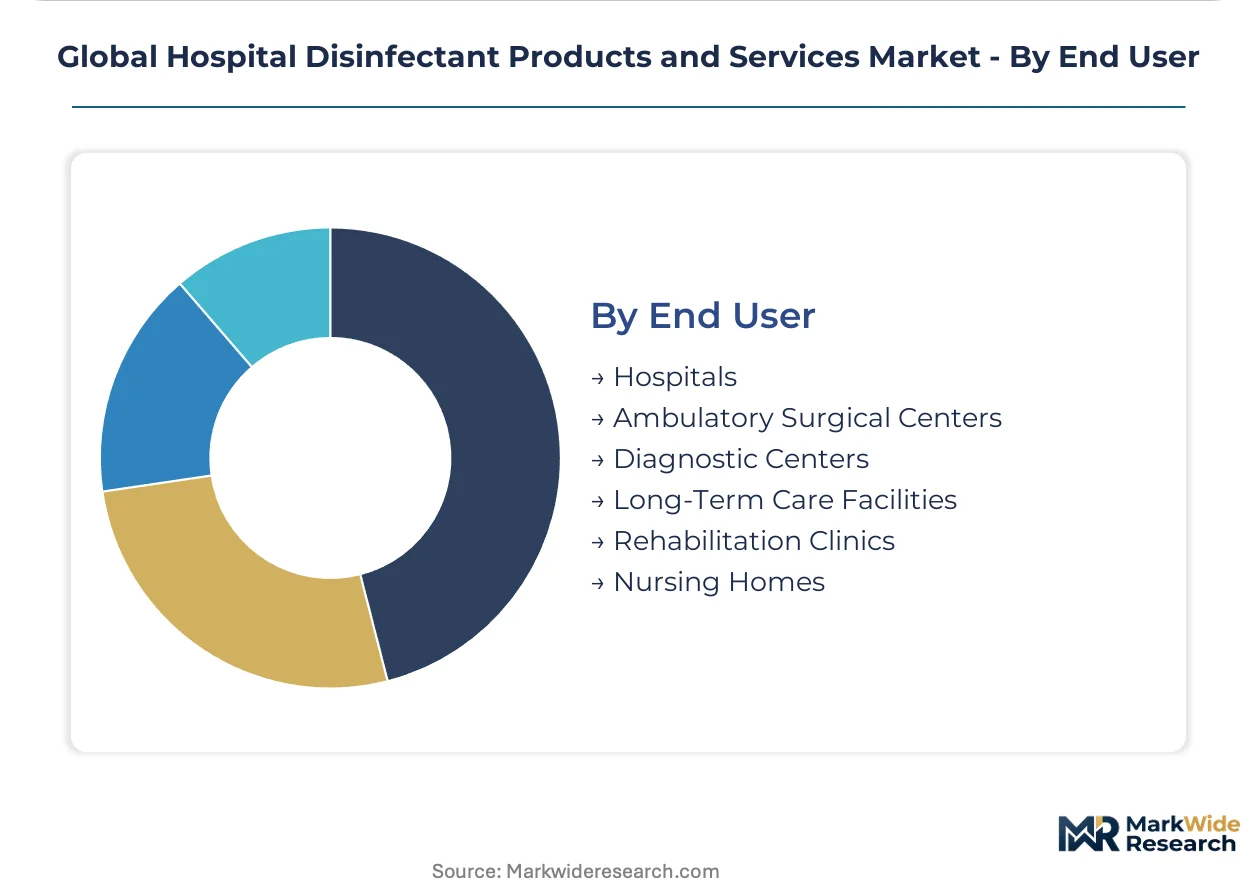
End User:
End user scale determines service model viability — integrated delivery networks bundle environmental hygiene services while standalone facilities transact chemical procurement.
- Hospitals:Acute care facilities above 200 beds generate sufficient scale for subscription-based environmental hygiene programs bundling chemical supply, UV equipment, and compliance reporting. Kaiser Permanente and similar IDNs in California anchor per-bed-day pricing models.
- Ambulatory Surgical Centers:Procedure volume concentration in ophthalmology and endoscopy drives compact high-level disinfectant system demand. Rapid instrument turnover requirements favor peracetic acid formulations with reduced contact times.
- Diagnostic Centers:Imaging equipment disinfection protocols sustain surface disinfectant consumption at lower per-facility volumes.
- Long-Term Care Facilities:Norovirus and influenza containment priorities shape procurement toward broad-spectrum virucidal claims.
- Rehabilitation Clinics:Therapy equipment disinfection sustains intermediate-tier chemical demand.
- Nursing Homes:Resident density and mobility limitations drive hand hygiene and surface disinfection protocols.
Hospitals anchor absolute volume, with ambulatory surgical centers showing the steepest expansion trajectory on procedure migration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Modern hospital disinfection protocols trace their regulatory foundations to post-war European sterilization standards and subsequent US EPA emerging pathogen frameworks. These dual lineages continue shaping procurement patterns across OECD healthcare systems.
United States
Acute care facilities in California and Massachusetts drive autonomous UV robot deployment where Medicaid penalties for hospital-acquired infections are most severe. EPA List N compliance mandates accelerate hydrogen peroxide and peracetic acid formulation stockpiling. Kaiser Permanente anchors subscription-based environmental hygiene bundling in the Pacific Coast corridor.
Germany
Hospital accreditation standards now mandate hydrogen peroxide vapor systems for operating room terminal cleaning, creating captive equipment-consumable bundling opportunities. EMA MDR reclassification forces notified body certification for high-level disinfectants, extending validation timelines. University hospitals in Bavaria pilot far-UVC excimer installations for continuous intraoperative decontamination.
China
Domestic manufacturers control 60-70% of benzalkonium chloride precursor output, exposing European and North American formulators to input volatility. The National Medical Products Administration tightens biosafety level requirements for centralized sterile processing departments. Shanghai and Beijing clusters concentrate automated washer-disinfector production for domestic hospital accreditation expansion.
India
NABH standards adoption in tier-2 and tier-3 cities creates first-mover positioning for automated washer-disinfector suppliers. Central Drugs Standard Control Organization oversight of medical device disinfectants intensifies documentation requirements. Maharashtra and Karnataka hospital networks drive peracetic acid-hydrogen peroxide convergence in flexible endoscope reprocessing.
United Kingdom
NHS procurement frameworks emphasize outcome-based environmental hygiene contracts with ATP bioluminescence validation requirements. Health and Safety Executive occupational exposure limits compress glutaraldehyde demand in endoscope reprocessing. London and Southeast England integrated care systems bundle surface disinfectant supply with compliance reporting infrastructure.
Global Hospital Disinfectant Products and Services Market Competitive Landscape
The competitive structure tilts toward integrated service providers with regulatory documentation capabilities. Tier-one positions concentrate among multinational chemical conglomerates with dedicated healthcare divisions, while mid-scale specialists compete on formulation breadth and regional compliance expertise. Two dominant competitive moves define current positioning: strategic partnerships bundling equipment with consumable supply, and geographic expansion through acquisition of regional environmental hygiene service providers.
Among diversified chemical conglomerates, Ecolab Inc. and STERIS plc occupy positions exemplifying the integrated service archetype, combining chemical supply with compliance infrastructure. Diversey Holdings, Ltd. represents the formulation breadth specialist tier, sustaining development pipelines across multiple chemistries. Reckitt Benckiser Group plc anchors the consumer-healthcare hybrid segment, leveraging brand recognition in adjacent hygiene categories.
| Leading Market Players |
|---|
| Ecolab Inc. |
| Reckitt Benckiser Group plc |
| STERIS plc |
| 3M Company |
| Diversey Holdings, Ltd. |
| Johnson & Johnson Company |
| The Clorox Company |
| Colgate-Palmolive Company |
| Kimberly-Clark Corporation |
| Others |
Supply & Pricing Matrix
Benzalkonium chloride precursor costs cascade from Chinese manufacturing clusters through European and North American formulators, compressing margins for quaternary ammonium surface disinfectants while hydrogen peroxide platforms command premium positioning through supply security.
Pricing Analysis
Subscription-based environmental hygiene bundling separates acute care facilities above 200 beds from smaller standalone hospitals transacting chemical procurement. Price differentiation hinges on EPA List N certification tier and after-sales compliance documentation depth. Cost compression in the quaternary ammonium tier intensifies because REACH authorization uncertainty forces reformulation investments. Ambulatory surgical centers exhibit the highest price sensitivity due to procedure volume concentration, while integrated delivery networks in California and Massachusetts markets absorb premium pricing to offset Medicaid reimbursement penalties.
Supply Chain Analysis
Regional distribution centers in Germany, the United States, and China anchor hub-and-spoke patterns for hydrogen peroxide vapor equipment and consumable refills. Active ingredient manufacturing draws from Chinese benzalkonium chloride facilities, Indian peracetic acid producers, and German hydrogen peroxide specialists. Single-source vulnerability concentrates in benzalkonium chloride precursor supply, exposing formulators to tariff exposure and input volatility. Distribution runs through healthcare group purchasing organizations and direct hospital contracts, with accreditation-mandated vapor systems shifting toward captive equipment-consumable bundling.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hospital disinfectant procurement has shifted toward validated outcome guarantees, rewarding suppliers with integrated service capabilities and regulatory documentation infrastructure over commodity chemical vendors.
For Market Incumbents: Anchor market position through backward integration into hydrogen peroxide vapor equipment manufacturing and captive consumable supply, neutralizing emerging entrant price aggression in the UV disinfection segment. Extend notified body certification capabilities to preempt EMA MDR documentation burdens that threaten smaller formulation specialists. For New Entrants and Emerging Players: The mid-tier pricing gap between premium hydrogen peroxide vapor systems and economy-grade quaternary ammonium formulations offers white-space positioning for peracetic acid-hydrogen peroxide convergent chemistries. Target tier-2 Indian cities where NABH accreditation expansion outpaces local supplier capacity, deploying automated washer-disinfector systems through hospital system partnerships with embedded training protocols. For Investors and Strategic Acquirers: Consolidation pressure builds where EMA MDR reclassification extends validation timelines beyond 18 months, straining mid-scale specialists without dedicated regulatory affairs capabilities. Long-term viability favors integrated service providers with environmental hygiene bundling expertise; monitor EPA emerging pathogen designation frequency as inflection indicator for sporicidal formulation demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Notified Body Certification Investment | EMA MDR compliance enables continued high-level disinfectant market access across German and French hospital procurement frameworks. |
| Peracetic Acid-Hydrogen Peroxide Convergence | Reduced contact time formulations penetrate flexible endoscope reprocessing workflows in US ambulatory surgical centers. |
| UV-C Robotics Deployment Partnership | Autonomous no-touch systems displace manual terminal cleaning in California and Massachusetts isolation units facing Medicaid penalties. |
| Environmental Hygiene Service Unbundling | Standalone ATP bioluminescence auditing creates recurring revenue separate from chemical supply contracts in NHS procurement frameworks. |
| Far-UVC Excimer Pilot Expansion | German university hospital installations validate continuous intraoperative decontamination for operating room workflow compression. |
Research Methodology
Multiple input streams — primary interviews with hospital infection control officers, sterile processing department managers, and GPO contracts administrators; secondary validation through EPA List N registrations, EMA MDR technical documentation filings, and hospital procurement databases; plus customs data on benzalkonium chloride trade flows — were reconciled through bottom-up facility-level demand modeling and top-down market sizing triangulation.
Data-stream reconciliation anchored volume and value outputs across product type, technology platform, application zone, and end-user scale dimensions over the projection horizon. CAGRs were derived from facility upgrade cycle analysis and regulatory mandate implementation timelines, incorporating hydrogen peroxide vapor system deployment rates and UV robot adoption curves as industry-specific forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for far-UVC excimer lamp continuous disinfection would alter the outlook if photobiological safety validation accelerates beyond current pilot timelines. Forecasts reflect stated assumptions regarding EPA emerging pathogen designation frequency and EMA MDR implementation enforcement; decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Infection Control
Salivary Gland Infection Market
Infection Control
Global Biofilms Treatment Market
Infection Control
Global Hospital Acquired Infection Control Market
Infection Control
Global Viral Inactivation Market
Infection Control
Sterilization Market
Infection Control
Sterilization Monitoring Market
Infection Control
Disinfection Equipment Market
Infection Control
Germicidal UV Lamp Market
Infection Control
Surgical Site Infection Control Market
Infection Control
Global High Level Disinfection Services Market
Infection Control
Multi-Surface Disinfection Booster Systems with Low QAC Load Market
Infection Control
UV Disinfection Equipment Market
Infection Control
Steam and Hydrogen Peroxide Biological Indicators Market
Infection Control
Antiseptic Bathing Market
Infection Control
Europe Ultrasound Probe Disinfection Market
Infection Control
Antimicrobial Catheters Market