
 Sterilization Tunnel Market | 2026-2036
Sterilization Tunnel Market Size, Share, and Industry Trends Forecast 2026-2036
Sterilization Tunnel Market Analytics
Modular cleanroom architecture is fragmenting traditional sterilization tunnel procurement, as pharmaceutical buyers demand skid-mounted systems that integrate with isolator-barrier technologies rather than standalone units. Bosch Packaging Technology leverages its downstream filling portfolio to bundle tunnel-isolator combinations. Steriline anchors its competitive stance through concentrated Italian manufacturing and European regulatory intimacy. Romaco Group differentiates via flexible batch-size configurations that accommodate growing biologics contract manufacturing.
A sterilization tunnel is a continuous-processing chamber that exposes packaged or unpackaged products to validated sterilizing agents—thermal, chemical, or radiant—while conveying them on a precision-timed belt system at temperatures typically ranging from 250°C to 350°C for depyrogenation applications. Its primary industrial purpose is to render pharmaceutical vials, ampoules, and medical device packaging bioburden-free prior to aseptic filling or final sealing. High-pressure steam tunnels retain dominant share in legacy small-molecule injectable facilities, while hydrogen peroxide vapor systems are gaining fastest in biologics suites where heat-sensitive polymer containers predominate. Conveyor system technology remains the mature baseline, though robotic automation is capturing margin pools in high-value cell and gene therapy cleanrooms where human intervention carries catastrophic contamination risk.
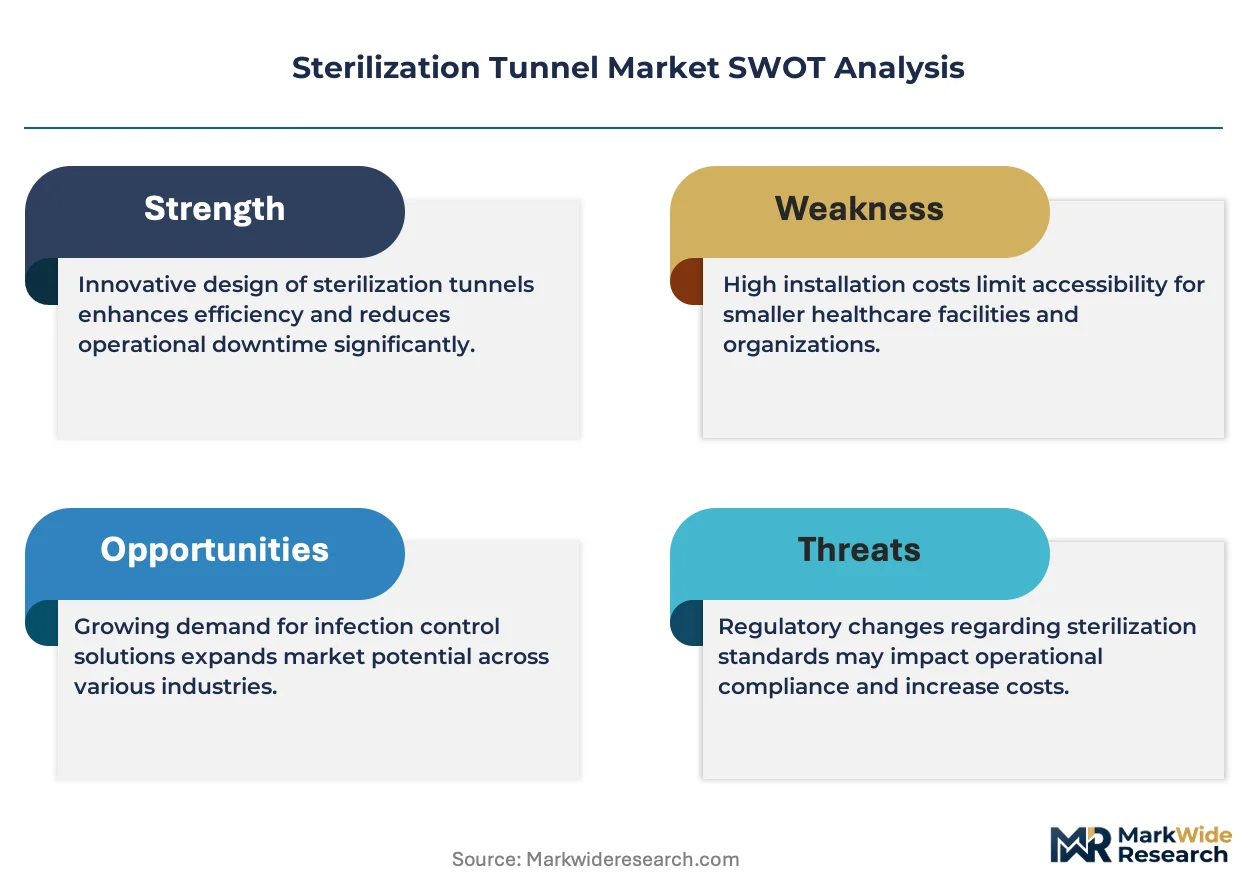
FDA sterility guidance and EU GMP Annex 1 revisions are forcing simultaneous upgrades to both tunnel hardware and surrounding environmental monitoring infrastructure, compressing replacement cycles for equipment installed before 2015. ISO 14644 cleanroom classifications and the EU's MDR traceability requirements further constrain supplier qualification, favoring vendors with established notified-body relationships. Stakeholders must weigh capital allocation between tunnel replacement and full line integration, as regulatory convergence between US and European standards narrows the field of compliant equipment architectures.
Market Dynamics
Modular cleanroom architecture is fragmenting traditional sterilization tunnel procurement, as pharmaceutical buyers demand skid-mounted systems that integrate with isolator-barrier technologies rather than standalone units. This structural shift compresses replacement cycles and favors vendors with bundled downstream filling portfolios.
Growth Catalysts
- EU GMP Annex 1 revisions:The updated sterile manufacturing guidance mandates continuous viable and non-viable particle monitoring, forcing facility upgrades that include tunnel replacements.
- Biologics contract manufacturing:Heat-sensitive polymer containers for cell and gene therapies require hydrogen peroxide vapor tunnels instead of legacy thermal systems.
- German injectable drug clusters:Dense concentrations of vial and ampoule filling facilities in Baden-Württemberg and Bavaria concentrate equipment procurement.
Market Restraints
- Stainless steel input volatility:Grade 316L and 304 price swings compress margins for tunnel fabricators with fixed-price contracts.
- Notified body capacity constraints:EU MDR certification backlogs extend equipment qualification timelines by 8-14 months.
- Isolator technology substitution:Closed restricted access barrier systems increasingly displace open tunnel configurations in new greenfield builds.
Strategic Opportunities
- Indian CDMO expansion:Contract development and manufacturing organizations in Hyderabad and Ahmedabad are modernizing sterile filling lines under PLI scheme incentives.
- Robotic automation convergence:Integration of collaborative robots with tunnel infeed and outfeed systems reduces human intervention in high-value therapy suites.
- Outcome-based service models:Equipment vendors can capture recurring revenue through guaranteed uptime contracts tied to validated sterilization performance.
Industry Challenges
- Cleanroom commissioning specialists:Shortages of engineers qualified in ISO 14644-3 testing and FDA validation documentation delay project handovers.
- Legacy SCADA integration:Pre-2015 tunnel installations require costly control system upgrades to meet 21 CFR Part 11 electronic records requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sterilization Tunnel Market |
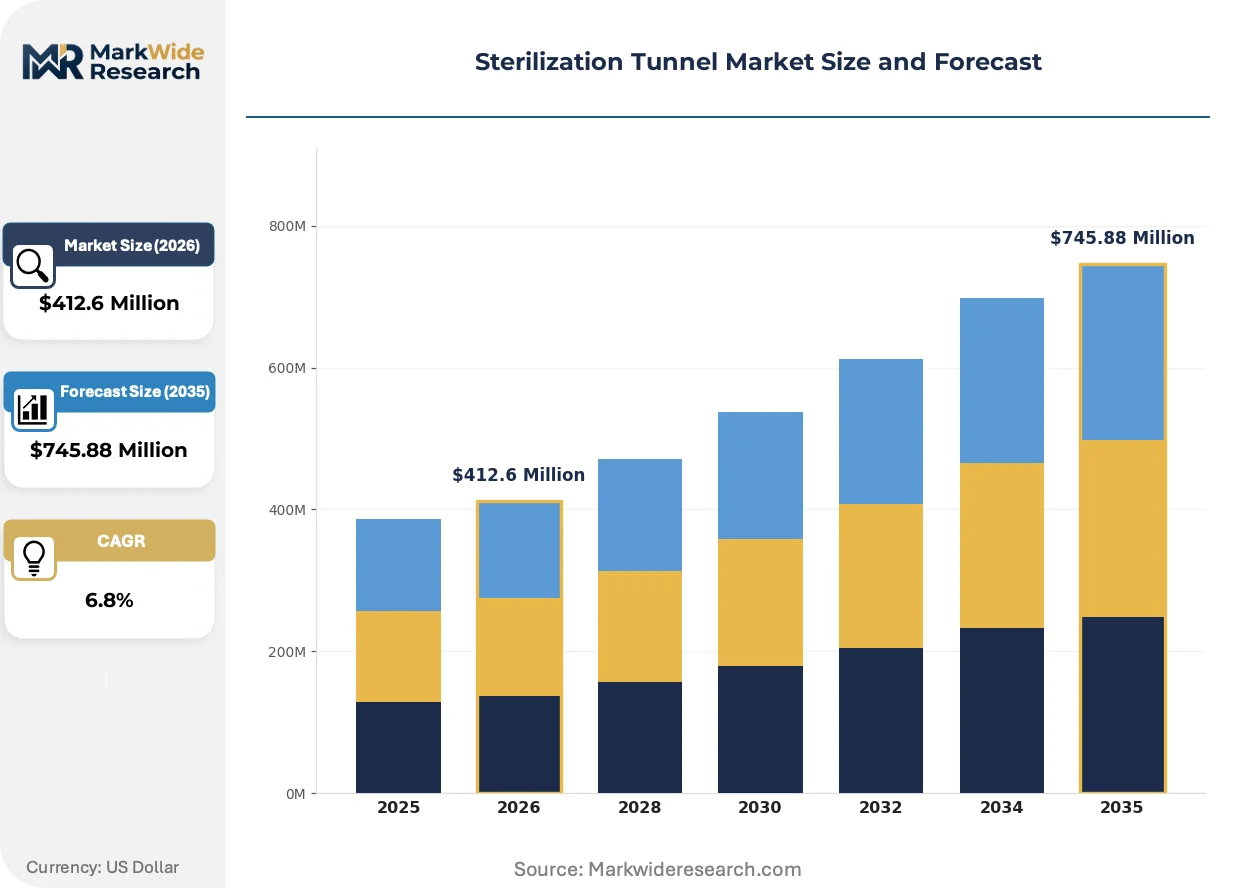
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $745.88 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Medium-Pressure UV, High-Pressure Steam, Ethylene Oxide, Hydrogen Peroxide Application: Pharmaceuticals, Food & Beverage, Medical Devices, Laboratory Equipment End User: Hospitals, Research Facilities, Pharmaceutical Companies, Manufacturing Units Technology: Conveyor Systems, Robotic Automation, Laser Sterilization, Ozone Treatment |
| Companies Covered | Bosch Packaging Technology, Steriline, Romaco Group, IMA Group, Bausch+Ströbel, Optima Packaging Group, Marchesini Group, Cozzoli Machine Company, Steris Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sterilization Tunnel Market Evolving Landscape
Sterilization tunnel technology is migrating toward integrated barrier systems, regulatory validation automation, and service-based commercial models. These shifts reshape competitive positioning around software competence and regulatory intimacy rather than mechanical engineering alone.
Continuous processing is migrating from batch thermal sterilization to in-line hydrogen peroxide vapor systems that accommodate temperature-sensitive biologic containers. Cell and gene therapy manufacturers in Switzerland and Massachusetts are adopting these systems at 2-3x the rate of traditional pharmaceutical facilities. The technology is migrating from standalone equipment sales toward bundled tunnel-isolator-filling line configurations that compress vendor selection to integrated platform providers.
FDA's updated guidance on sterile drug products issued in 2023 tightens validation requirements for depyrogenation cycle development and documentation. The regulation forces simultaneous upgrades to tunnel hardware, environmental monitoring infrastructure, and data integrity systems. Small-molecule injectable facilities in the US Midwest and Puerto Rico face the steepest compliance costs due to aging installed bases.
Equipment buyers are consolidating vendor relationships from multi-supplier line builds toward single-source platform procurement. Large pharmaceutical manufacturers now require tunnel suppliers to demonstrate downstream filling integration capabilities before qualification. This pattern concentrates in Germany and Switzerland, where major vaccine and biologics producers operate integrated manufacturing campuses.
Sterilization Tunnel Market Segmentation
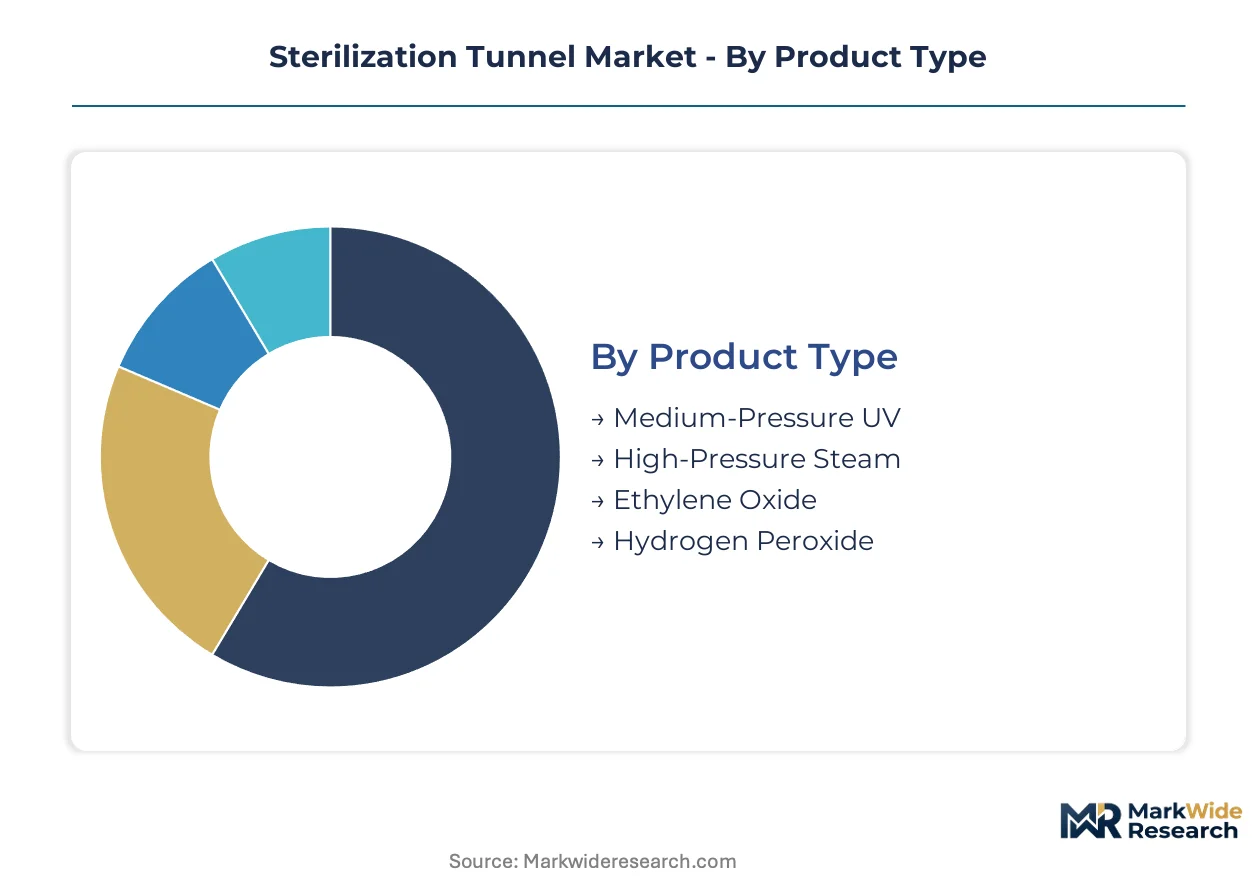
Sterilization tunnel procurement patterns diverge sharply across sterilizing agent chemistry, downstream application, and facility integration requirements. Each segmentation axis reveals distinct margin pools, qualification barriers, and vendor competitive advantages that reshape equipment specification workflows.
Product Type:
The use-case spectrum spans thermal depyrogenation for glass containers through low-temperature chemical vapor systems for polymer-based biologics packaging.
- High-Pressure Steam:Saturated steam at 121°C to 134°C penetrates porous loads and wrapped medical devices. Legacy injectable facilities in Germany and Switzerland retain this technology for vial sterilization despite longer cycle times.
- Hydrogen Peroxide:Vapor-phase hydrogen peroxide at 30-35°C enables terminal sterilization of heat-sensitive prefilled syringes and cell therapy containers. Massachusetts biologics manufacturers deploy these systems at accelerated rates for gene therapy suites.
- Medium-Pressure UV:254nm germicidal irradiation for surface disinfection of packaging materials and laboratory equipment where thermal methods risk degradation.
- Ethylene Oxide:Alkylating gas chemistry for temperature-sensitive medical devices with complex geometries, requiring extended aeration cycles and residual testing protocols.
The dominant share belongs to High-Pressure Steam, while Hydrogen Peroxide is closing the gap fastest.
Application:
Facility validation requirements and batch economics create divergent specification priorities across terminal sterilization workflows.
- Pharmaceuticals:Aseptic filling line integration demands validated depyrogenation cycles meeting FDA sterile drug product guidance. Injectable drug clusters in Baden-Württemberg concentrate procurement of tunnel-isolator combinations.
- Medical Devices:Implantable and single-use device packaging requires SAL 10^-6 sterility assurance levels with ISO 11135 or ISO 17665 compliance documentation.
- Food & Beverage:Aseptic carton and bottle sterilization for extended-shelf-life dairy and juice products, predominantly in European dairy processing corridors.
- Laboratory Equipment:Research-scale decontamination of glassware and media preparation vessels, often employing benchtop UV or steam tunnel configurations.
Pharmaceuticals command premium pricing tiers, though Medical Devices is expanding most quickly under EU MDR traceability mandates.
End User:
Capital deployment capacity and regulatory sophistication stratify procurement patterns across facility types.
- Pharmaceutical Companies:Integrated manufacturing campuses in Switzerland and Germany specify skid-mounted tunnel systems with isolator-barrier integration and 21 CFR Part 11 data integrity compliance.
- Manufacturing Units:Contract development and manufacturing organizations in Hyderabad and Ahmedabad modernize sterile filling lines under India's PLI scheme incentives.
- Hospitals:Central sterile services departments employ compact steam tunnels for surgical instrument reprocessing, constrained by facility footprint limitations.
- Research Facilities:Academic and government laboratories prioritize flexible batch-size configurations for investigational product development.
Pharmaceutical Companies retain the largest installed base, while Manufacturing Units is gaining share fastest through CDMO expansion.
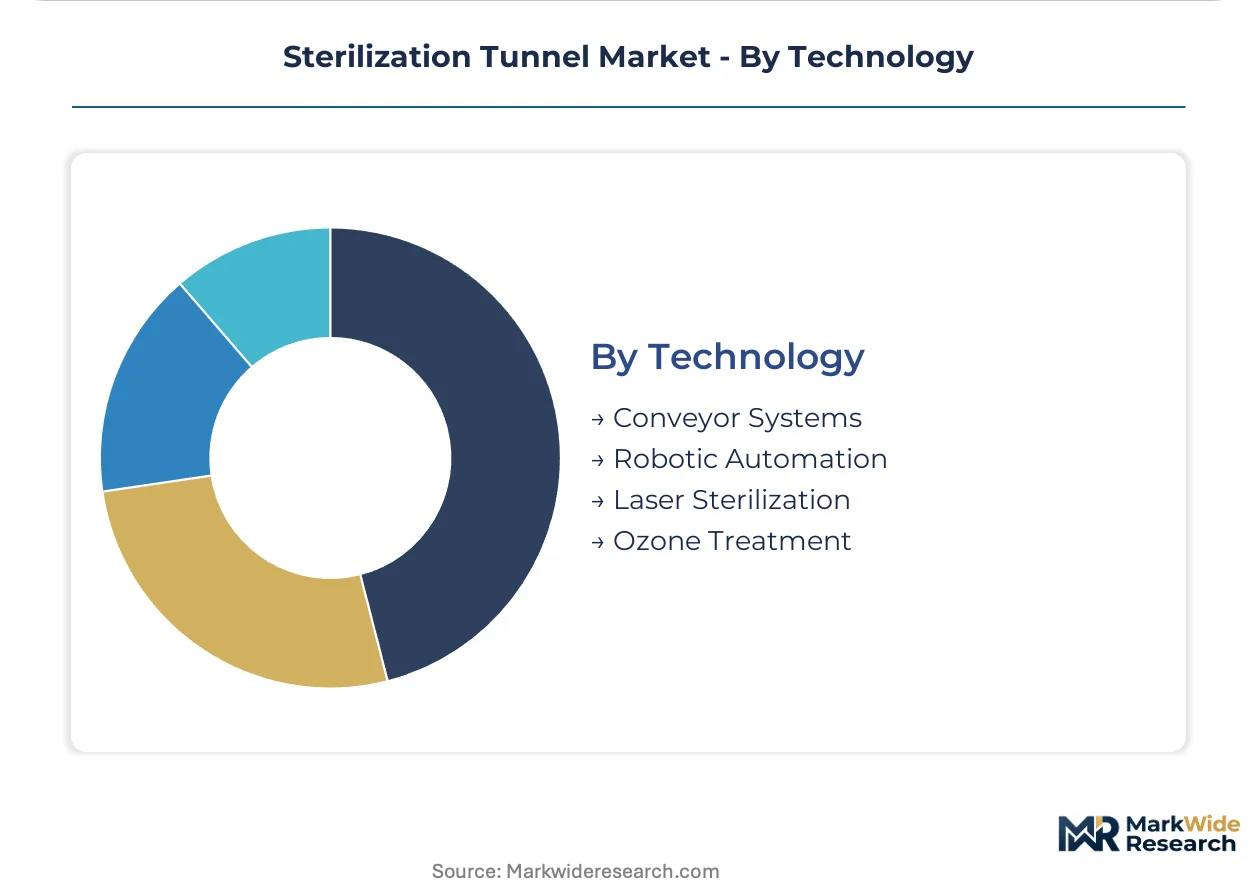
Technology:
Mechanical conveyance architectures compete with robotic automation for contamination control and throughput optimization.
- Conveyor Systems:Precision-timed belt mechanisms with HEPA-filtered laminar flow coverage remain the baseline for high-volume vial and ampoule processing.
- Robotic Automation:Collaborative robots for tunnel infeed and outfeed operations eliminate human intervention in cell and gene therapy cleanrooms where contamination carries catastrophic financial consequences.
- Laser Sterilization:Pulsed light and UV laser systems for targeted surface decontamination of complex medical device geometries.
- Ozone Treatment:Gaseous ozone chemistry for water-intensive applications and certain packaging material sterilization workflows.
Conveyor Systems holds established dominance, yet Robotic Automation is climbing the fastest as biologics manufacturers prioritize closed-system processing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export intensity from German and Swiss equipment fabricators exceeds import dependency across most sterilization tunnel categories, while Asian CDMOs drive inbound procurement of European-origin systems. Trade balances favor precision-engineered thermal and vapor-phase units shipped from Central European manufacturing clusters.
Germany
Injectable drug manufacturing in Baden-Württemberg and Bavaria sustains dense demand for tunnel-isolator combinations. The country's national pharmaceutical regulator enforces EU GMP Annex 1 compliance timelines that compress replacement cycles. Stuttgart and Munich anchor fabrication of skid-mounted systems for aseptic filling lines.
United States
FDA sterile drug product guidance issued in 2023 forces simultaneous hardware and validation infrastructure upgrades. Puerto Rico and the US Midwest concentrate aging installed bases requiring 21 CFR Part 11 control system retrofits. Massachusetts biologics manufacturers deploy hydrogen peroxide vapor tunnels at accelerated rates.
Switzerland
Cell and gene therapy cleanrooms in Basel and Zug prioritize robotic automation to eliminate human intervention. Swissmedic maintains stringent notified-body relationships that favor vendors with established European regulatory intimacy. The Lake Geneva corridor integrates tunnel systems with isolator-barrier technologies.
India
Hyderabad and Ahmedabad CDMOs modernize sterile filling lines under PLI scheme incentives for pharmaceutical manufacturing. The country's national pharmaceutical regulator aligns with EU GMP standards to facilitate export qualification. Telangana and Gujarat concentrate contract manufacturing expansion.
Italy
Specialized fabricators in Emilia-Romagna and Lombardy concentrate European manufacturing of flexible batch-size configurations. CE marking and EU MDR traceability requirements constrain supplier qualification to established notified-body relationships. Bologna and Milan anchor production of tunnel systems for biologics contract manufacturing.
Sterilization Tunnel Market Competitive Landscape
On the supply side, the industry is consolidating around integrated platform providers rather than standalone equipment vendors. Tiered competitive positioning separates full-line integrators from component specialists and regional fabricators. Strategic archetypes include bundled downstream filling portfolio holders, concentrated manufacturing specialists, and flexible batch-size configurators. Dominant competitive moves encompass M&A for filling line integration and geographic expansion into Indian CDMO corridors.
Among Germany-based full-line integrators, Bosch Packaging Technology and Bausch+Ströbel occupy positions that exemplify bundled tunnel-isolator-filling combinations. Italian specialists Steriline and IMA Group represent the concentrated European manufacturing archetype with deep regulatory intimacy. Romaco Group sits within the flexible configuration tier serving biologics contract manufacturing scale requirements.
| Leading Market Players |
|---|
| Bosch Packaging Technology |
| Steriline |
| Romaco Group |
| IMA Group |
| Bausch+Ströbel |
| Optima Packaging Group |
| Marchesini Group |
| Cozzoli Machine Company |
| Steris Corporation |
| Others |
Value Network & Pricing Analysis
The Rhine-Alpine freight corridor's volatile container rates compress margins for tunnel fabricators shipping skid-mounted systems from Stuttgart to Indian CDMOs, concentrating pricing power with German and Swiss full-line integrators while forcing tier-two Italian specialists toward economy-tier positioning.
Pricing Analysis
Technology-generation pricing gaps separate legacy thermal conveyor systems from hydrogen peroxide vapor tunnels and emerging robotic automation configurations. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and downstream filling integration depth. Pricing pressure stems from stainless steel input volatility and fixed-price contract exposure among component fabricators. Contract development and manufacturing organizations in India exhibit highest price sensitivity, while integrated biologics campuses in Switzerland accept premium positioning for validated isolator-tunnel combinations.
Supply Chain Analysis
Export-control regimes on precision motion-control components and HEPA filtration systems constrain technology transfer to non-EU manufacturing facilities. Supply concentration centers on Germany, Switzerland, and Italy for engineered thermal systems and barrier-integration expertise. Grade 316L stainless steel, precision conveyor belting, and validated SCADA modules constitute critical input dependencies. Single-source vulnerability concentrates in notified-body certification capacity for EU MDR compliance. Distribution runs through direct OEM relationships for integrated line builds and regional equipment distributors for standalone tunnel procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Early-cycle expansion characterizes this market as biologics contract manufacturing penetration accelerates and regulatory convergence between FDA and EU GMP Annex 1 standards forces simultaneous hardware and validation infrastructure upgrades.
For Market Incumbents: Insulate margin position through backward integration into precision conveyor component manufacturing and captive supply of validated SCADA systems. Hydrogen peroxide vapor tunnel technology from emerging specialists threatens premium positioning. Capacity addition in Hyderabad and Ahmedabad CDMO corridors anchors volume defense. For New Entrants and Emerging Players: Pursue robotic automation integration for cell and gene therapy cleanrooms where contamination risk premiums override price sensitivity. Massachusetts and Basel biologics clusters represent most penetrable demand pockets. Go-to-market execution through equipment-leasing partnerships with Indian PLI scheme beneficiaries bypasses capital barrier. For Investors and Strategic Acquirers: Flexible batch-size configurators with established EU notified-body relationships command scarcity premiums in biologics contract manufacturing expansion. Five-to-ten year viability hinges on regulatory validation automation capabilities. Monitor FDA guidance revision timing as inflection signal for replacement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Isolator-Tunnel Integration | Bundled platform procurement concentrates vendor selection to full-line integrators with downstream filling portfolios. |
| Robotic Infeed/Outfeed Automation | Collaborative robot deployment eliminates human intervention in high-value cell therapy cleanrooms. |
| Indian CDMO Corridor Expansion | Hyderabad and Ahmedabad sterile line modernization under PLI scheme incentives captures outbound equipment demand. |
| Outcome-Based Service Contracts | Guaranteed uptime agreements tied to validated sterilization performance generate recurring revenue streams. |
| Hydrogen Peroxide Vapor Technology Migration | Low-temperature chemical sterilization accommodates heat-sensitive polymer containers for gene therapy suites. |
Research Methodology
A standing panel of aseptic filling line engineers, pharmaceutical regulatory affairs leads, cleanroom commissioning specialists, and CDMO procurement directors provided ongoing calibration across primary interview cycles. Secondary validation drew from FDA sterile drug product guidance documents, EU GMP Annex 1 revision drafts, notified-body certification databases, and equipment vendor SEC filings. Bottom-up unit economics triangulated against top-down pharmaceutical capital expenditure patterns.
Scenario-bracketing framed low, base, and high cases across sterilizing agent chemistry, facility integration depth, and regional regulatory cluster adoption timelines. Segmentation dimensions spanned product type, application workflow, end-user capital deployment capacity, and mechanical conveyance architecture. CAGRs derived from replacement cycle compression analysis and greenfield facility investment pipelines. Industry-specific inputs included EU MDR traceability mandate implementation schedules and hydrogen peroxide vapor technology penetration curves in biologics suites.
Sensitivities concentrate around stainless steel commodity price trajectories, notified-body certification backlog resolution, and FDA guidance revision timing. Forecasts reflect documented assumptions on regulatory convergence pace and CDMO expansion cadence. Material shifts in EU MDR enforcement intensity or isolator technology substitution rates would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Infection Control
Hand Hygiene Products Market
Infection Control
Infection Surveillance Solutions Market
Infection Control
Salivary Gland Infection Market
Infection Control
Surgical Site Infection Control Market
Infection Control
Multi-Surface Disinfection Booster Systems with Low QAC Load Market
Infection Control
United States Hand Sanitizer Market
Infection Control
Global Disease Control and Prevention Vaccine Market
Infection Control
Salivary Gland Infection Treatment Market
Infection Control
Disinfection Equipment Market
Infection Control
Antimicrobial Hospital Curtains Market
Infection Control
Virus Filtration Market
Infection Control
Veterinary Disinfectant for Pets and Farms Market
Infection Control
Dental Infection Treatment Market
Infection Control
Biological and Chemical Indicators Market
Infection Control
Blood Stream Infection Testing Market
Infection Control
Medical Washer Disinfector Market