
 Medical Disinfectant Wipes Market | 2026-2036
Medical Disinfectant Wipes Market Size, Share, and Industry Trends Forecast 2026-2036
Medical Disinfectant Wipes Market Intelligence
The European Union's Biocidal Products Regulation (BPR) is unwinding the historical advantage of incumbent suppliers by tightening efficacy and safety data requirements. PDI Healthcare Inc. leverages its specialization in infection prevention to navigate these complex regulatory pathways. Metrex Research LLC sustains its market position through a focus on chemical formulation R&D for its surface disinfectants. Global consumer health giant The Clorox Company competes by extending its established brand recognition from consumer to clinical settings.
Medical disinfectant wipes are pre-moistened, single-use cloths saturated with a chemical agent designed to decontaminate surfaces in clinical environments. The substrate material, often a non-woven fabric, must ensure consistent liquid release and mechanical strength without leaving lint residue. Hospitals command the largest share among end-users, while the home care segment demonstrates significant expansion. Demand for biodegradable materials is influencing product design, though non-woven fabrics still dominate volume based on cost and performance.
Market access is governed by stringent efficacy testing protocols mandated by regulators like the US Environmental Protection Agency (EPA) and the European Chemicals Agency (ECHA). In parallel, quality systems for manufacturing are audited against standards such as ISO 13485 to ensure product consistency and safety for medical use. Future competitive advantage will hinge on developing formulations that balance high-level disinfection with improved material sustainability and user safety.
Market Dynamics
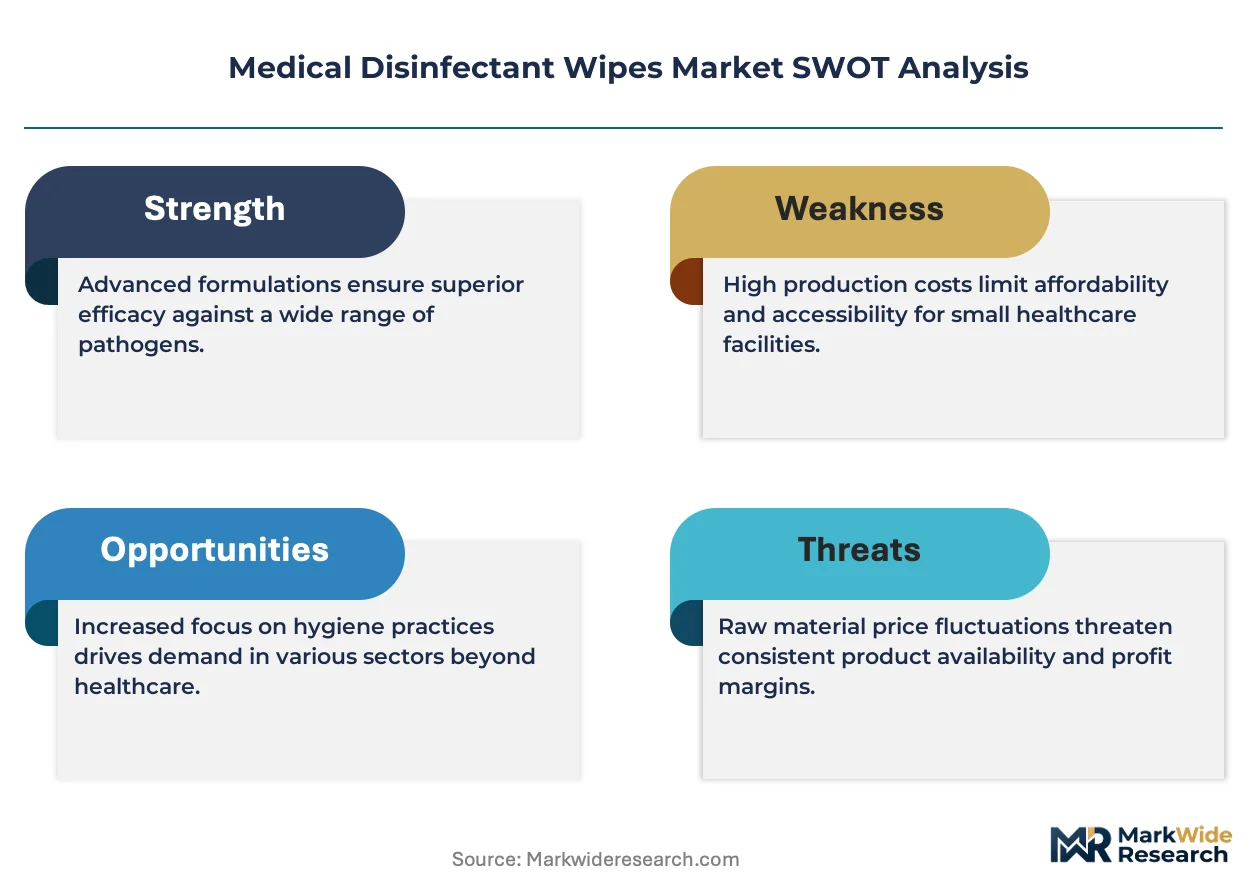
The central dynamic shaping the market is the tension between stringent regulatory demands for proven biocidal efficacy, exemplified by the EU's Biocidal Products Regulation (BPR), and the simultaneous market pull towards sustainable, biodegradable materials with lower chemical footprints.
Growth Catalysts
- Infection Control Mandates:Heightened protocols in hospitals and long-term care facilities to combat healthcare-associated infections (HAIs) create consistent, non-discretionary demand for certified surface disinfection products that comply with guidelines from bodies like the World Health Organization.
- Home Care Expansion:The growing prevalence of chronic diseases and an aging population are shifting patient care into home settings, expanding the user base for medical-grade disinfectant wipes beyond traditional clinical environments to ensure patient safety.
- Biodegradable Substrates:Product innovation focused on sustainable materials, such as wipes made from plant-based fibers like lyocell, addresses institutional ESG goals and consumer preference for environmentally responsible disposables, opening new product categories.
Market Restraints
- Input Cost Volatility:The pricing and availability of both non-woven fabrics and key active ingredients like quaternary ammonium compounds are subject to fluctuations in petrochemical and specialty chemical supply chains, impacting manufacturer margins.
- Regulatory Compliance Burden:The extensive and costly data requirements for product registration under authorities like the US Environmental Protection Agency (EPA) and European Chemicals Agency (ECHA) create significant barriers to entry for smaller firms.
- Material Compatibility Issues:Certain advanced biocidal agents can be incompatible with biodegradable substrates, leading to challenges in maintaining formulation stability and ensuring consistent disinfectant release over the product's shelf life, limiting material substitution.
Strategic Opportunities
- Emerging Market Penetration:Modernizing healthcare infrastructure in countries across Southeast Asia and Latin America presents significant opportunities for introducing established disinfectant wipe products as infection control standards are elevated in new hospitals and clinics.
- Specialty Formulations:There is an unmet need for wipes developed for specific applications, such as non-corrosive formulas for delicate electronic medical equipment or sporicidal wipes for terminal cleaning in high-risk areas like operating rooms.
- Smart Packaging Integration:Incorporating features like time-temperature indicators or wetness sensors into packaging can provide end-users with clear visual cues about product integrity and efficacy, offering a distinct point of differentiation and enhancing user confidence.
Industry Challenges
- Supply Chain Fragility:Dependence on a concentrated number of suppliers for specialized active pharmaceutical ingredients and medical-grade non-woven textiles creates vulnerability to disruptions, which can lead to production delays and stock shortages in healthcare settings.
- Extended Certification Timelines:The lengthy process for achieving and maintaining certifications, such as ISO 13485 for medical device quality management, and updating product registrations with new efficacy data can significantly slow the introduction of new or improved products.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medical Disinfectant Wipes Market |
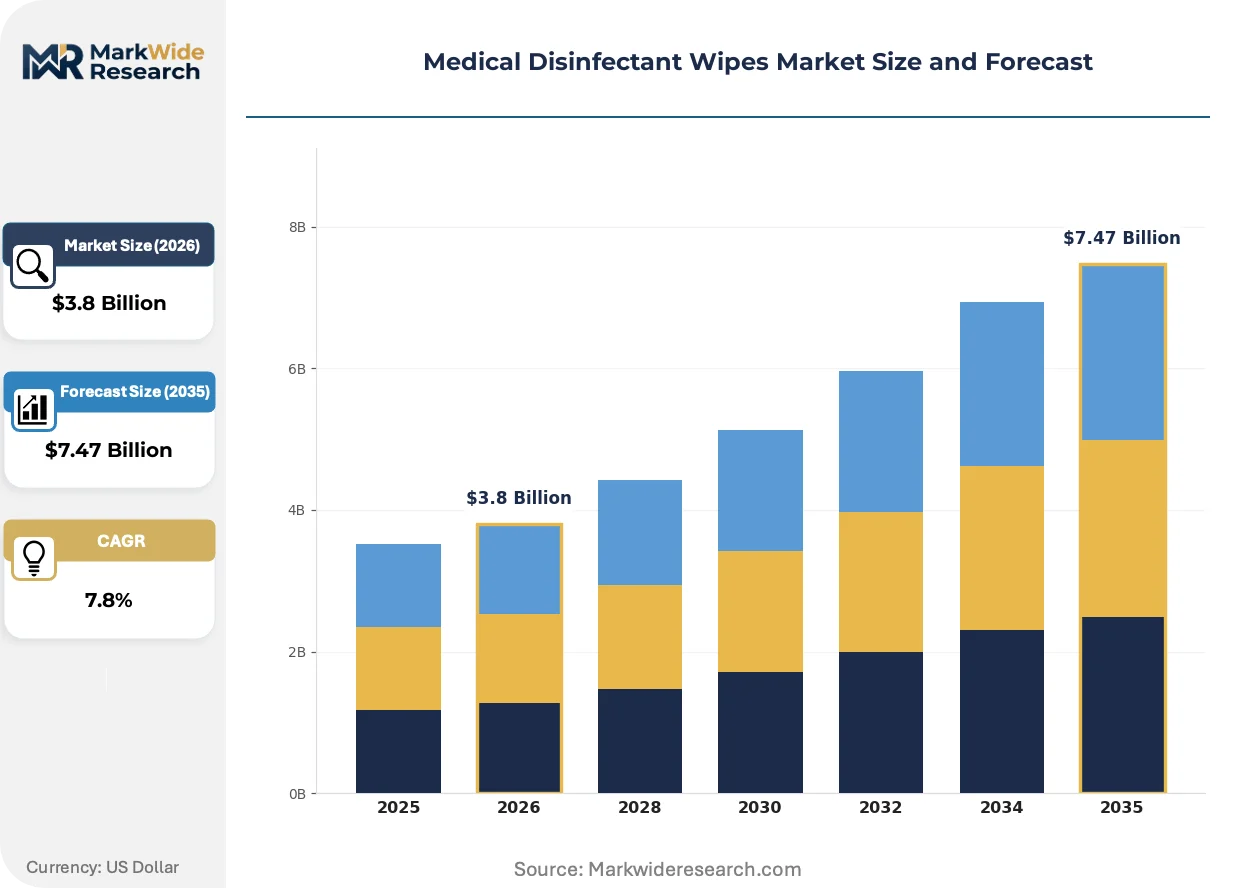
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.47 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Alcohol-Based, Chlorine-Based, Hydrogen Peroxide-Based, Quaternary Ammonium Compounds End User: Hospitals, Clinics, Laboratories, Home Care Material: Non-Woven Fabrics, Woven Fabrics, Biodegradable Materials, Plastic Packaging Type: Bottles, Canisters, Pouches, Tubs |
| Companies Covered | Reckitt Benckiser Group plc, PDI Healthcare Inc., Kimberly-Clark Corporation, Metrex Research LLC, Steris Corporation, The Clorox Company, Procter & Gamble, Ecolab Healthcare, 3M Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medical Disinfectant Wipes Market Strategic Shifts & Innovations
Material science advancements and evolving regulatory frameworks are concurrently defining product development cycles. This dual pressure forces manufacturers to balance the pursuit of novel, safer chemical formulations with the rigorous validation required to bring them to market.
Technology and Product Evolution
Formulations free from quaternary ammonium compounds or alcohol are gaining traction as a key product evolution. These wipes, which often use agents like hydrogen peroxide or hypochlorous acid, are designed to reduce chemical residue and mitigate occupational health risks for clinical staff. Hospitals and specialized clinics are gradually adopting these alternatives, particularly in sensitive environments, and this development is fragmenting the previously uniform market for general-purpose wipes.
Regulatory and Policy Shifts
The US Environmental Protection Agency's (EPA) rigorous registration process under the Federal Insecticide, Fungicide, and Rodenticide Act (FIFRA) mandates extensive efficacy data against a list of clinically relevant pathogens. This requirement forces manufacturers to continuously invest in laboratory testing to substantiate new kill claims, especially for emerging viral threats. Consequently, suppliers targeting the United States healthcare sector must maintain active R&D programs to ensure their product labels remain compliant and competitive.
Demand-Side and Behavioral Shifts
A notable behavioral shift is occurring in how healthcare systems purchase disinfectant products, moving from departmental buys to centralized, system-wide contracts. This trend disrupts the traditional sales model, as large Group Purchasing Organizations (GPOs) and integrated delivery networks consolidate purchasing power to secure favorable pricing on entire infection prevention portfolios. This procurement pattern is most advanced within the highly consolidated healthcare markets of the United States and Germany.
Medical Disinfectant Wipes Market Segmentation
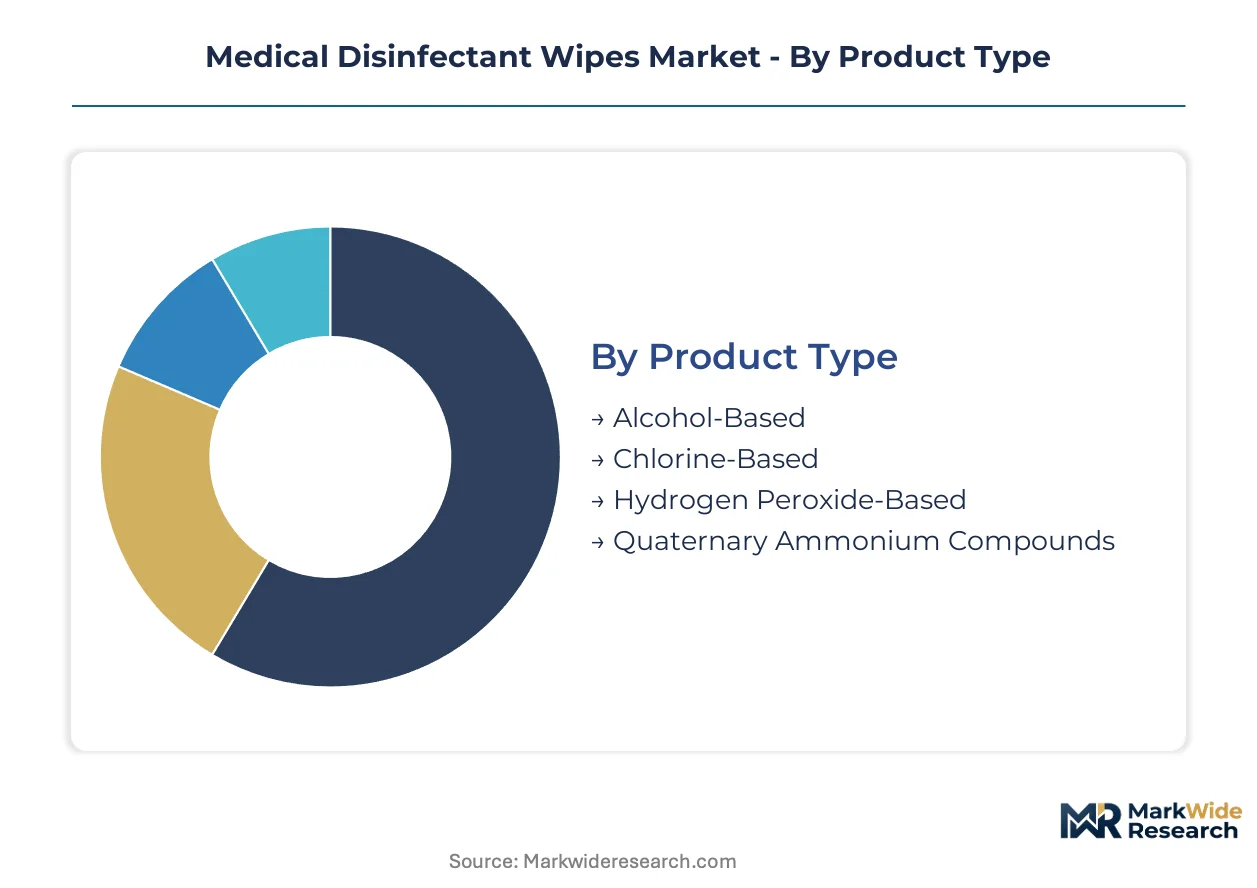
Segmentation analysis provides a granular view of the medical disinfectant wipes market, highlighting where specific product attributes and end-user needs intersect. This detailed breakdown helps manufacturers align product development with evolving regulatory landscapes and shifting demand patterns. Understanding these segments is crucial for strategic market positioning and resource allocation across diverse clinical environments.
Product Type:
Margin pools within product types often concentrate around novel, high-efficacy formulations that address specific pathogen challenges or reduce material compatibility issues.
- Quaternary Ammonium Compounds:These formulations are widely used for their broad-spectrum efficacy against bacteria and viruses, offering a cost-effective solution for routine disinfection. Demand remains consistently high in hospital settings and for general surface decontamination in the United States and Germany.
- Hydrogen Peroxide-Based:These wipes utilize hydrogen peroxide as an active ingredient, known for leaving minimal residue and offering a safer profile for users and delicate equipment. Their adoption is increasing in sensitive clinical areas and for specific electronic medical devices.
- Alcohol-Based:Characterized by rapid kill times, alcohol-based wipes are common for quick disinfection tasks, particularly on non-porous surfaces.
- Chlorine-Based:These potent formulations are reserved for high-level disinfection and terminal cleaning, especially in situations requiring sporicidal action.
Quaternary Ammonium Compounds hold significant installed capacity. Hydrogen Peroxide-Based formulations are rotating up the share rankings.
End User:
Application-specific requirements drive product differentiation and volume distribution across end-user segments.
- Hospitals:This segment represents the largest end-user category, driven by stringent infection control protocols and the high volume of patient interactions. Hospitals demand broad-spectrum efficacy and compliance with guidelines from organizations like the World Health Organization.
- Home Care:The home care segment is expanding significantly, fueled by an aging population and the growing prevalence of chronic diseases requiring at-home patient management. Products for this segment prioritize ease of use and safety for non-professional caregivers.
- Clinics:Clinics maintain consistent demand for disinfectant wipes for routine surface decontamination in examination rooms and waiting areas.
- Laboratories:Specialized needs for decontamination of scientific equipment and sterile surfaces characterize the demand from laboratory environments.
The home care segment exhibits the steepest expansion trajectory, while hospitals maintain foundational demand.
Material:
The cost tier of substrate materials significantly influences the final product's market positioning and sustainability profile.
- Non-Woven Fabrics:These materials dominate the market due to their cost-effectiveness, consistent liquid release properties, and adequate mechanical strength without leaving lint. Demand is substantial in high-volume clinical settings globally, including Germany and Japan.
- Biodegradable Materials:Product innovation focuses on sustainable materials like plant-based fibers, addressing institutional environmental, social, and governance (ESG) goals. Demand is growing from healthcare providers prioritizing environmentally responsible disposables, particularly in European markets.
- Woven Fabrics:Less common for general-purpose wipes, woven fabrics are typically higher cost and used for specialized, often reusable, applications.
- Plastic:Direct use of plastic as a primary wipe material is limited; however, synthetic fibers derived from plastic are components in many non-woven wipe substrates.
Innovation in biodegradable materials is attracting significant investment, while non-woven fabrics maintain substantial supply concentration.
Packaging Type:
Customer convenience and usage environment dictate the preferred packaging types across clinical and home settings.
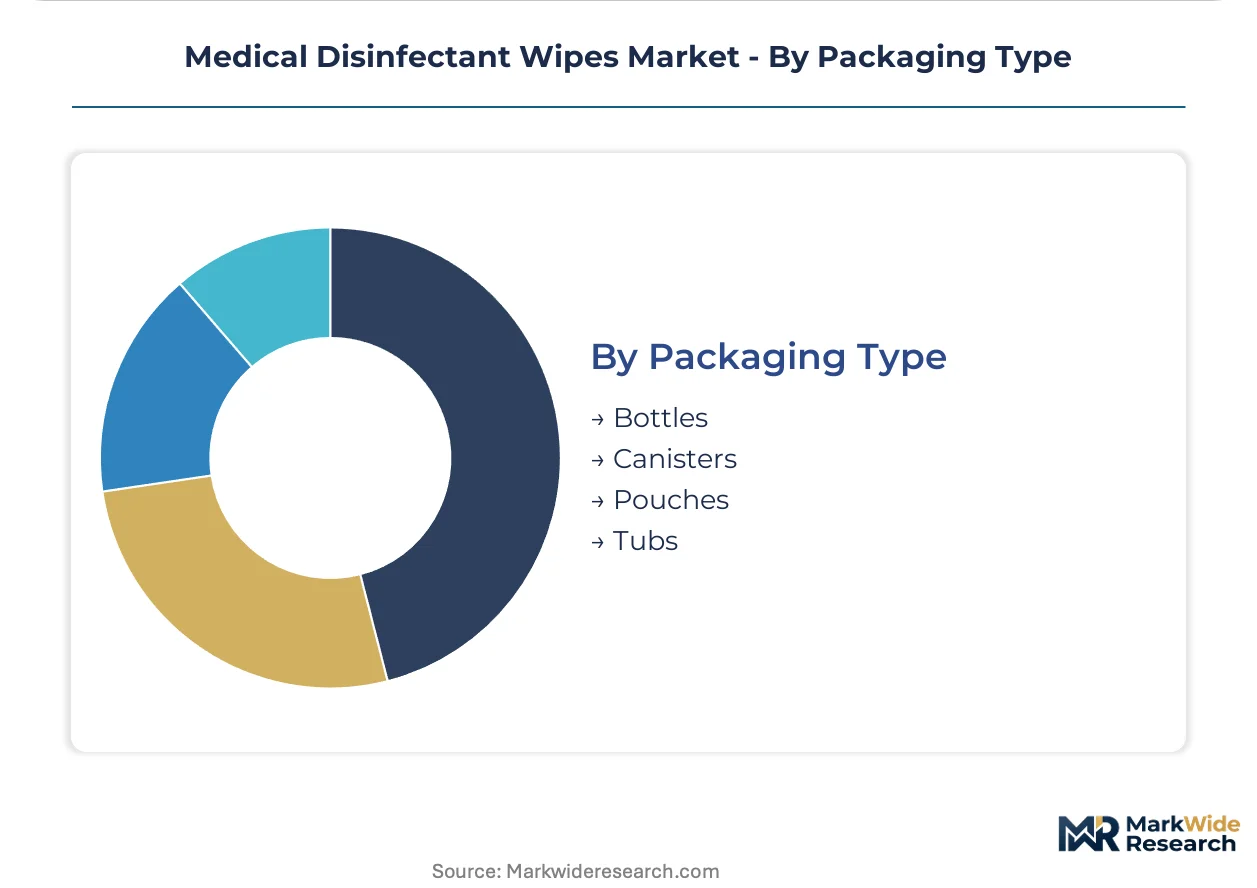
- Canisters:These are the most common packaging type, offering easy dispensing and re-sealable features for high-volume, frequent use. Hospitals and clinics in the United States widely adopt canister packaging.
- Pouches:Pouches provide flexible and portable solutions, often available in single-use or smaller pack sizes, suitable for home care settings and emergency medical kits. This format supports mobile healthcare applications.
- Bottles:While less common for wipes, bottles are primarily used for liquid disinfectants that may be applied with separate cloths.
- Tubs:Similar to canisters but often larger, tubs are designed for high-usage environments where a greater quantity of wipes is needed.
Canisters hold the largest market preference due to their practical design, while pouches are gaining traction for portable applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospitals and integrated delivery networks represent a significant buyer archetype across developed healthcare markets. These large-scale purchasers influence demand patterns for medical disinfectant wipes. Stringent infection control mandates drive consistent product procurement globally.
United States
Demand for medical disinfectant wipes in the United States is consistently high due to extensive hospital networks and a large home care segment. The US Environmental Protection Agency (EPA) mandates rigorous efficacy testing for all biocidal products, impacting market access. Major metropolitan areas like New York and Los Angeles see concentrated procurement by large Group Purchasing Organizations.
Germany
Germany's advanced healthcare system drives substantial demand for high-quality medical disinfectant wipes, particularly in hospital settings. The European Union's Biocidal Products Regulation (BPR) imposes strict data requirements for product registration and market entry. The Rhine-Main region, a hub for pharmaceutical and chemical industries, supports innovation in disinfectant formulations.
Japan
An aging population and a focus on preventative healthcare contribute to steady demand for medical disinfectant wipes across Japanese hospitals and clinics. The Ministry of Health, Labour and Welfare (MHLW) oversees medical device and disinfectant regulations, emphasizing product safety and efficacy. Tokyo's extensive healthcare infrastructure drives significant volume for infection prevention supplies.
China
Expanding healthcare infrastructure and increased awareness of infection control in China are boosting demand for medical disinfectant wipes. The National Medical Products Administration (NMPA) regulates medical devices and disinfectants, shaping product development and market access. Coastal economic zones, such as the Yangtze River Delta, exhibit rapid adoption of modern clinical hygiene practices.
United Kingdom
Hospitals and long-term care facilities in the United Kingdom prioritize medical disinfectant wipes to comply with National Health Service (NHS) infection control guidelines. Post-Brexit, the UK still largely aligns with European Union standards like the BPR for biocidal product approvals. London's numerous hospitals and private clinics form a significant demand cluster for advanced cleaning solutions.
Medical Disinfectant Wipes Market Key Industry Players
Player mix skews toward established chemical and consumer health conglomerates, alongside specialized medical device and hygiene providers. The market structure exhibits a moderate concentration, with several large entities holding significant shares through extensive distribution networks. Strategic archetypes include dedicated infection prevention specialists, chemical formulation innovators, and broad-portfolio consumer health firms leveraging their brand recognition. Dominant competitive moves involve continuous research and development for novel chemical formulations and strategic partnerships to expand market access in new healthcare segments.
Specialists in infection prevention solutions, such as PDI Healthcare Inc., exemplify focused expertise in navigating complex regulatory pathways and delivering targeted clinical products. Global consumer health entities like The Clorox Company represent the leverage of established brand recognition and extensive distribution networks to extend their offerings into clinical settings. Meanwhile, Metrex Research LLC occupies a position anchored by its emphasis on chemical formulation research and development, continuously innovating surface disinfectants to meet evolving efficacy and safety standards. These companies collectively demonstrate the varied approaches to maintaining market presence in the medical disinfectant wipes sector.
| Leading Market Players |
|---|
| Reckitt Benckiser Group plc |
| PDI Healthcare Inc. |
| Kimberly-Clark Corporation |
| Metrex Research LLC |
| Steris Corporation |
| The Clorox Company |
| Procter & Gamble |
| Ecolab Healthcare |
| 3M Company |
| Others |
Cost & Logistics Intelligence
Extended procurement lead times for specialized non-woven fabrics and active ingredients directly influence pricing power, especially for manufacturers reliant on concentrated supply regions. This dynamic creates a tension between cost efficiency and supply resilience, impacting overall market stability.
Pricing Analysis
Cost-plus contract patterns, often indexed to petrochemical and specialty chemical prices, dominate procurement for large healthcare systems. Premium-mid-economy pricing differentiation exists, driven by certification levels like ISO 13485 compliance and established brand recognition. Pricing softness stems from intense competition among suppliers and the consolidated purchasing power of Group Purchasing Organizations in the United States and Germany. The home care segment exhibits higher price sensitivity compared to hospitals, which prioritize efficacy and regulatory compliance.
Supply Chain Analysis
China and the United States anchor the production of key active ingredients and non-woven fabric components for medical disinfectant wipes. The supply chain draws from specialized chemical producers for quaternary ammonium compounds and hydrogen peroxide. Single-source vulnerability for certain advanced biocidal agents poses a structural risk, leading to potential production delays. Distribution runs through a dual model, with direct sales channels for large hospital networks and third-party distributors serving smaller clinics and the expanding home care segment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The medical disinfectant wipes market is experiencing a significant shift in buyer power, primarily driven by the consolidation of purchasing entities such as Group Purchasing Organizations (GPOs) in developed healthcare markets.
For Market Incumbents: Secure long-term supply agreements for critical raw materials to mitigate input cost volatility. Invest in research and development for sustainable, biodegradable formulations to address evolving regulatory demands like the EU's BPR and institutional ESG goals. Strengthen relationships with large GPOs through tailored product portfolios and value-added services to counter competitive threats from new entrants and maintain market share against established rivals.
For New Entrants and Emerging Players: Anchor in niche application areas, such as non-corrosive wipes for delicate electronic medical equipment or sporicidal formulations for high-risk clinical environments. The home care segment in rapidly modernizing healthcare infrastructures across Southeast Asia presents a penetrable market. A go-to-market strategy focusing on superior material sustainability and user safety, backed by robust efficacy data, can differentiate offerings.
For Investors and Strategic Acquirers: Carve-out targets emerge from chemical and consumer health conglomerates seeking to divest non-core hygiene assets. The long-term viability of this market is strong, driven by non-discretionary infection control demand. Acquisition targets should possess strong intellectual property in novel chemical formulations or advanced biodegradable substrate technologies. A signal to watch is an increase in regulatory approvals for new, environmentally friendly biocidal agents.
| Strategic Initiative | Industry Significance |
|---|---|
| R&D in Biodegradable Substrates | This initiative enables compliance with environmental regulations and meets growing demand for sustainable products from healthcare providers. |
| Regulatory Pathway Acceleration | Streamlining product registration under agencies like the US EPA ensures faster market access for novel formulations. |
| GPO Contract Optimization | Securing favorable terms with large Group Purchasing Organizations enhances market penetration and volume stability in hospitals. |
| Emerging Market Expansion | Penetrating new healthcare infrastructure in regions like Southeast Asia unlocks significant untapped demand. |
| Specialty Formulation Development | Creating targeted wipes for specific applications, such as medical electronics, addresses unmet clinical needs and commands premium pricing. |
Research Approach
Initial hypotheses were tested against primary input from hospital procurement managers, infection control specialists, chemical engineers, and regulatory affairs leads, and refined through iterative feedback loops. This primary research was triangulated with extensive secondary validation, drawing from US EPA filings, ECHA BPR dossiers, World Health Organization guidelines, and ISO 13485 audit reports. Both bottom-up and top-down analytical approaches were employed to ensure data accuracy and comprehensive market coverage.
Variance decomposition formed the basis of the forecast framework, disaggregating market growth into its constituent drivers across the analysis window. Segmentation dimensions modeled included product type, end user, material, packaging type, and regional regulatory compliance. Compound Annual Growth Rates were derived from historical trends and projected market drivers, with industry-specific inputs like healthcare-associated infection prevalence rates and new biocidal agent approvals feeding the model.
Decision-makers should treat outputs as directional under current regulatory frameworks and supply chain stability; material deviation would warrant model refresh. Unforeseen pandemic events or sudden shifts in raw material costs represent specific risk factors that could revise forecasts. Recalibration cycles align with material shifts in named drivers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Infection Control
Middle East and Africa Hand Sanitizer Market
Infection Control
Preventable Vaccines Market
Infection Control
Intra-Amniotic Infection Treatment Market
Infection Control
Sterilization Technologies Market
Infection Control
Infection Control Surveillance Solutions Market
Infection Control
Germicidal UV Lamp Market
Infection Control
Ultrasound Probe Disinfection Market
Infection Control
Hygiene Stations Market
Infection Control
Global Dental Infection Control Products Market
Infection Control
Australia Healthcare Surface Disinfectant Wipes Market
Infection Control
Healthcare Associated Infections (HAI) Treatment Market
Infection Control
Infection Control Supplies Market
Infection Control
Global High Level Disinfection Services Market
Infection Control
Biological and Chemical Indicators Market
Infection Control
Global Disease Control and Prevention Vaccine Market
Infection Control
Patient Hygiene Aids Market