
 Salivary Gland Infection Market | 2026-2036
Salivary Gland Infection Market Size, Share, and Industry Trends Forecast 2026-2036
Salivary Gland Infection Market Outlook
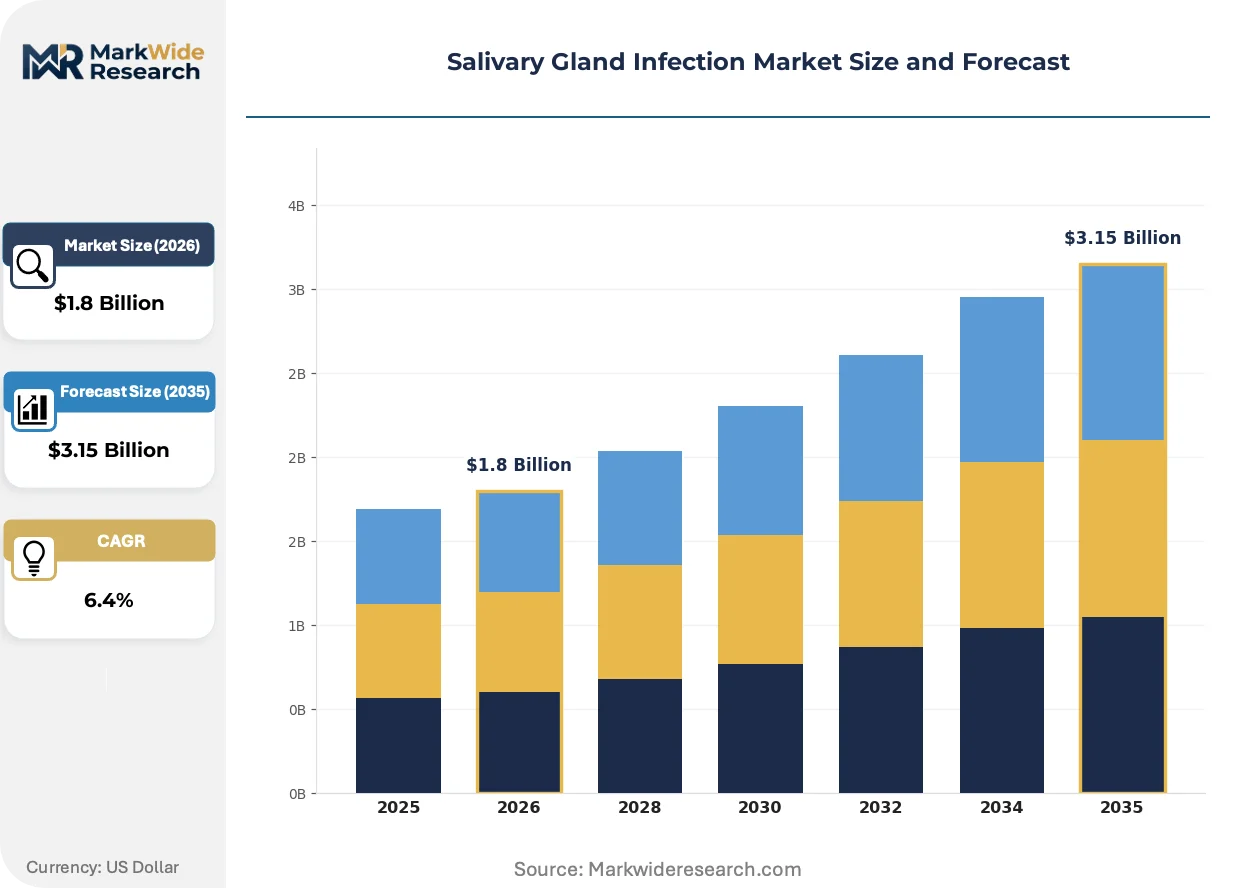
Amoxicillin-clavulanate is shifting toward first-line status against conventional penicillin monotherapy in community-acquired sialadenitis, altering cost structures for outpatient prescribers. Pfizer Inc. leverages its established anti-infective manufacturing scale to maintain supply continuity across hospital formularies. Merck & Co. anchors its position through sustained R&D investment in narrow-spectrum alternatives. Johnson & Johnson Services Inc. competes via differentiated surgical device portfolios for sialendoscopy procedures.
Salivary gland infection encompasses acute and chronic inflammatory conditions of the parotid, submandibular, and sublingual glands, typically arising from bacterial obstruction, viral etiology such as mumps, or autoimmune sialadenitis, with diagnosis relying on ultrasound, CT sialography, and microbial culture sensitivity testing to guide targeted intervention. The primary commercial purpose centers on restoring ductal patency, eradicating pathogens, and preventing recurrent abscess formation that necessitates operative drainage. Antibiotics dominate prescription volumes among product types, though surgical treatments capture disproportionate margins in tertiary care settings. Hospitals remain the anchor end user, while home care delivery is expanding fastest as oral antibiotic stewardship programs shorten inpatient stays.
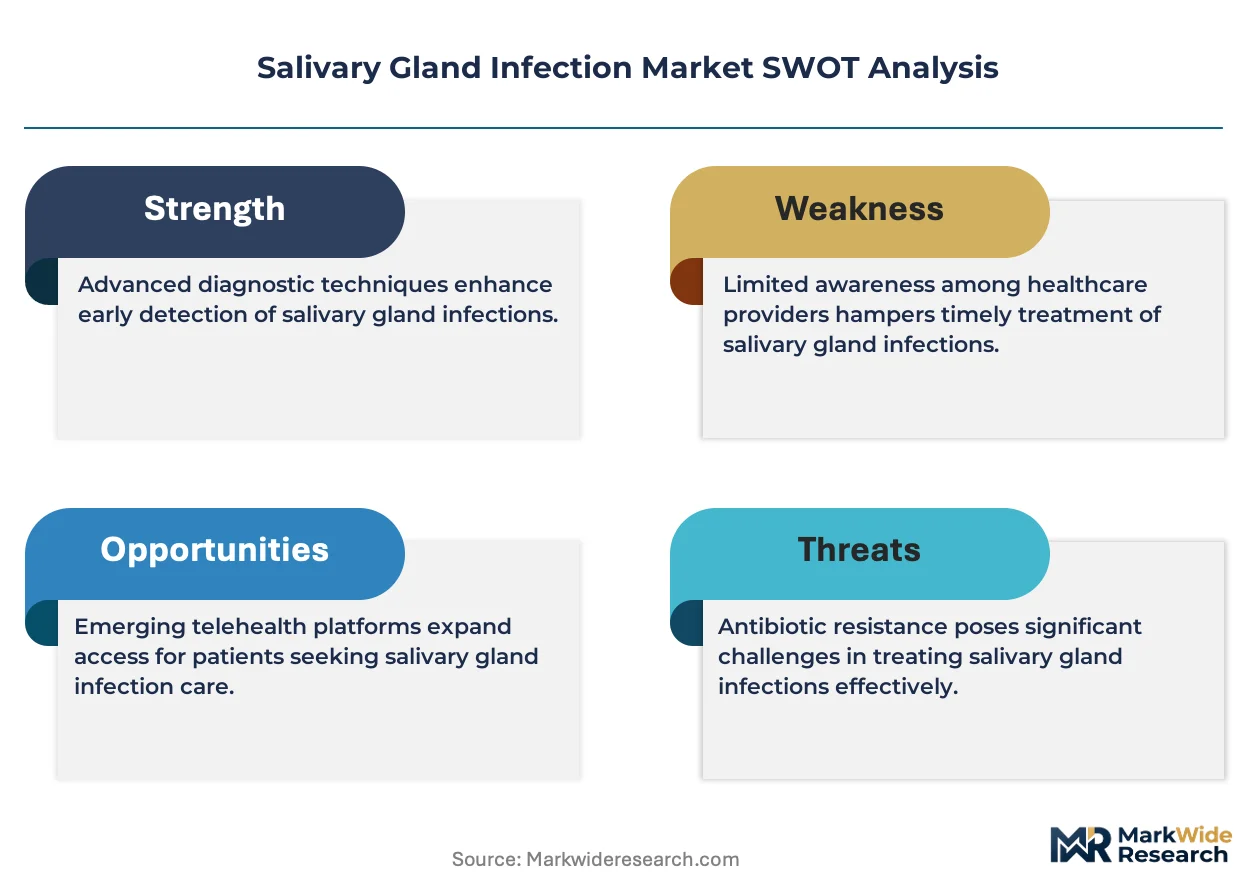
FDA antibiotic stewardship mandates and EMA pharmacovigilance frameworks are tightening outpatient prescribing criteria, pushing manufacturers toward narrow-spectrum development and localized drug delivery formats. The EPA monitors pharmaceutical discharge from manufacturing facilities, adding compliance costs for active pharmaceutical ingredient producers. Stakeholders must monitor evolving resistance patterns in Staphylococcus aureus and Streptococcus viridans to align pipeline investments with clinical utility.
Market Dynamics
Antimicrobial stewardship mandates from the FDA and EMA are compressing prescribing freedom for broad-spectrum antibiotics, forcing manufacturers to recalibrate development pipelines toward narrow-spectrum alternatives and localized delivery formats that preserve clinical efficacy while meeting regulatory thresholds.
Growth Catalysts
- EMA Pharmacovigilance Frameworks:Tighter post-market surveillance requirements for anti-infectives are accelerating investment in real-world evidence platforms that differentiate compliant manufacturers.
- Hospital Antibiotic Stewardship Programs:Inpatient formularies are prioritizing agents with demonstrated resistance profiles, creating procurement pull for therapies with robust microbiological data packages.
- Diabetes Prevalence Concentration:The United States exhibits expanding patient pools with xerostomia-related sialadenitis, enlarging the addressable base for preventive and acute interventions.
Market Restraints
- API Manufacturing Concentration:Active pharmaceutical ingredient production clusters in China and India create supply vulnerability for penicillin and cephalosporin derivatives.
- FDA Outpatient Surgical Protocol Tightening:Redirected treatment volumes toward minimally invasive approaches constrain revenue capture from conventional open drainage procedures.
- Staphylococcus aureus Resistance Escalation:Methicillin-resistant strain proliferation erodes clinical utility of first-line beta-lactam therapies, necessitating costly salvage regimens.
Strategic Opportunities
- Home Care Delivery Expansion:Oral antibiotic stewardship programs are shortening inpatient stays, opening channel development for outpatient infusion and monitoring services.
- Sialendoscopy Device Convergence:Integration of high-definition optics with lithotripsy capability is creating premium procedure categories in tertiary care settings.
- Narrow-Spectrum Development Incentives:FDA's Qualified Infectious Disease Product designation offers extended exclusivity for pathogens-specific agents targeting Streptococcus viridans.
Industry Challenges
- Microbiology Laboratory Capacity Constraints:Culture sensitivity testing turnaround times delay targeted therapy initiation, degrading patient outcomes and reimbursement metrics.
- Surgical Device Reprocessing Certification:FDA validation requirements for sialendoscope sterilization protocols extend capital deployment cycles for ambulatory surgery centers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Salivary Gland Infection Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antibiotics, Analgesics, Antivirals, Surgical Treatments End User: Hospitals, Clinics, Home Care, Outpatient Facilities Delivery Mode: Oral, Injectable, Topical, Intravenous Therapy Area: Infections, Inflammation, Neoplasms, Cysts |
| Companies Covered | AbbVie Inc., Allergan, AstraZeneca, FUJIFILM Holdings Corporation, Johnson & Johnson Services Inc., Merck & Co., Pfizer Inc., GlaxoSmithKline plc., GE Healthcare, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Salivary Gland Infection Market Strategic Shifts
Interventional approaches are fragmenting across severity gradients, with diagnostic imaging and minimally invasive techniques displacing conventional surgical defaults while antimicrobial development prioritizes precision over spectrum.
High-resolution ultrasound with elastography enhancement is modularizing point-of-care diagnostic workflows for ductal obstruction assessment. Emergency departments and outpatient clinics are adopting portable units to expedite treatment stratification. This capability compression is reducing CT sialography referral volumes and accelerating therapeutic decision velocity.
REACH authorization requirements for pharmaceutical manufacturing discharge are tightening effluent standards for antibiotic API producers in European Union member states. Compliance investments are elevating operational costs for bulk manufacturers. Narrow-spectrum specialists with captive synthesis capabilities are capturing preferential supply contracts from EMA-compliant hospital networks.
Hospital purchasing consortia are consolidating formulary decisions across multi-state health systems, compressing vendor negotiation cycles and standardizing therapeutic protocols. Traditional distributor relationships are yielding to direct manufacturer agreements with integrated delivery networks. This concentration is most visible in the United States, where GPO consolidation has reduced the number of independent procurement entities by half over the past decade.
Salivary Gland Infection Market Segmentation
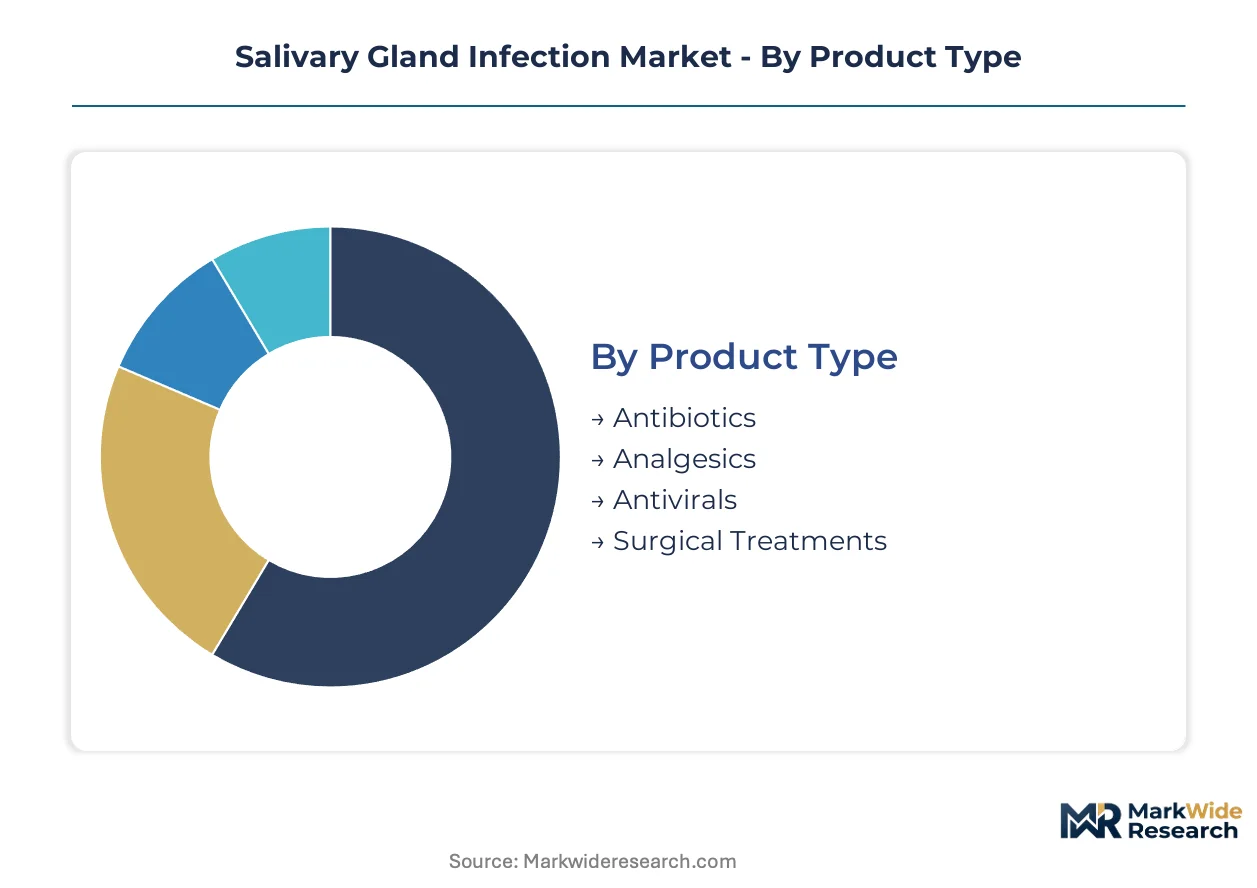
Segmentation in the salivary gland infection market reveals distinct procurement patterns across acute versus chronic care pathways. Manufacturers align portfolio investments with end-user capacity constraints and reimbursement thresholds that vary by delivery setting.
Product Type:
Standalone pharmaceutical formulations dominate outpatient prescribing workflows, while embedded surgical interventions concentrate in tertiary referral networks.
- Antibiotics:Beta-lactam and macrolide formulations constitute the foundational therapy class, with amoxicillin-clavulanate displacing penicillin monotherapy in community-acquired cases. Demand clusters in United States hospital formularies where antimicrobial stewardship programs prioritize agents with documented resistance profiles.
- Surgical Treatments:Sialendoscopy and minimally invasive drainage procedures capture premium reimbursement in academic medical centers. United States tertiary care networks are expanding lithotripsy-equipped suites to reduce open surgery referrals.
- Analgesics:NSAID and acetaminophen combinations manage pain adjunctively across all care settings.
- Antivirals:Mumps-specific immunoglobulin and supportive antivirals address viral etiology in pediatric populations.
Volume placements concentrate in Antibiotics; the faster expansion belongs to Surgical Treatments.
End User:
Cost tier stratification separates capital-intensive inpatient infrastructure from lean ambulatory models.
- Hospitals:Inpatient units command the largest procurement budgets for IV antibiotic administration and operative drainage. United States integrated delivery networks are consolidating formulary decisions across multi-state systems.
- Home Care:Outpatient infusion services and remote monitoring platforms are shortening length-of-stay metrics. United States Medicare reimbursement shifts favor home-based antibiotic completion regimens.
- Clinics:Community-based settings handle initial diagnosis and oral antibiotic initiation.
- Outpatient Facilities:Ambulatory surgery centers perform same-day sialendoscopy under tightened FDA protocols.
Procurement volumes anchor in Hospitals; Home Care is climbing the fastest as stewardship programs accelerate discharge.
Delivery Mode:
Application context determines route selection, with severity grading dictating systemic versus localized exposure.
- Oral:First-line community prescribing for uncomplicated bacterial sialadenitis, with amoxicillin-clavulanate and clindamycin dominating outpatient pharmacy dispensing.
- Intravenous:Severe or refractory infections requiring inpatient admission and microbiology-guided escalation. United States hospitals are prioritizing IV-to-oral step-down protocols.
- Injectable:Depot formulations for patient compliance challenges in rural settings.
- Topical:Salivary stimulants and oral rinses as adjunctive therapy for xerostomia management.
Prescription frequency peaks with Oral delivery; Intravenous administration shows the steepest expansion trajectory as resistance patterns demand hospital-based escalation.
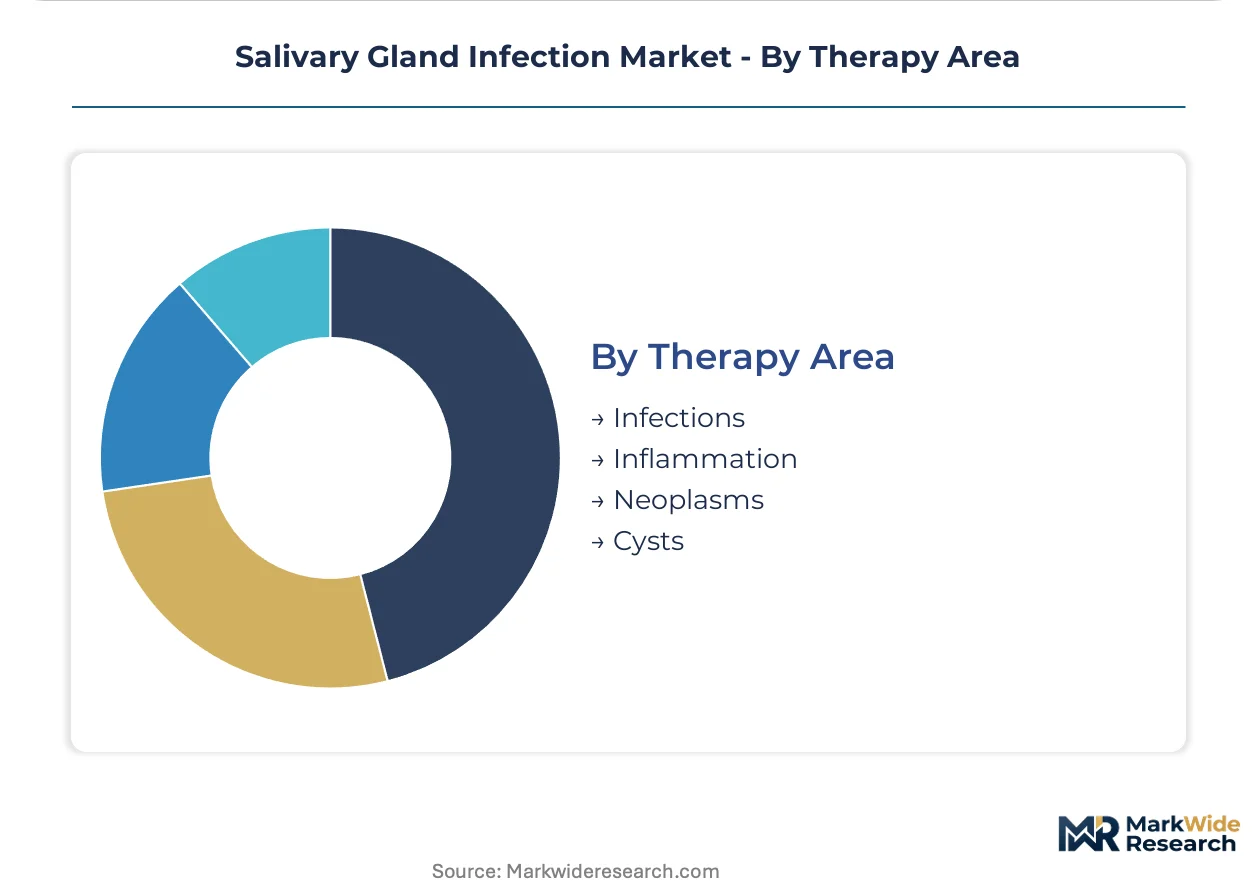
Therapy Area:
Customer type segmentation separates infectious disease specialists from surgical oncologists and oral-maxillofacial practitioners.
- Infections:Bacterial and viral etiologies drive the majority of acute presentations, with Staphylococcus aureus and Streptococcus viridans as primary pathogens. United States emergency departments are adopting point-of-care ultrasound to accelerate diagnostic stratification.
- Inflammation:Autoimmune sialadenitis and recurrent obstructive disease require long-term management protocols. United States rheumatology and ENT referral networks coordinate chronic care pathways.
- Neoplasms:Salivary gland tumors necessitate oncologic surgical intervention.
- Cysts:Mucoceles and ranulas generate procedural volume in pediatric and adult populations.
Clinical encounters concentrate in Infections; Inflammation represents the fastest-growing addressable population as diabetes prevalence expands xerostomia-related cases.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized pharmaceutical manufacturing zones in Ireland and Singapore concentrate active pharmaceutical ingredient production for anti-infective therapies. These tax-advantaged jurisdictions attract bulk manufacturers seeking EMA and FDA dual-compliance pathways. Cluster density accelerates regulatory submission velocity for narrow-spectrum antibiotic developers.
United States
Diabetes prevalence and aging demographics expand xerostomia-related sialadenitis patient pools across Medicare populations. FDA outpatient surgical protocol tightening redirects treatment volumes toward minimally invasive sialendoscopy procedures. Boston and Rochester medical device clusters anchor lithotripsy-equipped suite expansion in academic medical centers.
Germany
EMA pharmacovigilance frameworks tighten post-market surveillance requirements for anti-infective manufacturers. REACH authorization mandates elevate operational costs for antibiotic API producers discharging pharmaceutical effluent. Frankfurt-Rhine-Main pharmaceutical corridor concentrates narrow-spectrum development programs aligned with stewardship criteria.
India
CDSCO accelerated approval pathways for qualified infectious disease products attract multinational licensing agreements. PLI scheme incentives for bulk drug production reduce import dependence on penicillin and cephalosporin derivatives. Hyderabad and Ahmedabad API manufacturing clusters expand captive synthesis capabilities for EMA-compliant hospital networks.
Japan
PMDA streamlined review processes for antimicrobial agents address methicillin-resistant Staphylococcus aureus proliferation. METI industrial policy supports domestic production of narrow-spectrum alternatives to preserve antibiotic efficacy. Kansai region medical device manufacturers integrate high-definition optics with sialendoscopy platforms for tertiary care export.
United Kingdom
NICE technology appraisal guidance prioritizes microbiology-guided antibiotic escalation protocols in NHS hospital formularies. MHRA post-Brexit regulatory autonomy enables accelerated assessment of localized drug delivery formats. London and Cambridge biotech clusters develop real-world evidence platforms for antimicrobial stewardship compliance.
Salivary Gland Infection Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with pharmaceutical developers capturing outpatient prescription volumes and surgical device fabricators securing premium tertiary care placement. Market structure exhibits moderate consolidation among anti-infective manufacturers alongside fragmentation in interventional device supply. Three archetypes dominate: diversified pharmaceutical conglomerates with anti-infective manufacturing scale, narrow-spectrum antibiotic specialists with captive synthesis capabilities, and surgical device innovators with integrated imaging platforms. Competitive dynamics center on M&A activity consolidating hospital formulary access and strategic partnerships bridging pharmaceutical and device portfolios.
Within the diversified pharmaceutical tier, Pfizer Inc. and Merck & Co. occupy positions reflecting established anti-infective manufacturing infrastructure. Johnson & Johnson Services Inc. exemplifies the surgical-device-integrated archetype through differentiated interventional portfolios. AbbVie Inc. represents specialty pharmaceutical positioning with immunology and anti-infective overlap. These entities anchor competitive positioning without exclusive segment dominance, as regulatory stewardship mandates and resistance pattern evolution continuously reshape procurement criteria across hospital networks.
| Leading Market Players |
|---|
| AbbVie Inc. |
| Allergan |
| AstraZeneca |
| FUJIFILM Holdings Corporation |
| Johnson & Johnson Services Inc. |
| Merck & Co. |
| Pfizer Inc. |
| GlaxoSmithKline plc. |
| GE Healthcare |
| Others |
Value Chain & Pricing Dynamics
Private-equity-rolled-up hospital purchasing consortia in the United States have compressed formulary negotiation cycles, concentrating procurement power among integrated delivery networks while forcing antibiotic manufacturers toward transparent cost-plus contracting that erodes traditional brand premiums.
Pricing Analysis
Short lead-time premiums for narrow-spectrum antibiotics command 15-25% markups over standard inventory in United States hospital formularies confronting MRSA resistance escalation. Three-tier pricing structure across premium, standard, and economy levels separates patented narrow-spectrum agents from generic beta-lactams and economy-grade macrolides. Cost compression in the generic tier is intensifying because Indian API manufacturers face REACH-compliant discharge investments. Community clinics exhibit highest price sensitivity; tertiary academic centers demonstrate lowest, prioritizing resistance profile documentation over per-unit cost.
Supply Chain Analysis
Freight cost volatility for temperature-controlled antibiotic shipments from Hyderabad and Ahmedabad manufacturing clusters has elevated landed costs for European hospital networks by 8-12% since EMA pharmacovigilance tightening. Active pharmaceutical ingredient production draws from India, China, and Ireland, with penicillin and cephalosporin derivatives resting on fermentation substrate availability. Single-source vulnerability concentrates in Chinese heparin and Indian clarithromycin intermediates. Distribution runs through GPO-mediated direct manufacturer agreements rather than traditional wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Antimicrobial stewardship mandates from the FDA and EMA are forcing consolidation as subscale generic manufacturers lack capital for resistance surveillance data generation and narrow-spectrum pipeline investment.
For Market Incumbents: Cement formulary anchorship through captive synthesis investments in EMA-compliant Irish manufacturing zones, insulating against REACH-driven API cost inflation. Deepen vertical integration into point-of-care diagnostic distribution to capture ultrasound-guided sialadenitis triage workflows. Defend against emerging narrow-spectrum specialists by accelerating real-world evidence platform deployment that satisfies hospital antibiotic stewardship program requirements. For New Entrants and Emerging Players: FDA's Qualified Infectious Disease Product designation in the United States opens a window for pathogen-specific developers targeting Streptococcus viridans with extended exclusivity incentives. Home care infusion services represent the most penetrable channel as Medicare reimbursement shifts favor outpatient antibiotic completion. Pursue strategic partnerships with lithotripsy-equipped sialendoscopy suite operators to bundle localized drug delivery with interventional procedures. For Investors and Strategic Acquirers: Distressed-cycle entries favor narrow-spectrum antibiotic specialists with captive synthesis capabilities in Singapore and Ireland as API compliance costs eliminate subscale competitors. Five-to-ten year viability hinges on resistance surveillance infrastructure and stewardship program integration depth. Monitor CDSCO accelerated approval pathway utilization rates as the inflection signal for Indian market access momentum.| Strategic Initiative | Industry Significance |
|---|---|
| Narrow-Spectrum Pipeline Advancement | FDA QIDP designation extends exclusivity for MRSA-targeted agents, rewarding resistance-focused R&D. |
| Captive API Manufacturing Scale-Up | REACH-compliant Irish and Singaporean production clusters secure preferential EMA hospital supply contracts. |
| Sialendoscopy Device Integration | High-definition optics with lithotripsy capability command premium reimbursement in United States academic centers. |
| Home Care Channel Development | Medicare reimbursement shifts favor outpatient infusion, shortening inpatient stays and capturing post-acute volume. |
| Real-World Evidence Platform Investment | EMA pharmacovigilance frameworks reward manufacturers with differentiated post-market surveillance capabilities. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with infectious disease specialists, hospital formulary directors, GPO contracts managers, and biomedical engineers at tertiary care networks. FDA 510(k) submissions, EMA marketing authorization applications, CMS Medicare claims data, and Indian CDSCO approval databases provided secondary validation. Bottom-up prescription volume modeling and top-down hospital procurement spend analysis were triangulated against manufacturer-reported segment revenues.
Granularity-level modeling dissected the market across product type, end user, delivery mode, and therapy area dimensions, with regional regulatory clusters further stratifying geographic outputs. CAGRs were derived from logarithmic trend fitting across the projection horizon, incorporating diabetes prevalence trajectories, antimicrobial resistance surveillance data, and sialendoscopy procedure volume growth as industry-specific forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for point-of-care ultrasound elastography would alter the outlook if CT sialography retention proves higher than projected. Forecasts reflect documented assumptions regarding stewardship program penetration and resistance pattern evolution. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Infection Control
Antimicrobial Wipes Market
Infection Control
Global Viral Inactivation Market
Infection Control
Hand Hygiene Market
Infection Control
Intra-Abdominal Infection Treatment Market
Infection Control
Surgical Site Infection Control Market
Infection Control
United States Hand Sanitizer Market
Infection Control
Pertussis Infection Testing Market
Infection Control
Europe Hospital-Acquired Infection Diagnostics Market
Infection Control
Global Dental Infection Control Products Market
Infection Control
Infection Control Market
Infection Control
Disinfection Cupboard Market
Infection Control
Global Hospital Disinfectant Products and Services Market
Infection Control
Antiseptic Bathing Market
Infection Control
Infection Control Supplies Market
Infection Control
Biological and Chemical Indicators Market
Infection Control
Veterinary Disinfectant for Pets and Farms Market