
 Ultrasound Probe Market | 2026-2036
Ultrasound Probe Market Size, Share, and Industry Trends Forecast 2026-2036
Ultrasound Probe Market Outlook
CE marking under the EU Medical Device Regulation is bifurcating the competitive landscape between established manufacturers and emerging entrants. GE Healthcare leverages its captive transducer manufacturing to sustain pricing control across hospital networks. Siemens Healthineers anchors its position through R&D intensity in single-crystal piezoelectric materials. Koninklijke Philips N.V. competes on channel density, dominating ambulatory surgery center placements in Western Europe.
An ultrasound probe is a handheld transducer assembly that converts electrical pulses into acoustic waves and vice versa, typically operating between 2 and 15 MHz depending on clinical depth requirements. Its core function is to enable real-time anatomical visualization for diagnostic and interventional procedures across medical specialties. Linear probes command premium pricing in musculoskeletal and vascular applications where high-frequency resolution justifies replacement cycles. Digital ultrasound technology is displacing analog architectures fastest in portable configurations, while phased array probes concentrate margin pools in cardiology due to specialized beam-steering firmware. Convex probes occupy the mature obstetrics segment where volume scale offsets lower per-unit margins.
The FDA enforces quality system regulation compliance for transducer biocompatibility and electrical safety, while the EU MDR imposes post-market surveillance obligations that extend probe lifecycle documentation. Japan's PMDA maintains distinct electromagnetic compatibility standards that filter non-compliant imports from European and North American suppliers. Stakeholders must monitor how divergent sterilization validation protocols between FDA and MDR frameworks reshape aftermarket service economics and probe refurbishment viability.
Market Dynamics
Digital beamforming architectures are collapsing the traditional distinction between premium cart-based systems and portable ultrasound configurations, forcing probe manufacturers to recalibrate component sourcing and firmware development roadmaps.
Growth Catalysts
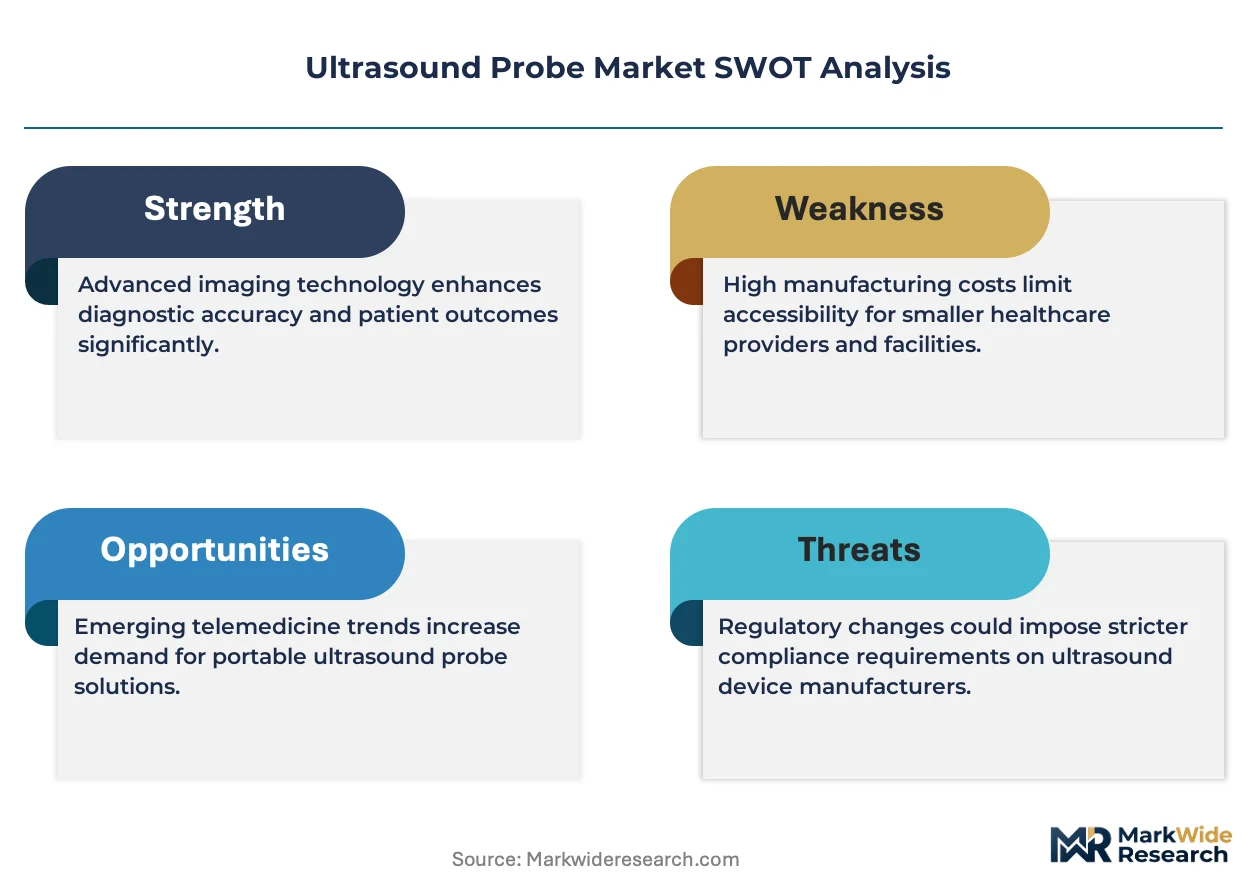
- EU MDR post-market surveillance mandates:Extended documentation requirements for probe lifecycle tracking are creating recurring revenue streams for manufacturers with established quality management systems.
- Emergency medicine point-of-care imaging:Accelerated replacement cycles in hospital emergency departments are compressing probe refresh timelines from seven years to under four years.
- Single-crystal piezoelectric materials:Superior acoustic impedance matching in these advanced ceramics is enabling deeper tissue penetration at higher frequencies for cardiology applications.
Market Restraints
- Piezoelectric ceramic supply concentration:Japanese and Chinese suppliers control over eighty percent of high-purity PZT material output, exposing probe manufacturers to input cost volatility and export restriction risks.
- FDA quality system regulation compliance burden:Biocompatibility testing and electrical safety validation requirements extend new product introduction timelines by fourteen to eighteen months.
- Phased array technical complexity:Specialized beam-steering firmware development requires rare acoustic engineering expertise that concentrates among a handful of specialist firms.
Strategic Opportunities
- Underpenetrated ambulatory surgery centers:Western European ASC networks are standardizing on digital probe fleets, creating first-mover advantages for suppliers with channel density.
- Wireless probe convergence with tablet-based visualization:Integration of Bluetooth Low Energy transducers with consumer-grade displays is collapsing system price points for primary care.
- Japan PMDA electromagnetic compatibility harmonization:Alignment initiatives with IEC 60601 standards are reducing technical barriers for North American and European suppliers.
Industry Challenges
- Acoustic engineer talent scarcity:Specialized expertise in transducer design and beam physics concentrates among retiring specialists and a limited pipeline of university programs.
- Sterilization validation protocol divergence:Incompatible requirements between FDA and EU MDR frameworks complicate probe refurbishment economics and aftermarket service models.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ultrasound Probe Market |
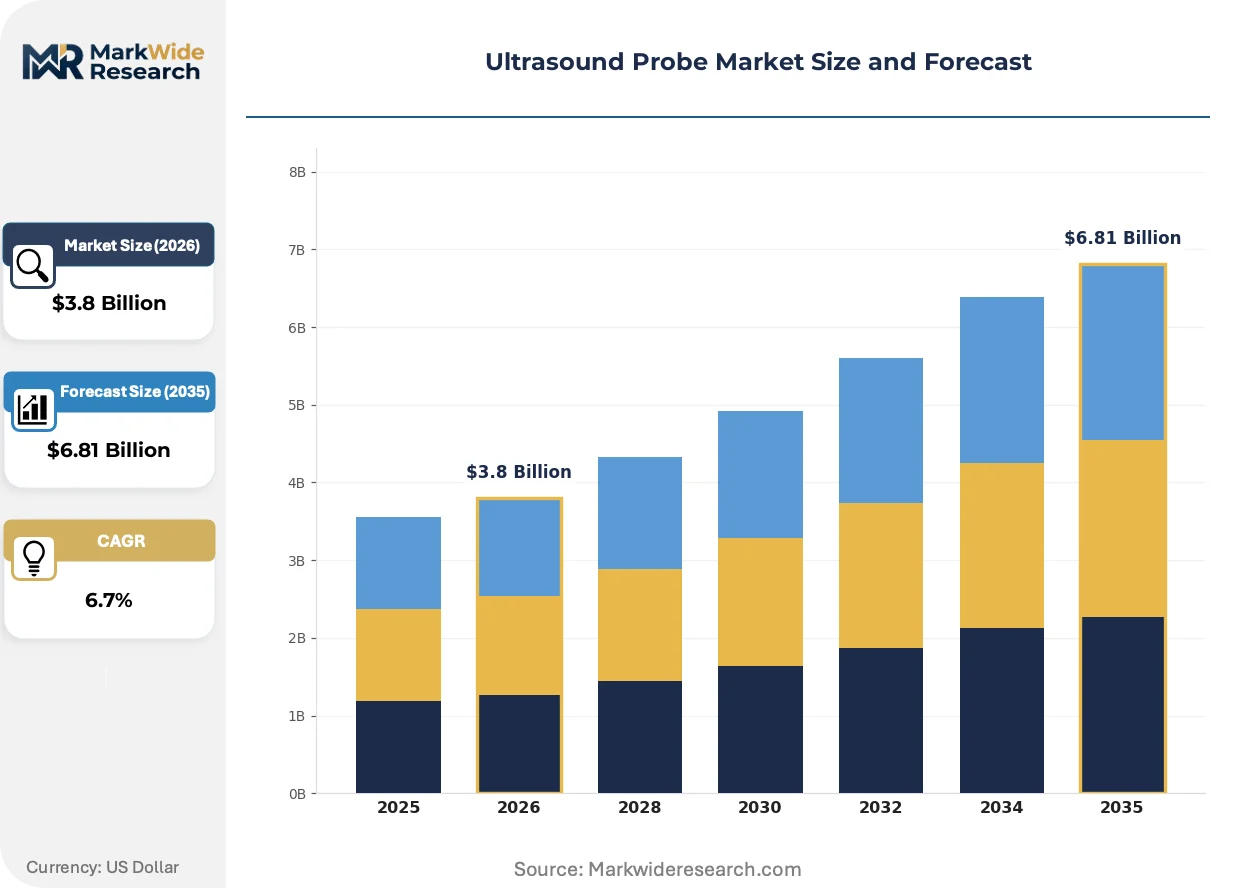
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Linear Probes, Convex Probes, Phased Array Probes, Endocavitary Probes Technology: Analog Ultrasound, Digital Ultrasound, 3D Ultrasound, Portable Ultrasound End User: Hospitals, Clinics, Diagnostic Centers, Research Institutions Application: Obstetrics, Cardiology, Urology, Emergency Medicine |
| Companies Covered | Canon Medical Systems, Samsung Medison Co., Ltd., GE Healthcare, Konica Minolta Inc., FUJIFILM SonoSite, Inc., Koninklijke Philips N.V., Mindray Medical International Limited, Esaote, Siemens Healthineers AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ultrasound Probe Market Strategic Shifts
Probe architecture is fragmenting along clinical workflow boundaries, with firmware-defined functionality replacing hardware-differentiated product tiers and collapsing traditional segmentation logic.
Capacitive micromachined ultrasonic transducer technology is decomposing the conventional piezoelectric probe supply chain. Semiconductor foundries in Taiwan and South Korea are fabricating CMUT arrays for cardiology and intravascular applications. This silicon-based approach is decomposing the historical barrier between disposable and reusable probe economics, enabling single-use sterile packaging for interventional procedures.
EU MDR technical documentation requirements are extending probe lifecycle accountability from manufacturers to refurbishment service providers. Post-market clinical follow-up obligations now mandate traceability of acoustic output degradation over extended use cycles. Cardiology probe suppliers are responding by embedding calibration logging firmware that automatically flags performance drift.
Hospital network procurement is consolidating ultrasound probe specifications across affiliated facilities, unbundling after-sales service from capital equipment contracts. Third-party probe refurbishment specialists are capturing service revenue previously retained by original equipment manufacturers. This concentration is most visible in United States health systems where standardized digital probe fleets reduce training and inventory complexity.
Ultrasound Probe Market Segmentation
Ultrasound probe segmentation reveals how clinical workflow specialization drives component architecture decisions. Manufacturers must align transducer design, frequency tuning, and firmware capabilities with distinct end-use requirements across diagnostic and interventional settings.
Product Type:
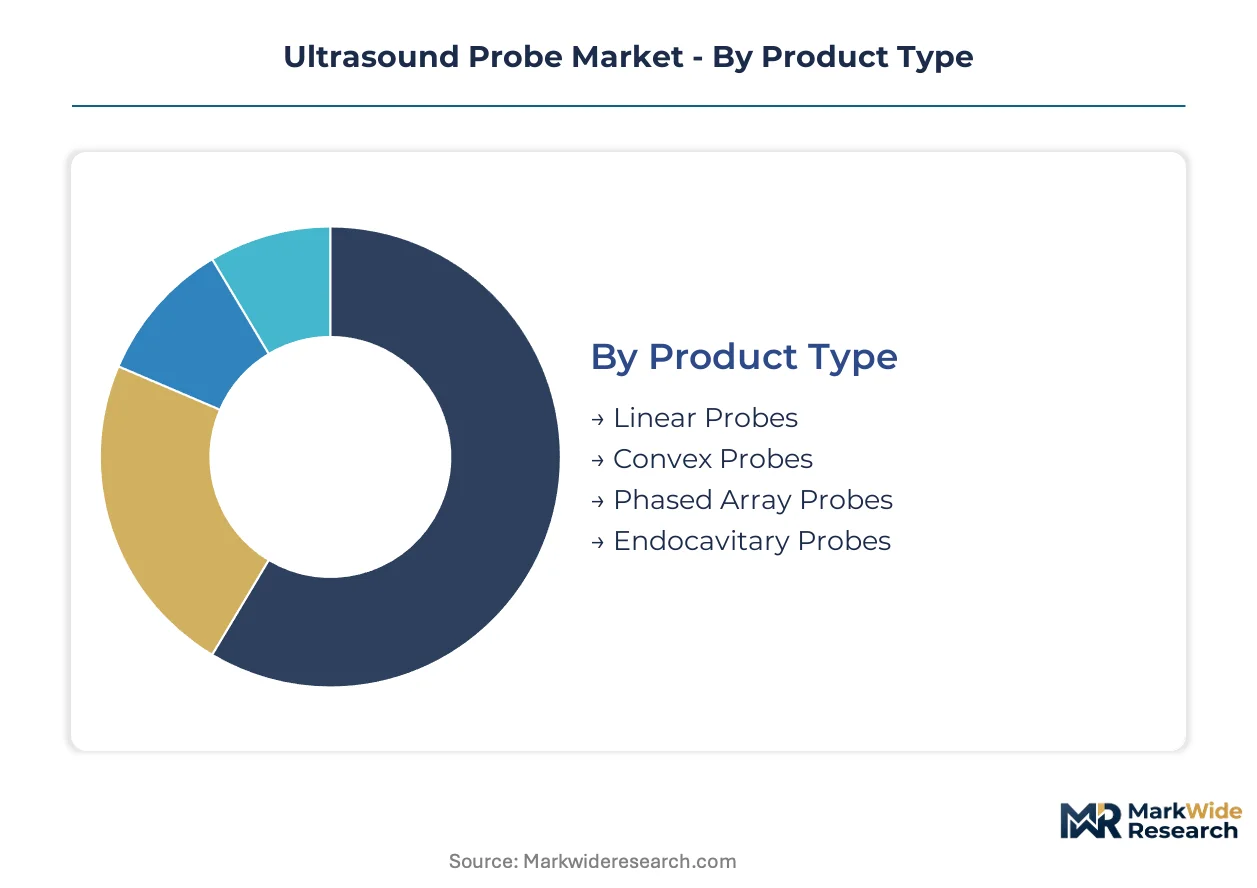
Linear probes dominate domestic demand in North American musculoskeletal practices, while convex and phased array variants anchor export volumes to hospital networks in Germany and Japan.
- Linear Probes:High-frequency transducers operating above 7 MHz deliver superficial tissue resolution for vascular access and musculoskeletal imaging. Demand concentrates in United States ambulatory surgery centers where premium pricing justifies replacement cycles driven by sterile field requirements.
- Convex Probes:Curved arrays with 2-5 MHz range enable deep abdominal and obstetric visualization through wider acoustic windows. Export volumes to Latin American public health systems sustain manufacturing scale despite lower per-unit margins.
- Phased Array Probes:Electronic beam-steering through 64-128 elements enables cardiac imaging via intercostal acoustic windows. Japanese cardiology clinics drive specification requirements.
- Endocavitary Probes:High-frequency micro-convex designs for transvaginal and transrectal applications with dedicated sterilization protocols. European gynecology practices set performance benchmarks.
Convex probes hold the largest share; momentum sits with phased array variants as cardiology point-of-care imaging accelerates probe refresh timelines.
Technology:
Cost tier stratification separates semiconductor-intensive digital architectures from legacy analog systems, with portable configurations collapsing price points fastest in primary care settings.
- Analog Ultrasound:Legacy beamforming through discrete crystal arrays with dedicated hardware amplifiers. Remains entrenched in cost-sensitive developing market installations where digital migration lags.
- Digital Ultrasound:Software-defined beamforming through field-programmable gate arrays enables firmware-upgradable performance. Demand concentrates in United States health systems standardizing fleet specifications across consolidated networks.
- 3D Ultrasound:Matrix array transducers with mechanical or electronic volume acquisition for fetal and cardiac structural assessment. German prenatal diagnostic centers anchor European adoption.
- Portable Ultrasound:Battery-powered systems with tablet or smartphone integration, collapsing system price points for emergency medicine and rural deployment. Steepest expansion trajectory as Bluetooth Low Energy probes enable wireless workflows.
Digital platforms command the revenue base; portable configurations are gaining share fastest as wireless probe-tablet convergence redefines primary care access.
End User:
Customer type determines procurement channel structure, with hospital network consolidation favoring fleet standardization while diagnostic centers prioritize modality flexibility.
- Hospitals:Multi-specialty imaging departments with centralized biomedical engineering and standardized probe inventories. United States health system consolidation is compressing vendor diversity.
- Clinics:Single or limited-specialty practices with point-of-care ultrasound integration for immediate diagnostic confirmation. European primary care networks drive portable system specifications.
- Diagnostic Centers:Dedicated imaging facilities with high throughput and multi-modality workflow requirements. Japanese imaging chains emphasize probe durability under continuous use.
- Research Institutions:Academic medical centers and translational research programs driving experimental transducer architectures. United States NIH-funded programs anchor preclinical CMUT development.
Hospitals represent the installed base anchor; clinics are expanding most quickly as wireless probe adoption collapses capital barriers.
Application:
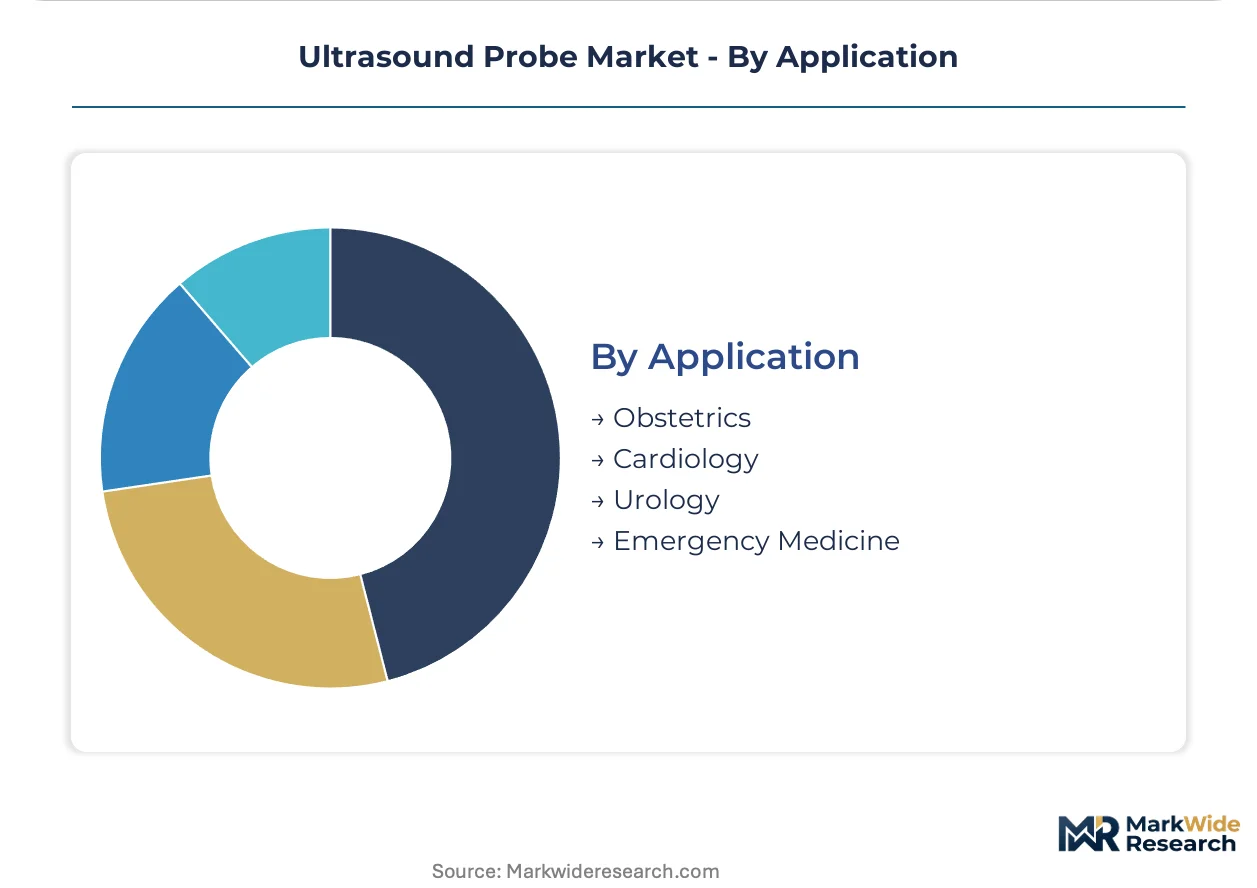
Maturity gradients separate established obstetric volume markets from technology-intensive cardiology segments where firmware differentiation sustains premium positioning.
- Obstetrics:Mature segment with convex probe dominance for fetal biometry and anatomical survey. Volume scale in China and India offsets pricing pressure from public procurement.
- Cardiology:Phased array dependence with specialized beam-steering firmware for valvular and wall-motion assessment. United States emergency department point-of-care protocols are accelerating probe replacement.
- Urology:Endocavitary probe requirements for transrectal prostate imaging and bladder volume measurement. German urology practices set technical specifications for European markets.
- Emergency Medicine:Multi-probe portfolios supporting FAST protocols, vascular access, and lung imaging under time-critical conditions. Steepest growth as four-year replacement cycles displace seven-year norms.
Obstetrics retains volume leadership; emergency medicine is climbing the fastest as point-of-care imaging protocols standardize across trauma networks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement officers in the United States, Germany, and Japan concentrate ultrasound probe purchasing power through consolidated network contracts. Emergency medicine point-of-care protocols and cardiology firmware specialization drive regional specification divergence.
United States
Health system consolidation compresses vendor diversity as standardized digital probe fleets reduce training overhead. FDA quality system regulation updates extend biocompatibility validation timelines for transducer suppliers. Texas Medical Center and Mayo Clinic networks anchor procurement concentration in the South and Midwest.
Germany
Prenatal diagnostic centers and urology practices set European technical benchmarks for 3D matrix arrays and endocavitary designs. EU MDR post-market surveillance mandates extend probe lifecycle documentation obligations to refurbishment providers. Baden-Württemberg and Bavaria host precision manufacturing clusters serving Siemens Healthineers supply chains.
Japan
Cardiology clinics drive phased array specification requirements through specialized beam-steering firmware demands. PMDA electromagnetic compatibility standards filter non-compliant imports from Western suppliers. Tokyo and Osaka metropolitan areas concentrate imaging chain procurement for high-throughput diagnostic centers.
China
Public health system volume scale in obstetrics offsets pricing pressure from centralized procurement. NMPA device registration harmonization with international standards accelerates domestic manufacturer export capability. Yangtze River Delta semiconductor foundries fabricate CMUT arrays for emerging probe architectures.
United Kingdom
Ambulatory surgery center networks standardize on portable ultrasound configurations with wireless probe-tablet convergence. MHRA alignment with EU MDR technical documentation requirements preserves market access continuity post-Brexit. London and Southeast England concentrate private diagnostic imaging investment.
Ultrasound Probe Market Competitive Environment
Player mix skews toward diversified medical imaging conglomerates with captive transducer manufacturing capabilities. Three to five integrated systems houses control premium-tier positioning through firmware-defined beamforming differentiation. Strategic archetypes include semiconductor-intensive CMUT developers, piezoelectric ceramic specialists, and wireless probe-tablet integrators. Competitive moves concentrate on backward integration into single-crystal material supply and strategic partnerships with Taiwan semiconductor foundries.
Within the diversified imaging systems tier, GE Healthcare, Siemens Healthineers AG, and Koninklijke Philips N.V. exemplify contrasting geographic anchoring and channel density strategies. Samsung Medison Co., Ltd. and Canon Medical Systems occupy positions bridging consumer electronics scale with medical device regulatory expertise. Mindray Medical International Limited represents the China-based challenger archetype leveraging domestic volume scale for export expansion.
| Leading Market Players |
|---|
| Canon Medical Systems |
| Samsung Medison Co., Ltd. |
| GE Healthcare |
| Konica Minolta Inc. |
| FUJIFILM SonoSite, Inc. |
| Koninklijke Philips N.V. |
| Mindray Medical International Limited |
| Esaote |
| Siemens Healthineers AG |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake agreements with Japanese and Chinese piezoelectric ceramic suppliers lock in PZT material access and price visibility for probe manufacturers, insulating tier-one suppliers from spot market volatility while compressing margins for buyers without backward integration into single-crystal sourcing.
Pricing Analysis
Cost-plus contracts with PZT price indexation anchor component procurement for transducer manufacturers. Three-tier pricing structure across premium, standard, and economy levels separates firmware-upgradable digital probes from legacy analog systems and disposable CMUT arrays. Price differentiation hinges on FDA 510(k) clearance tier and single-crystal piezoelectric content. Cost compression in economy-tier analog probes is intensifying because Chinese manufacturers leverage domestic PZT supply scale. Ambulatory surgery centers exhibit highest price sensitivity; cardiology clinics show lowest sensitivity due to specialized beam-steering firmware requirements.
Supply Chain Analysis
Inbound logistics costs from Yokohama and Shanghai ports constrain just-in-time delivery of high-purity PZT ceramics to transducer assembly facilities. Manufacturing gravity centers on Japan, China, and Germany for piezoelectric material processing and probe final assembly. Raw material dependencies include lead zirconate titanate ceramics, single-crystal PMN-PT wafers, and semiconductor-grade silicon for CMUT fabrication. Single-source vulnerability concentrates in Japanese suppliers controlling eighty percent of medical-grade PZT output. Distribution runs through hospital GPO contracts and direct OEM service networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Probe architecture fragmentation creates entry niches as firmware-defined functionality displaces hardware-differentiated tiers, enabling specialist suppliers to capture margin pools in wireless tablet integration and CMUT semiconductor fabrication.
For Market Incumbents: Shield installed base revenue by embedding calibration logging firmware that flags acoustic performance drift, locking hospital networks into proprietary service ecosystems. Accelerate backward integration into single-crystal PMN-PT material supply to defend margin position against emerging CMUT entrants. Prioritize certification investment for EU MDR technical documentation to extend lifecycle accountability advantages over refurbishment competitors. For New Entrants and Emerging Players: FDA breakthrough device designation fast-track offers accelerated market entry for wireless probe-tablet systems targeting primary care workflows. White-space concentrates in underpenetrated Western European ambulatory surgery centers standardizing on portable digital fleets. Target acquisition of acoustic engineering talent from retiring specialists at Siemens Healthineers and GE Healthcare legacy programs. Go-to-market angle: Bluetooth Low Energy probe-tablet bundles at fifty percent capital cost of cart-based systems. For Investors and Strategic Acquirers: Capital is best deployed toward semiconductor foundry partnerships with Taiwan and South Korea fabricators capable of CMUT array production at medical device yield rates. Long-term viability favors probe manufacturers with captive piezoelectric material supply and firmware-defined upgrade pathways. Watch FDA quality system regulation enforcement intensity as inflection signal for compliance cost barriers favoring scaled incumbents.| Strategic Initiative | Industry Significance |
|---|---|
| Single-Crystal Material Backward Integration | Captive PMN-PT supply secures acoustic performance differentiation against PZT-dependent competitors. |
| EU MDR Technical Documentation Investment | Extended probe lifecycle tracking creates recurring service revenue from post-market surveillance mandates. |
| Wireless Probe-Tablet Platform Launch | Bluetooth Low Energy convergence collapses system price points for European primary care networks. |
| CMUT Semiconductor Foundry Partnership | Taiwan fabrication access enables single-use sterile packaging for interventional cardiology procedures. |
| Hospital GPO Contract Consolidation | Standardized digital fleet procurement reduces vendor diversity across United States health system networks. |
Study Parameters
A spread of perspectives from biomedical engineers, hospital purchasing committee members, GPO contracts managers, and transducer manufacturing executives converged on the working assumptions driving probe demand forecasts. Primary fieldwork with ultrasound OEM product strategists and refurbishment service operators combined with secondary validation through FDA 510(k) filings, EU MDR technical documentation databases, hospital procurement records, and piezoelectric ceramics trade data. Bottom-up unit economics for linear, convex, phased array, and endocavitary probe categories triangulated against top-down health system capital expenditure patterns.
Segmentation dimensions modeled span product type, technology architecture, end-user facility category, and clinical application across the analysis window. CAGRs derived from probe replacement cycle compression in emergency medicine, cardiology point-of-care expansion, and obstetrics volume scale in public health systems. Forecast inputs incorporated single-crystal piezoelectric penetration rates, CMUT commercialization timelines, and wireless probe-tablet adoption curves in primary care settings.
Underlying assumptions cover FDA quality system regulation stability, PZT supply chain continuity from Japanese and Chinese sources, and EU MDR enforcement consistency, with deviation risk concentrated in export restriction events, electromagnetic compatibility standard harmonization failures, and acoustic engineer talent pipeline collapse. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Automated CPR Devices Market
Medical Devices
Global Retinoscopes Market
Medical Devices
Medical LED Headlight Market
Medical Devices
Asia-Pacific Single-Use Medical Device Reprocessing Market
Medical Devices
Distal Embolic Filters Market
Medical Devices
Next-Generation Neurofeedback Device Market
Medical Devices
Global IVF Devices Market
Medical Devices
Europe Ablation Technologies Market
Medical Devices
United States Stair Lift Market
Medical Devices
Medical Fiber Optics Market
Medical Devices
Laser Resurfacing Market
Medical Devices
Manual Wheelchair Market
Medical Devices
United Kingdom General Surgical Devices Market
Medical Devices
US Medical Display Monitors Market
Medical Devices
Dermal Allograft Market
Medical Devices
Cranial Navigation Systems Market