
 Perianal Infection Treatment Market | 2026-2036
Perianal Infection Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Perianal Infection Treatment Market Analytics
FDA 510(k) clearance cycles for novel topical antimicrobial formulations is bifurcating competitive access between established pharmaceutical manufacturers and emerging specialty developers. Baxter International leverages its hospital formulary relationships to sustain institutional distribution dominance in injectable antibiotic segments. Teva Pharmaceutical Industries Ltd. anchors its position through broad-spectrum generic portfolios that compete aggressively on price in oral therapy categories.
Perianal infection treatment encompasses pharmacological and procedural interventions targeting bacterial, fungal, and polymicrobial infections of the perianal skin, anal canal, and surrounding soft tissues, typically involving topical metronidazole formulations, extended-spectrum cephalosporins, or combination antifungal-corticosteroid preparations with minimum inhibitory concentration thresholds calibrated against anaerobic pathogens. These therapies serve to resolve active infection, prevent fistula formation, and reduce recurrence rates in immunocompromised and post-surgical patient populations. Antibiotics occupies the largest revenue pool within product type segments due to entrenched surgical prophylaxis protocols, while topical delivery mode segments capture expanding share as outpatient shift accelerates preference for non-invasive administration. Homecare end user segments represent the fastest structural growth channel, driven by post-discharge antimicrobial stewardship programs and remote wound monitoring integration.
FDA antimicrobial stewardship mandates, EMA pharmacovigilance reporting requirements, and WHO AWaRe classification frameworks collectively constrain empirical prescribing and favor pathogen-directed therapy selection in perianal indications. These regulatory layers elevate documentation burdens but simultaneously create market access advantages for manufacturers with robust susceptibility testing partnerships and narrow-spectrum development pipelines. Stakeholders must monitor evolving FDA guidance on topical antimicrobial resistance surveillance and prioritize formulation investments that align with institutional stewardship scorecards.
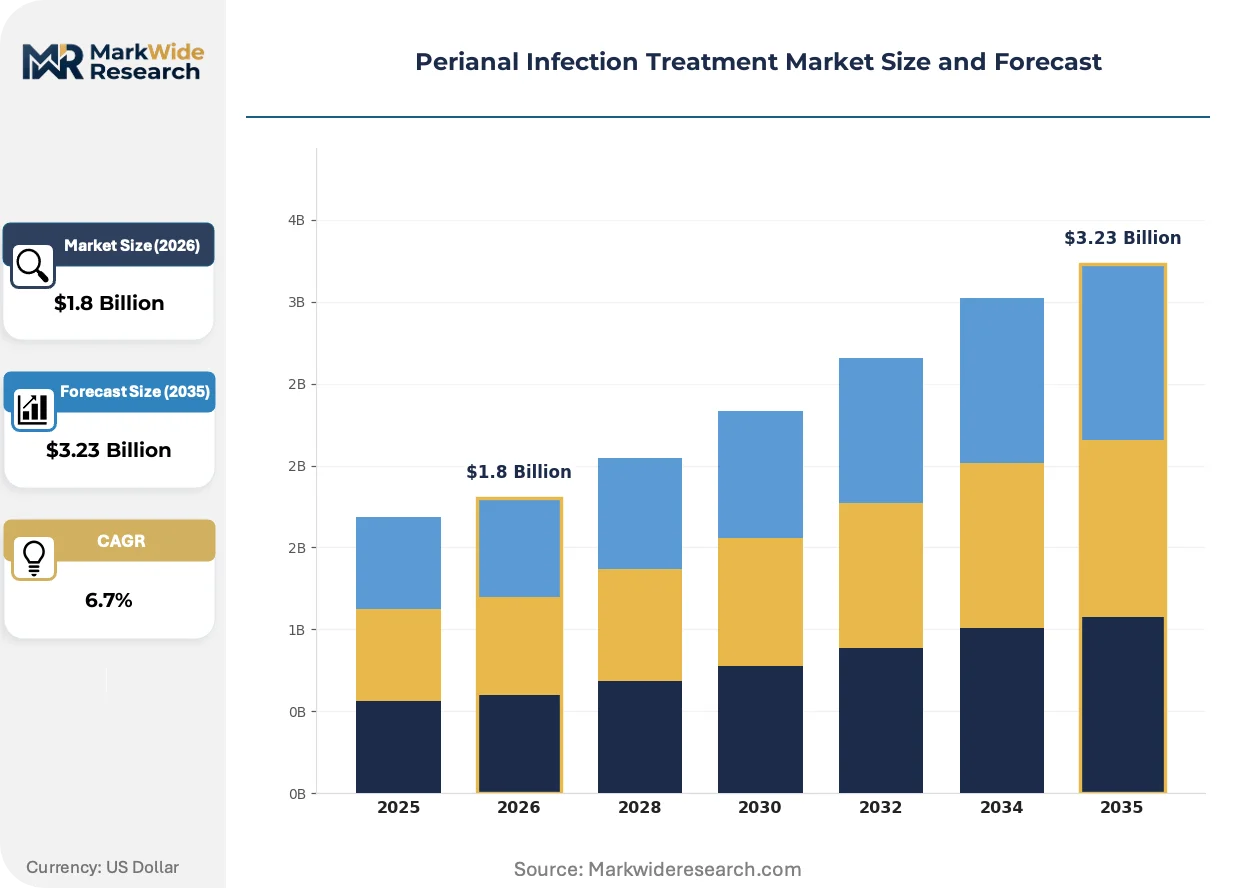
Market Dynamics
Antimicrobial stewardship mandates from FDA and EMA are restructuring prescription authority in perianal infection management, elevating narrow-spectrum formulations over empirical broad-spectrum regimens and forcing manufacturers to rebuild clinical evidence packages around susceptibility-guided therapy.
Growth Catalysts
- Surgical Site Infection Protocols:Tightening hospital accreditation standards in the United States and Germany mandate perioperative antimicrobial prophylaxis, institutionalizing demand for targeted perianal therapies.
- WHO AWaRe Classification:The Access-Watch-Reserve framework steers formulary committees toward pathogen-directed antibiotic selection, creating procurement advantages for developers with anaerobe-calibrated minimum inhibitory concentration data.
- Homecare Monitoring Integration:Remote wound surveillance platforms enable post-discharge antimicrobial stewardship, expanding addressable patient populations beyond acute care settings.
Market Restraints
- Active Pharmaceutical Ingredient Concentration:Dependence on Chinese and Indian bulk cephalosporin and nitroimidazole suppliers exposes manufacturers to supply volatility and quality enforcement actions.
- EMA Pharmacovigilance Burden:Post-market surveillance reporting requirements for topical antimicrobials extend development timelines and inflate regulatory compliance costs for specialty developers.
- Generic Substitution Pressure:Oral metronidazole and clindamycin commoditization compresses pricing power in outpatient segments, limiting branded formulation penetration.
Strategic Opportunities
- Japan's Aging Surgical Population:Expanding colorectal procedure volumes among elderly patients with compromised healing profiles create demand for advanced topical antimicrobial-corticosteroid combinations.
- Microbiome-Targeted Formulations:Convergence of anaerobic culture diagnostics and biofilm-disrupting delivery vehicles enables development of pathogen-specific therapies without collateral microbiome damage.
- Institutional Stewardship Scorecards:FDA guidance on topical antimicrobial resistance surveillance creates first-mover advantages for manufacturers with integrated susceptibility testing partnerships.
Industry Challenges
- Clinical Microbiology Talent Scarcity:Shortages of anaerobic pathogen identification specialists delay susceptibility testing turnaround times, undermining stewardship program efficacy.
- Legacy EHR Integration:Antimicrobial decision support tools require costly interface development with hospital electronic health record systems, fragmenting vendor competitive positions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Perianal Infection Treatment Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antibiotics, Analgesics, Antifungal Agents, Topical Creams Delivery Mode: Oral, Topical, Injectable, Transdermal End User: Hospitals, Clinics, Homecare, Ambulatory Surgical Centers Treatment Duration: Short-term, Long-term, Maintenance, Acute |
| Companies Covered | Baxter International Inc., Hospira Inc., Sandoz, Arbor Pharmaceuticals LLC, Abbott, Eli Lilly & Co. Ltd., Allergan Plc., Teva Pharmaceutical Industries Ltd., AbbVie Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Perianal Infection Treatment Market Evolving Landscape
Topical bioadhesive antimicrobial formulations are reshaping competitive positioning in perianal infection management by enabling sustained drug release at infection sites while systemic exposure declines.
Bioadhesive hydrogel carriers loaded with metronidazole and extended-spectrum agents provide localized concentration gradients that exceed planktonic minimum inhibitory concentrations for polymicrobial anaerobes. Outpatient surgical centers in Germany and the United States are adopting these platforms for post-fistulotomy wound care, displacing conventional gauze-based delivery systems that require frequent dressing changes and demonstrate inferior tissue penetration. The shift compresses nursing labor costs while reducing hospital readmission rates for wound complications.
EMA's 2023 revision to veterinary and human antimicrobial environmental risk assessment guidelines extends data requirements for topical formulations, forcing developers to submit ecotoxicity profiles for active pharmaceutical ingredients and metabolites. Manufacturers with existing environmental fate studies gain accelerated market access, while late entrants face 18-24 month delays to generate aquatic toxicity and biodegradation data. This regulatory layering favors established pharmaceutical portfolios with legacy environmental dossiers.
Hospital formulary committees now require antimicrobial stewardship program endorsement before adding novel perianal therapies to restricted lists, unbundling traditional sales relationships between manufacturers and procurement departments. Specialty distributors with integrated clinical pharmacist advisory services capture contracting authority from legacy broadline distributors in the United States. This channel restructuring concentrates purchasing influence among institutional decision-makers with direct accountability for resistance metrics rather than cost-per-dose optimization.
Perianal Infection Treatment Market Segmentation
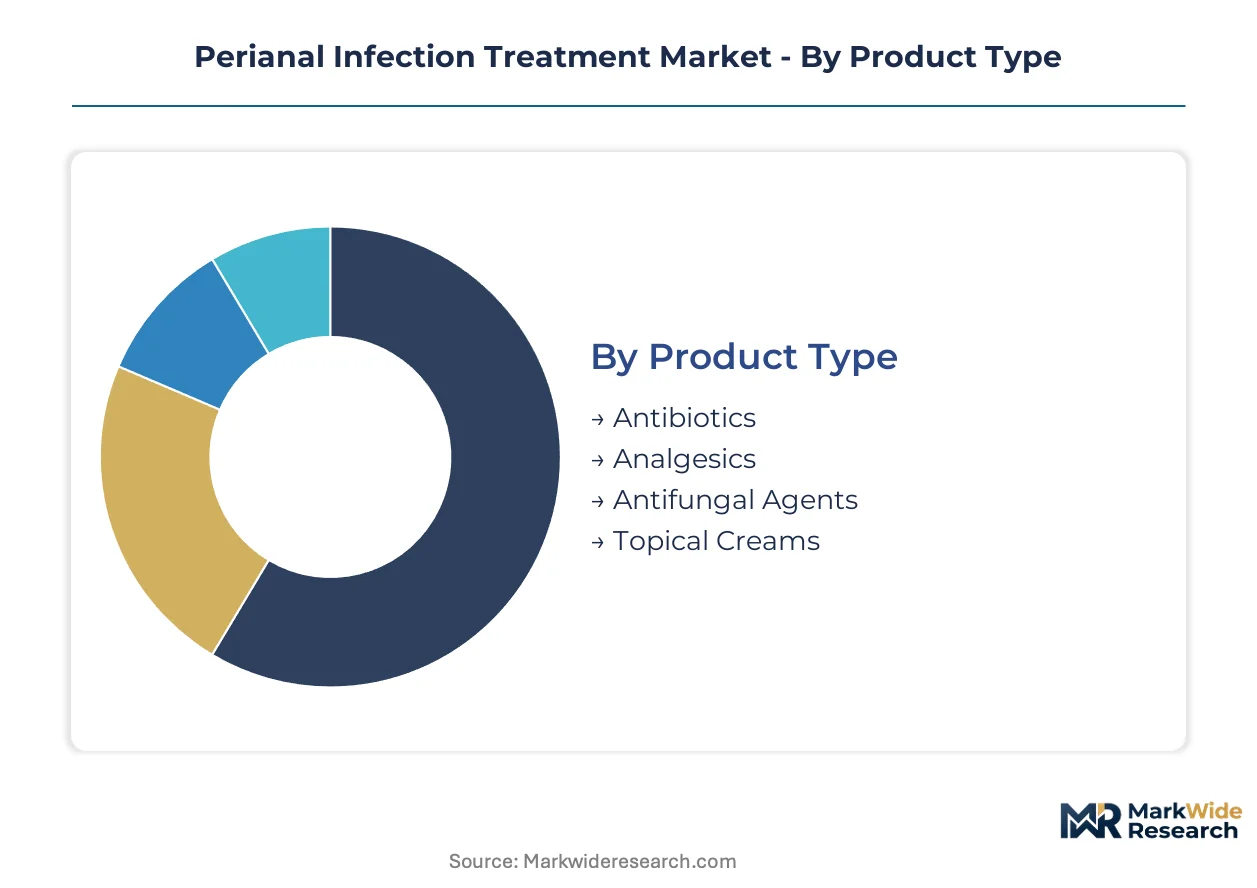
Segmentation in perianal infection treatment reveals divergent margin profiles across administration routes and care settings. Procurement patterns increasingly favor pathogen-directed categories aligned with antimicrobial stewardship mandates.
Product Type:
Margin pools concentrate in narrow-spectrum formulations with anaerobe-calibrated minimum inhibitory concentration data, while commoditized broad-spectrum agents face pricing compression.
- Antibiotics:Extended-spectrum cephalosporins and nitroimidazoles dominate hospital formulary procurement, with metronidazole formulations capturing the largest revenue pool due to entrenched surgical prophylaxis protocols in the United States and Germany.
- Analgesics:Non-opioid and opioid adjuncts serve post-procedural pain management, with demand concentrating in ambulatory surgical centers seeking reduced readmission risk profiles.
- Antifungal Agents:Azole and polyene preparations address Candida superinfections in immunocompromised populations, typically co-prescribed with antibacterial regimens.
- Topical Creams:Combination antimicrobial-corticosteroid preparations expand in outpatient channels, driven by preference for localized therapy without systemic exposure.
The dominant share belongs to Antibiotics, while Topical Creams are closing the gap fastest.
Delivery Mode:
Volume flows track the outpatient shift, with non-invasive administration modes capturing expanding patient populations beyond acute care settings.
- Oral:Generic metronidazole and clindamycin tablets anchor outpatient therapy, though commoditization limits branded formulation pricing power in retail pharmacy channels.
- Topical:Bioadhesive hydrogel carriers with sustained-release metronidazole reshape competitive positioning in Germany and United States post-fistulotomy wound care, displacing conventional gauze-based systems.
- Injectable:Hospital-based procurement of extended-spectrum cephalosporins tightens as surgical site infection protocols mandate perioperative antimicrobial prophylaxis in accredited United States and German facilities.
- Transdermal:Patch-based delivery remains nascent, with limited clinical evidence packages restricting formulary adoption despite theoretical advantages in patient compliance.
Injectable routes retain the largest institutional volume, though Topical delivery is gaining share most rapidly.
End User:
Revenue concentration follows antimicrobial stewardship accountability, with settings bearing direct resistance metrics commanding procurement influence.
- Hospitals:Tightening accreditation standards in the United States and Germany institutionalize demand for targeted perianal therapies, with formulary committees requiring stewardship program endorsement before restricted list addition.
- Clinics:Outpatient colorectal specialists in Japan drive adoption of advanced topical antimicrobial-corticosteroid combinations for elderly patients with compromised healing profiles.
- Homecare:Remote wound surveillance platforms enable post-discharge antimicrobial stewardship, representing the steepest expansion trajectory as monitoring integration expands addressable populations.
- Ambulatory Surgical Centers:Cost compression priorities favor rapid-turnover topical regimens over extended parenteral therapy in United States outpatient surgical settings.
Hospitals maintain procurement dominance, while Homecare is climbing the fastest.
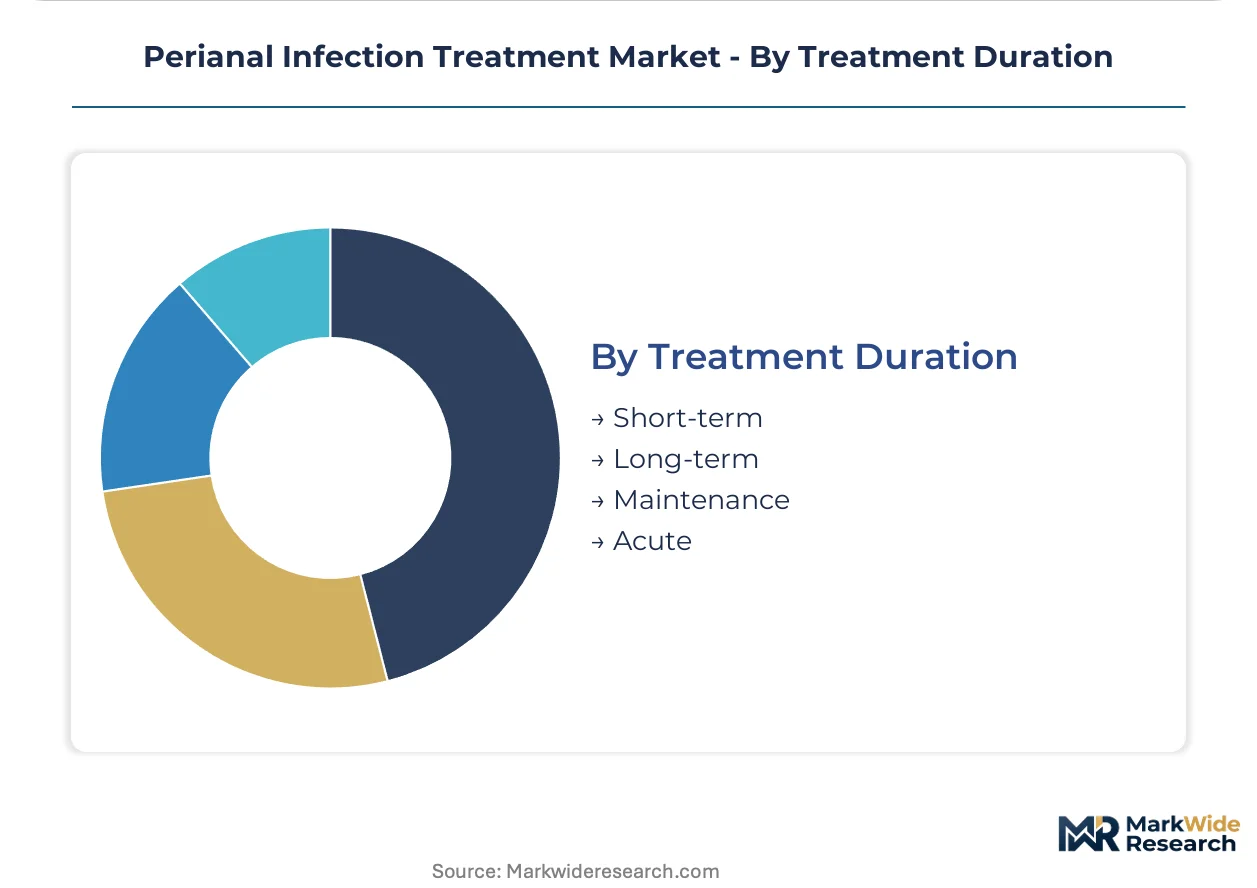
Treatment Duration:
Stewardship frameworks reshape duration protocols, elevating precision over empirical extended regimens.
- Short-term:Perioperative prophylaxis protocols in United States and German hospitals standardize 24-48 hour antimicrobial coverage, institutionalizing predictable demand cycles.
- Long-term:Recurrent fistula management requires extended suppressive therapy, with susceptibility-guided selection replacing empirical broad-spectrum regimens under WHO AWaRe frameworks.
- Maintenance:Chronic immunocompromised populations require intermittent prophylaxis, though EMA pharmacovigilance burdens extend development timelines for maintenance-indicated formulations.
- Acute:Severe polymicrobial infections with abscess formation demand immediate parenteral intervention, concentrating in emergency department and inpatient settings.
Short-term protocols capture the largest volume, while Maintenance regimens are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Antimicrobial stewardship frameworks in the United States, Germany, and Japan are tightening reimbursement pathways for perianal infection therapies, concentrating procurement authority in institutional settings with direct accountability for resistance metrics.
United States
FDA antimicrobial stewardship mandates and surgical site infection accreditation standards institutionalize demand for targeted perianal therapies in acute care settings. Hospital formulary committees now require stewardship program endorsement before restricted list addition. The Greater Boston and Pacific Northwest surgical clusters drive adoption of bioadhesive antimicrobial formulations in post-fistulotomy wound care protocols.
Germany
EMA pharmacovigilance reporting requirements and perioperative prophylaxis protocols reshape prescription patterns across university hospital networks. The country's national pharmaceutical regulator enforces extended data requirements for topical antimicrobial environmental risk assessments. Bavaria and North Rhine-Westphalia anchor specialized colorectal surgical volumes where advanced topical antimicrobial-corticosteroid combinations penetrate outpatient channels.
Japan
PMDA frameworks and an aging surgical population expand addressable demand for advanced wound care in elderly patients with compromised healing profiles. METI industrial policy supports domestic pharmaceutical manufacturing capacity for narrow-spectrum anaerobic therapies. The Kanto region surrounding Tokyo concentrates outpatient colorectal specialist practices driving adoption of sustained-release metronidazole platforms.
India
CDSCO regulatory pathways and expanding private hospital networks create procurement opportunities for generic antimicrobial manufacturers serving price-sensitive outpatient segments. The country's national pharmaceutical regulator accelerates abbreviated approval tracks for locally manufactured nitroimidazole formulations. Maharashtra and Gujarat host contract manufacturing clusters supplying bulk cephalosporin active pharmaceutical ingredients to global formulators.
United Kingdom
NHS antimicrobial stewardship programs and post-discharge monitoring integration expand homecare channel penetration for perianal infection management. The Medicines and Healthcare products Regulatory Agency aligns post-market surveillance requirements with EMA pharmacovigilance frameworks. London and the Southeast concentrate specialized colorectal surgical centers where remote wound surveillance platforms enable post-discharge antimicrobial stewardship.
Perianal Infection Treatment Market Competitive Landscape
Listed leaders compete with private specialists across formulary access and institutional distribution channels. The market structure fragments across three tiers: diversified pharmaceutical conglomerates with hospital procurement relationships, generic manufacturers competing on price in commoditized oral therapy segments, and emerging specialty developers targeting narrow-spectrum formulation niches. Strategic archetypes include stewardship-aligned innovators with susceptibility testing partnerships, cost-optimized generic anchors, and bioadhesive delivery vehicle specialists. Dominant competitive moves center on institutional formulary contracting authority and integrated clinical pharmacist advisory services.
Within the diversified pharmaceutical tier, Baxter International Inc. and Abbott occupy positions anchored by hospital formulary relationships and institutional distribution infrastructure. Teva Pharmaceutical Industries Ltd. exemplifies the generic manufacturing archetype competing aggressively on price in oral metronidazole and clindamycin categories. Eli Lilly & Co. Ltd. represents the specialty pharmaceutical vector with development pipelines targeting narrow-spectrum anaerobic indications.
| Leading Market Players |
|---|
| Baxter International Inc. |
| Hospira Inc. |
| Sandoz |
| Arbor Pharmaceuticals LLC |
| Abbott |
| Eli Lilly & Co. Ltd. |
| Allergan Plc. |
| Teva Pharmaceutical Industries Ltd. |
| AbbVie Inc. |
| Others |
Value Network & Pricing Analysis
Bioadhesive hydrogel carriers displacing conventional gauze-based delivery systems simultaneously concentrates procurement authority in German and United States hospital networks while compressing per-unit pricing for legacy topical formulations. This substitution dynamic elevates formulation sophistication as the primary margin determinant while eroding commodity pricing power in mature delivery modes.
Pricing Analysis
Certification level creates the primary spread between premium FDA 510(k)-cleared sustained-release platforms and economy-tier generic metronidazole creams. Three-tier pricing structure across premium bioadhesive systems, standard topical preparations, and economy oral tablets reflects divergent reimbursement pathways across institutional and retail channels. Pricing pressure stems from generic substitution in outpatient metronidazole and clindamycin segments where Indian and Chinese API manufacturers compete aggressively on cost. Retail pharmacy buyers exhibit highest price sensitivity, while hospital formulary committees prioritize resistance metrics over per-dose economics.
Supply Chain Analysis
Inbound logistics costs through Rotterdam and Hamburg ports constrain just-in-time delivery of temperature-sensitive bioadhesive formulations to German university hospital networks. Active pharmaceutical ingredient production draws from Chinese bulk cephalosporin manufacturers and Indian nitroimidazole specialists, with formulation finishing concentrated in United States, Germany, and Japan. Single-source vulnerability in anaerobic culture diagnostic reagents threatens susceptibility testing turnaround times. Distribution runs through institutional procurement consortia and specialty pharmacy distributors with integrated clinical advisory services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution pressure from microbiome-targeted formulations that promise pathogen specificity without collateral resistance, requiring defensive repositioning around integrated diagnostic-therapeutic platforms.
For Market Incumbents: Fortify hospital formulary relationships through susceptibility testing partnerships that embed stewardship scorecard alignment into contracting protocols. Deepen backward integration into bioadhesive polymer supply to secure formulation differentiation against emerging delivery vehicle specialists. Prioritize EMA environmental fate dossier completion to exploit regulatory layering advantages over late entrants facing 18-24 month ecotoxicity data generation delays.
For New Entrants and Emerging Players: FDA 510(k) fast-track pathways for narrow-spectrum anaerobic therapies offer the most penetrable entry vector, particularly for developers with calibrated minimum inhibitory concentration data against polymicrobial perianal pathogens. Target Japan's aging surgical population where compromised healing profiles create demand for advanced antimicrobial-corticosteroid combinations with limited incumbent saturation. Deploy remote wound monitoring integration as the primary go-to-market angle to bypass entrenched hospital distribution relationships.
For Investors and Strategic Acquirers: The market sits at a stewardship-mandate consolidation phase that favors developers with integrated diagnostic partnerships over standalone formulation plays. Long-term viability over a multi-year horizon rests on regulatory alignment with evolving FDA topical antimicrobial resistance surveillance guidance. Watch for inflection signals in institutional procurement committee composition shifts toward clinical pharmacist dominance over traditional supply chain managers.
| Strategic Initiative | Industry Significance |
|---|---|
| Susceptibility Testing Partnership | Embedded diagnostic alignment secures formulary access under FDA stewardship mandates. |
| Bioadhesive Formulation Development | Sustained-release platforms command premium positioning in German post-surgical wound protocols. |
| EMA Environmental Dossier Completion | Legacy ecotoxicity data accelerates market entry against delayed competitors. |
| Homecare Monitoring Integration | Remote surveillance platforms expand addressable populations beyond acute care settings. |
| Narrow-Spectrum Pipeline Investment | Pathogen-directed therapies align with WHO AWaRe procurement advantages. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA 510(k) clearance databases, EMA pharmacovigilance registries, and hospital formulary restriction lists. Primary interviews engaged drug development executives at specialty pharmaceutical firms, regulatory affairs leads navigating environmental risk assessment revisions, formulary directors at United States academic medical centers, and procurement managers at German university hospital networks. Secondary validation drew from ClinicalTrials.gov anaerobic infection study entries, WHO AWaRe classification updates, and antimicrobial stewardship program documentation. Bottom-up patient flow modeling and top-down pharmaceutical expenditure triangulation anchored volume and value estimates.
Segmentation dimensions modeled span product type, delivery mode, end user setting, and treatment duration across the projection horizon. Analytical frameworks incorporated surgical procedure volume trajectories, reimbursement pathway evolution, and regulatory compliance cost burdens to derive expansion rates. Forecast inputs included colorectal surgery incidence patterns, antimicrobial resistance surveillance data, and institutional procurement committee decision-weight shifts.
Underlying assumptions cover sustained FDA and EMA stewardship mandate enforcement, stable API supply from established Chinese and Indian manufacturing clusters, and gradual homecare channel penetration, with deviation risk concentrated in regulatory timeline acceleration or trade restriction imposition on bulk pharmaceutical imports. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Infection Control
Sterilization Monitoring Market
Infection Control
Global Sepsis Therapeutics Market
Infection Control
Global Hospital Disinfectant Products and Services Market
Infection Control
Patient Hygiene Aids Market
Infection Control
Hand Sanitizer Spray Market
Infection Control
Infection Surveillance Solutions Market
Infection Control
Medical Washer Disinfector Market
Infection Control
Global Hospital Acquired Infection Control Market
Infection Control
Sterilization Technologies Market
Infection Control
Medical Disinfectant Wipes Market
Infection Control
Disinfection Cupboard Market
Infection Control
Antimicrobial Catheters Market
Infection Control
Global Skin Antiseptic Products Market
Infection Control
Steam and Hydrogen Peroxide Biological Indicators Market
Infection Control
Healthcare Associated Infections (HAI) Treatment Market
Infection Control
Europe Ultrasound Probe Disinfection Market