
 Australia Neurology Devices Market | 2026-2036
Australia Neurology Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Australia Neurology Devices Market Outlook
Aftermarket service revenue is narrowing as manufacturers shift toward bundled device-and-monitoring contracts. Medtronic leverages its neurostimulation service infrastructure to lock in multi-year hospital agreements. Stryker Corporation anchors its position through specialized sales teams covering Queensland and Western Australia. Anatomics Pty Ltd differentiates via patient-specific cranial implant manufacturing from its Melbourne base.
Australia neurology devices encompass instruments for diagnosing, monitoring, and treating disorders of the central and peripheral nervous systems, including implantable pulse generators delivering electrical impulses at programmed frequencies and wearable EEG headsets capturing cortical activity through dry electrode arrays. These devices serve to restore motor function, suppress pathological neural firing, or enable real-time neurophysiological assessment in clinical and ambulatory settings. Neurostimulation devices occupy the deepest margin pools due to recurring battery replacement cycles and proprietary programming ecosystems. EEG systems sustain faster volume growth as ambulatory surgical centers expand intraoperative monitoring capabilities. Deep brain stimulators concentrate demand among movement disorder specialists in tertiary referral hospitals.
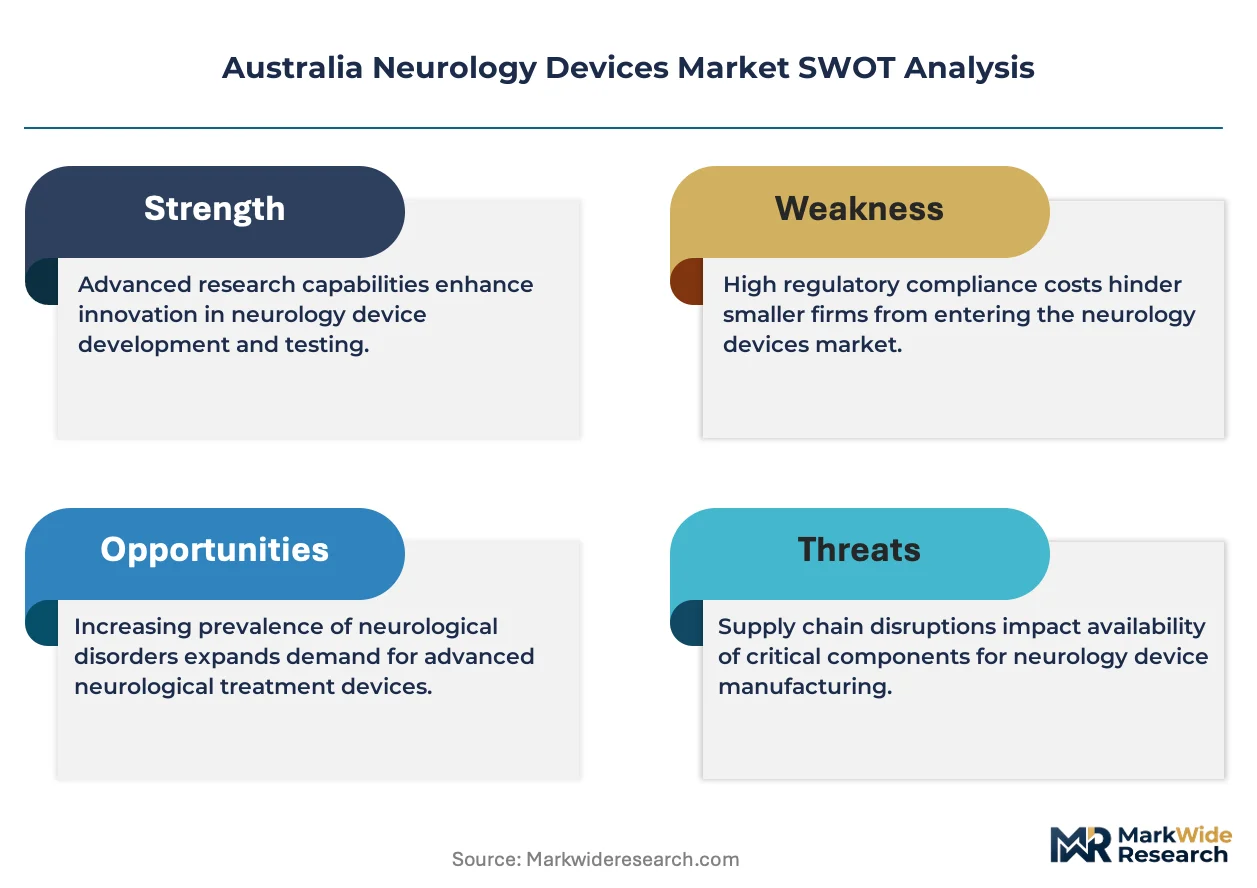
The Therapeutic Goods Administration governs active implantable medical devices under the Australian Regulatory Guidelines for Medical Devices, mandating clinical evidence standards that filter out lower-tier suppliers. Health Technology Assessment processes through the Medical Services Advisory Committee shape reimbursement eligibility for novel neurostimulation therapies. Stakeholders must monitor how the TGA's alignment with EU MDR standards reshapes conformity assessment pathways for imported devices.
Market Dynamics
The Therapeutic Goods Administration's alignment with EU MDR standards is compressing conformity assessment timelines for imported neurostimulation systems, forcing distributors to accelerate local compliance infrastructure investments.
Growth Catalysts
- Deep brain stimulation procurement:Public hospital neurology departments in Victoria and New South Wales are expanding capital budgets for movement disorder treatment infrastructure.
- Ambulatory EEG expansion:Surgical centers across metropolitan Melbourne and Sydney are adding intraoperative monitoring capabilities to capture outpatient neurophysiology revenue.
- TGA framework acceleration:The updated active implantable medical devices regulatory pathway is filtering out lower-tier suppliers and consolidating procurement toward compliant manufacturers.
Market Restraints
- Proprietary programming ecosystems:Neurostimulation device lock-in creates switching costs that suppress price competition and limit hospital vendor flexibility.
- Battery replacement concentration:Recurring replacement cycles concentrate service revenue with original manufacturers, squeezing independent service providers.
- Metropolitan demand clustering:Specialist neurosurgical capacity anchors in Sydney and Melbourne, leaving regional Queensland and Western Australia with delayed access timelines.
Strategic Opportunities
- Patient-specific manufacturing:Cranial implant production localized in Melbourne enables rapid turnaround for trauma centers seeking customized reconstruction solutions.
- Regional Queensland penetration:Specialized sales coverage gaps in tertiary hospitals outside Brisbane create entry points for differentiated service models.
- MSAC reimbursement expansion:Health Technology Assessment processes for novel neurostimulation therapies could unlock public funding for previously self-funded procedures.
Industry Challenges
- Neurophysiology technician scarcity:Intraoperative monitoring programs face recruitment bottlenecks for certified technologists capable of managing ambulatory EEG systems.
- Legacy device integration:Hospital IT departments struggle to interface proprietary neurostimulation programming platforms with electronic health record systems.
- Clinical evidence generation:TGA clinical evidence standards require extended local data collection timelines that delay market entry for novel implantable pulse generators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Neurology Devices Market |
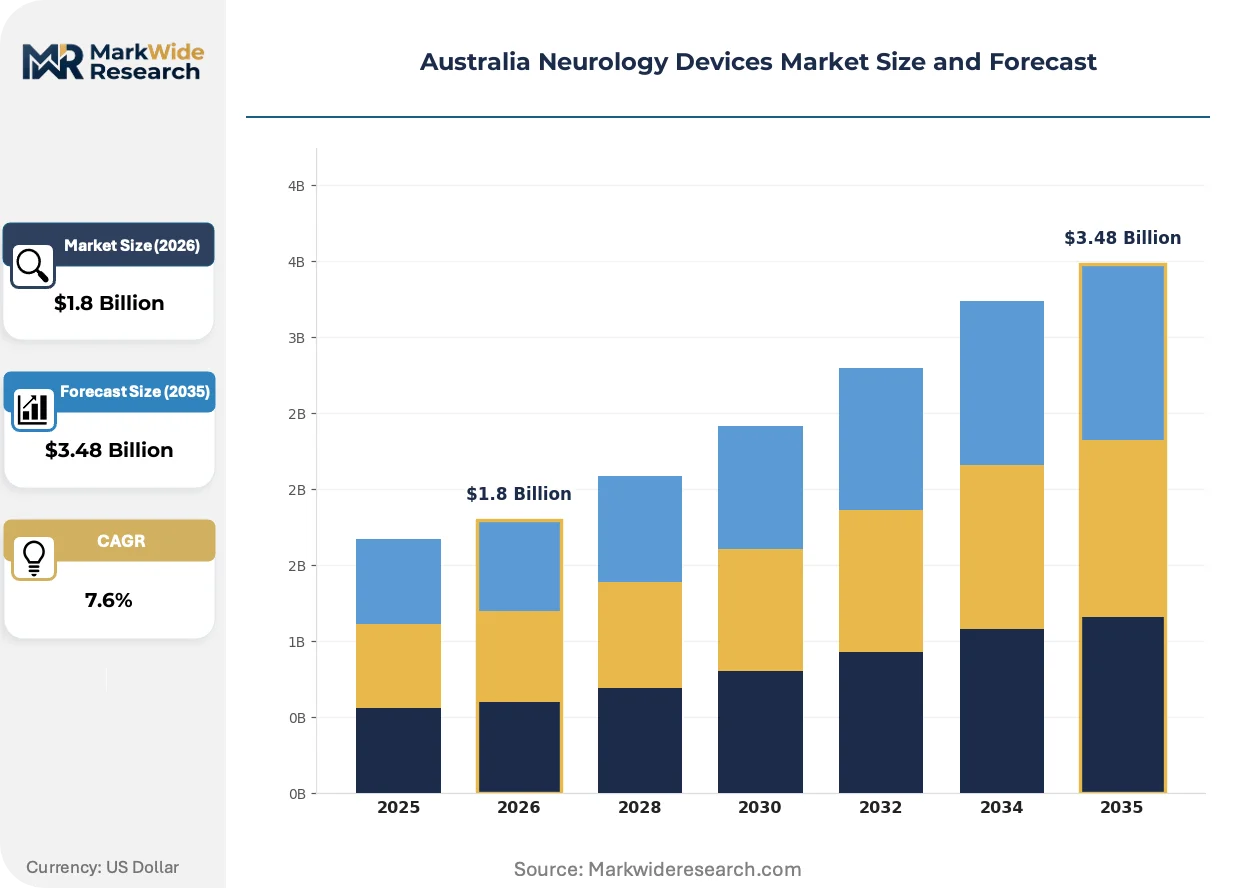
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.48 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Neurostimulation Devices, MRI Machines, EEG Systems, Deep Brain Stimulators Application: Chronic Pain Management, Epilepsy Treatment, Parkinson's Disease Therapy, Neurorehabilitation End User: Hospitals, Diagnostic Centers, Ambulatory Surgical Centers, Home Care Settings Technology: Invasive, Non-Invasive, Wearable Devices, Telemedicine Solutions |
| Companies Covered | Medtronic, Stryker Corporation, B. Braun Melsungen AG, Boston Scientific, Nihon Kohden Corporation, Anatomics Pty Ltd, Penumbra, Inc., Abbott Laboratories, LivaNova, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Neurology Devices Market Strategic Shifts
Dry electrode array technology is compressing setup times for cortical monitoring while regulatory harmonization is reshaping import pathways. Procurement contracts are bundling hardware with longitudinal monitoring services.
Closed-loop neurostimulation systems are hybridizing sensing and therapeutic delivery into single implantable platforms. Movement disorder specialists in Sydney teaching hospitals are piloting these adaptive systems for Parkinson's disease management. The convergence is compressing the traditional separation between diagnostic recording and therapeutic intervention into unified care pathways.
The Therapeutic Goods Administration's active implantable medical devices framework is mandating clinical evidence standards that exceed previous conformity requirements. Imported deep brain stimulation systems now face extended local assessment timelines before reimbursement eligibility. Victoria's public hospital procurement offices are responding by front-loading regulatory documentation requirements into vendor selection criteria.
Hospital purchasing committees are consolidating device procurement with multi-year monitoring service agreements. Bundled contracts are displacing standalone hardware sales in tertiary referral centers across New South Wales and Queensland. This shift is most visible in metropolitan Melbourne, where neurosurgical departments are locking in exclusive programming and battery replacement schedules with single manufacturers.
Australia Neurology Devices Market Segmentation
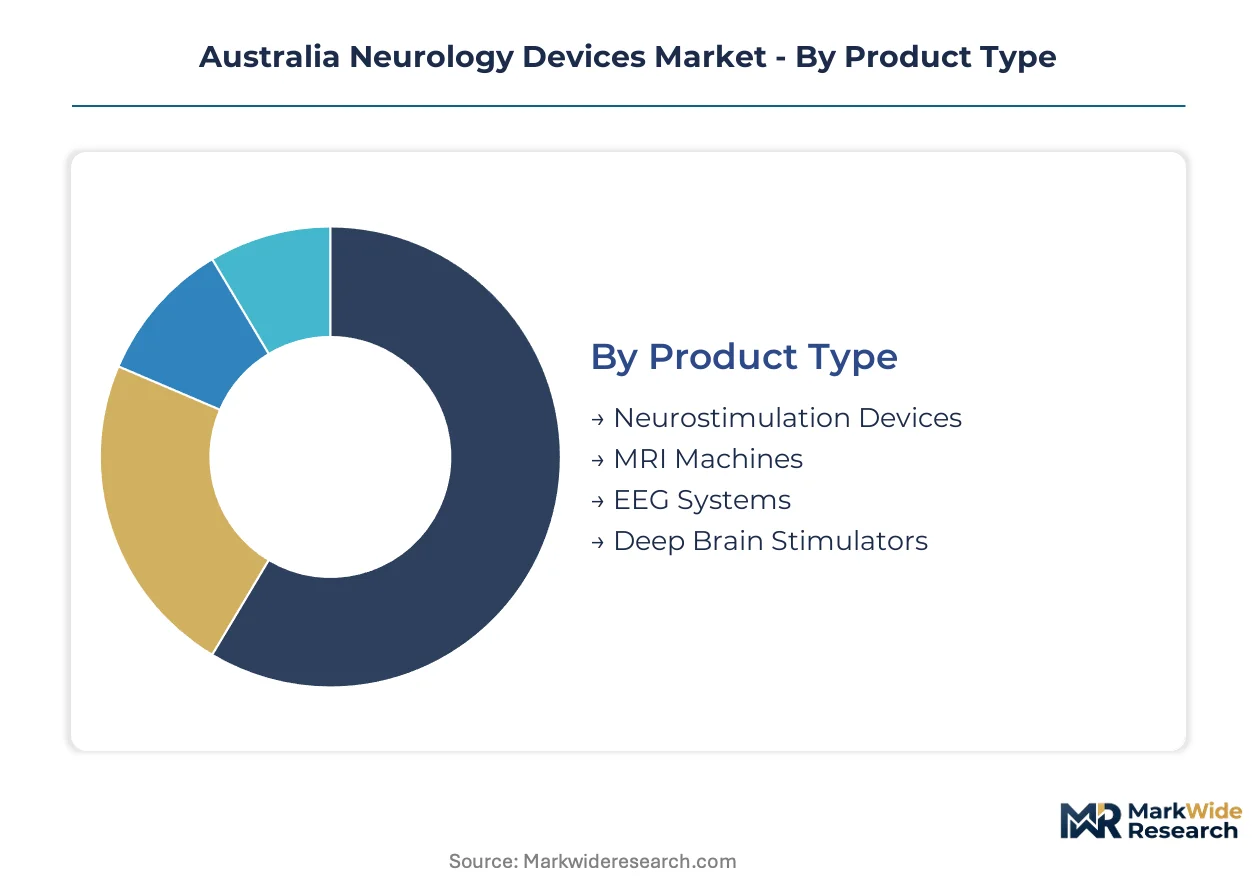
Segmentation reveals how procurement cycles, reimbursement pathways, and clinical workflows fragment demand across device categories. Understanding these divisions exposes where margin pools concentrate and where volume expansion faces structural barriers.
Product Type:
Replacement cycles range from multi-year battery swaps in implantable systems to rapid refresh schedules for diagnostic hardware, creating divergent revenue recognition patterns across manufacturer portfolios.
- Neurostimulation Devices:Implantable pulse generators deliver electrical impulses at programmed frequencies to modulate neural activity. Victorian public hospitals anchor demand through movement disorder programs, with procurement committees favoring vendors offering bundled programming and replacement services.
- MRI Machines:High-field magnetic resonance systems enable structural and functional neuroimaging with superior soft-tissue contrast. Metropolitan Sydney and Melbourne teaching hospitals concentrate installed base, though regional Queensland faces extended procurement timelines due to specialist radiologist scarcity.
- EEG Systems:Cortical monitoring hardware capturing electrical activity through scalp electrodes. Ambulatory surgical centers across New South Wales are expanding intraoperative monitoring capabilities.
- Deep Brain Stimulators:Targeted implantable systems for movement disorder management. TGA compliance investments filter procurement toward established manufacturers with local service infrastructure.
Neurostimulation devices dominate installed base through recurring replacement revenue. EEG systems are where expansion concentrates as ambulatory monitoring spreads beyond tertiary centers.
Application:
Reimbursement maturity separates established indications with MSAC funding from emerging therapies requiring self-funded patient pathways.
- Chronic Pain Management:Spinal cord stimulation and peripheral nerve targeting for refractory neuropathic conditions. Private hospital chains in Sydney prioritize devices with proprietary programming ecosystems that lock in longitudinal service contracts.
- Epilepsy Treatment:Responsive neurostimulation and vagus nerve stimulation for drug-resistant seizure disorders. Victorian public health networks are expanding access following updated TGA guidance on active implantable devices.
- Parkinson's Disease Therapy:Deep brain stimulation targeting subthalamic nucleus or globus pallidus interna. Movement disorder specialists in Melbourne anchor utilization.
- Neurorehabilitation:Brain-computer interfaces and functional electrical stimulation for motor recovery. Home care settings in Queensland represent emerging demand pockets.
Parkinson's disease therapy dominates installed base through established surgical workflows. Chronic pain management is where expansion concentrates as private payers broaden coverage for refractory cases.
End User:
Capital intensity and regulatory compliance requirements stratify procurement authority across facility types.
- Hospitals:Tertiary referral centers with neurosurgical departments and dedicated neurology wards. Public hospitals in Victoria and New South Wales anchor deep brain stimulation procurement through centralized capital budgeting.
- Diagnostic Centers:Outpatient facilities specializing in neurophysiological assessment and imaging. Melbourne-based clusters concentrate high-volume EEG interpretation services.
- Ambulatory Surgical Centers:Same-day procedure facilities expanding intraoperative monitoring capabilities. Sydney metropolitan area leads volume growth.
- Home Care Settings:Patient-domiciled environments for remote monitoring and rehabilitation. Telemedicine integration faces TGA cybersecurity compliance hurdles.
Hospitals dominate installed base through capital-intensive implantable device programs. Ambulatory surgical centers are where expansion concentrates as outpatient neurophysiology migrates from inpatient settings.
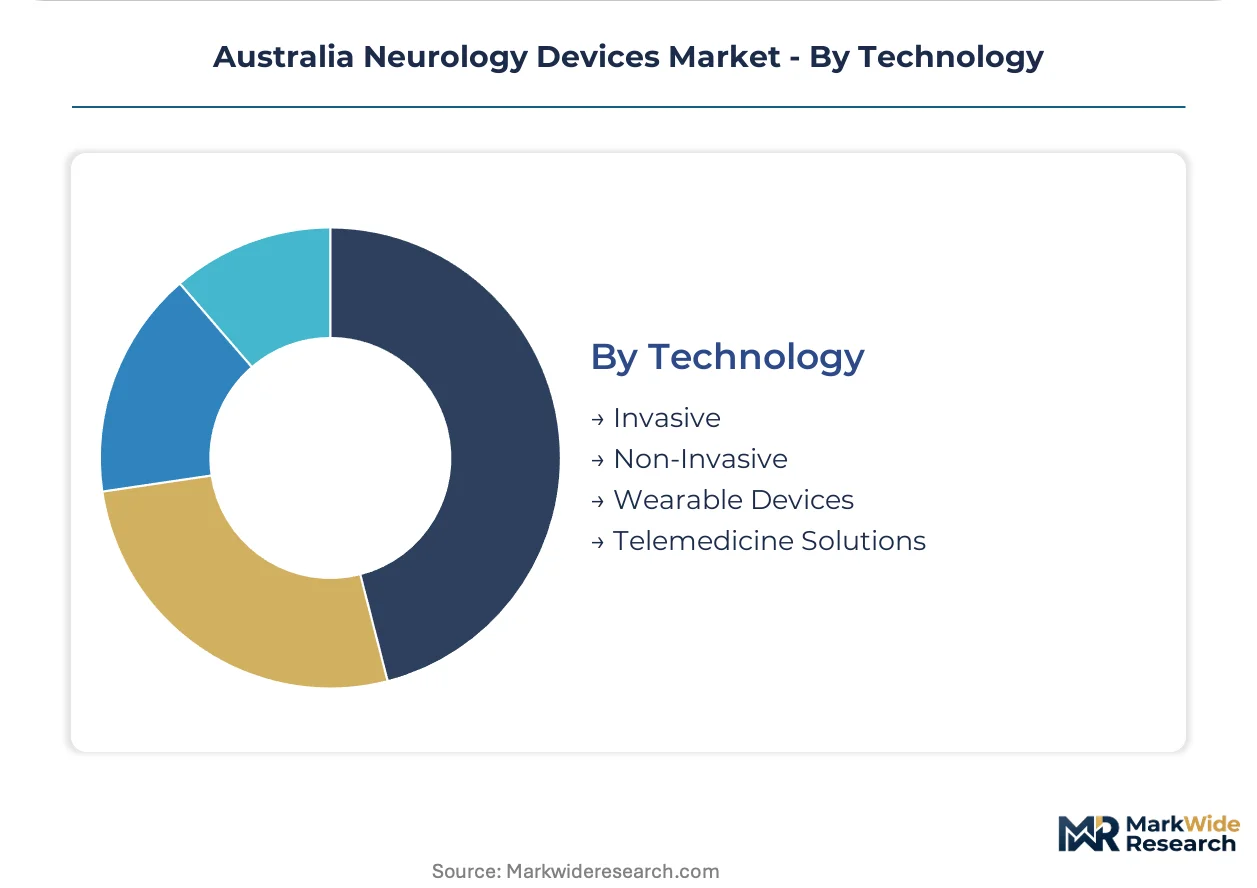
Technology:
Regulatory burden scales with invasiveness, filtering market entry and shaping competitive consolidation patterns.
- Invasive:Surgically implanted systems requiring operating theater infrastructure and specialist surgical capacity. TGA active implantable medical devices framework mandates clinical evidence standards that extend assessment timelines.
- Non-Invasive:External therapeutic and diagnostic systems including transcranial magnetic stimulation. Diagnostic centers in Sydney favor platforms with rapid setup protocols.
- Wearable Devices:Dry electrode arrays and portable monitoring hardware for ambulatory cortical assessment. Melbourne trauma centers pilot patient-specific manufacturing integration.
- Telemedicine Solutions:Remote programming and monitoring platforms for implanted device management. Health Technology Assessment processes through MSAC shape reimbursement eligibility.
Invasive technology dominates installed base through high-value replacement cycles. Wearable devices are where expansion concentrates as dry electrode arrays compress setup times for cortical monitoring.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Metropolitan Sydney and Melbourne buyers exhibit low price elasticity for deep brain stimulation systems, while regional Queensland and Western Australia hospitals face stretched procurement budgets that compress vendor margins.
New South Wales
Tertiary referral hospitals in Sydney concentrate neurostimulation procurement through centralized capital budgeting. The Therapeutic Goods Administration's active implantable medical devices framework filters vendor selection toward compliant manufacturers. The Royal Prince Alfred Hospital and Westmead Hospital anchor deep brain stimulation utilization for movement disorder programs.
Victoria
Public hospital neurology departments in Melbourne are expanding procurement of implantable pulse generators for Parkinson's disease therapy. The Medical Services Advisory Committee shapes reimbursement eligibility for novel neurostimulation therapies. The Alfred Hospital and Austin Health anchor specialist neurosurgical clusters with dedicated functional neurosurgery units.
Queensland
Regional tertiary hospitals outside Brisbane face delayed access timelines due to specialist neurosurgical capacity constraints. The state's health department is negotiating bundled device-and-monitoring contracts to reduce total cost of ownership. The Royal Brisbane and Women's Hospital anchors procurement while Gold Coast and Cairns facilities rely on fly-in surgical teams.
Western Australia
Perth-based teaching hospitals concentrate the state's limited deep brain stimulation capacity. Stryker Corporation maintains specialized sales coverage to serve this geographic isolation. Sir Charles Gairdner Hospital and Royal Perth Hospital manage complex movement disorder referrals from across the vast state territory.
South Australia
The Flinders Medical Centre and Royal Adelaide Hospital anchor neurostimulation services for the state. Procurement committees prioritize vendors with local service infrastructure to minimize device downtime. Interstate patient transfers for complex cases create demand leakage toward Melbourne and Sydney facilities.
Australia Neurology Devices Market Competitive Environment
Multinational device conglomerates and specialized regional manufacturers split the market into distinct capability tiers. The vendor base concentrates around neurostimulation systems with proprietary programming ecosystems that generate recurring service revenue. Three strategic archetypes dominate: integrated neurology platforms with full-stack service infrastructure, specialized neurosurgical device suppliers with targeted geographic coverage, and patient-specific implant fabricators with rapid manufacturing turnaround. Competitive moves center on multi-year hospital agreements locking in exclusive battery replacement schedules and regional sales team expansion into underserved tertiary markets.
Among multinational conglomerates, Medtronic and Stryker Corporation occupy positions exemplifying the integrated platform archetype, leveraging neurostimulation service infrastructure to anchor hospital relationships. Boston Scientific and Abbott Laboratories sit within the same tier, representing diversified medical device portfolios with neurology verticals. Anatomics Pty Ltd, as a Melbourne-based specialty manufacturer, exemplifies the patient-specific fabrication archetype with localized cranial implant production. These named entities illustrate how competitive positioning stratifies between scale-driven service bundling and customization-focused manufacturing proximity.
| Leading Market Players |
|---|
| Medtronic |
| Stryker Corporation |
| B. Braun Melsungen AG |
| Boston Scientific |
| Nihon Kohden Corporation |
| Anatomics Pty Ltd |
| Penumbra, Inc. |
| Abbott Laboratories |
| LivaNova |
| Others |
Value Chain & Pricing Dynamics
Undercapacity in regional Queensland neurosurgical units drives premium pricing for fly-in specialist services while compressing margins for device distributors serving isolated Western Australia hospitals. Metropolitan Sydney and Melbourne's concentrated specialist capacity creates pricing power for manufacturers with local service infrastructure.
Pricing Analysis
Extended battery replacement and programming service contracts generate lifetime value exceeding initial hardware margins. Three-tier pricing structure across premium, standard, and economy levels differentiates by clinical evidence depth and TGA compliance tier. Pricing pressure stems from bundled procurement contracts consolidating toward compliant manufacturers with multi-year monitoring agreements. Regional hospitals exhibit highest price sensitivity due to stretched capital budgets, while metropolitan teaching hospitals prioritize service reliability over unit cost.
Supply Chain Analysis
Extended payment terms from public hospital procurement offices in Victoria and New South Wales strain distributor working capital requirements. Manufacturing concentrates in Ireland, Switzerland, and the United States for implantable pulse generators, while electrode arrays and diagnostic hardware source primarily from Japan and Germany. Supply chain risk centers on single-source vulnerability for proprietary programming platforms and specialized battery cell formats. Distribution runs through authorized dealer networks with TGA certification, anchored by manufacturer-direct service teams in Sydney and Melbourne.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Australia neurology devices market represents early-cycle expansion as closed-loop neurostimulation systems penetrate movement disorder programs and ambulatory EEG capabilities spread beyond tertiary centers.
For Market Incumbents: Pre-empt regional market entry by deploying specialized sales coverage to Queensland tertiary hospitals outside Brisbane before competitors establish service infrastructure. Lock in exclusive programming and battery replacement schedules through multi-year bundled contracts with Victorian and New South Wales public hospital networks. Counter emerging patient-specific manufacturing competition by integrating rapid cranial implant customization into existing neurostimulation service platforms. For New Entrants and Emerging Players: Regional Queensland tertiary hospitals with fly-in surgical dependencies represent the most penetrable entry point for differentiated service models combining device supply with remote programming support. Western Australia's geographic isolation creates whitespace for vendors offering compressed delivery timelines and localized technical support. Home care settings for neurorehabilitation in Queensland present emerging demand pockets accessible through telemedicine-integrated distribution partnerships. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among manufacturers with proprietary programming ecosystems and established battery replacement schedules. Long-term viability across the analysis window favors vendors with TGA-compliant active implantable device portfolios and multi-year hospital agreements. Acquisition targets should demonstrate local service infrastructure depth and MSAC reimbursement pathway progress. The signal to watch is MSAC funding expansion for novel neurostimulation therapies, which would unlock public procurement for previously self-funded procedures.| Strategic Initiative | Industry Significance |
|---|---|
| TGA Compliance Investment | Accelerated local assessment timelines filter procurement toward manufacturers with established clinical evidence packages. |
| Hospital System Partnership | Exclusive multi-year agreements with Royal Prince Alfred Hospital and The Alfred Hospital lock in replacement revenue streams. |
| Regional Sales Expansion | Specialized coverage in Gold Coast and Cairns addresses Queensland's specialist neurosurgical capacity constraints. |
| Software Companion Development | Proprietary programming platforms create switching costs that suppress price competition and anchor service contracts. |
| Reimbursement Strategy | MSAC pathway navigation for novel neurostimulation therapies unlocks public funding and expands addressable patient populations. |
Study Parameters
Operator-level perspectives from neurosurgeons, hospital purchasing committee members, biomedical engineers, and GPO contracts managers anchored the qualitative base. Primary interviews combined with secondary validation from TGA regulatory filings, MSAC assessment reports, hospital procurement databases, and public health network capital budget disclosures. Bottom-up installed base modeling and top-down market sizing triangulated volume and value estimates.
Scenario-bracketing framed analytical outputs across the projection horizon, with segmentation modeling across product type, application, end user, and technology dimensions. CAGRs derived from fitted growth curves incorporating replacement cycle dynamics, regulatory pathway timelines, and reimbursement expansion trajectories. Forecast inputs included TGA active implantable device approval rates and MSAC funding decision pipelines.
Macroeconomic conditions sit as an overlay; deviation in public health expenditure growth or specialist workforce availability would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory harmonization progress and reimbursement pathway maturation. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Neurology
Global Diabetic Neuropathy Treatment Market
Neurology
Global Neurovascular Embolization Devices (Neurology) Market
Neurology
Parkinsons Disease Therapeutics Market
Neurology
Neurodegenerative Disease Treatment Market
Neurology
Amnestic Disorders Therapeutics Market
Neurology
North America Neurology Monitoring Market
Neurology
Movement Disorder Market
Neurology
Cerebral Spinal Fluid (CSF) Management Market
Neurology
Spinal Laminoplasty Market
Neurology
Mild Cognitive Impairment Market
Neurology
Chiari Malformation Treatment Market
Neurology
Arachnoiditis Treatment Market
Neurology
China Neurology Devices Market
Neurology
Traumatic Brain Injuries Assessment Market
Neurology
Diabetic Neuropathy Market
Neurology
Netherlands Neurology Devices Market