
 Asia-Pacific Hand Sanitizer Market | 2026-2036
Asia-Pacific Hand Sanitizer Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Hand Sanitizer Market Analysis
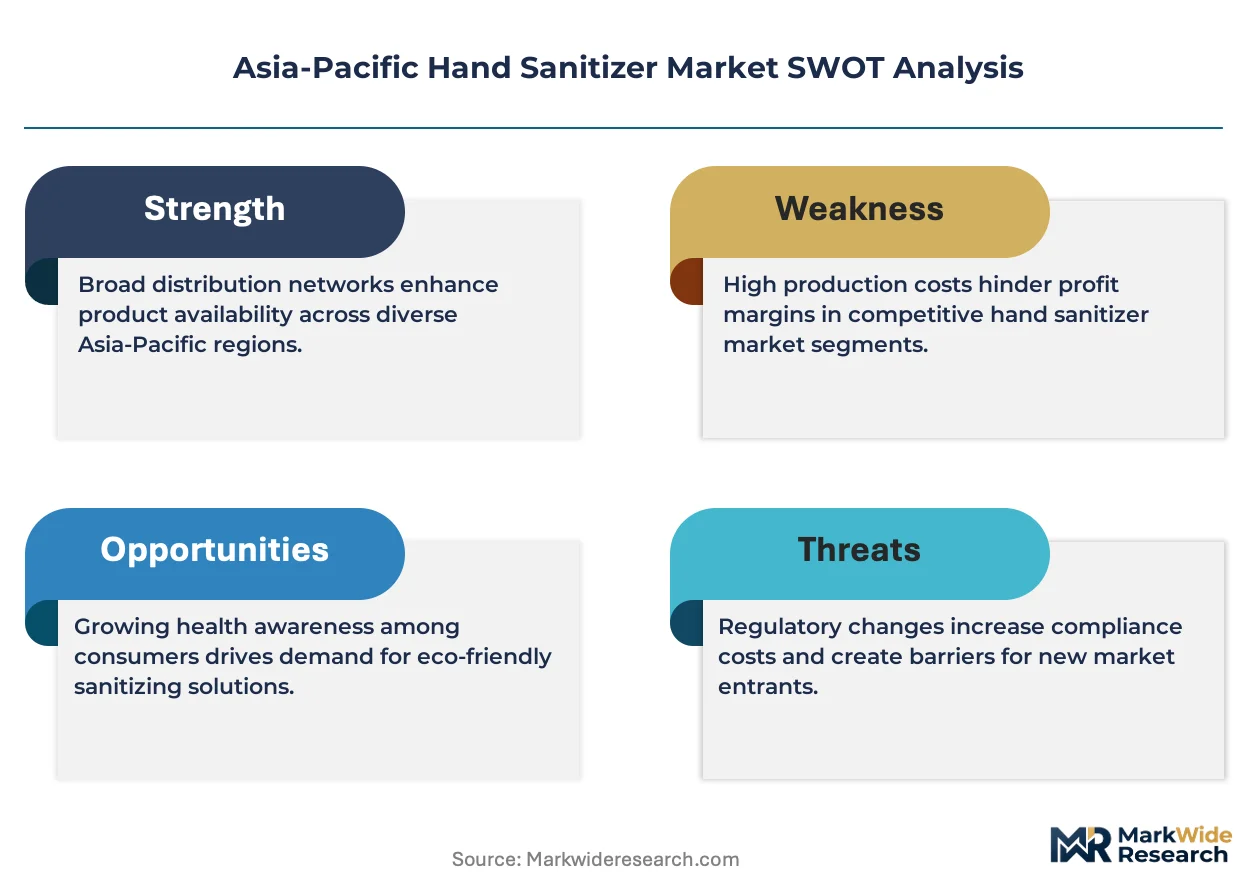
Premium clinical-grade sanitizer pricing is decoupling from commodity household variants as ingredient purity standards diverge. Kao Corporation leverages its Japanese manufacturing base to sustain high-alcohol formulations for medical channels. Godrej Consumer Products anchors mass-market penetration across Indian tier-two cities through cost-efficient gel formats. Unilever competes on brand recognition in Southeast Asian retail shelves, while 3M Company specializes in industrial-strength dispensers for factory floor deployments.
Asia-Pacific hand sanitizer denotes topical antiseptic solutions formulated with ethanol, isopropyl alcohol, or benzalkonium chloride at concentrations typically ranging from 60% to 95% active ingredient, designed for pathogen reduction on human hands without water rinsing. Manufacturing employs continuous batch blending with pH stabilization and viscosity modulation to achieve gel, foam, or spray delivery systems. Gel formulations dominate volume throughput due to lower packaging complexity and established consumer familiarity across pharmacy and supermarket channels. Alcohol-based formulations capture the majority of healthcare procurement budgets, while foam variants gain traction in educational institutions where rapid-dry properties reduce classroom disruption. Online retail distribution accelerates fastest among channels, though pharmacies retain margin density through clinical credibility and professional recommendation leverage.
India's CDSCO mandates alcohol percentage disclosure on all therapeutic sanitizer labels, while Australia's TGA enforces Good Manufacturing Practice certification for hospital-grade supply. China's SAMR supervises cosmetic-versus-drug classification disputes that determine import tariff treatment for foreign brands. Japan's PMDA evaluates quasi-drug registrations for antimicrobial claims, creating multi-month approval timelines that filter market entrants. Stakeholders must monitor evolving classification harmonization between cosmetic and pharmaceutical regulators, as reclassification decisions reshape competitive access and compliance investment requirements.
Market Dynamics
Hospital-grade alcohol concentration mandates from India's CDSCO and Australia's TGA are fragmenting manufacturing compliance requirements, forcing producers to maintain parallel formulation lines and dual-label inventories across the region.
Growth Catalysts
- CDSCO Labeling Mandates:India's therapeutic goods regulator now requires precise alcohol percentage disclosure on all sanitizer packaging, compelling manufacturers to reformulate toward standardized 70-75% ethanol concentrations that align with WHO guidelines.
- Healthcare Facility Expansion:Southeast Asian hospital networks are scaling bulk procurement of clinical-grade formulations for surgical theaters and isolation wards, creating dedicated supply contracts that bypass retail distribution entirely.
- Quasi-Drug Pathway:Japan's PMDA registration process for antimicrobial claims, despite its multi-month timeline, validates product efficacy in ways that command premium positioning in pharmacy channels across East Asia.
Market Restraints
- Ethanol Input Volatility:Fuel-grade ethanol diversion to biofuel programs in Indonesia and Thailand periodically constrains industrial alcohol supply for sanitizer production, squeezing margin structures during harvest seasons.
- Concentrated Active Ingredient Supply:Isopropyl alcohol production concentrates in South Korean and Chinese petrochemical complexes, exposing downstream formulators to single-source dependency risks during port congestion or maintenance turnarounds.
- Cosmetic-Drug Classification Friction:China's SAMR maintains ambiguous jurisdiction boundaries between cosmetic and pharmaceutical sanitizer categories, creating import tariff uncertainty that delays foreign brand market entry.
Strategic Opportunities
- Tier-Two Indian Urbanization:Godrej Consumer Products and regional competitors are establishing gel production facilities in Pune and Ahmedabad to capture pharmacy and modern trade penetration in cities below two million population.
- Foam Format Education Adoption:Australian primary schools and Japanese universities are specifying rapid-dry foam dispensers for classroom deployment, opening institutional procurement channels that favor automated wall-mounted systems over portable bottles.
- E-Commerce Direct Distribution:Online retail platforms in Indonesia and Vietnam are bypassing traditional pharmacy intermediaries, enabling private-label brands to reach household buyers with subscription replenishment models.
Industry Challenges
- PMDA Registration Timeline Compression:Japan's quasi-drug approval process requires extensive antimicrobial efficacy documentation that extends product launch cycles to 12-18 months, demanding sustained R&D investment without revenue offset.
- Cross-Border Formulation Harmonization:Manufacturers serving both Australian TGA hospital-grade specifications and Indian CDSCO therapeutic claims must maintain incompatible alcohol concentration ranges, complicating regional production consolidation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Hand Sanitizer Market |
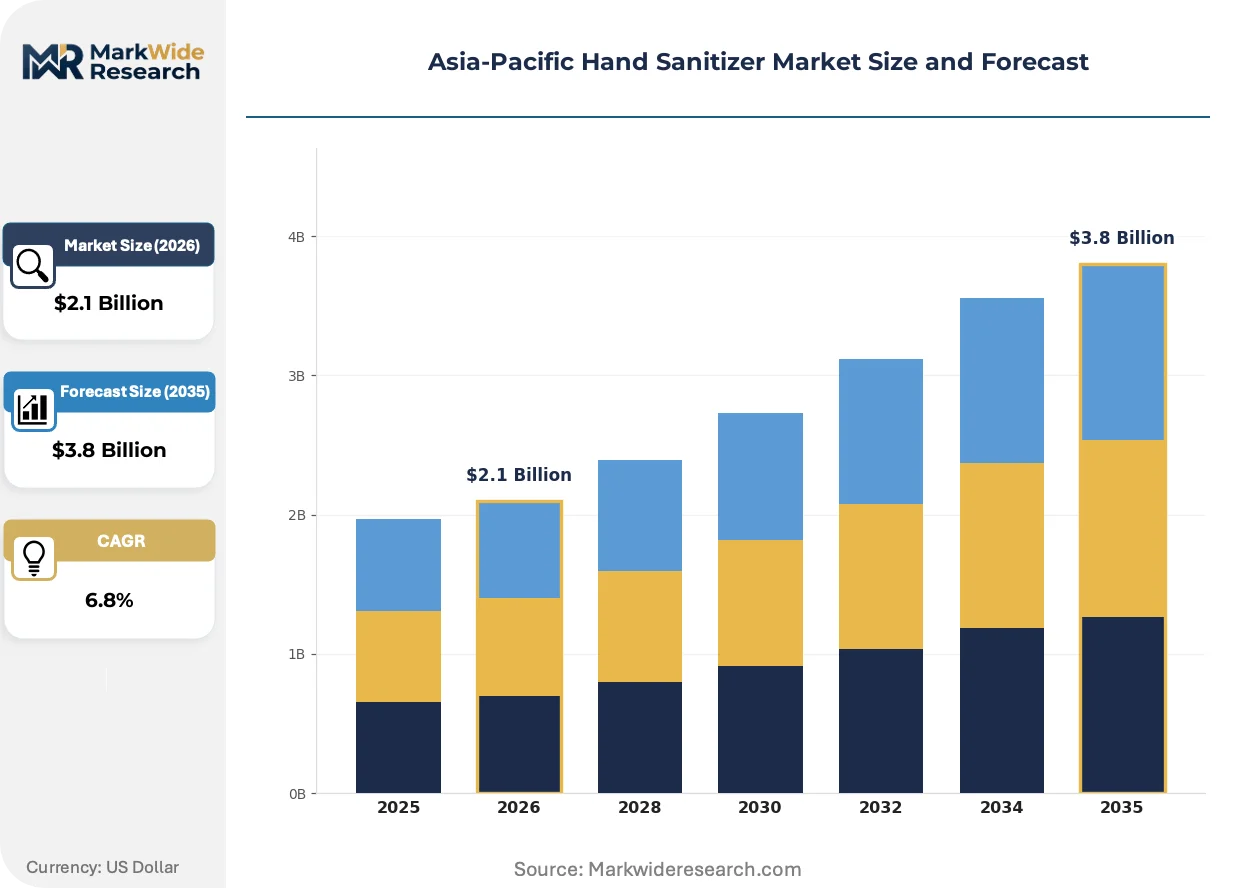
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.8 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gel, Foam, Spray, Wipes End User: Households, Healthcare Facilities, Educational Institutions, Businesses Distribution Channel: Supermarkets, Online Retail, Pharmacies, Convenience Stores Formulation: Alcohol-Based, Non-Alcohol-Based, Herbal, Antibacterial |
| Companies Covered | Kao Corporation, Lion Corporation, JMnano, Unilever, 3M Company, GOJO Industries, Procter & Gamble, Reckitt Benckiser Group, Godrej Consumer Products, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Hand Sanitizer Market Emerging Trajectories
Formulation chemistry and delivery mechanism engineering are diverging sharply between clinical-grade and household sanitizer segments, with regulatory compliance becoming the primary axis of product differentiation rather than price positioning alone.
Encapsulated alcohol technology is integrating timed-release polymers that extend antimicrobial persistence on skin surfaces beyond the evaporation point of conventional ethanol gels. Australian surgical supply purchasers are piloting these formulations in operating theater pre-scrub protocols. This technology is integrating extended-duration protection claims that justify 40-60% price premiums over standard gel alternatives in hospital procurement tenders.
Australia's TGA tightened Good Manufacturing Practice certification requirements for all hospital-grade sanitizer suppliers in early 2024, mandating batch-level alcohol concentration verification and independent laboratory assay documentation. Domestic manufacturers have absorbed compliance costs through dedicated quality control staffing, while imported brands face extended customs inspection protocols. Southeast Asian contract manufacturers are responding by seeking TGA pre-certification to maintain access to Australian healthcare procurement channels.
Pharmacy channel loyalty is eroding as Indonesian and Vietnamese consumers migrate to mobile-commerce platforms for routine household sanitizer replenishment. Shopee and Lazada fulfillment centers now stock regional distribution hubs with economy-format sachets and bulk refill pouches that undercut pharmacy per-unit pricing by 25-35%. Metro Manila and Ho Chi Minh City exhibit the most pronounced channel shift, with traditional pharmacy sanitizer shelf space contracting 15-20% in favor of personal care and supplement categories.
Asia-Pacific Hand Sanitizer Market Segmentation
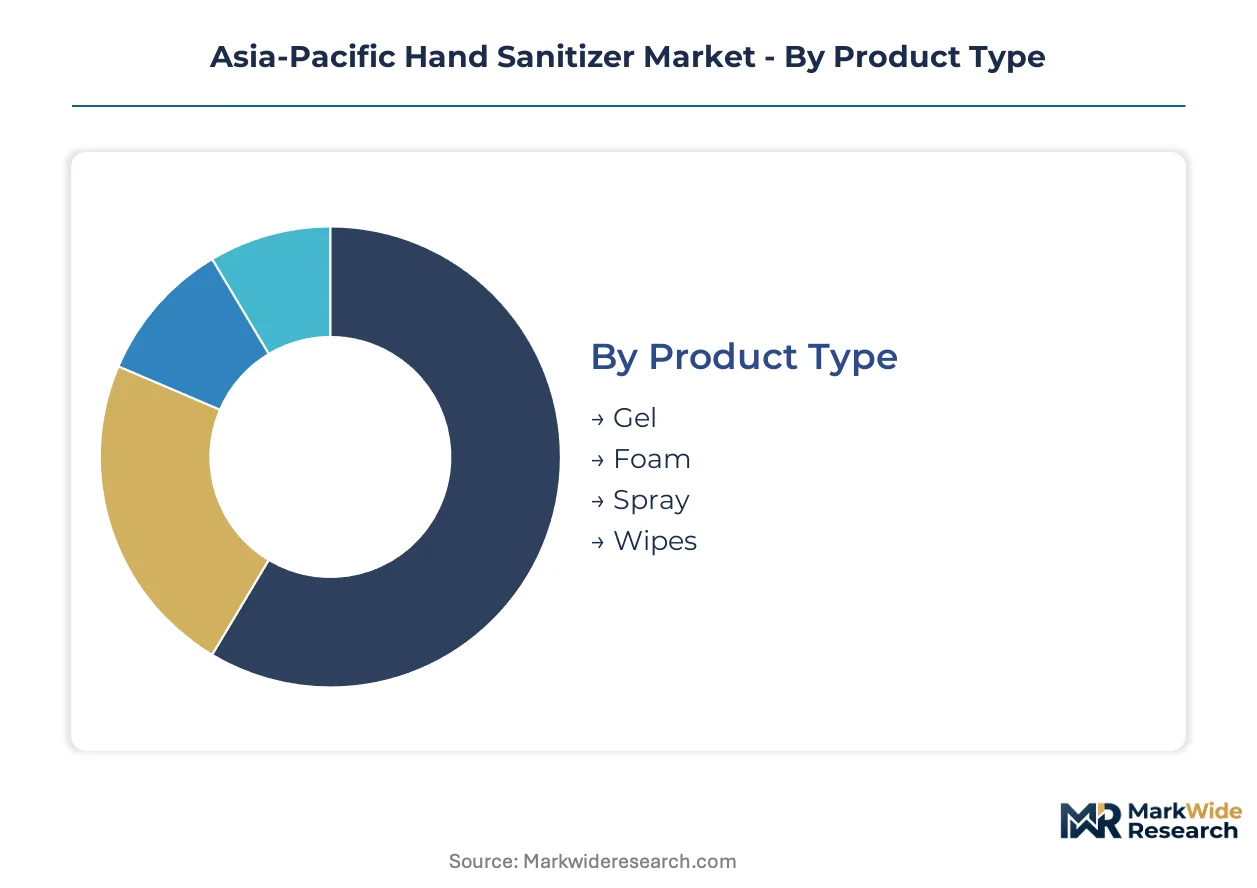
Segmentation in Asia-Pacific hand sanitizer markets reflects divergent compliance requirements and channel economics. Hospital-grade formulations demand GMP certification and precise alcohol disclosure, while household variants compete on packaging convenience and price positioning. Understanding these splits enables targeted production investments and regulatory navigation.
Product Type:
Gel, foam, spray, and wipe formats sit at different points on the standardization-customization spectrum, with gel offering lowest production complexity and foam requiring specialized dispenser integration.
- Gel:Viscous ethanol or isopropyl alcohol suspensions with carbomer or cellulose thickeners achieve 60-95% active concentration. Indian pharmacy chains and Australian supermarket shelves both favor gel for its spill resistance and established consumer habit. CDSCO labeling mandates push manufacturers toward standardized 70-75% ethanol ranges that simplify cross-border production.
- Foam:Air-entrained formulations dispense through specialized pump mechanisms that reduce per-use volume by 30-40% versus gel equivalents. Japanese universities and Australian primary schools specify foam dispensers for rapid-dry properties that minimize classroom disruption. PMDA quasi-drug registration requirements extend approval timelines for antimicrobial foam claims.
- Spray:Low-viscosity alcohol solutions in trigger or aerosol delivery suit industrial and vehicular applications where rapid surface coverage matters. Indonesian factory floors deploy spray formats for equipment sanitization protocols.
- Wipes:Nonwoven substrates saturated with alcohol or quaternary ammonium solutions target travel and foodservice segments. Vietnam's hospitality sector sources bulk wipe canisters for table sanitization between guests.
Leading the category by volume: gel. Growing fastest: foam.
End User:
Customer archetypes range from price-sensitive mass consumers to procurement-professional institutions with stringent certification requirements.
- Households:Individual consumers purchasing through retail or e-commerce channels prioritize unit economics and brand recognition. Shopee and Lazada subscription models in Indonesia and Vietnam capture recurring replenishment demand with 25-35% pharmacy undercut pricing.
- Healthcare Facilities:Hospitals, clinics, and surgical theaters require TGA GMP certification or CDSCO therapeutic goods registration. Australian hospital networks now mandate batch-level alcohol verification and independent laboratory assay documentation. Southeast Asian hospital procurement bypasses retail entirely through dedicated supply contracts.
- Educational Institutions:Schools and universities specify rapid-dry formats and automated wall-mounted dispensers over portable bottles. Australian primary schools and Japanese universities drive foam format specification.
- Businesses:Corporate offices, manufacturing plants, and foodservice operations balance cost efficiency with employee safety compliance. 3M Company specializes in industrial-strength dispensers for factory floor deployments across the region.
Highest margin concentration: healthcare facilities. Expanding most quickly: educational institutions.
Distribution Channel:
Channel selection determines margin capture, with direct e-commerce eroding traditional pharmacy intermediaries.
- Supermarkets:Mass-market gel formats dominate shelf space with economy pricing and promotional bundling. Unilever competes on brand recognition in Southeast Asian retail shelves.
- Online Retail:Mobile-commerce platforms in Indonesia and Vietnam enable private-label brands to reach household buyers with subscription replenishment models. Metro Manila and Ho Chi Minh City exhibit the most pronounced channel shift.
- Pharmacies:Clinical credibility and professional recommendation leverage sustain margin density despite shelf space contraction of 15-20% in favor of personal care categories. Kao Corporation leverages Japanese manufacturing to sustain high-alcohol formulations for medical pharmacy channels.
- Convenience Stores:Impulse-purchase single units and travel-size formats target urban commuters. Tier-two Indian cities below two million population show rising convenience store penetration.
Steepest expansion trajectory: online retail. Margin preservation: pharmacies.
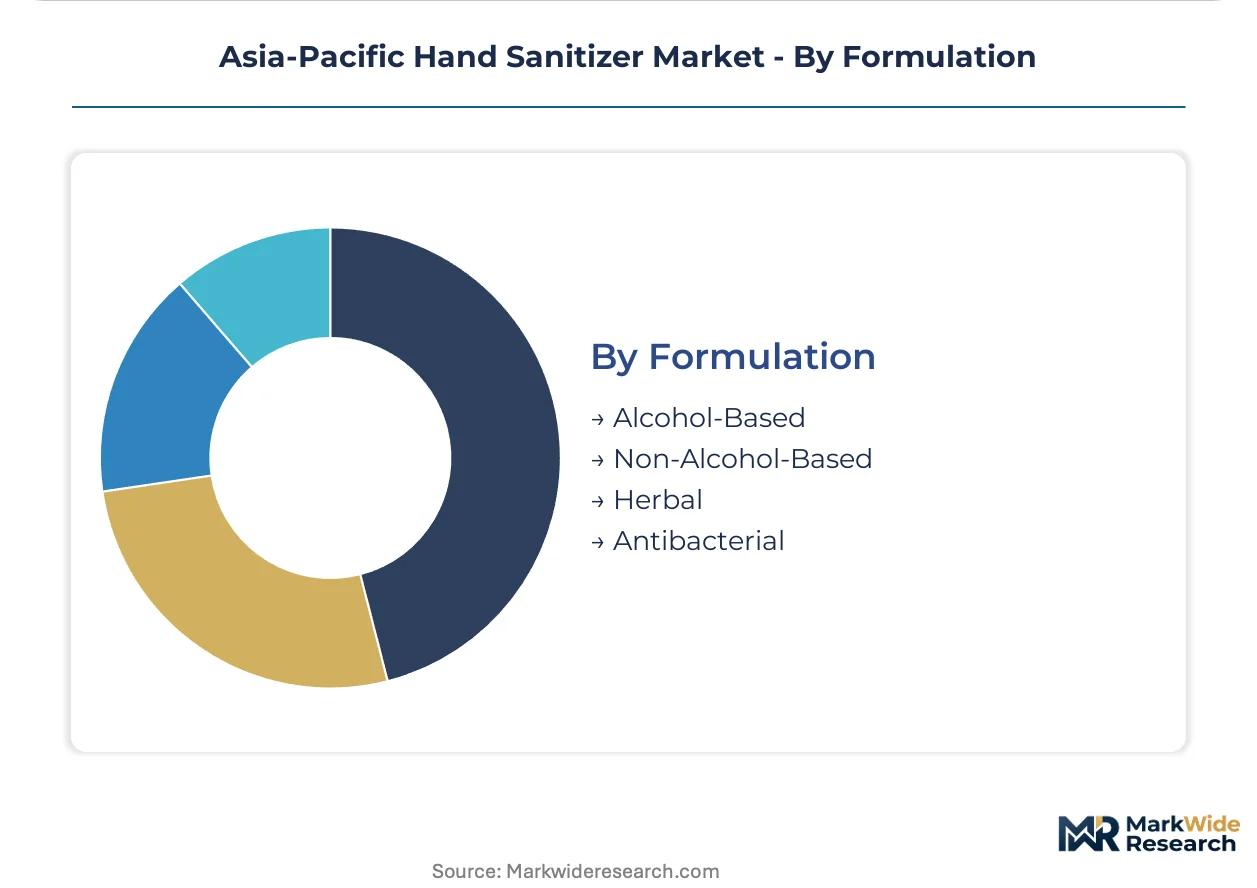
Formulation:
Active ingredient chemistry determines regulatory classification and market access across cosmetic-drug jurisdiction boundaries.
- Alcohol-Based:Ethanol or isopropyl alcohol at 60-95% concentration achieves WHO-recommended pathogen reduction. Captures majority of healthcare procurement budgets across Southeast Asian hospital networks. China's SAMR cosmetic-versus-drug classification disputes create import tariff uncertainty for foreign brands.
- Non-Alcohol-Based:Benzalkonium chloride or other quaternary ammonium compounds suit environments with alcohol ignition risks or skin sensitivity concerns. Aviation and electronics manufacturing facilities specify non-flammable alternatives.
- Herbal:Plant-derived extracts with limited antimicrobial validation target natural-product consumer segments. Indian ayurvedic formulations navigate CDSCO therapeutic claims scrutiny.
- Antibacterial:Triclosan or triclocarban formulations face regulatory pressure from environmental and resistance concerns. Australia's TGA and Japan's PMDA maintain stricter oversight than household cosmetic regulators.
Volume dominance: alcohol-based. Regulatory headwinds: antibacterial.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mumbai anchors Asia-Pacific sanitizer procurement through its pharmaceutical distribution corridors and hospital network procurement hubs. The city's wholesale markets channel formulations to tier-two cities across western India. CDSCO labeling enforcement has concentrated compliance expertise in this cluster.
India
Urban pharmacy chains in Delhi and Bangalore drive household gel demand through modern trade formats. CDSCO mandates precise alcohol percentage disclosure on therapeutic sanitizer packaging. Pune and Ahmedabad host new production facilities targeting tier-two city penetration below two million population.
Australia
Metropolitan hospital networks in Sydney and Melbourne scale bulk procurement of clinical-grade formulations for surgical theaters. TGA tightened Good Manufacturing Practice certification requirements in early 2024 with batch-level verification mandates. Domestic manufacturers absorb compliance costs through dedicated quality control staffing.
Japan
Universities and primary schools in Tokyo and Osaka specify rapid-dry foam dispensers for classroom deployment. PMDA quasi-drug registration processes require extensive antimicrobial efficacy documentation extending launch cycles. Kao Corporation leverages its domestic manufacturing base for high-alcohol medical channel formulations.
Indonesia
Shopee and Lazada fulfillment centers in Jakarta and Surabaya stock regional hubs with economy sachets and bulk refill pouches. Mobile-commerce platforms bypass traditional pharmacy intermediaries with subscription replenishment models. Metro Manila and Ho Chi Minh City exhibit pronounced channel shift with pharmacy shelf space contracting.
Vietnam
Hospitality sector demand in Ho Chi Minh City and Hanoi sources bulk wipe canisters for table sanitization between guests. Factory floors deploy spray formats for equipment sanitization protocols. E-commerce direct distribution enables private-label brands to reach household buyers outside pharmacy networks.
Asia-Pacific Hand Sanitizer Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across formulation and delivery system development. The market structure fragments between multinational consumer goods conglomerates with brand recognition advantages and regional specialists with regulatory compliance proximity. Three archetypes dominate: Japanese quasi-drug registrants with PMDA-validated efficacy claims, Indian mass-market gel producers with tier-two distribution depth, and Southeast Asian contract manufacturers seeking TGA pre-certification. Competitive moves concentrate on automated dispenser integration for institutional channels and e-commerce subscription infrastructure for household replenishment.
Among Japanese-based specialists, Kao Corporation and Lion Corporation occupy positions anchored by domestic manufacturing infrastructure and quasi-drug registration expertise. Unilever represents the multinational consumer goods archetype competing on brand recognition across Southeast Asian retail shelves. Godrej Consumer Products exemplifies the India-focused mass-market specialist with cost-efficient production formats and tier-two city penetration strategies.
| Leading Market Players |
|---|
| Kao Corporation |
| Lion Corporation |
| JMnano |
| Unilever |
| 3M Company |
| GOJO Industries |
| Procter & Gamble |
| Reckitt Benckiser Group |
| Godrej Consumer Products |
| Others |
Supply Flow & Price Mechanics
Southeast Asian hospital procurement networks concentrate purchasing power for clinical-grade formulations, enforcing contract-based long-term offtake agreements that lock in volume commitments and compress spot-market exposure for manufacturers. This buyer concentration rewards TGA-certified domestic producers with pricing stability while forcing import-dependent brands into tariff-absorbing margin sacrifices.
Pricing Analysis
Value-based pricing anchored to antimicrobial efficacy validation commands 40-60% premiums in Australian surgical theater procurement. Three-tier pricing structure across premium, standard, and economy levels separates PMDA-registered quasi-drugs from cosmetic-grade household gels and bulk institutional refills. Pricing pressure stems from Indonesian and Vietnamese e-commerce platforms undercutting pharmacy channels by 25-35% through subscription replenishment models. Healthcare facilities exhibit lowest price sensitivity due to GMP certification requirements, while mass-market household buyers in Indian tier-two cities drive aggressive cost competition.
Supply Chain Analysis
Dual-sourcing requirements from Australian hospital networks mandate qualified suppliers in both domestic manufacturing and pre-certified Southeast Asian contract facilities. Industrial alcohol feedstock concentrates in South Korean and Chinese petrochemical complexes, with carbomer thickeners and specialized foam pump mechanisms drawing from Japanese and Taiwanese component specialists. Single-source vulnerability in isopropyl alcohol production exposes formulators to port congestion disruptions during regional maintenance turnarounds. Distribution runs through pharmaceutical wholesale corridors in Mumbai and Jakarta, with e-commerce fulfillment centers increasingly bypassing traditional intermediaries in Metro Manila and Ho Chi Minh City.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Competitive positioning in this market is accelerating into a vertical-integration race, with manufacturers pursuing captive ethanol distillation capacity to insulate margins from biofuel program diversion in Indonesia and Thailand.
For Market Incumbents: Acquire fermentation-based ethanol production assets in Maharashtra and Gujarat to secure feedstock independence from fuel-grade diversion. Consolidate position by pre-certifying Southeast Asian contract facilities for TGA hospital-grade compliance before 2024 batch-verification mandates harden import barriers. Channel control through automated dispenser installation in Australian educational institutions defends against private-label e-commerce erosion. For New Entrants and Emerging Players: Encapsulated alcohol timed-release technology offers a technology-first wedge into Australian surgical supply tenders where extended-duration protection justifies premium positioning. White-space concentration sits in Indonesian and Vietnamese subscription-based household replenishment, where pharmacy shelf space contraction creates direct-to-consumer openings. Target foam format specification in Japanese university procurement as the most penetrable institutional segment. For Investors and Strategic Acquirers: The window for entry favors regional specialists with existing quasi-drug registration expertise over multinational brand portfolios lacking PMDA validation infrastructure. Long-term viability rests on acquisition of mid-cap Indian gel producers with established tier-two distribution depth rather than greenfield capacity builds. Watch CDSCO therapeutic classification harmonization attempts as the signal for competitive access reshaping.| Strategic Initiative | Industry Significance |
|---|---|
| TGA Pre-Certification Investment | Secures access to Australian hospital procurement channels before import inspection protocols harden. |
| Backward Integration into Ethanol Distillation | Captive feedstock supply insulates margin structures from Indonesian biofuel program diversion. |
| Foam Dispenser Automated Installation | Wall-mounted system deployment locks in Japanese university and Australian primary school specifications. |
| E-Commerce Subscription Infrastructure | Direct household replenishment in Indonesia and Vietnam bypasses pharmacy intermediary margin capture. |
| CDSCO Therapeutic Registration Pathway | Precise alcohol percentage disclosure compliance enables premium positioning in Indian pharmacy chains. |
Methodological Framework
Regulatory filings from CDSCO, TGA, PMDA, and SAMR, trade flow databases, and hospital procurement contract records formed the secondary backbone for supply-side mapping. Primary interviews with formulation chemists at regional manufacturers, pharmacy chain category managers in Delhi and Bangalore, and biomedical procurement officers at Australian metropolitan hospital networks validated demand-side assumptions. Bottom-up volume builds from production facility utilization rates and top-down expenditure flows from healthcare capital budgets were triangulated to constrain estimate variance.
Bottom-up modeling anchored forecasts to individual country-level regulatory cluster evolution and channel shift velocity across the projection horizon. Segmentation dimensions included product format, end-user archetype, distribution channel, and formulation chemistry classification. CAGRs were derived from alcohol input cost trajectory assumptions and healthcare facility expansion pipelines. PMDA registration timeline compression and CDSCO labeling mandate enforcement schedules served as key forecast sensitivity inputs.
Several conditions sit outside the modeled scope, including sudden reclassification of cosmetic-versus-drug sanitizer categories by China's SAMR and unanticipated fuel-grade ethanol export restrictions by Indonesian or Thai authorities. Forecasts reflect assumptions about regulatory harmonization progress and biofuel policy stability. Deviation in PMDA quasi-drug approval timeline compression or TGA GMP certification reciprocity agreements would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Infection Control
Ultraviolet Germicidal Irradiation Market
Infection Control
Pertussis Infection Testing Market
Infection Control
Alcohol Wipes Market
Infection Control
Infection Prevention Market
Infection Control
Intra-Abdominal Infection Treatment Market
Infection Control
Hand Hygiene Market
Infection Control
Dental Infection Treatment Market
Infection Control
Salivary Gland Infection Market
Infection Control
Multi-Surface Disinfection Booster Systems with Low QAC Load Market
Infection Control
Hand Sanitizer Spray Market
Infection Control
Yeast Infection Market
Infection Control
Ultrasound Probe Disinfection Market
Infection Control
Medical Activated Carbon Dressing Market
Infection Control
Global Viral Inactivation Market
Infection Control
Australia Healthcare Surface Disinfectant Wipes Market
Infection Control
Community Acquired Pneumonia (CAP) Market