
 Ultrasonic Flow Meter Market | 2026-2036
Ultrasonic Flow Meter Market Size, Share, and Industry Trends Forecast 2026-2036
Ultrasonic Flow Meter Market Intelligence
IEC 61508 functional safety certification is rotating as the primary gate for suppliers serving oil and gas custody-transfer applications. Emerson Electric Co. leverages its Rosemount instrumentation heritage to sustain premium positioning in North American petrochemical contracts. KROHNE Group anchors European demand through deep calibration laboratory investments in Germany and the Netherlands. Siemens AG competes on digital twin integration, bundling ultrasonic flow data into its SIMATIC process control ecosystem.
An ultrasonic flow meter measures fluid velocity by transmitting acoustic pulses between transducers and calculating transit-time differentials or frequency shifts, with typical accuracy ranging from ±0.5% to ±1.0% of reading depending on pipe diameter and fluid homogeneity. The device serves primarily to enable non-intrusive volumetric measurement in closed pipes without pressure drop or moving parts. Transit time technology dominates custody-transfer applications where precision drives contract valuation, while clamp-on configurations represent the fastest-expanding product category due to retrofit demand across aging water distribution networks. Oil and gas measurement applications concentrate margin pools at the high end, where dual-beam and four-path designs command pricing premiums for multiphase flow conditions.
The EPA enforces Clean Water Act compliance timelines that accelerate municipal utility replacement cycles, while the EU F-Gas Regulation indirectly shapes meter specification through refrigerant monitoring mandates in HVAC applications. OIML R137 international metrology standards govern custody-transfer certification, creating barrier-to-entry effects for uncertified manufacturers. Stakeholders must monitor evolving hydrogen blending requirements in natural gas pipelines, as transit-time ultrasonic designs face recalibration demands for compressibility-adjusted flow computation at variable hydrogen concentrations.
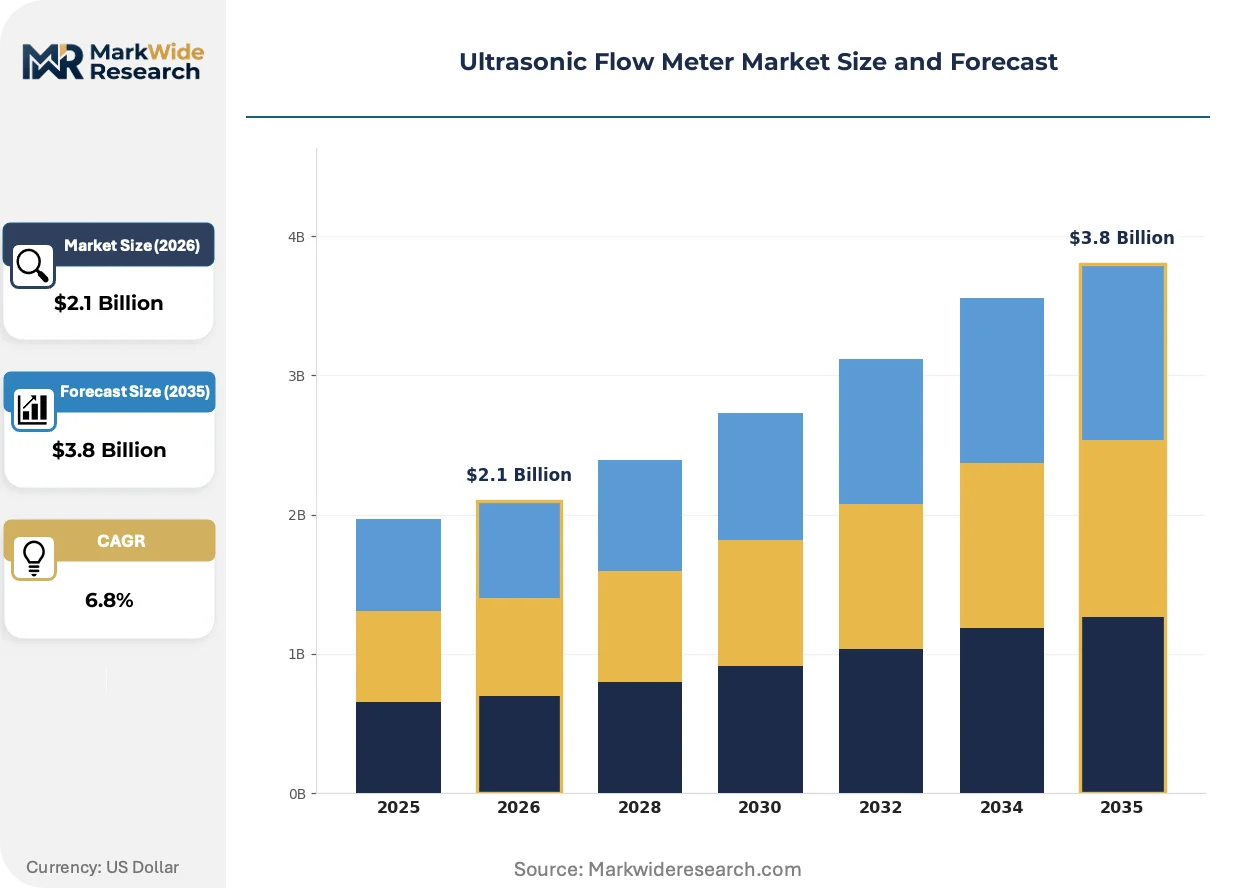
Market Dynamics
The ultrasonic flow meter market pivots on non-intrusive measurement technology displacing mechanical alternatives across municipal water infrastructure, with regulatory mandates for lead-free monitoring systems compressing replacement cycles in aging distribution networks.
Growth Catalysts
- EPA Lead and Copper Rule revisions:Municipal utilities in the United States face compelled upgrades from legacy mechanical meters to non-intrusive ultrasonic alternatives, eliminating pipeline shutdowns during installation.
- Clamp-on retrofit configurations:Water and wastewater utilities are expanding adoption of externally mounted transducer systems to bypass excavation and hot-tap requirements in aging pipe networks.
- Rhine corridor industrial automation cluster:Dense concentration of process instrumentation engineering in Germany sustains calibration infrastructure and skilled technician pipelines for custody-transfer applications.
Market Restraints
- High-purity ceramic transducer costs:Piezoelectric crystal supply concentrates among specialized Japanese and German material suppliers, creating input cost volatility for meter manufacturers.
- Multiphase flow measurement limitations:Transit-time designs face accuracy degradation in crude oil with high gas void fractions, restricting penetration in upstream production metering.
- OIML R137 certification friction:International metrology standards create multi-year approval timelines for custody-transfer applications, blocking uncertified manufacturers from premium segments.
Strategic Opportunities
- Hydrogen blending in natural gas pipelines:Variable hydrogen concentrations demand recalibrated compressibility-adjusted flow computation, opening retrofit demand for transit-time ultrasonic designs.
- EU F-Gas Regulation refrigerant monitoring:HVAC system leak detection mandates create new specification requirements for compact ultrasonic meters in building automation.
- Digital twin integration:Bundling flow data into process control ecosystems enables predictive maintenance contracts and recurring software revenue streams.
Industry Challenges
- IEC 61508 functional safety certification:Oil and gas custody-transfer applications demand SIL-rated designs, extending product development timelines and engineering headcount requirements.
- Legacy SCADA integration complexity:Municipal utilities operate decades-old telemetry infrastructure, forcing custom protocol adapters and field commissioning delays.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ultrasonic Flow Meter Market |
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.8 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Transit Time, Doppler, Hybrid, Clamp-on, Insertion Technology: Dual Beam, Triangulation, Phase Shift, Ultrasonic Pulse, Continuous Wave Application: Water & Wastewater, Oil & Gas Measurement, Chemical Processing, Food & Beverage, Power Generation End User: Municipal Utilities, Petrochemical Plants, Food Processing Units, Power Stations, HVAC Companies |
| Companies Covered | Siemens AG, Emerson Electric Co., Endress+Hauser Group Services AG, KROHNE Group, Badger Meter, Inc., Danfoss, Fuji Electric Co., Ltd., Baker Hughes Company, Honeywell International Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ultrasonic Flow Meter Market Strategic Shifts & Innovations
Transit-time measurement architectures are fragmenting into application-specific variants, with sensor miniaturization and wireless telemetry convergence redefining deployment economics across water, energy, and industrial verticals.
MEMS-based ultrasonic transducer arrays are miniaturizing into battery-powered clamp-on configurations for temporary flow auditing. Water utilities in Germany and the Netherlands deploy these pocket-sized units for seasonal demand profiling without permanent installation. The form factor compression is displacing rental-based service models with utility-owned intermittent monitoring fleets.
EPA enforcement timelines under the Clean Water Act are compressing municipal procurement cycles from multi-year capital planning to emergency replacement schedules. Utilities respond by pre-qualifying vendor pools and standardizing on dual-beam designs to reduce technical evaluation overhead. The regulatory acceleration most affects mid-sized cities with legacy cast-iron distribution infrastructure.
After-sales service unbundling is fragmenting long-term maintenance contracts into component-level subscriptions. Industrial buyers in petrochemical corridors now procure transducer replacement programs separately from firmware updates and calibration services. The unbundling is most advanced in North American markets where third-party metrology laboratories compete with original manufacturers for recertification business.
Ultrasonic Flow Meter Market Segmentation
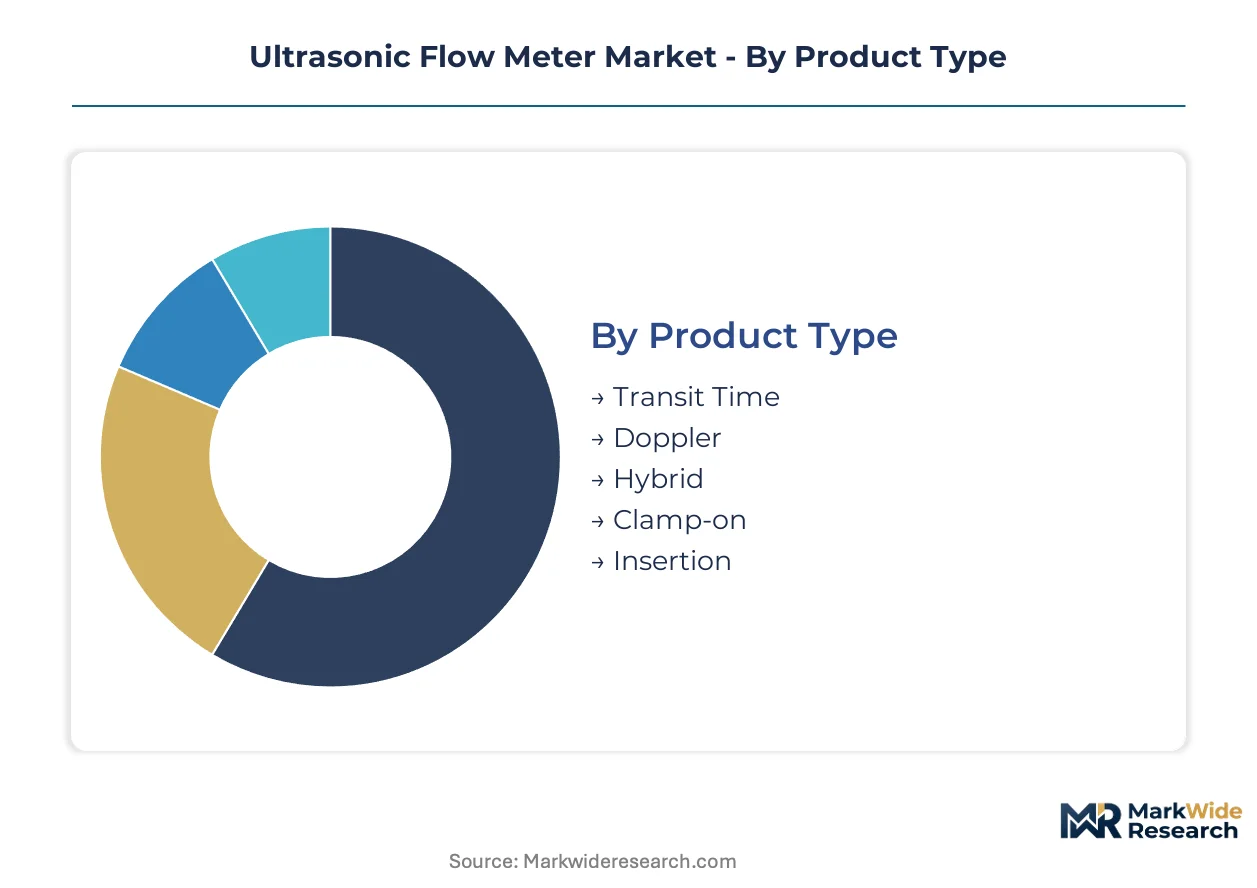
Ultrasonic flow meter procurement channels diverge sharply by segment. Transit-time designs flow through engineering-procurement-construction contractors for greenfield petrochemical projects, while clamp-on configurations reach municipal utilities via direct manufacturer sales and specialized waterworks distributors.
Product Type:
Channel economics vary dramatically across mounting configurations and measurement principles. Permanent installation designs concentrate in project-based channels, while portable retrofit units bypass traditional distribution.
- Transit Time:Measures fluid velocity by calculating differential transit times of acoustic pulses traveling upstream versus downstream. Custody-transfer contracts in German petrochemical corridors and US Gulf Coast refineries concentrate demand, driven by OIML R137 certification requirements for fiscal metering.
- Clamp-on:Externally mounted transducers eliminate pipe cutting and process shutdown. Municipal water utilities in the Netherlands and mid-sized US cities are expanding fleet purchases for seasonal demand auditing, bypassing capital budget cycles through operating expenditure models.
- Doppler:Detects frequency shifts from suspended particles or bubbles in fluid streams.
- Hybrid:Combines transit-time and Doppler principles for variable flow conditions.
- Insertion:Penetrates pipe walls for direct fluid contact in large-diameter applications.
Transit-time designs dominate installed base in custody-transfer applications. Clamp-on configurations are where expansion concentrates fastest.
Technology:
Cost tiers separate single-beam utility specifications from multi-path precision systems. Dual-beam and four-path designs command premium pricing for multiphase measurement, while simpler pulse architectures serve volume markets.
- Dual Beam:Employs two acoustic paths crossing the pipe at opposing angles to cancel flow profile asymmetries. Oil and gas custody-transfer installations in Alberta's oil sands and Norway's North Sea platforms specify these for high gas-void-fraction tolerance.
- Triangulation:Uses three or more beam paths to reconstruct velocity profiles across pipe cross-sections.
- Phase Shift:Detects minute phase differences in received signals for high-resolution measurement.
- Ultrasonic Pulse:Transmits discrete acoustic bursts with gated reception windows.
- Continuous Wave:Maintains steady acoustic transmission for stable averaging in clean fluids.
Dual-beam architectures anchor high-margin custody-transfer revenue. Triangulation methods are gaining share in power generation feedwater monitoring.
Application:
Volume concentration varies by vertical regulatory intensity. Water infrastructure replacement cycles and emissions monitoring mandates create divergent procurement rhythms across end-markets.
- Water & Wastewater:EPA Lead and Copper Rule compliance deadlines are compressing replacement schedules for legacy mechanical meters in US municipal systems. German utilities along the Rhine corridor deploy clamp-on units for non-revenue water reduction programs.
- Oil & Gas Measurement:Fiscal metering for pipeline custody transfer demands SIL-rated designs under IEC 61508. North American shale producers and Middle Eastern national oil companies specify four-path ultrasonic systems for multiphase wellhead measurement.
- Chemical Processing:Corrosive fluid handling drives specification for exotic transducer housings.
- Food & Beverage:Hygienic clamp connections and CIP compatibility dominate sanitary applications.
- Power Generation:Feedwater and cooling water monitoring in combined-cycle plants.
Water and wastewater holds the largest installed base. Oil and gas measurement delivers the steepest margin expansion.
End User:
Customer maturity shapes specification complexity. Municipal utilities prioritize lifecycle cost and interoperability with legacy SCADA, while industrial buyers emphasize predictive maintenance integration.
- Municipal Utilities:Aging distribution infrastructure and federal compliance mandates dominate procurement criteria. US mid-sized cities with cast-iron pipe networks are pre-qualifying vendor pools to accelerate emergency replacement timelines under Clean Water Act enforcement.
- Petrochemical Plants:Integrated process control ecosystems drive bundling decisions. German BASF and Bayer complexes along the Ludwigshafen corridor specify meters compatible with SIMATIC and DeltaV distributed control systems.
- Food Processing Units:Sanitary design certifications and washdown ratings determine vendor selection.
- Power Stations:ASME PTC compliance and turbine protection systems guide specification.
- HVAC Companies:EU F-Gas Regulation leak detection mandates are creating specification requirements for compact refrigerant monitoring meters in building automation retrofits across France and Italy.
Municipal utilities represent the deepest replacement cycle backlog. Petrochemical plants are where digital twin integration and predictive maintenance contracts are concentrating.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Federal compliance mandates and industrial cluster density determine regional demand trajectories. The United States leads municipal replacement cycles under EPA enforcement timelines. Germany anchors precision manufacturing supply chains for custody-transfer applications.
United States
EPA Lead and Copper Rule revisions compel municipal utilities to replace legacy mechanical meters with non-intrusive ultrasonic alternatives. Clean Water Act enforcement timelines compress procurement from multi-year capital planning to emergency replacement schedules. Mid-sized cities with cast-iron distribution infrastructure in the Midwest and Northeast pre-qualify vendor pools to accelerate deployment.
Germany
KROHNE and Endress+Hauser anchor a dense industrial automation cluster along the Rhine corridor with deep calibration laboratory investments. EU F-Gas Regulation refrigerant monitoring mandates create specification requirements for compact meters in building automation. BASF and Bayer complexes in Ludwigshafen specify meters compatible with SIMATIC process control ecosystems.
Netherlands
Water utilities deploy clamp-on units for non-revenue water reduction programs and seasonal demand auditing. The country's advanced water management infrastructure supports operating expenditure procurement models for temporary monitoring fleets. Rotterdam's port logistics and pipeline networks drive custody-transfer meter specifications.
China
Municipal water infrastructure expansion and industrial process automation investments concentrate demand in coastal manufacturing provinces. NMPA and GB standards shape certification requirements for domestic and export-bound production. Yangtze River Delta petrochemical complexes specify multiphase-capable designs for refinery applications.
United Arab Emirates
Desalination plant expansion and district cooling network investments drive high-precision flow measurement demand. MOHAP and federal water authority procurement standards emphasize SIL-rated designs for critical infrastructure. Dubai and Abu Dhabi utility privatization programs attract international meter suppliers through long-term service contracts.
Ultrasonic Flow Meter Market Key Industry Players
Listed leaders compete with private specialists across certification depth and calibration infrastructure. The vendor base clusters around three tiers: diversified industrial conglomerates with process control ecosystems, dedicated flow measurement specialists with metrology laboratory networks, and regional fabricators serving utility retrofit markets. Consolidation pressure concentrates at the mid-tier where scale advantages in OIML R137 certification create exit barriers. Dominant competitive moves include strategic partnerships for digital twin integration and geographic expansion through calibration laboratory franchising.
Within the diversified industrial tier, Siemens AG and Emerson Electric Co. exemplify platform bundling strategies that embed flow data into broader automation ecosystems. KROHNE Group represents the specialist archetype with captive calibration infrastructure and Rhine corridor engineering density. Endress+Hauser Group Services AG occupies a position between these models, combining family-owned governance with global metrology laboratory investments.
| Leading Market Players |
|---|
| Siemens AG |
| Emerson Electric Co. |
| Endress+Hauser Group Services AG |
| KROHNE Group |
| Badger Meter, Inc. |
| Danfoss |
| Fuji Electric Co., Ltd. |
| Baker Hughes Company |
| Honeywell International Inc. |
| Others |
Cost & Logistics Intelligence
Ninety-day lead times for OIML R137-certified ceramic transducers concentrate pricing power with Japanese and German material suppliers, compressing margins for meter assemblers while amplifying premiums for calibration-laboratory owners. This inventory-to-certification nexus forces buyers into long-term offtake contracts or spot-market vulnerability.
Pricing Analysis
Certification level creates the primary spread between custody-transfer and utility-grade offerings. Three-tier pricing structure across SIL-rated, OIML-certified, and uncertified product levels segments buyers by application criticality. Cost compression in standard utility specifications intensifies as municipal procurement shifts to operating-expenditure models. Municipal utilities exhibit highest price sensitivity; oil and gas custody-transfer buyers prioritize metrological certainty over unit cost.
Supply Chain Analysis
Strategic stockpiling of piezoelectric crystals dominates procurement strategy over just-in-time preferences due to single-source concentration risks. Manufacturing draws from Japan, Germany, and China for ceramic substrates, precision machining, and final assembly respectively. Single-source vulnerability in high-purity lead zirconate titanate supply creates tariff-exposure risk for non-captive producers. Distribution runs through engineering-procurement-construction contractors for project-based channels and direct manufacturer sales for retrofit applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Calibration laboratory accreditation and SIL-rated design capabilities represent the scarcest assets in this market, concentrating competitive advantage with incumbent specialists who have already absorbed multi-year certification timelines.
For Market Incumbents: Secure captive calibration infrastructure in Rhine corridor proximity to defend against emerging Asian competitors with cost-advantaged manufacturing but unproven metrology networks. Deepen backward integration into ceramic transducer supply to offset Japanese supplier pricing leverage. For New Entrants and Emerging Players: Lead with clamp-on retrofit configurations for US municipal utilities facing EPA compliance deadlines, where specification complexity is lower and procurement urgency is higher than custody-transfer segments. Partner with third-party metrology laboratories to bypass OIML R137 certification friction. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with underutilized flow-meter divisions lacking digital twin integration capabilities. Long-term viability hinges on software-recurring revenue attachment rates. Watch hydrogen blending mandates in European natural gas networks as inflection indicator for transit-time recalibration service demand.| Strategic Initiative | Industry Significance |
|---|---|
| Calibration Laboratory Expansion | OIML R137 accreditation blocks uncertified competitors from premium custody-transfer contracts. |
| Digital Twin Integration | SIMATIC and DeltaV ecosystem compatibility commands bundling premiums in German petrochemical corridors. |
| Clamp-on Product Miniaturization | MEMS-based battery-powered units displace rental service models in Dutch seasonal auditing programs. |
| Hydrogen Flow Recalibration Services | Variable hydrogen concentration mandates create retrofit demand for compressibility-adjusted transit-time designs. |
| After-sales Service Unbundling | Component-level subscriptions fragment maintenance contracts in North American third-party metrology markets. |
Research Approach
Cross-validation between primary interviews with calibration laboratory directors and secondary analysis of OIML certification databases anchors the qualitative findings. Field discussions with municipal utility procurement officers, petrochemical maintenance directors, and waterworks distributors combined with EPA enforcement timeline records, EU F-Gas Regulation implementation reports, and customs trade data enabled bottom-up and top-down triangulation.
Sensitivity analysis across hydrogen blending penetration rates and municipal replacement cycle acceleration scenarios tested forecast robustness. The modeling framework segments by mounting configuration, measurement principle, path architecture, end-use vertical, and regional regulatory cluster throughout the projection horizon. CAGRs derive from installed base turnover rates and new specification inflows, with inputs including ceramic transducer pricing indices and SCADA interoperability migration timelines.
The analysis sits within stated boundaries; outcomes outside sustained EPA enforcement intensity or stable piezoelectric supply conditions would require recalibration. Forecasts reflect documented assumptions regarding certification timeline continuity and municipal capital availability. Revision becomes warranted when hydrogen concentration thresholds in natural gas pipelines exceed current transit-time recalibration bandwidth.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Smart Home Technologies Market
Others
Bulgur Market
Others
Global Webinar and Webcast Market
Others
Pickup Truck Market
Others
Europe Virtual Reality Gaming Market
Others
Medical Simulation Market
Others
China Cloud Gaming Technology Market
Others
Durian Market
Others
Wingboards Market
Others
Tobacco Packaging Market
Others
Cat Food Market
Others
Air Separation Module Kit Market
Others
Japan 3D Printing Construction Market
Others
Global Aircraft Sensors Market
Others
Solar Animal Repellent Market
Others
Ceramic Machinery Market