
 Tobacco Packaging Market | 2026-2036
Tobacco Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Tobacco Packaging Market Intelligence
The push for sustainable materials alongside stringent anti-smoking regulations is repositioning the market, creating a sharp divide between high-value, compliant packaging and basic, commodity-grade cartons. Amcor leverages its expertise in flexible films and laminates to serve the premium and next-generation product segments. Mondi Group specializes in paperboard and sustainable solutions, aligning with corporate ESG goals. WestRock dominates the high-volume hard pack and carton box sector through its extensive manufacturing scale.
Tobacco packaging encompasses specialized primary and secondary containers designed to protect tobacco products from moisture, contamination, and physical damage while preserving aroma and freshness. These solutions often incorporate multi-layer structures, such as foil-laminated paperboard or metalized PET films, to create effective barrier properties. Paperboard continues to lead in hard pack and carton box formats due to its structural integrity and printability. Meanwhile, flexible materials like plastic films and laminates are gaining share in sachets for smokeless tobacco and pouches for roll-your-own products.
The regulatory environment is defined by bodies like the US Food and Drug Administration (FDA) and frameworks such as the EU's Tobacco Products Directive (TPD). These regulations mandate large graphic health warnings, plain packaging, and track-and-trace features, directly influencing material choice and printing technology. Navigating the dual pressures of increasing regulation and the demand for sustainable, premium materials for new product categories will define future competitive success.
Market Dynamics
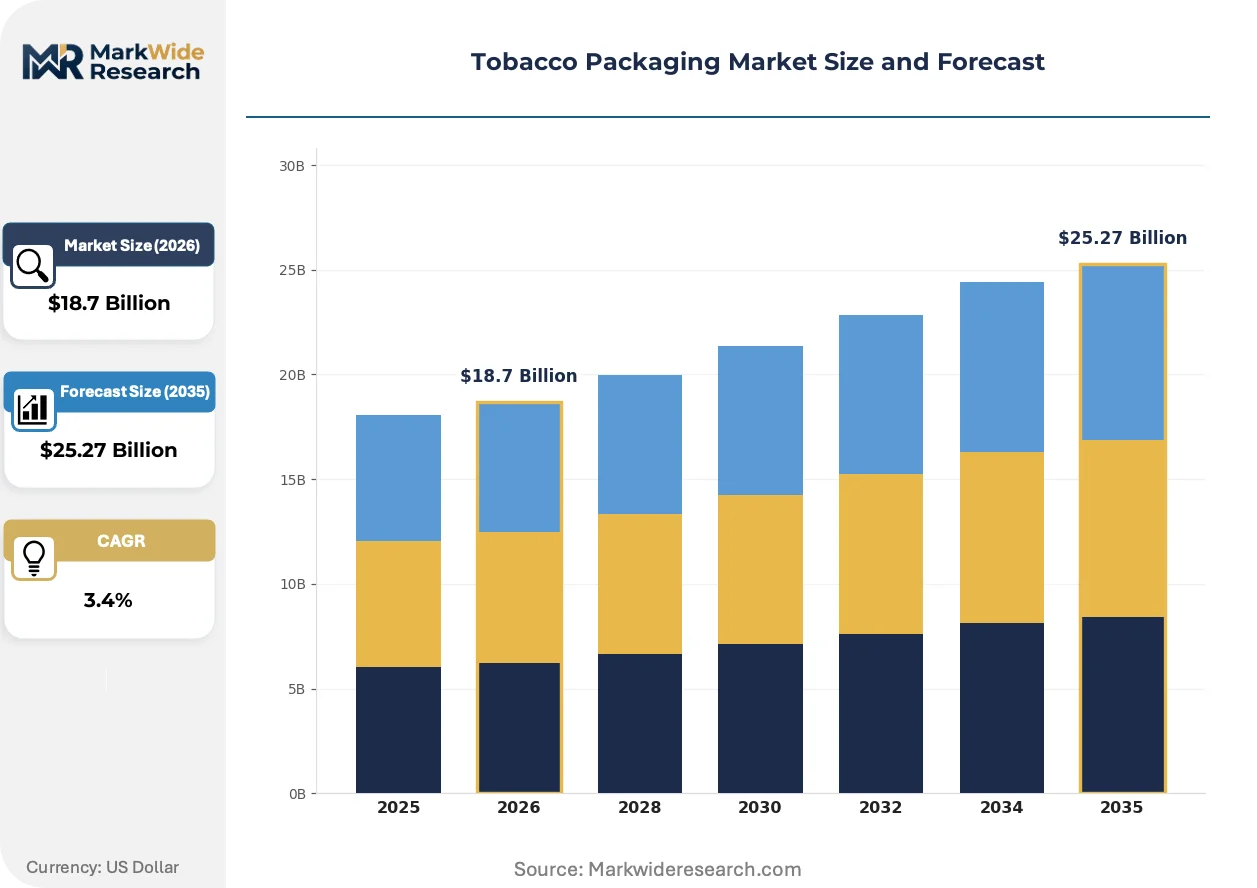
The tobacco packaging market is defined by a fundamental split between highly regulated, standardized packaging for traditional cigarettes and innovative, value-added formats for next-generation products. This divergence is driven by stringent plain packaging mandates and the commercial push for novel tobacco consumption methods.
Growth Catalysts
- Next-Generation Products:The expansion of heated tobacco and modern oral nicotine products necessitates new packaging solutions, such as specialized cartons and flexible pouches, that offer enhanced barrier protection and unique form factors.
- Regulatory Mandates for Security:Implementation of track-and-trace regulations, like those under the EU's Tobacco Products Directive, creates non-discretionary demand for packaging with unique identifiers and anti-tampering features, boosting the value of compliant packaging.
- Smokeless Tobacco Formats:Rising consumption of smokeless tobacco, particularly in North America and Scandinavia, fuels demand for flexible pouches and sachets that prioritize moisture control and portioning convenience.
Market Restraints
- Plain Packaging Legislation:Government mandates for plain packaging, enforced in countries like Australia, France, and the UK, severely restrict branding, color, and material choices, commoditizing primary packs and reducing differentiation potential.
- Input Material Price Volatility:Fluctuations in the cost of key raw materials, including specialty paperboard, aluminum foil, and plastic films, create margin pressure for converters, especially in the high-volume carton segment.
- Declining Combustible Volumes:The persistent decline in cigarette consumption rates in many developed regions acts as a structural headwind, capping volume growth for traditional hard pack and soft pack formats.
Strategic Opportunities
- Sustainable Material Innovation:There is a significant opportunity in developing and commercializing recyclable, mono-material flexible films and biodegradable paperboards to meet corporate ESG targets and preempt future environmental regulations.
- Packaging for Heated Tobacco Systems:Concentrated demand in markets like Japan and South Korea for sophisticated packaging for heated tobacco sticks and devices presents a high-value opportunity for suppliers with advanced converting capabilities.
- Child-Resistant Features:Integrating certified child-resistant closures and mechanisms into packaging for oral nicotine pouches and e-liquids opens a new market for specialized, compliant solutions that address safety concerns.
Industry Challenges
- Global Compliance Complexity:Managing disparate regulatory requirements for health warnings, tax stamps, and serialization codes across multiple jurisdictions creates significant operational and logistical burdens for packaging suppliers.
- Capital Investment for New Formats:Shifting production to accommodate novel packaging for next-generation products requires substantial capital expenditure in new converting machinery, printing technologies, and assembly lines.
- Supply Chain Transparency:Achieving full transparency in sourcing certified sustainable materials, such as FSC-certified paper, while maintaining cost-competitiveness and supply chain resilience remains a significant operational hurdle.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tobacco Packaging Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $25.27 Billion |
| CAGR (2026 – 2036) | 3.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Paperboard, Plastic Film, Foil, Cellophane, Laminates, Metalized PET Packaging Format: Soft Pack, Hard Pack, Carton Box, Sachets, Gift Boxes, Display Trays End Use Industry: Manufacturers, Distributors, Retailers, Hospitality Sector, Specialty Stores, Vending Machines Printing Technology: Flexography, Gravure, Digital Printing, Offset Printing, Screen Printing, Letterpress |
| Companies Covered | Mondi Group, Stora Enso, Amcor, Graphic Packaging International, Sonoco, WestRock, International Paper, Delfort, Smurfit WestRock, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tobacco Packaging Market Strategic Shifts & Innovations
Material science advancements and digital technologies are being deployed to solve the dual challenges of regulatory compliance and product integrity. The market's evolution is increasingly tied to a supplier's ability to integrate sustainability features with sophisticated anti-counterfeiting and tracking technologies demanded by regulators.
Digital printing technology provides on-demand, variable data capabilities for cartons and flexible packaging. Converters and tobacco manufacturers are adopting this technology to manage the short production runs associated with frequent regulatory changes and for product personalization. This technology is unifying the previously separate needs for mass-market compliance and niche product differentiation onto a single, flexible production platform.
Regulations such as the US Food and Drug Administration (FDA) authority over tobacco products and the EU's Tobacco Products Directive (TPD) are primary forces shaping package design. These frameworks compel the use of large graphic health warnings and robust track-and-trace systems. The paperboard hard pack segment is most directly impacted, with designs being re-engineered to maximize space for warnings while preserving structural integrity.
A notable behavioral shift is occurring in how tobacco companies source packaging for new product categories. The traditional, transactional procurement of standard cartons is being displaced by collaborative partnerships with packaging suppliers for developing formats for heated tobacco and oral nicotine pouches. This trend is most pronounced in European and East Asian markets where the pace of new product innovation is fastest.
Tobacco Packaging Market Segmentation
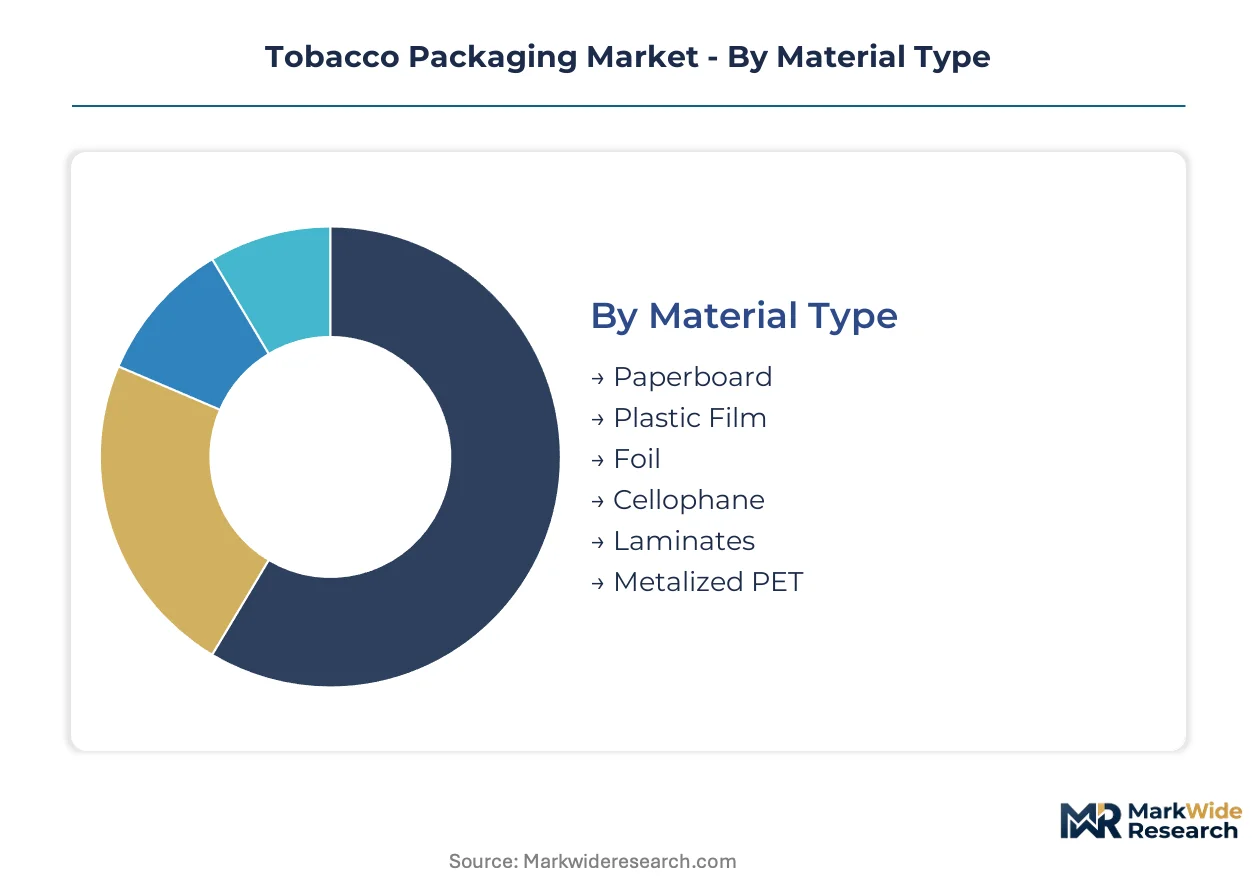
Understanding the tobacco packaging market's segmentation is essential for navigating its dual pressures of regulatory compliance and product innovation. The market's diverse needs, from high-volume standardized cartons to specialized next-generation product formats, drive distinct material and technology choices.
Material Type:
The choice of material reflects a spectrum from highly standardized, cost-efficient options to specialized, multi-functional solutions for enhanced product protection and regulatory adherence.
- Paperboard:This material forms the structural backbone for traditional cigarette hard packs and carton boxes. Its rigidity, printability, and cost-effectiveness make it a primary choice for high-volume applications, particularly in established combustible tobacco markets.
- Laminates:Multi-layer structures combining materials like paper, plastic, and foil offer superior barrier properties against moisture and oxygen. Demand for laminates is concentrating in sophisticated packaging for heated tobacco products and oral nicotine pouches, especially in developed markets like Japan and South Korea.
- Plastic Film:Flexible plastic films, including BOPP and PE, provide moisture barrier properties and are used for overwraps and inner liners. These films are critical for maintaining product freshness in soft packs and pouches.
- Foil:Aluminum foil provides an excellent barrier against light, moisture, and aroma degradation. It is frequently integrated into multi-layer structures for premium tobacco products.
- Cellophane:Transparent cellulose-based films offer good barrier properties and are often used as an outer wrap for traditional cigarette packs. Its use is declining due to cost and performance alternatives.
- Metalized PET:This material combines the barrier properties of metal with the flexibility of plastic. Metalized PET films enhance visual appeal and extend shelf life for various tobacco products.
Most installed capacity flows through Paperboard. Expansion is steepest in Laminates.
Packaging Format:
Packaging formats are differentiated by their application versatility, ranging from traditional high-volume cigarette packs to innovative solutions for modern oral nicotine products.
- Hard Pack:This rigid paperboard format dominates the combustible cigarette market globally, offering structural integrity and brand visibility. Regulatory mandates for graphic health warnings significantly influence its design and printing area.
- Sachets:Flexible pouches designed for smokeless tobacco and oral nicotine products prioritize moisture control and portioning convenience. Rising consumption of modern oral nicotine products in North America and Scandinavia fuels specific demand for these flexible formats.
- Soft Pack:A traditional, less rigid paperboard format for cigarettes, soft packs are often associated with certain regional preferences. Their compact nature provides a distinct tactile experience for consumers.
- Carton Box:These larger paperboard containers group multiple individual cigarette packs for distribution and retail display. Carton boxes require robust construction to protect contents during transit.
- Gift Boxes:Premium packaging for specialized or limited-edition tobacco products, gift boxes emphasize aesthetics and material quality. They cater to niche consumer segments seeking high-end presentation.
- Display Trays:Designed for point-of-sale presentation, display trays organize and showcase tobacco products in retail environments. They often integrate branding and promotional elements.
Volume is dominated by Hard Pack. Innovation is concentrated in Sachets.
End Use Industry:
The market's end-use segmentation reflects the various points along the supply chain where packaging is procured and utilized, from direct manufacturing to consumer-facing retail.
- Manufacturers:Tobacco manufacturers represent the largest direct purchasers of packaging materials and finished formats. They require high-volume, cost-efficient solutions that adhere to stringent regulatory specifications.
- Retailers:Retailers demand packaging that facilitates efficient display, inventory management, and point-of-sale security. Packaging for this segment often incorporates anti-theft features and clear product information.
- Distributors:Packaging for distributors focuses on logistical efficiency and protection during bulk transport. Solutions include robust carton boxes and overpacks for safe delivery to retail outlets.
- Hospitality Sector:This segment includes hotels, bars, and restaurants that may offer tobacco products. Packaging here often needs to be compact and sometimes branded for specific venues.
- Specialty Stores:Shops specializing in tobacco or vaping products require diverse packaging options, including premium and customized solutions. These stores often cater to discerning consumers.
- Vending Machines:Packaging for vending machines must meet precise dimensional specifications for automated dispensing. Durability and consistent sizing are crucial for this channel.
Direct procurement drives demand from Manufacturers. Point-of-sale presentation is critical for Retailers.
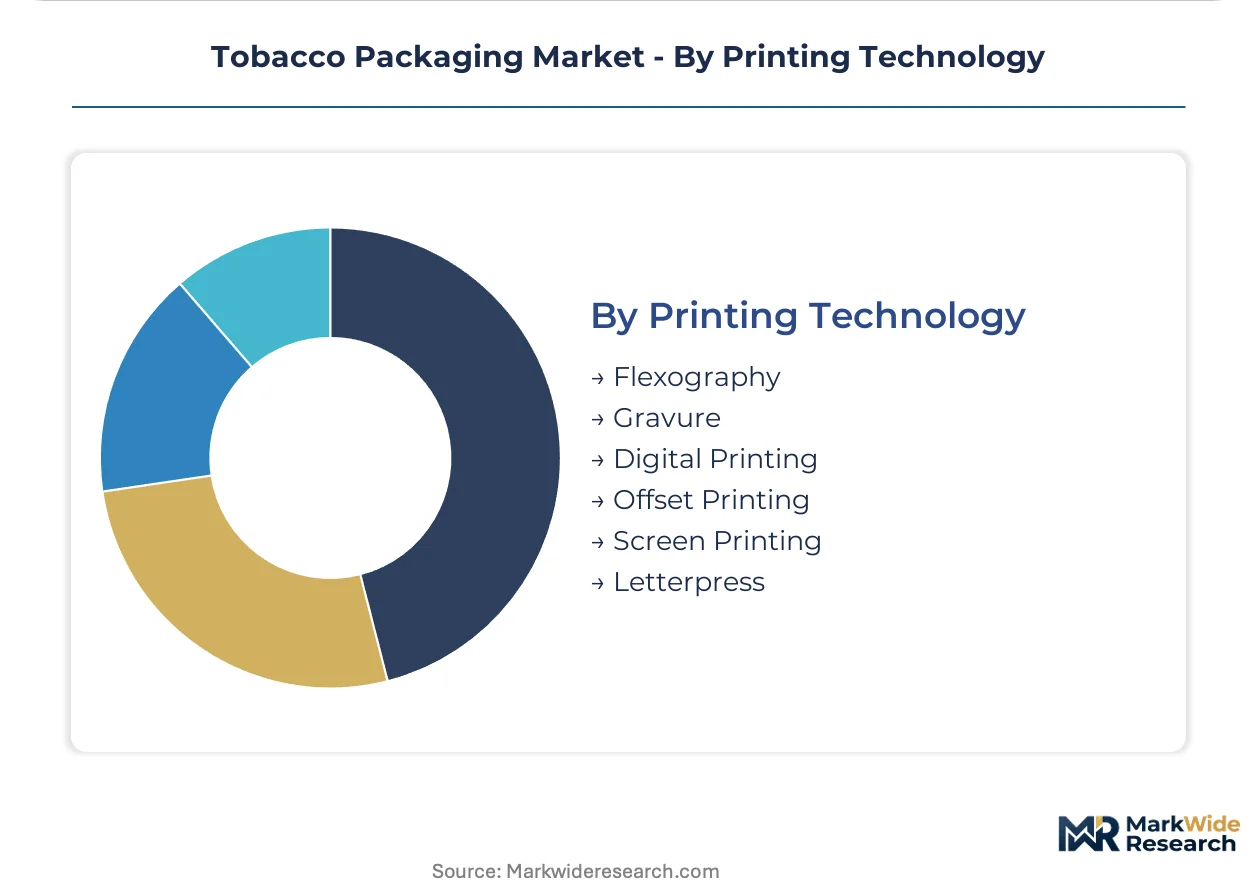
Printing Technology:
Printing technologies are differentiated by their capability for customization, cost-efficiency, and ability to meet complex regulatory requirements for variable data and graphic reproduction.
- Flexography:This high-speed, cost-effective printing method is widely used for large-volume runs on flexible materials and paperboard. Flexography is a workhorse for standardized packaging, offering consistent quality for basic branding and warnings.
- Digital Printing:Offering on-demand, variable data printing, digital technology enables short production runs and customization. Its flexibility supports frequent regulatory changes and product personalization, particularly for next-generation products or limited editions.
- Gravure:Known for its high-quality image reproduction and durability, gravure printing is suitable for long runs and complex graphics. It is often employed for premium packaging where visual impact is critical.
- Offset Printing:This versatile printing method provides excellent image quality on various substrates, including paperboard. Offset printing is commonly used for carton boxes and other structured packaging components.
- Screen Printing:Screen printing allows for thick ink deposits and vibrant colors, often used for specialty effects or on non-traditional substrates. Its application in tobacco packaging is typically for niche or premium products.
- Letterpress:An older printing technique, letterpress offers a distinct tactile quality and is sometimes used for high-end, artisanal packaging. Its use in mass-market tobacco packaging is limited.
High-volume production relies on Flexography. Agility for regulatory changes depends on Digital Printing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Highly skilled packaging engineers and material scientists anchor the significant regional variations in the tobacco packaging market. These specialized workforces drive innovation for next-generation products while navigating complex regulatory landscapes. Different regions exhibit distinct demand patterns for traditional versus modern tobacco formats.
United States
Demand for child-resistant features on oral nicotine pouches and specialized packaging for e-liquids drives innovation. The US Food and Drug Administration (FDA) mandates stringent packaging requirements for all tobacco products. Packaging hubs in the Southeast, particularly around North Carolina, focus on developing compliant and secure solutions for manufacturers.
Germany
The shift towards heated tobacco products and premium traditional cigarettes fuels demand for sophisticated laminates and high-quality paperboard. The EU's Tobacco Products Directive (TPD) enforces strict plain packaging and graphic health warning rules. Production facilities near Hamburg and Frankfurt specialize in advanced printing and converting technologies for European markets.
Japan
Significant demand for high-value packaging for heated tobacco sticks and devices drives material science advancements. METI regulations influence material standards and recycling initiatives for consumer goods packaging. Tokyo-based packaging design firms collaborate closely with tobacco companies on aesthetic and functional innovations.
China
A vast consumer base for traditional cigarettes and growing interest in novel tobacco products create diverse packaging needs. SAMR oversees product quality and labeling standards for domestic and imported tobacco packaging. Manufacturing clusters in the Yangtze River Delta produce high volumes of paperboard cartons and flexible films for the region.
India
Rising consumption of smokeless tobacco and traditional bidis generates demand for cost-effective pouches and basic paperboard solutions. BIS standards dictate material specifications and labeling requirements for tobacco product packaging. Packaging material suppliers in Maharashtra and Gujarat focus on high-volume production for the mass market.
Tobacco Packaging Market Key Industry Players
Top-tier vendors anchor the premium and specialized packaging segments, while a fragmented base of regional players competes in commodity-grade cartons. The market exhibits a tiered structure, with global leaders focusing on innovation for next-generation products. Strategic archetypes include large-scale integrated producers, specialized material converters, and regional niche providers. Portfolio diversification into sustainable materials and strategic partnerships for technology development are dominant competitive moves.
At the scale-driven end, WestRock, a US-based corporation, dominates the high-volume hard pack and carton box sector through its extensive manufacturing capabilities. Mondi Group, an international packaging and paper company, exemplifies a focus on paperboard and sustainable solutions, aligning with corporate ESG goals. Amcor, a global packaging leader, represents expertise in flexible films and laminates, serving the premium and next-generation product segments with advanced barrier properties. These companies leverage their distinct strengths to address the market's varied demands.
| Leading Market Players |
|---|
| Mondi Group |
| Stora Enso |
| Amcor |
| Graphic Packaging International |
| Sonoco |
| WestRock |
| International Paper |
| Delfort |
| Smurfit WestRock |
| Others |
Cost & Logistics Intelligence
Family-owned mid-caps and private-equity-backed converters influence supply behavior and pricing discipline in the tobacco packaging market. Their financial structures often dictate investment in new machinery and material sourcing strategies.
Pricing Analysis
Bundled service offerings, combining material supply with design and converting, command higher prices than unbundled commodity material sales. Pricing for tobacco packaging is primarily per-unit transactional, influenced by customization level and volume scale. Quality grade, particularly for barrier properties and print fidelity, drives significant price differentiation. Pricing softness stems from intense competition in the high-volume paperboard segment. Manufacturers of traditional cigarettes are highly price-sensitive, while next-generation product developers prioritize value and innovation.
Supply Chain Analysis
Dual-sourcing requirements from major tobacco companies ensure supply resilience and competitive tension among packaging suppliers. The supply of specialty paperboard, aluminum foil, and plastic films concentrates in China, Germany, and the US. Raw material dependencies include wood pulp, petrochemicals for films, and bauxite for foil. Commodity price volatility presents a structural supply chain risk for converters. Distribution runs through a mix of direct manufacturer-to-factory delivery and regional logistics hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The tobacco packaging market operates as a stable compounder, driven by non-discretionary regulatory mandates for product integrity and consumer safety. Continuous innovation for next-generation products further underpins this consistent expansion.
For Market Incumbents: Extend flexible film and laminate capabilities to capture the high-value heated tobacco and oral nicotine segments. Invest in advanced digital printing technologies to manage frequent regulatory changes and offer customization, mitigating the threat of commoditization from plain packaging. Deepen vertical integration into sustainable material production, such as mono-material films, to meet evolving ESG targets and preempt future environmental regulations.
For New Entrants and Emerging Players: Begin with specialized offerings for child-resistant features on oral nicotine pouches, a segment with high regulatory barriers to entry. Target markets like the US and Scandinavia where demand for modern oral nicotine products is concentrated and safety compliance is paramount. A go-to-market angle focused on certified safety solutions and rapid prototyping can differentiate early players.
For Investors and Strategic Acquirers: Global packaging conglomerates are the most active acquirers in this space, seeking to consolidate specialized capabilities. The long-term viability of the market over a 5-10 year window remains strong due to non-discretionary regulatory demand and product innovation. Acquisition targets should be specialized material converters with proprietary barrier technologies or advanced digital printing assets. A signal to watch is the increasing M&A activity in sustainable packaging solution providers for tobacco products.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Mono-Material Films | Reduces environmental impact and meets corporate ESG objectives for tobacco manufacturers. |
| Develop Child-Resistant Closures | Addresses safety concerns for oral nicotine products, complying with FDA mandates. |
| Expand Digital Printing Capacity | Enables agile response to frequent regulatory changes and product customization. |
| Form Joint Ventures for Barrier Materials | Accesses specialized expertise for heated tobacco product packaging. |
| Certify Sustainable Sourcing | Ensures supply chain transparency and aligns with consumer and regulatory demands. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary insights with robust secondary validation. Primary research involved discussions with packaging engineers, procurement managers at tobacco companies, material suppliers, and regulatory compliance officers. Secondary data sources included government reports (e.g., FDA, TPD), industry association publications, and company financial filings. This dual approach ensured bottom-up market sizing and top-down validation of segment trends.
Historical data from comparable periods anchored the forecast window, establishing baseline growth rates and market dynamics. The analytical framework modeled segmentation dimensions including material type, packaging format, end-use industry, and printing technology. CAGRs were derived through a combination of regression analysis and expert consensus across the modeling period. Key industry-specific forecast inputs included tobacco consumption trends and regulatory compliance timelines.
Several conditions sit outside the modeled scope, including unforeseen geopolitical events and rapid shifts in global economic conditions. Forecasts reflect assumptions regarding stable regulatory enforcement and consistent raw material supply. Deviation in global anti-smoking sentiment would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Asia-Pacific Legal Services Market
Others
Folding Screen Mobile Phone Market
Others
Palatants Market
Others
Level Measuring Instrument Market
Others
Global Smart Devices Market
Others
Plastic Films and Sheets Market
Others
Fluid Bed Systems Market
Others
Moonstone Market
Others
Global Pumpkin Candles Market
Others
Smart Home Technologies Market
Others
Drum Motor Market
Others
Global Wireless Asset Management Market
Others
Infant Positioning Aids Market
Others
North America Medical Simulation Market
Others
DIY Smart Home Market
Others
APAC Machine Vision Systems Market