
 Medical Simulation Market | 2026-2036
Medical Simulation Market Size, Share, and Industry Trends Forecast 2026-2036
Medical Simulation Market Intelligence
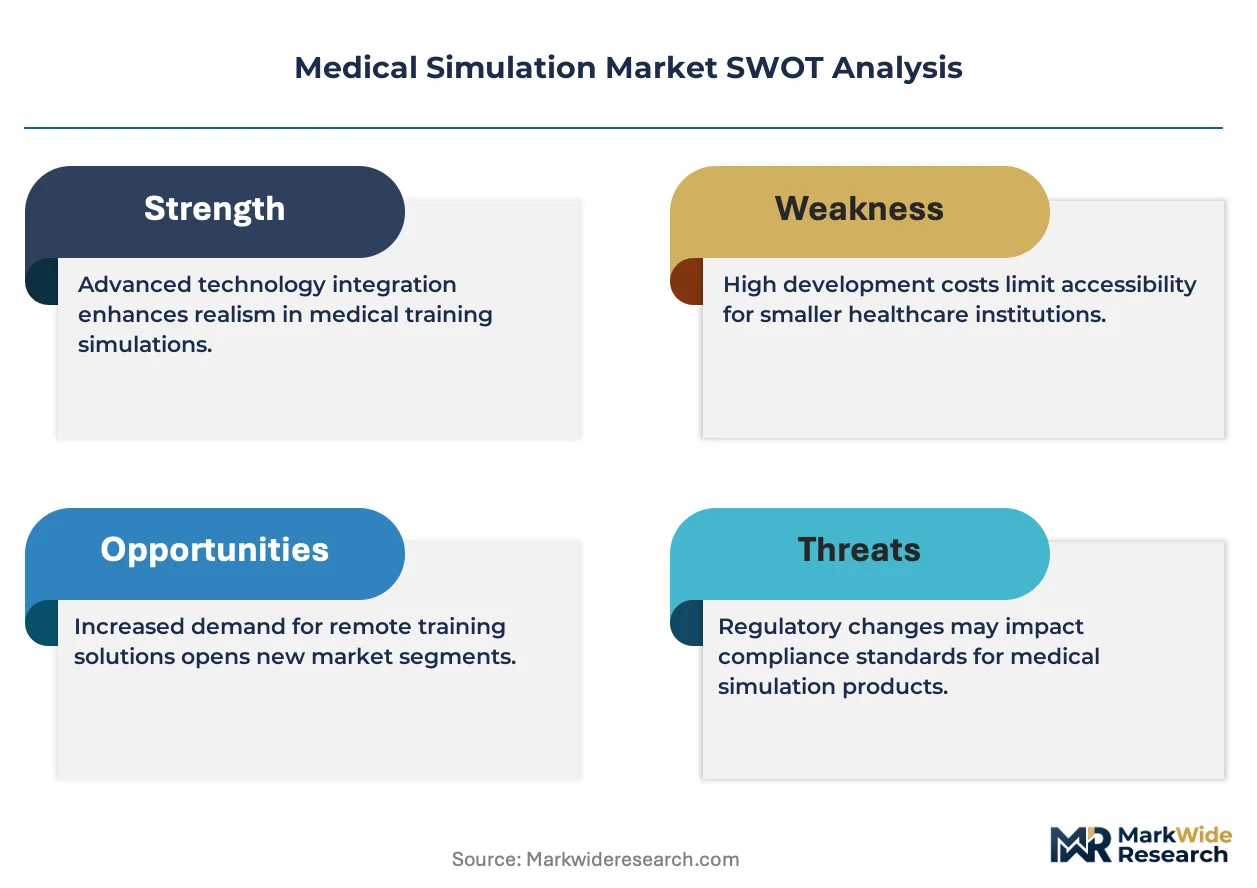
Silicone is recalibrating product economics across patient simulator manufacturing as thermoplastic elastomers displace traditional latex and PVC in task trainer construction. CAE Inc. leverages integrated digital-physical platforms to sustain technology leadership in aviation-derived healthcare simulation. Laerdal Medical anchors its position through R&D intensity focused on resuscitation training ecosystems. Gaumard Scientific differentiates via specialized maternal-fetal and trauma simulator lines that occupy distinct clinical niches.
Medical simulation encompasses the design and deployment of anatomically accurate physical models, computer-generated virtual environments, and hybrid systems that replicate physiological responses for clinical skills acquisition and competency assessment. These platforms integrate haptic feedback mechanisms, programmable physiological algorithms, and biometric tracking to enable repeatable, risk-free training scenarios across surgical, emergency, and diagnostic disciplines. High-fidelity simulators dominate current revenue pools due to their complexity and institutional procurement cycles, while virtual reality simulators represent the fastest-expanding segment as hardware costs decline and software libraries deepen. Surgical training applications command concentrated margin pools because procedure-specific modules carry premium pricing and recurrent content licensing.
FDA software-as-medical-device guidance, ISO 13485 quality management requirements, and HIPAA privacy frameworks collectively shape product validation pathways and institutional purchasing criteria in the United States. The European Medical Device Regulation imposes additional conformity assessment burdens on simulation hardware marketed for clinical credentialing purposes. Stakeholders must monitor evolving regulatory distinctions between educational tools and diagnostic adjuncts, as reclassification would trigger substantially different compliance obligations and market access conditions.
Market Dynamics
Immersive training systems are recalibrating institutional procurement priorities as academic medical centers shift capital allocation from static manikins to programmable, scenario-driven platforms. This hardware transition compresses replacement cycles and elevates software licensing to recurring revenue centrality.
Growth Catalysts
- FDA Software-as-Medical-Device Guidance:The framework validates simulation platforms as clinical decision support tools, expanding reimbursable applications and institutional justification for capital expenditure.
- Thermoplastic Elastomer Displacement:Advanced polymers replace latex and PVC in task trainer construction, reducing allergen liability while improving durability and anatomical fidelity.
- Residency Program Accreditation Mandates:The Accreditation Council for Graduate Medical Education intensifies competency-based assessment requirements, embedding simulation hours into core training curricula.
Market Restraints
- High-Fidelity Hardware Concentration:Surgical simulator manufacturing clusters in select North American and European production hubs, exposing buyers to extended lead times and currency fluctuation exposure.
- Silicone Feedstock Volatility:Medical-grade silicone pricing oscillates with semiconductor and automotive sector demand, compressing margins on patient simulator production.
- Legacy Platform Interoperability:Proprietary physiological engines resist data exchange with hospital information systems, limiting longitudinal competency tracking.
Strategic Opportunities
- India Healthcare Infrastructure Expansion:The country's medical education regulator mandates simulation-based training for new nursing colleges, creating greenfield demand for mid-fidelity platforms.
- AI-Physiology Algorithm Convergence:Machine learning integration with programmable patient responses enables adaptive difficulty scaling and personalized remediation pathways.
- Subscription-Based Content Licensing:Procedure-specific module libraries shift revenue from one-time hardware sales to recurring software access, improving customer lifetime value metrics.
Industry Challenges
- Biomedical Engineer Talent Scarcity:The intersection of clinical knowledge, haptic systems engineering, and software development creates recruitment bottlenecks for simulator manufacturers.
- ISO 13485 Certification Timelines:Quality management system validation for hardware marketed as clinical credentialing tools extends product launch schedules by twelve to eighteen months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medical Simulation Market |
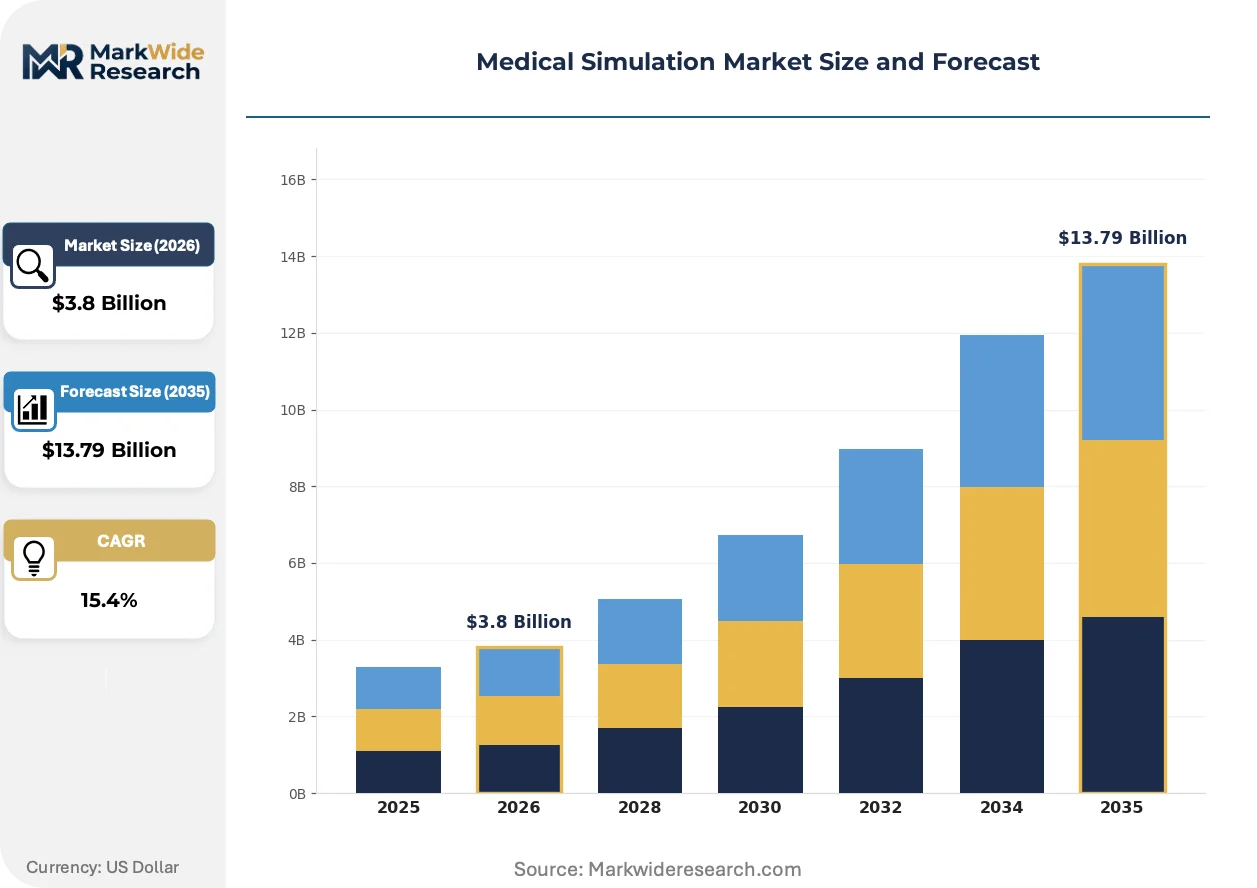
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $13.79 Billion |
| CAGR (2026 – 2036) | 15.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: High-fidelity Simulators, Low-fidelity Simulators, Virtual Reality Simulators, Hybrid Simulators End User: Medical Schools, Hospitals, Nursing Institutions, Emergency Services Delivery Mode: Web-based Training, On-site Training, Blended Learning, Simulation Centers Application: Surgical Training, Clinical Skills Training, Assessment and Evaluation, Team Training |
| Companies Covered | CAE Inc., Laerdal Medical, Gaumard Scientific, 3D Systems, Simulab Corporation, Surgical Science Sweden AB, Limbs & Things Ltd, Simulaids, Kyoto Kagaku Co., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medical Simulation Market Strategic Shifts & Innovations
Digital-physical hybrid architectures are displacing standalone simulation modalities as institutional buyers prioritize platforms that bridge virtual scenario libraries with tangible haptic interfaces.
Virtual reality simulators are expanding into laparoscopic and endoscopic training applications as hardware costs decline and haptic glove fidelity improves. Teaching hospitals in Germany and South Korea accelerate procurement of VR suites for resident skills labs. The technology is compressing physical facility requirements while enabling remote proctoring and asynchronous competency validation.
The European Medical Device Regulation imposes conformity assessment burdens on simulation hardware marketed for clinical credentialing, requiring notified body involvement for products previously self-certified as educational tools. Manufacturers serving European academic medical centers must revalidate quality management systems and technical documentation. High-fidelity surgical simulators face the steepest compliance cost escalation, advantaging larger platforms with dedicated regulatory affairs functions.
Leasing arrangements and managed service contracts displace capital purchase models for high-fidelity installations as hospital CFOs prioritize operational expenditure flexibility. Academic medical centers in the United States and United Kingdom lead this transition, bundling hardware refresh cycles with software updates and technical support. The shift compresses upfront revenue recognition while elongating customer relationships and embedding vendors deeper into institutional training workflows.
Medical Simulation Market Segmentation
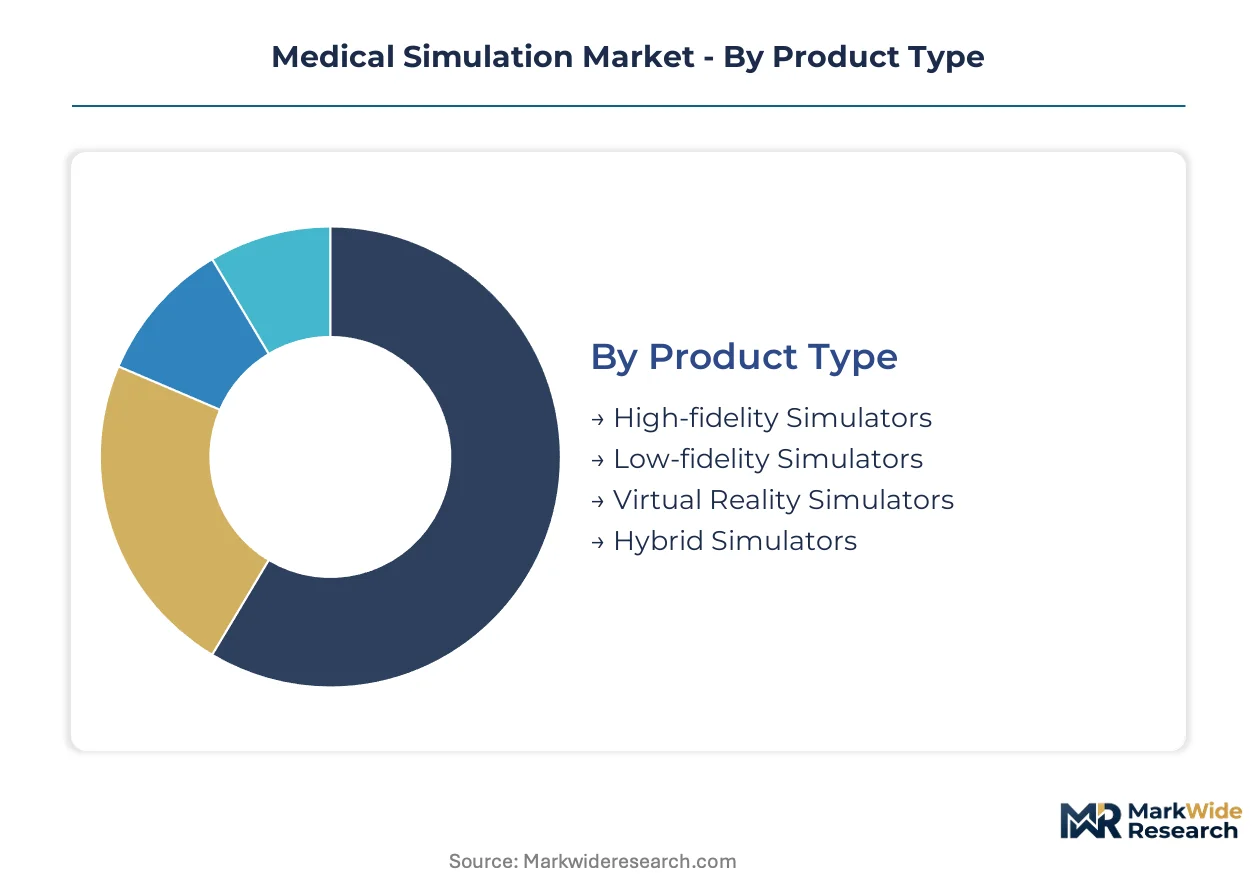
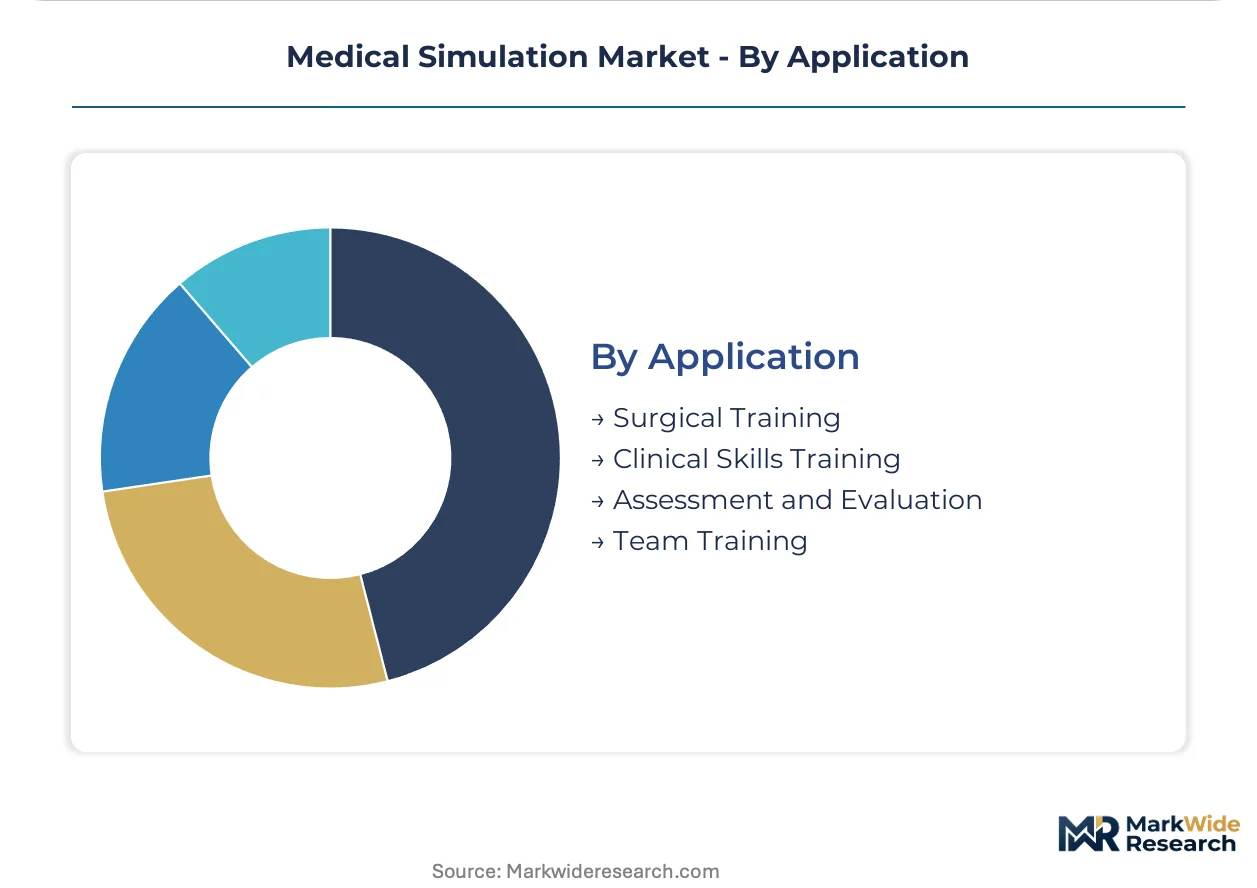
Medical simulation procurement follows distinct budget cycles and competency requirements across institutional buyer types. Product configuration, delivery architecture, and application specificity drive divergent pricing tiers and vendor selection criteria.
Product Type:
Capital allocation intensity separates institutional buyers, with academic medical centers prioritizing programmable physiological fidelity while community hospitals optimize for task-specific durability.
- High-fidelity Simulators:Programmable patient manikins integrate haptic feedback, biometric tracking, and scenario libraries for immersive crisis management training. Procurement concentrates in United States teaching hospitals where ACGME mandates embed simulation hours into residency curricula.
- Virtual Reality Simulators:Head-mounted displays with haptic gloves enable laparoscopic and endoscopic skill acquisition without physical facility requirements. German and South Korean teaching hospitals accelerate procurement as hardware costs decline and software libraries deepen procedural coverage.
- Low-fidelity Simulators:Static task trainers constructed from thermoplastic elastomers support repetitive psychomotor skill development at accessible price points.
- Hybrid Simulators:Digital-physical architectures bridge virtual scenario libraries with tangible haptic interfaces for comprehensive competency validation.
Volume sits with high-fidelity platforms; growth tilts toward virtual reality simulators as remote proctoring capabilities expand reimbursable applications.
End User:
Regulatory accreditation intensity shapes procurement sophistication, with degree-granting institutions facing stricter competency documentation requirements than emergency response organizations.
- Hospitals:Academic medical centers anchor investment in surgical simulators where procedure-specific modules command premium pricing and recurrent content licensing. CFOs increasingly favor operational expenditure models through managed service contracts.
- Medical Schools:Pre-clinical curricula integrate standardized patient encounters and virtual anatomy platforms to bridge classroom instruction with clinical rotations.
- Nursing Institutions:India's medical education regulator mandates simulation-based training for new college approvals, creating greenfield demand for mid-fidelity platforms.
- Emergency Services:Fire departments and ambulance services prioritize portable task trainers for field-ready skill maintenance.
Revenue concentrates in hospital procurement; nursing institutions represent the steepest expansion trajectory amid regulatory mandates in emerging markets.
Delivery Mode:
Facility infrastructure and IT governance capabilities determine feasible deployment architectures across institutional settings.
- Simulation Centers:Dedicated physical facilities with integrated audiovisual capture and debriefing suites support high-stakes competency examinations.
- Blended Learning:Asynchronous virtual modules combined with scheduled physical sessions optimize resource utilization across distributed learner populations.
- On-site Training:Vendor-deployed mobile simulation units deliver turnkey experiences for institutions lacking permanent installation capacity.
- Web-based Training:Browser-accessible platforms enable remote access to virtual patient scenarios with limited haptic fidelity.
Capital commitment clusters in simulation centers; blended learning gains share fastest as hybrid workforce models persist.
Application:
Procedure risk profiles and reimbursement linkages concentrate investment in surgical disciplines where technical errors carry liability and financial consequences.
- Surgical Training:Procedure-specific simulators for laparoscopy, endoscopy, and open techniques carry premium module pricing and recurrent licensing. Margin pools concentrate here due to specialized content development costs and credentialing body endorsement requirements.
- Team Training:Crisis resource management scenarios replicate emergency department and operating room communication dynamics for interprofessional competency validation.
- Clinical Skills Training:Venipuncture, catheterization, and airway management task trainers support foundational psychomotor acquisition.
- Assessment and Evaluation:Standardized simulation-based examinations supply objective competency data for licensure and promotion decisions.
Surgical applications dominate current revenue; team training climbs fastest as healthcare systems prioritize safety culture interventions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Academic medical centers in the United States concentrate procurement of high-fidelity surgical simulators, while German and South Korean teaching hospitals accelerate virtual reality suite adoption for resident training programs.
United States
FDA software-as-medical-device guidance validates simulation platforms as clinical decision support tools, expanding reimbursable applications for institutional buyers. HIPAA privacy frameworks shape data governance requirements for platforms tracking biometric performance metrics. The Greater Boston corridor anchors concentrated demand from Harvard-affiliated teaching hospitals investing in programmable physiological manikins.
Germany
The European Medical Device Regulation imposes conformity assessment burdens on hardware marketed for clinical credentialing, requiring notified body involvement for products previously self-certified. German academic medical centers in Heidelberg and Berlin lead procurement of VR suites for laparoscopic skills laboratories. Baden-Württemberg's medical device manufacturing cluster supplies haptic feedback components to domestic simulator producers.
South Korea
MFDS regulatory alignment with international standards streamlines market access for imported simulation platforms. Seoul National University Hospital anchors demand for endoscopic training systems integrating head-mounted displays with force-feedback instruments. The Pangyo Techno Valley cluster concentrates domestic VR hardware development for healthcare applications.
India
The country's medical education regulator mandates simulation-based training for new nursing college approvals, creating greenfield demand for mid-fidelity platforms. CDSCO quality management requirements shape procurement criteria for imported patient simulators. Maharashtra's Mumbai-Pune corridor concentrates new nursing institution development driving platform deployment.
United Kingdom
NHS England operational expenditure flexibility policies accelerate managed service contract adoption for high-fidelity installations. The Medicines and Healthcare products Regulatory Agency oversees conformity assessment for simulation hardware used in licensure examinations. London's Imperial College Healthcare NHS Trust anchors procurement of hybrid digital-physical training architectures.
Medical Simulation Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with integrated platform developers commanding premium positioning in academic medical center procurement while component suppliers serve mid-fidelity volume tiers. The vendor base organizes around three archetypes: aviation-heritage systems integrators, resuscitation-focused training ecosystem builders, and specialized anatomical model fabricators. Dominant competitive moves include R&D intensity focused on physiological algorithm development and strategic partnerships bridging hardware manufacturing with software content libraries.
Within the systems integrator tier, CAE Inc. and Laerdal Medical occupy positions exemplifying divergent strategic anchors—CAE leveraging aviation-derived digital-physical platforms while Laerdal concentrates resuscitation training ecosystems. Gaumard Scientific represents the specialized anatomical model archetype through maternal-fetal and trauma simulator lines. Among European-based developers, Surgical Science Sweden AB sits within the surgical simulation software segment.
| Leading Market Players |
|---|
| CAE Inc. |
| Laerdal Medical |
| Gaumard Scientific |
| 3D Systems |
| Simulab Corporation |
| Surgical Science Sweden AB |
| Limbs & Things Ltd |
| Simulaids |
| Kyoto Kagaku Co. |
| Others |
Cost & Logistics Intelligence
Thermoplastic elastomer displacement of latex and PVC in task trainer construction simultaneously compresses per-unit material costs and concentrates molding expertise among North American and European polymer processors with medical-grade certification. This materials transition elevates pricing power for qualified suppliers while pressuring legacy manufacturers dependent on volatile silicone feedstock contracts with semiconductor and automotive sector buyers.
Pricing Analysis
Volume concentrates in mid-fidelity task trainers while margin pools accrue to high-fidelity surgical simulators with procedure-specific module licensing. Three-tier pricing structure across premium, standard, and economy levels differentiates by physiological algorithm complexity and ACGME endorsement status. Pricing pressure stems from silicone feedstock volatility linked to automotive and electronics sector demand cycles. Community hospitals exhibit highest price sensitivity, deferring to operational expenditure models, while academic medical centers absorb premium hardware costs through accreditation-mandated procurement.
Supply Chain Analysis
Biomedical engineer scarcity across Massachusetts, Bavaria, and Ontario constrains production scaling for programmable physiological platforms. Manufacturing draws from medical-grade silicone suppliers in Germany, precision haptic component fabricators in Japan, and thermoplastic elastomer processors in the United States. Single-source vulnerability concentrates in semiconductor-dependent haptic feedback controllers. Distribution runs through GPO contracts with academic medical center networks and direct institutional sales for high-fidelity installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized biomedical engineering talent scarcity props pricing for qualified simulation platform developers, constraining rapid capacity expansion despite regulatory-mandated demand acceleration from nursing education regulators.
For Market Incumbents: Hedge against AI-physiology algorithm disruption by acquiring machine learning competencies through targeted hiring in Seoul and Boston talent clusters. Secure backward integration into thermoplastic elastomer molding through captive supply agreements with Baden-Württemberg processors. Defensive patent filing around adaptive difficulty scaling algorithms protects recurring licensing revenue streams from open-source physiology engines. For New Entrants and Emerging Players: Enter via India's greenfield nursing college simulation mandates, where CDSCO quality requirements favor mid-fidelity platform developers over complex high-fidelity incumbents. Target Maharashtra's Mumbai-Pune corridor for initial deployment partnerships with new institutional approvals. SaaS-based virtual scenario libraries bypass capital-intensive hardware manufacturing while capturing recurring revenue through subscription licensing. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by aviation-heritage systems integrators seeking healthcare diversification and private equity roll-ups of specialized anatomical model fabricators. Long-term viability favors platforms with FDA software-as-medical-device validation and embedded institutional training workflows. Monitor MFDS regulatory alignment announcements as inflection signal for Asia-Pacific market access expansion.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Software-as-Medical-Device Submission | Validates platforms as clinical decision support tools, expanding reimbursable applications beyond educational use. |
| Hospital System Partnership | Locks in multi-year managed service contracts with academic medical centers facing ACGME accreditation mandates. |
| AI-Physiology Algorithm Development | Enables adaptive difficulty scaling and personalized remediation pathways that differentiate premium platforms. |
| CE Marking Pathway under MDR | Required for European clinical credentialing hardware, filtering out smaller competitors lacking regulatory affairs capacity. |
| Reimbursement Strategy | Positions simulation hours as billable clinical decision support under evolving payer frameworks. |
Research Approach
Independent corroboration across hospital procurement databases, GPO contract filings, and CMS Medicare simulation reimbursement records underwrites the qualitative findings. Primary interviews with biomedical engineers, hospital purchasing committee members, GPO contracts managers, and nursing education regulators combined with secondary validation from FDA 510(k) filings, CDSCO quality management registrations, and ISO 13485 certification databases. Bottom-up unit economics modeling and top-down market sizing triangulate volume estimates across product tiers.
Comparable-period anchoring to historical procurement cycles in United States teaching hospitals and German academic medical centers established baseline adoption trajectories across the projection horizon. Segmentation modeling incorporated product fidelity tier, delivery architecture, end-user institution type, and regional regulatory cluster dimensions. CAGRs derived from elasticity-adjusted demand curves and replacement cycle compression factors, with surgical training application premiums and thermoplastic elastomer cost curves as key forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under MFDS regulatory alignment delays or silicone feedstock price spikes. Forecasts reflect documented assumptions regarding ACGME mandate enforcement intensity and India nursing college approval velocity. Material deviation in FDA software-as-medical-device reclassification timelines or European Medical Device Regulation conformity cost escalation warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Brown Ht Market
Others
Taiwan Retail Market
Others
Global Duty-Free Retailing Market
Others
Asia-Pacific IVD Regulatory Affairs Outsourcing Market
Others
Vegetable Carbon Market
Others
Green Technologies Market
Others
Smart Card Market
Others
Powder Coating Equipment Market
Others
China Smart Home Market
Others
Fiber to the X (Fttx) Tester Market
Others
Connected TV Market
Others
Enterprise Video Content Management Market
Others
Coriolis Meters Market
Others
North America Ultraviolet Disinfection Equipment Market
Others
Italy Smart Home Market
Others
Tanned Fish Skin Leather Market