
 Pickup Truck Market | 2026-2036
Pickup Truck Market Size, Share, and Industry Trends Forecast 2026-2036
Pickup Truck Market Analysis
The capability gap between capital-intensive full-line manufacturers and asset-light EV entrants is collapsing. Ford Motor Company leverages its integrated powertrain and stamping infrastructure to sustain cost advantages in heavy-duty segments. General Motors anchors its position through in-house battery cell production and modular EV architecture. Toyota Motor Corporation differentiates via hybrid system reliability and resale value retention in commercial channels.
A pickup truck is a light-to-heavy commercial vehicle with an open cargo bed aft of the passenger cabin, typically constructed with body-on-frame architecture and rated for payloads exceeding half-ton capacity; its primary purpose spans construction logistics, agricultural transport, and consumer utility towing. Light-duty gasoline configurations still occupy the largest volume pool, though electric and hybrid fuel types are capturing disproportionate investment as battery costs decline and charging infrastructure densifies. Fleet operators represent the fastest-expanding end user category, driven by electrification mandates and telematics-enabled total cost tracking.
NHTSA crashworthiness standards, EPA Tier 3 emissions rules, and California Air Resources Board zero-emission vehicle mandates collectively reshape powertrain portfolios and certification costs for every manufacturer selling in the United States. The EU's CO2 fleet targets and China's NEV credit system create parallel compliance pressures for any company with export or joint-venture exposure. Stakeholders must monitor battery mineral supply agreements and regional charging buildout schedules before committing capacity to specific powertrain platforms.
Market Dynamics
Electrification mandates from California Air Resources Board and EPA Tier 3 rules are compressing development timelines for powertrain portfolios while battery mineral supply agreements determine which manufacturers can scale electric platforms.
Growth Catalysts
- EPA Tier 3 Emissions Standards:Fleet operators face compliance deadlines that accelerate procurement of hybrid and electric configurations, expanding addressable demand for zero-emission capable platforms.
- Telematics Integration:Real-time total cost of ownership tracking enables fleet managers to quantify electrification savings, shortening payback justification cycles for capital-intensive battery-electric acquisitions.
- Texas Urban Corridors:Construction logistics demand in Dallas-Fort Worth and Houston sustains volume for heavy-duty configurations while supporting charging infrastructure density targets.
Market Restraints
- Lithium Supply Concentration:Chilean and Australian hard-rock spodumene operations control cathode material flows, exposing manufacturers to price volatility and offtake competition from energy storage sectors.
- Body-on-Frame Technical Limits:Legacy architecture constraints complicate battery pack integration without sacrificing payload ratings or ground clearance specifications demanded by commercial users.
- NHTSA Crashworthiness Certification:Modified vehicle testing requirements for electric powertrains extend homologation timelines and raise engineering validation costs for new platform introductions.
Strategic Opportunities
- Canadian Resource Corridors:Mining and forestry operations in Alberta and British Columbia present fleet electrification pilots where duty cycles and depot charging align with battery-economics.
- Vehicle-to-Grid Convergence:Bidirectional charging technology creates revenue streams from grid services, transforming parked fleet assets into distributed energy resources.
- IRA Commercial Clean Vehicle Credits:Federal tax incentives up to forty thousand dollars per qualified electric truck compress total cost of ownership gaps against diesel equivalents.
Industry Challenges
- High-Voltage Technician Shortage:Fleet maintenance operations lack certified personnel for battery system diagnostics and repair, extending downtime and raising service costs.
- Multi-Platform Powertrain Capex:Simultaneous investment in internal combustion, hybrid, and full-electric architectures strains engineering bandwidth and tooling budgets.
- Charging Interoperability Standards:Fragmented connector protocols and payment systems across networks complicate route planning for long-haul electric operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pickup Truck Market |
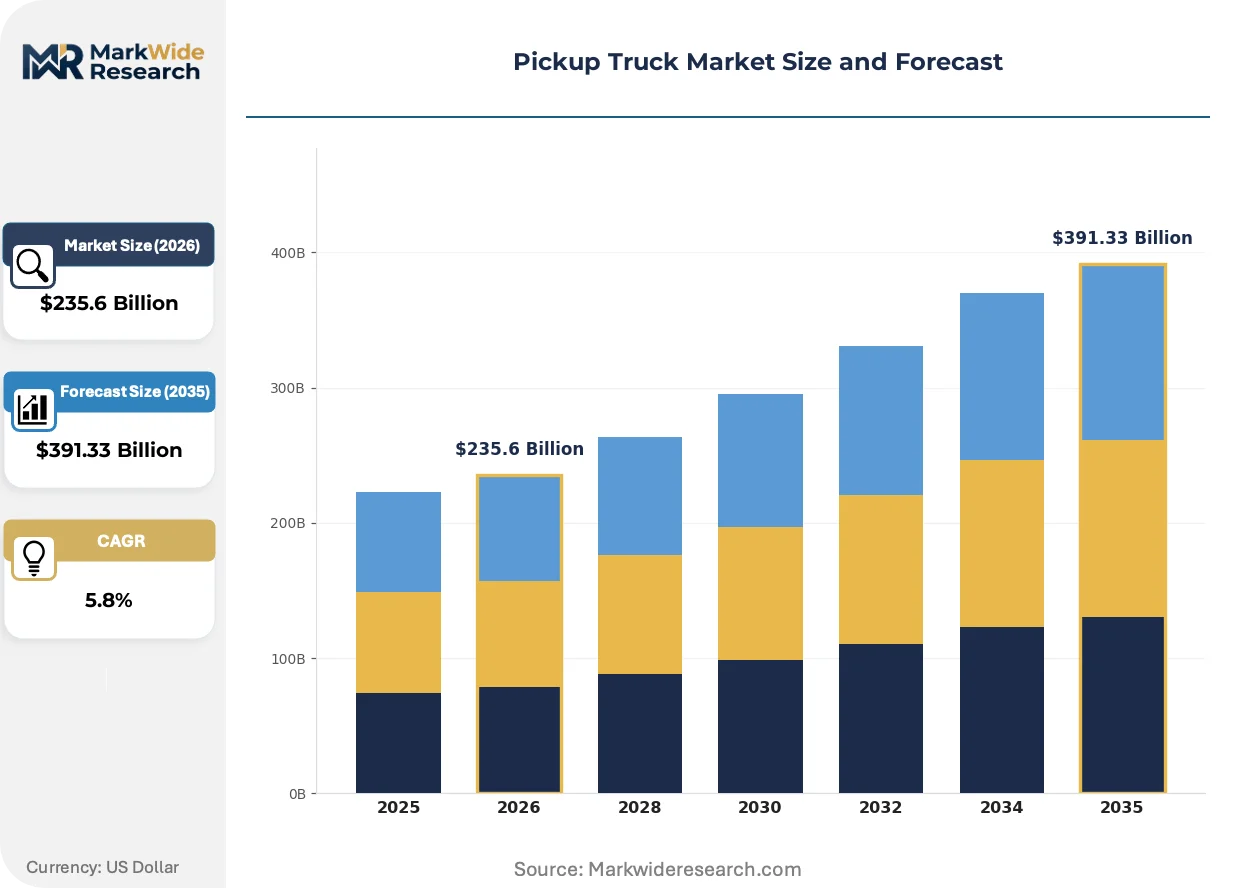
| Market Size in 2026 | $235.6 Billion |
| Market Size in 2035 | $391.33 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Light-Duty, Medium-Duty, Heavy-Duty, Super Duty Fuel Type: Gasoline, Diesel, Electric, Hybrid Drive Type: 4WD, RWD, AWD, FWD End User: Commercial, Consumer, Government, Fleet Operators |
| Companies Covered | Ford Motor Company, General Motors, Stellantis, Toyota Motor Corporation, Nissan Motor, Tesla, Rivian, Hyundai, Honda, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pickup Truck Market Emerging Trajectories
Powertrain architecture choices now determine competitive positioning more than brand heritage, with modular battery platforms and software-defined vehicle systems enabling feature differentiation independent of mechanical engineering.
Cell-to-pack battery designs are decomposing traditional module-and-pack hierarchies, reducing part count and improving volumetric energy density. Fleet operators in California municipal contracts are specifying these configurations for weight-sensitive applications. The structural simplification is compressing manufacturing cost curves and enabling faster platform iteration cycles.
EPA Tier 3 particulate matter standards are forcing particulate filter and selective catalytic reduction upgrades across diesel portfolios. Engine manufacturers must recalibrate thermal management systems to meet bin standards while preserving towing performance. Heavy-duty segments in Texas oilfield services are absorbing compliance costs through extended replacement cycles.
Fleet procurement departments are consolidating supplier relationships around telematics-integrated service contracts that bundle vehicles, charging infrastructure, and energy management. Construction logistics operators in urban California markets are replacing transactional dealer purchases with multi-year total cost agreements. This concentration shifts margin capture from unit sales to lifecycle service provision.
Pickup Truck Market Segmentation
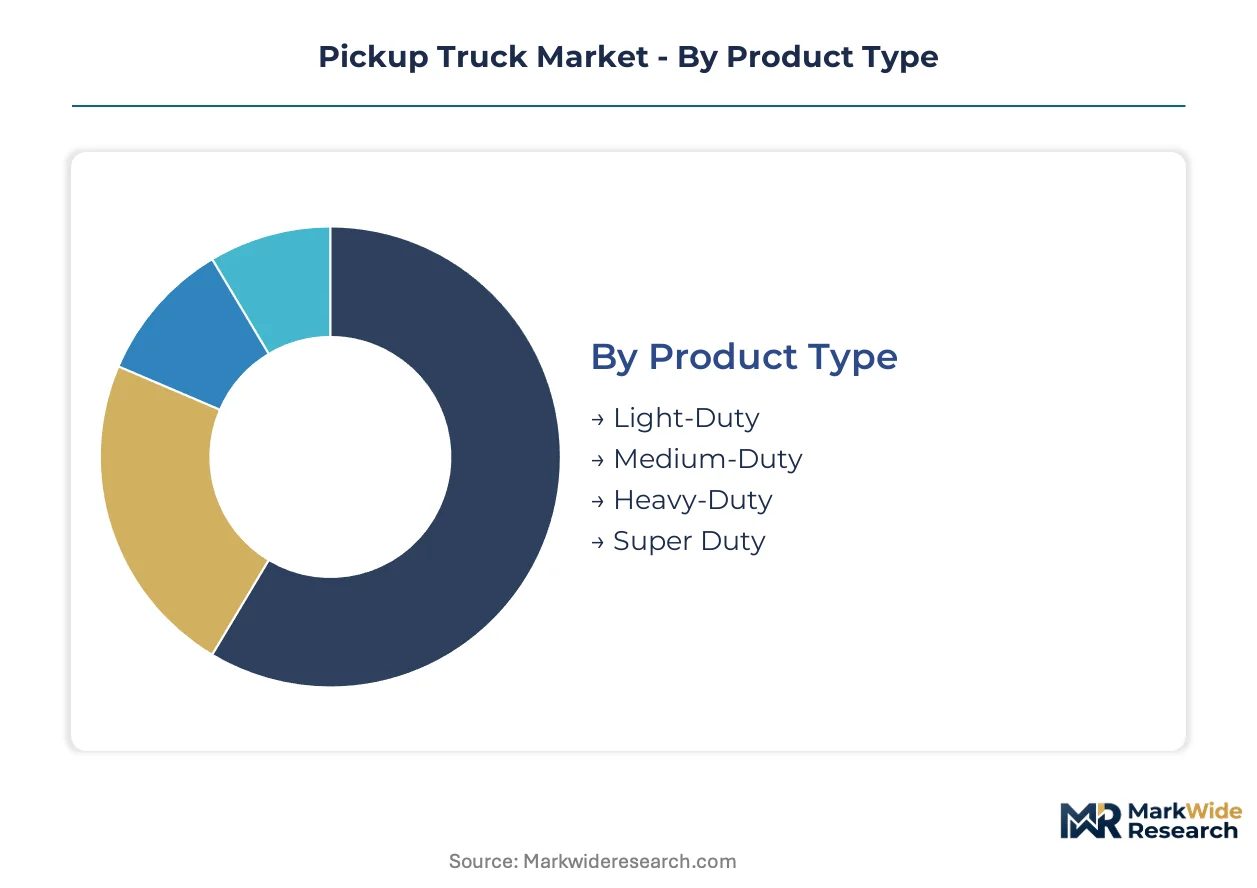
Pickup truck segmentation reveals how powertrain electrification and duty-cycle specialization are fragmenting traditional categories. Fleet procurement patterns now override consumer preference hierarchies, reshaping volume distribution across product tiers and fuel configurations.
Product Type:
Substitution pressure from electric vans and last-mile delivery vehicles compresses growth potential in lighter payload categories while reinforcing heavy-duty moats.
- Light-Duty:Half-ton payload ratings with unibody or light body-on-frame construction dominate suburban consumer registrations. Texas and California urban corridors sustain volume despite electrification headwinds from compact commercial vans.
- Heavy-Duty:Three-quarter and one-ton configurations with reinforced frames and dual-rear-wheel options anchor oilfield services and construction logistics in Houston and Dallas-Fort Worth. Payload ratings above 3,500 pounds insulate this tier from van substitution.
- Medium-Duty:Chassis-cab configurations serve municipal utilities and regional delivery fleets requiring flatbed or box-truck upfits.
- Super Duty:Specialized towing configurations exceeding 30,000-pound gross combined weight ratings target commercial haulers and recreational fifth-wheel operators.
Light-Duty retains volume leadership; Heavy-Duty holds the steepest expansion curve.
Fuel Type:
Cost tier stratification now separates capital-intensive electric platforms from legacy internal combustion, with hybrid architectures bridging total cost of ownership gaps.
- Gasoline:Naturally aspirated and turbocharged V6/V8 engines dominate consumer retail channels and light commercial fleets. EPA Tier 3 compliance costs are compressing margins while sustaining volume in price-sensitive segments.
- Electric:Battery-electric platforms with 300+ mile range ratings and 240V fast-charging capability capture municipal fleet mandates and IRA Commercial Clean Vehicle Credit eligibility. Cell-to-pack designs reduce weight penalties for California municipal contracts.
- Diesel:Compression-ignition engines with selective catalytic reduction and particulate filters retain towing efficiency advantages in heavy-duty long-haul applications.
- Hybrid:Parallel and series-parallel architectures blend torque-fill electric motors with downsized gasoline engines for urban delivery cycles.
Gasoline retains volume leadership; Electric is expanding most quickly.
Drive Type:
Application-specific traction requirements segment demand across terrain capability and fuel efficiency trade-offs.
- 4WD:Part-time and full-time four-wheel-drive systems with low-range transfer cases dominate construction, agriculture, and snow-belt consumer markets. Canadian resource corridors in Alberta and British Columbia mandate this configuration for mining and forestry fleet procurement.
- AWD:Full-time all-wheel-drive with torque-vectoring differentials gains share in urban consumer segments prioritizing on-road stability over off-road articulation.
- RWD:Rear-wheel-drive layouts persist in warm-climate fleet applications where payload capacity outweighs traction requirements.
- FWD:Front-wheel-drive configurations remain marginal in compact unibody trucks targeting fuel economy over utility ratings.
4WD retains volume leadership; AWD is climbing the fastest.
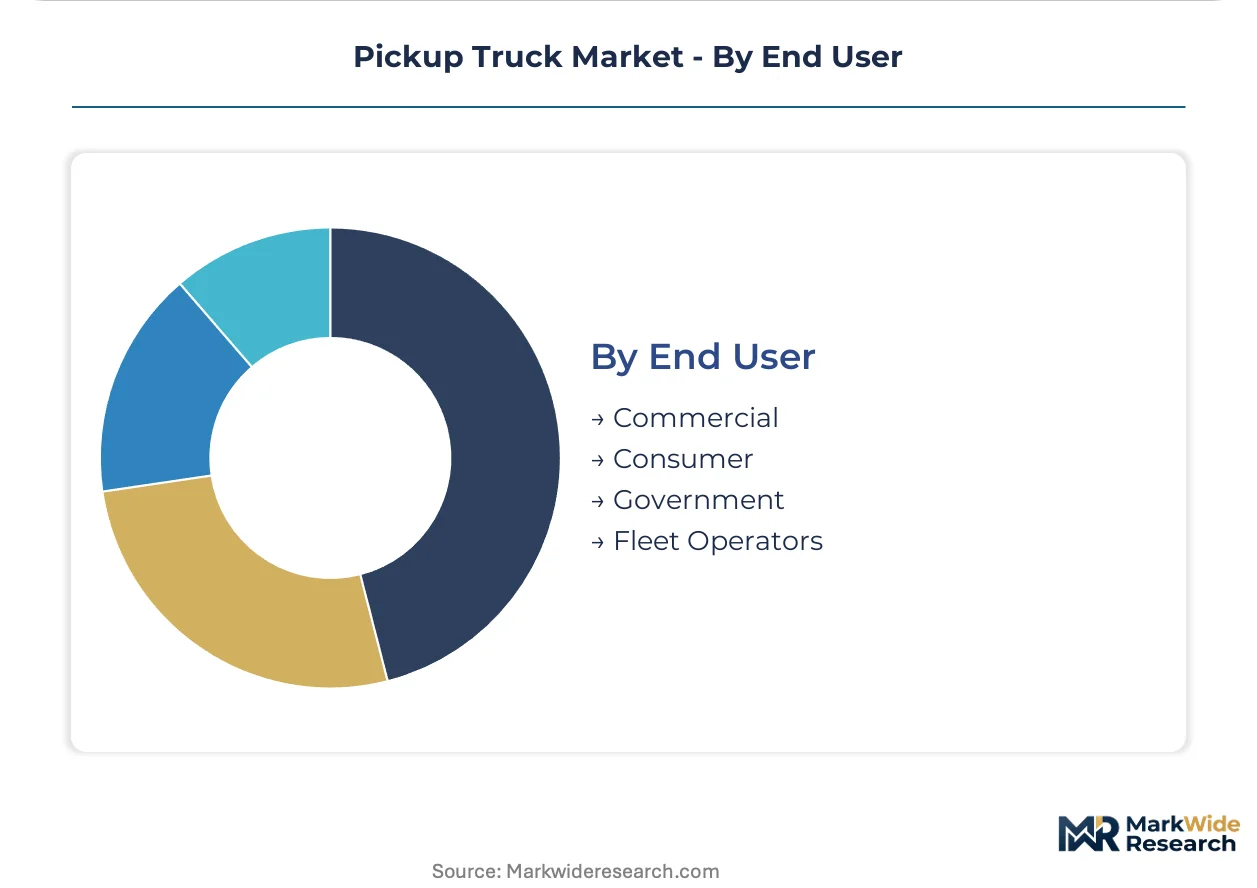
End User:
Customer-type concentration around fleet procurement is displacing traditional dealer-retail economics with lifecycle service contracts.
- Fleet Operators:Multi-vehicle procurement departments with telematics-enabled total cost tracking and electrification mandates. California municipal contracts and Texas construction logistics firms are consolidating supplier relationships around bundled vehicle-charging-service agreements.
- Commercial:Small-business owner-operators in construction, landscaping, and agriculture with mixed consumer-commercial utilization patterns.
- Consumer:Retail purchasers prioritizing towing capacity, cabin amenities, and brand heritage for personal utility and recreational applications.
- Government:Federal, state, and municipal agencies with standardized procurement specifications and domestic content requirements.
Consumer retains volume leadership; Fleet Operators is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States fleet buyers demonstrate the lowest price elasticity as electrification mandates override capital constraints, while emerging market operators retain acute sensitivity to upfront acquisition costs despite favorable total cost of ownership projections.
United States
Texas construction logistics and California municipal procurement anchor volume concentration, with Dallas-Fort Worth oilfield services sustaining heavy-duty demand despite electrification headwinds. EPA Tier 3 emissions standards and IRA Commercial Clean Vehicle Credits up to forty thousand dollars reshape powertrain procurement timelines. Detroit-Warren-Dearborn manufacturing clusters integrate cell-to-pack battery designs for weight-sensitive fleet applications.
Canada
Alberta mining operations and British Columbia forestry fleets pilot electrified heavy-duty configurations where depot charging aligns with duty-cycle economics. Environment and Climate Change Canada federal procurement mandates and provincial zero-emission vehicle regulations accelerate municipal adoption curves. Calgary-Edmonton resource corridors concentrate Super Duty demand for payload-intensive extraction logistics.
Mexico
Automotive assembly export demand and northern border state commercial logistics sustain light-duty volume despite consumer price sensitivity. NOM-163-SEMARNAT-2013 emissions standards and PROSELEC federal energy efficiency programs create compliance pressure on powertrain portfolios. Nuevo León manufacturing clusters near Monterrey supply North American integrated production networks with chassis-cab configurations.
China
Domestic commercial logistics and rural utility applications absorb medium-duty production, with joint-venture manufacturers targeting export compliance rather than local electrification. MIIT NEV credit system and dual carbon goals force powertrain portfolio diversification despite diesel retention in heavy-load segments. Yangtze River Delta manufacturing bases supply battery pack components to global OEM platform programs.
Germany
Commercial fleet operators test electric chassis-cab derivatives for last-mile logistics, though payload requirements limit penetration in construction-adjacent segments. EU CO2 fleet targets and KBA type-approval standards extend homologation timelines for modified electric platforms. Stuttgart industrial corridors concentrate powertrain engineering resources for modular EV architecture development.
Pickup Truck Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with full-line manufacturers leveraging captive battery supply and stamping infrastructure against asset-light entrants dependent on contract manufacturing. The structure rewards scale in heavy-duty body-on-frame segments while permitting niche positioning in premium electric configurations. Two archetypes dominate: legacy OEMs with backward-integrated powertrain operations and pure-play EV specialists with software-defined vehicle architectures. Competitive moves concentrate on strategic partnerships for charging infrastructure and capacity expansion in cell-to-pack battery assembly.
Among Detroit-based integrated manufacturers, Ford Motor Company and General Motors occupy positions exemplifying the legacy archetype with captive supply chain control, while California-based Rivian represents the specialist tier with platform-native electric architecture. Toyota Motor Corporation anchors the hybrid transition pathway with commercial channel reliability positioning. These three entities illustrate the competitive tension between manufacturing scale advantages and technology-native design flexibility.
| Leading Market Players |
|---|
| Ford Motor Company |
| General Motors |
| Stellantis |
| Toyota Motor Corporation |
| Nissan Motor |
| Tesla |
| Rivian |
| Hyundai |
| Honda |
| Others |
Supply Flow & Price Mechanics
Stamping press utilization rates above 80 percent at Detroit-Warren-Dearborn manufacturing clusters create cost floors that contract manufacturers cannot match, compressing margin structures for asset-light EV entrants while reinforcing incumbent pricing power in heavy-duty body-on-frame segments.
Pricing Analysis
After-sales service contracts and telematics-enabled fleet management subscriptions now generate lifetime value multiples exceeding original equipment margins. Three-tier pricing structure across premium, standard, and economy levels segments buyers by duty-cycle intensity and charging infrastructure access. Cost compression in electric powertrain tiers stems from IRA Commercial Clean Vehicle Credit absorption and battery mineral price volatility. Fleet operators demonstrate lowest price sensitivity due to total cost of ownership mandates, while consumer retail channels retain acute upfront acquisition cost consciousness.
Supply Chain Analysis
Strategic stockpiling of lithium hydroxide and nickel sulfate cathode precursors dominates inventory strategy as manufacturers buffer against Chilean and Australian hard-rock spodumene supply disruptions. Cell-to-pack battery assembly draws from China, South Korea, and Japan for electrode manufacturing equipment and separator films. High-voltage cable harnesses and thermal management components rest on single-source vulnerability from Tier 2 automotive suppliers concentrated in Mexico and Germany. Distribution runs through OEM captive finance subsidiaries and consolidated fleet procurement departments rather than traditional dealer networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Charging infrastructure interoperability standards and vehicle-to-grid protocol convergence are transforming pickup truck economics from product sales to platform ecosystems, with bidirectional energy services creating recurring revenue attachments independent of unit volume.
For Market Incumbents: Secure captive offtake agreements for lithium carbonate and nickel sulfate before energy storage sector competition intensifies. Consolidate stamping capacity in Texas and Michigan manufacturing corridors to defend cost advantages against modular platform entrants. Prioritize certification investment for NHTSA modified-vehicle crashworthiness standards to extend homologation timelines that strain EV specialist resources. For New Entrants and Emerging Players: Differentiate on software-defined vehicle architectures that enable over-the-air feature monetization beyond hardware specifications. Target Canadian resource corridor fleet pilots in Alberta mining and British Columbia forestry where depot charging economics align with duty-cycle patterns. Pursue telematics-integrated service contracts as primary go-to-market channel, displacing transactional dealer relationships with lifecycle total cost agreements. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among fleet-focused platform providers with charging infrastructure bundling capabilities. Five-to-ten year viability favors manufacturers with backward-integrated battery cell production and modular EV architecture flexibility over pure-play hardware assemblers. Monitor EPA Tier 3 compliance timeline acceleration and IRA credit extension negotiations as primary inflection indicators for powertrain portfolio reallocation.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | Cell-to-pack cathode offtake from Chilean and Australian producers secures scaling capacity for electric platform production. |
| Charging Infrastructure Partnership | Network interoperability with Texas and California corridor operators reduces fleet customer route-planning friction. |
| Software-Defined Vehicle Investment | Over-the-air update architectures enable feature monetization independent of body-on-frame hardware cycles. |
| Platform Standardization | Modular battery pack geometries across light-duty and heavy-duty segments compress engineering validation costs. |
| Geographic Manufacturing Footprint | Detroit-Warren-Dearborn stamping integration preserves cost advantages against contract assembly competitors. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of EPA regulatory filings, NHTSA crashworthiness databases, and vehicle production registration records. Primary interviews engaged OEM platform engineers, Tier 1 supplier procurement leads, fleet operations managers at Texas construction logistics firms, and California municipal procurement officers. Secondary validation drew from IHS Markit registration data, automotive customs trade records, and SEC manufacturer disclosure filings. Bottom-up segment sizing triangulates against top-down macroeconomic demand indicators across the analysis window.
Segmentation dimensions modeled include vehicle class, propulsion architecture, payload rating tier, and regional production cluster. CAGRs derive from regression analysis of historical volume trajectories against regulatory mandate timelines and infrastructure buildout schedules. Industry-specific forecast inputs incorporate battery mineral supply agreement announcements and IRA Commercial Clean Vehicle Credit utilization rates.
The analysis sits within stated boundaries; outcomes outside sustained lithium price stability and charging network interoperability standardization would require recalibration. Forecasts reflect assumptions regarding EPA Tier 3 compliance deadlines and NHTSA certification pathway durations. Revision becomes warranted when battery mineral supply concentration or high-voltage technician shortage severity crosses operational disruption thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Asia Pacific Cloud Infrastructure Testing Services Market
Others
Surgical Simulation Market
Others
Global Multi Domain Controller Market
Others
Asia-Pacific Induced Pluripotent Stem Cells (Ipscs) Market
Others
United States Cigarette Market
Others
Smart Plug Market
Others
8K Technology Market
Others
Badminton Apparel Market
Others
Latin America Fire Sprinklers Market
Others
Cloud Gaming Baas Market
Others
Durian Fruit Market
Others
Middle East 3D Printing Construction Market
Others
Convertible Shipper Display Market
Others
Banknote Printing Machine Market
Others
Asia-Pacific Intercom Devices Market
Others
United States Smart Homes Market