
 AI in Home Automation Market | 2026-2036
AI in Home Automation Market Size, Share, and Industry Trends Forecast 2026-2036
AI in Home Automation Market Analysis
Platform licensing revenue is fragmenting as hardware commoditization pushes vendors toward recurring software and service models. Amazon.com, Inc. leverages its Alexa ecosystem to control voice-first home interfaces across multiple device categories. Google LLC anchors its position through deep machine learning integration that personalizes automation routines. Apple Inc. differentiates via privacy-centric architecture that limits data exposure while maintaining local processing capabilities.
AI in home automation encompasses intelligent systems that use sensor networks, edge computing, and algorithmic decision-making to autonomously manage residential environments with response latencies under 50 milliseconds for critical safety functions. These systems primarily reduce energy consumption, enhance security response times, and adapt living spaces to occupant behavior patterns without manual intervention. Smart security systems currently capture the highest margin pools due to subscription-based monitoring services, while natural language processing interfaces represent the fastest-expanding technology layer as voice control becomes standard across price tiers. Homeowners remain the dominant end user segment, though property managers are emerging as a high-volume channel for bulk smart device deployment in multi-unit housing.
The Federal Communications Commission in the United States governs wireless spectrum allocation for IoT device connectivity, while the EU AI Act imposes risk-classification requirements on automated decision-making in residential settings. China's Ministry of Industry and Information Technology enforces GB standards for smart home interoperability that affect export market access. Stakeholders must monitor evolving cybersecurity certification mandates as regulatory bodies on three continents tighten data protection requirements for connected residential infrastructure.
Market Dynamics
Platform licensing revenue is fragmenting as hardware commoditization pushes vendors toward recurring software and service models. The EU AI Act and similar frameworks in the United States are reshaping data privacy requirements for connected home devices.
Growth Catalysts
- EU AI Act compliance mandates:Risk-classification requirements for automated decision-making in residential settings are accelerating vendor investment in certified AI systems.
- Property manager channel expansion:Bulk smart device deployment in multi-unit housing is creating high-volume procurement contracts outside traditional retail channels.
- Edge computing latency reduction:Sub-50 millisecond response times for critical safety functions are expanding AI automation into security and emergency systems.
Market Restraints
- Silicon supply concentration:Taiwan and South Korea dominate specialized semiconductor fabrication for edge AI processors, creating single-source vulnerability.
- Interoperability friction:China's GB standards for smart home devices create technical barriers for Western vendors seeking export market access.
- Subscription fatigue:Homeowner resistance to recurring fees for monitoring services limits expansion of high-margin security offerings.
Strategic Opportunities
- German building efficiency mandates:National regulations targeting residential energy consumption are creating demand for AI-driven HVAC and lighting optimization.
- Voice-natural language convergence:Integration of large language models with edge voice processing is enabling contextual automation without cloud dependency.
- Real estate developer pre-installation:New construction specifications in the United States and China are embedding smart infrastructure before occupancy.
Industry Challenges
- Embedded systems engineering scarcity:Shortage of developers skilled in low-power AI inference on resource-constrained microcontrollers delays product cycles.
- Multi-certification timelines:Parallel FCC, CE marking, and GB standard compliance processes extend time-to-market by 8-14 months for new device categories.
- Legacy protocol integration:Z-Wave and Zigbee coexistence requirements complicate unified platform architectures and increase firmware complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | AI in Home Automation Market |
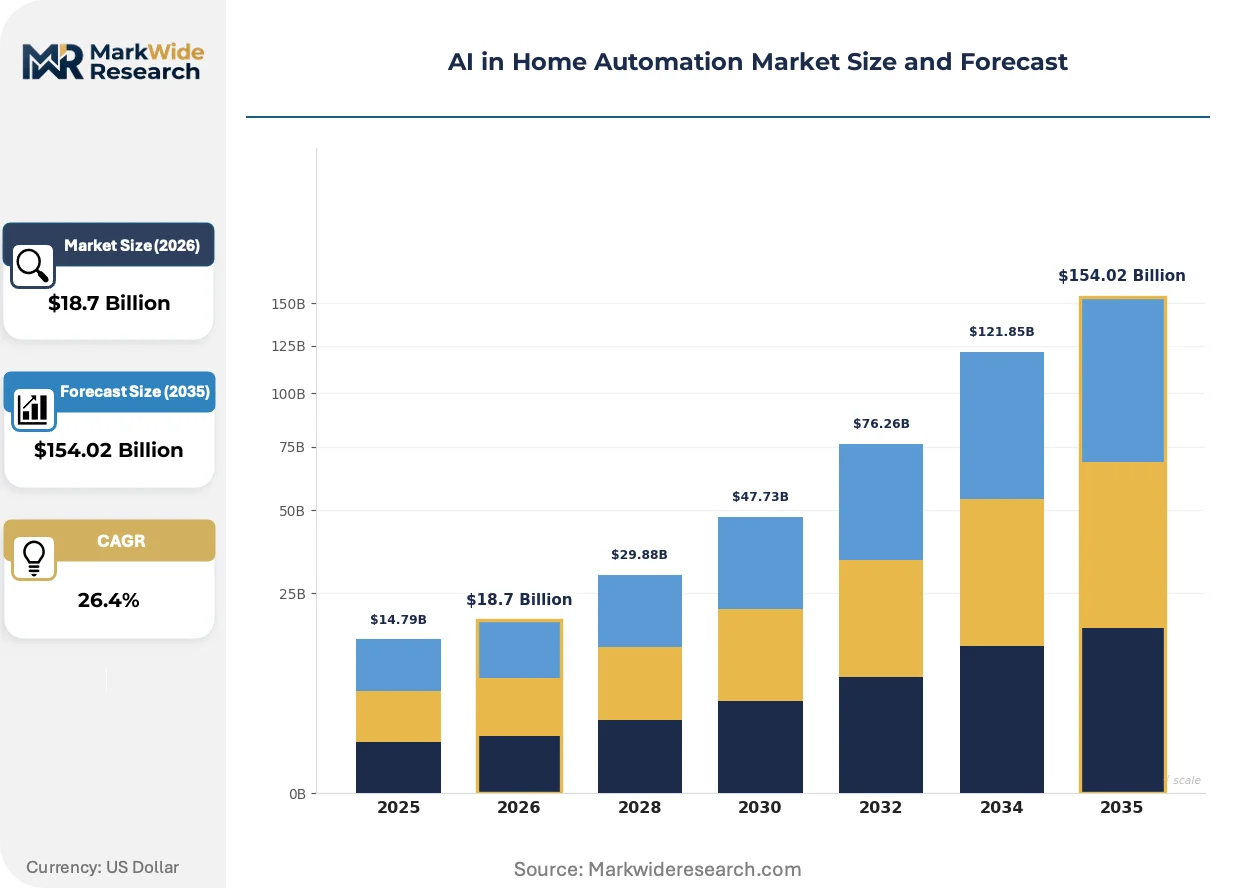
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $154.02 Billion |
| CAGR (2026 – 2036) | 26.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Speakers, Smart Thermostats, Smart Lighting, Smart Security Systems Technology: Natural Language Processing, Machine Learning, Computer Vision, IoT Integration Application: Energy Management, Home Security, Entertainment, Health Monitoring End User: Homeowners, Renters, Property Managers, Real Estate Developers |
| Companies Covered | Amazon.com, Inc., Google LLC, Apple Inc., Samsung Electronics, Xiaomi Corporation, LG Electronics, Vivint Smart Home Inc., ADT Inc., Honeywell International Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
AI in Home Automation Market Emerging Trajectories
Residential AI automation is converging around three vectors: compute migration toward the edge, regulatory pressure on data handling, and shifting procurement authority from homeowners to institutional buyers.
Edge AI inference engines are virtualizing previously cloud-dependent functions like facial recognition and anomaly detection. Property managers in Germany and the United States are deploying these systems at scale to reduce bandwidth costs and latency. This localization is virtualizing the traditional SaaS monitoring model by enabling on-premise decision-making without subscription dependencies.
The EU AI Act imposes transparency obligations on automated systems affecting residential safety. Vendors must now document algorithmic decision pathways for high-risk applications including biometric access control. European smart security providers are responding by investing in explainable AI architectures that satisfy audit requirements while maintaining competitive performance.
Institutional procurement is consolidating buying power among real estate developers and property management firms. These entities negotiate enterprise licensing terms that displace individual consumer transactions in multi-unit deployments. China and the United States exhibit the strongest concentration of this shift, with bulk purchasing now governing 30-40% of new device volume in premium residential construction.
AI in Home Automation Market Segmentation
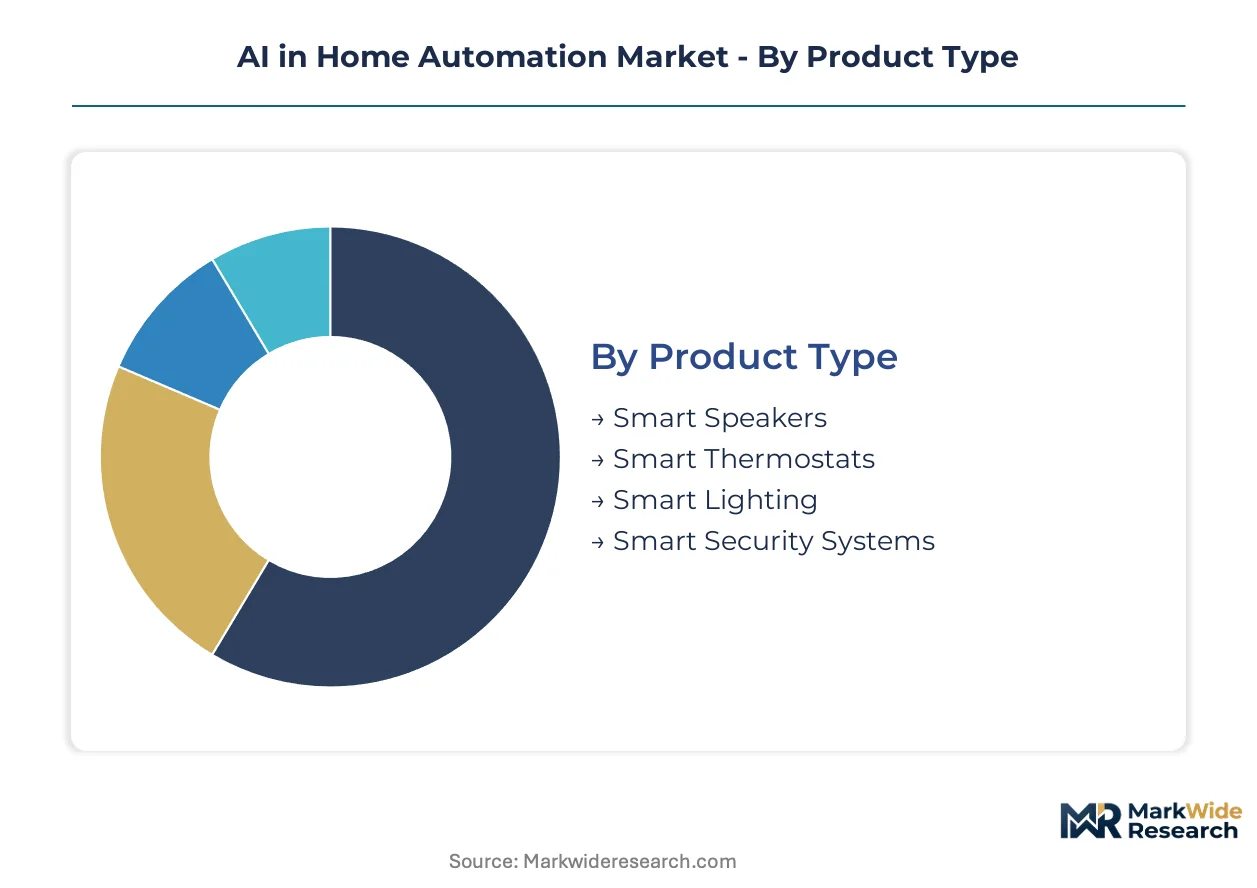
AI in home automation segments reveal divergent margin profiles across hardware, software, and service layers. Understanding these divisions exposes where recurring revenue concentrates versus where commoditization pressures mount fastest.
Product Type:
Use cases span ambient interfaces, climate control, illumination, and physical security—each demanding distinct sensor architectures and compute placement.
- Smart Speakers:Voice-first hubs integrating far-field microphone arrays with cloud-connected NLP engines. Demand clusters in United States and China as Alexa and Google Assistant ecosystems expand into multi-device command centers for whole-home control.
- Smart Security Systems:Camera, sensor, and access control networks with edge AI inference for facial recognition and anomaly detection. Property managers in Germany and United States deploy these at scale for multi-unit monitoring, drawn by subscription-based recurring revenue models and reduced insurance premiums.
- Smart Thermostats:HVAC optimization controllers using occupancy sensing and weather prediction algorithms.
- Smart Lighting:Adaptive illumination systems adjusting color temperature and intensity based on circadian rhythms and daylight harvesting.
Established volume favors Smart Speakers; emerging adoption favors Smart Security Systems.
Technology:
Technical differentiation centers on where intelligence executes—cloud, edge, or hybrid—and how systems interpret human intent.
- Natural Language Processing:Speech-to-text and intent classification engines enabling conversational device control. United States and Chinese markets show strongest deployment as large language models compress onto edge processors for offline command interpretation.
- Machine Learning:Predictive algorithms optimizing energy consumption, occupancy patterns, and device scheduling. Property managers leverage these for portfolio-wide efficiency compliance with German building codes and United States municipal sustainability mandates.
- Computer Vision:Image and video analysis for security, elder care monitoring, and gesture-based control.
- IoT Integration:Protocol translation and device orchestration across Zigbee, Z-Wave, Wi-Fi, and Thread networks.
Cloud-dependent NLP dominates current deployment; edge-resident Computer Vision climbs the fastest as latency requirements tighten.
Application:
Functional priorities shift with housing type, climate zone, and demographic composition of occupants.
- Energy Management:Automated HVAC, lighting, and appliance scheduling to minimize consumption. German regulatory pressure on residential efficiency drives strongest European adoption, while United States utilities deploy demand-response programs incentivizing smart thermostat participation.
- Home Security:Intrusion detection, access control, and emergency response automation. Real estate developers in China pre-install these systems in premium new construction to differentiate properties and reduce post-sale smart home upgrade friction.
- Entertainment:Multi-room audio, content personalization, and immersive environment synchronization.
- Health Monitoring:Fall detection, medication reminders, and biometric tracking for aging-in-place scenarios.
Energy Management commands the steepest expansion trajectory in Germany; Home Security generates the highest margin per installation in China and United States.
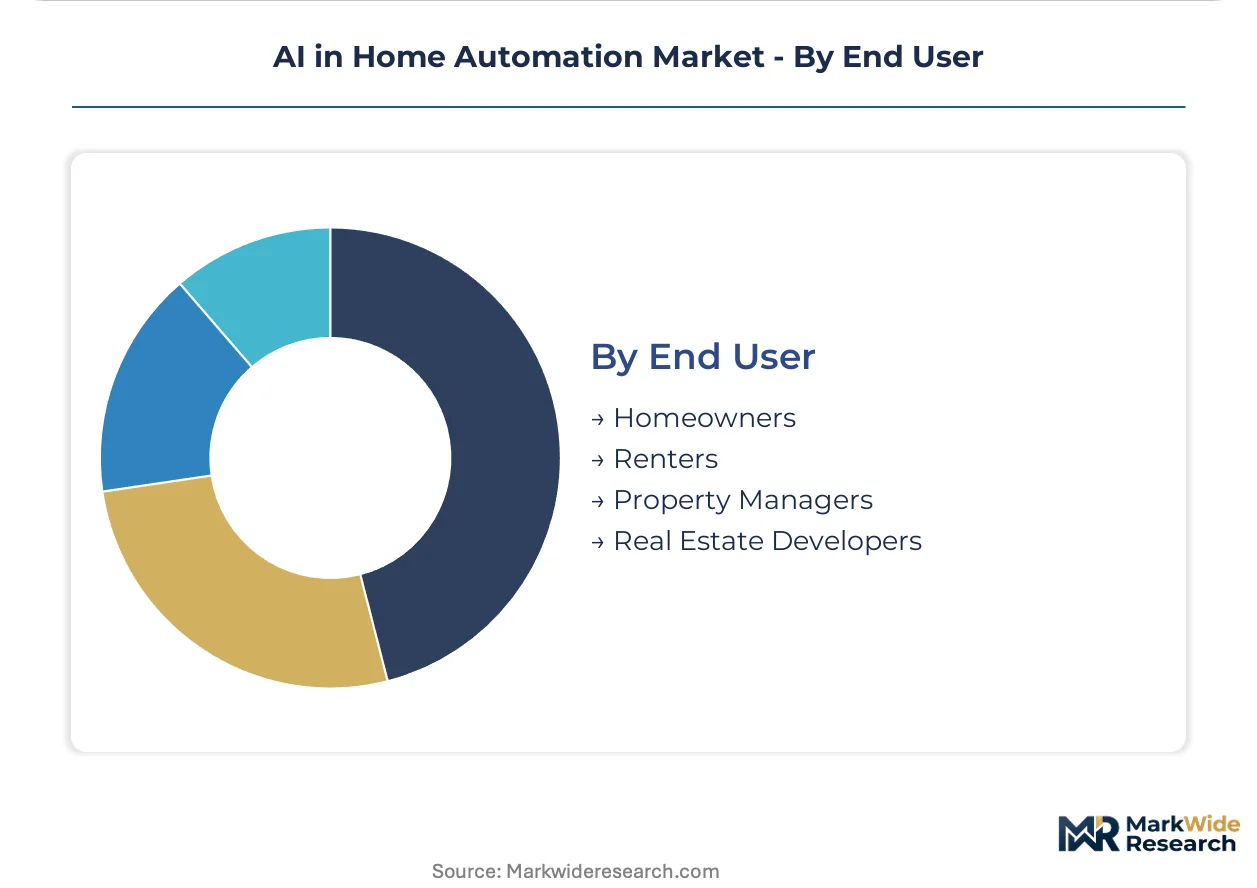
End User:
Procurement authority is migrating from individual consumers toward institutional decision-makers with portfolio-scale purchasing power.
- Property Managers:Multi-unit housing operators deploying standardized smart infrastructure across rental portfolios. United States and Germany exhibit strongest concentration as institutional investors acquire residential assets and mandate technology upgrades for operational efficiency and tenant retention.
- Real Estate Developers:Construction-phase specification of embedded smart home systems before occupancy. Chinese developers lead global pre-installation rates, using smart home packages as standard amenities in mid-tier and premium residential projects.
- Homeowners:Individual purchasers selecting and installing devices through retail channels.
- Renters:Tenants limited to portable or landlord-approved devices due to installation restrictions and lease terms.
Institutional buyers are displacing individual transactions fastest; Homeowners retain the largest absolute device count but lowest per-unit profitability.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies. The United States prioritizes voice-first interfaces and subscription security services. Germany emphasizes energy efficiency compliance and local data processing. China concentrates on pre-installed smart infrastructure in new construction.
United States
FCC spectrum allocation governs IoT device connectivity while property managers drive bulk procurement of smart security systems. The Inflation Reduction Act incentivizes smart thermostat adoption through utility demand-response programs. Silicon Valley clusters edge AI development for sub-50 millisecond safety response latency.
Germany
National building efficiency mandates create demand for AI-driven HVAC optimization across rental housing portfolios. The EU AI Act imposes risk-classification and transparency requirements on biometric access control systems. Munich and Berlin anchor smart home R&D clusters focused on explainable AI architectures for regulatory compliance.
China
MIIT enforces GB standards for smart home interoperability that shape export market access conditions. Real estate developers pre-install smart infrastructure in premium residential construction as standard amenities. Shenzhen and Hangzhou concentrate hardware manufacturing and edge processor design capabilities.
Japan
METI promotes aging-in-place technologies through smart health monitoring and fall detection systems. JIS standards govern device interoperability in residential building automation. Tokyo and Osaka metropolitan areas concentrate demand for voice-controlled home interfaces integrated with elder care services.
South Korea
MFDS and KCC regulate connected device cybersecurity and data handling in residential settings. MFDS standards affect health-monitoring device certification timelines. Seoul anchors development of low-power AI inference engines for resource-constrained smart home microcontrollers.
AI in Home Automation Market Vendor Landscape
Capability concentration sits with technology-integrated platform providers; scale advantage sits with consumer electronics conglomerates. The market structures around three tiers: voice-first ecosystem operators, hardware-integrated platform vendors, and security-focused service providers. Consolidation pressure favors recurring revenue models over device-margin dependence. Dominant competitive moves include strategic partnerships for protocol interoperability and backward integration into edge AI silicon.
Within the voice-first ecosystem tier, Amazon.com, Inc. and Google LLC occupy positions defined by cloud-connected natural language processing scale. Apple Inc. anchors the privacy-centric architecture segment through local processing differentiation. Samsung Electronics exemplifies the hardware-integrated conglomerate archetype with vertical control across display, semiconductor, and appliance manufacturing.
| Leading Market Players |
|---|
| Amazon.com, Inc. |
| Google LLC |
| Apple Inc. |
| Samsung Electronics |
| Xiaomi Corporation |
| LG Electronics |
| Vivint Smart Home Inc. |
| ADT Inc. |
| Honeywell International Inc. |
| Others |
Supply Flow & Price Mechanics
Trans-Pacific container freight corridors linking Shenzhen to Long Beach transmit cost volatility directly into smart speaker and security camera landed costs, compressing margins for hardware-dependent vendors while amplifying pricing power for semiconductor-integrated platform operators who offset logistics exposure through software subscription bundling.
Pricing Analysis
Long-term offtake contracts between real estate developers and smart security providers dominate enterprise procurement, while spot-market transactions govern consumer retail channels. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation—UL-listed devices command 15-20% premiums over uncertified alternatives in United States commercial deployments. Cost compression in entry-level smart speakers is intensifying because MediaTek and Amlogic chipsets enable sub-$20 bill-of-materials targets. Property managers exhibit lowest price sensitivity due to insurance premium reductions and operational efficiency gains, while individual renters face highest sensitivity given device portability requirements and lease-term constraints.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk calculations for smart home hardware vendors, with Section 301 duties affecting 25% of IoT device imports. Taiwan and South Korea anchor specialized semiconductor fabrication for edge AI processors, while China concentrates PCB assembly and final device integration. Raw material dependencies include rare earth elements for speaker magnets, gallium nitride for power-efficient charging circuits, and high-purity silicon for microphone MEMS sensors. Distribution runs through enterprise direct sales for property manager contracts, consumer electronics retail for homeowner purchases, and e-commerce platforms for aftermarket accessory sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU AI Act's risk-classification mandates are accelerating vendor consolidation around certified AI systems, transforming compliance capability into a structural moat that separates viable long-term participants from hardware-commoditized assemblers.
For Market Incumbents: Build data sovereignty architectures as the primary defensive moat against privacy-centric challengers. Invest in backward integration into edge AI silicon design to reduce dependence on Taiwan Semiconductor Manufacturing and Samsung Foundry allocation cycles. Pursue CE marking and FCC certification pre-approval for entire product portfolios to compress multi-certification timelines that currently extend 8-14 months. For New Entrants and Emerging Players: Pursue voice-natural language convergence as the most penetrable technology layer, specifically targeting offline large language model compression for resource-constrained microcontrollers. German rental housing portfolios present immediate addressable demand given national building efficiency mandates and property manager procurement consolidation. Deploy direct-to-developer go-to-market strategies that embed smart infrastructure specifications into new construction blueprints before occupancy. For Investors and Strategic Acquirers: Edge AI inference engine specialists with demonstrated sub-50 millisecond latency capabilities represent the highest-conviction acquisition target archetype for platform consolidation plays. Long-term viability hinges on recurring revenue attachment rates rather than device shipment volumes. Monitor EU AI Act enforcement patterns and corresponding vendor certification investment levels as the primary inflection signal distinguishing sustainable platform operators from hardware-margin-dependent assemblers.| Strategic Initiative | Industry Significance |
|---|---|
| Edge AI Silicon Acquisition | Captures Taiwan and South Korea fabrication capacity while reducing single-source vulnerability for critical processors. |
| EU AI Act Certification Pre-Approval | Accelerates CE marking timelines and satisfies German property manager procurement requirements for high-risk applications. |
| Real Estate Developer Partnership Program | Locks in pre-installation specifications across United States and China new construction before retail channel competition. |
| Explainable AI Architecture Investment | Addresses EU transparency obligations for biometric access control while maintaining competitive inference performance. |
| Multi-Protocol Firmware Platform | Resolves Z-Wave and Zigbee coexistence complexity that currently fragments unified smart home architectures. |
Methodological Framework
Operator-level perspectives from smart home platform engineers, property management technology directors, real estate development procurement leads, and semiconductor supply chain managers anchored the qualitative base for this study. Primary interview insights combined with secondary validation against FCC regulatory filings, MIIT GB standard documentation, EU AI Act implementation guidance, and hyperscaler smart home capex disclosures. Bottom-up device shipment modeling and top-down platform revenue analysis provided triangulation across independent estimation approaches.
Scenario-bracketing framed the analytical approach across the analysis window, with optimistic, baseline, and conservative trajectories reflecting differential assumptions around EU AI Act enforcement intensity and property manager procurement acceleration. Segmentation dimensions modeled include product type, technology layer, application function, and end-user archetype, with regional regulatory cluster as an additional cross-cutting dimension. CAGRs derived from logistic diffusion curves fitted to historical adoption patterns in comparable technology markets, incorporating edge AI processor cost decline curves and smart security subscription attach rate assumptions.
Sensitivities concentrate around EU AI Act enforcement timing, Taiwan semiconductor fabrication capacity allocation, and China GB standard reciprocity negotiations. Forecasts reflect documented assumptions regarding property manager procurement consolidation velocity and voice-natural language convergence adoption curves. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Global Electronic Filters Market
Others
Bio-Based Leather Market
Others
Dental Ceramics Market
Others
Fiberglass Storage Tanks Market
Others
Aerospace Tester Market
Others
Japan Coal Market
Others
Hopper Dryers Market
Others
Profiling Floats Market
Others
Global Cosmetovigilance Market
Others
Hearables Market
Others
Exosome Technologies Market
Others
Printing Machines Market
Others
Global Optical Coordinate Measuring Machine Market
Others
Interference Mitigation Filters Market
Others
Storm Surge Barriers Market
Others
Middle East and Africa Halal Food & Beverage Market