
 Global Webinar and Webcast Market | 2026-2036
Global Webinar and Webcast Market Size, Share, and Industry Trends Forecast 2026-2036
Global Webinar and Webcast Market Foresight
The capital-intensity gap between self-service streaming tools and enterprise-grade webinar infrastructure is collapsing as mid-market vendors match broadcast-grade reliability. ON24 sustains premium positioning through deep analytics integration for investor relations and demand generation workflows. Cisco Webex dominates in regulated verticals where FedRAMP authorization and end-to-end encryption anchor procurement decisions. StreamYard competes on creator-economy accessibility, leveraging browser-native production to lower technical barriers for solo operators and small agencies.
Webinar and webcast platforms deliver real-time audiovisual content distribution over IP networks, typically supporting 1080p streaming, sub-five-second latency thresholds, and simultaneous audience capacities exceeding 100,000 participants for single events. Their primary commercial purpose centers on scalable knowledge transfer, lead generation, and stakeholder communication without physical venue constraints. Cloud-based deployment leads in revenue contribution due to elastic infrastructure economics and rapid provisioning cycles, while automated webinar solutions represent the fastest-expanding solution category as marketing teams prioritize evergreen content pipelines and timezone-agnostic audience reach. Audience engagement tools command disproportionate margin pools because interactive polling, Q&A orchestration, and behavioral analytics differentiate platform stickiness in renewal negotiations.
FDA 21 CFR Part 11 considerations shape validation requirements for pharmaceutical firms deploying webinar platforms in promotional and clinical training contexts, while GDPR and the EU AI Act impose data residency and algorithmic transparency obligations on European deployments. The FCC's net neutrality framework indirectly affects streaming quality economics for US-based providers and their enterprise customers. Stakeholders must monitor how emerging AI-generated content disclosure mandates from multiple national regulators reshape platform architecture roadmaps and customer compliance workflows.
Market Dynamics
Cloud infrastructure elasticity is compressing the capital barrier between entry-level streaming tools and broadcast-grade webinar platforms, forcing mid-market vendors to match enterprise reliability standards while defending margin structures.
Growth Catalysts
- FDA 21 CFR Part 11:Validation requirements for pharmaceutical promotional webinars and clinical training sessions create specialized demand for compliant platform architectures in the United States.
- Hybrid workforce normalization:Fortune 500 technology and financial services firms sustain procurement of premium solutions for distributed onboarding and investor relations workflows.
- EU AI Act algorithmic transparency mandates:European cloud migration requirements accelerate platform redesigns for data residency and automated content disclosure compliance.
Market Restraints
- Sub-five-second latency engineering:Real-time streaming quality demands specialized CDN infrastructure that concentrates supplier power among three dominant cloud providers.
- FCC net neutrality uncertainty:Quality-of-service economics for US-based streaming providers face regulatory friction that distorts capacity planning and pricing models.
- Browser-native production ceilings:Technical limitations in WebRTC implementations constrain simultaneous broadcast quality above 50,000 concurrent viewers without dedicated edge infrastructure.
Strategic Opportunities
- Saudi Arabia and UAE enterprise digitization:MOHAP and SFDA compliance frameworks in Gulf Cooperation Council states create first-mover advantages for localized webinar infrastructure deployment.
- Evergreen content automation:Marketing teams in timezone-distributed organizations prioritize automated webinar pipelines that operate without live presenter dependency.
- Behavioral analytics convergence with CRM:Integration between engagement telemetry and customer data platforms opens margin pools in renewal negotiations for demand generation workflows.
Industry Challenges
- ISO 27001 and SOC 2 Type II certification timelines:Security attestation requirements stretch 6-14 months, delaying enterprise procurement cycles for emerging platform vendors.
- Legacy video conferencing integration complexity:Migration from on-premise Cisco and Polycom estates requires custom API development that consumes engineering bandwidth.
- Real-time translation engineering talent scarcity:AI-powered multilingual captioning demands computational linguistics expertise that concentrates in Tel Aviv, Bangalore, and Berlin labor markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Webinar and Webcast Market |
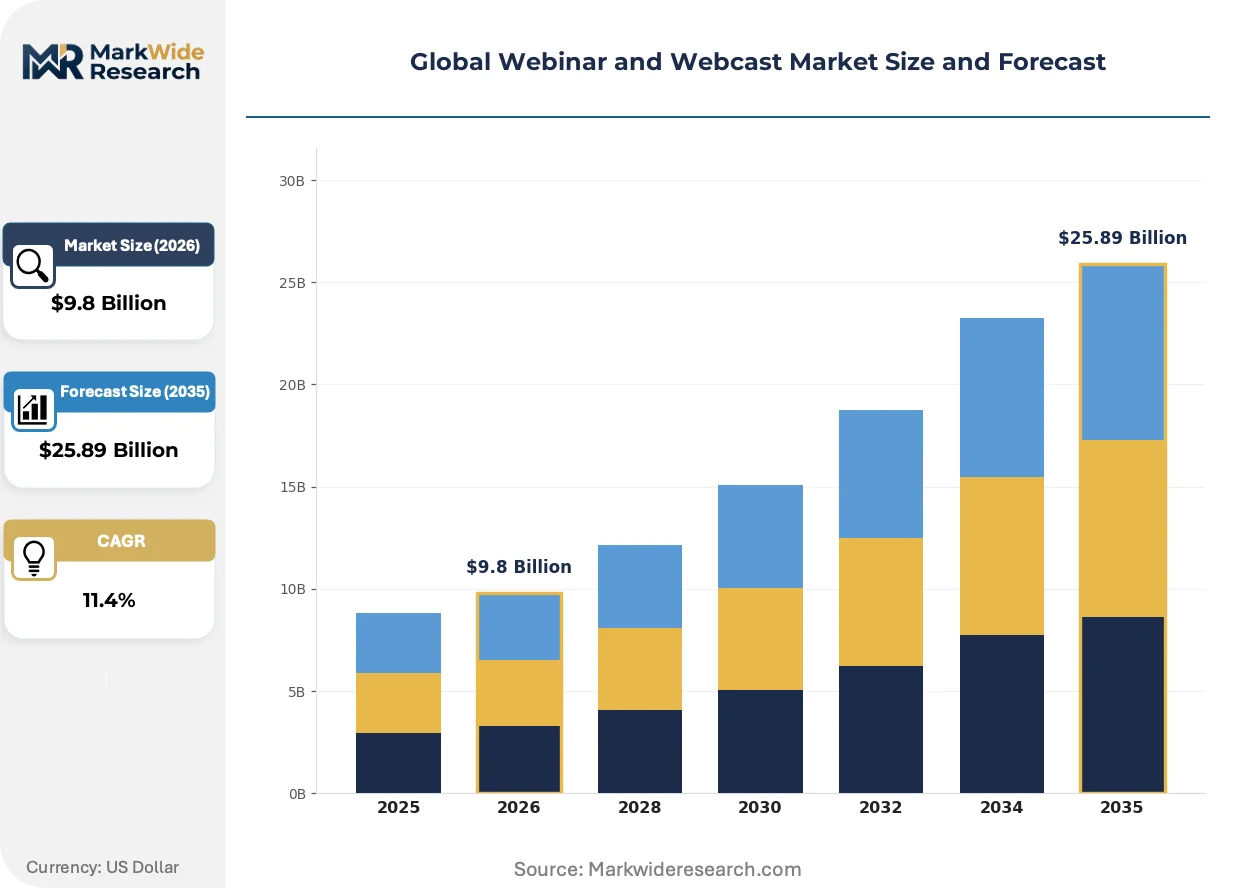
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $25.89 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premises, Hybrid, Hosted Solution: Live Streaming, Automated Webinars, Simulive, Event Management, Audience Engagement Use Case: Corporate Training, Product Launches, Investor Relations, Educational Seminars, Internal Communications End User: Technology Providers, Financial Services, Higher Education Institutions, Consulting Firms |
| Companies Covered | BigMarker, StreamYard, ClickMeeting, Cisco Webex, WebinarJam, Zoom Webinars, ON24, Microsoft Teams, GoToWebinar, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Webinar and Webcast Market Shifts & Advancements
Artificial intelligence is restructuring webinar platform architecture across three vectors: automated content generation, real-time engagement optimization, and compliance documentation. These shifts compress operational overhead while elevating technical sophistication requirements.
Browser-native production stacks leveraging WebAssembly and GPU acceleration are displacing downloadable encoder software for solo operators and small agencies. Marketing teams at mid-sized B2B firms adopt these tools within 90-day procurement cycles. The displacement collapses the technical barrier between amateur and professional broadcast quality, eroding the premium positioning of legacy installed-base solutions.
GDPR Article 22 automated decision-making provisions and the EU AI Act's synthetic content disclosure requirements reshape European platform roadmaps. Vendors must embed algorithmic transparency logs and real-time AI-generated content labeling into streaming workflows. Pharmaceutical and financial services deployments in Germany, France, and the Netherlands face the steepest compliance engineering costs.
Subscription fatigue among marketing operations leaders drives unbundling of all-in-one webinar suites into specialized components. Buyers now assemble best-of-breed stacks combining StreamYard-class production tools with dedicated analytics and CRM synchronization layers. This pattern concentrates in US technology and professional services verticals where procurement autonomy sits with departmental budgets rather than centralized IT.
Global Webinar and Webcast Market Segmentation
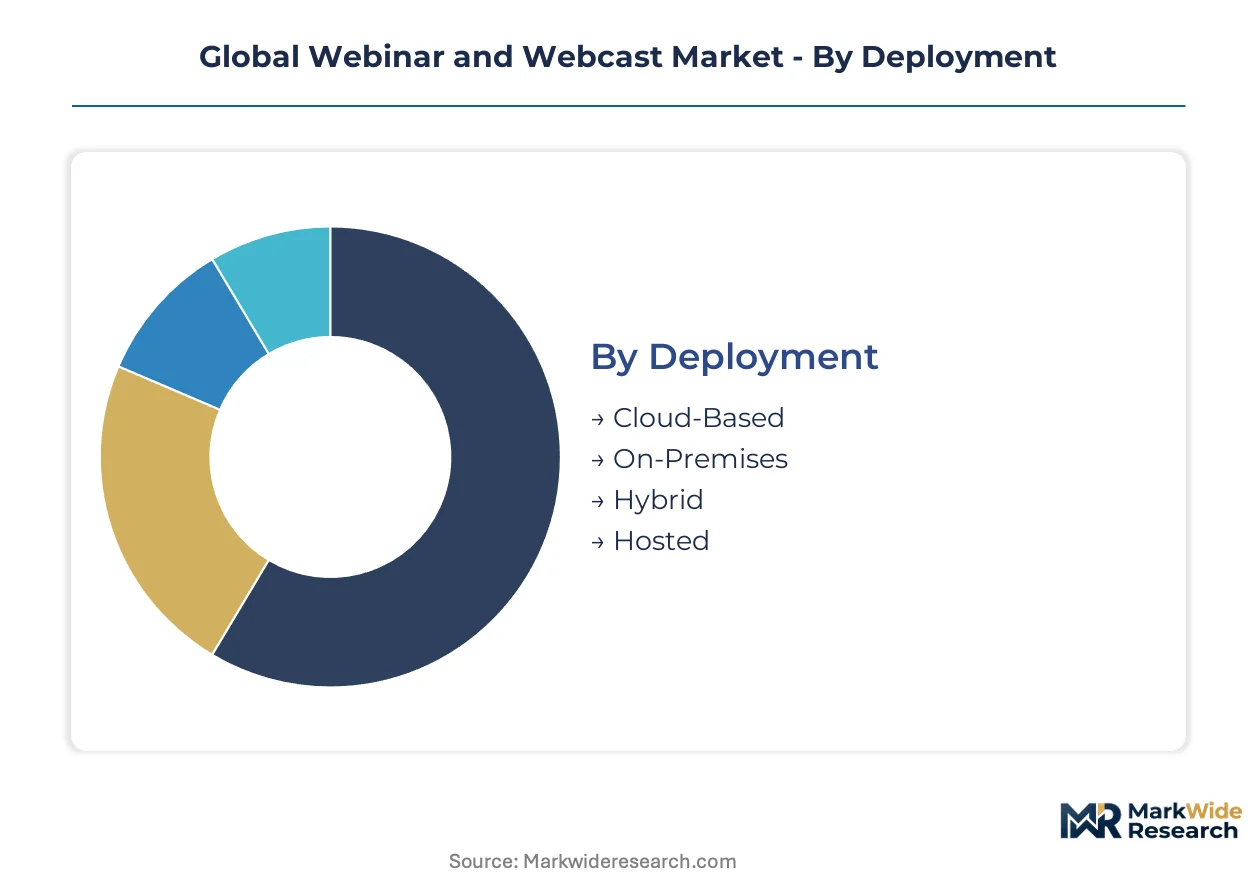
Webinar platform procurement patterns diverge sharply across deployment models, solution architectures, and organizational use cases. Segmentation reveals where vendor substitution pressures concentrate and which customer profiles sustain premium pricing power.
Deployment:
Substitution pressure from browser-native tools weighs heaviest on hosted and hybrid configurations as WebRTC implementations close the reliability gap with dedicated infrastructure.
- Cloud-Based:Elastic compute provisioning enables sub-hour deployment cycles and automatic scaling beyond 100,000 concurrent viewers. Demand concentrates among Fortune 500 technology providers in the United States where FedRAMP authorization and SOC 2 Type II attestation anchor procurement decisions.
- On-Premises:Dedicated hardware stacks in customer data centers deliver full data sovereignty and sub-five-second latency without third-party CDN dependency. Financial services firms in Frankfurt and Zurich deploy these configurations to satisfy national financial regulator data residency mandates.
- Hybrid:Split architectures route sensitive content through private infrastructure while leveraging public cloud burst capacity for peak audiences.
- Hosted:Single-tenant managed deployments in vendor-controlled facilities serve mid-market buyers seeking compliance without internal infrastructure investment.
Cloud-Based deployments anchor the volume base while Hybrid configurations gain share at the steepest rate as European GDPR and EU AI Act compliance requirements accelerate architecture redesigns.
Solution:
Margin concentration follows capability differentiation, with engagement analytics commanding premium positioning against commoditized streaming infrastructure.
- Live Streaming:Real-time audiovisual distribution over IP networks supporting 1080p resolution and interactive features including polling and Q&A orchestration. Technology providers in San Francisco and Seattle sustain procurement of broadcast-grade reliability for product announcement events.
- Audience Engagement:Behavioral telemetry platforms capturing attention metrics, sentiment analysis, and CRM-synchronized lead scoring. Consulting firms in London and New York prioritize these tools for demand generation workflow integration.
- Automated Webinars:Pre-recorded content pipelines operating without live presenter dependency across timezone-distributed audiences.
- Simulive:Hybrid formats combining pre-recorded core content with real-time moderator interaction.
- Event Management:Registration, scheduling, and post-event analytics suites for multi-session programming.
Live Streaming generates the revenue foundation while Audience Engagement solutions expand most quickly as marketing operations leaders unbundle all-in-one suites for best-of-breed stacks.
Use Case:
Application-specific compliance requirements create vendor stickiness variations, with regulated contexts locking in platform selection more tightly than discretionary marketing deployments.
- Corporate Training:Scalable knowledge transfer for distributed workforce onboarding and certification tracking. Higher education institutions in Singapore and Australia deploy these solutions for remote degree program delivery.
- Investor Relations:Earnings calls, shareholder meetings, and regulatory disclosure events with archival documentation requirements. Financial services firms in New York and London anchor demand for deep analytics integration and SEC-compliant retention.
- Product Launches:High-production-value streaming for market introduction events and press coordination.
- Educational Seminars:Academic lecture capture and continuing professional education credit tracking.
- Internal Communications:Town halls, policy updates, and crisis response messaging for geographically dispersed employees.
Corporate Training commands the installed base while Investor Relations climbs the fastest as quarterly disclosure automation and behavioral analytics reshape procurement priorities.
End User:
Customer-type segmentation reveals procurement autonomy patterns, with departmental budgets in professional services enabling faster vendor switching than centralized IT governance in regulated industries.
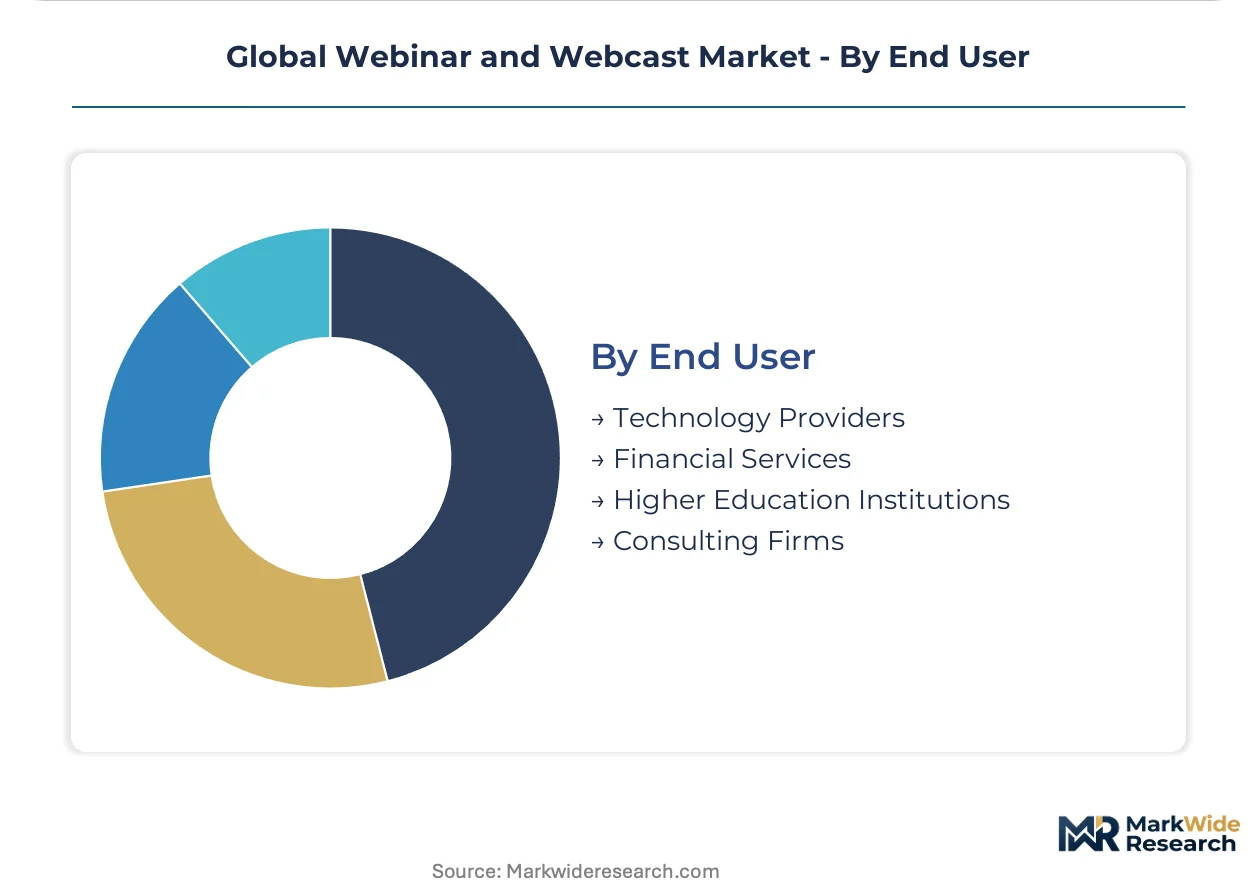
- Technology Providers:SaaS vendors and hardware manufacturers deploying webinars for product marketing and developer relations. Firms in Austin and Tel Aviv drive demand for API-first architectures and CRM-native integration.
- Financial Services:Banks, asset managers, and insurance carriers with FedRAMP, SEC, and national financial regulator compliance obligations. Institutions in New York, London, and Zurich sustain premium solution procurement for investor relations workflows.
- Higher Education Institutions:Universities and business schools delivering remote degree programs and executive education.
- Consulting Firms:Professional services organizations leveraging webinars for thought leadership distribution and client acquisition.
Technology Providers anchor the customer volume base while Financial Services delivers the steepest expansion trajectory as regulatory disclosure automation and hybrid work normalization sustain enterprise procurement cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity for webinar platforms varies sharply by geography. United States buyers absorb premium pricing for FedRAMP-authorized solutions, while Indian and Southeast Asian procurement prioritizes browser-native accessibility over broadcast-grade infrastructure.
United States
Fortune 500 technology firms in San Francisco and Seattle sustain demand for enterprise-grade streaming with sub-five-second latency. SEC disclosure requirements and FDA 21 CFR Part 11 validation protocols shape procurement specifications for financial services and pharmaceutical verticals. New York-based asset managers anchor the investor relations segment with deep analytics integration requirements.
Germany
Automotive manufacturers and industrial conglomerates in Stuttgart and Munich deploy hybrid architectures for supplier training and engineering knowledge transfer. GDPR data residency mandates and EU AI Act algorithmic transparency obligations accelerate platform redesigns for European cloud deployments. Frankfurt financial institutions drive on-premises demand for BaFin-compliant data sovereignty.
United Kingdom
London consulting firms and professional services organizations prioritize audience engagement tools for demand generation workflows. FCA regulatory disclosure frameworks shape archival documentation requirements for earnings calls and shareholder communications. Cambridge and Oxford university clusters sustain educational seminar procurement for remote degree program delivery.
India
IT services firms in Bangalore and Hyderabad scale corporate training deployments for distributed workforce onboarding across multiple timezones. TRAI data localization discussions and RBI cybersecurity guidelines influence cloud architecture decisions for financial services clients. Mumbai-based banking institutions represent the fastest-growing enterprise segment for compliance-oriented solutions.
United Arab Emirates
MOHAP and SFDA compliance frameworks in Dubai and Abu Dhabi create specialized demand for localized webinar infrastructure in healthcare and pharmaceutical verticals. Government digitization initiatives under Vision 2030 sustain procurement of premium platforms for public sector training. Saudi Aramco and sovereign wealth fund investor relations workflows anchor high-revenue deployments.
Global Webinar and Webcast Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure. Broadcast-grade reliability with sub-five-second latency concentrates among infrastructure-heavy vendors, while browser-native accessibility dominates the long tail of solo operators and small agencies. Three archetypes define the field: enterprise-grade platforms with deep analytics integration, mid-market solutions emphasizing rapid deployment cycles, and creator-economy tools leveraging WebRTC accessibility. Consolidation pressure manifests through API-first acquisition strategies and vertical specialization into regulated verticals.
Within the enterprise analytics tier, ON24 and Cisco Webex occupy positions defined by compliance depth and investor relations workflow integration. StreamYard anchors the creator-economy accessibility vector with browser-native production stacks that collapse technical barriers for non-technical users. These three exemplify how vendor selection diverges between procurement-autonomous marketing teams and centralized IT governance in regulated industries.
| Leading Market Players |
|---|
| BigMarker |
| StreamYard |
| ClickMeeting |
| Cisco Webex |
| WebinarJam |
| Zoom Webinars |
| ON24 |
| Microsoft Teams |
| GoToWebinar |
| Others |
Supply & Pricing Matrix
Six-to-fourteen-month ISO 27001 and SOC 2 Type II certification timelines compress procurement velocity for emerging vendors while anchoring premium pricing power with established cloud infrastructure providers who have already cleared security attestation gates.
Pricing Analysis
After-sales revenue from multi-year enterprise support contracts and API integration services drives lifetime value beyond initial SaaS subscription tiers. Three-tier pricing structure across premium, standard, and economy levels stratifies by FedRAMP authorization status and real-time analytics depth. Cost compression in mid-market browser-native tiers is intensifying because WebRTC implementations erode technical differentiation. Marketing operations leaders at professional services firms exhibit highest price sensitivity, while financial services procurement in New York and London absorbs premiums for SEC-compliant archival retention.
Supply Chain Analysis
Content delivery network chokepoints in Northern Virginia, Frankfurt, and Singapore anchor global streaming quality economics. Webinar infrastructure draws from hyperscale cloud compute in the United States, submarine cable capacity across the Atlantic corridor, and GPU acceleration hardware concentrated in Taiwan and South Korea. Single-source vulnerability concentrates in three dominant CDN providers controlling sub-five-second latency engineering. Distribution runs through direct enterprise sales teams for regulated verticals and self-service web portals for creator-economy segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity concentrates in unbundled best-of-breed stacks as marketing operations leaders abandon monolithic suites for specialized engagement analytics and CRM synchronization layers.
For Market Incumbents: Compound defensive positioning through deeper vertical integration into edge infrastructure and accelerated FedRAMP authorization expansion. Threat substitution from browser-native WebRTC tools demands counter-investment in proprietary low-latency networks. Certification investment in EU AI Act algorithmic transparency compliance locks in European financial services procurement. For New Entrants and Emerging Players: Differentiate on real-time multilingual captioning capabilities targeting Indian IT services firms and Gulf Cooperation Council healthcare digitization. White-space penetration concentrates in automated webinar pipelines for timezone-distributed corporate training. Go-to-market through API-first partnerships with existing CRM and customer data platforms reduces customer acquisition friction. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across browser-native production segments as WebAssembly and GPU acceleration collapse encoder software requirements. Long-term viability favors platforms with durable compliance moats in FDA 21 CFR Part 11 and GDPR Article 22 contexts. Acquisition target archetype: mid-market vendors with established SOC 2 Type II attestation and underdeveloped enterprise sales infrastructure. Signal to watch: EU AI Act enforcement patterns in Germany and France as inflection indicator for compliance engineering cost trajectories.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | API-first architectures enable CRM synchronization for ON24-class demand generation workflows. |
| Geographic Expansion | Localized infrastructure deployment captures MOHAP and SFDA compliance opportunities in Dubai and Riyadh. |
| Acquisition of Specialist Firm | Real-time translation engineering talent scarcity in Tel Aviv and Bangalore drives computational linguistics consolidation. |
| Product Launch | Automated webinar pipelines address timezone-agnostic audience reach for Fortune 500 distributed workforces. |
| Strategic Partnership | Hyperscaler CDN alliances secure sub-five-second latency capacity beyond 50,000 concurrent viewer ceilings. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with platform engineering directors, marketing operations leaders, and enterprise IT procurement officers; and secondary validation through SEC filings of publicly traded software vendors, hyperscaler capex disclosures, and compliance documentation from FDA and EU regulatory databases. Bottom-up sizing triangulated against top-down macroeconomic indicators across cloud infrastructure spend and enterprise software procurement trends.
Across the modeling period, the analytical framework segmented by deployment architecture, solution capability tier, organizational use case, and end-user industry vertical. CAGRs were derived from elasticity-adjusted adoption curves incorporating hybrid workforce normalization rates and regulatory compliance mandate timelines. Industry-specific inputs included real-time streaming latency engineering costs and AI-generated content disclosure implementation trajectories.
The analysis sits within stated boundaries; outcomes outside sustained cloud infrastructure investment and stable net neutrality frameworks would require recalibration. Forecasts reflect documented assumptions regarding enterprise procurement cycle durations and certification timeline stability. Practitioners should keep alternative scenarios live as EU AI Act enforcement patterns and FCC regulatory positioning evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Global Personal Care Packaging Market
Others
Workstation Desktops Market
Others
Channel-In-A-Box (Ciab) Market
Others
Post Consumer Recycled Bottles Market
Others
PCB Laminate Market
Others
Magnetic Stripe Readers Market
Others
Duckweed Market
Others
Asia-Pacific Military 4D Printing Market
Others
Global Luxury High End Furniture Market
Others
Global Crowdsourced Testing Market
Others
Managed Testing Services Market
Others
Global Electroshock Weapons Market
Others
Japan Automotive LED Lighting Market
Others
Coriolis Meters Market
Others
Mobile Computer Market
Others
Dry Washer Market