
 Process Instrumentation Equipment Market | 2026-2036
Process Instrumentation Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Process Instrumentation Equipment Market Outlook
IEC 61508 functional safety certification is reorganizing competitive tiers in process instrumentation, forcing vendors to demonstrate SIL-rated architectures before qualifying for major capital projects. Emerson Electric Co. sustains R&D intensity across pressure and flow measurement platforms. Siemens AG dominates digital twin integration with its instrumentation portfolio. Yokogawa Electric Corporation anchors market presence in Asia through specialized control system compatibility.
Process instrumentation equipment comprises sensors, transmitters, analyzers, and controllers that measure pressure, flow, temperature, and level variables with accuracies typically ranging from 0.025% to 0.1% of span, converting physical parameters into standardized 4-20 mA or digital fieldbus signals for real-time process optimization and safety interlocking. Pressure transmitters and flow meters command the largest installed base, while smart sensors with embedded diagnostics represent the fastest-expanding technology segment as facilities pursue predictive maintenance strategies. Wireless technologies are gaining traction in brownfield sites where cabling retrofit costs prove prohibitive.
EPA emissions monitoring mandates and EU F-Gas Regulation compliance deadlines shape product roadmaps for US and European suppliers, compelling continuous analyzer upgrades and refrigerant-free instrument designs. FDA's process analytical technology guidance drives pharmaceutical sector demand for in-line spectroscopic and chromatographic instrumentation. Stakeholders must weigh certification backlog timelines against project award cycles when allocating engineering resources across regional qualification requirements.
Market Dynamics
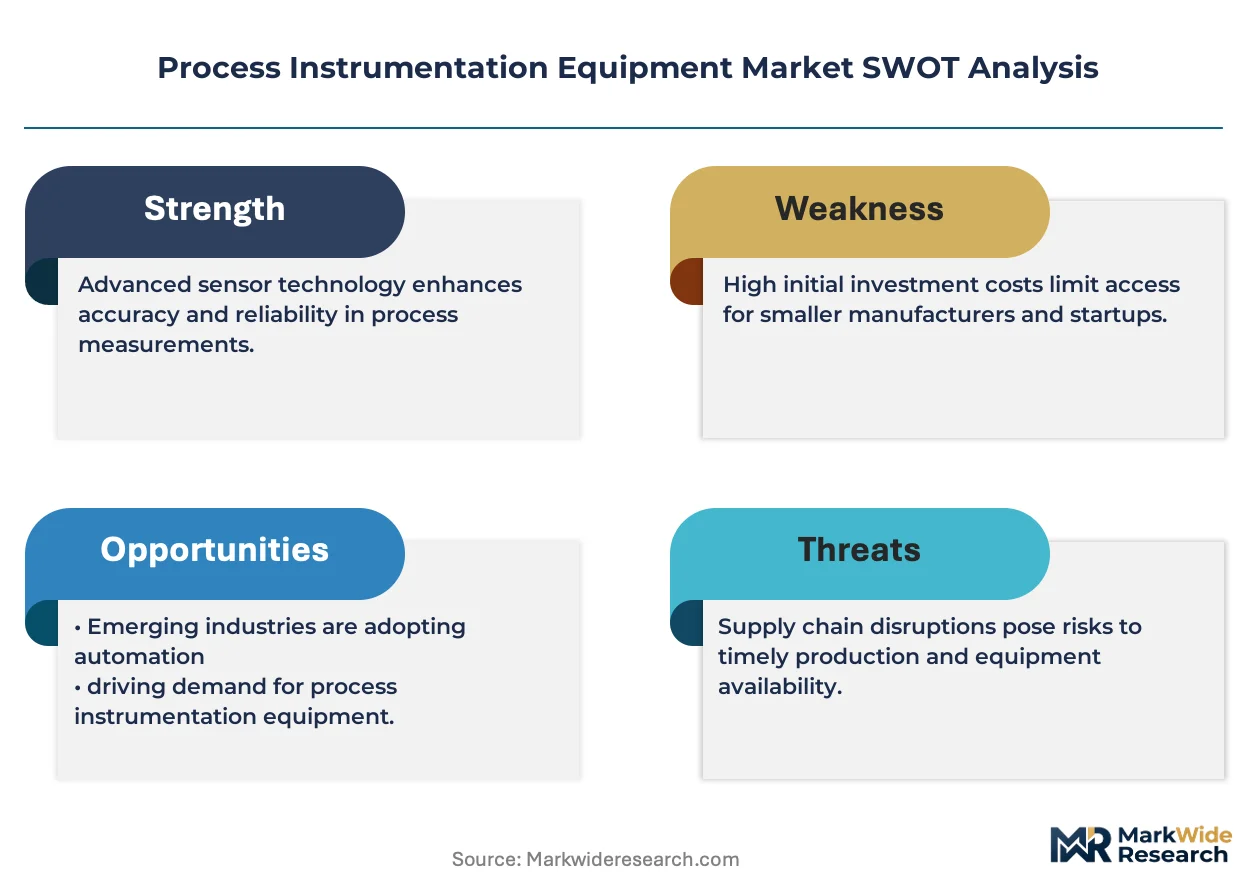
Pharmaceutical manufacturers are accelerating batch control modernization, forcing instrumentation vendors to pre-certify SIL-rated architectures before qualifying for capital projects. This certification bottleneck is reorganizing competitive tiers and compressing project timelines across the installed base.
Growth Catalysts
- EU F-Gas Regulation:Compliance deadlines are compelling replacement of legacy refrigerant-based instruments with compliant alternatives across European process facilities.
- Pharmaceutical manufacturing:FDA process analytical technology guidance drives demand for in-line spectroscopic and chromatographic instrumentation in active pharmaceutical ingredient production.
- Wireless retrofit economics:Brownfield sites in Germany's industrial automation corridor around Stuttgart and Mannheim are adopting wireless technologies where cabling costs prove prohibitive.
Market Restraints
- Semiconductor sensor supply:Concentrated fabrication capacity in East Asia creates input cost volatility and extended lead times for smart sensor components.
- IEC 61508 certification backlog:Third-party functional safety assessment queues extend 14-18 months, delaying project awards for non-certified vendors.
- Legacy 4-20 mA infrastructure:Existing analog signal architectures create technical friction against digital fieldbus migration in mature process plants.
Strategic Opportunities
- Predictive maintenance convergence:Embedded diagnostic sensors combined with edge analytics create white space in asset performance management services.
- India's pharmaceutical expansion:CDSCO quality mandates and PLI scheme incentives are concentrating greenfield API facility investment in Andhra Pradesh and Gujarat.
- Digital twin integration:Real-time instrumentation data feeds are enabling new performance-based service contracts with integrated hardware-software bundles.
Industry Challenges
- SIL-rated firmware engineering:Functional safety software development expertise scarcity constrains vendor capacity to execute multiple concurrent certification programs.
- Multi-protocol integration complexity:Fieldbus standard fragmentation across HART, Foundation Fieldbus, and PROFIBUS creates commissioning delays in brownfield retrofits.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Process Instrumentation Equipment Market |
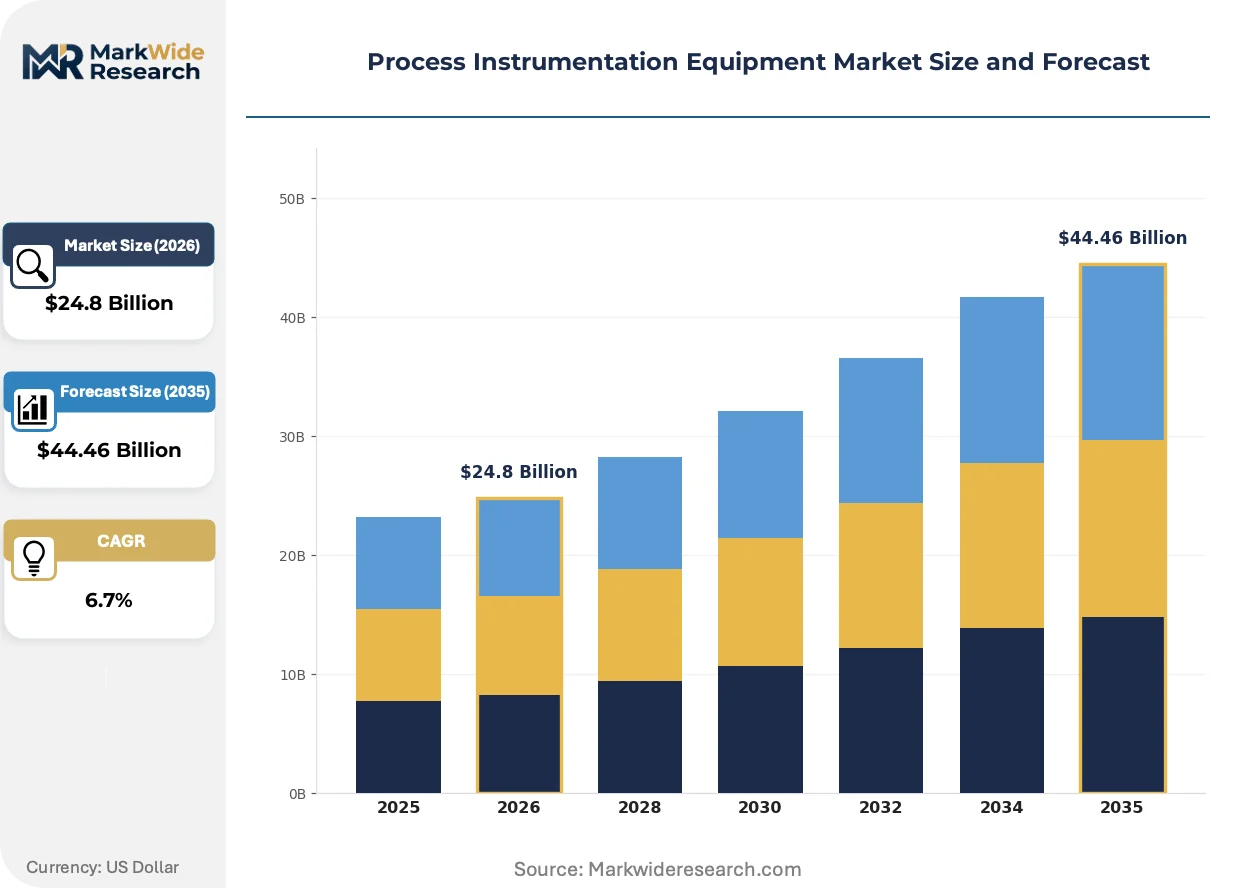
| Market Size in 2026 | $24.8 Billion |
| Market Size in 2035 | $44.46 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pressure Transmitters, Flow Meters, Temperature Sensors, Level Controllers Technology: Smart Sensors, Wireless Technologies, Analog Devices, Digital Devices Application: Manufacturing Processes, Chemical Processing, Energy Management, Water Treatment End User: Oil & Gas, Pharmaceuticals, Food & Beverage, Aerospace |
| Companies Covered | Schneider Electric, Emerson Electric Co., Siemens AG, Yokogawa Electric Corporation, Endress+Hauser Group, ABB Ltd., Rockwell Automation, KROHNE Messtechnik GmbH, Honeywell International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Process Instrumentation Equipment Market Strategic Shifts
Smart sensor architectures with embedded diagnostics are compressing maintenance cycles and enabling predictive strategies. Vendors are racing to integrate edge computing capabilities while navigating certification complexity.
Multi-variable transmitters are bifurcating the pressure and flow measurement segments. These devices combine temperature, pressure, and flow sensing in single housings. Pharmaceutical batch processors are adopting them aggressively to reduce instrument count and wiring density. The technology is bifurcating vendor portfolios into dedicated single-variable suppliers versus integrated platform providers.
EPA emissions monitoring mandates are forcing continuous analyzer upgrades in US petrochemical and refining operations. The regulations require real-time reporting of volatile organic compounds and hazardous air pollutants. Stack monitoring and fenceline detection systems face the steepest compliance ramps, with suppliers accelerating optical and mass spectrometry roadmaps to meet tightened detection thresholds.
Service unbundling is fragmenting traditional procurement relationships. End-users are separating hardware acquisition from calibration, maintenance, and certification services. Chemical processors in the US Gulf Coast are driving this most visibly, negotiating multi-vendor service contracts that break single-source dependencies and compress total cost of ownership through competitive tendering.
Process Instrumentation Equipment Market Segmentation
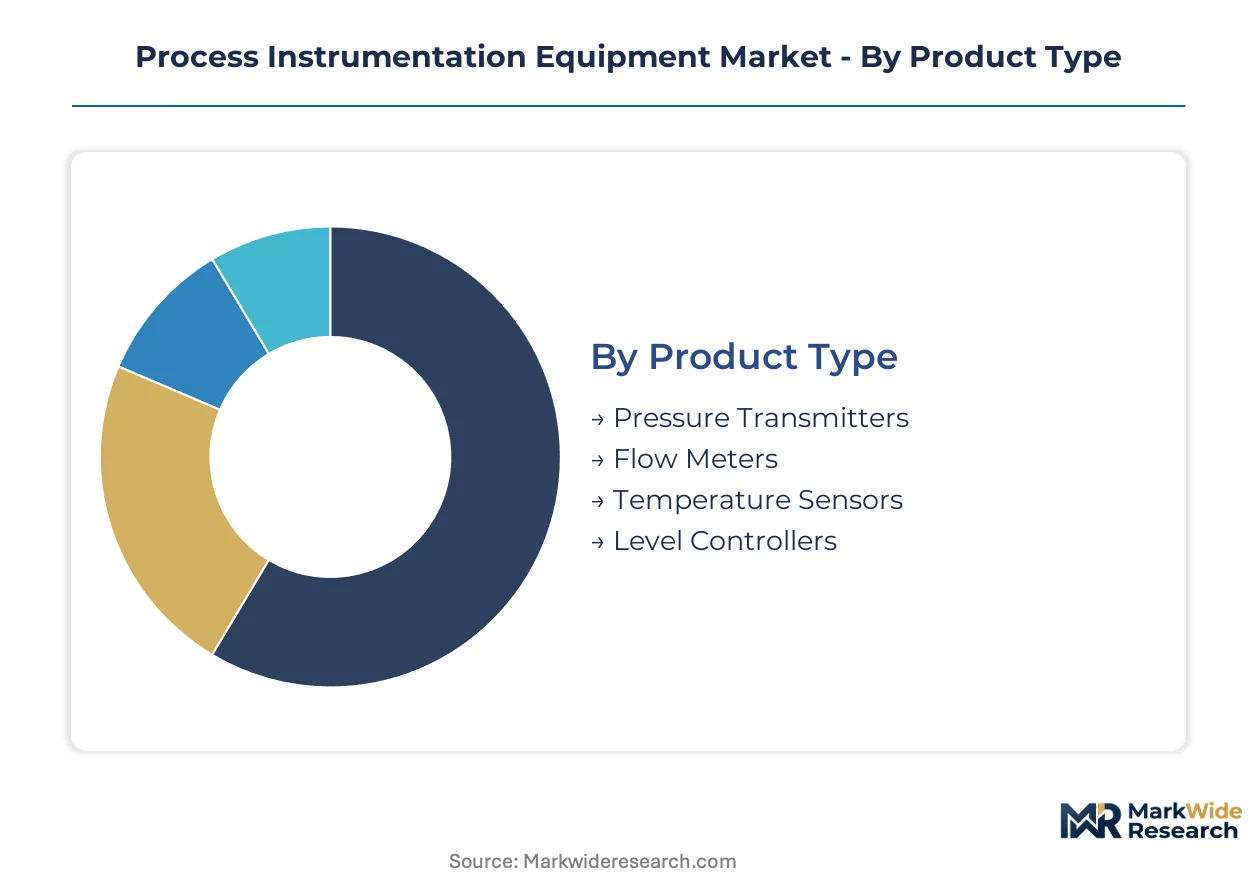
Process instrumentation equipment segments diverge sharply on certification requirements and signal architecture. Product type and technology choices cascade into application eligibility and end-user procurement specifications.
Product Type:
EPA emissions monitoring mandates and FDA process analytical technology guidance create divergent accuracy and response time requirements across instrument categories.
- Pressure Transmitters:Piezoelectric and capacitive sensing elements measure static and differential pressure with SIL-rated safety loops for emergency shutdown systems. Oil & gas facilities in the US Gulf Coast specify these for wellhead monitoring where IEC 61508 certification is mandatory for project qualification.
- Flow Meters:Coriolis, ultrasonic, and electromagnetic technologies handle multiphase and corrosive media measurement. Chemical processors in Germany's Stuttgart-Mannheim corridor deploy Coriolis meters for precision batch dosing under EU F-Gas Regulation compliance deadlines.
- Temperature Sensors:RTD and thermocouple elements with transmitter heads convert thermal signals for control loops.
- Level Controllers:Radar, guided wave, and capacitive technologies manage inventory and overflow protection.
Pressure transmitters handle the majority of throughput; flow meters are the fastest mover on share.
Technology:
Signal architecture choices determine retrofit economics and predictive maintenance capability in brownfield versus greenfield deployments.
- Smart Sensors:Embedded diagnostics and edge computing capabilities enable condition-based maintenance with HART or Foundation Fieldbus digital overlays. Pharmaceutical manufacturers prioritize these for FDA process analytical technology compliance in active pharmaceutical ingredient production.
- Wireless Technologies:ISA100.11a and WirelessHART protocols eliminate cabling infrastructure in legacy sites. Brownfield facilities in Germany adopt these where conduit replacement costs exceed instrument capital expense.
- Analog Devices:4-20 mA signal loops dominate mature plant infrastructure.
- Digital Devices:PROFIBUS and EtherNet/IP fieldbus integration supports digital twin architectures.
Smart sensors command the highest unit margins; wireless technologies are expanding most quickly in brownfield retrofit applications.
Application:
Process criticality and regulatory exposure shape instrumentation specification intensity across verticals.
- Manufacturing Processes:Discrete and batch automation for quality-critical production lines. Automotive and electronics assembly in Japan's industrial zones specify high-speed temperature and pressure loops for precision joining operations.
- Chemical Processing:Reactor monitoring and hazardous area classification drive explosion-proof housing and SIL-rated redundancy. US petrochemical facilities face EPA hazardous air pollutant monitoring mandates requiring continuous analyzer integration.
- Energy Management:Steam, compressed air, and fuel flow optimization for carbon accounting.
- Water Treatment:Chlorine, pH, and turbidity monitoring for municipal and industrial effluent compliance.
Chemical processing absorbs the largest absolute instrument count; energy management is climbing the fastest on decarbonization reporting requirements.
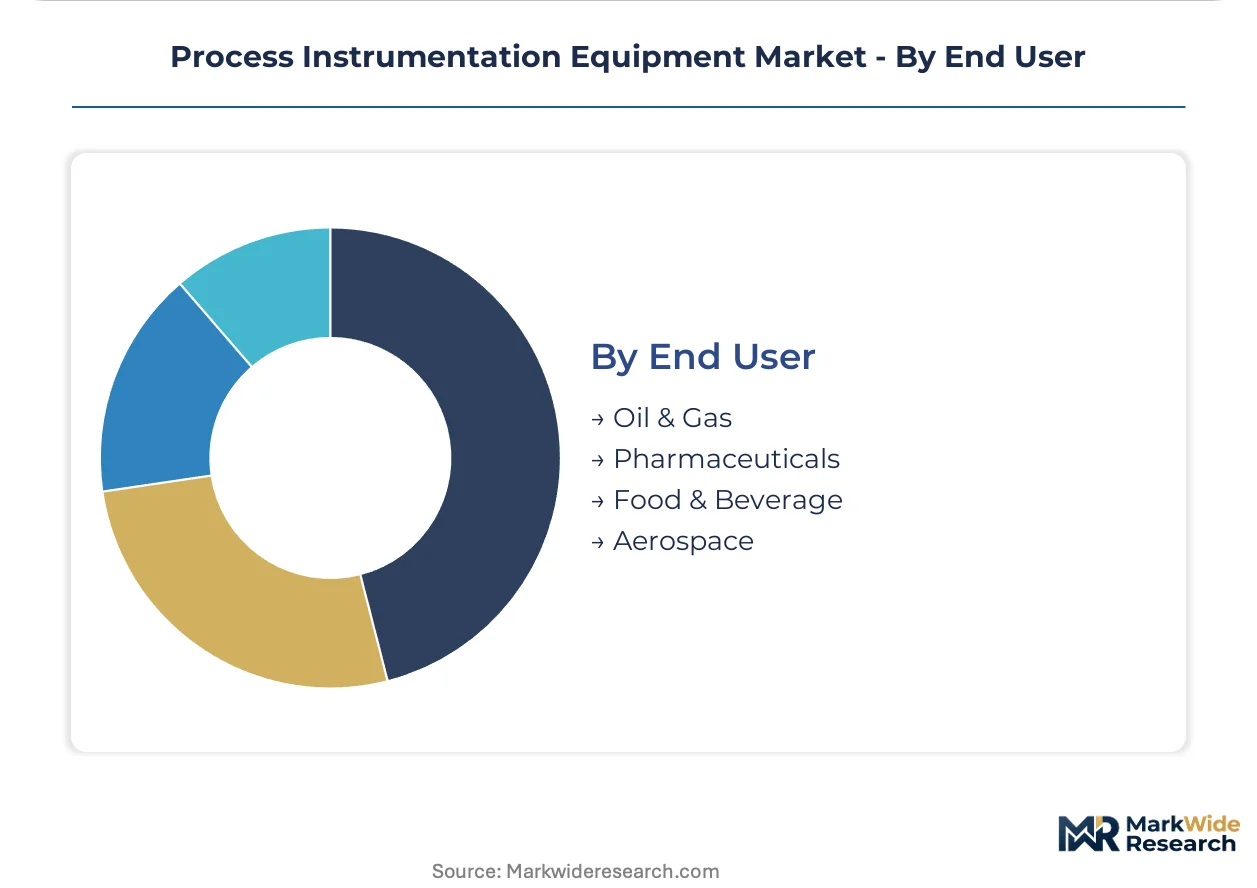
End User:
Capital intensity and regulatory scrutiny create tiered procurement specifications across buyer categories.
- Oil & Gas:Upstream, midstream, and downstream operations requiring SIL-rated safety instrumented systems and custody transfer accuracy. Exploration companies in the US Permian Basin specify redundant pressure and flow architectures for wellpad automation.
- Pharmaceuticals:Batch control and process analytical technology for active pharmaceutical ingredient synthesis. CDSCO quality mandates in India's Andhra Pradesh and Gujarat clusters drive spectroscopic and chromatographic instrumentation demand.
- Food & Beverage:CIP/SIP validation and hygienic design for dairy and beverage processing.
- Aerospace:Test stand and fuel system measurement for propulsion development.
Oil & gas maintains the largest installed base; pharmaceuticals is gaining share fastest on batch modernization cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rotterdam-Antwerp pipeline corridor anchors European demand for flow measurement instrumentation serving integrated refining and chemical complexes. This infrastructure asset underwrites the region's role in process instrumentation deployment.
United States
Permian Basin wellpad automation drives redundant pressure transmitter specifications for upstream safety instrumented systems. EPA hazardous air pollutant monitoring mandates force continuous analyzer upgrades across Texas and Louisiana petrochemical corridors. Houston-Gulf Coast processors unbundle hardware procurement from calibration services to compress total cost of ownership.
Germany
Stuttgart-Mannheim industrial automation corridor concentrates demand for Coriolis flow meters in precision chemical batch dosing applications. EU F-Gas Regulation compliance deadlines accelerate replacement of refrigerant-based instruments across Baden-Württemberg process facilities. Brownfield sites adopt WirelessHART protocols where conduit replacement costs exceed instrument capital expense.
India
Andhra Pradesh and Gujarat pharmaceutical clusters absorb spectroscopic and chromatographic instrumentation for active pharmaceutical ingredient synthesis. CDSCO quality mandates and PLI scheme incentives concentrate greenfield API facility investment in these states. Domestic batch control modernization creates demand for SIL-rated pressure and temperature transmitters.
China
Yangtze River Delta petrochemical integration projects specify smart sensors with embedded diagnostics for predictive maintenance. National dual carbon goals drive emissions monitoring instrumentation deployment across Shanghai-Ningbo refining complexes. Local suppliers compete with European and Japanese vendors on digital fieldbus integration capabilities.
Japan
Kanto region automotive and electronics assembly lines specify high-speed temperature and pressure loops for precision joining operations. METI industrial efficiency standards accelerate wireless retrofit adoption in mature manufacturing facilities. Yokohama-Chiba process industries demand multi-variable transmitters to reduce instrument count and wiring density.
Process Instrumentation Equipment Market Competitive Environment
Listed leaders compete with private specialists across functional safety certification and digital integration capabilities. The vendor base organizes into three tiers: diversified industrial conglomerates with full instrumentation portfolios, focused measurement specialists with deep vertical expertise, and regional system integrators with strong local service networks. Two competitive moves dominate: M&A activity targeting predictive maintenance software capabilities, and strategic partnerships between hardware vendors and cloud analytics platforms.
Within the diversified conglomerate tier, Emerson Electric Co., Siemens AG, and Yokogawa Electric Corporation exemplify contrasting geographic anchoring strategies. Emerson sustains R&D intensity across pressure and flow platforms from its US base. Siemens dominates digital twin integration from its German headquarters. Yokogawa anchors Asia-Pacific market presence through specialized control system compatibility from its Japanese origins.
| Leading Market Players |
|---|
| Schneider Electric |
| Emerson Electric Co. |
| Siemens AG |
| Yokogawa Electric Corporation |
| Endress+Hauser Group |
| ABB Ltd. |
| Rockwell Automation |
| KROHNE Messtechnik GmbH |
| Honeywell International |
| Others |
Value Chain & Pricing Dynamics
Fourteen-to-eighteen-month IEC 61508 certification queues compress vendor pricing power while concentrating supply leverage among pre-certified tier-one suppliers. This lead-time band forces project sponsors into sole-source negotiations with SIL-qualified vendors, amplifying margin capture for certified architectures while squeezing non-certified competitors into price-competitive commodity tiers.
Pricing Analysis
Volume-discount tiering structures stratify across premium SIL-certified, standard smart-sensor, and economy analog-device levels. Price differentiation hinges on IEC 61508 certification grade and embedded diagnostic capability, with pharmaceutical batch processors showing least price sensitivity for safety-rated architectures. Cost compression in the analog tier is intensifying because brownfield sites prioritize wireless retrofit economics over premium digital fieldbus migration. Chemical processors in Germany's Stuttgart-Mannheim corridor exhibit highest price sensitivity, unbundling hardware procurement from calibration services to compress total cost of ownership.
Supply Chain Analysis
Strategic stockpile preferences dominate sensor component procurement as semiconductor fabrication concentrates in Taiwan, South Korea, and China. Raw material dependencies center on MEMS sensing elements, specialized ceramic substrates, and high-purity refrigerant alternatives for EU F-Gas Regulation compliance. Single-source vulnerability in East Asian wafer fabrication creates input cost volatility and extended lead times for smart sensor components. Distribution runs through authorized regional integrators with IEC 61508 certification authority, bypassing direct OEM relationships for complex safety-instrumented system deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity concentrates in predictive maintenance service layers as pharmaceutical and chemical end-users unbundle hardware procurement from calibration and certification contracts. This demand-side shift creates niche entry points for specialized service providers between instrument vendors and facility operators.
For Market Incumbents: Consolidate certification capacity advantage by accelerating SIL-rated firmware engineering pipelines before third-party assessment queues lengthen further. Acquire predictive maintenance software capabilities to capture recurring revenue streams as hardware margins compress. Channel control through authorized integrator networks defends position against direct-sales challengers targeting unbundled service procurement.
For New Entrants and Emerging Players: Calibration-as-a-service gaps in India's Andhra Pradesh and Gujarat pharmaceutical clusters offer immediate white-space capture. Target brownfield wireless retrofit applications where cabling infrastructure replacement costs exceed instrument capital expense. Partner with regional system integrators holding IEC 61508 certification authority to bypass direct safety-architecture qualification barriers.
For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because functional safety software development expertise scarcity constrains vendor capacity to execute multiple concurrent certification programs. Acquisition target archetype: mid-cap measurement specialists with deep vertical expertise in pharmaceutical or chemical processing applications. Watch IEC 61508 certification backlog timelines as inflection indicator—compression below twelve months signals incumbent pricing power erosion.
| Strategic Initiative | Industry Significance |
|---|---|
| SIL Certification Acceleration | Pre-qualification for pharmaceutical capital projects before third-party queues extend further. |
| Predictive Maintenance Software Acquisition | Captures recurring revenue as hardware procurement unbundles from service contracts. |
| Wireless Protocol Specialization | Addresses brownfield retrofit economics in Germany's industrial automation corridor. |
| Regional Integrator Partnership | Bypasses direct certification barriers through authorized channel relationships. |
| Multi-Variable Transmitter Platform | Reduces instrument count for pharmaceutical batch processors pursuing wiring density compression. |
Study Parameters
Operator-level perspectives from plant engineers, maintenance directors, OEM procurement teams, and aftermarket service heads anchored the qualitative base. Primary interviews combined with secondary validation from SEC filings, customs and trade data, IEC certification registries, and pharmaceutical facility investment databases. Bottom-up instrument shipment modeling and top-down capital expenditure triangulation cross-verified market sizing across the projection horizon.
Sensitivity analysis tested forecast robustness across alternative regulatory compliance timelines and semiconductor supply scenarios. Segmentation dimensions modeled include product type, signal architecture, application criticality, and end-user regulatory exposure. CAGRs derived from weighted average of historical trajectory and forward-looking capital project pipelines, incorporating EPA emissions monitoring mandate schedules and EU F-Gas Regulation deadline clustering.
Underlying assumptions cover certification backlog persistence and East Asian semiconductor supply stability, with deviation risk concentrated in IEC 61508 assessment queue compression or trade policy disruption affecting sensor component flows. Revision becomes warranted when certification timelines compress below twelve months or wireless protocol standardization accelerates fieldbus migration economics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Latin America Travel Retail Market
Others
Global OTA Testing Market
Others
Linear Shaft Market
Others
Enterprise Video Market
Others
Safety Critical Software Testing Market
Others
North America Printed Signage Market
Others
Industrial Hooters Market
Others
Global Bio-Based Chemicals Market
Others
Latin America Fire Sprinklers Market
Others
Convenience Stores Market
Others
Profiling Floats Market
Others
Global Hardware As a Service (Haas) Market
Others
Global Phablets and Superphones Market
Others
Banknote Printing Machine Market
Others
Global Mica Market
Others
5G Smartphone Market