
 Bulgur Market | 2026-2036
Bulgur Market Size, Share, and Industry Trends Forecast 2026-2036
Bulgur Market Analysis
The capital-intensity divergence between artisan stone-grinding operations and industrial roller-milling facilities is unwinding traditional competitive boundaries in bulgur processing. Sunnylands Mills leverages its integrated durum wheat supply chain to sustain cost advantages across coarse and fine grades. Tipiak Group anchors its European position through specialized organic bulgur lines distributed through retail and foodservice channels. Bob's Red Mill Natural Foods competes on brand recognition in North American specialty stores with heritage processing methods.
Bulgur consists of parboiled, cracked durum wheat with moisture content typically below 14% and particle size classified by screening mesh from fine to coarse grades; the parboiling process gelatinizes starches, reducing subsequent cooking time to 10-20 minutes for commercial and household use. Fine bulgur dominates volume in Middle Eastern tabbouleh and kibbeh applications where quick hydration matters, while organic bulgur captures expanding margin pools in European and North American retail channels driven by EFSA-aligned clean-label preferences. Coarse bulgur sustains steady demand from institutional food manufacturers producing pilaf and stuffing bases for restaurants and catering services.
Turkey's Ministry of Agriculture and Forestry oversees national bulgur standards alongside BIS in India and FDA food safety requirements in the United States, creating a multi-jurisdictional compliance landscape for exporters. The EU's Farm to Fork Strategy and REACH-aligned packaging rules are reshaping import specifications for vacuum-sealed and bulk formats entering European supermarkets. Stakeholders must monitor evolving pesticide residue thresholds and sustainability certification demands as purchasing criteria across wholesale distributors and online retail platforms harden.
Market Dynamics
The Farm to Fork Strategy is compressing compliance timelines for bulgur exporters while Turkey's dominance in durum wheat sourcing concentrates processing capacity along the Aegean and Southeastern Anatolia corridors.
Growth Catalysts
- EFSA-aligned clean-label mandates:European retailers are expanding shelf space for organic bulgur varieties as the EU Green Deal tightens pesticide residue thresholds for grain imports.
- Foodservice institutionalization:Restaurant chains across the Mediterranean basin are standardizing tabbouleh and pilaf preparations, locking in coarse-grade bulgur procurement contracts.
- Parboiling automation:Steam-injection systems are reducing gelatinization energy costs by half, enabling smaller mills to achieve industrial-grade output consistency.
Market Restraints
- Durum wheat price volatility:Climate stress across the Black Sea breadbasket is amplifying input cost swings for processors dependent on Turkish and Russian grain origination.
- REACH packaging compliance:Vacuum-sealed export formats face extended ECHA registration timelines, delaying European supermarket listings by 8-14 months.
- Quinoa and freekeh substitution:Health-food retailers in North America are displacing fine bulgur with higher-protein ancient grains in prepared salad applications.
Strategic Opportunities
- Indian FSSAI organic certification:Mumbai and Bangalore retail channels remain underpenetrated for heritage wheat products, offering first-mover positioning before domestic millers scale.
- Ready-to-eat meal integration:Coarse bulgur is penetrating airline catering and military ration packs as a shelf-stable carbohydrate base requiring no refrigeration.
- Solar-drying technology convergence:Photovoltaic-powered parboiling facilities are opening off-grid processing nodes in Morocco and Jordan with zero Scope 2 emissions.
Industry Challenges
- Artisan stone-grinding skill scarcity:Master millers capable of calibrated cracking for kibbeh-grade fine bulgur are aging out of the workforce across Gaziantep and Şanlıurfa.
- Multi-jurisdictional audit fatigue:Exporters simultaneously pursuing BIS mark, FDA facility registration, and EFSA-approved supplier status face duplicative documentation burdens.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bulgur Market |
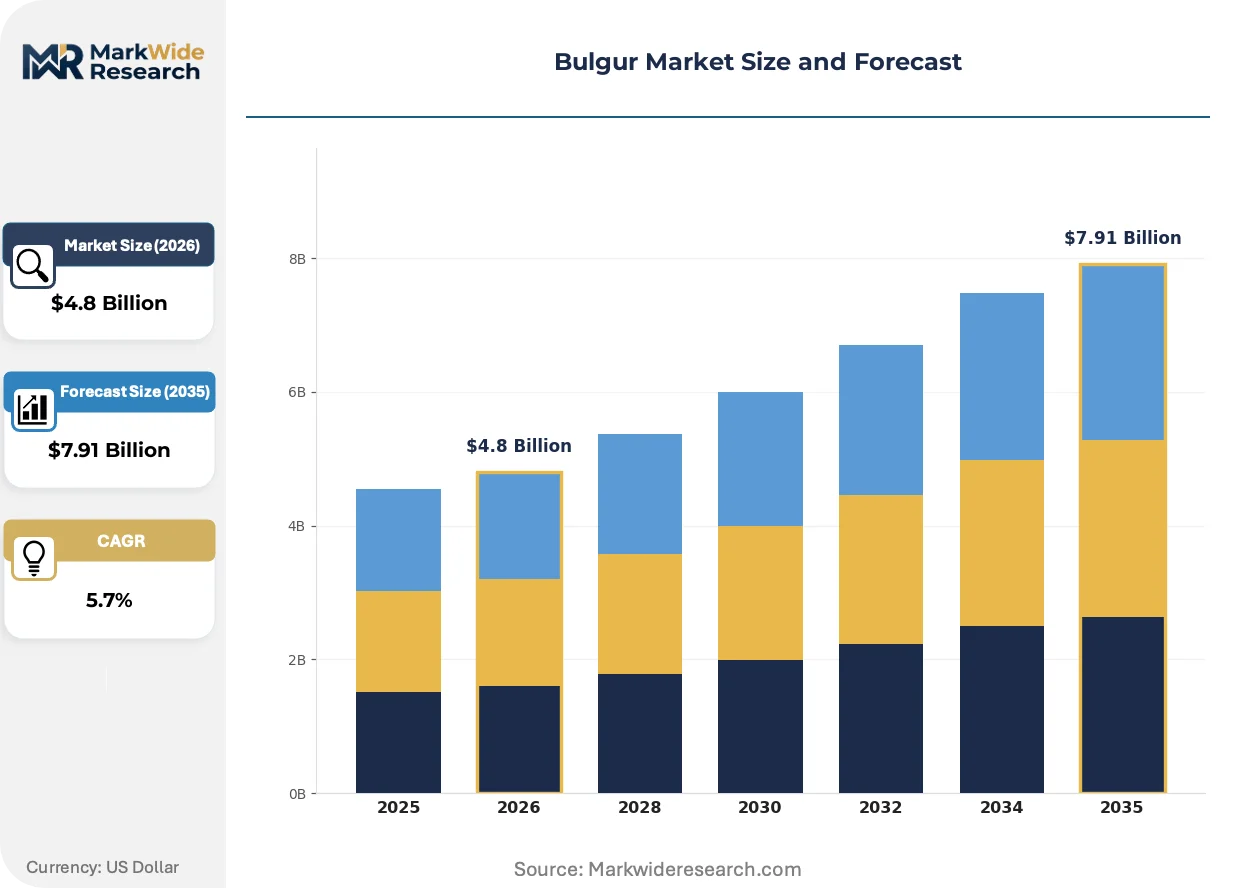
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fine Bulgur, Coarse Bulgur, Whole Bulgur, Organic Bulgur End User: Households, Restaurants, Food Manufacturers, Catering Services Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Wholesale Distributors Packaging Type: Bags, Boxes, Bulk Packaging, Vacuum Sealed |
| Companies Covered | Sunnylands Mills, Bulsan Bulgur, Arrowhead Mills, Inc., Tipiak Group, Mitsides Public Company Ltd., Bob’s Red Mill Natural Foods, Inc., Ipek Bulgur, Armada A.S., Celnat S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bulgur Market Emerging Trajectories
Processing technology is splitting the bulgur value chain into premium heritage segments and commodity efficiency tiers, while regulatory pressure and buyer behavior shifts reshape competitive positioning.
Near-infrared spectroscopy is bifurcating quality assurance protocols across the industry. Large-scale roller mills deploy real-time moisture and protein mapping to optimize parboiling parameters, while artisan producers reject automated sorting to preserve terroir marketing claims. Food manufacturers sourcing for private-label retail are demanding NIR-certified consistency, compressing margin for small-batch operators.
REACH-aligned packaging rules are forcing material transitions across European-bound supply chains. Composite films containing PFAS face phased prohibition, compelling Turkish exporters to validate cellulose-based barrier alternatives. Vacuum-sealed organic bulgur SKUs destined for German and French supermarkets bear the highest compliance burden, with reformulation costs concentrated in the 2024-2026 transition window.
Direct-to-restaurant procurement is displacing traditional wholesale distributor relationships in North American urban markets. Chef-owned Mediterranean concepts in Los Angeles, Toronto, and New York are sourcing coarse bulgur through importer-aggregator platforms that bypass broadline foodservice distributors. This channel compression is most visible in the fine-dining segment, where traceability documentation and small-batch provenance command 15-25% price premiums over commodity grades.
Bulgur Market Segmentation
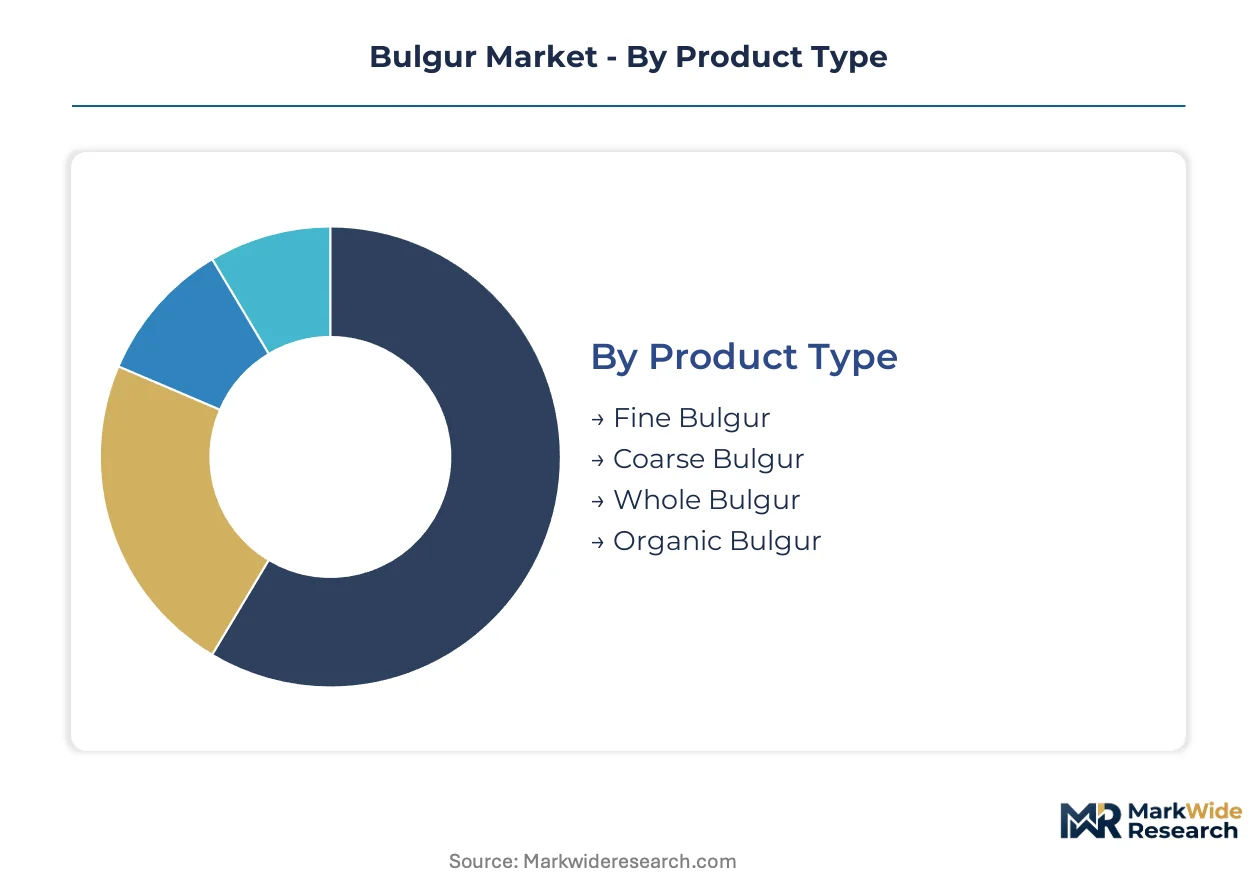
Bulgur's parboiling process and particle-size grading create distinct margin architectures across product tiers. End-use applications and channel configurations further stratify profitability, with organic certification and foodservice institutionalization commanding premium positioning.
Product Type:
Margin pools concentrate in certified organic lines and heritage-grade fine bulgur, where EFSA-aligned clean-label premiums offset higher processing costs.
- Fine Bulgur:Screened through fine mesh for rapid hydration in tabbouleh and kibbeh preparations. Lebanese and Syrian diaspora communities in Germany and France sustain specialized procurement through Mediterranean importers. Labor-intensive cracking calibrated for uniform particle size preserves artisan pricing power.
- Organic Bulgur:Cultivated without synthetic pesticides under EU organic regulation and USDA National Organic Program standards. German and French supermarkets allocate expanding shelf space as REACH-aligned packaging rules harden entry requirements. Certification costs concentrate margin among integrated Turkish millers with captive durum wheat supply.
- Coarse Bulgur:Larger cracked grains for pilaf and stuffing bases serving institutional food manufacturers.
- Whole Bulgur:Minimal processing retains bran layer for fiber-forward positioning in North American health-food channels.
Coarse bulgur holds installed capacity. Organic bulgur is rotating up the share rankings.
End User:
Volume concentration tilts toward food manufacturers, while pricing power clusters in restaurant chains standardizing Mediterranean menu formats.
- Food Manufacturers:Institutional buyers producing pilaf mixes, stuffing bases, and ready-to-eat grain bowls. Turkish processors along the Aegean corridor lock in annual contracts with European and Middle Eastern prepared-food suppliers. Parboiling automation enables consistent gelatinization at industrial scale.
- Restaurants:Chef-owned Mediterranean concepts in Los Angeles, Toronto, and New York source through importer-aggregator platforms bypassing broadline distributors. Traceability documentation and small-batch provenance command 15-25% price premiums over commodity grades.
- Households:Retail consumers purchasing vacuum-sealed and bulk formats through supermarkets and specialty stores.
- Catering Services:Event and airline meal providers requiring shelf-stable carbohydrate bases without refrigeration.
Food manufacturers dominate throughput volumes. Restaurants are climbing the fastest on value contribution.
Distribution Channel:
Channel economics favor direct procurement relationships that compress intermediary margins, particularly in urban North American markets.
- Online Retail:Amazon and specialized Mediterranean food platforms serve diaspora communities and health-conscious consumers seeking heritage-grade products. Subscription models for organic bulgur build recurring revenue streams with lower customer acquisition costs than brick-and-mortar.
- Supermarkets:Carrefour, REWE, and Whole Foods Market allocate expanding shelf space for organic and vacuum-sealed SKUs. REACH-aligned packaging transitions impose reformulation costs concentrated in the 2024-2026 window.
- Specialty Stores:Middle Eastern grocers in Berlin, Paris, and Dearborn maintain curated selections of fine bulgur for traditional preparations.
- Wholesale Distributors:Broadline foodservice distributors face displacement as chef-owned concepts adopt direct-import relationships.
Supermarkets anchor volume throughput. Online retail is gaining share fastest.
Packaging Type:
Regulatory pressure on materials and shelf-life extension drive investment in barrier technology and sustainable substrates.
- Vacuum Sealed:Multi-layer films excluding oxygen extend shelf life to 24 months for export logistics. ECHA registration timelines for REACH-compliant alternatives delay European supermarket listings by 8-14 months. Cellulose-based barrier validation concentrates R&D spending among Turkish exporters.
- Bulk Packaging:Food manufacturers and catering services purchase 10-25kg sacks reducing per-unit material costs. Port of Mersin and İzmir logistics clusters enable efficient container loading for Middle Eastern and European destinations.
- Bags:Standard retail formats for household consumption through supermarkets and specialty stores.
- Boxes:Premium positioning for gift sets and organic product lines in North American specialty channels.
Bulk packaging holds installed capacity. Vacuum sealed is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Turkish processors command pricing power in European coarse-grade contracts, while North American health-food channels extract premiums for heritage fine bulgur through direct-import relationships.
Turkey
Gaziantep and Şanlıurfa millers supply diaspora communities across Germany and France with kibbeh-calibrated fine grades. The Ministry of Agriculture and Forestry enforces national bulgur standards that align with BIS and FDA requirements for export certification. Aegean corridor processors near İzmir leverage port logistics to lock in annual contracts with Middle Eastern and European prepared-food manufacturers.
Germany
Lebanese and Syrian communities in Berlin and Frankfurt sustain specialized procurement through Mediterranean importers for tabbouleh applications. EFSA-aligned clean-label mandates under the EU Green Deal tighten pesticide residue thresholds for grain imports. REWE and Carrefour supermarkets allocate expanding shelf space for organic vacuum-sealed SKUs despite REACH packaging compliance delays.
United States
Chef-owned Mediterranean concepts in Los Angeles and New York source coarse bulgur through importer-aggregator platforms that bypass broadline distributors. FDA facility registration requirements create documentation burdens for Turkish exporters seeking retail placement. Heritage processing methods in Pacific Northwest specialty stores command 15-25% price premiums over commodity grades.
France
Tipiak Group anchors European market presence through specialized organic lines distributed via retail and foodservice channels. ECHA registration timelines for REACH-compliant packaging alternatives delay supermarket listings by 8-14 months. Paris-based Mediterranean grocers maintain curated fine bulgur selections for traditional preparations.
India
Mumbai and Bangalore retail channels remain underpenetrated for heritage wheat products despite expanding health-conscious consumer bases. FSSAI organic certification requirements create first-mover positioning opportunities before domestic millers scale production. BIS standards for grain-based foods add compliance complexity for Turkish exporters targeting premium urban markets.
Bulgur Market Vendor Landscape
Concentration sits with integrated Turkish millers controlling captive durum wheat supply and Aegean logistics infrastructure. The vendor base stratifies across three tiers: heritage stone-grinding artisans preserving calibrated cracking expertise, industrial roller-mill operators achieving parboiling automation at scale, and regional packagers serving diaspora grocery channels. Dominant competitive moves include backward integration into durum wheat origination and geographic expansion through importer-aggregator platforms bypassing traditional wholesale distributors.
Among Turkish-integrated processors, Sunnylands Mills exemplifies the supply-chain-anchored archetype through its Aegean corridor concentration, while Bulsan Bulgur and Ipek Bulgur represent Gaziantep-Şanlıurfa heritage specialists competing on calibrated particle-size consistency for kibbeh applications. On the North American specialty vector, Bob's Red Mill Natural Foods occupies a position defined by brand recognition in heritage processing methods, with Tipiak Group anchoring European organic distribution through retail and foodservice channel penetration.
| Leading Market Players |
|---|
| Sunnylands Mills |
| Bulsan Bulgur |
| Arrowhead Mills, Inc. |
| Tipiak Group |
| Mitsides Public Company Ltd. |
| Bob's Red Mill Natural Foods, Inc. |
| Ipek Bulgur |
| Armada A.S. |
| Celnat S.A. |
| Others |
Supply Flow & Price Mechanics
Long-term offtake contracts between Turkish Aegean processors and European prepared-food manufacturers lock in durum wheat supply access while anchoring price visibility across coarse-grade bulgur volumes. These arrangements insulate institutional buyers from Black Sea grain volatility while compressing spot-market participation for smaller mills.
Pricing Analysis
The customization-premium spread in bulgur separates artisan-calibrated fine grades from commodity roller-milled output. Three-tier pricing structure across heritage, certified-organic, and standard industrial levels captures EFSA-aligned clean-label premiums and kibbeh-grade particle consistency. Pricing pressure stems from quinoa and freekeh displacement in North American health-food retail, eroding fine bulgur's positioning. Food manufacturers exhibit highest price sensitivity due to volume procurement and substitutable carbohydrate alternatives, while chef-owned Mediterranean concepts absorb premiums for traceability documentation.
Supply Chain Analysis
Just-in-time inventory strategies dominate European foodservice procurement, while strategic stockpiling persists among Middle Eastern distributors buffering against Turkish seasonal processing cycles. Supply concentrates in Turkey, with secondary nodes in India and France for organic certification and regional blending. Durum wheat, parboiling energy, and REACH-compliant packaging films constitute critical input dependencies. Single-source vulnerability runs through Gaziantep-Şanlıurfa heritage milling corridors where master miller scarcity threatens calibrated cracking capacity. Distribution runs through importer-aggregator platforms displacing broadline foodservice distributors in North American urban markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Bulgur incumbents face a substitution defense against quinoa and freekeh encroachment in health-food channels, requiring positioning that emphasizes parboiling convenience and Mediterranean culinary authenticity.
For Market Incumbents: Shield heritage-grade positioning by securing captive durum wheat supply through backward integration into Aegean and Southeastern Anatolia origination. Anchor EFSA-aligned organic certification to defend margin pools in German and French supermarkets against private-label commoditization. Lock in chef-owned restaurant relationships through importer-aggregator platforms that bypass distributor margin extraction.
For New Entrants and Emerging Players: Differentiate on FSSAI organic certification to capture first-mover positioning in Mumbai and Bangalore retail channels before domestic Indian millers scale heritage wheat production. Target solar-drying technology integration in Morocco and Jordan for zero-Scope 2 emission claims that resonate with EU Green Deal procurement criteria. Deploy direct-to-restaurant aggregation platforms in Toronto and Los Angeles to compress intermediary layers.
For Investors and Strategic Acquirers: Capital is best deployed toward integrated Turkish millers with captive durum supply and Aegean logistics infrastructure that sustain cost advantages across export grades. Long-term viability hinges on parboiling automation scalability and REACH-compliant packaging transition completion. Monitor ECHA registration timeline compression for cellulose-based barrier alternatives as inflection signal for European supermarket listing acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Durum Wheat Origination | Captive supply from Aegean and Southeastern Anatolia corridors locks in input cost stability against Black Sea volatility. |
| EFSA-Aligned Organic Certification Investment | Clean-label positioning secures shelf space expansion in REWE and Carrefour despite REACH packaging compliance burdens. |
| Parboiling Automation Scale-Up | Steam-injection systems reduce gelatinization energy costs while achieving industrial-grade consistency for food manufacturer contracts. |
| Direct-to-Restaurant Platform Development | Importer-aggregator relationships bypass broadline distributors and capture 15-25% traceability premiums in urban North America. |
| Solar-Drying Technology Deployment | Photovoltaic-powered facilities in Morocco and Jordan enable zero-Scope 2 emission claims aligned with EU Green Deal procurement. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with Turkish mill operators, European retail category buyers, and Mediterranean restaurant chefs; and secondary validation through customs trade records, EFSA pesticide residue databases, and BIS grain standards documentation. Bottom-up triangulation across processing capacity estimates and top-down demand segmentation ensured cross-verified outputs.
Across the projection horizon, the analytical framework modeled volume and value trajectories by product grade tier, end-use application, distribution channel configuration, and regional regulatory cluster. CAGRs were derived from segmented growth rate assumptions applied to baseline consumption estimates. Forecast inputs incorporated durum wheat price volatility indices and ECHA packaging compliance timeline scenarios.
Material uncertainties — durum wheat supply shocks from Black Sea climate stress, REACH alternative-material validation delays, and quinoa substitution acceleration — sit outside the modeled envelope. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Middle East and Africa Cocoa Products Market
Others
Global Multi-Access Edge Computing Market
Others
AC Switchgear Market
Others
Australia Content Services Platform Market
Others
Handheld Mobile Computers Market
Others
Transportation Lighting Market
Others
Asia-Pacific Battery E-Commerce Market
Others
Digital Supply Chain Market
Others
Spain Smart Home Market
Others
India Smart Home Market
Others
Printed Leather Market
Others
Griffin Beaker Market
Others
Residential Electrical Conduit Market
Others
3D Printing Construction Market
Others
Smart Home Gateways Market
Others
Egg and Egg Products Market