
 3D Printing Construction Market | 2026-2036
3D Printing Construction Market Size, Share, and Industry Trends Forecast 2026-2036
3D Printing Construction Market Intelligence
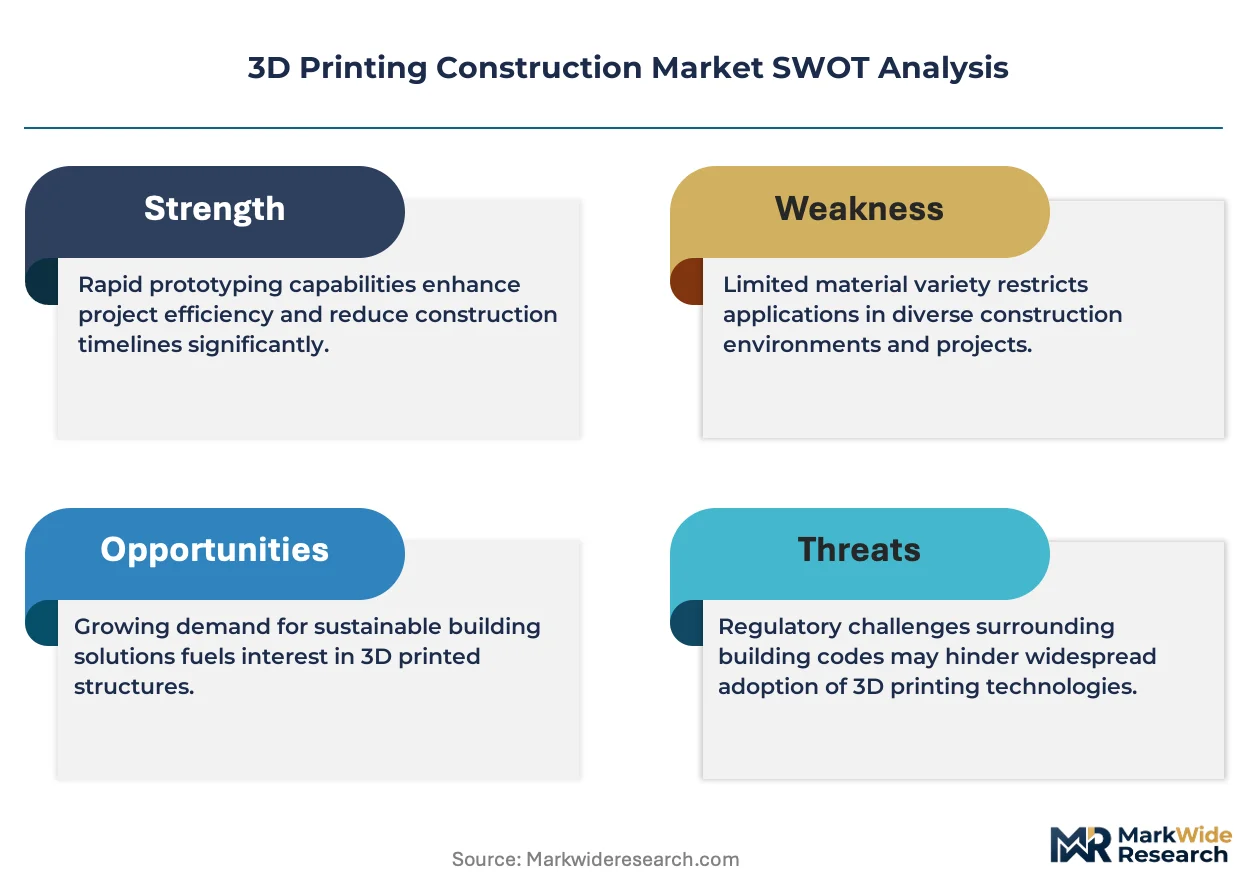
Extrusion-based concrete printing is fragmenting traditional construction workflows by decoupling formwork from structural deposition, enabling continuous wall fabrication without conventional molds. COBOD International A/S anchors European market penetration through its BOD2 gantry systems deployed across multiple continents. ICON Technology Inc. competes in the Americas with proprietary Lavacrete formulations optimized for seismic and thermal performance. Mighty Buildings differentiates through factory-based panel printing that bypasses on-site weather dependencies entirely.
3D printing construction deploys layer-by-layer additive manufacturing to fabricate building elements directly from digital models, typically using cementitious mixtures with particle sizes below 2.5mm and print speeds of 100-600mm per second for structural integrity. The technology serves commercial and residential sectors by compressing project timelines from months to days while reducing material waste through precise deposition control. Concrete dominates product type demand due to its thermal mass properties and compatibility with existing building codes, though composite segments are gaining traction for high-strength architectural features. Extrusion technology leads operational deployment for vertical structures, while powder bed fusion occupies specialized niches in metal connector fabrication where geometric complexity exceeds conventional casting limits.
US-based projects navigate OSHA fall-protection mandates alongside local ICC evaluation service reports for novel structural systems, creating dual compliance burdens that slow first-mover adoption. The EU Green Deal's embodied carbon thresholds intersect with REACH chemical restrictions on printable resin formulations, reshaping material R&D priorities for construction firms operating across European jurisdictions. Dubai's MEE-enforced building sustainability regulations and the UAE's mandatory 3D printing targets for government-backed housing are compressing procurement timelines for certified equipment suppliers. Stakeholders must monitor how fragmented national building codes converge or diverge on performance-based standards for additively manufactured structural elements.
Market Dynamics
Extrusion-based concrete printing is collapsing traditional formwork economics by eliminating mold fabrication cycles, compressing residential wall assembly timelines from weeks to single-day continuous pours while forcing recalibration of contractor labor models and equipment financing structures.
Growth Catalysts
- UAE Mandate Architecture:Dubai's 3D Printing Strategy mandates printed components in 25% of new buildings, creating guaranteed offtake for certified equipment suppliers and material formulators.
- German Code Modernization:MDR-aligned building codes for additive manufacturing are accelerating certification pathways for structural concrete elements, reducing time-to-market for novel systems.
- Seismic-Optimized Formulations:Proprietary cementitious mixtures with enhanced thermal and earthquake resistance are unlocking adoption in high-risk zones previously closed to printed construction.
Market Restraints
- Portland Cement Price Volatility:Input cost swings for the primary binder in printable concrete mixtures compress margin visibility for project developers and equipment lessors.
- Equipment Supplier Concentration:Gantry system production concentrates among a handful of European and North American manufacturers, creating delivery bottlenecks during demand surges.
- OSHA Fall-Protection Overlap:US contractors face dual compliance burdens from federal safety mandates and local ICC evaluation requirements for novel structural systems.
Strategic Opportunities
- Affordable Housing Vertical:US residential developers are scaling printed wall assemblies for cost-constrained projects, creating volume anchors for equipment amortization.
- Factory-Based Panel Printing:Climate-controlled manufacturing bypasses on-site weather dependencies entirely, opening year-round production windows in seasonal markets.
- EU Green Deal Intersection:Embodied carbon thresholds are redirecting R&D toward low-carbon printable mixtures that qualify for green procurement preferences.
Industry Challenges
- Digital Fabrication Skill Gap:Construction labor pools lack proficiency in CAD-to-print workflow management and real-time deposition monitoring, slowing crew scaling.
- Multi-Jurisdictional Certification Timelines:Structural engineers must secure parallel approvals from divergent national building codes, extending project front-end durations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 3D Printing Construction Market |
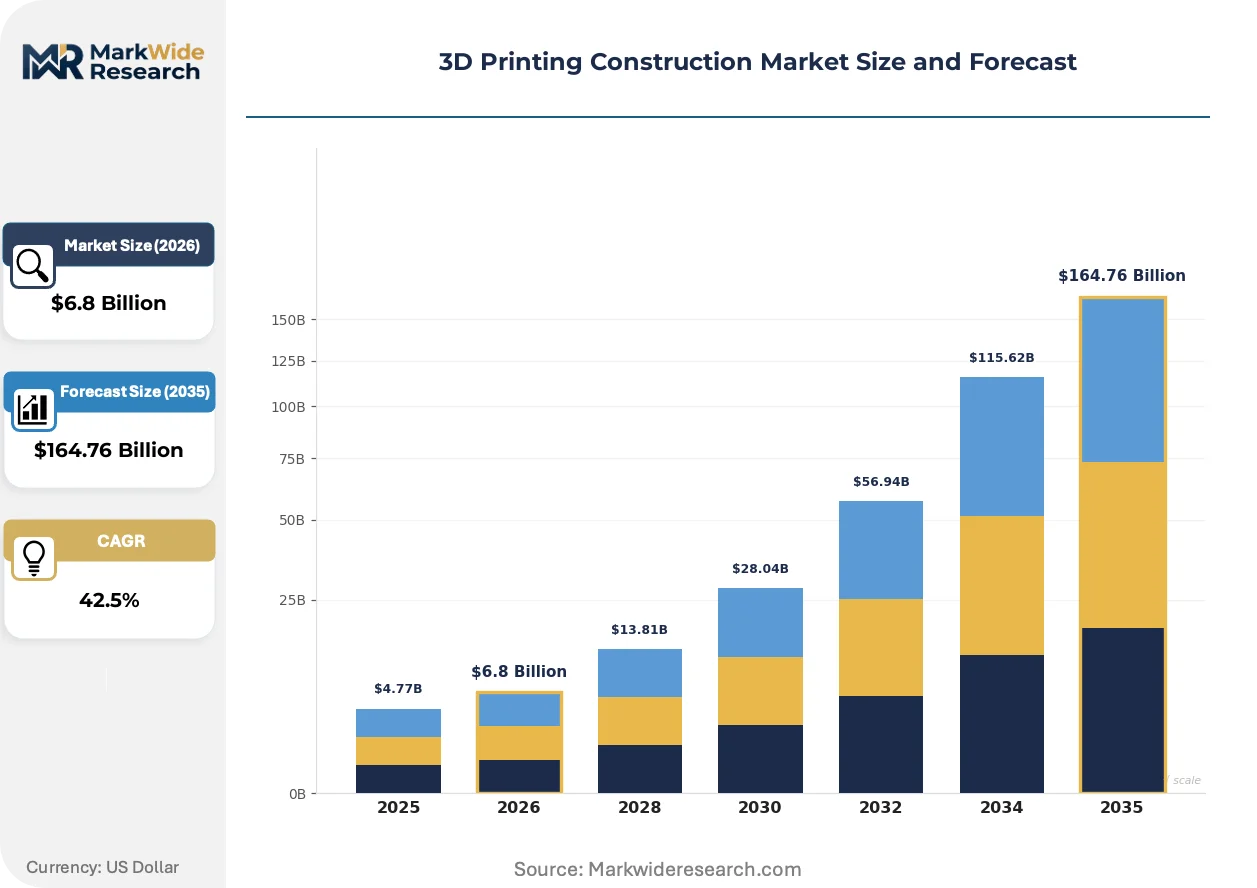
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $164.76 Billion |
| CAGR (2026 – 2036) | 42.5% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
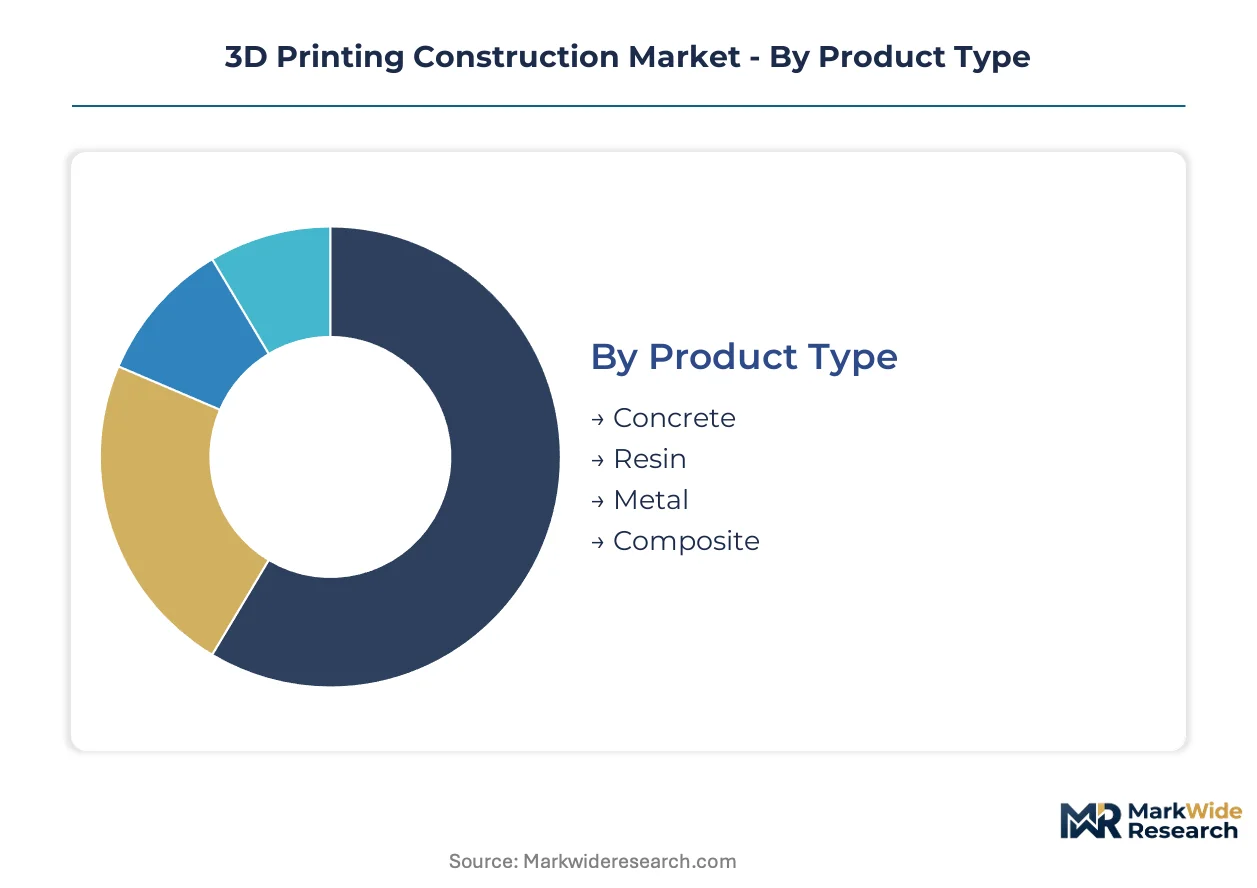
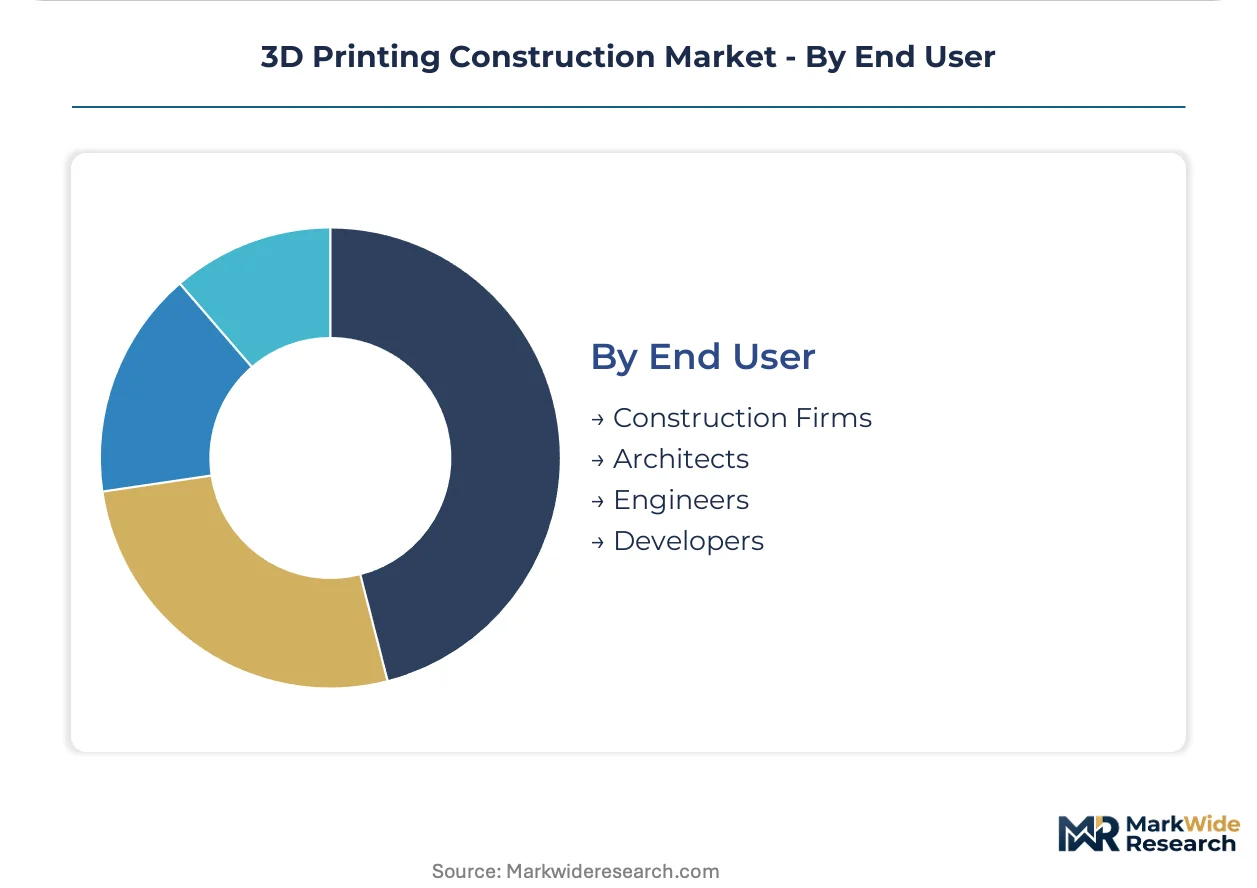
| Segmentation | Product Type: Concrete, Resin, Metal, Composite Application: Residential Structures, Commercial Buildings, Infrastructure, Custom Fabrication Technology: Extrusion, Binder Jetting, Material Jetting, Powder Bed Fusion End User: Construction Firms, Architects, Engineers, Developers |
| Companies Covered | Apis Cor, COBOD International A/S, ICON Technology Inc., Yingchuang Building Technique (Winsun), CyBe Construction, Contour Crafting Corporation, Branch Technology, XtreeE, Mighty Buildings, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
3D Printing Construction Market Strategic Shifts & Innovations
Digital fabrication workflows are actively compressing the boundary between architectural design and physical construction, eliminating intermediary drafting stages while forcing parallel evolution of material science and robotic control systems.
Multi-axis robotic arms with real-time slump monitoring are collapsing the distinction between planar wall printing and complex geometric facade elements. High-end architectural practices in the UAE and Nordic markets are adopting these systems for non-standard residential and cultural building envelopes. The technology is collapsing traditional trade boundaries by merging structural concrete placement with finished surface quality in a single deposition pass.
Germany's updated MDR-aligned building codes for additive manufacturing are establishing performance-based certification templates that other European regulators are referencing. The industrial consequence is accelerated type-approval for structural printed elements, compressing time-to-permit from years to months. French and Dutch building authorities are adapting these frameworks for their own code revisions, creating regulatory harmonization momentum across Continental construction markets.
Design-build contractors are consolidating procurement authority by bringing printing equipment in-house rather than subcontracting to specialized firms. This channel compression displaces traditional equipment-leasing intermediaries and forces manufacturers to develop direct service and training capabilities. The shift is most visible in US affordable housing developments where developers prioritize capital control over operational flexibility.
3D Printing Construction Market Segmentation
Segmentation in 3D printing construction reveals how material constraints, structural requirements, and stakeholder workflows fragment procurement patterns. Understanding these divides exposes where equipment financing concentrates and which certification pathways create bottlenecks for technology adoption.
Product Type:
Cementitious mixtures turn over fastest in project pipelines due to code familiarity, while resin and metal formulations linger in extended testing cycles before structural approval.
- Concrete:Cementitious mixtures with particle sizes below 2.5mm dominate structural deposition for thermal mass and seismic performance. US affordable housing developers and UAE government contractors anchor demand here, though Portland cement price volatility compresses margin visibility for project financiers.
- Resin:Photopolymer formulations enable high-resolution architectural features and non-load-bearing facade elements. REACH chemical restrictions across European jurisdictions are redirecting R&D toward bio-based alternatives that satisfy EU Green Deal embodied carbon thresholds.
- Metal:Powder-based deposition fabricates structural connectors and reinforcement elements exceeding conventional casting geometric limits.
- Composite:Hybrid fiber-reinforced mixtures combine polymer matrices with mineral aggregates for high-strength architectural applications.
Concrete anchors the volume base while composite formulations gain share at the steepest rate as architects specify complex geometries.
Application:
Cost tier stratification separates high-volume standardized housing from premium custom fabrication, with infrastructure occupying a mid-tier procurement band characterized by extended public tender cycles.
- Residential Structures:Printed wall assemblies compress single-family and multi-family construction timelines from months to days. German MDR-aligned building codes and Dubai's 25% printed component mandate are accelerating certification pathways for structural elements in these markets.
- Commercial Buildings:Office and retail envelopes leverage continuous deposition for complex facade geometries without traditional formwork. OSHA fall-protection mandates in the US create dual compliance burdens alongside ICC evaluation requirements that slow first-mover adoption.
- Infrastructure:Bridges, culverts, and utility structures demand performance-based durability standards extending procurement front-ends.
- Custom Fabrication:Bespoke architectural elements and cultural building components command premium pricing for geometric complexity.
Residential structures anchor the volume base while custom fabrication climbs the fastest as high-end architectural practices adopt multi-axis robotic systems.
Technology:
Volume concentration in extrusion systems reflects their compatibility with vertical construction workflows, while powder-based methods serve specialized niches where geometric complexity justifies slower deposition rates.
- Extrusion:Gantry and robotic arm systems deposit viscous cementitious mixtures at 100-600mm per second for structural wall fabrication. COBOD International A/S and ICON Technology Inc. equipment deployments span multiple continents, though supplier concentration creates delivery bottlenecks during demand surges.
- Binder Jetting:Liquid binding agents fuse powder layers for sand-based molds and architectural prototypes.
- Material Jetting:Photopolymer droplet deposition achieves surface finishes suitable for detailed facade elements.
- Powder Bed Fusion:Laser and electron beam systems sinter metal powders for structural connectors exceeding conventional casting limits.
Extrusion anchors the volume base while powder bed fusion expands most quickly in metal connector fabrication for seismic-resistant structural systems.
End User:
Customer type determines procurement authority concentration, with construction firms consolidating equipment in-house while architects and engineers remain specification influencers without direct capital deployment.
- Construction Firms:General contractors and specialty trades bring printing equipment in-house to compress project timelines and control capital deployment. US affordable housing developers prioritize this channel compression over operational flexibility, displacing traditional equipment-leasing intermediaries.
- Architects:Design practices specify printed elements and facade geometries, influencing material selection without direct procurement authority.
- Engineers:Structural engineers navigate multi-jurisdictional certification timelines for parallel approvals from divergent national building codes.
- Developers:Real estate development entities finance equipment amortization through volume commitments in large-scale residential portfolios.
Construction firms anchor the volume base while developers are gaining share fastest as design-build integration consolidates procurement authority.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German equipment manufacturers export gantry systems to contractors in the United States and the United Arab Emirates, establishing a trade corridor that channels European engineering expertise into high-growth construction automation markets.
United States
Affordable housing developers in Texas and California are scaling printed wall assemblies to compress project timelines. OSHA fall-protection mandates intersect with ICC evaluation requirements for novel structural systems, creating dual compliance burdens that slow first-mover adoption. Austin and Los Angeles anchor demand clusters where design-build contractors consolidate printing equipment in-house.
Germany
MDR-aligned building codes for additive manufacturing are accelerating certification pathways for structural concrete elements. The EU Green Deal's embodied carbon thresholds intersect with REACH chemical restrictions, redirecting material R&D priorities for construction firms. Bavaria and North Rhine-Westphalia concentrate equipment manufacturing and regulatory expertise.
United Arab Emirates
Dubai's 3D Printing Strategy mandates printed components in 25% of new buildings, creating guaranteed offtake for certified equipment suppliers. MEE-enforced building sustainability regulations compress procurement timelines for government-backed housing projects. Dubai and Abu Dhabi anchor the Gulf's most concentrated deployment of extrusion-based construction systems.
China
Prefabrication specialists in Jiangsu and Zhejiang provinces are integrating gantry printing into modular construction workflows. GB standards for additive manufacturing in construction are evolving to accommodate cementitious deposition at scale. The Yangtze River Delta concentrates both equipment fabrication capacity and demonstration projects for multi-story printed structures.
Netherlands
Architectural practices in the Randstad region are adopting multi-axis robotic systems for complex facade geometries in cultural and commercial envelopes. ECHA chemical regulations shape printable resin formulation choices for non-structural elements. Eindhoven anchors a cluster where design studios collaborate with technical universities on performance-based building code advocacy.
3D Printing Construction Market Key Industry Players
Channel-controlling players compete with product-specialist players for procurement authority in project pipelines. The vendor base stratifies into three tiers: equipment manufacturers supplying gantry and robotic systems, material formulators developing proprietary cementitious mixtures, and design-build contractors integrating both capabilities in-house. Consolidation pressures concentrate among equipment suppliers where delivery bottlenecks emerge during demand surges. Competitive moves center on geographic expansion into mandate-driven markets and backward integration into material supply chains.
Among Danish and American equipment specialists, COBOD International A/S and ICON Technology Inc. occupy positions representing the gantry-system and proprietary-formulation archetypes respectively. California-based Mighty Buildings exemplifies the factory-based panel printing model that bypasses on-site weather dependencies. These three entities anchor distinct strategic vectors within a competitive set where technology licensing and direct equipment sales compete for channel dominance.
| Leading Market Players |
|---|
| Apis Cor |
| COBOD International A/S |
| ICON Technology Inc. |
| Yingchuang Building Technique (Winsun) |
| CyBe Construction |
| Contour Crafting Corporation |
| Branch Technology |
| XtreeE |
| Mighty Buildings |
| Others |
Cost & Logistics Intelligence
Gantry system undercapacity in European manufacturing hubs is compressing delivery timelines for UAE and US contractors while simultaneously hardening equipment pricing power for incumbent suppliers navigating surge demand cycles.
Pricing Analysis
Second-generation gantry systems command a 40-60% premium over first-generation BOD-class equipment, while next-generation multi-axis robotic platforms remain pre-commercial with beta-access pricing negotiated through exclusive development partnerships. Three-tier pricing structure across premium certified, standard compliant, and economy non-certified equipment levels dominates procurement patterns. Pricing pressure stems from Portland cement input volatility squeezing margin visibility for project developers financing large-scale affordable housing portfolios. Volume-scaled developers with multi-unit commitments extract the steepest discounts, while single-project contractors face the highest per-unit equipment lease rates.
Supply Chain Analysis
Tariff exposure between Germany and the United Arab Emirates dominates procurement risk profiles for Middle Eastern contractors sourcing MDR-certified gantry systems. Equipment fabrication concentrates in Denmark, Germany, and the United States, while specialty nozzle assemblies and robotic control modules draw from Japanese and South Korean precision manufacturing. Single-source vulnerability around proprietary Lavacrete-type cementitious formulations creates dependency lock-in for seismic-optimized project specifications. Distribution runs through direct manufacturer-to-contractor channels with displaced equipment-leasing intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Dubai's 25% printed component mandate represents a regulatory inflection compressing technology adoption curves from decades to single-digit years, establishing high-growth disruption mechanics across construction automation.
For Market Incumbents: Insulate equipment financing margins by developing captive material supply chains for cementitious formulations, reducing exposure to Portland cement price volatility. Accelerate MDR-aligned certification investments to maintain regulatory moats against emerging gantry manufacturers from China. Channel control through direct service capabilities displaces traditional leasing intermediaries threatened by design-build integration. For New Entrants and Emerging Players: Mid-market commercial buildings in Southeast Asia represent the most penetrable entry point, with Singapore and Thailand lacking mandate-driven procurement timelines that concentrate incumbent attention elsewhere. Factory-based panel printing for seasonal climate markets offers white-space differentiation from on-site weather-dependent competitors. Go-to-market positioning should emphasize year-round production guarantees through climate-controlled manufacturing partnerships. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across factory-based panel printing as equipment amortization spreads across higher-volume production runs. Five-to-ten year viability favors acquisition targets with integrated material formulation capabilities rather than pure-play equipment manufacturers. Signal to monitor: German MDR code adoption velocity across French and Dutch regulatory authorities as harmonization indicator for addressable market expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Material Supply | Captive cementitious formulation production insulates margins from Portland price volatility affecting project financiers. |
| MDR Certification Pathway Investment | Accelerated type-approval from German building authorities compresses time-to-permit for structural concrete elements. |
| Multi-Axis Robotic Platform Development | Real-time slump monitoring merges structural placement with finished surface quality for complex UAE facade geometries. |
| Factory-Based Panel Manufacturing Scale-Up | Climate-controlled production bypasses on-site weather dependencies for year-round delivery in seasonal US markets. |
| Direct Service Capability Buildout | Channel compression displaces equipment-leasing intermediaries as design-build contractors consolidate procurement authority. |
Research Approach
Cross-validation between equipment manufacturer shipment disclosures and municipal permitting databases anchors the qualitative findings on adoption velocity. Primary interviews with construction firm procurement directors, structural engineering consultants, building code officials, and cementitious material R&D heads combined with secondary validation from ICC evaluation service reports, OSHA technical guidance documents, EU Green Deal policy frameworks, and Dubai MEE sustainability regulations. Bottom-up project pipeline tracking triangulates against top-down equipment production capacity estimates.
Calibration against historical certification timeline data and mandate implementation schedules informs the projection framework across the analysis window. Segmentation dimensions modeled include product type, application vertical, technology platform, and end-user procurement authority concentration. CAGRs derive from equipment deployment trajectories intersecting with regulatory mandate phase-in schedules. Industry-specific inputs incorporate Portland cement price elasticity coefficients and gantry system delivery bottleneck durations.
Practitioners should monitor German MDR code export velocity to other European jurisdictions and UAE mandate compliance enforcement intensity for early signals of demand inflection. Forecasts reflect assumptions on certification pathway acceleration and equipment supplier capacity expansion. Macroeconomic construction cycle downturn, regulatory code revision delays, or breakthrough alternative fabrication technologies would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Commercial Aircraft Angle of Attack Sensors Market
Others
Paraffin Physical Therapy Market
Others
Automatic Barriers and Bollards Market
Others
Molybdenum-99 Market
Others
AC Switchgear Market
Others
Global Hardware Acceleration Market
Others
Japan Automotive LED Lighting Market
Others
Cashew Kernel Market
Others
Taiwan Retail Market
Others
Diamond Mining Market
Others
Level Measuring Instrument Market
Others
Griffin Beaker Market
Others
Fluorite Market
Others
Global Sportswear Market
Others
Solar Lighting Tower Market
Others
Lined Tank Market