
 Japan 3D Printing Construction Market | 2026-2036
Japan 3D Printing Construction Market Size, Share, and Industry Trends Forecast 2026-2036
Japan 3D Printing Construction Market Insights
A shrinking pool of skilled construction labor is reorganizing how Japanese builders approach project delivery. Obayashi Corporation leverages its integrated engineering capabilities to deploy large-scale concrete printing for infrastructure frameworks. Yoshimura Construction Industry anchors regional housing markets through specialized material extrusion systems tailored to seismic-resistant designs. Mitsubishi Heavy Industries extends its industrial manufacturing pedigree into construction-grade metal additive processes for complex structural joints.
Japan 3D printing construction deploys layer-by-layer material deposition to fabricate building components, with concrete mixes achieving compressive strengths exceeding standard cast-in-place thresholds through optimized binder jetting formulations. The primary purpose centers on reducing on-site labor hours while enabling geometrically complex forms impractical with conventional formwork. Concrete products dominate current deployment volumes given Japan's mature ready-mix supply chains and familiarity with cementitious materials. Material extrusion technology leads operational installations due to its compatibility with existing construction workflows and lower capital barriers for contractors. Infrastructure applications represent the fastest-expanding segment as Japan's Ministry of Land, Infrastructure, Transport and Tourism prioritizes bridge and tunnel maintenance automation.
METI's i-Construction initiative and the Ministry of Land, Infrastructure, Transport and Tourism's guidelines for performance-based material approvals shape how printed construction products enter commercial use. JIS standards for structural concrete and building material fire resistance create compliance benchmarks that technology providers must satisfy before project integration. Stakeholders should monitor how prefectural building codes evolve to address layer-bonding integrity and long-term durability certification for additively manufactured structural elements.
Market Dynamics
METI's i-Construction productivity reforms are compressing project timelines while forcing contractors to adopt automated fabrication methods. The convergence of labor scarcity and seismic resilience mandates is restructuring how structural components get sourced and assembled.
Growth Catalysts
- Tokyo's urban redevelopment zones:Disaster-resilient housing mandates in high-density districts are accelerating printed concrete adoption for rapid structural assembly.
- METI's construction productivity reforms:Performance-based material approvals under i-Construction standards are reducing regulatory friction for novel fabrication methods.
- Layer-bonding integrity certification:Emerging JIS standards for additively manufactured structural elements are creating compliance pathways for commercial deployment.
Market Restraints
- Ready-mix supply chain concentration:Japan's mature cementitious material networks create path dependency that slows alternative binder adoption.
- Prefectural building code fragmentation:Municipal-level enforcement variations for printed structural elements generate compliance uncertainty across project sites.
- Capital intensity of gantry systems:Large-scale concrete printers require substantial upfront investment that mid-tier contractors struggle to finance.
Strategic Opportunities
- Osaka-Kobe corridor infrastructure renewal:Aging bridge and tunnel maintenance creates demand for automated repair and replacement fabrication.
- Seismic joint metal additive manufacturing:Complex structural connection geometries achievable through powder bed fusion open premium application niches.
- Fire resistance certification acceleration:Ministry of Land, Infrastructure, Transport and Tourism guidelines for performance-based material testing reduce time-to-market for novel compositions.
Industry Challenges
- Structural engineer retraining:Layer-specific load path analysis requires skills absent from conventional concrete design curricula.
- On-site printer mobilization logistics:Gantry assembly and calibration consume project hours that erode labor savings.
- Long-term durability data gaps:Accelerated aging protocols for printed concrete remain unresolved within JIS certification frameworks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan 3D Printing Construction Market |
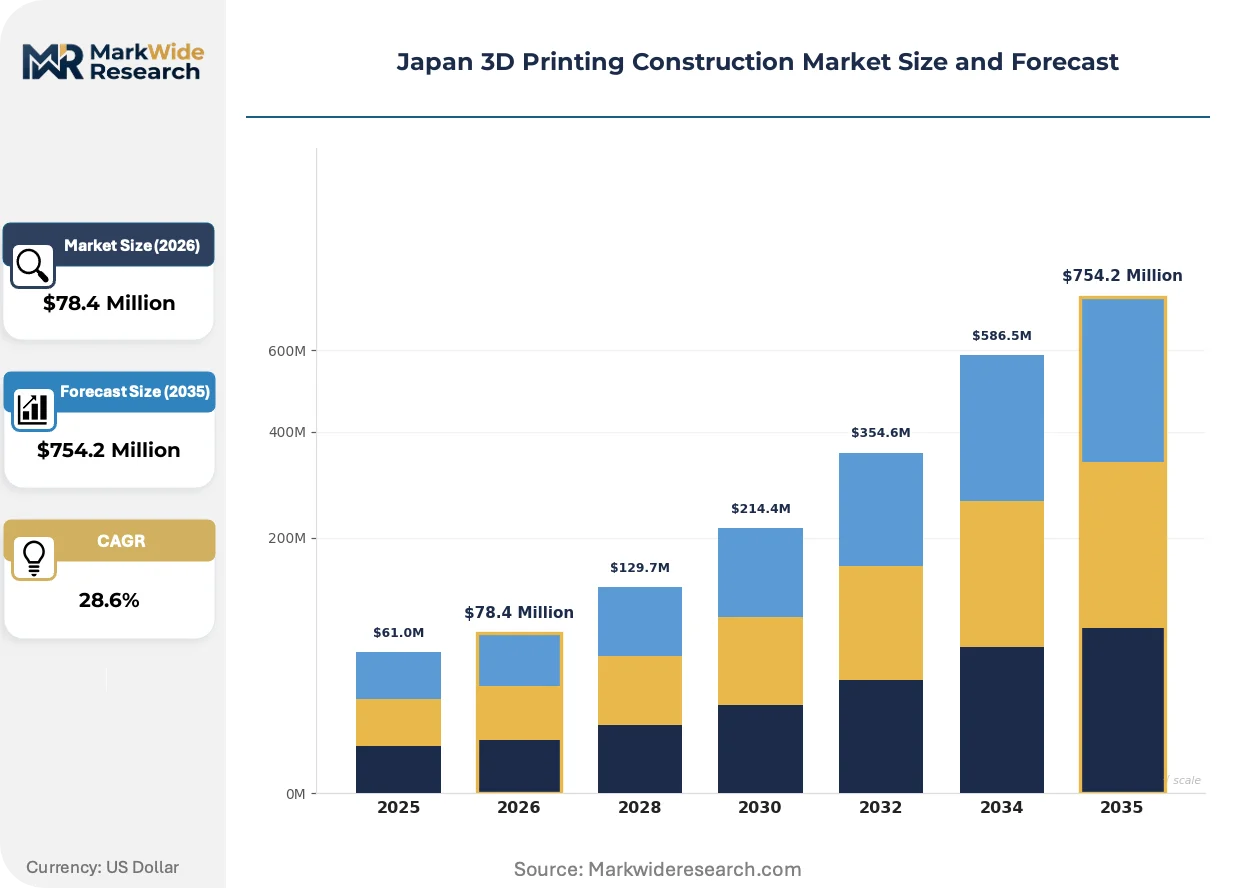
| Market Size in 2026 | $78.4 Million |
| Market Size in 2035 | $754.2 Million |
| CAGR (2026 – 2036) | 28.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Concrete, Metal, Plastic, Composite Technology: Binder Jetting, Material Extrusion, Vat Polymerization, DLP Application: Residential Structures, Commercial Buildings, Infrastructure Projects, Decorative Items End User: Contractors, Architects, Builders, Manufacturers |
| Companies Covered | Mitsubishi Heavy Industries, Toshiba Machine, Yoshimura Construction Industry, Mimaki Engineering, Canon Inc., Polyuse, Ricoh Company, Roland DG, Obayashi Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan 3D Printing Construction Market Trends and Innovations
Digital fabrication workflows are penetrating Japanese construction through three converging vectors: equipment footprint reduction, regulatory pathway clarification, and procurement model experimentation. Each vector addresses distinct friction points in technology adoption.
Robotic extrusion systems for concrete deposition are miniaturizing from warehouse-scale gantries to containerized mobile units. Regional contractors in Kansai are piloting truck-mounted printers for sidewalk and retaining wall segments. This footprint compression is enabling deployment on constrained urban sites previously inaccessible to fixed infrastructure.
METI's i-Construction initiative is mandating BIM-to-fabrication data pipelines for public infrastructure tenders. Contractors must demonstrate digital thread continuity from design files to printed output. Bridge maintenance divisions within the Ministry of Land, Infrastructure, Transport and Tourism are requiring additive methods for complex formwork replacement.
Performance-based contracting is displacing unit-price arrangements for printed structural elements. Tokyo metropolitan housing developers are accepting durability guarantees in lieu of conventional material specifications. This risk transfer model concentrates in seismic retrofit projects where geometric complexity justifies fabrication premium.
Japan 3D Printing Construction Market Segmentation
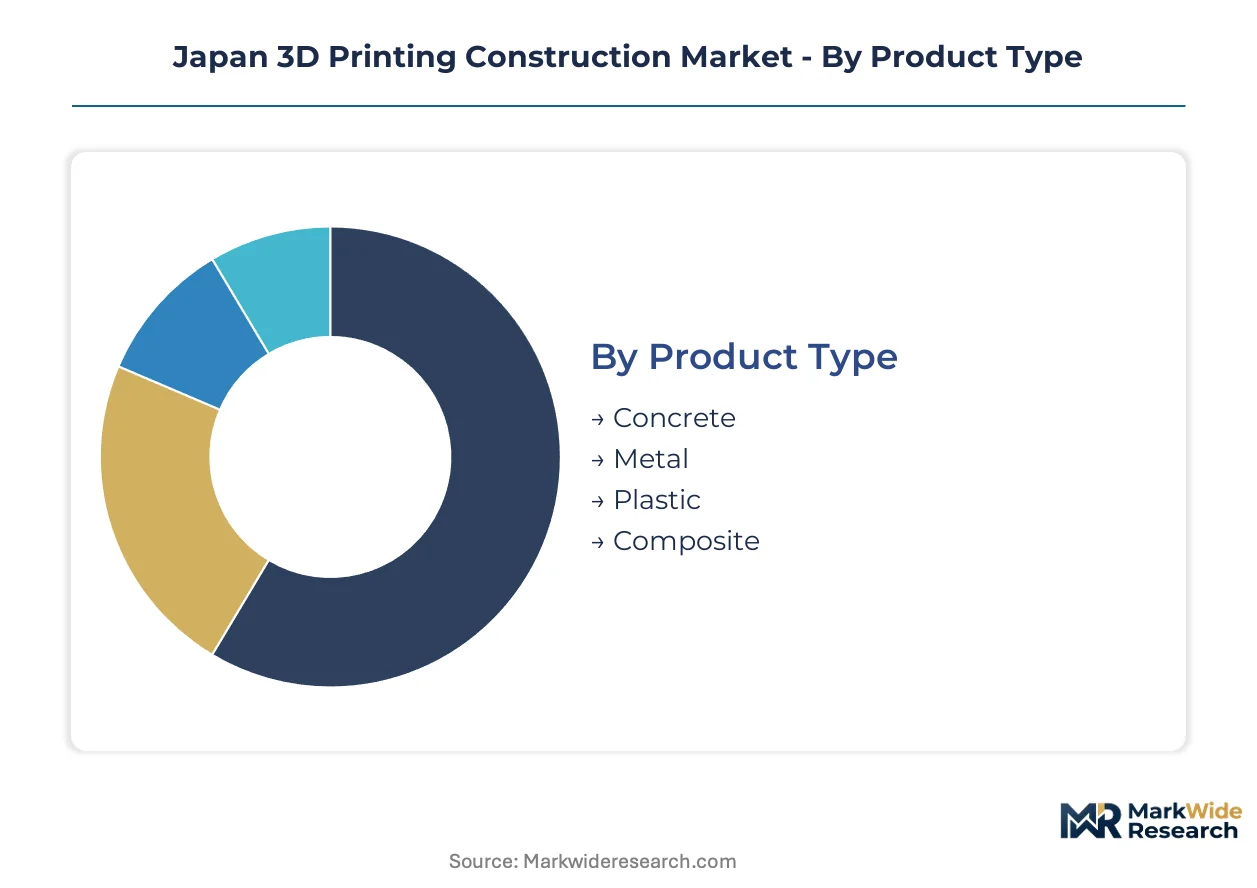
Segmentation reveals how Japan's 3D printing construction market stratifies across material types, fabrication technologies, and project applications. Each dimension carries distinct regulatory footprints and capital requirements that shape contractor adoption patterns.
Product Type:
Concrete dominates domestic deployment volumes while metal and composite segments serve specialized export-adjacent applications.
- Concrete:Cementitious mixes optimized through binder jetting achieve compressive strengths exceeding conventional cast-in-place thresholds. Demand concentrates in Tokyo's urban redevelopment zones where METI's i-Construction standards mandate rapid structural assembly for disaster-resilient housing.
- Metal:Powder bed fusion processes fabricate complex structural joints from titanium and aluminum alloys. Osaka-Kobe corridor infrastructure renewal projects drive adoption for seismic connection geometries impractical with conventional machining.
- Plastic:Polymer formulations serve temporary formwork and architectural mockups rather than load-bearing applications. Prefectural building codes restrict plastic use to non-structural elements pending fire resistance certification.
- Composite:Fiber-reinforced polymer matrices combine lightweight properties with directional strength characteristics. Niche deployment in decorative cladding and acoustic panels targets premium commercial developments.
Concrete holds the largest share; momentum sits with metal as infrastructure automation accelerates.
Technology:
Capital intensity and workflow compatibility determine which fabrication methods penetrate contractor operations at different project scales.
- Binder Jetting:Layer-wise deposition of liquid binding agents onto powder beds enables high-speed concrete component fabrication. Large-scale gantry installations at Obayashi Corporation facilities process infrastructure frameworks with minimal formwork labor.
- Material Extrusion:Continuous deposition through robotic nozzles integrates with existing ready-mix supply chains. Regional contractors favor this technology for its lower capital barriers and compatibility with seismic-resistant design workflows.
- Vat Polymerization:Photopolymer curing in resin baths produces high-resolution architectural models and connection prototypes. Limited construction-scale deployment due to material cost and build volume constraints.
- DLP:Digital light projection enables rapid prototyping of complex joint geometries for structural validation. Engineering consultancies employ DLP systems to verify load path assumptions before full-scale fabrication.
Material extrusion dominates installed base; binder jetting is climbing the fastest as METI productivity reforms favor throughput.
Application:
Project type determines which regulatory pathways and performance certifications apply to printed structural elements.
- Residential Structures:Single-family and multi-unit housing projects utilize printed concrete walls and floor slabs. Yoshimura Construction Industry anchors this segment through specialized extrusion systems tailored to regional seismic codes.
- Commercial Buildings:Office and retail developments incorporate printed facade elements and interior partitions. Performance-based contracting models in Tokyo metropolitan projects accept durability guarantees in lieu of conventional material specifications.
- Infrastructure Projects:Bridge maintenance and tunnel rehabilitation drive automated fabrication demand. Ministry of Land, Infrastructure, Transport and Tourism guidelines prioritize additive methods for complex formwork replacement in aging structures.
- Decorative Items:Non-structural architectural features and landscape elements represent entry points for smaller contractors. Lower certification barriers enable experimentation with geometrically complex designs.
Infrastructure projects command premium pricing; residential structures are gaining share fastest as labor scarcity intensifies.
End User:
Organizational capabilities and project pipelines determine which stakeholder groups integrate additive fabrication into core operations.
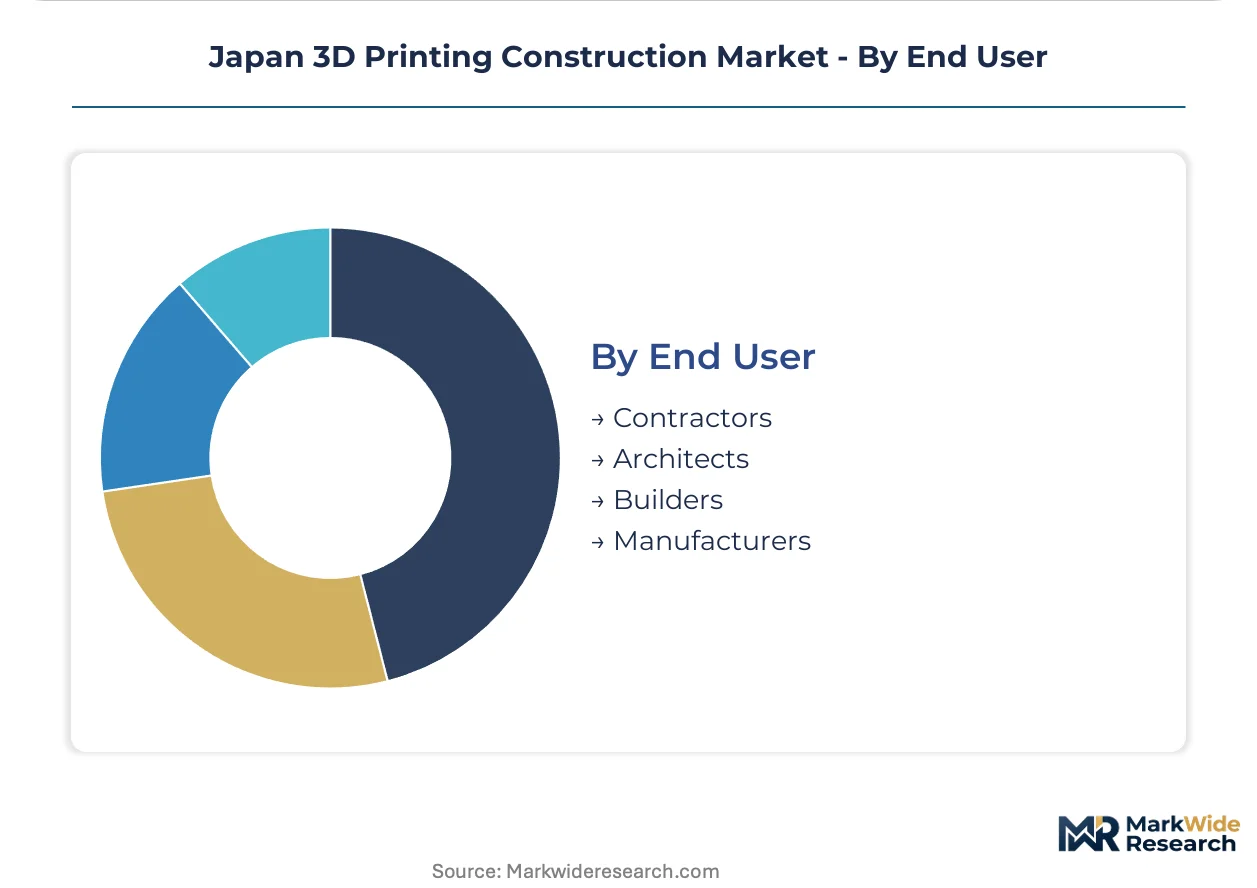
- Contractors:Construction firms with integrated engineering capabilities deploy gantry-scale systems for repetitive structural components. METI's BIM-to-fabrication mandates for public tenders favor contractors with established digital workflows.
- Architects:Design practices utilize printed prototypes and mockups to validate complex geometries before construction. Limited direct fabrication role due to regulatory restrictions on structural engineering licensure.
- Builders:Mid-tier construction entities pilot containerized mobile printers for sidewalk and retaining wall segments. Kansai regional operators lead this adoption pattern on constrained urban sites.
- Manufacturers:Industrial firms including Mitsubishi Heavy Industries extend additive expertise from aerospace into construction-grade metal processes. Structural joint production for seismic applications represents primary market entry point.
Contractors capture the largest value share; manufacturers are expanding most quickly through cross-sector capability transfer.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
METI anchors Japan's construction productivity reforms through i-Construction standards that mandate BIM-to-fabrication data pipelines. Regional adoption patterns concentrate in metropolitan zones where labor scarcity and seismic resilience mandates converge.
Kanto/Tokyo
Tokyo's urban redevelopment zones drive printed concrete demand for disaster-resilient housing assembly. METI's performance-based material approvals under i-Construction reduce regulatory friction for novel fabrication methods. Obayashi Corporation deploys gantry-scale systems in the capital region for infrastructure frameworks.
Kansai/Osaka
The Osaka-Kobe corridor generates demand for automated bridge and tunnel maintenance fabrication. Ministry of Land, Infrastructure, Transport and Tourism guidelines prioritize additive methods for complex formwork replacement in aging structures. Regional contractors pilot truck-mounted printers for sidewalk segments on constrained urban sites.
Chubu/Nagoya
Industrial manufacturing heritage in Aichi Prefecture supports construction-grade metal additive process development. JIS standards for structural concrete create compliance benchmarks for technology providers entering commercial use. Mitsubishi Heavy Industries extends aerospace additive expertise into seismic joint production for regional infrastructure.
Kyushu
Fukuoka's growing tech sector attracts construction automation startups seeking lower operational costs than Tokyo. Prefectural building code enforcement variations generate compliance uncertainty that slows mid-tier contractor adoption. Local housing developers experiment with containerized mobile printers for residential wall segments.
Tohoku
Post-disaster reconstruction priorities in Sendai and coastal municipalities emphasize rapid structural assembly methods. METI's productivity reforms channel funding toward automated fabrication for resilient housing stock replacement. Regional builders test material extrusion systems tailored to seismic-resistant design workflows.
Japan 3D Printing Construction Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across Japan's 3D printing construction sector. The vendor base clusters around three strategic groupings: integrated engineering conglomerates with gantry-scale infrastructure capabilities, specialized regional contractors with seismic design expertise, and industrial manufacturers transferring additive processes from adjacent sectors. Dominant competitive moves include strategic partnerships between equipment providers and ready-mix suppliers, plus portfolio diversification into performance-based contracting models.
Among integrated engineering conglomerates, Obayashi Corporation and Mitsubishi Heavy Industries occupy positions that exemplify scale-driven infrastructure automation. Yoshimura Construction Industry anchors the specialized contractor tier with regional seismic design capabilities. These three entities represent distinct archetypes: the engineering-integrated deployer, the cross-sector industrial transfer specialist, and the regionally focused fabrication expert.
| Leading Market Players |
|---|
| Mitsubishi Heavy Industries |
| Toshiba Machine |
| Yoshimura Construction Industry |
| Mimaki Engineering |
| Canon Inc. |
| Polyuse |
| Ricoh Company |
| Roland DG |
| Obayashi Corporation |
| Others |
Pricing and Supply Chain Analysis
Gantry-scale printer utilization rates at Obayashi Corporation's Tokyo facilities demonstrate how fixed-asset intensity concentrates supply-side power among integrated engineering conglomerates, compressing price floors for mid-tier contractors while elevating premiums for seismic-certified fabrication.
Pricing Analysis
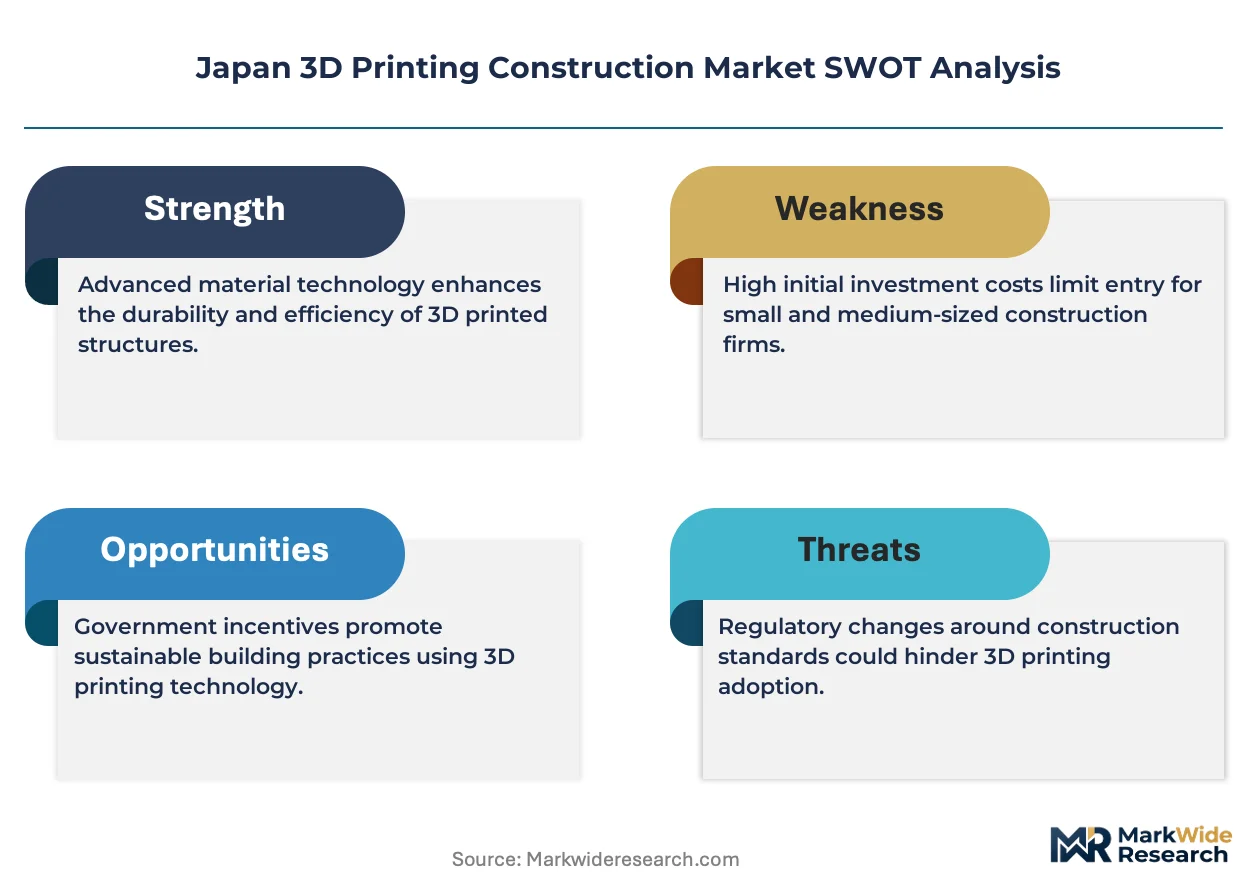
Tokyo metropolitan projects command 15-25% fabrication premiums over Osaka-Kobe corridor equivalents due to land-constrained site logistics and METI-mandated BIM compliance costs. Three-tier pricing structure separates i-Construction certified premium tier from standard JIS-compliant mid-tier and uncertified economy tier. Cost compression in the economy tier is intensifying because regional contractors deploy containerized mobile printers with lower capital recovery thresholds. Mid-tier builders exhibit highest price sensitivity; infrastructure divisions within the Ministry of Land, Infrastructure, Transport and Tourism show lowest sensitivity due to performance-based contracting acceptance.
Supply Chain Analysis
Inbound logistics costs for binder jetting powder feedstocks through Yokohama and Kobe ports fluctuate with container availability on China-Japan trade lanes, compressing margins for regional contractors without captive material storage. Japan's ready-mix concrete supply chain draws from domestic limestone and silica deposits, with specialty admixtures sourced from South Korea and Germany. Single-source vulnerability concentrates in high-performance cementitious binder formulations where JIS certification creates switching costs. Distribution runs through ready-mix supplier networks with printer OEM technical service overlays.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Japan's 3D printing construction market tracks infrastructure investment cycles, with METI's productivity reform mandates providing sustained demand visibility through public tender pipelines.
For Market Incumbents: Shield core gantry-scale infrastructure revenue by securing exclusive ready-mix supplier partnerships that lock in binder jetting feedstock access. Accelerate JIS certification investment for layer-bonding integrity protocols before prefectural code harmonization closes first-mover windows. Emerging metal additive specialists from Chubu's industrial base pose substitution threats for seismic joint applications. For New Entrants and Emerging Players: Post-printing structural validation services represent a service-layer gap where incumbents under-serve mid-tier contractors lacking in-house engineering capabilities. Kyushu's Fukuoka tech corridor offers lowest operational cost entry point with receptive municipal housing authorities. Target containerized mobile printer deployment for sidewalk and retaining wall segments in Kansai's constrained urban sites, leveraging truck-mounted system flexibility as the primary go-to-market angle. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors cross-sector industrial transfer specialists with proven powder bed fusion capabilities from aerospace or automotive applications. Long-term viability hinges on regulatory pathway clarity for structural metal additive elements across the analysis window. Acquisition targets should demonstrate METI i-Construction compliance infrastructure and active prefectural code engagement. Monitor Osaka-Kobe infrastructure renewal tender awards as inflection indicator for automated fabrication demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Binder Formulation | Obayashi Corporation's captive supply of JIS-certified cementitious mixes locks in feedstock quality and reduces port logistics exposure. |
| Mobile Printer Fleet Expansion | Regional contractors in Kansai deploy truck-mounted extrusion systems to access Tokyo-inaccessible constrained urban sites. |
| Seismic Joint Metal Additive Certification | Mitsubishi Heavy Industries leverages aerospace powder bed fusion expertise for Ministry-approved infrastructure connection geometries. |
| Performance-Based Contracting Model Adoption | Tokyo metropolitan developers accept durability guarantees from Yoshimura Construction Industry in lieu of conventional material specifications. |
| BIM-to-Fabrication Data Pipeline Integration | METI's i-Construction mandates require digital thread continuity from design files to printed output for public infrastructure tenders. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with construction firm engineering directors, ready-mix supplier technical sales leads, prefectural building code officials, and Ministry of Land, Infrastructure, Transport and Tourism infrastructure planners. Secondary validation incorporated METI i-Construction policy documents, JIS standards committee proceedings, Japan Ready-Mixed Concrete Association production statistics, and municipal tender award databases. Bottom-up project pipeline enumeration was triangulated against top-down capital expenditure tracking across the analysis window.
Across the projection horizon, the analytical framework modeled volume and value outputs through segmentation across material type, fabrication technology, application category, and end-user archetype. CAGRs were derived from regression-based trend extrapolation with scenario-weighted regulatory adoption assumptions. Industry-specific forecast inputs included METI productivity reform implementation timelines and prefectural building code amendment trajectories.
Forecasts assume regulatory continuity in METI i-Construction standards and JIS structural concrete certification regimes; material policy shifts would require re-modeling. Accelerated aging protocol resolution for printed concrete durability and prefectural code harmonization pace represent specific risk factors that could revise projections. Practitioners should keep alternative scenarios live as layer-bonding integrity certification frameworks evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Smart Home Platforms Market
Others
US Camping and Caravanning Market
Others
Vegan Confectionery Market
Others
Moveable Water Tap Market
Others
LAMEA Astrology Market
Others
LED Packaging Market
Others
ASEAN Agricultural Logistics Market
Others
CAR T Cell Therapy Market
Others
Couscous Market
Others
Canada 3D Printing Construction Market
Others
Thailand Commercial Vehicles Lubricants Market
Others
Land Surveying Equipment Market
Others
Asia Pacific Video Conferencing Hardware Market
Others
Buchner Funnels Market
Others
Solar Panel Testers Market
Others
Remanufacturing-as-a-Service (RaaS) Market