
 Europe Flow Battery Market | 2026-2036
Europe Flow Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Flow Battery Market Insights
Aftermarket service revenue is reconfiguring margin pools away from pure hardware sales toward lifecycle contracts and electrolyte management. Invinity Energy Systems PLC leverages its vertically integrated manufacturing footprint to control cell stack production and reduce lead times. VRB Energy anchors its position through proprietary vanadium electrolyte formulation and utility-scale project execution. Vanadis Power GmbH differentiates by specializing in compact system architectures for commercial and industrial sites.
A flow battery stores electrical energy in liquid electrolytes circulated through electrochemical cells, with vanadium, zinc-bromine, or iron-chromium chemistries enabling independent scaling of power and energy capacity for durations exceeding four hours. The primary purpose is grid stabilization, renewable firming, and resilient backup for critical loads. All-vanadium systems dominate installed capacity due to proven cycle life and electrolyte recyclability, while organic flow chemistries represent the fastest-expanding technology segment as developers target cost reductions below vanadium's raw material exposure. Grid storage applications capture the largest revenue pool, though renewable integration projects are accelerating fastest as offshore wind buildouts in the North Sea create intermittency management needs.
The EU Green Deal and REPowerEU framework shape demand by mandating renewable penetration targets that require multi-hour storage, while CE marking and the EU Battery Regulation establish product standards for safety, recycling, and carbon footprint disclosure. Germany's KBA and federal network regulator enforce grid connection codes that favor frequency-responsive storage assets. Stakeholders must monitor electrolyte supply chain localization decisions and evolving capacity remuneration mechanisms in national power markets.
Market Dynamics
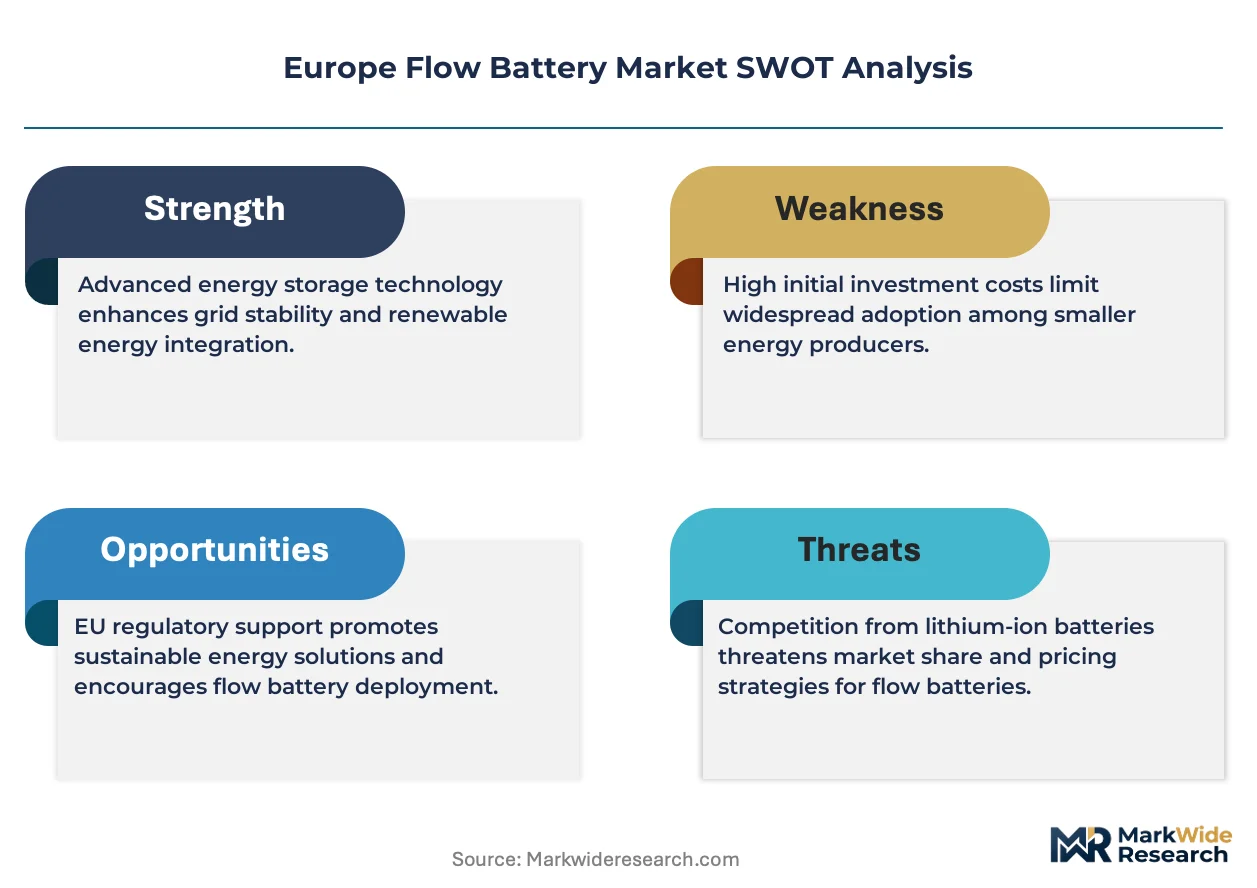
The EU Green Deal's decarbonization mandates are forcing utility-scale grid operators across Germany, Spain, and the Nordic corridor to displace conventional peaker plants with long-duration electrochemical storage systems, fundamentally restructuring procurement priorities toward multi-hour duration assets.
Growth Catalysts
- REPowerEU Framework:The EU's energy independence initiative mandates renewable penetration targets that require four-to-twelve hour storage duration, directly expanding addressable market for vanadium and organic flow chemistries.
- Industrial Cluster Resilience:Manufacturing hubs in Germany's Ruhr region and Bavaria are procuring backup power systems to insulate operations from grid instability and volatile electricity pricing.
- North Sea Offshore Wind Buildouts:Intermittency management needs from gigawatt-scale wind installations in Danish, Dutch, and German waters are creating dedicated procurement streams for frequency-responsive storage.
Market Restraints
- Vanadium Feedstock Concentration:Primary vanadium supply concentrates in Chinese and Russian metallurgical operations, exposing European system integrators to raw material price volatility and geopolitical supply risk.
- Capital Intensity Barriers:Front-loaded electrolyte costs and civil works requirements for utility-scale installations constrain project finance availability compared to lithium-ion alternatives with established lending track records.
- CE Marking Complexity:The EU Battery Regulation's carbon footprint disclosure and recycling mandates impose compliance timelines that extend product certification cycles by twelve to eighteen months versus prior regimes.
Strategic Opportunities
- Spanish Grid Modernization:Iberia's transmission network expansion and renewable curtailment challenges create underpenetrated demand for eight-hour duration systems in solar-rich regions.
- Organic Flow Chemistry Convergence:Integration of synthetic electrolyte design with automated manufacturing processes promises capital cost reductions below vanadium's resource-linked pricing floor.
- Industrial Microgrids:Poland and Czech Republic manufacturing zones outside Germany's core market represent emerging application segments seeking islanding capability and power quality services.
Industry Challenges
- Electrochemical Engineering Talent Scarcity:Specialized expertise in membrane degradation modeling and electrolyte formulation remains concentrated among a handful of research institutions and incumbent manufacturers.
- Grid Code Harmonization Friction:Divergent frequency response and voltage ride-through requirements between Germany's KBA, Spain's REE, and Nordic TSOs force product variant proliferation that strains engineering bandwidth.
- Legacy SCADA Integration Complexity:Utility procurement specifications increasingly demand seamless interfacing with existing control architectures, extending commissioning timelines and field service requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Flow Battery Market |
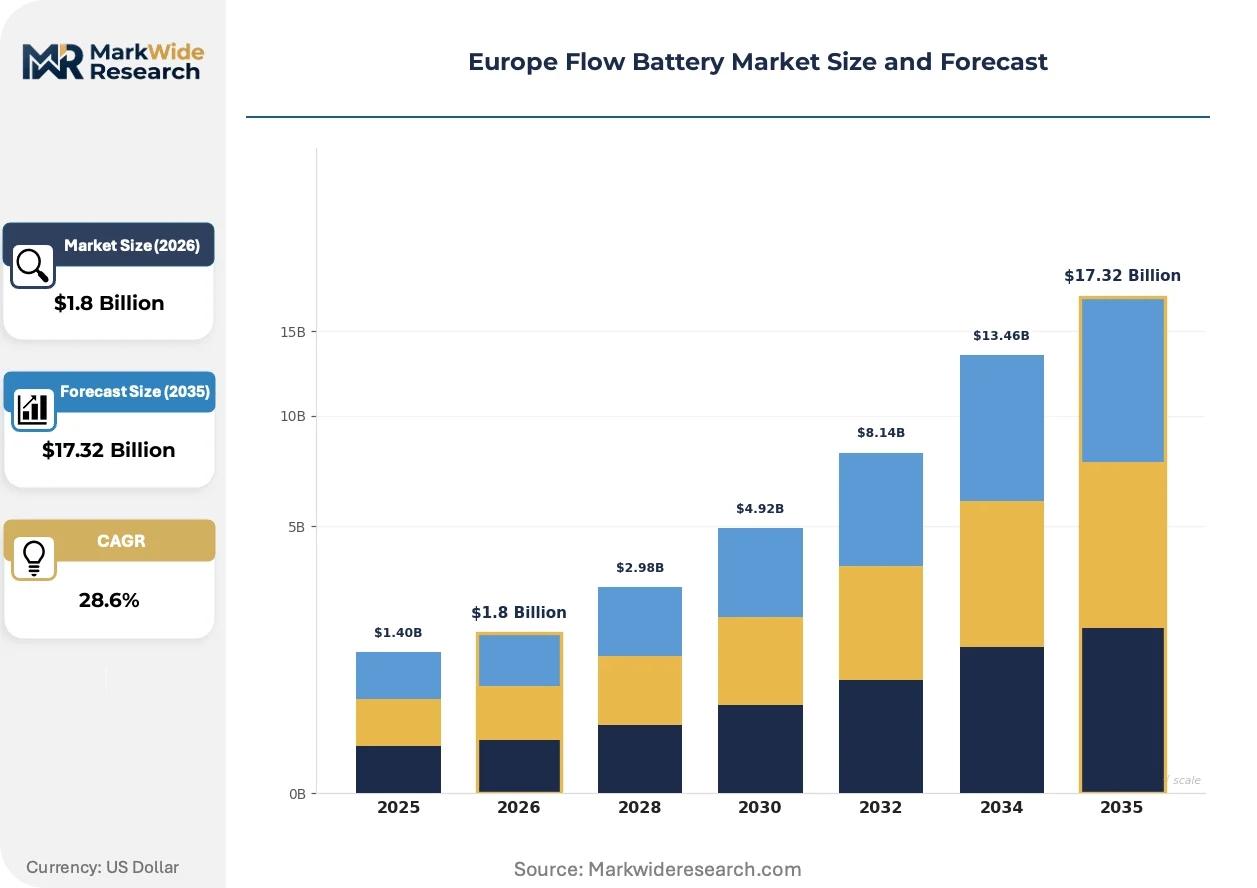
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $17.32 Billion |
| CAGR (2026 – 2036) | 28.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: All-Vanadium, Zinc-Bromine, Iron-Chromium, Organic Flow End User: Utilities, Commercial, Industrial, Renewable Energy Application: Grid Storage, Renewable Integration, Backup Power, Remote Power Capacity: Below 10 MWh, 10-50 MWh, 51-100 MWh, Above 100 MWh |
| Companies Covered | Invinity Energy Systems PLC, VRB Energy, RedFlow Ltd, ESS Tech Inc., Primus Power Corporation, Vanadis Power GmbH, Elestor BV, Gebr. SCHMID GmbH, Enerox GmbH, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Flow Battery Market Trends and Innovations
Electrolyte chemistry diversification and manufacturing automation are compressing system costs while regulatory frameworks are mandating disclosure standards that favor proven cycle-life technologies over unproven alternatives.
Organic flow battery technology is collapsing the historical cost premium against vanadium systems by eliminating raw material commodity exposure through synthetic electrolyte design. Industrial pilot deployments in chemical parks across the Netherlands and Belgium are validating six-thousand-cycle durability claims. The structural consequence is collapsing price floors for four-to-eight hour duration applications previously ceded to lithium-ion dominance.
REACH regulation amendments and the EU Battery Regulation's carbon footprint disclosure requirements are mandating supply chain traceability and end-of-life recycling protocols for electrochemical storage systems. Manufacturers must now document electrolyte sourcing and establish take-back infrastructure before CE marking approval. Grid-scale project developers in Germany and France are prioritizing chemistries with established recycling pathways to de-risk permitting timelines.
Lifecycle service contracting is displacing equipment-only procurement as the dominant commercial model among Nordic and German utility buyers. Operators are unbundling hardware acquisition from electrolyte management, preventive maintenance, and performance guarantees into multi-year operational expenditure structures. This pattern is most visible in Denmark's district heating-integrated storage projects and industrial cogeneration sites in Sweden's forest products sector.
Europe Flow Battery Market Segmentation
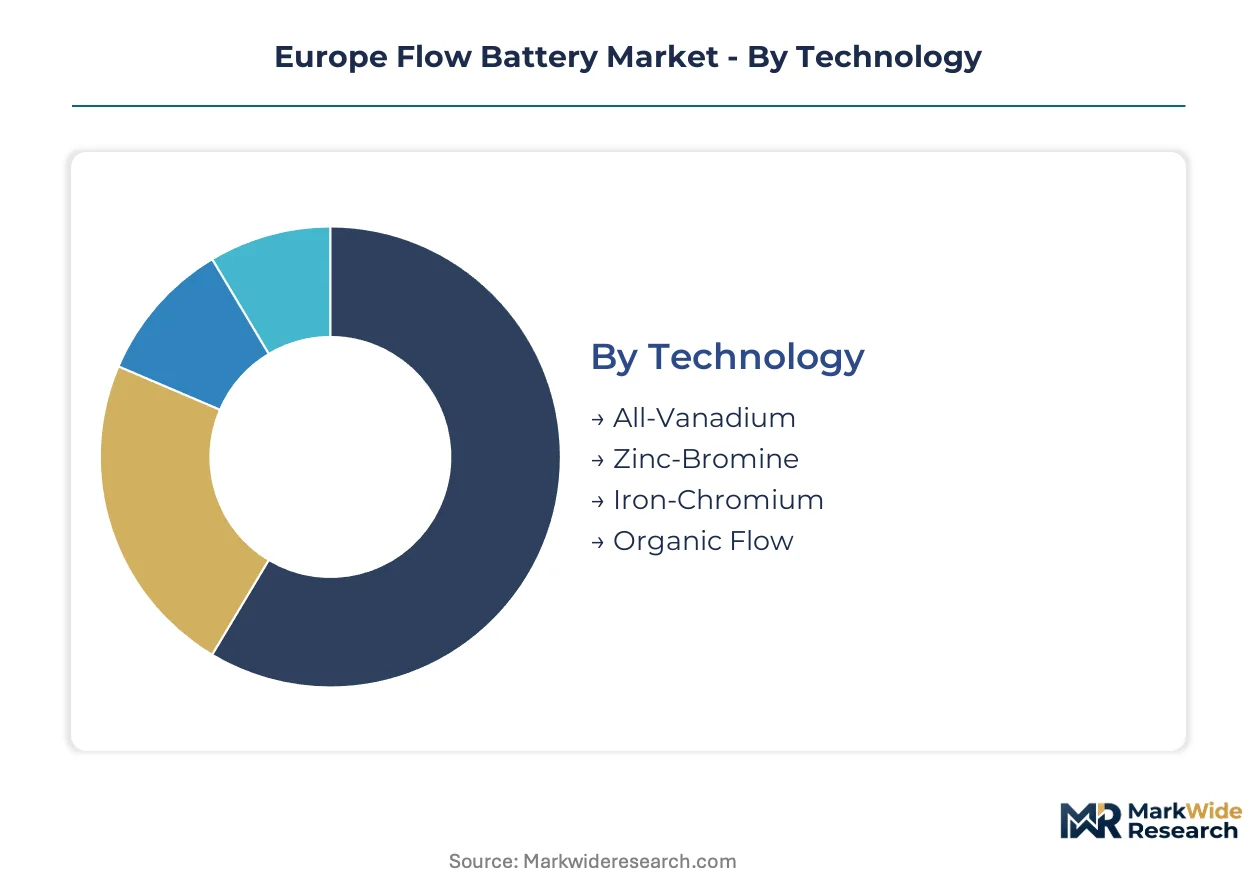
Technology selection determines capital structure, raw material exposure, and recyclability pathways for European developers navigating EU Battery Regulation compliance. Application duration requirements and grid code specifications further stratify procurement patterns across utility and industrial buyer segments.
Technology:
Cost tier positioning separates proven chemistries from emerging alternatives with differentiated raw material risk profiles.
- All-Vanadium:Proton exchange membrane architecture enables indefinite electrolyte reuse without capacity fade. German transmission operators and Nordic district heating utilities anchor procurement volumes due to established cycle-life documentation under CE marking protocols.
- Organic Flow:Synthetic quinone or TEMPO-based electrolytes eliminate commodity price linkage. Dutch chemical parks and Belgian industrial clusters are piloting six-thousand-cycle systems to validate durability claims before utility-scale deployment.
- Zinc-Bromine:Hybrid flow architecture achieves higher energy density through zinc plating mechanics. Remote telecom and mining applications in Scandinavia favor this chemistry for containerized footprint requirements.
- Iron-Chromium:Abundant feedstock base reduces geopolitical supply concentration. Early-stage project pipelines in Spain and Poland target cost-sensitive renewable integration tenders.
All-Vanadium holds installed capacity. Organic Flow is rotating up the share rankings.
End User:
Customer type dictates contracting structure, with utilities favoring lifecycle service models and industrial buyers prioritizing islanding capability.
- Utilities:Transmission and distribution operators procure multi-hour duration assets for frequency regulation and renewable firming. Germany's KBA grid codes and Spain's REE technical specifications shape procurement requirements across Central and Southern Europe.
- Industrial:Manufacturing clusters in Bavaria and the Ruhr region contract backup power systems to insulate operations from price volatility and supply interruption. Steel, chemicals, and automotive sectors dominate inquiry volumes.
- Commercial:Data centers, hospitals, and retail distribution hubs seek four-to-eight hour resilience without utility-scale civil works. Urban sites in France and Italy favor compact system footprints.
- Renewable Energy:Offshore wind developers in Danish, Dutch, and German North Sea waters require dedicated storage for intermittency management and grid connection optimization.
Utilities dominate procurement value. Renewable Energy is climbing the fastest as offshore buildouts accelerate.
Application:
Volume scale and duration requirements create distinct engineering specifications across use cases.
- Grid Storage:Bulk energy shifting and ancillary services for transmission operators. German and Nordic markets lead deployment with eight-to-twelve hour duration specifications replacing conventional peaker capacity.
- Renewable Integration:Solar and wind output smoothing with sub-hour to four-hour response windows. Spanish solar-rich regions and North Sea wind corridors concentrate developer activity.
- Backup Power:Uninterruptible supply for critical infrastructure and manufacturing processes. Industrial microgrids in Poland and Czech Republic are expanding this application segment.
- Remote Power:Off-grid and weak-grid installations for mining, telecom, and island communities. Scandinavian archipelago and Alpine sites favor containerized zinc-bromine systems.
Grid Storage captures the largest revenue pool. Renewable Integration is gaining share fastest as curtailment penalties tighten.
Capacity:
System scale determines project finance availability, civil works intensity, and electrolyte procurement strategy.
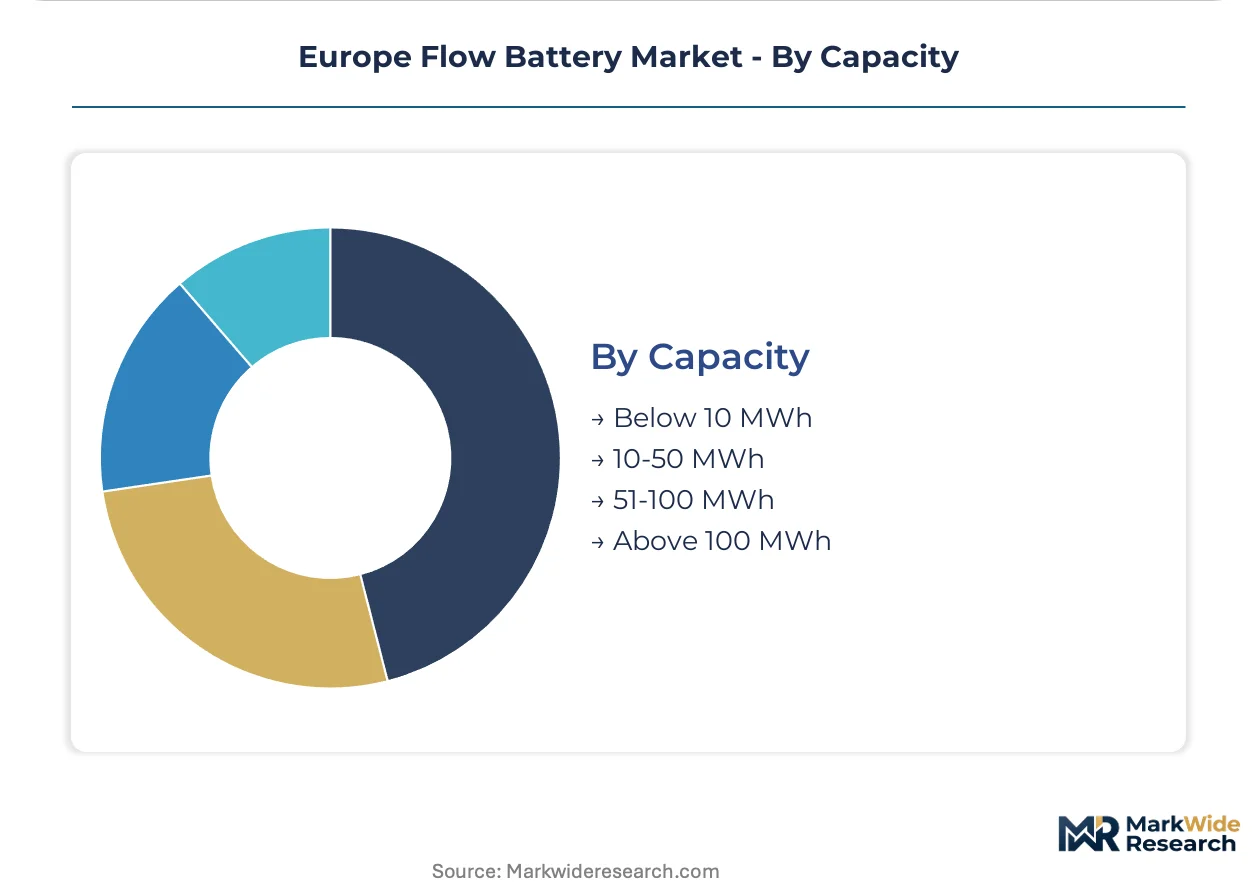
- Below 10 MWh:Containerized or skid-mounted systems for commercial and light industrial sites. French and Italian urban deployments favor this scale for permitting simplicity and site constraints.
- 10-50 MWh:Standardized utility and industrial configurations with modular expansion capability. German industrial parks and Danish district heating projects cluster procurement in this band.
- 51-100 MWh:Dedicated utility-scale installations requiring custom electrolyte supply arrangements. Spanish renewable hybrid projects and Dutch grid reinforcement tenders target this threshold.
- Above 100 MWh:Strategic transmission assets with multi-day duration potential. German and Nordic markets are developing project pipelines for seasonal storage and black-start capability.
10-50 MWh holds the densest project pipeline. Above 100 MWh is expanding most quickly as long-duration targets harden.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across European markets. German industrial buyers absorb premium pricing for proven cycle-life documentation, while Spanish and Polish developers prioritize capital efficiency in competitive renewable tenders. Nordic utilities occupy the middle ground, valuing lifecycle service integration over upfront hardware discounts.
Germany
Industrial clusters in Bavaria and the Ruhr region drive procurement of resilient backup systems for manufacturing continuity. The KBA grid codes and federal network regulator requirements favor frequency-responsive assets with eight-to-twelve hour duration specifications. Berlin-Brandenburg and Hamburg harbor districts are developing above-100 MWh installations for seasonal storage and black-start capability.
Spain
Solar-rich regions in Andalusia and Extremadura face curtailment penalties that accelerate demand for eight-hour duration systems. The REPowerEU framework and national renewable targets mandate storage co-location for new solar capacity. Madrid and Catalonia transmission operators are expanding procurement for grid reinforcement and renewable hybrid projects.
Netherlands
Chemical parks in Rotterdam and Eindhoven Region pilot organic flow systems to validate six-thousand-cycle durability claims. REACH regulation amendments impose electrolyte sourcing documentation requirements before CE marking approval. Randstad urban data centers favor compact four-to-eight hour systems for resilience without utility-scale civil works.
Denmark
North Sea offshore wind buildouts create dedicated procurement streams for intermittency management and grid connection optimization. District heating-integrated storage projects in Copenhagen and Aarhus unbundle hardware from electrolyte management into multi-year operational expenditure contracts. The Danish TSO's frequency response specifications differ from German KBA codes, forcing product variant adaptation.
Poland
Manufacturing zones in Silesia and Greater Poland seek islanding capability and power quality services outside Germany's core market. Iron-chromium chemistry developers target cost-sensitive renewable integration tenders with abundant feedstock advantages. Warsaw and Łódź industrial microgrids represent emerging application segments as grid instability risks rise.
Europe Flow Battery Market Competitive Landscape
Capability concentration sits with vertically integrated specialists controlling cell stack production and electrolyte formulation; scale advantage sits with project execution platforms securing utility-scale deployment contracts. The vendor base stratifies across three tiers: integrated manufacturers with captive supply chains, technology licensors partnering with regional EPCs, and pure-play project developers aggregating finance. Consolidation pressure intensifies as lifecycle service contracts displace equipment-only procurement. Dominant competitive moves include backward integration into membrane manufacturing and strategic alliances with North Sea offshore wind developers.
Within the integrated manufacturing tier, Invinity Energy Systems PLC and VRB Energy exemplify contrasting geographic positioning—UK-based and China-anchored respectively—while both emphasize proprietary control over core components. Vanadis Power GmbH occupies a specialization position targeting compact system architectures for commercial and industrial sites. These three entities represent the archetype spectrum: full vertical integration, electrolyte chemistry mastery, and application-specific engineering focus.
| Leading Market Players |
|---|
| Invinity Energy Systems PLC |
| VRB Energy |
| RedFlow Ltd |
| ESS Tech Inc. |
| Primus Power Corporation |
| Vanadis Power GmbH |
| Elestor BV |
| Gebr. SCHMID GmbH |
| Enerox GmbH |
| Others |
Pricing and Supply Chain Analysis
Vanadium feedstock concentration in Chinese and Russian metallurgical operations creates a dual pricing vulnerability that widens tier spreads between all-vanadium systems and emerging organic alternatives while forcing European integrators toward electrolyte supply chain localization. This raw material geopolitics simultaneously compresses margins on established chemistries and accelerates cost engineering on synthetic electrolyte pathways.
Pricing Analysis
Lifecycle service contracts now drive lifetime value capture, with electrolyte management and preventive maintenance bundling generating recurring revenue streams that offset front-loaded hardware depreciation. Pricing stratifies across premium, standard, and economy tiers based on cycle-life documentation depth and CE marking compliance status. Cost compression in the standard tier intensifies as organic flow chemistry developers undercut vanadium's resource-linked pricing floor. Industrial buyers in Germany's Ruhr region demonstrate lowest price sensitivity, prioritizing proven performance guarantees over capital efficiency.
Supply Chain Analysis
Upstream vanadium pentoxide feedstock draws from Chinese steel slag recovery operations and Russian vanadium titano-magnetite mining, with secondary processing concentrated in South African and Chinese chemical plants. Membrane components and bipolar plates hinge on specialty polymer supply from German and Japanese chemical manufacturers. Single-source vulnerability in electrolyte precursor chemicals exposes European system integrators to export restriction risk. Distribution runs through regional EPC contractors and utility procurement frameworks rather than direct manufacturer sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe Flow Battery Market functions as a defensive-moat arena where regulatory entrenchment through CE marking and EU Battery Regulation compliance creates switching costs that protect incumbent positions.
For Market Incumbents: Pre-empt organic flow chemistry displacement by securing backward integration into membrane manufacturing and electrolyte precursor supply. Lock in multi-year lifecycle service contracts with German transmission operators before Spanish and Polish price-sensitive tenders commoditize hardware margins. Prioritize certification investment in Denmark's divergent grid code specifications to force product variant proliferation on challengers.
For New Entrants and Emerging Players: Mid-market commercial and industrial sites in Poland and Czech Republic manufacturing zones represent the most penetrable entry point, with islanding capability and power quality services underserved by German-focused incumbents. Spanish solar-rich regions facing curtailment penalties offer secondary white-space for eight-hour duration systems in competitive renewable tenders. Lead with automated manufacturing cost advantages and synthetic electrolyte supply security against vanadium volatility.
For Investors and Strategic Acquirers: The market sits at a technology-convergence phase that favors vertically integrated manufacturers with captive cell stack production and electrolyte formulation control. Long-term viability rests on multi-hour duration storage mandates hardening across EU Green Deal implementation. Acquisition target archetype: mid-scale specialists with proven CE marking pathways and Nordic or German utility reference contracts. Monitor organic flow chemistry pilot-to-scale conversion rates as inflection indicator for vanadium system displacement velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Electrolyte Supply Localization | Mitigates Chinese and Russian feedstock concentration risk for European integrators. |
| Lifecycle Service Contract Expansion | Captures recurring revenue from German utility and Nordic district heating operators. |
| Organic Flow Chemistry Scale-Up | Collapses cost premium against vanadium through synthetic electrolyte manufacturing automation. |
| CE Marking Acceleration | Compresses eighteen-month certification cycles to outpace EU Battery Regulation compliance deadlines. |
| North Sea Wind Developer Alliances | Secures dedicated procurement streams for intermittency management in Danish and Dutch waters. |
Research Methodology
Operator-level perspectives from utility planning officers, EPC contractors, electrolyte supply specialists, and grid code compliance consultants anchored the qualitative base for this study. Primary fieldwork combined structured interviews with secondary validation against EU Battery Regulation filings, national TSO procurement databases, and REACH amendment documentation. Customs and trade flow data for vanadium pentoxide and membrane precursor chemicals provided upstream supply chain calibration. Bottom-up project pipeline aggregation and top-down policy target reconciliation enabled demand-side triangulation.
Scenario-bracketing around REPowerEU implementation pace and organic flow chemistry durability validation shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include technology chemistry, end-user archetype, application duration requirement, and system capacity tier. CAGRs were derived from installed base expansion rates and replacement cycle assumptions. Forecast inputs incorporated offshore wind buildout schedules in the North Sea and industrial microgrid resilience spending patterns in Central Europe.
Practitioners should monitor vanadium price volatility, REACH enforcement intensity, and Nordic-German grid code harmonization progress for early signals of forecast revision. Cross-checking against IEA long-duration storage deployment trackers and national TSO ten-year network development plans is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Griffin Beaker Market
Others
Agitator Bead Mill Market
Others
Badminton Apparel Market
Others
Advanced Combat Helmet Market
Others
Vegan Confectionery Market
Others
CAR T Cell Therapy Market
Others
Aerospace Engineering Services Outsourcing Market
Others
Global Virtual Keyboard Market
Others
LED Packaging Market
Others
One-Way Degassing Valve Market
Others
United States Printed Signage Market
Others
Gym Wipes Market
Others
Asia Pacific Contract Packaging Market
Others
Paper Shredder Market
Others
Plastic Films and Sheets Market
Others
Global Essential Oils and Plant Extracts for Livestock Market