
 Global Aircraft Sensors Market | 2026-2036
Global Aircraft Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
Global Aircraft Sensors Market Foresight
Multi-source procurement is restructuring how tier-one avionics suppliers secure critical sensing components. Honeywell International Inc. leverages its vertically integrated foundry network to control MEMS wafer supply. RTX Corporation sustains long-term sensor development contracts across multiple US defense programs. Safran SA anchors European aftermarket demand through its distributed MRO sensor replacement network.
Aircraft sensors are electromechanical or solid-state devices that transduce physical variables—pressure, temperature, acceleration, angular position—into electrical signals with specified accuracy bands, typically operating across temperature extremes from −55°C to 125°C and vibration environments exceeding 20g RMS; they serve as the perceptual layer enabling closed-loop flight control, propulsion management, and structural health monitoring in both civil and military aviation. Pressure sensors and temperature sensors occupy the largest installed base due to their ubiquity across engine monitoring and cabin environment applications, though fiber optic sensors represent the fastest-growing technology segment as fly-by-light architectures displace copper harnesses in next-generation platforms. MEMS sensors compete aggressively on unit cost and miniaturization, particularly within landing gear and fuel management systems where weight reduction delivers direct fuel burn savings.
FAA airworthiness directives and EASA certification specifications shape sensor qualification timelines, while China's GB standards and NMPA processes create parallel compliance pathways for suppliers accessing its domestic COMAC supply chain. The EU AI Act introduces emerging obligations for sensor-integrated autonomous flight systems, particularly in urban air mobility prototypes. Stakeholders must monitor divergence between US DO-178C software assurance and European CS-25 equipment certification to avoid redundant qualification costs.
Market Dynamics
Fly-by-light architectures are forcing a generational replacement cycle across commercial and military platforms, as fiber optic sensing networks displace legacy copper harnesses to reduce electromagnetic interference and wiring weight.
Growth Catalysts
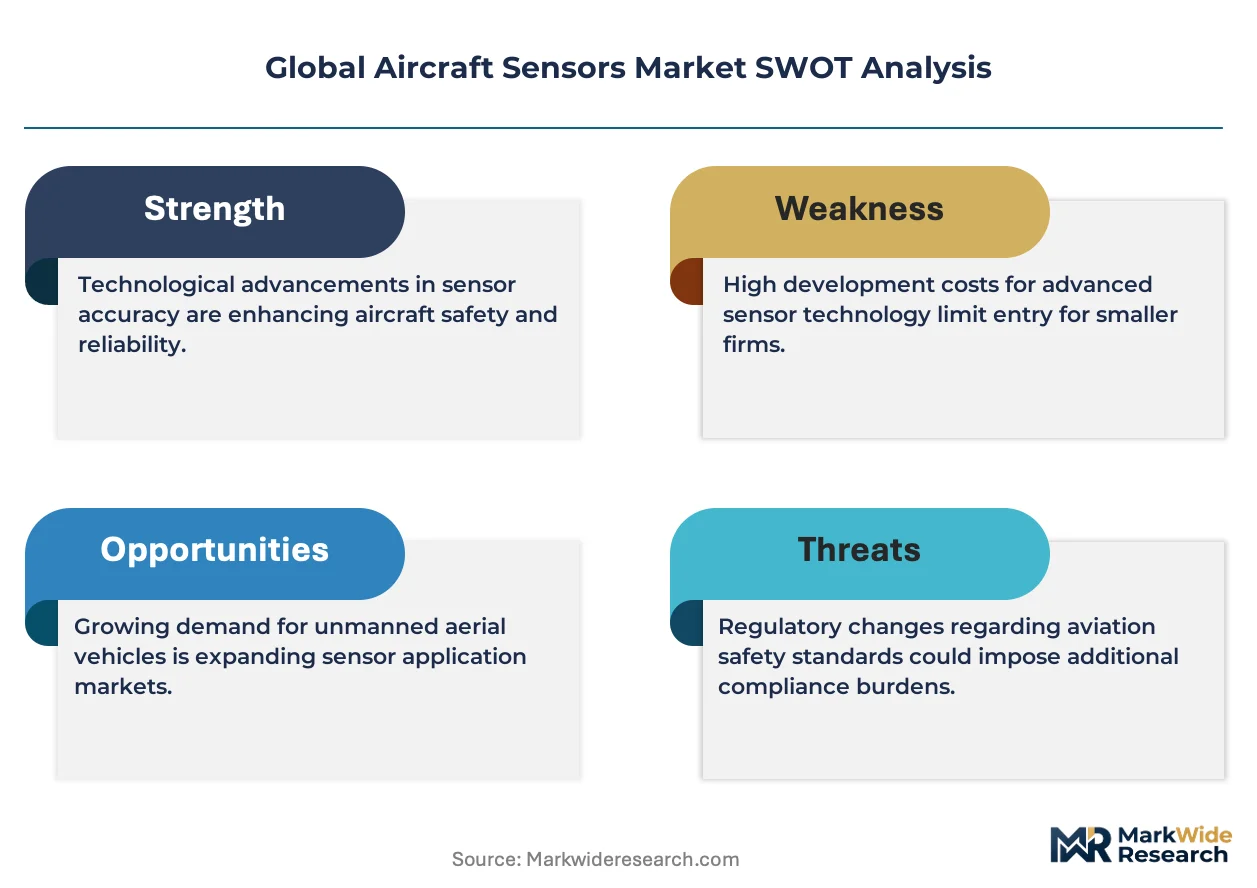
- FAA Engine Health Monitoring Mandates:Real-time propulsion diagnostics requirements under tightening airworthiness directives are expanding sensor penetration across turbine fleets.
- Urban Air Mobility Prototypes:Electric vertical take-off and landing developers in Germany and the United States are procuring lightweight MEMS inertial units for autonomous flight control.
- NATO Next-Generation Fighter Programs:Multi-domain combat aircraft development is accelerating demand for hardened environmental sensors with extended temperature ranges.
Market Restraints
- MEMS Wafer Supply Concentration:Foundry capacity for aerospace-grade silicon wafers clusters in East Asian manufacturing hubs, creating single-source vulnerability.
- Dual Certification Burden:Divergence between FAA DO-178C software assurance and EASA CS-25 equipment standards forces redundant qualification cycles.
- Platinum Group Metal Input Volatility:Exhaust gas temperature sensors rely on thermocouple alloys whose raw material costs fluctuate with mining output from South Africa and Russia.
Strategic Opportunities
- India Defense Indigenization:The country's PLI scheme and offset requirements for foreign OEMs are creating captive demand for domestic sensor assembly.
- Structural Health Monitoring Retrofits:Aging narrow-body fleets in Southeast Asia present aftermarket fiber optic strain sensor installation potential during heavy maintenance checks.
- AI-Act Compliance Services:European urban air mobility developers need sensor-integrated autonomous system documentation for algorithmic transparency certification.
Industry Challenges
- Aerospace Software Assurance Talent Scarcity:Qualified DO-178C verification engineers command premium compensation and extend development timelines.
- Legacy Platform Integration Complexity:Analog-to-digital signal conditioning for 1980s-era airframes requires custom interface electronics that resist economies of scale.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Aircraft Sensors Market |
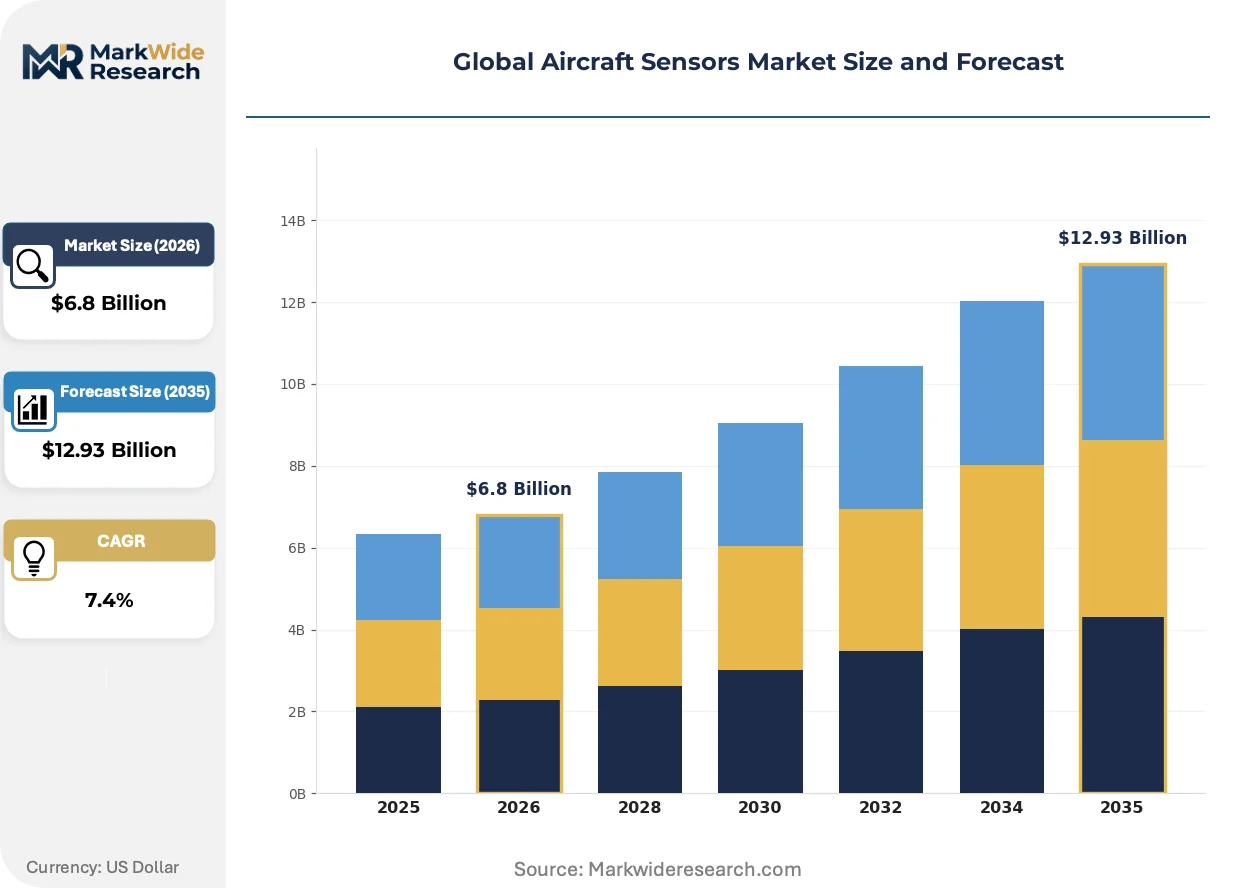
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $12.93 Billion |
| CAGR (2026 – 2036) | 7.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Sensor Type: Pressure Sensors, Temperature Sensors, Position Sensors, Flow Sensors, Acceleration Sensors, Proximity Sensors Technology: Fiber Optic Sensors, MEMS Sensors, Ultrasonic Sensors, Capacitive Sensors, Inductive Sensors, Piezoelectric Sensors Application: Flight Control Systems, Engine Monitoring, Cabin Environment, Landing Gear, Fuel Management, Navigation Systems End User: OEMs, Maintenance Providers, Aircraft Manufacturers, Avionics Suppliers, Defense Contractors, Research Institutions |
| Companies Covered | Honeywell International Inc., RTX Corporation, General Electric Company, Safran SA, TE Connectivity Ltd, Curtiss-Wright Corporation, Collins Aerospace, Thales Group, Meggitt PLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Aircraft Sensors Market Shifts & Advancements
Photonic sensing architectures are compressing the traditional avionics supply chain by enabling direct optical signal transmission from airframe to flight computer, eliminating intermediate conversion stages.
Fiber Bragg grating sensor arrays are modularizing across wing and fuselage structural monitoring applications. Boeing and Airbus next-generation programs are specifying these networks for strain and temperature mapping. The technology is modularizing maintenance protocols by enabling continuous health assessment without scheduled disassembly.
China's GB standards and NMPA certification processes are creating parallel compliance pathways distinct from FAA-EASA harmonization. Suppliers targeting COMAC supply chains must duplicate qualification testing under divergent electromagnetic compatibility requirements. Domestic Chinese sensor vendors are capturing volume in this bifurcated regulatory environment.
Airline technical procurement departments are consolidating sensor vendors to reduce qualification overhead and leverage multi-program volume commitments. Legacy fragmented supplier relationships with discrete component specialists are giving way to system-level contracts with integrated avionics houses. This concentration is most visible among low-cost carriers in Southeast Asia and the Middle East operating standardized narrow-body fleets.
Global Aircraft Sensors Market Segmentation
Sensor procurement patterns diverge sharply across aviation subsectors. Defense contractors prioritize hardened environmental specifications while commercial airlines optimize for total lifecycle cost. Understanding these buyer archetypes enables suppliers to align qualification investments with revenue concentration.
Sensor Type:
Commercial airlines and defense contractors make fundamentally different tradeoffs between precision grade and field reliability.
- Pressure Sensors:Piezoresistive and capacitive transducers measure static and dynamic pressure across pitot-static systems, engine bleed air, and hydraulic circuits. Boeing and Airbus specify these for every flight control surface. FAA mandates for real-time engine health monitoring are tightening accuracy requirements across turbine fleets.
- Temperature Sensors:Thermocouple and RTD-based devices monitor exhaust gas temperatures, bearing conditions, and thermal management systems. Exhaust gas sensors rely on platinum-rhodium alloys whose raw material costs fluctuate with mining output from South Africa and Russia.
- Position Sensors:LVDT and RVDT devices track control surface deflection and landing gear deployment.
- Flow Sensors:Mass flow and volumetric devices meter fuel consumption and pneumatic distribution.
- Acceleration Sensors:MEMS-based accelerometers detect vibration signatures for structural health monitoring.
- Proximity Sensors:Eddy-current and Hall-effect devices sense gear position and door status.
Pressure sensors lead volumes today; temperature sensors are gaining share fastest due to propulsion monitoring mandates.
Technology:
Platform generation determines whether buyers prioritize miniaturization or electromagnetic immunity.
- Fiber Optic Sensors:Fiber Bragg grating arrays transduce strain and temperature through wavelength modulation, eliminating electromagnetic interference susceptibility. Boeing and Airbus next-generation programs specify these networks for wing and fuselage structural mapping. Fly-by-light architectures are displacing copper harnesses in next-generation platforms.
- MEMS Sensors:Micromachined silicon structures deliver accelerometer and gyroscope functions at unit costs below traditional quartz designs. Urban air mobility developers in Germany and the United States procure these for autonomous flight control systems.
- Ultrasonic Sensors:Piezoelectric transducers enable non-contact distance measurement and material characterization.
- Capacitive Sensors:Variable capacitance designs detect proximity and pressure with minimal power draw.
- Inductive Sensors:Coil-based architectures tolerate contaminated environments in landing gear applications.
- Piezoelectric Sensors:Crystalline materials generate charge under mechanical stress for vibration monitoring.
MEMS sensors dominate installed base economics; fiber optic sensors are expanding most quickly as fly-by-light architectures proliferate.
Application:
Certification pathway complexity varies dramatically across airframe systems.
- Flight Control Systems:Inertial reference units and air data computers feed primary flight control laws with fault-tolerant architectures. These systems face the most stringent DO-178C software assurance requirements.
- Engine Monitoring:Real-time propulsion diagnostics requirements under tightening FAA airworthiness directives are expanding sensor penetration across turbine fleets.
- Cabin Environment:Temperature, humidity, and pressure sensors manage passenger comfort and pressurization safety.
- Landing Gear:Proximity and position sensors monitor extension, retraction, and brake conditions.
- Fuel Management:Level, pressure, and flow sensors optimize burn efficiency and prevent starvation events.
- Navigation Systems:GPS-aided inertial units and magnetic field sensors enable precise position fixing.
Engine monitoring commands the steepest expansion trajectory; flight control systems retain the highest unit value concentration.
End User:
Contract structure and volume predictability separate long-term program participants from spot-market suppliers.
- OEMs:Original equipment manufacturers integrate sensors at airframe assembly, locking in decade-long production commitments. Consolidated vendor relationships reduce qualification overhead and leverage multi-program volume.
- Maintenance Providers:Distributed MRO networks drive aftermarket sensor replacement demand, particularly for fiber optic strain sensors during heavy maintenance checks on aging narrow-body fleets.
- Aircraft Manufacturers:Airframers specify system-level performance requirements that cascade to component suppliers.
- Avionics Suppliers:Tier-one integrators consolidate discrete component procurement into system-level contracts.
- Defense Contractors:NATO next-generation fighter programs are accelerating demand for hardened environmental sensors with extended temperature ranges.
- Research Institutions:Urban air mobility developers need sensor-integrated autonomous system documentation for EU AI Act algorithmic transparency certification.
OEMs anchor revenue stability today; maintenance providers are climbing the fastest as fleet age extends replacement cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Seattle and Wichita anchor aerospace sensor demand through Boeing's commercial assembly and Spirit AeroSystems' tier-one manufacturing. Defense procurement concentrates around Washington DC and Texas corridors. European production clusters in Toulouse and Hamburg feed Airbus supply chains.
United States
FAA mandates for real-time engine health monitoring are tightening certification timelines across turbine fleets. The IRA's domestic manufacturing incentives support MEMS foundry investments in Arizona and New Mexico. Seattle's aerospace corridor concentrates Boeing 787 and 777X sensor integration activity.
Germany
Urban air mobility developers in Munich and Hamburg procure lightweight MEMS inertial units for autonomous flight control prototypes. The EU AI Act introduces algorithmic transparency obligations for sensor-integrated autonomous systems. Bavaria's aerospace cluster around Munich anchors MTU Aero Engines' propulsion monitoring sensor demand.
France
Safran's distributed MRO network drives aftermarket sensor replacement across European narrow-body fleets. EASA CS-25 equipment certification requirements shape qualification pathways distinct from FAA harmonization. Toulouse's Airbus final assembly lines specify fiber optic strain sensor networks for next-generation wing programs.
China
COMAC's C919 production ramp is creating captive demand for domestic sensor vendors under GB standards and NMPA certification. The country's dual carbon goals accelerate fuel management sensor deployment for burn efficiency optimization. Shanghai's Yangtze River Delta cluster concentrates avionics integration for indigenous commercial programs.
India
Defense indigenization under the PLI scheme and offset requirements for foreign OEMs are creating captive demand for domestic sensor assembly. DGFT import substitution policies favor local sourcing for military avionics. Bangalore's aerospace park hosts Hindustan Aeronautics Limited's sensor integration for indigenous fighter programs.
Global Aircraft Sensors Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue urban air mobility and defense indigenization opportunities. The vendor base organizes around three archetypes: vertically integrated avionics houses controlling captive MEMS supply, tier-one system integrators consolidating discrete component procurement, and specialized sensor vendors competing on qualification speed. Dominant competitive moves include multi-program volume commitments from low-cost carriers and strategic partnerships for fly-by-light architecture development.
Among US-based conglomerates, Honeywell International Inc. and RTX Corporation exemplify vertically integrated structures with in-house foundry networks and long-term defense program anchors. Safran SA represents the European aftermarket-focused archetype through its distributed MRO sensor replacement infrastructure. These three entities illustrate how geographic regulatory alignment shapes competitive positioning across FAA-EASA bifurcation.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| RTX Corporation |
| General Electric Company |
| Safran SA |
| TE Connectivity Ltd |
| Curtiss-Wright Corporation |
| Collins Aerospace |
| Thales Group |
| Meggitt PLC |
| Others |
Supply & Pricing Matrix
Platinum-rhodium alloy price indices cascade through aircraft sensor supply chains into three-tier pricing structures across premium, standard, and economy levels. Defense contractors absorb premium-tier costs for hardened environmental specifications while commercial airlines negotiate volume-driven standard-tier contracts for narrow-body fleet retrofits.
Pricing Analysis
Input-cost pass-through from platinum group metals and aerospace-grade silicon wafers compresses margins at the economy tier. Pricing stratifies across premium, standard, and economy tiers based on certification grade and after-sales service bundling. Cost compression in the MEMS segment is intensifying because foundry capacity constraints limit supplier bargaining power. Low-cost carriers operating standardized narrow-body fleets exhibit the highest price sensitivity, while NATO defense programs demonstrate the least.
Supply Chain Analysis
India's PLI scheme and DGFT import substitution policies are reshaping sourcing patterns for military avionics suppliers. MEMS wafer fabrication concentrates in Taiwan, South Korea, and the United States; platinum-rhodium alloys draw from South African and Russian mining output. Single-source vulnerability in East Asian foundry capacity threatens component availability. Distribution runs through tier-one avionics integrators consolidating discrete component procurement into system-level contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between FAA DO-178C software assurance costs in the United States and EASA CS-25 equipment certification timelines in Europe, with regulatory divergence creating cost differentials for dual-qualified suppliers.
For Market Incumbents: Cement backward integration into captive MEMS foundry capacity to defend against emerging Chinese sensor vendors capturing COMAC supply chain volume. Lock in multi-program volume commitments from low-cost carriers in Southeast Asia to secure decade-long production anchors against price erosion. For New Entrants and Emerging Players: Capture urban air mobility sensor demand in Germany and the United States by positioning lightweight MEMS inertial units for autonomous flight control prototypes. Target India's defense indigenization requirements under PLI scheme offset obligations as the most penetrable geography, leveraging domestic assembly partnerships as the primary go-to-market angle. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized fiber optic sensor vendors holding fly-by-light architecture qualifications for Boeing and Airbus next-generation programs. Five-to-ten year viability hinges on certification speed rather than scale. Watch for EASA-FAA harmonization progress as the inflection signal for reduced dual-qualification overhead.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into MEMS Foundry Capacity | Honeywell's captive wafer supply controls cost position against East Asian foundry concentration. |
| Multi-Program Volume Commitments | Consolidated airline procurement reduces qualification overhead for tier-one avionics integrators. |
| Fiber Optic Architecture Partnerships | Boeing and Airbus next-generation wing programs specify photonic sensing networks for electromagnetic immunity. |
| Defense Indigenization Joint Ventures | India's PLI scheme creates captive demand for domestic sensor assembly with foreign OEM offset requirements. |
| EU AI Act Compliance Documentation | Urban air mobility developers need algorithmic transparency certification for sensor-integrated autonomous systems. |
Research Methodology
Multiple input streams — primary interviews with avionics procurement directors, MEMS foundry operations managers, and FAA certification engineers; secondary validation through EASA submission databases, SEC 10-K filings from tier-one suppliers, and customs trade data for platinum group metal flows — were reconciled through bottom-up and top-down triangulation.
Historical production volumes from airframe assembly databases were cross-referenced against panel input from defense program managers and airline technical procurement heads across the projection horizon. Segmentation dimensions modeled include sensor type, technology platform, application system, and end-user contract structure. CAGRs were derived from installed base replacement cycles and next-generation platform procurement schedules, with fiber optic penetration rates and MEMS cost curves as industry-specific forecast inputs.
Regulatory divergence between FAA and EASA, platinum-rhodium supply disruption from mining jurisdictions, and urban air mobility program cancellation are the dominant revision risks to which forecasts reflect underlying assumptions. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Astrology Market
Others
Hopper Dryers Market
Others
Basketball Apparel Market
Others
Spain Feed Additives Market
Others
Global Drug Discovery Informatics Market
Others
Edible Insects for Animal Feed Market
Others
Global Multi Domain Controller Market
Others
Rotary Dial Machine Market
Others
China Smart Home Market
Others
Server Market
Others
Healthcare Bioconvergence Market
Others
Double Card Mobile Phone Market
Others
Global Social Networking Market
Others
Water and Waste Water Treatment Chemicals Market
Others
Solid White Films Market
Others
Europe Refrigerated Display Cases Market