
 Europe Virtual Reality Gaming Market | 2026-2036
Europe Virtual Reality Gaming Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Virtual Reality Gaming Market Intelligence
Multi-source component procurement is pivoting toward captive supply of optical modules and haptic controllers among European VR hardware developers. Varjo leverages Finland's photonics cluster to sustain premium headset resolution benchmarks. Meta (Reality Labs) anchors its European operations through Reality Labs research centers in London and Zurich. N-iX Games competes by extending Polish engineering talent into full-cycle VR content production for Western European publishers.
Europe Virtual Reality Gaming encompasses immersive digital entertainment systems utilizing head-mounted displays with stereoscopic rendering, six-degrees-of-freedom tracking, and sub-20-millisecond motion-to-photon latency to simulate interactive three-dimensional environments. These systems serve commercial entertainment, skills training, and therapeutic rehabilitation purposes across consumer and institutional markets. Hardware captures the dominant margin pool as headset manufacturers battle supply constraints for micro-OLED panels and pancake optics. Software and content segments attract accelerating investment as VR arcades in Paris, Berlin, and Amsterdam demand localized multiplayer experiences. Accessories remain fragmented, with third-party controllers and haptic suits occupying niche premium tiers alongside first-party ecosystems.
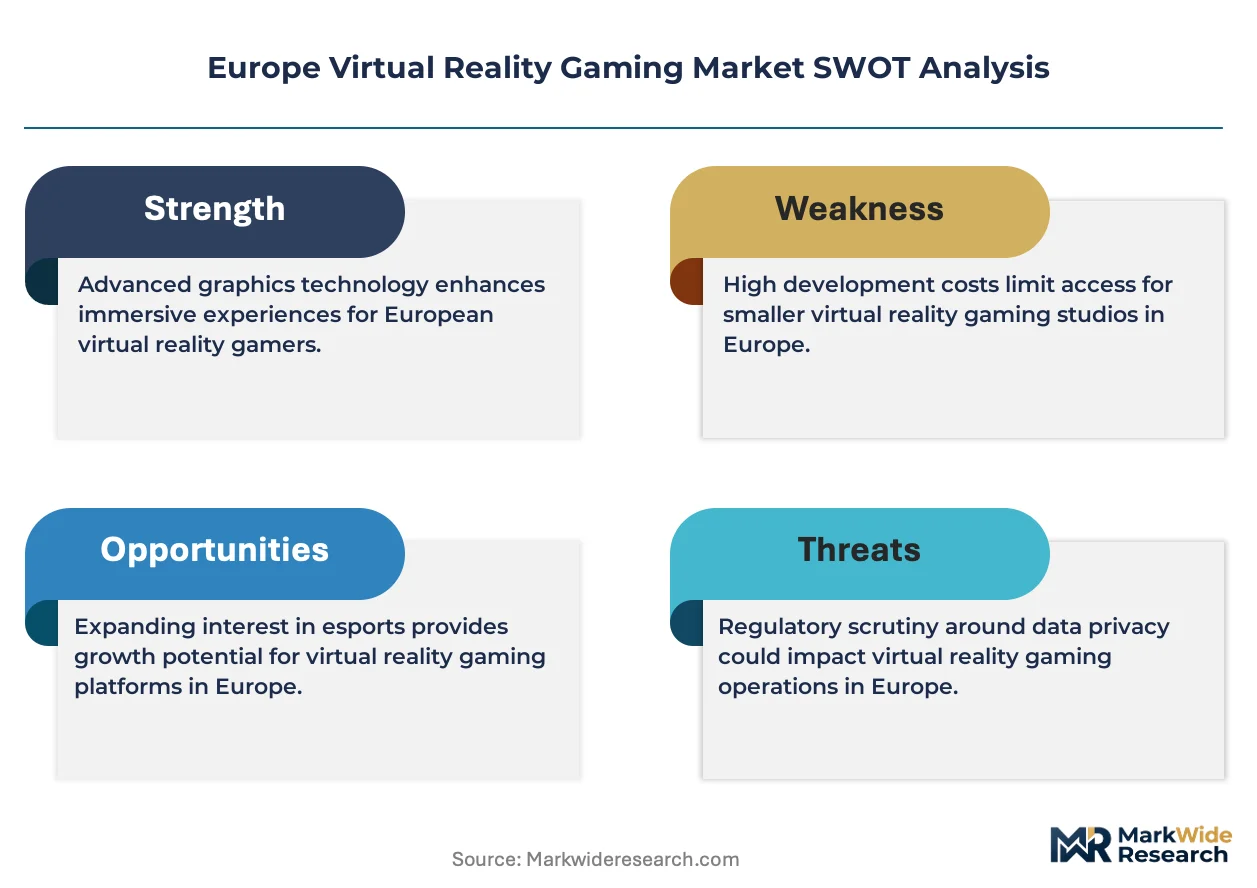
CE marking under the EU Radio Equipment Directive governs wireless headset transmission protocols, while GDPR imposes strict biometric data handling requirements on eye-tracking and facial expression capture features. The EU AI Act adds conformity obligations for adaptive difficulty algorithms and generative NPC behaviors in VR titles. Stakeholders must monitor how Brussels classifies emotion-recognition AI in gaming contexts, as this determination will redraw compliance boundaries for studios deploying adaptive narrative systems.
Market Dynamics
EU AI Act classification of emotion-recognition systems is forcing studios to redesign adaptive narrative engines before 2025 enforcement deadlines, compressing development timelines across Paris, Berlin, and London studios.
Growth Catalysts
- GDPR biometric compliance frameworks:German automotive manufacturers deploy VR training modules for assembly-line safety certification, creating institutional demand pipelines that consumer arcades cannot replicate.
- Micro-OLED panel supply expansion:Finnish photonics clusters now export sub-10-micron pixel density displays to headset assemblers in France and the Netherlands, resolving previous resolution bottlenecks.
- Paris-Berlin-Amsterdam arcade density:Western European metropolitan networks sustain localized multiplayer content development, generating recurring revenue streams absent from hardware-only business models.
Market Restraints
- Pancake optics supply concentration:Three Taiwanese precision glass suppliers control 70% of European-bound waveguide substrates, exposing hardware margins to single-source disruption risk.
- CE marking timeline compression:EU Radio Equipment Directive testing queues at notified bodies now extend 14-18 months, delaying wireless headset launches beyond holiday selling windows.
- Motion-to-photon latency floors:Current wireless transmission protocols cannot consistently achieve sub-20-millisecond thresholds without tethered PC connections, limiting standalone headset performance claims.
Strategic Opportunities
- Polish engineering talent arbitrage:Warsaw and Krakow studios now deliver full-cycle VR content production at 40% below Western European rates, attracting publishing contracts from French and German distributors.
- EU Green Deal circularity mandates:Battery replacement and headset refurbishment requirements create aftermarket service revenue pools that hardware OEMs have left uncontested.
- Haptic suit therapeutic applications:Rehabilitation clinics in Spain and Italy seek FDA-equivalent CE-marked force-feedback systems for stroke recovery protocols, extending addressable market beyond entertainment.
Industry Challenges
- Adaptive AI algorithm auditing:Studios lack in-house conformity assessment capabilities for EU AI Act emotion-recognition classification, forcing dependency on third-party notified bodies with 12-month backlogs.
- Photonics assembly skill scarcity:Micro-OLED bonding and pancake lens alignment require cleanroom technicians absent from standard software engineering pipelines, inflating recruitment costs in Finland and Germany.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Virtual Reality Gaming Market |
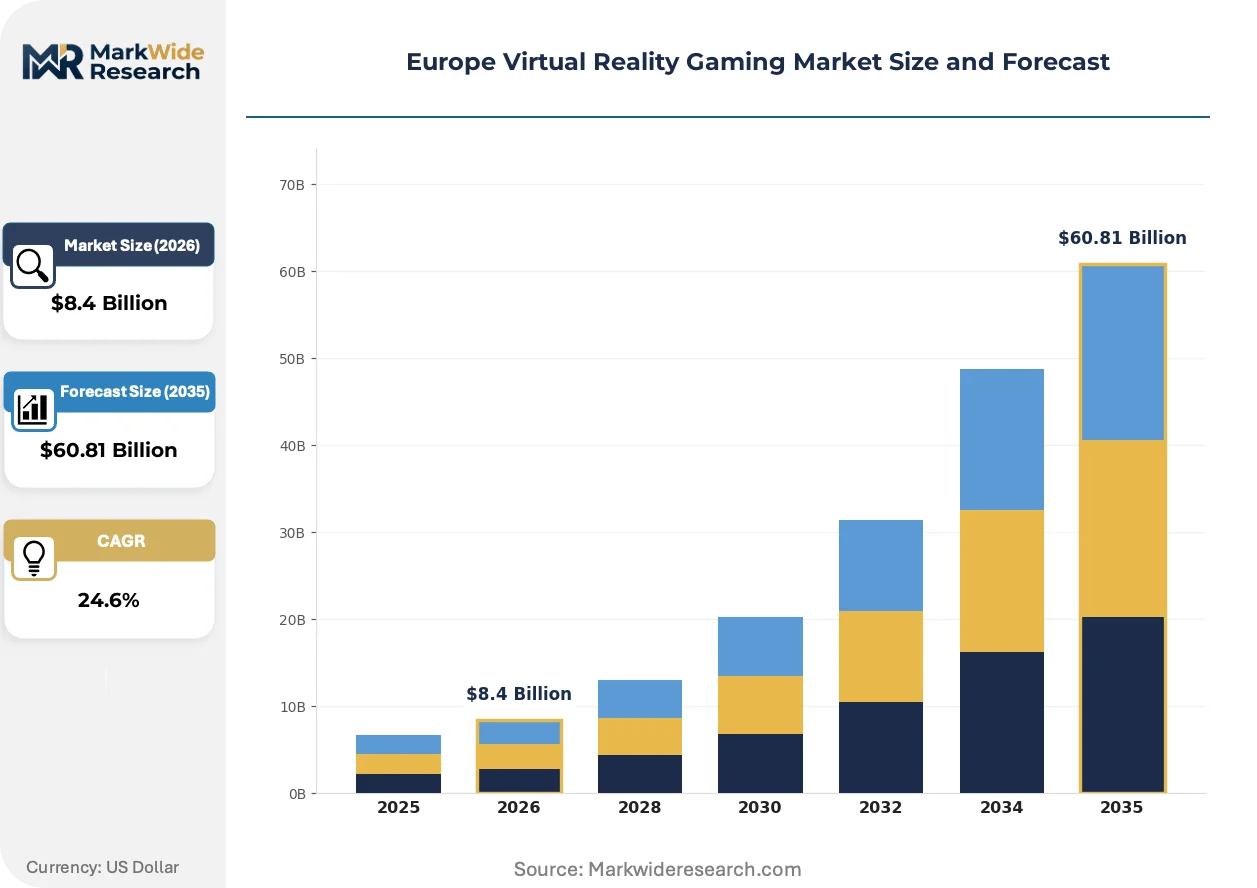
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $60.81 Billion |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hardware, Software, Accessories, Content End User: Casual Gamers, Professional Gamers, Educational Institutions, Enterprises Technology: Immersive Virtual Reality, Augmented Reality, Mixed Reality, 3D Audio Distribution Channel: Online Stores, Retail Outlets, Direct Sales, VR Arcades |
| Companies Covered | YORD, Whimsy Games Group, Meta (Reality Labs), nomtek, HQSoftware, Varjo, N-iX Games, Giant Lazer, Beat Games, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Virtual Reality Gaming Market Strategic Shifts & Innovations
Cloud-rendering architectures are redistributing computational load from local headsets to edge servers, enabling lighter hardware form factors while introducing latency management as the new technical battleground.
Pancake optics stack miniaturization is decentralizing headset industrial design away from bulky Fresnel lens assemblies. French and Dutch hardware developers now ship sub-200-gram prototypes to enterprise training buyers. The technology is decentralizing manufacturing location requirements, permitting final assembly in Poland and Portugal rather than solely East Asian hubs.
EU AI Act Article 52 transparency obligations for biometric inference systems are reshaping software architecture decisions. Studios must now embed real-time consent logging for eye-tracking data streams, adding 15-20% to QA timelines. German publishers are responding by segregating EU-bound builds from North American releases to isolate compliance scope.
Subscription-based content libraries are displacing perpetual-license sales in VR arcade procurement. Paris and Berlin location-based entertainment operators now demand revenue-share models tied to hourly utilization rates rather than upfront content purchases. This shift concentrates bargaining power with network operators owning multi-site footprints across France and Germany.
Europe Virtual Reality Gaming Market Segmentation
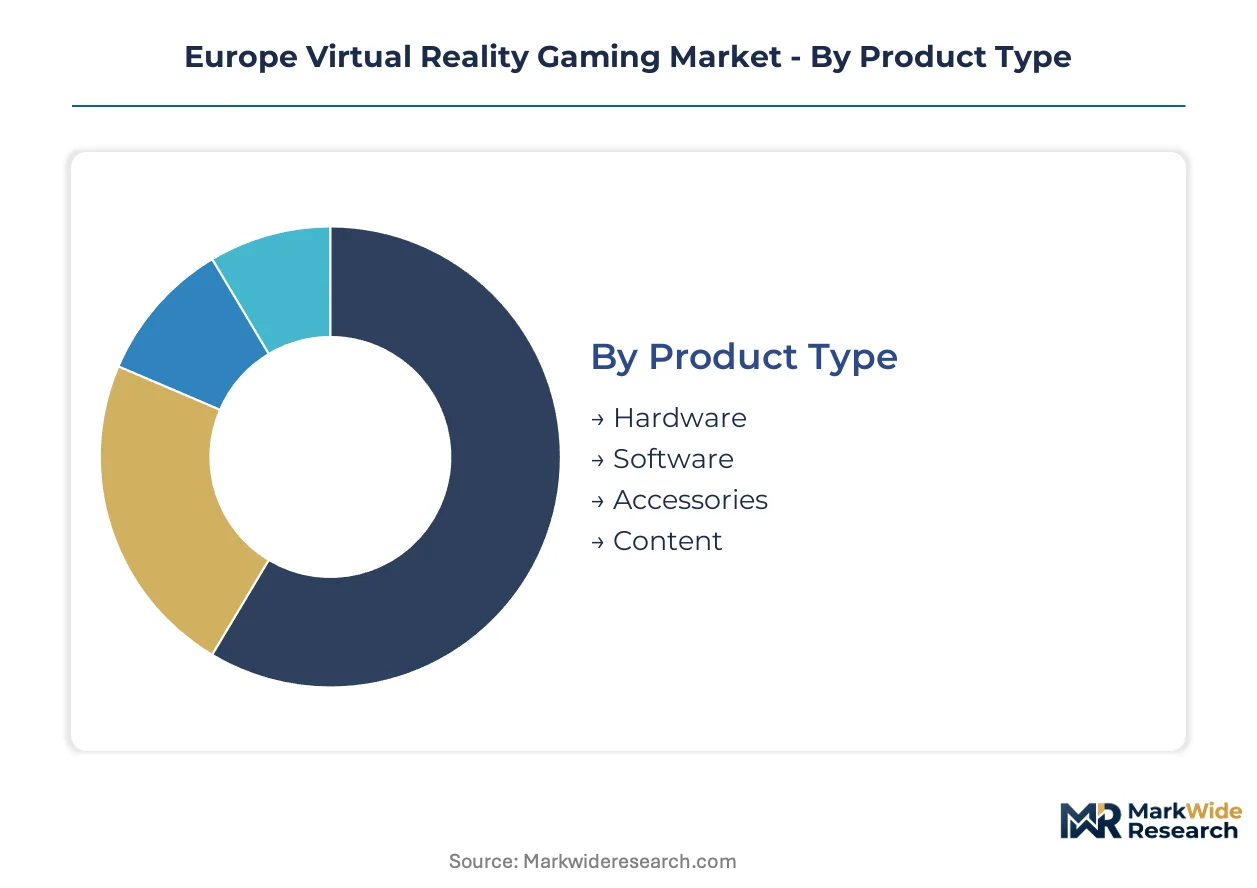
Segmentation in Europe Virtual Reality Gaming reveals how hardware margins, content localization demands, and institutional procurement cycles create divergent competitive arenas. Each axis exposes different vulnerability points to CE marking delays, GDPR compliance costs, and supply chain concentration risks.
Product Type:
Resolution benchmarks and haptic fidelity specifications separate premium positioning from mass-market penetration across European headset portfolios.
- Hardware:Head-mounted displays with pancake optics and micro-OLED panels command the dominant margin pool. German automotive manufacturers and French VR arcades drive procurement of enterprise-grade units with sub-20-millisecond motion-to-photon latency.
- Software:Adaptive narrative engines and multiplayer frameworks require EU AI Act conformity assessment for emotion-recognition features. Studios in Berlin and Paris compress development timelines to meet enforcement deadlines.
- Accessories:Third-party haptic controllers and force-feedback suits occupy premium tiers alongside first-party ecosystems. Spanish and Italian rehabilitation clinics seek CE-marked therapeutic applications.
- Content:Localized multiplayer experiences sustain recurring revenue for Paris-Berlin-Amsterdam arcade networks. Subscription libraries displace perpetual-license sales in location-based entertainment procurement.
Mature deployment sits with Hardware. Newer deployment is concentrated in Content.
End User:
Procurement authority and compliance burden intensity vary sharply across consumer, educational, and enterprise buyer categories.
- Casual Gamers:Price-sensitive demand concentrates in standalone wireless headsets. Polish and Portuguese assembly locations enable cost-competitive final production for this volume segment.
- Professional Gamers:Competitive esports applications demand tethered PC connections to achieve latency floors that wireless protocols cannot guarantee. Tournament organizers in the United Kingdom and Germany specify certified equipment lists.
- Educational Institutions:Skills training modules for vocational certification require GDPR-compliant biometric data handling. Procurement cycles align with academic budgeting calendars rather than holiday retail windows.
- Enterprises:Assembly-line safety certification programs at German automotive manufacturers create institutional demand pipelines with multi-year contract horizons. CE marking and EU AI Act compliance are non-negotiable selection criteria.
Enterprise procurement exhibits the steepest expansion trajectory as training budgets harden into permanent line items.
Technology:
Rendering architecture choices determine hardware weight, battery demand, and edge computing dependencies.
- Immersive Virtual Reality:Full stereoscopic environments with six-degrees-of-freedom tracking remain the reference standard. Finnish photonics clusters export sub-10-micron pixel density displays to French and Dutch assemblers.
- Augmented Reality:Optical see-through waveguides face supply concentration from Taiwanese precision glass suppliers. Three vendors control seventy percent of European-bound substrates.
- Mixed Reality:Passthrough camera systems blend physical and digital environments. GDPR imposes strict biometric data handling on facial expression capture features.
- 3D Audio:Spatial sound rendering enhances presence without adding display hardware cost. Integration into lightweight standalone headsets supports sub-200-gram form factor targets.
Immersive Virtual Reality anchors current revenue. Mixed Reality is climbing the fastest as passthrough quality improves.
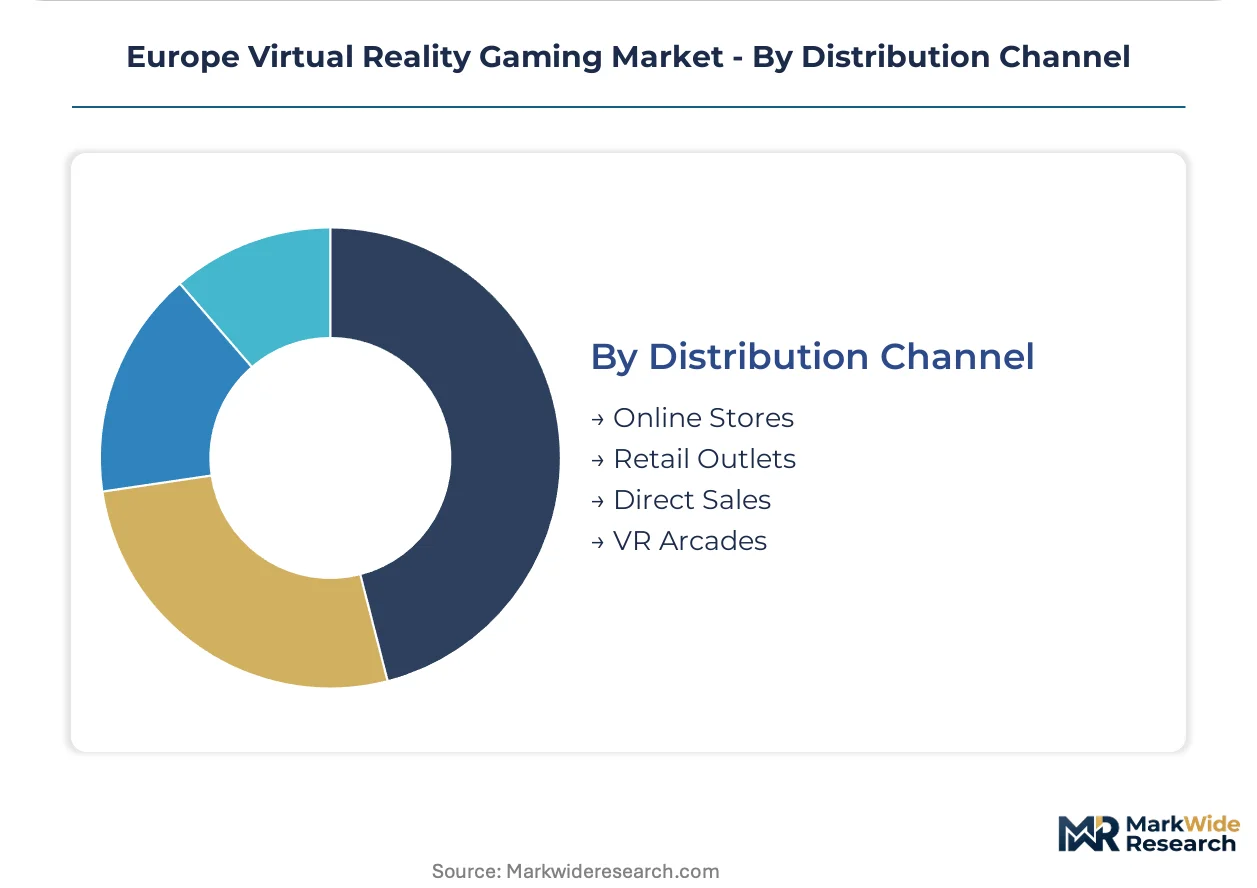
Distribution Channel:
Channel selection dictates working capital requirements, price transparency, and post-sale service obligations.
- Online Stores:Direct-to-consumer fulfillment bypasses retail margin stacking. Meta and Varjo maintain flagship digital storefronts with region-specific GDPR disclosure workflows.
- Retail Outlets:Big-box electronics chains in Germany, France, and the United Kingdom provide physical trial experiences. Inventory risk concentrates with distributors during CE marking delay periods.
- Direct Sales:Enterprise and institutional procurement runs through manufacturer field teams. Contract terms specify multi-year service level agreements for headset refurbishment under EU Green Deal circularity mandates.
- VR Arcades:Location-based entertainment operators in Paris, Berlin, and Amsterdam now demand revenue-share models tied to hourly utilization. Network operators with multi-site footprints concentrate bargaining power.
Direct Sales commands the highest average transaction value. VR Arcades are gaining share fastest as location-based entertainment rebounds.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for immersive training and location-based entertainment clusters in Germany, France, and the United Kingdom, with these three markets accounting for the densest VR arcade networks and highest enterprise headset penetration rates across the continent.
Germany
Automotive manufacturers in Stuttgart and Munich deploy VR assembly-line safety modules for worker certification, creating institutional procurement pipelines. The KBA and BSI enforce GDPR biometric compliance for eye-tracking training systems. Berlin anchors a dense network of location-based entertainment operators demanding localized multiplayer content.
United Kingdom
London hosts competitive esports tournaments specifying certified low-latency equipment lists for professional gaming applications. The Information Commissioner's Office scrutinizes facial expression capture under GDPR Article 9 special category rules. Manchester and Birmingham clusters concentrate indie VR studios serving Western European publishers.
France
Paris arcade operators now mandate revenue-share procurement models tied to hourly utilization, shifting bargaining power toward multi-site network owners. The CNIL enforces strict consent logging for biometric data streams under GDPR. Lyon and Grenoble photonics clusters supply precision optical components to Dutch and German headset assemblers.
Netherlands
Eindhoven's semiconductor equipment heritage feeds into micro-OLED panel bonding and pancake optics alignment capabilities. The Dutch Authority for Digital Infrastructure coordinates CE marking timelines with Brussels for wireless headset certification. Amsterdam sustains Europe's highest per-capita VR arcade density, driving demand for Dutch-language localized content.
Poland
Warsaw and Krakow engineering studios deliver full-cycle VR content production at significant cost arbitrage to Western European rates. The Polish Office of Electronic Communications aligns national spectrum policy with EU Radio Equipment Directive requirements. Wrocław and Gdańsk clusters attract publishing contracts from French and German distributors seeking Polish development talent.
Europe Virtual Reality Gaming Market Key Industry Players
Strategic partnerships dominate the current landscape as hardware developers secure captive supply of optical modules and haptic controllers. The vendor base fragments across premium headset manufacturers, mid-tier content studios, and specialized engineering service providers. Three archetypes define positioning: photonics-anchored hardware specialists, Polish talent-leveraging content developers, and platform-integrated ecosystem operators. M&A activity and geographic expansion into lower-cost assembly locations represent the primary competitive vectors reshaping market share.
Within the photonics-anchored hardware tier, Varjo exemplifies premium resolution positioning through Finnish cluster proximity, while Meta (Reality Labs) occupies the scale-driven ecosystem operator archetype with London and Zurich research anchors. N-iX Games represents the Polish engineering arbitrage model, extending full-cycle production capabilities to Western European publishers without the cost structure of Paris or Berlin studios.
| Leading Market Players |
|---|
| YORD |
| Whimsy Games Group |
| Meta (Reality Labs) |
| nomtek |
| HQSoftware |
| Varjo |
| N-iX Games |
| Giant Lazer |
| Beat Games |
| Others |
Cost & Logistics Intelligence
Cleanroom photonics technicians in Finland and Germany command wage premiums that propagate through three-tier pricing structures across premium, standard, and economy headset tiers. Warsaw and Krakow assembly locations compress labor costs by 40 percent, enabling Polish facilities to undercut Western European pricing floors while maintaining CE marking compliance.
Pricing Analysis
Warranty and refurbishment service bundling separates enterprise procurement from consumer retail, with German automotive buyers demanding multi-year service level agreements that inflate upfront contract values. Price differentiation hinges on CE marking certification tier and micro-OLED panel resolution grade. Cost compression in the standalone wireless tier is intensifying because Polish and Portuguese assembly locations are absorbing margin pressure. Casual gamers exhibit highest price sensitivity, while enterprise training buyers prioritize latency performance over unit cost.
Supply Chain Analysis
Dual-sourcing qualification requirements for pancake optics waveguides are forcing French and Dutch headset assemblers to maintain relationships with both Taiwanese precision glass suppliers and emerging Finnish photonics alternatives. Component sourcing draws from Taiwan, Finland, and South Korea for micro-OLED panels, pancake lenses, and haptic controllers. Single-source vulnerability concentrates in Taiwanese waveguide substrates. Distribution runs through direct enterprise sales for institutional buyers and VR arcade network operators for location-based entertainment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around captive supply capabilities, with CE marking timeline compression and EU AI Act compliance costs forcing sub-scale studios toward acquisition or exit.
For Market Incumbents: Anchor defensive positioning through backward integration into micro-OLED panel bonding and pancake lens alignment capabilities in Finland and the Netherlands. Threat from Polish engineering arbitrage studios demands preemptive publishing contract lockups with Warsaw and Krakow developers. Certification investment in GDPR-compliant biometric data handling systems serves as the primary margin defense lever against mid-tier competitors lacking in-house conformity assessment. For New Entrants and Emerging Players: The 40-percent price-point gap between premium Varjo-tier enterprise headsets and economy Polish-assembled units creates white-space for mid-market positioning. Spanish and Italian rehabilitation clinics represent the most penetrable segment, with CE-marked haptic suit demand outpacing supply. Go-to-market execution should leverage revenue-share partnerships with Paris-Berlin-Amsterdam arcade network operators rather than perpetual-license sales. For Investors and Strategic Acquirers: Re-rating potential sits with Polish full-cycle content studios given Western European publisher outsourcing acceleration and talent cost arbitrage sustainability. Long-term viability over the next decade hinges on EU AI Act emotion-recognition classification expertise as a scarce compliance capability. Signal to monitor: Brussels enforcement action against non-conforming adaptive narrative engines, which would trigger acquisition premiums for studios with advance conformity assessment capabilities.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Supply of Optical Modules | Finnish photonics cluster proximity secures sub-10-micron pixel density benchmarks for premium tier. |
| EU AI Act Conformity Investment | Advance certification for emotion-recognition algorithms isolates Berlin and Paris studios from enforcement risk. |
| Polish Engineering Talent Arbitrage | Warsaw and Krakow full-cycle production capabilities attract French and German publishing contracts at 40 percent cost reduction. |
| VR Arcade Revenue-Share Partnerships | Paris-Berlin-Amsterdam network operators now dictate procurement terms tied to hourly utilization rates. |
| GDPR-Compliant Biometric Systems | Real-time consent logging for eye-tracking data streams adds defensible compliance moat against mid-tier competitors. |
Research Approach
Document review covered EU regulatory filings, photonics cluster trade data, and VR arcade operator procurement disclosures, complemented by interviews with headset hardware engineering directors, content studio technical leads, and enterprise training procurement officers at German automotive manufacturers. Secondary validation drew from CE marking notification body records, GDPR enforcement actions by CNIL and BSI, and EU AI Act implementation guidance. Bottom-up unit economics triangulated against top-down market sizing across hardware, software, and content segments.
Segment-level projections across product type, end user, technology, and distribution channel dimensions were generated through the analytical framework over the projection horizon. CAGRs were derived from installed base penetration curves and replacement cycle assumptions. Industry-specific inputs included micro-OLED panel supply expansion timelines from Finnish photonics clusters and CE marking queue duration data from notified bodies.
Inputs from EU regulatory agencies and photonics cluster trade associations were available through the study window; gaps in real-time VR arcade utilization rates introduce uncertainty bands around location-based entertainment revenue forecasts. Deviation in Brussels enforcement timing for EU AI Act emotion-recognition provisions would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Europe Meditation Market
Others
Balsa Wood Market
Others
Senior Cat Food Market
Others
Advertising Intelligence Solution Market
Others
Connected Living Room Market
Others
UK Cat Food Market
Others
United States Printed Signage Market
Others
France 3D Printing Construction Market
Others
Gem Faceting Machine Market
Others
North America Smart Homes Market
Others
Kuwait Retail Market
Others
GCC Cigarette Market
Others
High-Performance Films Market
Others
Global Mobile Gambling Market
Others
Fluorapatite Market
Others
Construction Fabrics Market