
 Solar Animal Repellent Market | 2026-2036
Solar Animal Repellent Market Size, Share, and Industry Trends Forecast 2026-2036
Solar Animal Repellent Market Insights
Subscription-based deterrent monitoring is consolidating as a recurring revenue layer atop hardware sales, shifting vendor economics from one-time transactions to ongoing service relationships. Bird-X leverages its acoustic R&D pipeline to sustain technology leadership in ultrasonic systems. Duranom anchors its position through geographic dominance in European garden retail channels. Amerfist differentiates via aggressive channel control across North American e-commerce platforms.
Solar animal repellents combine photovoltaic cells with motion-activated emitters, typically operating at frequencies between 15 kHz and 65 kHz to target species-specific auditory ranges without human detection. These devices serve commercial agriculture and residential property management by reducing crop loss and landscape damage without chemical residues or physical barriers. Ultrasonic product types capture the dominant margin pool due to lower component costs and broader species coverage, while LED flashing devices represent the fastest-growing segment as nocturnal pest pressure intensifies in suburban corridors. Solar-powered technology leads unit shipments, though hybrid systems are gaining traction among farmers requiring consistent performance during low-light periods.
The EPA regulates chemical repellent alternatives under FIFRA, indirectly channeling demand toward solar-powered mechanical deterrents as registration requirements tighten. California's Department of Pesticide Regulation maintains the nation's strictest restrictions on wildlife-toxic compounds, creating compliance-driven substitution in the largest US state market. Stakeholders must monitor evolving municipal noise ordinances, as ultrasonic frequency thresholds increasingly appear in local land-use codes and could constrain deployment parameters in dense residential zones.
Market Dynamics
The solar animal repellent market is experiencing structural compression as FIFRA registration requirements tighten and landscape professionals abandon chemical alternatives en masse. This regulatory-driven substitution is accelerating hardware refresh cycles and forcing vendors to build recurring revenue through monitoring services.
Growth Catalysts
- EPA FIFRA Restrictions:The EPA's escalating registration burdens on chemical wildlife repellents are redirecting commercial groundskeeping budgets toward solar-powered mechanical deterrents, particularly in high-compliance states.
- Photovoltaic Cost Compression:Falling solar cell prices are enabling feature-rich entry-tier devices that previously required premium positioning, expanding addressable volume in residential channels.
- Suburban-Wildlife Interface Expansion:California, Texas, and Florida are experiencing intensified human-wildlife conflict as exurban development encroaches on habitat corridors, generating sustained replacement demand.
Market Restraints
- Lithium-Ion Supply Concentration:Battery pack sourcing remains concentrated among East Asian cell manufacturers, exposing vendors to input volatility and extended lead times during demand surges.
- Municipal Noise Ordinance Fragmentation:Ultrasonic frequency thresholds are appearing inconsistently across local land-use codes, complicating national product specifications and deployment parameters.
- Physical Barrier Substitution:Electric fencing and mesh exclusion systems retain cost advantages for large-scale agricultural applications, limiting solar repellent penetration in commodity crop segments.
Strategic Opportunities
- Subscription Monitoring Services:Cloud-connected deterrent networks with activity logging are creating recurring revenue layers that improve customer lifetime value and reduce churn.
- Nocturnal LED Flashing Segment:LED-based devices targeting crepuscular and nocturnal species represent underexploited white space with faster growth velocity than ultrasonic alternatives.
- Hybrid Power Architectures:Battery-backed solar systems with grid fallback capability are capturing farmer segments in low-light agricultural regions requiring consistent performance.
Industry Challenges
- Firmware Security Certification:IoT-enabled repellents require cybersecurity validation under emerging state-level connected device mandates, extending product launch timelines.
- Acoustic Engineer Talent Scarcity:Species-specific frequency optimization demands specialized bioacoustics expertise that vendors struggle to source at scale.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solar Animal Repellent Market |
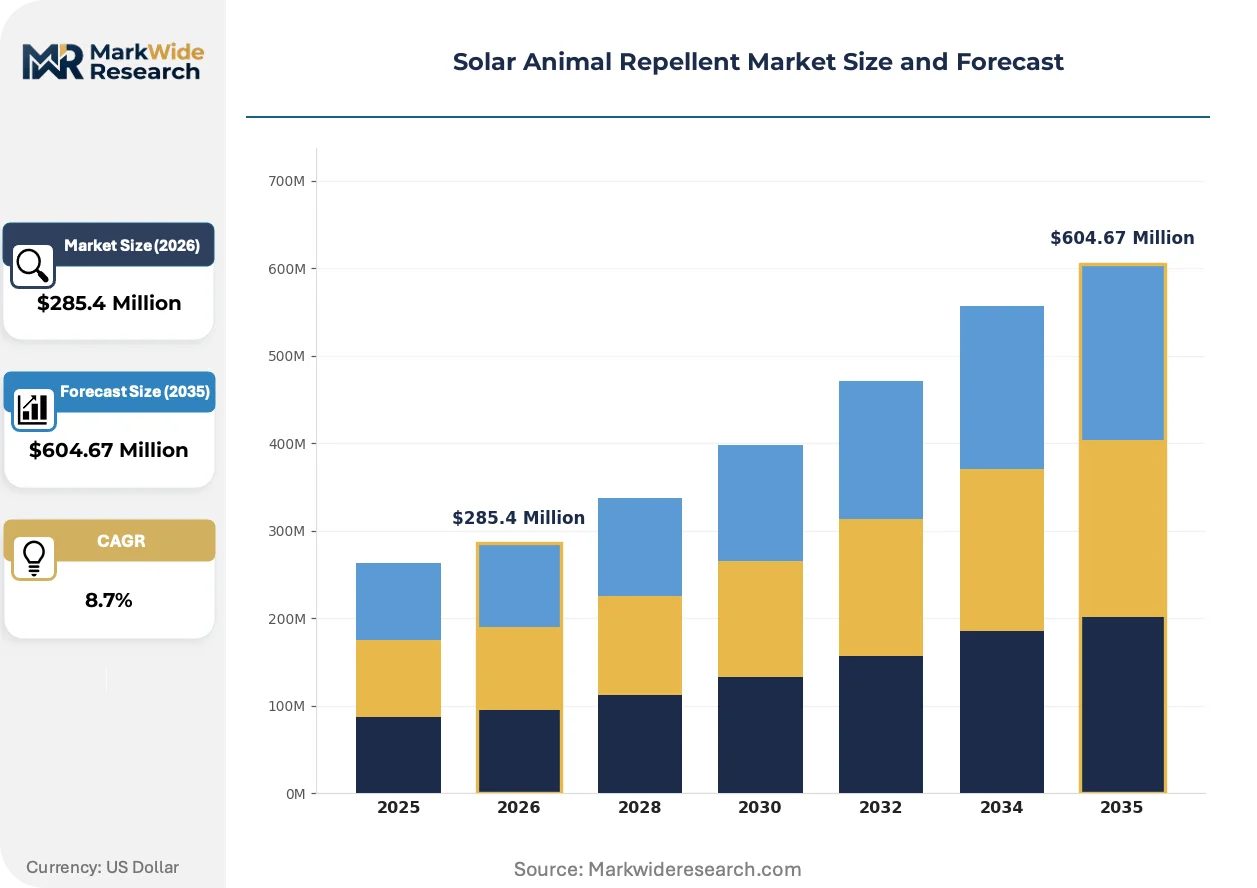
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $604.67 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ultrasonic, Visual Deterrents, LED Flashing Devices, Motion Sensors Application: Agricultural Fields, Gardens, Parks, Residential Areas Technology: Solar-Powered, Battery Operated, Wind-Powered, Hybrid Systems End User: Farmers, Homeowners, Landscape Professionals, Wildlife Managers |
| Companies Covered | Bird-X, Duranom, Amerfist, Aspectek, Hoont, PestAway, SWISSINNO, Bell & Howell, Guardian, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solar Animal Repellent Market Trends and Innovations
Motion-activated deterrent systems are integrating machine-learning classification to distinguish target species from benign wildlife, reducing false activation and preserving battery life. This intelligence layer is compressing competitive differentiation toward software rather than hardware specifications.
Edge computing modules embedded in ultrasonic emitters are automating real-time frequency adjustment based on detected animal signatures. Vineyard operators in California's Central Valley are deploying these adaptive systems to target specific pest species without disturbing pollinators. The technology is automating what previously required manual device repositioning or multiple single-purpose units.
California's Department of Pesticide Regulation maintains the nation's strictest wildlife-toxic compound restrictions, indirectly channeling municipal procurement toward solar mechanical alternatives. Landscape contractors serving public-sector clients must now document non-chemical compliance, creating specification advantages for certified solar deterrent vendors. Commercial groundskeeping segments in the state are responding by standardizing on rechargeable solar units with audit-trail capabilities.
Commercial buyers are consolidating vendor relationships and demanding multi-year service bundles that include hardware refresh guarantees. This bundling is displacing transactional e-commerce purchasing among professional landscape segments. The shift is most visible in Florida's homeowner association management sector, where centralized procurement offices now specify deterrent-as-service contracts rather than capital equipment purchases.
Solar Animal Repellent Market Segmentation
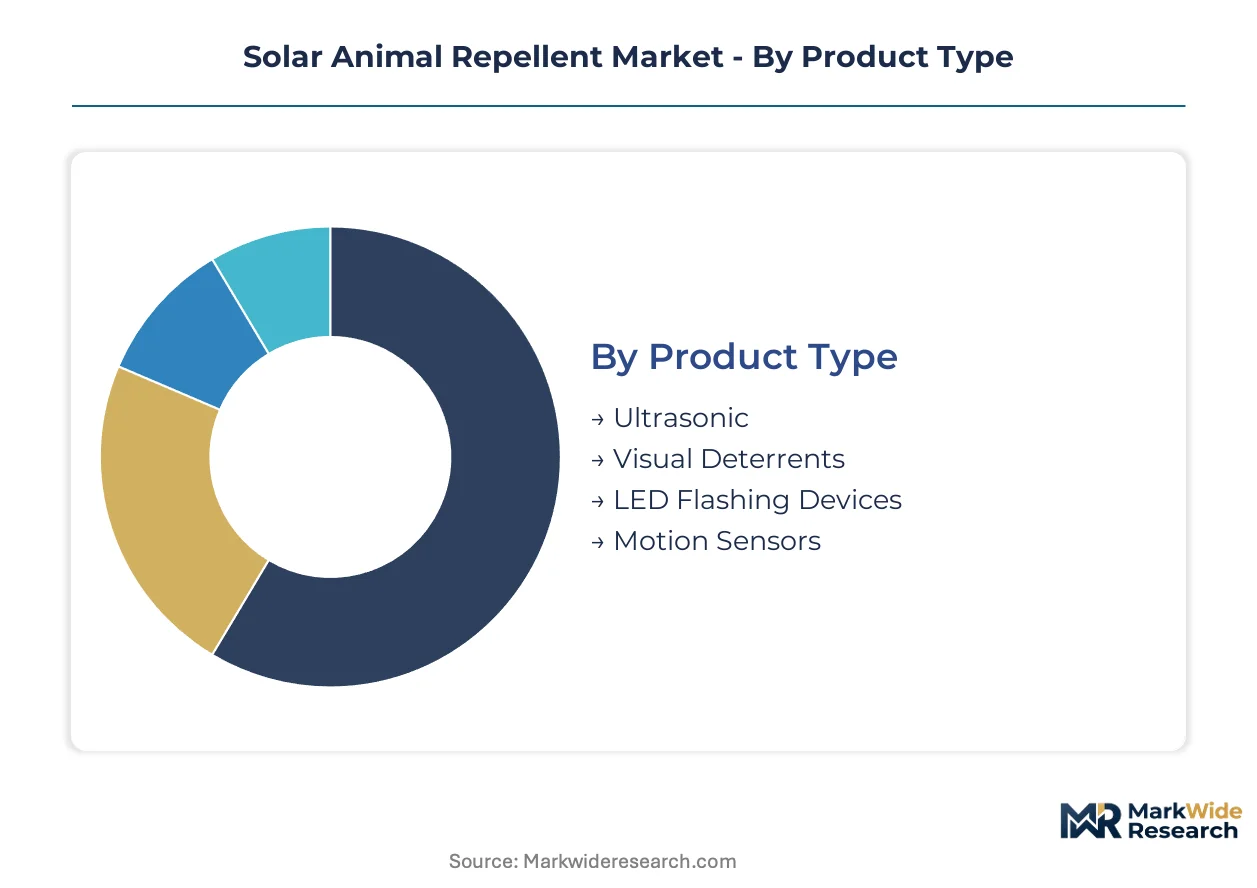
Solar animal repellent segmentation reveals divergent integration depths across product architectures. Standalone solar units dominate residential deployment, while embedded sensor networks penetrate commercial agriculture. Understanding these structural patterns clarifies where vendors must build service layers versus hardware margins.
Product Type:
Integration depth varies sharply: ultrasonic and LED devices function as standalone perimeter sentries, while motion sensors embed within broader IoT security networks.
- Ultrasonic:Photovoltaic-powered emitters generate frequencies between 15 kHz and 65 kHz, calibrated to species-specific auditory thresholds without human detection. Demand concentrates among California vineyard operators replacing chemical repellents under Department of Pesticide Regulation mandates. EPA FIFRA restrictions on wildlife-toxic compounds accelerate substitution in high-compliance states.
- LED Flashing Devices:Stroboscopic arrays target crepuscular and nocturnal species through irregular light patterns that disrupt feeding behavior. Texas and Florida suburban developments deploy these units along habitat corridors where raccoon and coyote encounters intensify. Nocturnal pest pressure in exurban corridors sustains replacement cycles.
- Visual Deterrents:Reflective tapes, predator-eye balloons, and holographic strips provide passive deterrence without power requirements. Budget-conscious homeowners in agricultural fringe zones favor these for seasonal bird control.
- Motion Sensors:PIR and microwave detection modules integrate with centralized monitoring platforms, serving wildlife managers requiring activity logging for compliance documentation. Professional landscape contractors specify these for municipal clients.
Volume placements concentrate in Ultrasonic; the faster expansion belongs to LED Flashing Devices.
Application:
Cost tier stratification separates capital-intensive agricultural deployments from discretionary residential purchases.
- Agricultural Fields:Large-scale row crop and specialty operations deploy hybrid-powered deterrent grids to protect high-value harvests. California Central Valley vineyard operators lead adoption, driven by export market residue restrictions and organic certification requirements. Consistent performance demands during low-light periods favor battery-backed solar architectures.
- Residential Areas:Single-family homeowners purchase entry-tier solar units through e-commerce channels for garden and perimeter protection. Florida homeowner association management offices now specify deterrent-as-service contracts rather than capital equipment, bundling hardware refresh guarantees.
- Gardens:Small-plot cultivators and hobbyist growers favor compact ultrasonic stakes for raised-bed protection. European garden retail channels stock these as seasonal merchandise.
- Parks:Municipal groundskeeping departments procure certified solar deterrents to satisfy non-chemical compliance documentation. Public-sector procurement standardizes on rechargeable units with audit-trail capabilities.
Revenue concentration sits with Agricultural Fields; steepest expansion trajectory runs through Residential Areas.
Technology:
Supply concentration in East Asian lithium-ion cell manufacturers shapes power architecture adoption curves.
- Solar-Powered:Standalone photovoltaic cells with integrated battery storage dominate unit shipments across all price tiers. Falling solar cell prices enable feature-rich entry devices that previously required premium positioning.
- Hybrid Systems:Battery-backed solar with grid fallback capability captures farmer segments in low-light agricultural regions requiring uninterrupted performance. Pacific Northwest and Northeast US operations specify these for winter reliability.
- Battery Operated:Disposable alkaline or rechargeable lithium configurations persist in temporary deployment scenarios and backup redundancy roles.
- Wind-Powered:Mechanical turbines drive acoustic emitters in remote off-grid locations without consistent solar irradiance. Niche applications include rangeland and backcountry installations.
Unit economics favor Solar-Powered; margin expansion concentrates in Hybrid Systems.
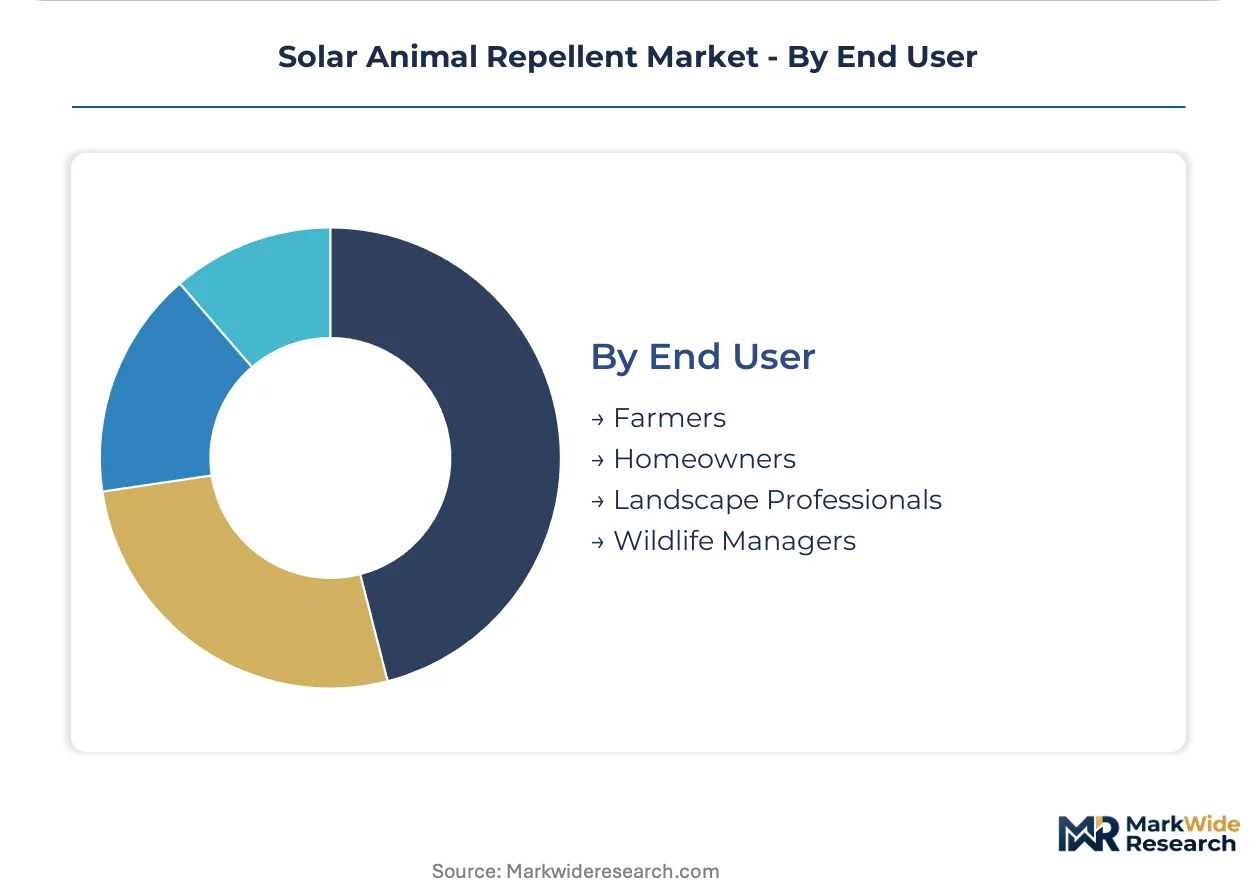
End User:
Customer type determines procurement modality: transactional e-commerce versus multi-year service contracts.
- Landscape Professionals:Commercial groundskeeping contractors consolidate vendor relationships and demand bundled service agreements with hardware refresh guarantees. This segment shifts market economics from one-time transactions to recurring revenue.
- Farmers:Agricultural producers prioritize total cost of ownership and species-specific efficacy, driving adaptive frequency systems with machine-learning classification. Edge computing modules automate real-time adjustment based on detected animal signatures.
- Homeowners:Price-sensitive residential buyers purchase through Amazon and big-box retail, with minimal service attachment and high churn rates.
- Wildlife Managers:Government and conservation agency personnel require IoT-enabled networks with activity logging for regulatory compliance and population monitoring.
Contract value peaks with Landscape Professionals; volume scale belongs to Homeowners.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing concentrates in East Asian battery cell clusters, while consumption gravity pulls toward North American and European markets facing tightening wildlife-toxic compound restrictions. This divergence shapes procurement patterns and vendor localization strategies across the forecast period.
United States
Suburban-wildlife conflict intensifies across California, Texas, and Florida as exurban development fragments habitat corridors. EPA FIFRA registration burdens on chemical repellents redirect commercial groundskeeping budgets toward solar-powered mechanical deterrents. California's Central Valley vineyard operators deploy adaptive frequency systems to satisfy Department of Pesticide Regulation mandates while protecting export-market access.
Germany
Precision agriculture adoption drives demand for IoT-enabled deterrent networks with compliance documentation capabilities. REACH restrictions on wildlife-toxic substances accelerate substitution away from chemical alternatives. Bavarian specialty crop producers integrate solar repellents into organic certification workflows to access premium European retail channels.
China
Domestic photovoltaic cell manufacturing supplies cost-competitive components to global vendor networks. Dual carbon goals under MIIT guidance encourage renewable-powered agricultural equipment deployment. Yangtze River Delta electronics clusters produce edge computing modules for species-recognition deterrent systems.
Australia
Vineyard and orchard operators face intensifying pressure from kangaroo, wallaby, and bird populations in premium wine regions. State-level environmental protection agencies restrict lethal wildlife control methods on agricultural land. South Australia's Barossa Valley and Victoria's Yarra Valley emerge as early adopters of hybrid solar-grid deterrent architectures for vintage protection.
United Kingdom
Post-Brexit agricultural subsidy restructuring prioritizes environmental stewardship and non-chemical pest management. Defra's Sustainable Farming Incentive channels capital toward renewable-powered wildlife deterrents. English vineyard expansion in Kent and Sussex generates specification demand for audit-trail-capable solar systems.
Solar Animal Repellent Market Competitive Landscape
Top-tier vendors anchor technology leadership through acoustic R&D and IoT integration, while mid-tier fabricators compete on channel access and geographic specialization. The vendor base stratifies across three tiers: multinational deterrent specialists with subscription service platforms, regional garden equipment distributors with private-label solar lines, and direct-to-consumer e-commerce brands optimizing for algorithmic visibility. Consolidation pressure intensifies as commercial buyers demand multi-year service bundles with hardware refresh guarantees.
Within the specialist tier, Bird-X exemplifies acoustic technology leadership through sustained ultrasonic R&D investment, while Duranom occupies a position anchored in European garden retail channel dominance. Amerfist represents the e-commerce optimization archetype with aggressive platform control across North American digital marketplaces. These three vendors illustrate divergent competitive vectors: proprietary frequency libraries versus retail footprint density versus algorithmic merchandising efficiency.
| Leading Market Players |
|---|
| Bird-X |
| Duranom |
| Amerfist |
| Aspectek |
| Hoont |
| PestAway |
| SWISSINNO |
| Bell & Howell |
| Guardian |
| Others |
Pricing and Supply Chain Analysis
Lithium-ion cell costs cascade through solar animal repellent pricing tiers, with East Asian battery pack sourcing anchoring landed costs for North American and European vendors while photovoltaic module deflation compresses entry-tier hardware margins.
Pricing Analysis
Cost-down pressure on residential-grade units accelerates because falling solar cell prices enable feature-rich entry devices that previously required premium positioning. Three-tier pricing structure across premium, standard, and economy levels separates adaptive frequency systems with machine-learning classification from basic ultrasonic stakes and passive visual deterrents. Price differentiation rests on certification grade—California Department of Pesticide Regulation compliance documentation commands premium positioning—and after-sales service bundling. Homeowners exhibit highest price sensitivity through Amazon and big-box retail channels, while landscape professionals prioritize total cost of ownership in multi-year service contracts.
Supply Chain Analysis
Direct-to-retail channels handle residential volume through Amazon and garden center networks, while direct-to-contractor relationships serve commercial groundskeeping procurement offices. Manufacturing concentrates in China's Yangtze River Delta electronics clusters for edge computing modules and photovoltaic cell fabrication, with South Korean and Japanese lithium-ion cell suppliers feeding battery pack assembly. Raw material dependencies span polysilicon for solar cells, rare earth elements for ultrasonic transducers, and cobalt-nickel cathode formulations for energy storage. Single-source vulnerability in East Asian battery cell manufacturers exposes vendors to input volatility during demand surges. Distribution runs through specialized garden equipment distributors in Europe and platform-optimized e-commerce fulfillment in North America.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is becoming a vertical-integration race as vendors pursue captive supply of lithium-ion cells and proprietary acoustic frequency libraries to escape commodity hardware margins.
For Market Incumbents: Extend subscription monitoring service penetration among Florida homeowner association management offices to lock in recurring revenue before hardware commoditization accelerates. Deepen backward integration into photovoltaic module sourcing to offset East Asian cell manufacturer pricing power. Fortify firmware security certification capabilities under emerging state-level connected device mandates to extend product launch timelines for challengers. For New Entrants and Emerging Players: Begin with LED flashing devices targeting nocturnal pest pressure in Texas and Florida suburban corridors, the fastest-expanding product segment with lower acoustic R&D barriers than ultrasonic alternatives. Exploit municipal procurement standardization on rechargeable units with audit-trail capabilities in California parks departments. Pursue vineyard operator direct sales in Australia's Barossa Valley where hybrid solar-grid architectures face limited incumbent penetration. For Investors and Strategic Acquirers: EPA FIFRA registration burden escalation is the leading indicator that chemical repellent displacement will sustain hardware refresh demand across the analysis window. Target acquisition candidates with proprietary bioacoustics expertise and existing cloud-connected deterrent networks. Monitor California Department of Pesticide Regulation enforcement actions as the signal for compliance-driven substitution velocity in the largest US state market.| Strategic Initiative | Industry Significance |
|---|---|
| Subscription Monitoring Service Launch | Recurring revenue layers improve customer lifetime value among landscape professionals in Florida and California. |
| Hybrid Power Architecture Development | Battery-backed solar with grid fallback captures farmer segments in Pacific Northwest and Northeast US low-light regions. |
| Acoustic R&D Talent Acquisition | Species-specific frequency optimization capabilities differentiate ultrasonic systems from commodity LED alternatives. |
| Channel Control Investment | European garden retail footprint density defends margin position against algorithmic e-commerce entrants. |
| Firmware Security Certification | IoT cybersecurity validation extends product launch timelines and raises barriers for unconnected hardware competitors. |
Research Methodology
Trade association filings, customs import records, and EPA FIFRA registration databases formed the secondary backbone, cross-referenced against primary interviews with commercial groundskeeping contractors, vineyard operations managers, municipal procurement officers, and lithium-ion battery supply planners. Bottom-up and top-down triangulation validated shipment volumes and pricing tiers across ultrasonic, LED flashing, and hybrid system categories.
Bottom-up modeling aggregated unit economics by product architecture and end-user segment, while top-down demand estimation calibrated against agricultural census data and suburban development permits in California, Texas, and Florida. Segmentation dimensions spanned product type, application, power technology, and customer procurement modality across the projection horizon. CAGRs derived from logistic diffusion curves fitted to regulatory substitution patterns and photovoltaic cost compression trajectories. Species-specific efficacy data and municipal noise ordinance adoption rates served as industry-specific forecast inputs.
Underlying measurement precision varies by segment; subscription service revenue and IoT-enabled network deployments carry tighter precision than discretionary residential e-commerce transactions. Forecasts reflect assumptions around EPA enforcement continuity, lithium-ion supply chain stability, and machine-learning classification adoption in agricultural settings. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Smart Home and Office Market
Others
Conditional Access System (CAS) Market
Others
Induced Pluripotent Stem Cells (Ipscs) Market
Others
Indoor LBS Market
Others
Document Camera Market
Others
South Korea Smart Home Market
Others
Brazil Cane Sugar Market
Others
GCC Cigarette Market
Others
Europe Digital Experience Platform Market
Others
Bitcoin Mining Hardware Market
Others
Industrial Gauges Market
Others
North America 3D Printing Construction Market
Others
Smart Badge Market
Others
Basketball Apparel Market
Others
Digital Thermal Plates Market
Others
Coalescing Filter Market