
 Global Smart Home Installation Service Market | 2026-2036
Global Smart Home Installation Service Market Size, Share, and Industry Trends Forecast 2026-2036
Global Smart Home Installation Service Market Intelligence
The EU Green Deal is realigning European building codes toward mandatory energy management and connected infrastructure, forcing retrofit demand across residential stock. Vivint Inc. dominates the North American subscription-installation model through its captive technician network. Comcast Corporation leverages its broadband subscriber base to bundle smart home configuration with connectivity services. HelloTech Inc. competes on gig-economy dispatch speed, covering same-day deployment in major metropolitan zones.
Smart home installation service encompasses the professional design, wiring, configuration, and commissioning of integrated residential automation systems, typically requiring low-voltage electrical certification and network topology expertise to ensure interoperability across device ecosystems. The primary commercial purpose is to translate fragmented consumer hardware into reliable, unified systems that reduce energy consumption and operational friction. Security system setup and HVAC integration currently anchor revenue as homeowners prioritize safety and climate optimization, while cloud-enabled platforms represent the fastest-growing deployment mode as remote monitoring and over-the-air firmware management become standard expectations. Zigbee and Thread Protocol are gaining protocol share as the Connectivity Standards Alliance pushes Matter interoperability, displacing earlier Wi-Fi-dependent configurations that suffered from congestion and power inefficiency.
FCC Part 15 regulations in the United States govern unlicensed radio frequency emissions from wireless smart home devices, directly shaping which protocols installers may legally deploy. Ecodesign requirements under the EU Green Deal and REACH substance restrictions constrain hardware selection and wiring materials available to European service providers. China's GB standards and MIIT radio transmission rules set certification barriers for imported equipment, favoring domestic installation ecosystems. Stakeholders must monitor regulatory divergence across these three jurisdictions to anticipate certification costs and protocol compatibility requirements that will determine which installation networks can scale profitably.
Market Dynamics
The Matter interoperability standard from the Connectivity Standards Alliance is consolidating previously fragmented device ecosystems, forcing installation networks to retrain technicians on unified commissioning protocols or face margin compression from callback rates on incompatible hardware pairings.
Growth Catalysts
- EU Green Deal building mandates:Mandatory energy management system requirements across residential retrofits are creating sustained demand for electrification and connected infrastructure deployment.
- Multi-unit residential developers:Property developers in Germany and China are pre-installing smart home infrastructure as competitive differentiation in new construction.
- Cloud-enabled remote management:Over-the-air firmware updates and remote monitoring capabilities are reducing truck-roll costs and expanding addressable service territories for installation providers.
Market Restraints
- Low-voltage electrician supply constraints:Certification bottlenecks in the United States and Germany limit technician pool expansion, constraining network scaling velocity.
- Copper and semiconductor input volatility:Wiring materials and radio module costs fluctuate with commodity markets, compressing fixed-price installation margins.
- Protocol transition friction:Legacy Z-Wave and proprietary Wi-Fi installations face stranded asset risk as Thread and Zigbee gain protocol share under Matter.
Strategic Opportunities
- Aging housing stock in Germany:Energy efficiency retrofit mandates targeting pre-1990 residential buildings represent underpenetrated installation volume for integrated HVAC and lighting automation.
- Utility-channel bundling:Electricity and gas providers are white-labeling smart home configuration as customer retention tools, opening B2B2C distribution paths.
- Convergence of solar-plus-storage with home automation:Bidirectional EV charging and battery management integration requires specialized commissioning expertise that general electrical contractors lack.
Industry Challenges
- Network topology certification gaps:Installers lack standardized credentials for multi-protocol mesh configuration, leading to interoperability failures and warranty disputes.
- Cross-border equipment compliance:FCC Part 15, EU REACH, and MIIT radio rules create divergent certification costs that fragment procurement for multinational service networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Smart Home Installation Service Market |
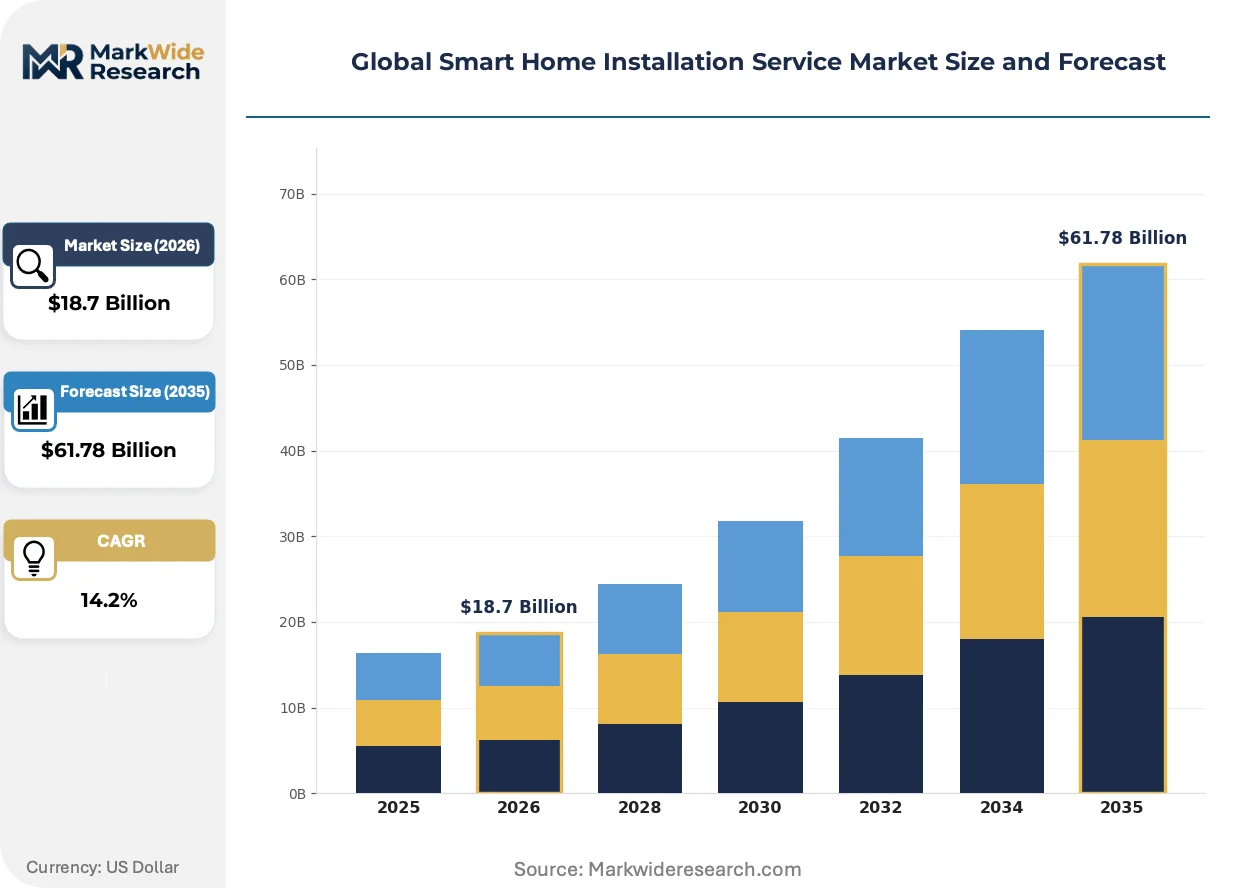
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $61.78 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Security System Setup, Lighting Control Installation, HVAC Integration, Audio Video Configuration, Appliance Automation Customer Type: Homeowners, Property Developers, Commercial Establishments, Facility Managers Deployment Mode: Wired Systems, Wireless Systems, Hybrid Networks, Cloud-Enabled Platforms Technology: Zigbee, Z-Wave, Wi-Fi, Bluetooth LE, Thread Protocol |
| Companies Covered | Calix Inc., HelloTech Inc., Red River Electric Inc., Vivint Inc., Insteon Inc., ADT Inc., Comcast Corporation, Handy Technologies, Inc., Puls Technologies Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Smart Home Installation Service Market Strategic Shifts & Innovations
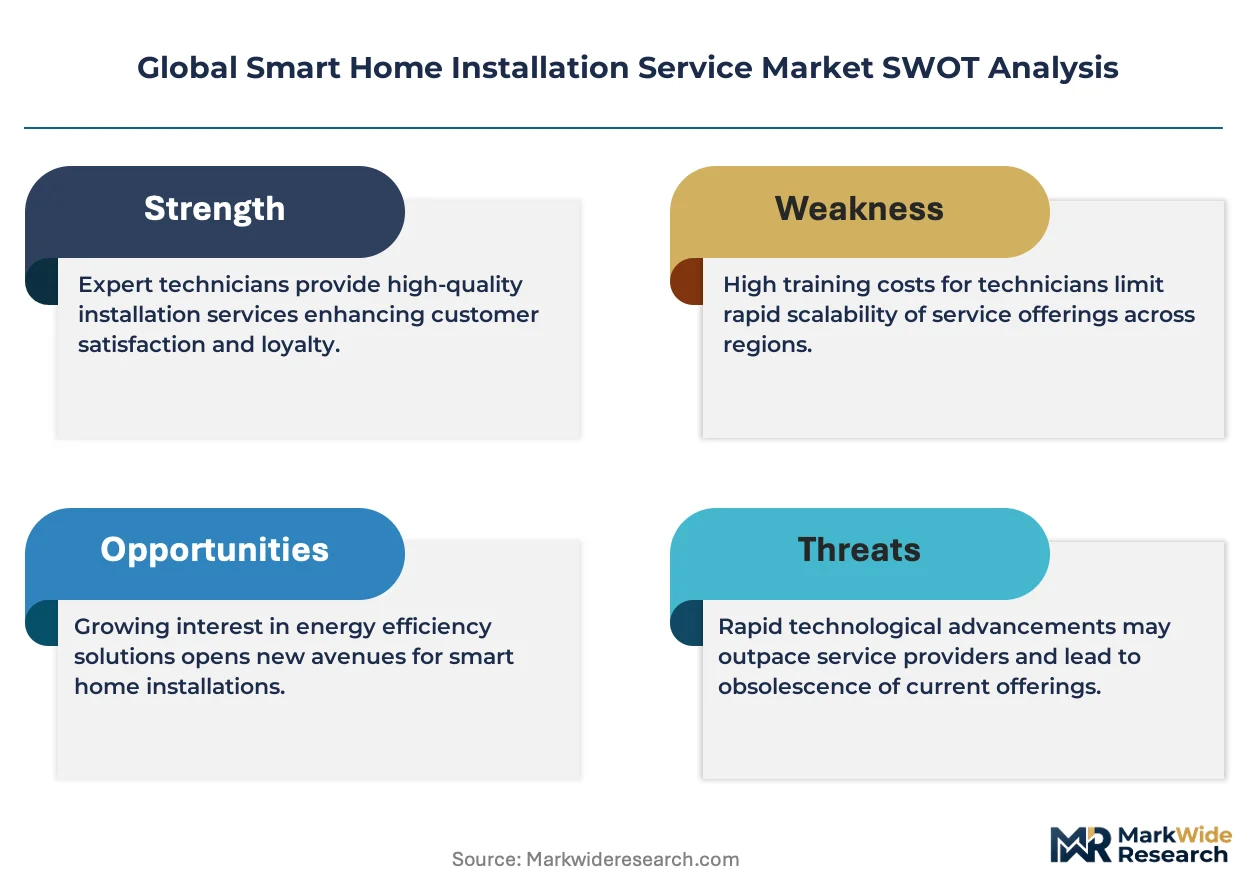
Installation service models are pivoting from hardware-margin dependence toward recurring revenue architectures, with technician expertise becoming the scarce asset that determines competitive positioning across metropolitan markets.
Thread protocol is overtaking legacy Wi-Fi-dependent configurations in new residential deployments. The low-power mesh topology eliminates congestion failures that plagued earlier installations. Multi-unit developers in Shenzhen and Austin are specifying Thread-native hardware to reduce callback rates. This protocol shift is overtaking the premium pricing power of Wi-Fi-specialized installers who lack mesh commissioning credentials.
REACH substance restrictions under the EU Green Deal are constraining wiring insulation and solder materials available to European service providers. The ECHA enforcement timeline is accelerating substitution toward halogen-free alternatives. German installation networks are absorbing compliance costs through supplier consolidation, while smaller operators face equipment write-downs on non-compliant inventory.
Homeowner purchasing for smart home services is fragmenting across direct-to-installer platforms, utility partnerships, and builder pre-installation channels. The traditional security-dealer model faces disintermediation from gig-economy dispatch apps and telecom bundling. This channel proliferation is most visible in United States metropolitan markets where Vivint and Comcast compete against HelloTech and regional electrical contractors for the same retrofit projects.
Global Smart Home Installation Service Market Segmentation
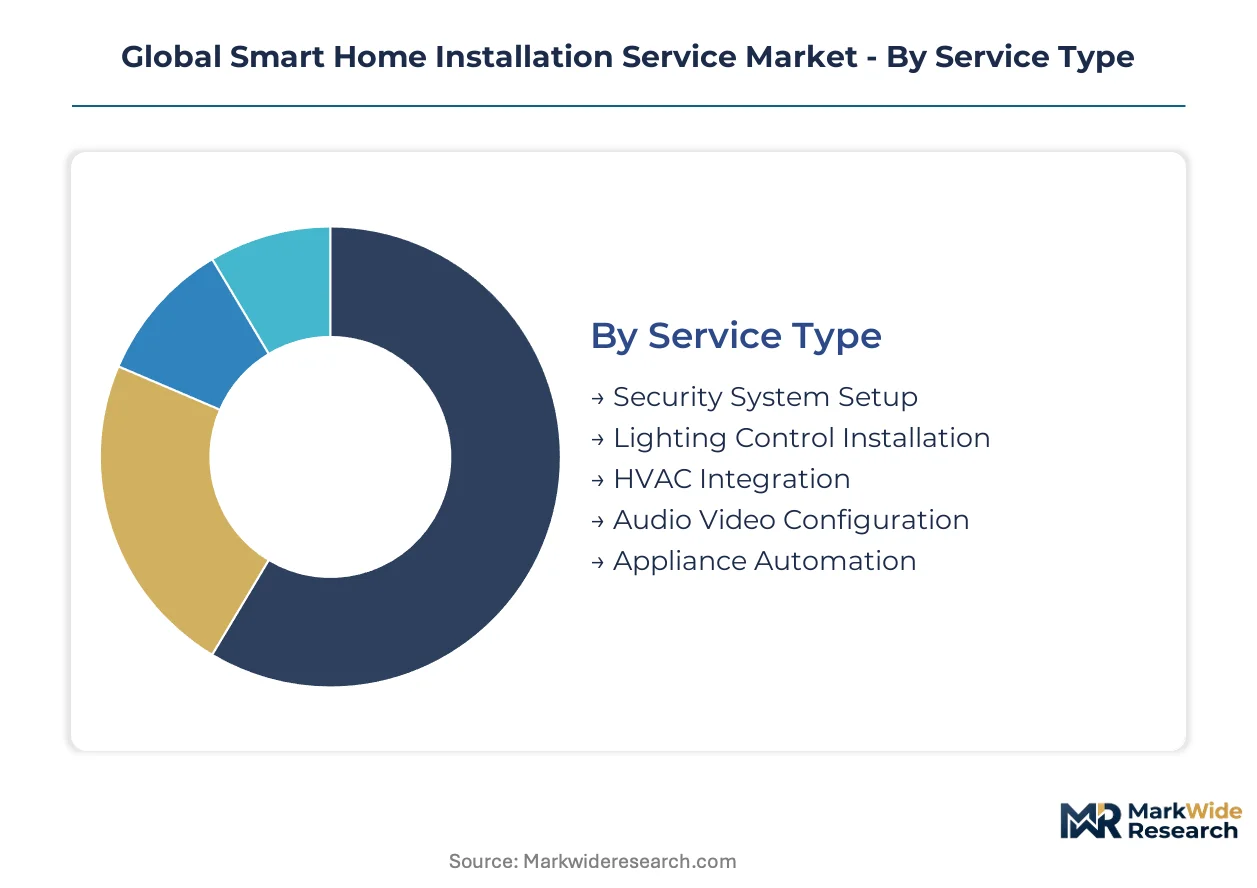
Smart home installation service providers must align technician certification and inventory with distinct service workflows, customer procurement patterns, and protocol ecosystems. Segmentation reveals where margin concentrates versus where volume scales across residential and commercial deployment contexts.
Service Type:
Volume concentrates in entry-level safety and comfort automation, while premium margins attach to multi-zone entertainment and whole-home integration projects.
- Security System Setup:Door, window, and motion sensor installation with central monitoring integration. Demand clusters in suburban United States retrofit markets where Vivint and Comcast compete for recurring monitoring subscriptions.
- HVAC Integration:Thermostat programming, zone control wiring, and energy management commissioning. German property developers specify these services to meet EU Green Deal efficiency mandates in multi-unit new construction.
- Lighting Control Installation:Dimmer circuits, scene programming, and daylight harvesting configuration. Shenzhen installers report rising specification in luxury residential towers.
- Audio Video Configuration:Multi-room streaming, home theater calibration, and acoustic treatment. Austin and Los Angeles metropolitan zones show concentration in custom integration.
- Appliance Automation:Smart refrigerator, oven, and laundry connectivity setup. White-glove delivery channels in China bundle this with premium appliance sales.
Today's leader: Security System Setup. Tomorrow's challenger: HVAC Integration.
Customer Type:
Procurement authority and project scale diverge sharply between individual decision-makers and institutional buyers with standardized specifications.
- Property Developers:Pre-installation contracts for multi-unit residential towers in Germany and China. These buyers demand Thread-native hardware to minimize callback liability.
- Homeowners:Retrofit projects triggered by insurance discounts or utility rebate programs. United States metropolitan markets show fragmentation across direct-to-installer platforms and telecom bundling.
- Facility Managers:Commercial building automation with centralized monitoring requirements. REACH compliance constraints shape European procurement.
- Commercial Establishments:Retail and hospitality deployments prioritizing energy management and occupancy analytics.
Property Developers capture the steepest expansion trajectory as pre-installation becomes competitive standard.
Deployment Mode:
Cost structure and technician skill requirements vary by infrastructure permanence and remote manageability.
- Cloud-Enabled Platforms:Over-the-air firmware management and remote diagnostics. This architecture expands addressable territories for installation networks by reducing truck-roll frequency.
- Hybrid Networks:Critical loads on wired backbone with wireless sensor extensions. German energy retrofit projects favor this for reliability.
- Wired Systems:Low-voltage structured cabling for new construction. Copper price volatility compresses fixed-quote margins.
- Wireless Systems:Battery-powered sensor mesh for rental properties and historic buildings. FCC Part 15 and MIIT radio rules constrain protocol selection.
Cloud-Enabled Platforms are gaining share fastest against legacy wired configurations.
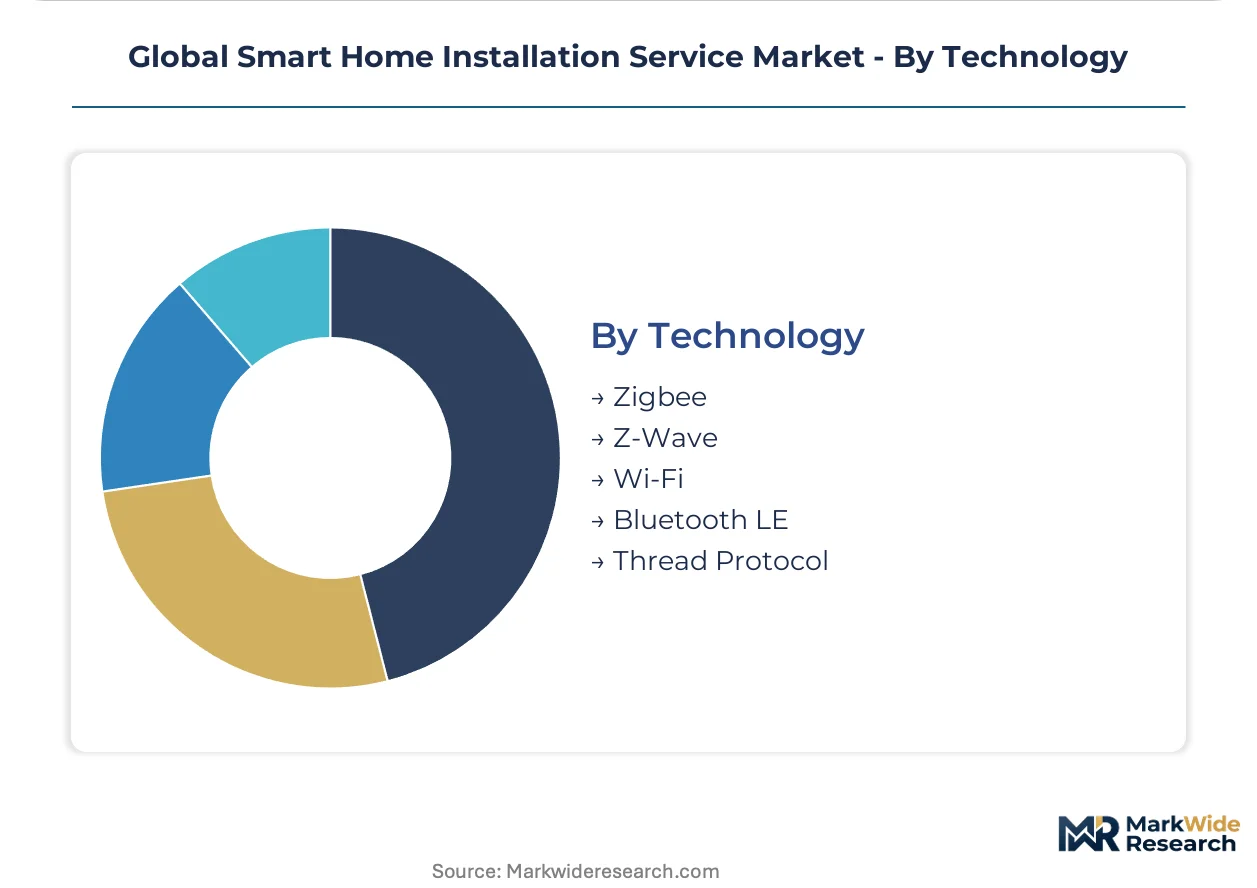
Technology:
Protocol choice determines installer certification requirements, equipment procurement, and interoperability warranty exposure.
- Thread Protocol:Low-power mesh with native IP addressing and Matter interoperability. Shenzhen and Austin developers specify Thread to eliminate congestion failures.
- Zigbee:Established mesh standard with broad device ecosystem. European networks retrain technicians as Matter consolidation proceeds.
- Z-Wave:Sub-GHz proprietary mesh facing stranded asset risk as Thread gains specification share.
- Wi-Fi:High-bandwidth configurations for video streaming devices. Power inefficiency and congestion limit whole-home deployment.
- Bluetooth LE:Point-to-point commissioning and proximity-based automation. Apple HomeKit ecosystems favor this for device onboarding.
Thread Protocol leads new specification. Zigbee defends installed base through Matter bridging.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States pioneered the subscription-based smart home installation model through security-dealer networks that scaled across suburban markets. Professional technician pools concentrated in metropolitan corridors as recurring revenue architectures replaced one-time hardware margins. Germany and China subsequently developed distinct regulatory-driven installation ecosystems.
United States
Suburban retrofit demand clusters around insurance discount programs and utility rebate incentives. FCC Part 15 regulations govern unlicensed radio frequency emissions from wireless devices, directly shaping protocol selection for installers. Technician networks concentrate in Austin and Los Angeles metropolitan zones where custom integration projects for multi-zone entertainment systems command premium pricing.
Germany
Energy efficiency retrofit mandates targeting pre-1990 residential buildings drive HVAC integration and lighting automation demand. Ecodesign requirements under the EU Green Deal constrain hardware selection and wiring materials through REACH substance restrictions. Installation networks in Bavaria and North Rhine-Westphalia absorb compliance costs through supplier consolidation while smaller operators face equipment write-downs.
China
Property developers in Shenzhen and Beijing-Tianjin-Hebei pre-install Thread-native smart home infrastructure as competitive differentiation in luxury residential towers. MIIT radio transmission rules and GB standards set certification barriers favoring domestic installation ecosystems. Pearl River Delta manufacturers supply halogen-free wiring alternatives as ECHA-style enforcement timelines accelerate material substitution.
United Kingdom
Utility-channel bundling of smart home configuration accelerates through electricity and gas provider white-label partnerships. GDPR compliance requirements shape data handling protocols for cloud-enabled remote management platforms. London and Southeast England installation networks compete on same-day dispatch speed against gig-economy dispatch applications.
Japan
Aging housing stock and energy efficiency targets create retrofit opportunities for integrated climate and security systems. METI efficiency standards and JIS certification requirements structure technician credentialing for low-voltage mesh configuration. Kanto region installers develop specialized expertise in bidirectional EV charging integration with home automation controllers.
Global Smart Home Installation Service Market Key Industry Players
Premium-margin players sit above commodity-margin players across certification depth and protocol specialization. The vendor base stratifies into three tiers: captive technician networks with recurring subscription models, gig-economy dispatch platforms optimizing for deployment velocity, and telecom-bundled service providers leveraging broadband subscriber bases. Dominant competitive moves include strategic partnerships with utility providers for B2B2C distribution and vertical integration into cloud-enabled remote management platforms to reduce truck-roll costs.
Within the subscription-installation tier, Vivint Inc. and Comcast Corporation exemplify divergent approaches to customer acquisition—one through proprietary technician networks, the other through broadband bundling. HelloTech Inc. occupies a position in the gig-economy dispatch segment where same-day metropolitan coverage determines competitive positioning. ADT Inc. anchors the traditional security-dealer archetype facing disintermediation pressure from channel proliferation.
| Leading Market Players |
|---|
| Calix Inc. |
| HelloTech Inc. |
| Red River Electric Inc. |
| Vivint Inc. |
| Insteon Inc. |
| ADT Inc. |
| Comcast Corporation |
| Handy Technologies, Inc. |
| Puls Technologies Inc. |
| Others |
Cost & Logistics Intelligence
Thread protocol migration and Matter interoperability standardization are compressing hardware margins while concentrating procurement power among certified technician networks that can warranty multi-protocol mesh configurations. Copper price volatility and semiconductor module costs feed directly into project quoting, forcing installation providers to index material costs or absorb margin risk on fixed-price contracts.
Pricing Analysis
Subscription-recurring models with hardware financing dominate the United States market, while project-based transactional pricing prevails in German retrofit markets. Price differentiation rests on technician certification tier and after-sales service bundling, with Matter-certified installers commanding premium rates over legacy Z-Wave specialists. Pricing pressure intensifies in entry-level security installations as telecom bundling and gig-economy dispatch platforms compress acquisition economics. Property developers show lowest price sensitivity due to callback liability concerns, while individual homeowners in metropolitan United States markets exhibit highest sensitivity to upfront hardware costs.
Supply Chain Analysis
MIIT radio certification requirements and China's GB standards are reshaping sourcing toward domestic Chinese radio module suppliers for installation networks targeting East Asian deployment. Component supply draws from China, Taiwan, and South Korea for Thread and Zigbee radio modules, copper wiring from Chile and Peru, and halogen-free insulation materials from German chemical suppliers. Single-source vulnerability concentrates in advanced radio chipsets where TSMC fabrication capacity constrains global availability. Distribution runs through manufacturer-direct channels for large property developers, regional electrical wholesalers for retrofit contractors, and platform-integrated procurement for gig-economy dispatch services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Installation service markets reward geographic arbitrage between German regulatory compliance costs and United States subscription-margin expansion, with technician certification differentials creating structurally divergent returns across these two demand centers.
For Market Incumbents: To counter gig-economy dispatch platform disintermediation, Vivint and Comcast should deepen captive technician network density in Austin and Los Angeles metropolitan zones where custom integration premiums persist. Backward integration into cloud-enabled remote management platforms reduces truck-roll costs and expands addressable territories beyond current metropolitan footprints. Certification investment in Thread and Matter protocols protects margin position against callback liability from incompatible hardware pairings.
For New Entrants and Emerging Players: The gap between premium whole-home integration and economy security-only installations creates entry space for mid-tier HVAC-focused specialists in German energy retrofit markets. White-label utility partnerships in the United Kingdom offer the most penetrable channel structure, with electricity and gas providers seeking customer retention tools. Direct-to-installer platform models targeting same-day metropolitan dispatch can capture price-sensitive homeowners disintermediated from traditional security dealers.
For Investors and Strategic Acquirers: Valuations sit cheapest among regional electrical contractors with Matter certification gaps but established customer relationships in aging housing stock markets. Long-term viability over the next decade hinges on technician network scalability and protocol transition completion. The inflection signal to watch is utility-channel bundling penetration rates, which indicate whether B2B2C distribution can sustain recurring revenue architectures against direct-to-consumer platform competition.
| Strategic Initiative | Industry Significance |
|---|---|
| Technician Certification Investment | Matter protocol credentials reduce callback liability and protect premium pricing in multi-unit developer contracts. |
| Cloud Platform Integration | Remote diagnostics capability expands serviceable territory beyond metropolitan technician density constraints. |
| Utility Partnership Development | White-label B2B2C channels capture customer acquisition economics that direct-to-consumer models cannot match. |
| Backward Integration into Hardware | In-house radio module procurement mitigates semiconductor supply volatility and MIIT certification delays. |
| Geographic Expansion to German Retrofit Markets | EU Green Deal mandates create sustained installation volume for HVAC and lighting automation specialists. |
Research Approach
Coverage spans the United States, Germany, China, the United Kingdom, and Japan, with primary inputs from each market's regulatory and competitive context. The research combines structured interviews with low-voltage installation network managers, smart home platform engineering leads, property developer procurement officers, and utility partnership directors with secondary validation through FCC Part 15 filings, ECHA REACH substance restriction updates, MIIT radio transmission rule publications, and Connectivity Standards Alliance Matter certification records. Bottom-up technician network capacity estimates and top-down construction permitting data provide triangulation anchors.
Rate-of-change decomposition separates volume expansion from value-per-installation trends across the analysis window. Segmentation dimensions modeled include service type, customer procurement authority, deployment mode infrastructure permanence, and protocol ecosystem. CAGRs derive from technician pool growth constraints, retrofit mandate enforcement timelines, and multi-unit residential construction forecasts. Industry-specific inputs include copper futures price trajectories and Matter device certification velocity.
Caveats apply where semiconductor supply disruptions, regulatory divergence between FCC Part 15 and MIIT radio rules, or protocol transition delays could materially shift the outlook. Forecasts reflect assumptions about technician certification pipeline throughput and property developer specification stickiness. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Global Essential Oils and Plant Extracts for Livestock Market
Others
Wearable Solar Devices Market
Others
Global Aircraft Sensors Market
Others
Storage Dewars Market
Others
Sunflower Husk Pellets Market
Others
Global Cigarette Packaging Market
Others
Global Smart Kitchen Market
Others
Global Luxury High End Furniture Market
Others
Middle East & Africa Air Insulated Switchgear Market
Others
Surface Green Mining Market
Others
Global Military Apparel Market
Others
Free Space Optics (FSO) Market
Others
Belt Press Filter Market
Others
Vegan Confectionery Market
Others
France 3D Printing Construction Market
Others
Managed Testing Services Market