
 Durian Market | 2026-2036
Durian Market Size, Share, and Industry Trends Forecast 2026-2036
Durian Market Analytics
Cold chain logistics standardization is narrowing the quality gap between fresh and frozen durian, enabling year-round commercial distribution previously limited by seasonal harvest windows. Top Fruits Sdn Bhd leverages integrated plantation-to-port operations across Peninsular Malaysia. Hernan Corporation anchors its position through specialized vacuum-freezing technology for puree preservation. Charoen Pokphand Group dominates Thai domestic procurement networks while extending processing capacity for industrial buyers.
Durian, the fruit of Durio zibethinus and related species, contains 27-30% carbohydrates, 2-3% protein, and distinctive sulfur-volatile compounds that define its sensory profile; processors flash-freeze arils at minus 40 degrees Celsius to preserve texture for industrial formulation. Fresh durian commands premium positioning in wholesale channels serving Chinese import markets, while frozen durian and puree segments capture expanding margin pools from beverage production and dessert applications. Durian chips occupy a mature niche with limited growth acceleration compared to puree derivatives.
Thailand's Ministry of Agriculture and Cooperatives enforces export phytosanitary standards aligned with China's General Administration of Customs requirements for fresh durian shipments. Malaysia's Department of Agriculture admingrades certification through Grade A and Organic classifications that determine market access tiers. Stakeholders must monitor evolving cold chain compliance thresholds and quality grade specifications as processing technology reshapes procurement criteria across industrial buyer segments.
Market Dynamics
Flash-freezing at minus 40 degrees Celsius is compressing seasonal supply windows into year-round distribution, eliminating the historical harvest-dependent scarcity that structured durian pricing and procurement.
Growth Catalysts
- China's General Administration of Customs phytosanitary protocols:Thailand's tightened export certification for fresh shipments creates quality-tier differentiation that validates premium positioning in cross-border trade.
- Industrial dessert formulation:Southeast Asian food manufacturers are embedding durian puree into ice cream, pastry, and confectionery product lines at accelerating scale.
- Vacuum-freezing technology:Puree preservation systems are extending shelf stability for processors serving beverage production facilities across Malaysia and Vietnam.
Market Restraints
- Input cost volatility:Fresh durian procurement prices fluctuate with monsoon-dependent harvest yields in Thai and Malaysian plantation zones.
- Supply concentration risk:Grade A fresh durian for Chinese wholesale channels concentrates in Thailand's eastern provinces and Peninsular Malaysia's Pahang region.
- Technical limitation:Sulfur-volatile compound degradation during conventional freezing degrades sensory profiles that industrial buyers require for consistent formulation.
Strategic Opportunities
- Vietnam's underpenetrated processing infrastructure:Industrial buyers are establishing toll-processing arrangements with Vietnamese cold chain operators to diversify supply origins.
- EU Green Deal-aligned organic certification:Malaysia's Department of Agriculture Organic classification opens duty-advantaged channels into European specialty food distribution.
- E-commerce direct-to-consumer frozen durian:Chinese cross-border platforms are disintermediating traditional wholesale layers for packaged aril segments.
Industry Challenges
- Cold chain technician scarcity:Minus 40 degrees Celsius flash-freezing operations require certified equipment specialists that plantation-to-port operators struggle to recruit.
- Phytosanitary compliance timeline compression:Thailand's Ministry of Agriculture export certification windows create shipment scheduling conflicts with Chinese import clearance cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Durian Market |
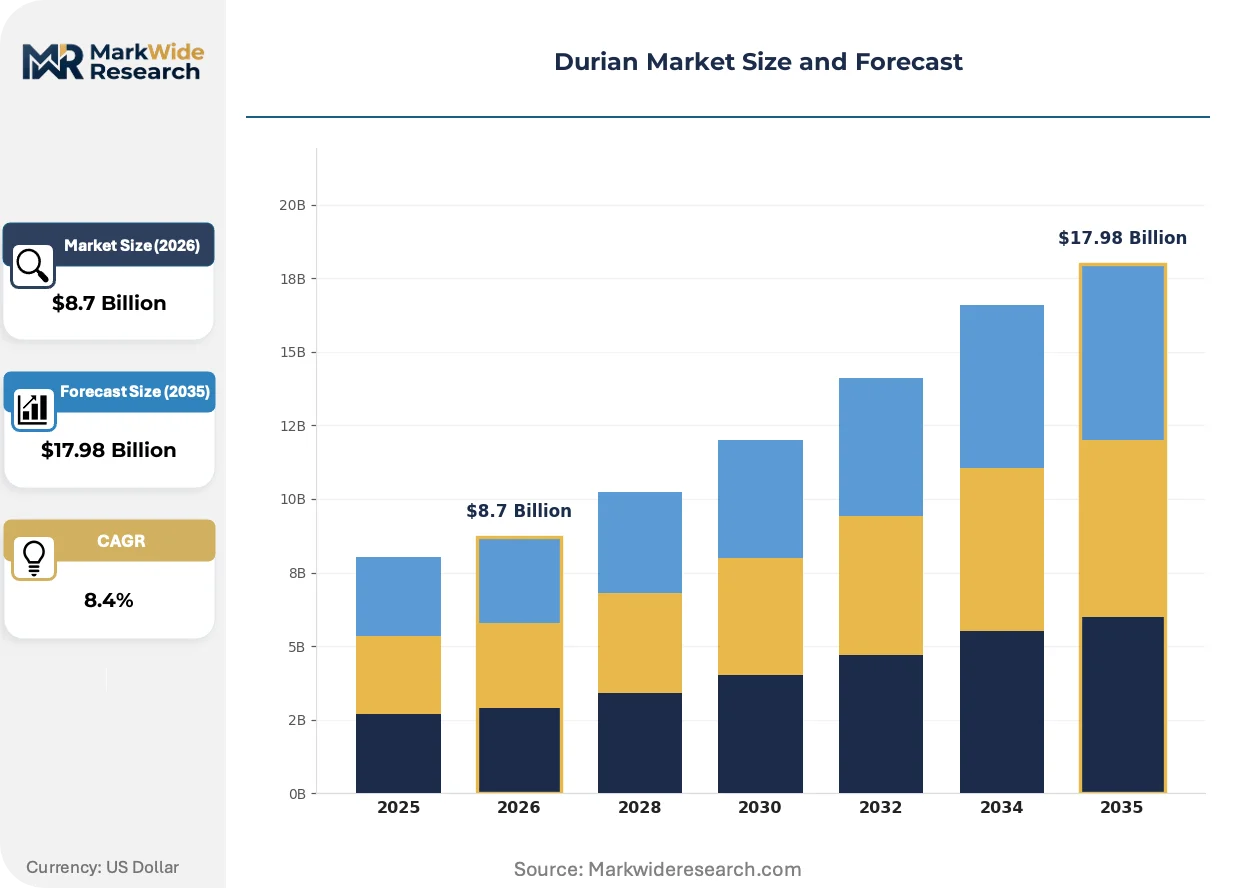
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $17.98 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fresh Durian, Frozen Durian, Durian Puree, Durian Chips End Use: Food Industry, Dessert Applications, Snacks, Beverage Production Distribution Channel: Supermarkets, Online Retail, Local Markets, Wholesale Quality Grade: Grade A, Grade B, Organic, Conventional |
| Companies Covered | Top Fruits Sdn Bhd, Hernan Corporation, Charoen Pokphand Group, Chainoi Food Company Limited, Interfresh Co., Ltd., Thai Agri Foods Public Company Limited, TRL (South East Asia) Sdn Bhd, Grand World International Co., Ltd., Sunshine International Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Durian Market Evolving Landscape
Processing technology and regulatory harmonization are converging to restructure how durian moves from plantation to industrial formulation, with digitization and compliance automation as central vectors.
Blockchain-enabled provenance tracking is digitizing supply chain transparency for Chinese import inspectors and industrial buyers. Major Thai exporters are deploying distributed ledger systems to document plantation origin, harvest date, and cold chain handoff points. This technology is digitizing the audit trail that China's General Administration of Customs requires for phytosanitary clearance, compressing inspection delays from days to hours.
Thailand's Ministry of Agriculture and Cooperatives is tightening alignment with China's General Administration of Customs technical standards for methyl bromide fumigation residues and cadmium limits. This regulatory convergence forces processors to upgrade laboratory testing capacity at packing stations. Fresh durian exporters serving Chinese wholesale channels bear the heaviest compliance burden, with some operators diverting lower-grade fruit to frozen processing to avoid rejection risk.
Industrial food manufacturers are consolidating procurement through long-term offtake agreements with integrated plantation-to-port operators. This purchasing pattern displaces spot-market buying that dominated historical durian trading. Beverage and dessert producers in Thailand, Malaysia, and Vietnam now favor contracted puree supply over auction-based fresh fruit procurement, locking in volume commitments that reshape supplier cash flow structures.
Durian Market Segmentation
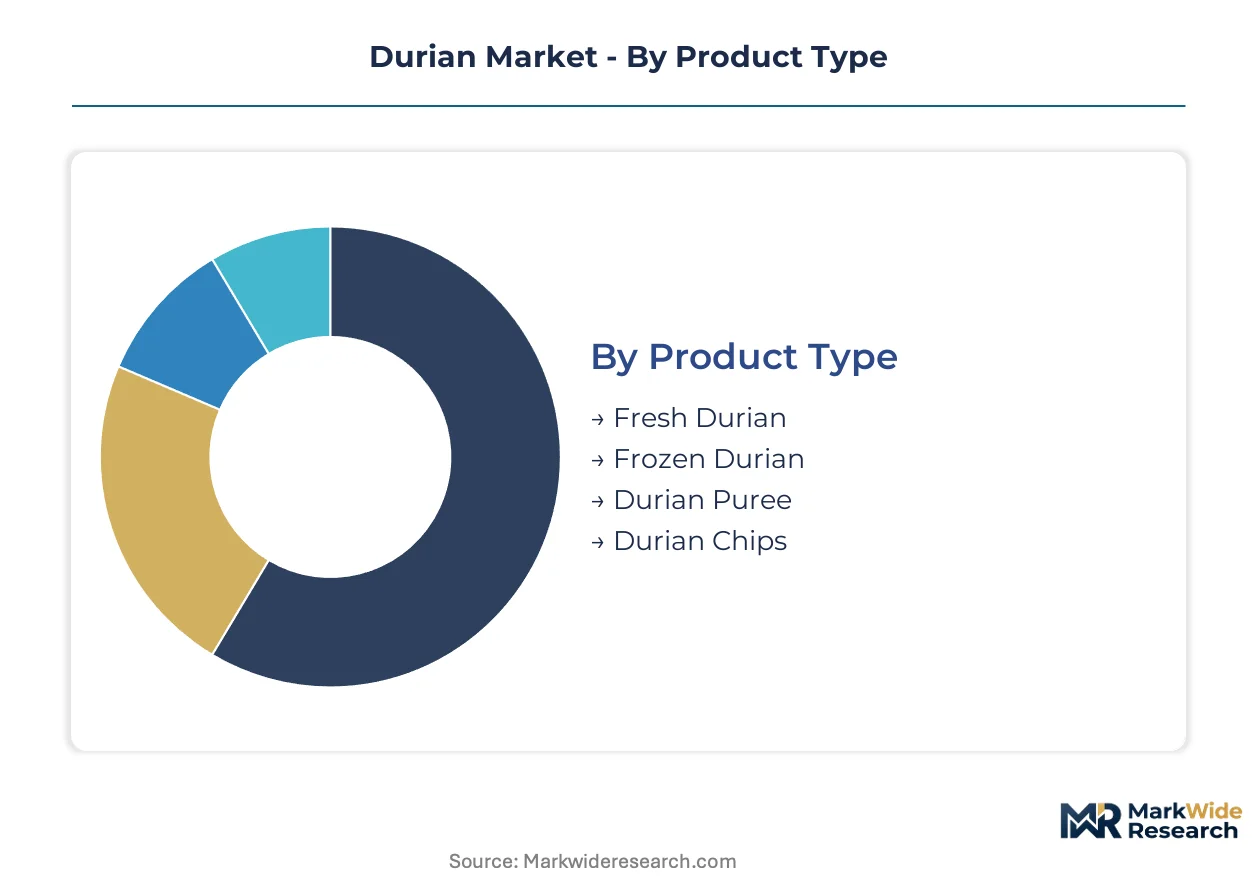
Durian segmentation reveals how processing intensity and shelf stability reshape procurement economics. Fresh fruit commands immediate premium realization while frozen and pureed formats compress seasonality into year-round revenue streams.
Product Type:
Inventory velocity varies dramatically across formats, with fresh durian turning in days while frozen stocks rotate across quarters and puree concentrates sit for months.
- Fresh Durian:Whole fruit with intact husk and unprocessed arils maintains volatile sulfur compound profiles that define sensory authenticity. Chinese wholesale buyers in Guangzhou and Shanghai prioritize Grade A shipments from Thailand's Chanthaburi province despite perishability constraints.
- Frozen Durian:Flash-frozen arils at minus 40 degrees Celsius lock cellular structure for industrial formulation. Malaysian processors serving Singaporean dessert manufacturers report strongest demand acceleration as cold chain reliability improves.
- Durian Puree:Vacuum-sealed paste extends shelf stability for beverage production lines. Vietnam's emerging toll-processing sector targets this segment for margin capture.
- Durian Chips:Dehydrated slices occupy mature snack positioning with limited formulation flexibility.
Fresh durian anchors the volume base while frozen durian gains share at the steepest rate.
End Use:
Application economics stratify by processing depth, with industrial buyers capturing scale advantages over artisanal channels.
- Food Industry:Bulk ingredient procurement for bakery and confectionery manufacturing concentrates in Thai and Malaysian processing zones. Industrial buyers favor long-term offtake contracts over spot-market exposure.
- Dessert Applications:Ice cream and pastry formulation drives puree demand acceleration across Southeast Asian food manufacturers.
- Snacks:Retail-packaged chips and dried segments face growth deceleration relative to ingredient-grade formats.
- Beverage Production:Smoothie and flavored drink manufacturers in Vietnam and Thailand integrate durian puree at expanding scale.
Food industry procurement dominates current volume while dessert applications expand most quickly.
Distribution Channel:
Channel selection determines margin retention and quality control exposure for producers.
- Supermarkets:Modern retail chains in Thailand and Malaysia stock packaged frozen arils for urban consumers. Cold chain requirements limit participation to integrated plantation-to-port operators.
- Online Retail:Chinese cross-border e-commerce platforms disintermediate traditional wholesale layers for direct-to-consumer frozen shipments.
- Local Markets:Traditional wet markets handle fresh fruit turnover in plantation-adjacent regions.
- Wholesale:Bulk fresh shipments to Chinese import channels concentrate through specialized export packers in Thailand's eastern provinces.
Wholesale channels capture the largest transaction values while online retail climbs the fastest.
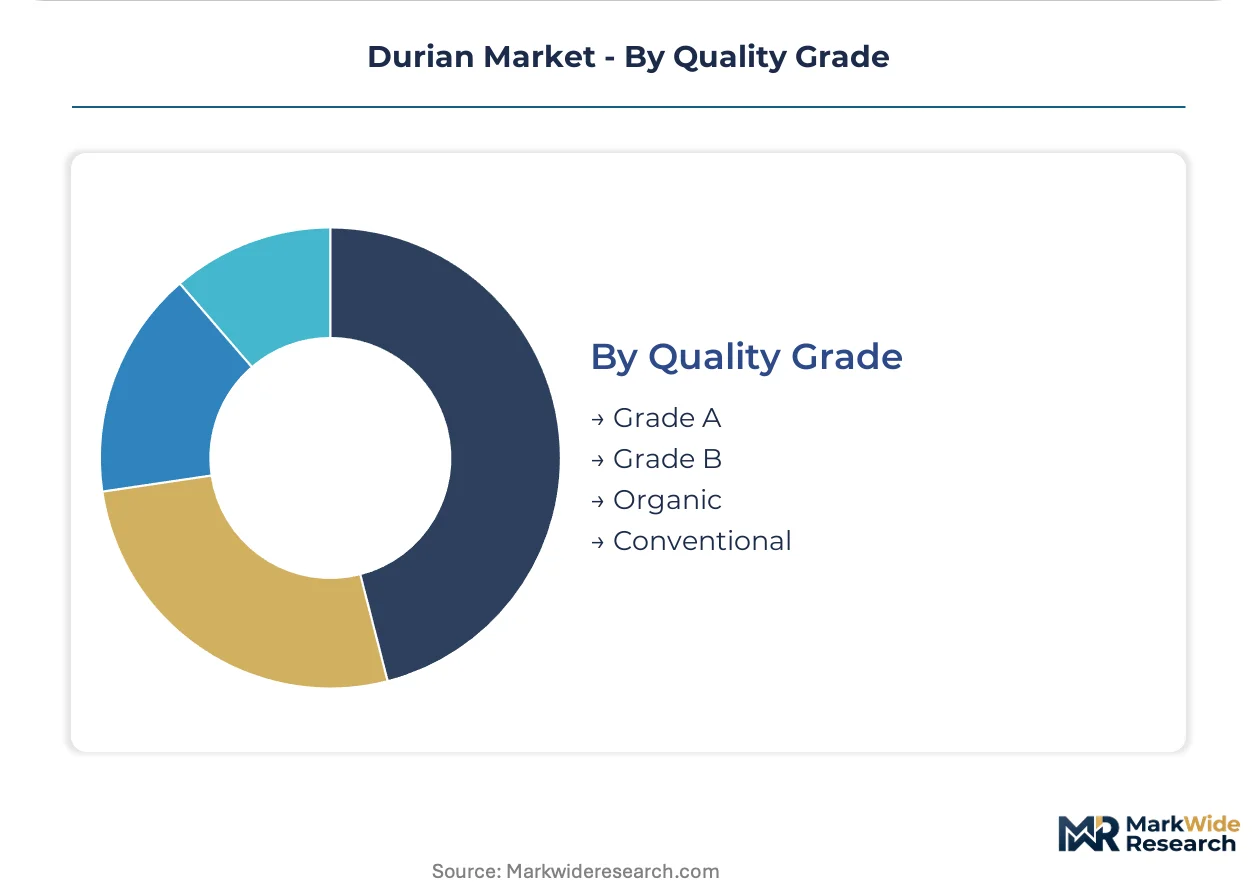
Quality Grade:
Certification tiers determine market access and pricing power across regulatory jurisdictions.
- Grade A:Premium classification under Thailand's Ministry of Agriculture and Cooperatives standards qualifies for Chinese General Administration of Customs phytosanitary clearance. Physical uniformity and residue compliance justify export price premiums.
- Grade B:Secondary quality tier diverts to domestic processing or frozen conversion to avoid rejection risk in regulated channels.
- Organic:Malaysia's Department of Agriculture certification aligns with EU Green Deal procurement preferences for European specialty food distribution.
- Conventional:Standard cultivation without organic designation serves price-sensitive industrial buyers.
Grade A fresh fruit anchors premium positioning while organic certification gains share fastest in European channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Thailand's export corridor to China dominates fresh durian trade flows, with Malaysia and Vietnam capturing frozen and processed segment growth across Southeast Asian industrial channels.
Thailand
Chinese wholesale demand for Grade A fresh fruit drives procurement concentration in Chanthaburi and Rayong provinces. Thailand's Ministry of Agriculture and Cooperatives enforces export phytosanitary certification aligned with China's General Administration of Customs methyl bromide and cadmium standards. Eastern plantation zones anchor integrated packing station networks serving cross-border cold chain logistics.
China
Guangzhou and Shanghai wholesale markets absorb premium fresh shipments while cross-border e-commerce platforms accelerate frozen aril adoption. China's General Administration of Customs maintains strict residue testing protocols for Thai imports. Southern import hubs in Guangdong province concentrate customs clearance infrastructure and cold storage capacity for durian distribution.
Malaysia
Pahang and Johor plantations supply Grade A and Organic-certified fruit to Singaporean dessert manufacturers and European specialty channels. Malaysia's Department of Agriculture administers certification tiers determining EU Green Deal market access. Peninsular Malaysia's integrated plantation-to-port operators leverage vacuum-freezing technology for puree preservation serving industrial buyers.
Vietnam
Emerging toll-processing arrangements attract Malaysian and Thai processors seeking supply diversification. Vietnam's underdeveloped cold chain infrastructure creates partnership opportunities with regional operators. Mekong Delta and southeastern provinces host nascent freezing capacity targeting beverage production demand.
Singapore
Industrial food manufacturers in Jurong and Tuas processing zones drive frozen durian and puree consumption for dessert formulation. Singapore Food Agency import standards shape regional quality benchmarks. The city-state's logistics hub position facilitates redistribution to Southeast Asian manufacturing clusters.
Durian Market Competitive Landscape
On the supply side, the industry is bifurcated between integrated plantation-to-port operators and specialized processing technology providers. Fresh fruit exporters concentrate in Thailand's eastern provinces while Malaysian and Vietnamese processors capture frozen and puree segment expansion. Three archetypes dominate: vertically integrated plantation operators, specialized freezing technology providers, and toll-processing intermediaries. Competitive moves center on backward integration into plantation control and strategic capacity expansion in Vietnamese processing zones.
Within the integrated operator tier, Top Fruits Sdn Bhd and Charoen Pokphand Group exemplify plantation-to-port control spanning Malaysian and Thai supply origins. Hernan Corporation occupies a position among specialized technology providers focused on vacuum-freezing systems for puree preservation. These three entities represent distinct strategic archetypes: geographic integration, processing technology specialization, and domestic procurement network dominance.
| Leading Market Players |
|---|
| Top Fruits Sdn Bhd |
| Hernan Corporation |
| Charoen Pokphand Group |
| Chainoi Food Company Limited |
| Interfresh Co., Ltd. |
| Thai Agri Foods Public Company Limited |
| TRL (South East Asia) Sdn Bhd |
| Grand World International Co., Ltd. |
| Sunshine International Co., Ltd. |
| Others |
Value Network & Pricing Analysis
Single-source dependency on Thailand's eastern plantation zones determines both Grade A premium spreads and frozen conversion economics across Southeast Asian supply networks. China's General Administration of Customs phytosanitary certification windows compress shipment scheduling flexibility, forcing exporters to absorb cold chain cost volatility or divert fruit to lower-margin processing channels.
Pricing Analysis
Flash-freezing technology gaps separate premium vacuum-preserved puree pricing from conventional frozen aril tiers across industrial buyer segments. Contract-based long-term offtake agreements dominate procurement, with price differentiation anchored in certification grade and cold chain integrity rather than spot-market commodity swings. Cost compression in Grade B fresh segments is intensifying because exporters divert substandard fruit to frozen processing to avoid Chinese customs rejection risk. Industrial food manufacturers show lowest price sensitivity due to formulation lock-in requirements, while snack segment buyers face margin pressure from commodity durian chip oversupply.
Supply Chain Analysis
Extended payment terms from Chinese wholesale buyers strain Thai packing station cash flows, forcing upstream financing dependence on integrated plantation-to-port operators. Geographic supply concentration centers on Thailand, Malaysia, and Vietnam, with raw material dependencies spanning methyl bromide fumigation capacity, cadmium testing laboratory access, and minus 40 degrees Celsius freezing equipment. Tariff exposure through EU Green Deal organic certification requirements creates compliance cost uncertainty for Malaysian exporters targeting European specialty channels. Distribution runs through cross-border cold chain logistics hubs in Guangdong province and Singaporean redistribution terminals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Durian markets track cyclical recovery patterns tied to Chinese import quota relaxation and post-harvest processing capacity expansion. Seasonal harvest volatility creates predictable troughs that favor contracted supply positions over spot-market exposure.
For Market Incumbents: Build regulatory compliance moats through pre-certified laboratory networks at Thai packing stations. Charoen Pokphand Group and Top Fruits Sdn Bhd should deepen backward integration into Pahang and Chanthaburi plantation control to secure Grade A fruit access. Vietnam toll-processing partnerships offer capacity hedging against Thai harvest shortfalls.
For New Entrants and Emerging Players: Establish a beachhead in Vietnam's underdeveloped freezing infrastructure segment. Malaysian vacuum-freezing technology licensing to Mekong Delta operators captures toll-processing margin pools. E-commerce direct-to-consumer frozen aril channels in Chinese cross-border platforms offer disintermediation angles with lower capital requirements than wholesale export licensing.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors integrated plantation-to-port operators with certified cold chain assets. Long-term viability over the next decade hinges on Chinese regulatory alignment and Southeast Asian processing capacity buildout. Acquisition targets should demonstrate Thailand's Ministry of Agriculture export certification compliance and minus 40 degrees Celsius freezing operational capability. The signal to watch is Chinese General Administration of Customs methyl bromide residue threshold tightening.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Plantation Control | Secures Grade A fruit access for Chinese export certification compliance. |
| Vacuum-Freezing Capacity Expansion | Extends puree shelf stability for Vietnamese beverage manufacturer contracts. |
| Blockchain Provenance Tracking Deployment | Compresses China customs inspection delays from days to hours. |
| Organic Certification Investment | Unlocks EU Green Deal duty-advantaged European specialty food channels. |
| E-Commerce Direct-to-Consumer Launch | Disintermediates Guangzhou wholesale layers for packaged frozen aril segments. |
Research Methodology
Initial hypotheses were tested against primary input from plantation operations managers, cold chain logistics coordinators, Chinese import clearance specialists, and Southeast Asian food manufacturer procurement directors and refined through secondary validation. Trade data from Thailand's Ministry of Commerce, China's General Administration of Customs import filings, Malaysian Department of Agriculture certification records, and ASEAN agricultural processing statistics anchored quantitative baselines. Bottom-up segment sizing triangulated against top-down macroeconomic drivers across the analysis window.
Demand-supply balance modeling captured flash-freezing capacity expansion, Chinese phytosanitary protocol evolution, and industrial buyer contract consolidation patterns. Segmentation dimensions spanned product format, quality grade certification tier, end-use application depth, and regional cold chain infrastructure maturity. CAGRs derived from historical volume trajectories adjusted for technology adoption curves and regulatory compliance timeline compression. Forecast inputs incorporated monsoon-dependent harvest yield variance and methyl bromide residue testing capacity constraints.
Stress conditions across Chinese import quota fluctuations, Thai harvest yield volatility, and Vietnamese freezing infrastructure buildout pace were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory alignment continuity and cold chain technology diffusion rates. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
8K Technology Market
Others
Augmented Reality (AR) in Manufacturing Market
Others
Singapore Retail Market
Others
Storage Dewars Market
Others
Rotary Evaporators Market
Others
Legal Services Market
Others
Retail Media Platform Market
Others
Vegetable Carbon Market
Others
Smart-Connected Power Plug Socket Market
Others
Smart Home Water Softener Market
Others
Diamond Mining Market
Others
Textile Composites Market
Others
Global Military Wearable Sensors Market
Others
North America Commercial Vehicles Lubricants Market
Others
Industrial Air Pollution Control Solutions Market
Others
India Battery E-Commerce Market