
 Wingboards Market | 2026-2036
Wingboards Market Size, Share, and Industry Trends Forecast 2026-2036
Wingboards Market Insights
The gap between premium carbon fiber wingboards and entry-level PVC models is shifting from a price divide into a performance-per-dollar calculation that shapes every purchase decision. Duotone Sports leverages its German engineering heritage to dominate high-end foil wing construction with precision-molded mast tracks. Fanatic competes through integrated board-and-wing ecosystems that reduce setup friction for rental services. Gong anchors the value tier with direct-to-consumer distribution that strips retail markup from hybrid wing configurations.
Wingboards are hydrodynamic planing platforms, typically 80–140 liters in volume, designed to harness wind energy through handheld inflatable or rigid wings while riding above or on the water surface; carbon fiber layups with PVC sandwich cores deliver the stiffness-to-weight ratio required for sustained foiling at wind speeds below 15 knots. Foil wings command the premium margin pool as experienced riders demand refined mast geometry and fuselage stability, while inflatable wings capture volume growth through travel portability that appeals to recreational surfers and school programs. Traditional wings retain niche dominance among competitive athletes who prioritize instantaneous power transfer and direct rail control in slalom and wave disciplines.
ISO 12217 small craft stability standards, CE marking for recreational watercraft, and REACH compliance for epoxy resin systems collectively govern material safety, buoyancy certification, and chemical handling across manufacturing and distribution channels. Australia's TGA does not regulate wingboards directly, but state maritime safety authorities enforce operator licensing that indirectly shapes school program procurement standards. Stakeholders must monitor evolving coastal access regulations and marine protected area restrictions that could constrain launch site availability faster than product innovation cycles can adapt.
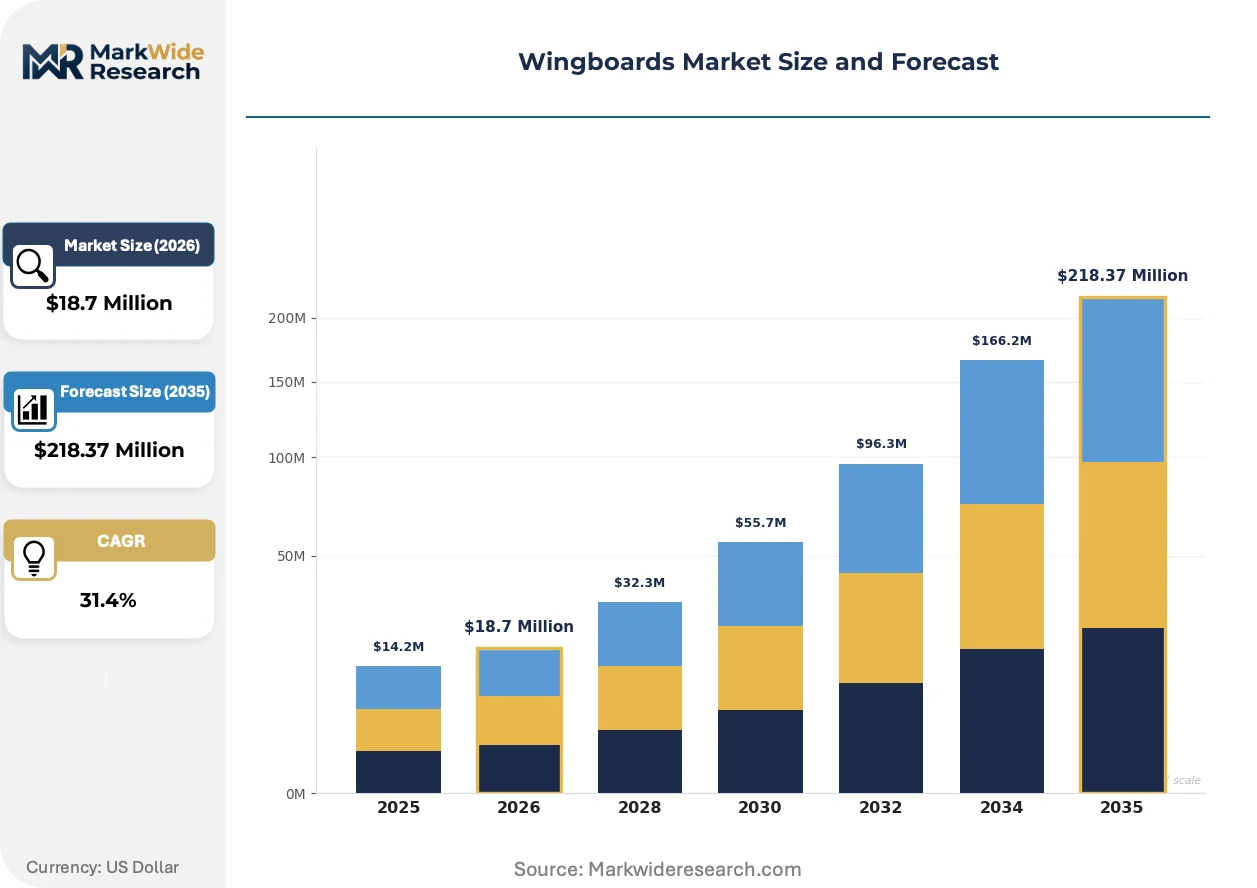
Market Dynamics
Carbon fiber layup automation is compressing production cycles and reconfiguring cost structures across the wingboard supply base, pulling premium foil construction toward mid-market price bands while forcing PVC-core manufacturers to defend margin through volume scale.
Growth Catalysts
- ISO 12217 stability certification:Standardized buoyancy testing protocols reduce school program liability exposure and accelerate institutional procurement cycles in coastal tourism markets.
- Recreational surfers:Post-pandemic coastal tourism recovery is expanding the addressable base beyond core athletes into leisure-oriented wind sports participants seeking entry-level inflatable configurations.
- Direct-to-consumer distribution:Manufacturers bypassing retail markup channels are capturing margin that funds R&D investment in hybrid wing geometries previously confined to premium tiers.
Market Restraints
- Epoxy resin price volatility:REACH compliance costs for chemical handling systems compound raw material exposure, squeezing margin on carbon fiber sandwich constructions.
- Australian supply concentration:Year-round wind condition dependence creates demand geography risk if coastal access regulations tighten faster than alternative market development.
- Foil mast geometry complexity:Precision-machined aluminum and titanium components require specialized tooling that limits supplier diversification and extends lead times.
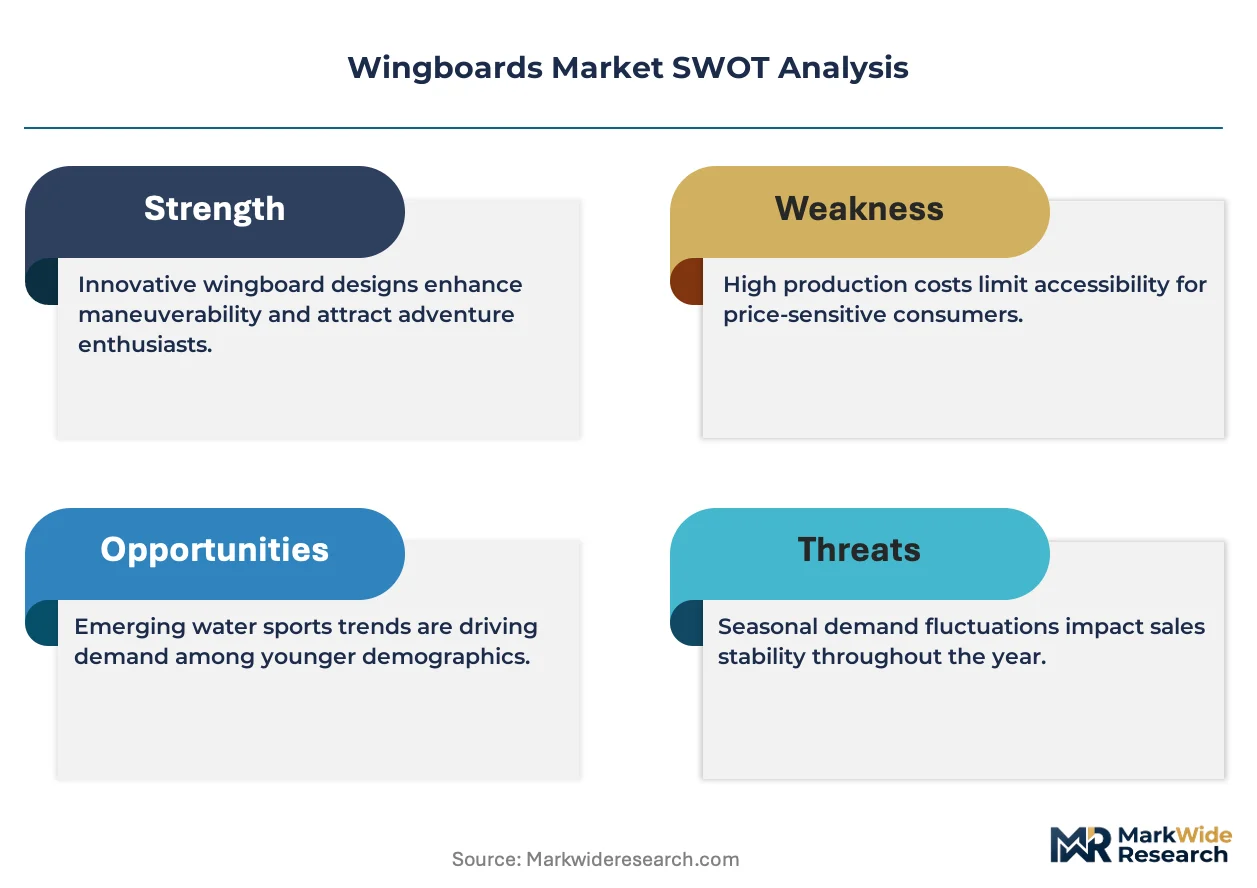
Strategic Opportunities
- Brazilian coastal expansion:Underdeveloped wind sports infrastructure along Rio Grande do Sul and Ceará coastlines offers first-mover positioning before regulatory frameworks mature.
- Marine protected area buffer zones:Emerging launch site restrictions in Australia are creating demand for portable inflatable systems that access non-traditional entry points.
- Board-and-wing ecosystem integration:Converging hardware and software platforms for real-time wind condition mapping enable subscription-based service models alongside equipment sales.
Industry Challenges
- Composite technician scarcity:Carbon fiber layup expertise concentrated in aerospace and automotive sectors creates recruitment friction for scaled wingboard production.
- CE marking timeline compression:Recreational watercraft certification delays extend product launch windows, forcing inventory carry costs during seasonal demand peaks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wingboards Market |
| Market Size in 2026 | $18.7 Million |
| Market Size in 2035 | $218.37 Million |
| CAGR (2026 – 2036) | 31.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Foil Wing, Traditional Wing, Inflatable Wing, Hybrid Wing Material: Carbon Fiber, Fiberglass, Aluminum, PVC End User: Recreational Surfer, Competitive Athlete, Rental Services, School Programs Distribution Channel: Online Retail, Specialty Stores, Sports Outlets, Trade Shows |
| Companies Covered | Duotone Sports, Fanatic, Slingshot Sports, Naish International, F-One, Cabrinha, North, Gong, Ocean Rodeo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wingboards Market Trends and Innovations
Material science advances and distribution model experimentation are fragmenting the traditional premium-economy dichotomy, creating intermediate performance tiers that serve evolving recreational user expectations.
Automated fiber placement for mast track integration is absorbing labor cost inflation that previously constrained carbon fiber board production scaling. School programs and rental operators in Australia are adopting these precision-molded configurations at accelerated replacement cycles. The technology is absorbing margin pressure that would otherwise force price increases, compressing the viable market position for hand-laid premium alternatives.
REACH enforcement for epoxy resin systems is tightening chemical handling documentation requirements across European manufacturing facilities. Industrial consequence includes accelerated investment in closed-loop solvent recovery systems that add fixed cost but reduce regulatory exposure. Foil wing producers serving competitive athletes are most affected, responding through consolidated supplier relationships that transfer compliance burden upstream.
Travel portability preferences among recreational surfers are fragmenting the traditional retail channel structure. Direct-to-consumer brands are displacing specialty surf shop distribution for inflatable wing configurations, particularly in secondary coastal markets where physical inventory carrying costs are prohibitive. This pattern is most visible in Australian school program procurement, where bulk purchasing through manufacturer portals now rivals traditional distributor relationships.
Wingboards Market Segmentation
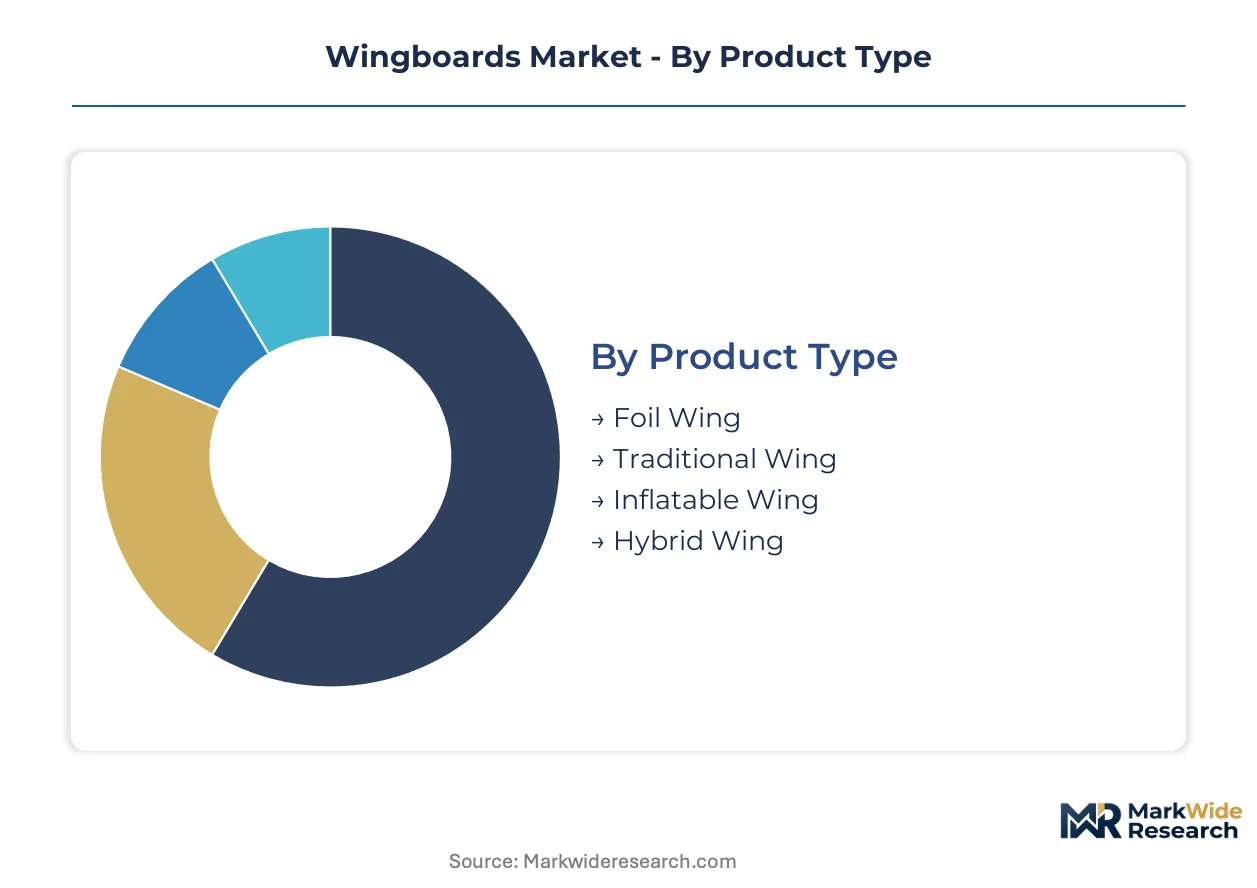
Wingboard segmentation tracks how riders trade off portability against hydrodynamic performance, with each dimension mapping to distinct cost structures and replacement cycles. Product type and material choices cascade through distribution economics and end-user procurement patterns.
Product Type:
Foil wings operate as standalone performance systems demanding precision-machined mast integration, while inflatable and hybrid configurations embed into rental fleets and travel-oriented user workflows.
- Foil Wing:Rigid carbon fiber or aluminum mast assemblies with tunable fuselage geometry deliver lift-to-drag ratios optimized for sustained foiling below 15 knots. Competitive athletes in Australia and school programs seeking ISO 12217 certified stability drive procurement.
- Inflatable Wing:Drop-stitch PVC bladders with reinforced leading edges pack to airline-checkable dimensions under 15 kilograms. Recreational surfers and coastal tourism operators in secondary markets favor these for launch site flexibility and reduced storage overhead.
- Traditional Wing:Rigid frame constructions with immediate power transfer dominate slalom and wave disciplines where rail control precision outweighs portability concerns.
- Hybrid Wing:Modular mast track systems accept both inflatable and rigid wing attachments, reducing fleet inventory duplication for rental services managing variable skill levels.
Inflatable wings lead volumes today; hybrid configurations are gaining share fastest.
Material:
Material selection stratifies across stiffness-to-weight requirements and REACH compliance exposure, with carbon fiber commanding premium positioning and PVC anchoring volume tiers.
- Carbon Fiber:Automated fiber placement enables 40-60% fiber volume fractions in mast tracks and board shells, delivering torsional rigidity for foil stability. REACH-compliant epoxy systems add documentation overhead that concentrates supply among consolidated European manufacturers.
- PVC:Sandwich core constructions with glass fiber reinforcement achieve 80-120 liter volumes at sub-10 kilogram weights for entry-level inflatable wings. Direct-to-consumer distribution strips retail markup and funds R&D in hybrid geometries.
- Fiberglass:Hand-layup techniques persist in mid-market board production where labor cost arbitrage offsets automation investment timelines.
- Aluminum:Extruded and CNC-machined mast sections provide corrosion-resistant fuselage components with tunable flex characteristics for recreational tuning.
PVC dominates unit economics across rental fleets; carbon fiber captures margin concentration in competitive segments.
End User:
End-user segmentation reflects skill progression curves and procurement authority structures, from individual recreational purchase decisions to institutional bulk contracting.
- Recreational Surfer:Post-pandemic coastal tourism recovery expands the addressable base beyond core athletes into leisure-oriented wind sports participants seeking entry-level inflatable configurations with minimal setup friction.
- School Programs:Institutional procurement in Australia demands ISO 12217 stability certification and CE marking to reduce liability exposure, accelerating replacement cycles for precision-molded mast track configurations.
- Competitive Athlete:Slalom and wave discipline specialists prioritize instantaneous power transfer and direct rail control, sustaining niche demand for traditional rigid wing constructions.
- Rental Services:Integrated board-and-wing ecosystems reduce equipment matching errors and maintenance overhead, with bulk purchasing through manufacturer portals displacing traditional distributor relationships.
Recreational surfers anchor volume expansion; school programs are climbing the fastest on certification-driven replacement cycles.
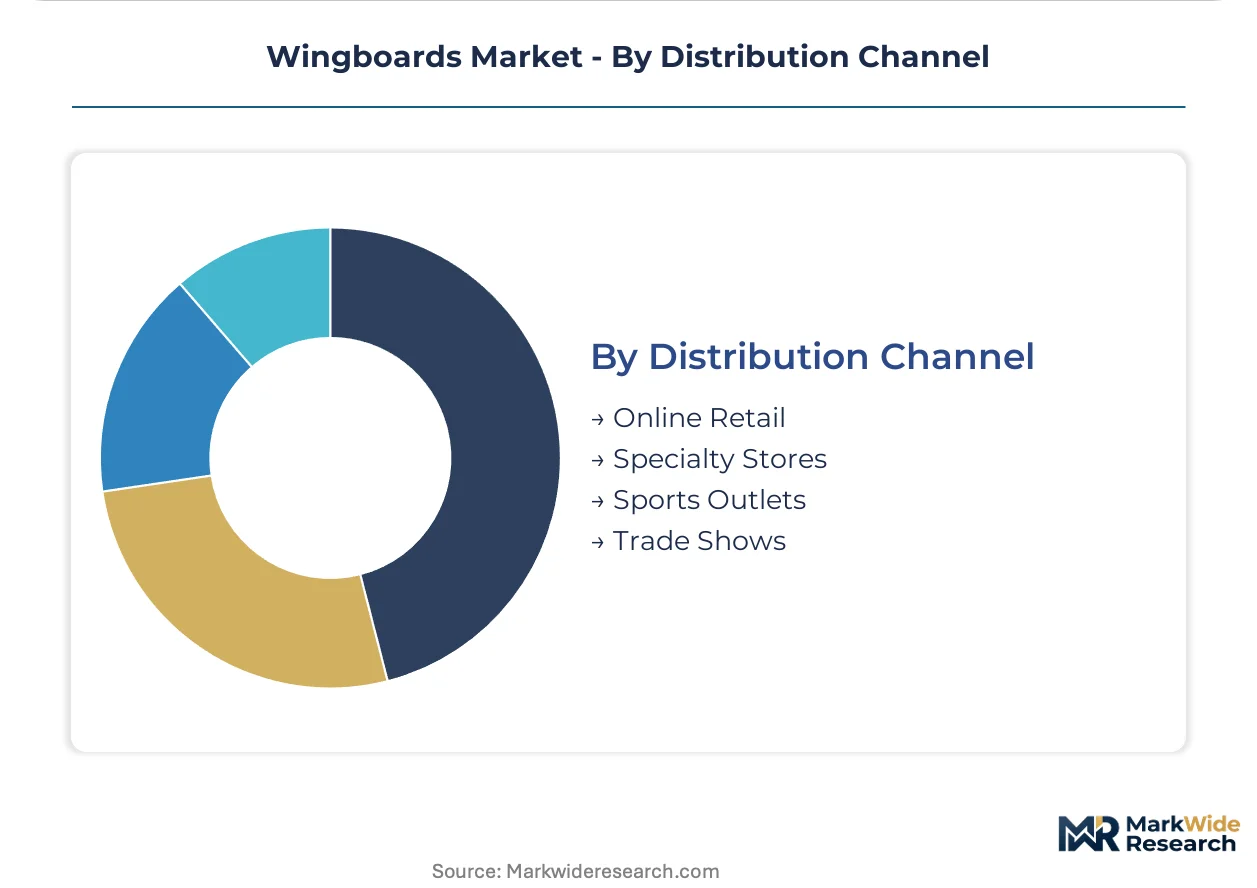
Distribution Channel:
Channel structure fragments between inventory-heavy specialty retail and direct-to-consumer models that capture margin for R&D reinvestment.
- Online Retail:Manufacturer portals and direct-to-consumer platforms strip retail markup from hybrid wing configurations, particularly visible in Australian school program procurement where bulk purchasing rivals traditional distributor relationships.
- Specialty Stores:Physical inventory carrying costs concentrate these channels in primary coastal markets with established water sports culture, serving riders demanding hands-on mast geometry comparison.
- Sports Outlets:Generalist sporting goods distribution captures entry-level inflatable wing volume in secondary markets where specialty surf shop economics prove prohibitive.
- Trade Shows:Seasonal exhibition cycles compress product launch windows and force inventory carry costs during demand peaks, particularly affecting CE marking timeline pressures.
Online retail leads volume capture; specialty stores retain margin concentration in premium foil configurations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Composite technicians concentrated in Australia's Gold Coast and Perth anchor production capacity for precision-molded mast assemblies. German engineering clusters around Lake Constance supply automated fiber placement systems. Brazilian coastal municipalities are recruiting school program operators to build instructor pipelines.
Australia
Year-round wind conditions along the Western Australia coastline sustain premium foil wing uptake among recreational surfers and competitive athletes. State maritime safety authorities enforce operator licensing that indirectly shapes school program procurement standards toward ISO 12217 certified configurations. Perth manufacturers cluster near Fremantle Harbor to minimize logistics friction for carbon fiber mast exports.
Germany
Precision engineering heritage concentrated around Friedrichshafen and Ravensburg drives automated mast track integration for foil wing systems. REACH compliance for epoxy resin systems tightens chemical handling documentation requirements across Baden-Württemberg manufacturing facilities. Lake Constance testing grounds enable rapid prototyping cycles for stiffness-to-weight optimization.
Brazil
Underdeveloped wind sports infrastructure along Rio Grande do Sul and Ceará coastlines attracts first-mover positioning from rental service operators. The country's national tourism promotion agency channels infrastructure investment toward coastal access development. Jericoacoara and Florianópolis are emerging as instructor training hubs for school program expansion.
United States
Post-pandemic coastal tourism recovery in California and Florida expands the addressable base for entry-level inflatable wing configurations. The EPA oversees chemical handling standards for composite manufacturing facilities in the Pacific Northwest. Hood River, Oregon anchors a testing and retail cluster where specialty stores concentrate hands-on mast geometry comparison.
France
Direct-to-consumer distribution models originating from Brittany and the Mediterranean coast strip retail markup from hybrid wing configurations. ANSM oversees workplace chemical exposure standards affecting composite layup facilities in the Pays de la Loire region. La Torche and Leucate host seasonal exhibition cycles that compress product launch windows for CE marking timeline pressures.
Wingboards Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across a fragmented vendor base where no single entity commands decisive share. Automated fiber placement systems require seven-figure capital commitments that favor consolidated European manufacturers, while direct-to-consumer brands bypass inventory carrying costs through build-to-order fulfillment. Three archetypes dominate: precision-engineered foil specialists, integrated board-and-wing ecosystem providers, and value-tier direct distributors. Competitive moves concentrate on geographic expansion into Brazilian coastal markets and backward integration into carbon fiber prepreg supply.
Among German-based precision specialists, Duotone Sports GmbH exemplifies the engineering-intensive archetype with Lake Constance manufacturing heritage. French direct-to-consumer operator Gong occupies a position within the value-tier vector that strips retail markup from hybrid configurations. Australian-originated Fanatic represents the integrated ecosystem approach, reducing setup friction for rental services through bundled procurement. These three anchors illustrate how geographic concentration shapes competitive positioning without determining market outcomes.
| Leading Market Players |
|---|
| Duotone Sports |
| Fanatic |
| Slingshot Sports |
| Naish International |
| F-One |
| Cabrinha |
| North |
| Gong |
| Ocean Rodeo |
| Others |
Pricing and Supply Chain Analysis
School programs in Australia concentrate procurement authority and drive a performance-per-dollar pricing model that rewards ISO 12217 certification over brand premium. This buyer archetype's bulk contracting power compresses margin for hand-laid premium alternatives while expanding addressable volume for automated fiber placement systems.
Pricing Analysis
Bundled board-and-wing ecosystems command premium positioning against unbundled component sales, with three-tier pricing structure across premium, standard, and economy levels separating foil wing systems from hybrid configurations from entry-level PVC constructions. Price differentiation hinges on certification grade and volume scale, with CE marking and ISO 12217 compliance adding documentation overhead that concentrates supply. Pricing pressure stems from carbon fiber layup automation absorbing labor cost inflation and pulling premium construction toward mid-market bands. Recreational surfers exhibit highest price sensitivity, while competitive athletes prioritize performance over cost.
Supply Chain Analysis
Regional distribution centers in Fremantle, Friedrichshafen, and Florianópolis anchor hub-and-spoke patterns that minimize logistics friction for mast exports. Manufacturing concentrates in Australia, Germany, and Brazil, drawing from carbon fiber prepreg, precision-machined aluminum, and REACH-compliant epoxy resin inputs. Single-source vulnerability in aerospace-trained composite technician pools creates recruitment friction for scaled production. Distribution runs through direct-to-consumer portals displacing specialty surf shop inventory carrying costs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Carbon fiber layup automation functions as the dominant margin-expansion driver, compressing production cycles and reconfiguring cost structures that enable premium-tier positioning at mid-market price points.
For Market Incumbents: Anchor defensive positioning through backward integration into carbon fiber prepreg supply and accelerated certification investment in ISO 12217 stability protocols. Consolidate supplier relationships to transfer REACH compliance burden upstream, countering margin pressure from epoxy resin price volatility. Expand automated fiber placement capacity to absorb labor cost inflation that constrains hand-laid alternatives. For New Entrants and Emerging Players: Begin with Brazilian coastal municipalities where underdeveloped wind sports infrastructure offers first-mover positioning before regulatory frameworks mature. Target school program procurement in secondary Australian markets through direct-to-consumer bulk purchasing portals that rival traditional distributor relationships. Emphasize travel portability and launch site flexibility as the primary go-to-market angle. For Investors and Strategic Acquirers: Precision sports equipment manufacturers with automated composite capabilities are the most active acquirer in this space, seeking technology transfer from aerospace and automotive sectors. Long-term viability rests on captive supply of carbon fiber layup expertise and certification-compliant manufacturing infrastructure. Monitor coastal access regulation tightening in Australia as the critical inflection signal for portable inflatable system demand.| Strategic Initiative | Industry Significance |
|---|---|
| Automated Fiber Placement Investment | Duotone Sports leverages Lake Constance engineering clusters to compress production cycles and defend margin. |
| Direct-to-Consumer Portal Launch | Gong strips retail markup from hybrid configurations and captures margin for R&D reinvestment in Brittany. |
| ISO 12217 Certification Acceleration | Fanatic reduces school program liability exposure and accelerates institutional procurement cycles in Perth. |
| Brazilian Coastal Expansion | Rental service operators secure first-mover positioning in Jericoacoara before infrastructure investment matures. |
| Backward Integration into Prepreg Supply | Consolidated European manufacturers transfer REACH compliance burden upstream and reduce raw material exposure. |
Research Methodology
Bottom-up end-user modeling reconciled against top-down supply-side tracking forms the analytical core of this study. Primary interviews with composite manufacturing plant managers, school program procurement officers, rental fleet operators, and carbon fiber distribution channel partners were validated against secondary sources including customs and trade data, SEC filings of precision sports equipment manufacturers, Australian maritime safety authority licensing records, and REACH compliance documentation from ECHA. Triangulation across these inputs ensures segmentation integrity across product type, material, and distribution channel dimensions.
Input-output matrices map carbon fiber prepreg consumption, mast track production capacity, and end-user replacement cycles to volume and value outputs across the projection horizon. Segmentation modeling incorporates product type, material stiffness-to-weight tier, end-user skill progression, and regional wind condition patterns. CAGRs were derived from replacement cycle analysis and coastal tourism recovery trajectories, with foil mast geometry complexity and composite technician scarcity serving as industry-specific forecast constraints.
Several conditions sit outside the modeled scope, including specific tariff rate changes, marine protected area boundary revisions, and abrupt shifts in epoxy resin commodity pricing. Forecasts reflect documented assumptions around automation adoption curves and certification timeline compression. Decision-makers should treat outputs as directional within the stated assumption set, recognizing that coastal access regulation changes could constrain launch site availability faster than product innovation cycles adapt.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
UK Automotive LED Lighting Market
Others
Africa Cotton Market
Others
Turkey Health and Medical Insurance Market
Others
Education and Learning Analytics Market
Others
Aerospace Engineering Services Outsourcing Market
Others
Bird Food Market
Others
Digital Transformation of Maritime Freight Market
Others
Nyerereite Market
Others
Bulgur Market
Others
Internet Protocol Television (IPTV) Market
Others
Blockchain in BFSI Market
Others
LED Packaging Market
Others
Global Augmented Reality in Retail Market
Others
DIY Smart Home Market
Others
Global Solder Balls Market
Others
Moonstone Market