
 Cat Food Market | 2026-2036
Cat Food Market Size, Share, and Industry Trends Forecast 2026-2036
Cat Food Market Intelligence
Multi-source protein procurement is hardening as a competitive requirement, with manufacturers diversifying away from single-origin supply chains. Nestlé Purina PetCare leverages its captive R&D network to control formulation pipelines from raw material to shelf. Mars Petcare anchors volume leadership through veterinary channel partnerships and prescription diet portfolios. Hill's Pet Nutrition specializes in clinical nutrition segments, sustaining margin premiums through science-backed positioning.
Cat food comprises nutritionally complete formulations designed to deliver species-appropriate protein, taurine, and essential fatty acids through extruded kibble, retorted wet products, or minimally processed raw formats. Manufacturing employs extrusion cooking at 120-150°C for dry products and thermal sterilization for wet formats to ensure microbial safety while preserving palatability. Wet food commands the fastest value growth due to hydration benefits and premium positioning, while grain-free formulations face structural pressure as veterinary scrutiny links certain legume-heavy diets to dilated cardiomyopathy risk. Pouch packaging is displacing cans in developed markets, driven by convenience and portion control preferences among single-cat households.
The FDA's Food Safety Modernization Act extends preventive controls to pet food facilities, elevating compliance costs for smaller manufacturers. AAFCO nutrient profiles and feeding trial protocols define market access thresholds, with state-level enforcement creating patchwork compliance obligations across the United States. The EU's Feed Hygiene Regulation and FEDIAF nutritional guidelines shape export requirements for North American suppliers. Stakeholders must monitor evolving veterinary consensus on grain-free formulations and the pace of state-by-state raw food retail regulation.
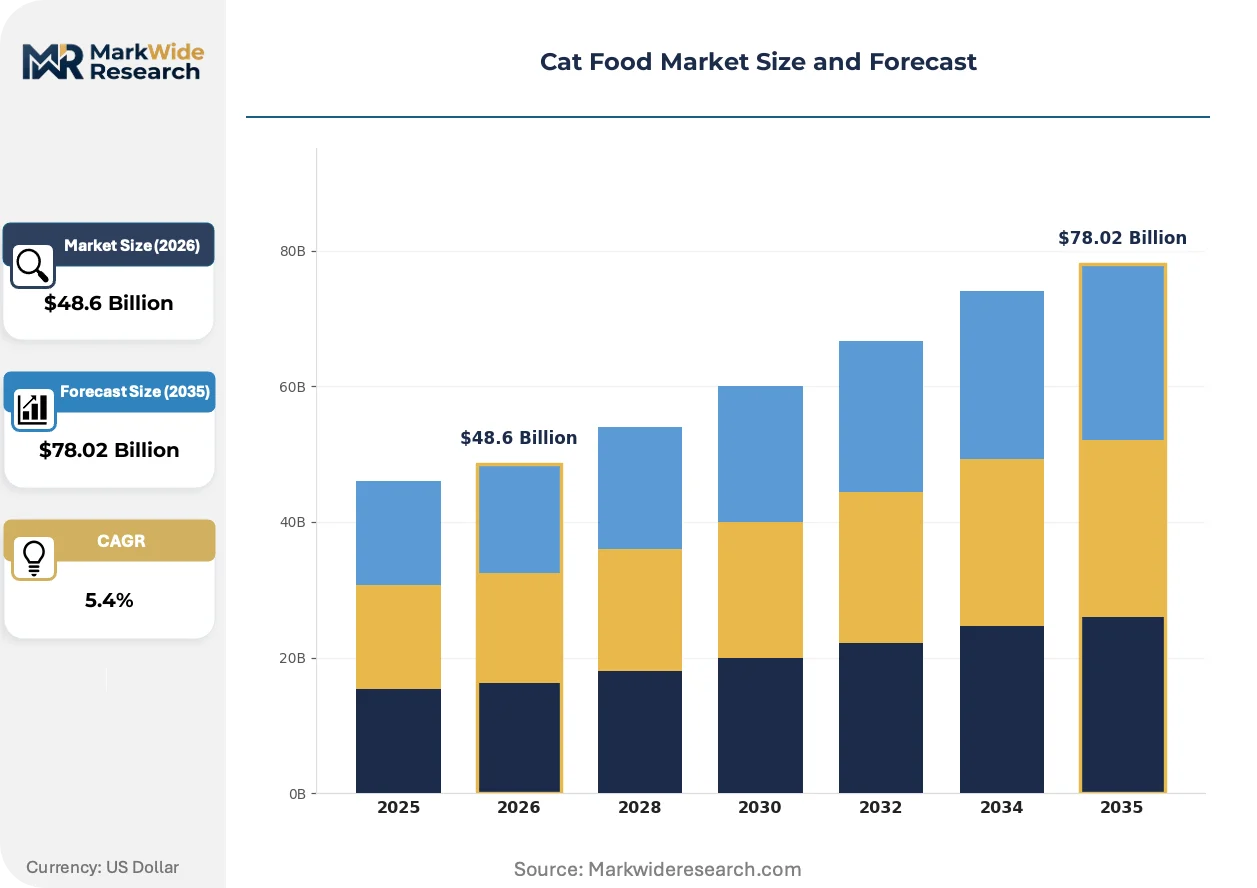
Market Dynamics
Urban millennial pet ownership patterns are compressing purchase cycles toward subscription models while FDA preventive control mandates reshape manufacturing economics across wet and dry format producers.
Growth Catalysts
- AAFCO Nutrient Profile Revisions:Updated feeding trial protocols and nutrient adequacy statements are elevating formulation standards, creating competitive separation between compliant and non-compliant manufacturers in United States distribution channels.
- E-commerce Subscription Models:Direct-to-consumer platforms are capturing recurring revenue streams from single-cat households seeking convenience and portion-controlled delivery schedules.
- Veterinary Channel Expansion:Prescription diet portfolios are deepening clinical nutrition penetration, with veterinary clinics functioning as gatekeepers for therapeutic formulations and premium-tier positioning.
Market Restraints
- Protein Input Cost Volatility:Fish meal and poultry by-product markets exhibit price swings tied to commodity agriculture cycles, compressing margin stability for mid-tier manufacturers without captive supply arrangements.
- Supply Concentration Risk:Wet format retort packaging capacity clusters among a limited set of North American co-manufacturers, creating bottleneck exposure during demand surges.
- Technical Limitation in Grain-Free Formulations:Veterinary scrutiny linking legume-heavy diets to dilated cardiomyopathy risk is constraining formulation freedom and forcing recipe reformulation investments.
Strategic Opportunities
- Raw and Minimally Processed Segments:State-by-state retail regulation gaps in United States markets create first-mover potential for brands establishing cold-chain compliance infrastructure ahead of harmonized standards.
- Pouch Packaging Innovation:Convenience-driven portion control formats are displacing traditional cans in developed markets, opening equipment investment windows for converters with retortable flexible film capabilities.
- IRA-Aligned Sustainable Protein Sourcing:Inflation Reduction Act incentives for domestic agriculture processing are reducing cost barriers for novel protein ingredient development and regional supply chain localization.
Industry Challenges
- FSMA Preventive Controls Implementation:FDA Food Safety Modernization Act compliance timelines demand hazard analysis and preventive control expertise that smaller manufacturers struggle to staff and document.
- Reformulation Capex Burden:Grain-free to grain-inclusive recipe transitions require extrusion die modifications, palatability testing cycles, and label redesign investments that strain working capital.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cat Food Market |
| Market Size in 2026 | $48.6 Billion |
| Market Size in 2035 | $78.02 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dry Food, Wet Food, Treats, Raw Food Ingredient Type: Meat-Based, Plant-Based, Grain-Free, Organic Packaging Type: Bags, Cans, Pouches, Tubs Customer Type: Pet Owners, Veterinarians, Pet Shops, Online Retailers |
| Companies Covered | Blue Buffalo, General Mills, Nestlé Purina PetCare, Unicharm Corporation, WellPet LLC, Mars Petcare, The J.M. Smucker Company, Affinity Petcare, Hill’s Pet Nutrition, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cat Food Market Strategic Shifts & Innovations
Formulation science and packaging technology are converging to reshape competitive positioning, with hydration-focused products and sustainable materials commanding disproportionate investment attention from established manufacturers.
High-pressure processing technology is electrifying raw and fresh format segments by delivering microbial safety without thermal degradation of heat-sensitive nutrients. Premium-positioned brands are adopting HPP equipment at accelerated pace to support refrigerated distribution claims. This capability is compressing the traditional wet-can advantage by enabling shelf-stable raw alternatives with superior palatability metrics.
The FDA's Food Safety Modernization Act preventive controls rule is extending human-food-grade hazard analysis requirements to pet food facilities with annual sales exceeding specified thresholds. Compliance investments are diverting capital from R&D programs at sub-scale manufacturers. Wet format producers with complex supply chains face disproportionate documentation burdens compared to dry extrusion operations with simpler ingredient flows.
Subscription-based replenishment is consolidating purchase decisions into automated delivery schedules that reduce brand-switching frequency. Single-cat households in United States metropolitan markets are driving this channel shift, with convenience outweighing price sensitivity in cohorts under forty. Veterinary clinics are responding by launching proprietary auto-ship programs to defend prescription diet dispensing relationships against third-party platform encroachment.
Cat Food Market Segmentation
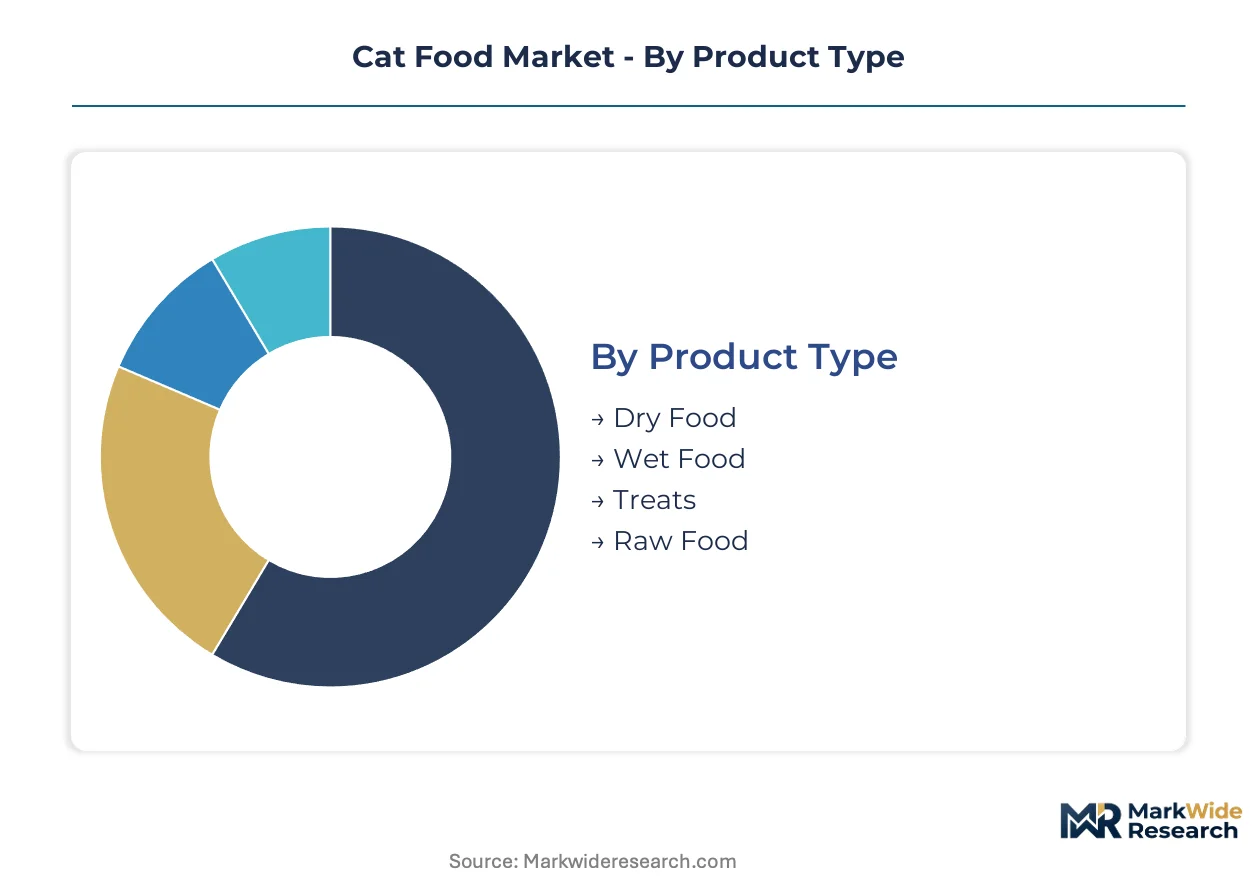
Segmentation in the cat food market reveals how supply chain configuration, formulation standards, and channel access create distinct competitive battlegrounds. Manufacturers must align production assets with specific segment requirements to capture margin premiums and defend shelf positioning.
Product Type:
Supply concentration varies sharply across format categories, with wet food retort capacity clustering among a limited set of North American co-manufacturers while dry extrusion remains more fragmented.
- Dry Food:Extruded kibble formulations cooked at 120-150°C deliver cost-efficient nutrition with extended shelf stability. Demand concentrates in multi-cat households and price-sensitive segments where portion scalability outweighs hydration benefits. Supply chains favor manufacturers with captive grain milling and extrusion die fabrication capabilities.
- Wet Food:Retorted products in gravy or pate formats command the steepest expansion trajectory through premium positioning and perceived palatability advantages. Urban millennial pet owners in United States metropolitan markets drive subscription adoption for single-serve portions. Thermal sterilization requirements concentrate production among FDA-registered facilities with validated preventive controls.
- Treats:Functional and indulgent snack formats occupy impulse purchase occasions with looser nutritional completeness requirements than complete diets.
- Raw Food:Minimally processed refrigerated or frozen segments exploit regulatory gaps in state-by-state retail frameworks, attracting venture-backed entrants with cold-chain infrastructure investments.
Today's leader: Wet Food. Tomorrow's challenger: Raw Food.
Ingredient Type:
Cost tier stratification separates commodity formulations from certified premium positioning, with protein sourcing decisions determining margin structure and regulatory exposure.
- Meat-Based:Poultry, fish, and red meat proteins dominate complete diet formulations through AAFCO-compliant amino acid profiles. United States veterinary channel expansion favors meat-first positioning for therapeutic diet credibility. Supply volatility in fish meal and poultry by-product markets compresses margin stability for non-integrated manufacturers.
- Grain-Free:Legume-heavy formulations face structural pressure as FDA and veterinary cardiology consensus links certain recipes to dilated cardiomyopathy risk. Reformulation investments and label redesign costs strain working capital for mid-tier brands without R&D scale.
- Plant-Based:Novel protein alternatives attract sustainability-positioned brands seeking IRA-aligned domestic agriculture incentives, though taurine supplementation remains mandatory for feline metabolic requirements.
- Organic:USDA-certified supply chains command shelf price premiums through restricted pesticide and antibiotic protocols, with procurement limited by certified organic protein availability.
Meat-Based maintains volume dominance. Plant-Based gains share fastest among sustainability-motivated cohorts.
Packaging Type:
Customer type preferences are reshaping format adoption, with convenience-driven single-cat households displacing traditional multi-serve containers.
- Pouches:Retortable flexible films enable portion-controlled dispensing with reduced storage footprint and improved palatability preservation versus metal cans. Equipment investment windows favor converters with high-barrier lamination capabilities.
- Cans:Traditional metal containers retain cost advantages for multi-cat households and institutional purchasers, though aluminum price volatility and recycling logistics create sustainability headwinds.
- Bags:Multi-wall paper and plastic laminates dominate dry food distribution with resealability features and graphic billboard space for shelf differentiation.
- Tubs:Refrigerated fresh formats leverage tamper-evident lidding for raw and HPP-processed segments requiring cold chain integrity claims.
Pouches displace cans in developed markets. Tubs emerge as the format for refrigerated premium expansion.
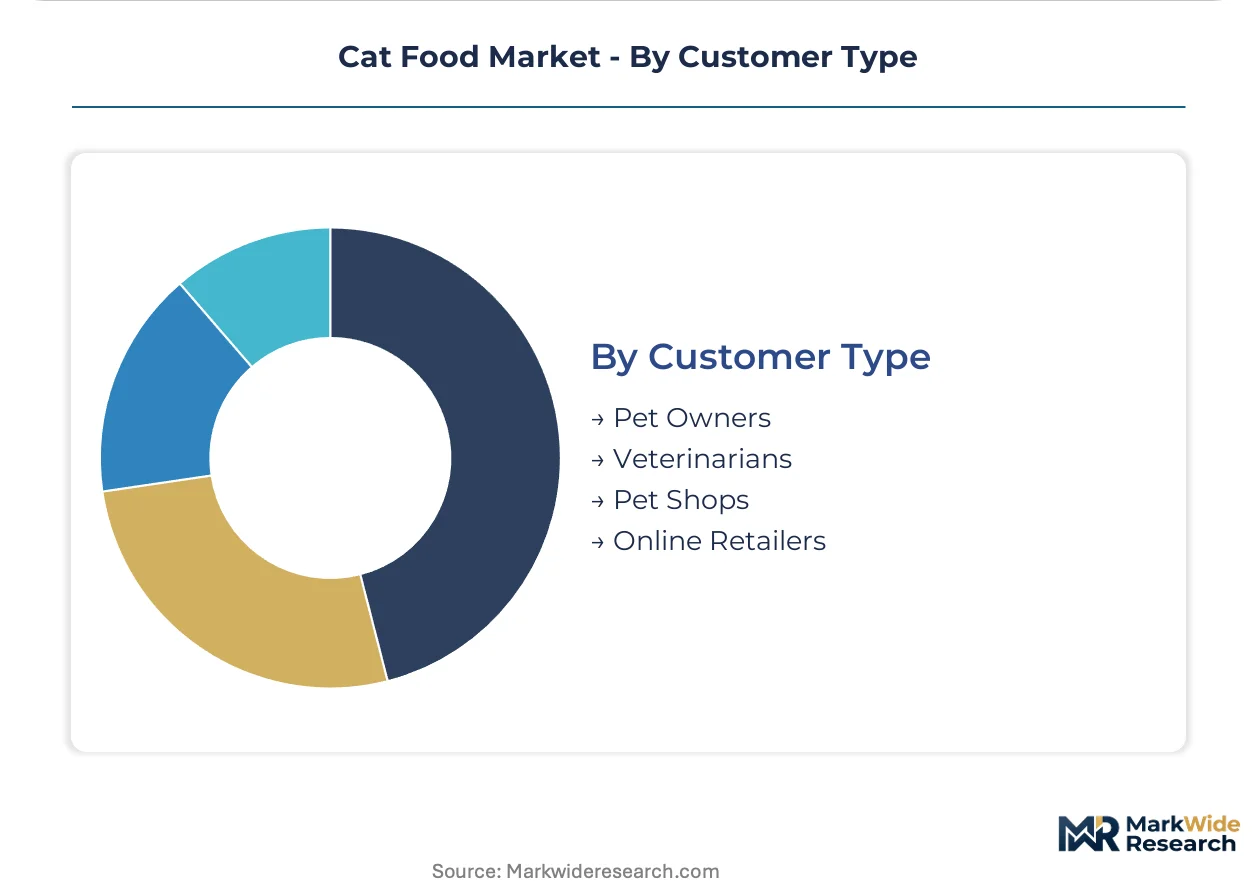
Customer Type:
Channel margin structures determine pricing power, with gatekeeper relationships in clinical settings sustaining premium positioning unavailable in mass retail.
- Veterinarians:Prescription diet dispensing functions as a margin-protected enclave where clinical credibility justifies price premiums and recurring purchase loyalty. Auto-ship program launches defend these relationships against third-party platform encroachment.
- Pet Owners:Direct purchasing decisions concentrate in subscription platforms for convenience-seeking urban demographics, with brand-switching frequency compressed through automated replenishment schedules.
- Pet Shops:Specialty retail channels provide tactile evaluation and staff consultation for premium trial purchases, though foot traffic erosion pressures floor space allocation.
- Online Retailers:Marketplace and direct-to-consumer platforms capture search-driven replenishment with algorithmic recommendation engines influencing brand discovery.
Veterinarians anchor premium pricing. Online Retailers capture volume growth through subscription infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States concentrates cat food manufacturing capacity and consumption, with regulatory tightening and e-commerce infrastructure defining competitive dynamics across North American, European, and Asia-Pacific markets.
United States
Urban millennial pet ownership and veterinary channel expansion drive premium wet food adoption. FDA preventive controls under FSMA elevate compliance costs for wet format retort facilities. Greater St. Louis hosts Nestlé Purina's captive R&D network controlling formulation pipelines from raw material through distribution.
Germany
Sustainability-motivated cohorts accelerate pouch packaging displacement of traditional cans. EU Feed Hygiene Regulation and FEDIAF nutritional guidelines shape formulation standards for export-oriented suppliers. Hamburg's port infrastructure enables novel protein ingredient import flows for domestic manufacturers.
Japan
Single-cat household density supports portion-controlled subscription delivery models. METI oversight of pet food safety aligns with FEDIAF guidelines for imported formulations. Tokyo-Osaka corridor concentrates premium retail distribution and veterinary clinic networks for therapeutic diet penetration.
United Kingdom
E-commerce subscription platforms capture recurring revenue from convenience-seeking urban demographics. Post-Brexit regulatory divergence from EU Feed Hygiene Regulation creates compliance complexity for cross-border suppliers. Greater London hosts specialized pet retail chains driving premium trial purchases.
Brazil
Mid-tier volume growth concentrates in multi-cat households favoring cost-efficient dry extrusion formats. ANVISA pharmaceutical-grade manufacturing standards influence quality positioning for domestic producers. São Paulo state's industrial corridor clusters co-manufacturing capacity serving Latin American distribution networks.
Cat Food Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue minimally processed and subscription-direct channels. Market structure concentrates among integrated multinationals with captive R&D networks, mid-tier regional specialists, and venture-backed cold-chain entrants. Three archetypes dominate: science-backed clinical nutrition specialists, mass-market volume leaders with veterinary channel anchoring, and sustainability-positioned novel protein developers. Competitive moves center on prescription diet portfolio expansion and retortable flexible film packaging equipment investments.
Among US-based manufacturers, Blue Buffalo exemplifies the premium natural positioning archetype, while General Mills represents diversified consumer goods conglomerates leveraging scale infrastructure. Nestlé Purina PetCare occupies the integrated multinational tier with captive supply chain control.
| Leading Market Players |
|---|
| Blue Buffalo |
| General Mills |
| Nestlé Purina PetCare |
| Unicharm Corporation |
| WellPet LLC |
| Mars Petcare |
| The J.M. Smucker Company |
| Affinity Petcare |
| Hill's Pet Nutrition |
| Others |
Cost & Logistics Intelligence
Family-owned mid-cap manufacturers in the United States pet food sector are consolidating through private-equity roll-ups, tightening procurement discipline and compressing margin tolerance across wet and dry format tiers. This ownership restructuring feeds directly into supply chain behavior, as rolled-up entities leverage pooled purchasing power to extract volume discounts while passing input volatility through to price-sensitive economy segments.
Pricing Analysis
Fish meal and poultry by-product cost pass-through determines margin stability across manufacturer tiers, with three-tier pricing structure across premium, standard, and economy levels separating veterinary-channel prescription diets from mass retail commodity kibble. Quality grade and certification level — FDA-registered facility status versus state-level feed license — create price differentiation between compliant and non-compliant suppliers. Pricing pressure stems from grain-free reformulation investments forced by veterinary cardiology consensus linking legume-heavy diets to dilated cardiomyopathy risk. Economy-tier dry food buyers exhibit highest price sensitivity, while single-cat household subscribers to premium wet formats tolerate recurring price adjustments.
Supply Chain Analysis
Dual-sourcing requirements for retort packaging capacity are mandating multi-supplier qualification among wet format producers, with supply concentrating in United States, Thailand, and Germany for high-barrier flexible film conversion. Raw material dependencies center on fish meal from Peruvian anchovy fisheries, poultry by-products from integrated Tyson and Pilgrim's Pride processing networks, and taurine supplementation from Chinese chemical manufacturers. Single-source vulnerability in North American co-manufacturing capacity creates bottleneck exposure during demand surges. Distribution runs through veterinary clinic gatekeepers for prescription diets, direct-to-consumer subscription platforms for premium convenience segments, and mass retail chains for economy-tier volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cat food market functions as a regulatory compounder, with FDA Food Safety Modernization Act preventive controls mandating hazard analysis investments that elevate compliance costs and consolidate competitive position among scaled manufacturers.
For Market Incumbents: Anchor prescription diet portfolios through veterinary clinic auto-ship program launches that defend dispensing relationships against third-party platform encroachment. Deepen backward integration into captive poultry by-product processing to insulate margin stability from commodity agriculture cycles. Prioritize retortable flexible film packaging equipment investments ahead of pouch displacement of traditional cans in developed markets. For New Entrants and Emerging Players: Single-cat households in United States metropolitan markets represent an underserved buyer archetype with convenience-driven subscription appetite and reduced brand-switching frequency. Exploit state-by-state retail regulation gaps for raw and minimally processed segments by establishing cold-chain compliance infrastructure ahead of harmonized standards. Pursue direct-to-consumer launch with algorithmic replenishment scheduling to compress customer acquisition costs. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier regional specialists lacking FDA-registered wet format capacity or AAFCO-compliant feeding trial documentation. Long-term viability over the projection horizon favors targets with veterinary channel anchoring and prescription diet portfolio depth. Watch for FDA enforcement action against non-compliant raw food retailers as inflection indicator for regulatory consolidation acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Veterinary Channel Auto-Ship Program Launch | Defends prescription diet dispensing relationships against Chewy and Amazon subscription encroachment. |
| Retortable Flexible Film Packaging Investment | Captures pouch displacement of aluminum cans in United States and German metropolitan markets. |
| Backward Integration into Poultry By-Product Processing | Insulates margin stability from Tyson and Pilgrim's Pride commodity pricing volatility. |
| Cold-Chain Infrastructure Buildout for Raw Formats | Establishes compliance-ready positioning ahead of state-by-state retail regulation harmonization. |
| AAFCO Feeding Trial Certification Investment | Creates competitive separation between compliant and non-compliant manufacturers in United States distribution. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with pet food manufacturing executives, veterinary clinic procurement managers, retail category buyers, and cold-chain logistics specialists with secondary validation through FDA FSMA compliance filings, AAFCO nutrient profile documentation, Nielsen retail audit data, and United States customs import records for fish meal and taurine derivatives. Bottom-up facility capacity modeling and top-down consumption estimation triangulated market sizing across wet, dry, treat, and raw format segments.
Comparable-period anchoring tied projection assumptions to historical reference periods spanning regulatory implementation phases, with volume and value outputs reflecting analytical framework approaches across product type, ingredient certification tier, packaging format, and customer channel dimensions. CAGRs derived from segment-level growth rate reconciliation with macro pet ownership demographic trends. Forecast inputs incorporated FDA enforcement intensity scenarios and e-commerce subscription penetration curves specific to single-cat household density.
Underlying measurement precision varies by segment; wet food and prescription diet categories carry tighter precision than raw food and treat segments due to regulatory reporting requirements. Forecasts reflect assumptions about AAFCO compliance adoption rates and veterinary channel expansion trajectories. Deviation in FDA FSMA enforcement intensity or state-level raw food retail regulation would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Ultrasonic Flow Meter Market
Others
Global Emergency Spill Response Market
Others
Short Video Applications Market
Others
8K Technology Market
Others
Middle East Location-Based Services Market
Others
Augmented Reality in Energy and Utilities Market
Others
Global ESD Protection Devices Market
Others
Tobacco Packaging Market
Others
Latin America Video Conferencing Hardware Market
Others
Industrial PC Market
Others
Safety Critical Software Testing Market
Others
India 3D Printing Construction Market
Others
Connected Wearable Patches Market
Others
Senior Cat Food Market
Others
US Tablet Market
Others
Asia-Pacific Induced Pluripotent Stem Cells (Ipscs) Market