
 Air Separation Module Kit Market | 2026-2036
Air Separation Module Kit Market Size, Share, and Industry Trends Forecast 2026-2036
Air Separation Module Kit Market Analytics
The performance gap between premium cryogenic systems and commodity PSA units is broadening as end users segment procurement by uptime criticality. Linde leverages its cryogenic engineering heritage to anchor high-purity contracts in semiconductor and healthcare verticals. Air Products and Chemicals competes through dense service networks that sustain long-term aftermarket revenue streams. Messer specializes in mid-scale membrane configurations that occupy the flexible-demand tier between bulk supply and captive generation.
An air separation module kit comprises engineered assemblies of adsorbent beds, membrane bundles, or distillation columns designed to fractionate atmospheric air into oxygen, nitrogen, and argon streams with specified purity levels. Cryogenic systems achieve parts-per-billion impurity thresholds through multi-stage distillation at temperatures below minus 180 degrees Celsius, serving steelmaking and electronics fabrication where purity failures halt production lines. PSA technology leads installed base volumes due to lower capital thresholds and modular expandability, while membrane systems represent the fastest-growing product type for mobile and remote applications where weight and footprint constraints dominate. Margin pools concentrate in cryogenic aftermarket services and in hydrogen production applications where pressure swing adsorption units process syngas streams.
The EPA enforces emissions limits on industrial gas facilities that shape compressor energy efficiency standards and refrigerant selection in cryogenic cycles, while OSHA's confined-space and oxygen-deficiency protocols mandate redundant monitoring in PSA installations. The FDA's medical gas purity requirements for US healthcare oxygen create a regulated demand floor that elevates certification costs for non-specialist entrants. Stakeholders must monitor how tightening EPA rules on fluorinated gases affect cryogenic refrigerant choices and whether membrane material advances from polyimide to mixed-matrix frameworks alter the PSA-membrate competitive boundary.
Market Dynamics
Steelmakers in China are consolidating captive oxygen and nitrogen generation capacity, compressing procurement timelines and forcing equipment suppliers to deliver modular, expandable PSA and membrane systems on accelerated schedules.
Growth Catalysts
- EPA emissions standards:Industrial gas producers in the United States must retrofit facilities with energy-efficient compressors and low-GWP refrigerants, creating replacement demand for compliant module kits.
- Semiconductor fabrication:Electronics manufacturers require parts-per-billion purity thresholds that cryogenic distillation achieves, sustaining premium system orders despite higher capital requirements.
- Remote healthcare deployment:Mobile membrane systems serve field hospitals and disaster response units where bulk liquid oxygen logistics fail, opening new installation categories.
Market Restraints
- Specialized adsorbent supply concentration:Zeolite molecular sieve production concentrates in limited geographies, exposing PSA system assemblers to input cost volatility and extended lead times.
- Cryogenic energy intensity:Multi-stage distillation cycles consume substantial electricity, creating operational cost disadvantages versus PSA alternatives in regions with high industrial power tariffs.
- Medical certification friction:FDA oxygen purity mandates for US healthcare applications elevate compliance costs and timeline risk for non-specialist kit manufacturers seeking market entry.
Strategic Opportunities
- India steel expansion:Integrated mill projects under the country's PLI scheme require captive nitrogen for blanketing and oxygen for basic oxygen furnaces, creating greenfield installation demand.
- Hydrogen production integration:PSA units processing syngas streams for blue hydrogen projects represent a converging application where air separation expertise transfers directly.
- EU F-Gas Regulation phase-down:Restrictions on fluorinated refrigerants accelerate adoption of alternative cryogenic cycles and membrane systems that avoid regulated working fluids.
Industry Challenges
- Cryogenic welding certification:Qualified technicians capable of fabricating vacuum-insulated cold boxes remain scarce, constraining production scaling for high-purity system manufacturers.
- Legacy control system integration:Digital monitoring upgrades for installed PSA units must interface with decades-old plant automation architectures, complicating retrofit deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Air Separation Module Kit Market |
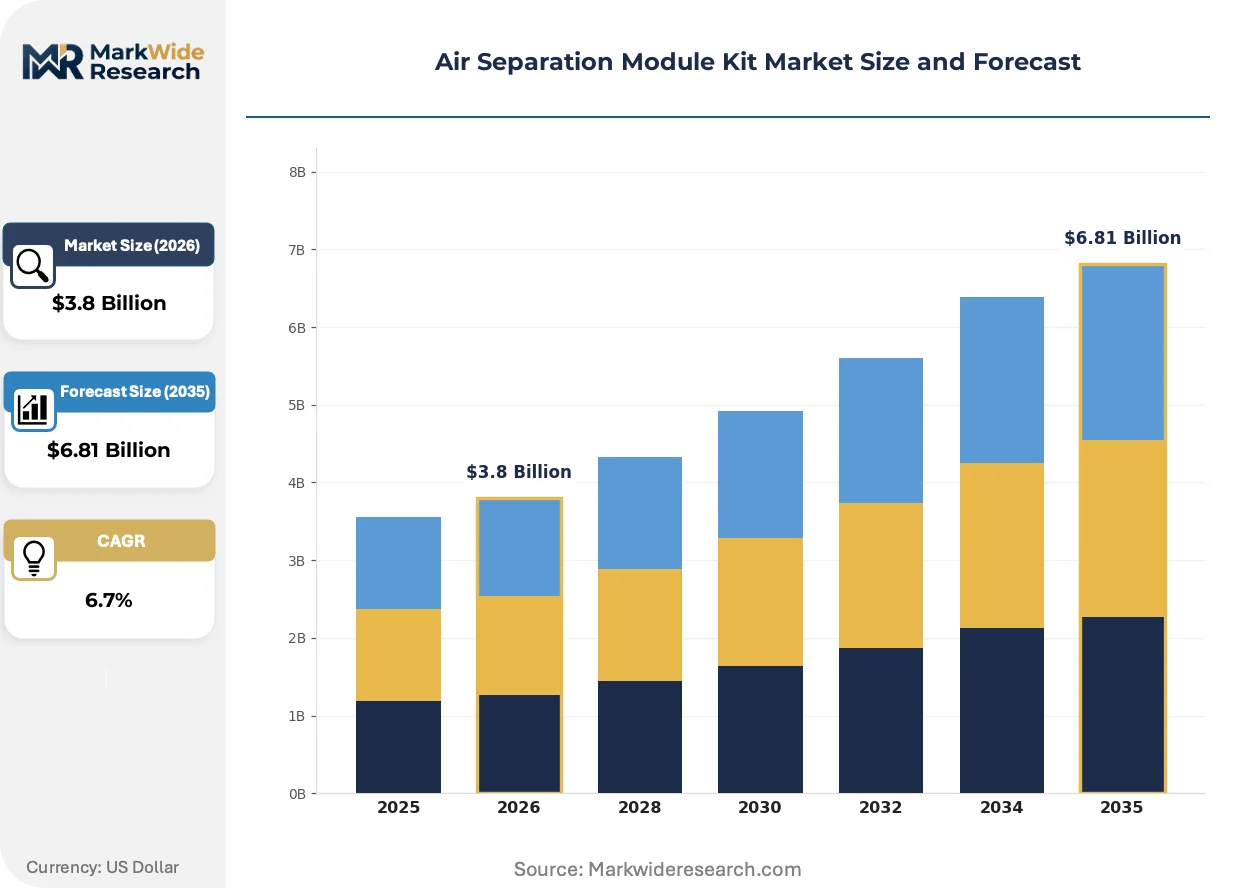
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PSA, Membrane, Cryogenic, Vacuum Pressure Swing Adsorption End User: Healthcare, Metal Production, Chemical Manufacturing, Energy Application: Oxygen Generation, Nitrogen Generation, Hydrogen Production, Argon Recovery Technology: Pressure Swing Adsorption, Absorption, Distillation, Vacuum Swing Adsorption |
| Companies Covered | Linde, Air Liquide, Air Products and Chemicals, Messer, Taiyo Nippon Sanso, Praxair Technology, Chart Industries, Gruppo SIAD, Universal Industrial Gases, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Air Separation Module Kit Market Evolving Landscape
Equipment intelligence and predictive maintenance architectures are reshaping how air separation modules are specified, operated, and serviced across industrial gas and captive generation installations.
Machine learning algorithms applied to vibration and purity sensor data are automating fault detection in PSA valve sequencing and membrane bundle degradation. Steelmakers with 24/7 oxygen demand are deploying these systems fastest, compressing maintenance windows and reducing unplanned outages that halt blast furnace operations. The technology is automating service contract structures, shifting revenue from scheduled visits to performance-guaranteed uptime agreements.
The EU F-Gas Regulation mandates phased reductions in hydrofluorocarbon use across refrigeration and industrial gas applications. Cryogenic system designers must evaluate propane, ethane, and nitrogen expander cycles as alternatives to conventional refrigerant loops. Semiconductor fabs in Germany and the Netherlands face the steepest compliance timelines, accelerating engineering validation of non-fluorinated distillation configurations.
Buying committees at steel and chemical complexes are unbundling aftermarket service from initial equipment procurement, forcing OEMs to compete for multi-year maintenance contracts against independent service providers. This behavior compresses upfront equipment margins while expanding the addressable pool for third-party technical support. The pattern is most visible in China's coastal province industrial clusters, where captive generation operators prioritize operational cost reduction over single-source supplier relationships.
Air Separation Module Kit Market Segmentation
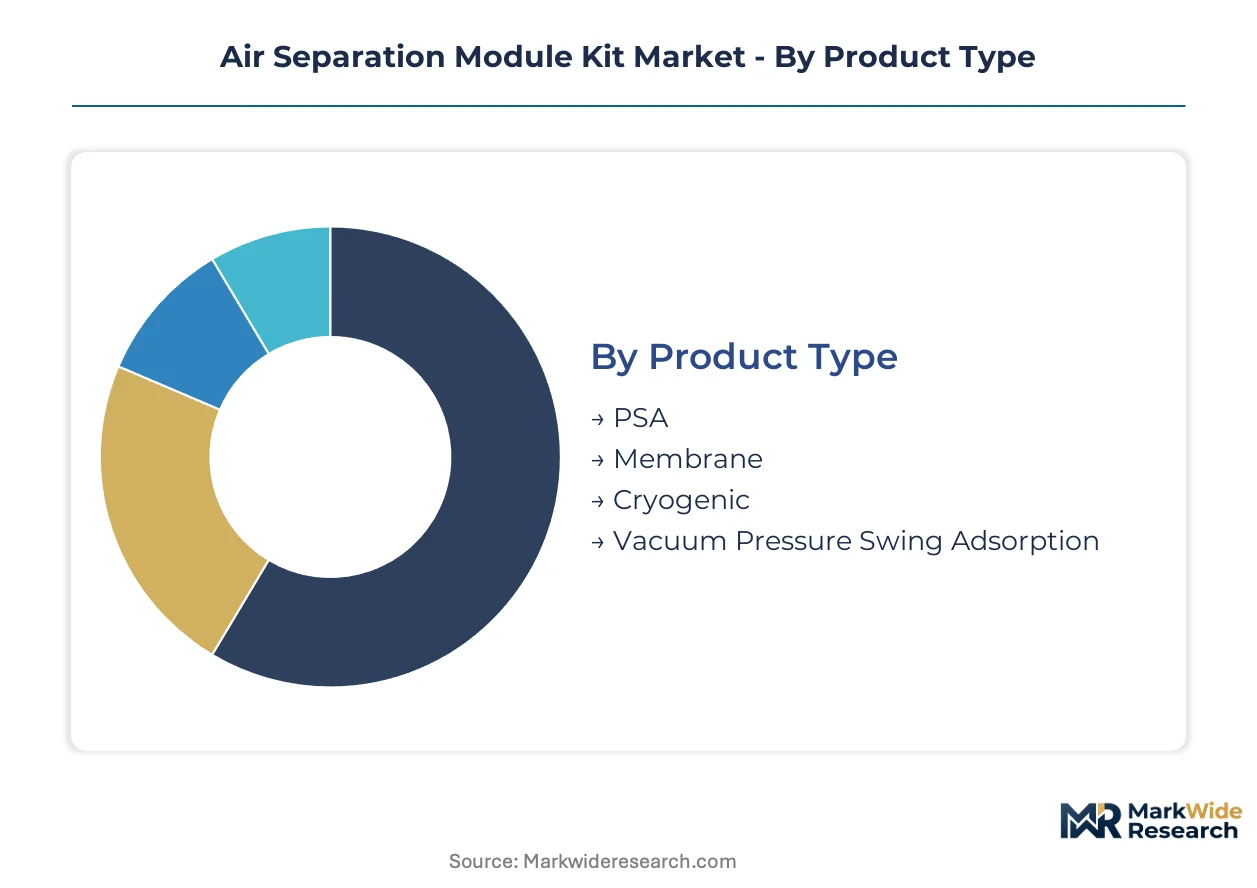
Segmentation in the air separation module kit market reveals how technology selection tracks capital intensity, purity requirements, and operational scale. Procurement committees weigh lifecycle energy costs against upfront equipment expenditure when matching product categories to captive generation or merchant gas supply models.
Product Type:
PSA systems dominate installed volumes while cryogenic units command premium pricing in high-purity applications.
- PSA:Pressure swing adsorption modules use zeolite molecular sieves to separate oxygen or nitrogen from compressed air through cyclic pressure changes. Steelmakers in China deploy these for captive oxygen supply at integrated mills, prioritizing modular expandability over absolute purity thresholds.
- Membrane:Hollow-fiber membrane bundles fractionate air through selective permeation, achieving lower purity at reduced energy input. Remote healthcare deployments and mobile military installations favor these systems where logistics constraints override purity specifications.
- Cryogenic:Multi-stage distillation at cryogenic temperatures delivers parts-per-billion purity for semiconductor fabrication.
- Vacuum Pressure Swing Adsorption:VPSA variants reduce desorption energy through vacuum pumps, improving efficiency for large-scale oxygen production.
Mature deployment sits with PSA. Newer deployment is concentrated in membrane systems.
End User:
Metal producers generate the highest equipment throughput, while healthcare applications impose the strictest certification requirements.
- Healthcare:Hospitals and clinics require FDA-validated oxygen purity for patient respiratory support, driving specification of certified PSA or cryogenic systems with redundant monitoring architectures.
- Metal Production:Basic oxygen furnaces and electric arc operations consume industrial oxygen at massive scale, creating demand for both captive PSA installations and bulk liquid supply infrastructure.
- Chemical Manufacturing:Nitrogen blanketing and inerting operations protect sensitive chemical processes from oxidation.
- Energy:Blue hydrogen projects integrate PSA units for syngas purification, transferring air separation expertise into emerging clean fuel supply chains.
Established demand concentrates in metal production. Expanding demand is visible in energy sector hydrogen integration.
Application:
Oxygen generation commands the largest equipment base, though hydrogen production applications are climbing the fastest.
- Oxygen Generation:Medical and industrial oxygen streams serve respiratory therapy, steelmaking, and wastewater treatment, with PSA technology capturing the mid-purity tier between bulk liquid and portable concentrators.
- Nitrogen Generation:Inerting and blanketing applications in electronics and food packaging favor membrane systems for their simplicity and minimal maintenance requirements.
- Hydrogen Production:PSA units processing syngas from steam methane reforming or gasification represent a converging application where air separation engineering applies directly to clean fuel infrastructure.
- Argon Recovery:Cryogenic distillation extracts argon from crude oxygen streams for welding shield gas and semiconductor crystal growth.
Volume leadership belongs to oxygen generation. Steepest expansion trajectory appears in hydrogen production applications.
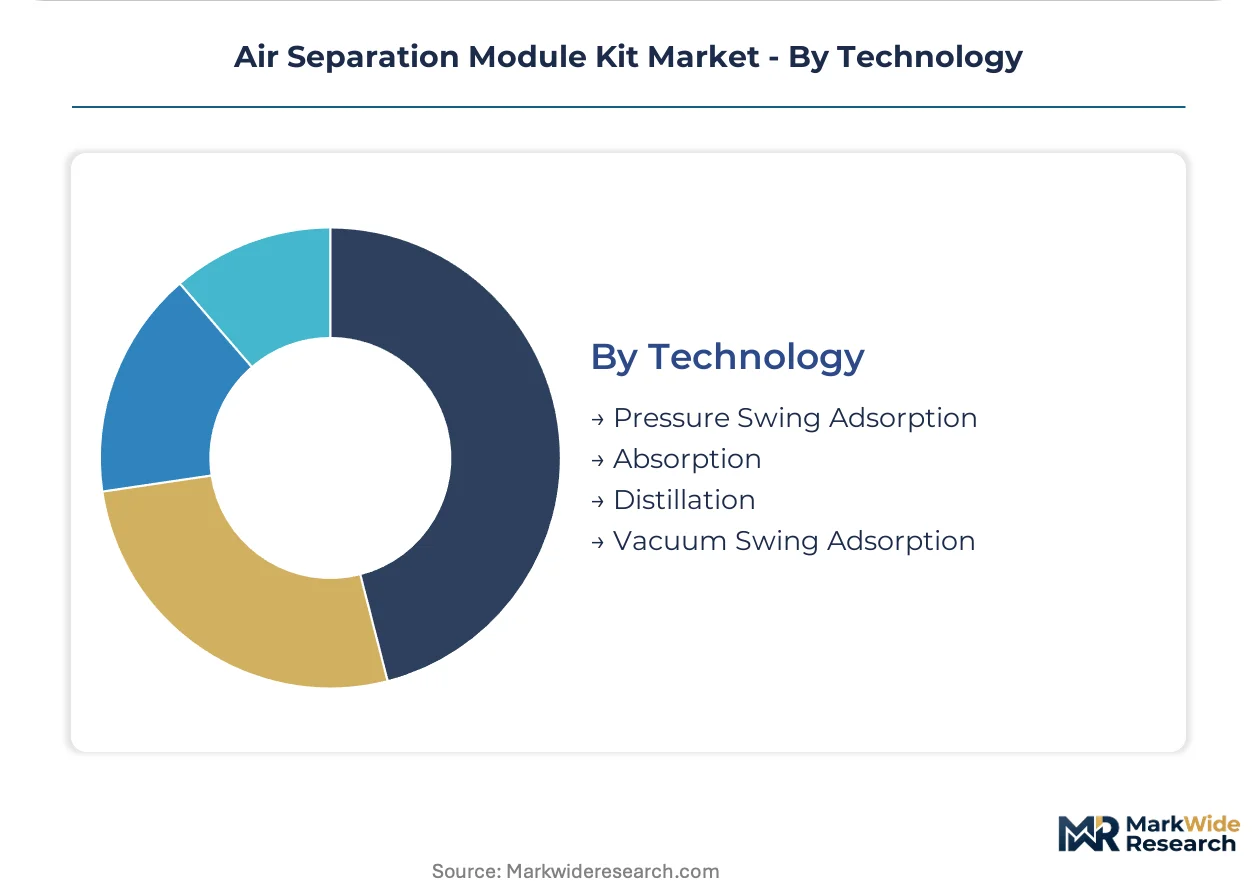
Technology:
Pressure swing adsorption anchors the installed base, while vacuum swing variants gain share in energy-intensive large-scale deployments.
- Pressure Swing Adsorption:Cyclic pressure changes drive selective adsorption on zeolite or carbon molecular sieves, dominating mid-scale applications where capital constraints limit cryogenic investment.
- Absorption:Chemical absorption systems remove acid gases or moisture from air feed streams, serving pretreatment roles rather than primary separation functions.
- Distillation:Cryogenic distillation achieves the highest purity thresholds through multi-stage temperature-fractionated separation, essential for semiconductor and specialty gas applications.
- Vacuum Swing Adsorption:Vacuum-assisted desorption reduces energy consumption versus conventional PSA, attracting steelmakers and chemical operators with high-volume oxygen requirements.
Conventional pressure swing adsorption represents the most mature technology platform. Vacuum swing configurations are gaining share in new large-capacity installations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Yangtze River Delta industrial corridor anchors equipment deployment, with Shanghai and Jiangsu province steel complexes driving captive oxygen and nitrogen generation demand.
China
Integrated steel mills in Hebei and Jiangsu provinces compress procurement timelines for modular PSA systems. The Ministry of Ecology and Environment enforces dual carbon goals that elevate energy efficiency requirements for captive generation. Tangshan steel cluster operators prioritize expandable membrane configurations for nitrogen blanketing operations.
United States
Healthcare facilities in Texas and California deploy on-site oxygen generation to secure supply chain resilience. EPA emissions standards force industrial gas producers toward low-GWP refrigerant cycles in cryogenic systems. The Houston Ship Channel petrochemical complex sustains demand for high-purity nitrogen in process inerting applications.
Germany
Semiconductor fabs in Dresden and Munich require parts-per-billion purity thresholds for argon and nitrogen streams. The EU F-Gas Regulation mandates phased hydrofluorocarbon reductions that accelerate alternative cryogenic cycle validation. The Bavarian chemical triangle sustains premium aftermarket service contracts for installed distillation units.
India
Steelmakers under the PLI scheme expand captive oxygen capacity for basic oxygen furnace operations. The Bureau of Indian Standards issues equipment certification protocols that elevate compliance costs for non-specialist entrants. The Odisha-Jharkhand iron ore belt concentrates greenfield installation demand for mid-scale PSA configurations.
Japan
Electronics manufacturers in Kyushu and the Kanto region sustain cryogenic system orders for wafer fabrication purity requirements. METI industrial decarbonization programs subsidize energy-efficient separation technology retrofits. The Nagoya automotive cluster drives nitrogen demand for laser cutting and thermal treatment processes.
Air Separation Module Kit Market Competitive Landscape
Premium-margin players sit above commodity-margin players across purity-tier segmentation, with cryogenic specialists commanding aftermarket service premiums while PSA assemblers compete on capital efficiency. The vendor base stratifies into three tiers: integrated industrial gas majors with full technology portfolios, regional equipment fabricators focused on modular PSA and membrane systems, and specialized cryogenic engineering houses serving semiconductor and healthcare verticals. Dominant competitive moves include vertical integration into adsorbent and membrane material supply, plus geographic expansion through local assembly partnerships in high-growth steel and chemical markets.
Within the integrated industrial gas tier, Linde and Air Liquide occupy positions that span cryogenic engineering heritage through dense service network coverage. Air Products and Chemicals exemplifies the service-revenue anchor model, sustaining long-term aftermarket streams independent of initial equipment procurement cycles. Among Asia-Pacific specialists, Taiyo Nippon Sanso represents the regional premium-purity archetype, with Messer occupying the flexible-demand tier between bulk supply and captive generation configurations.
| Leading Market Players |
|---|
| Linde |
| Air Liquide |
| Air Products and Chemicals |
| Messer |
| Taiyo Nippon Sanso |
| Praxair Technology |
| Chart Industries |
| Gruppo SIAD |
| Universal Industrial Gases |
| Others |
Value Network & Pricing Analysis
Steelmaker procurement committees in China anchor pricing power for modular PSA systems, compressing capital equipment margins while elevating long-term service contract premiums across captive generation deployments.
Pricing Analysis
Outcome-based pricing tied to guaranteed oxygen uptime anchors premium contracts for cryogenic systems serving semiconductor fabs in Dresden and Munich. Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated medical oxygen systems from industrial PSA units and commodity membrane configurations. Pricing pressure stems from unbundled aftermarket procurement in China's coastal industrial clusters, where captive operators prioritize operational cost reduction over single-source relationships. Steelmakers exhibit highest price sensitivity due to volume scale and energy cost exposure, while healthcare facilities accept premium positioning for regulatory compliance assurance.
Supply Chain Analysis
India's PLI scheme domestic-content mandates for steel equipment are reshaping sourcing patterns for PSA module assemblers serving integrated mill projects. Zeolite molecular sieve production concentrates in China and the United States, while hollow-fiber membrane bundles draw from Japan and Germany. Cryogenic cold box fabrication rests on qualified welding technicians concentrated in Germany and Japan. Single-source vulnerability in specialized adsorbent supply exposes assemblers to input cost volatility. Distribution runs through regional equipment fabricators with local assembly partnerships in high-growth steel and chemical markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EPA's medical gas purity mandates for US healthcare oxygen create a cost-of-compliance moat that elevates certification barriers and protects validated incumbents from non-specialist competition.
For Market Incumbents: To counter unbundled aftermarket procurement eroding upfront equipment margins, deepen service network density in China's Yangtze River Delta steel clusters and secure multi-year performance-guaranteed uptime agreements. Backward integration into zeolite molecular sieve production reduces input cost volatility exposure for PSA system manufacturers. For New Entrants and Emerging Players: Launch via mobile membrane system deployments serving remote healthcare and disaster response units where logistics constraints override purity specifications and FDA certification timelines are compressed. India's PLI scheme steel expansion offers the most penetrable greenfield installation demand for mid-scale PSA configurations without legacy service contract encumbrances. For Investors and Strategic Acquirers: The window for entry favors cryogenic engineering specialists with qualified vacuum-insulated cold box fabrication capabilities and established semiconductor fab relationships. Watch EU F-Gas Regulation compliance timelines as the inflection signal for alternative refrigerant cycle validation investments. Within these boundaries, the analytical envelope holds.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Adsorbent Supply | Captive zeolite molecular sieve production insulates PSA assemblers from China supply concentration risks. |
| Service Network Expansion | Dense technical coverage in Hebei and Jiangsu provinces captures unbundled aftermarket procurement from steelmakers. |
| Alternative Refrigerant Cycle Validation | Propane and nitrogen expander configurations address EU F-Gas Regulation phase-down mandates for German semiconductor fabs. |
| Mobile Membrane System Development | Lightweight configurations penetrate field hospital and military logistics applications beyond fixed infrastructure reach. |
| Hydrogen Production PSA Integration | Syngas purification expertise transfers directly into blue hydrogen project engineering for energy sector customers. |
Research Methodology
Multi-period observation of steelmaker captive generation deployments, EPA compliance retrofit timelines, and semiconductor fab capacity expansions anchored the trend analysis, supplemented by interviews with plant engineers at integrated mills, procurement leads at industrial gas majors, aftermarket service heads, and cryogenic welding technicians. Primary fieldwork combined with secondary validation from customs trade data, SEC filings of listed industrial gas producers, MEE environmental compliance disclosures, and hospital procurement databases. Bottom-up equipment shipment tracking and top-down industrial gas revenue analysis provided triangulation across the modeling period.
Input-output matrices modeled capacity installations, purity tier requirements, and energy efficiency specifications across product type, end-use vertical, application, and technology platform segmentation dimensions. CAGRs were derived from regression analysis of historical deployment patterns and forward projection of regulatory compliance deadlines. Forecast inputs incorporated steel production capacity expansion schedules under India's PLI scheme and EU F-Gas Regulation phase-down timelines affecting refrigerant selection.
Regulatory enforcement variance, adsorbent supply disruption, and cryogenic technician availability constraints are the dominant revision risks that could alter trajectory assumptions. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
HPHT Diamond Cubic Press Market
Others
China Packaging Primers Market
Others
Telecom Transformers Market
Others
Wearable Translator Market
Others
Bakery Packaging Market
Others
Eye Balm Market
Others
Fiber to the X (Fttx) Tester Market
Others
Asia-Pacific Eyelash Serum Market
Others
Global Food Fiber Market
Others
High-Performance Films Market
Others
Corn Fiber Market
Others
Green Technologies Market
Others
Europe Tablet PC Market
Others
South America Halal Food and Beverages Market
Others
Allogeneic T Cell Therapies Market
Others
Software Synthesizers Market