
 Ultrasonic Dissection Devices Market | 2026-2036
Ultrasonic Dissection Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Ultrasonic Dissection Devices Market Intelligence
The EU Medical Device Regulation is realigning the cost-of-entry calculus for ultrasonic dissection platforms by mandating expanded clinical evidence and post-market surveillance. Ethicon sustains its position through backward integration into generator and handpiece ecosystems. Olympus leverages its endoscopy-installed base to bundle ultrasonic instruments with visualization systems. Söring GmbH specializes in compact, mobile ultrasonic units for ambulatory settings where capital budgets constrain purchasing.
Ultrasonic dissection devices convert high-frequency electrical energy into mechanical vibrations, typically operating at frequencies between 20 kHz and 60 kHz to achieve tissue cutting and coagulation simultaneously with minimal thermal spread. These instruments serve primarily in minimally invasive and open surgical procedures where precise hemostasis reduces operative blood loss and improves visual field clarity. Ultrasonic scalpel systems anchor the product landscape due to their penetration across general surgery, gynecology, and thoracic disciplines. Single-use devices capture expanding share as hospitals prioritize infection control and eliminate reprocessing labor, while reusable instruments retain footholds in cost-sensitive surgical centers. Handheld device configurations dominate technology adoption where surgeon ergonomics and tactile feedback determine instrument selection.
FDA premarket notification requirements under 510(k) pathways shape product development timelines for manufacturers targeting the United States, while EMA oversight through notified body conformity assessments governs European market access. The EU AI Act introduces additional scrutiny for devices incorporating real-time tissue feedback algorithms, compelling firms to document decision transparency. Japan's PMDA maintains distinct biological safety testing protocols that extend registration cycles for foreign entrants. Stakeholders must monitor how divergent evidentiary standards across FDA, EMA, and PMDA jurisdictions influence portfolio prioritization and regulatory investment thresholds.
Market Dynamics
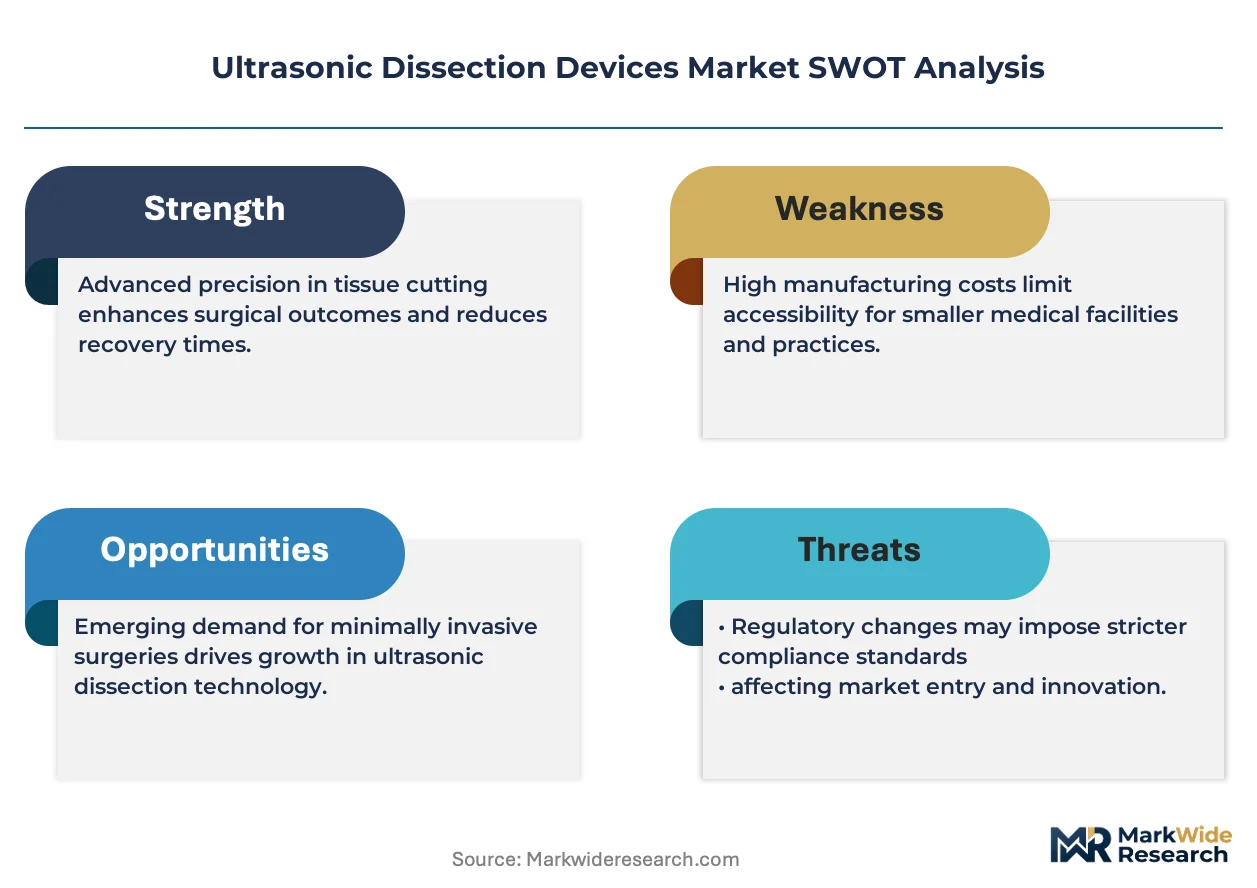
The EU Medical Device Regulation is compressing market entry timelines by demanding expanded clinical evidence for ultrasonic dissection platforms, forcing manufacturers to reallocate R&D budgets toward post-market surveillance infrastructure and notified body conformity assessments.
Growth Catalysts
- Minimally invasive surgery expansion:Laparoscopic suites in tertiary hospitals across Germany, France, and Japan are standardizing ultrasonic platforms for precision hemostasis in general surgery and gynecology procedures.
- REACH and RoHS compliance:European environmental frameworks are accelerating material substitutions in device coatings, driving innovation in biocompatible surface treatments that reduce thermal spread.
- Single-use preference:Infection control protocols in US academic medical centers are displacing reusable instrument reprocessing, expanding demand for disposable ultrasonic handpieces and generator-compatible cartridges.
Market Restraints
- Generator and handpiece ecosystem lock-in:Proprietary coupling between energy sources and instruments creates switching costs that fragment hospital procurement flexibility and entrench incumbent suppliers.
- Palladium and ceramic transducer supply:Concentration of piezoelectric material refining in China exposes manufacturers to export quota volatility and input cost spikes.
- Thermal injury litigation exposure:Malpractice claims related to unintended tissue necrosis from ultrasonic energy spread are elevating product liability premiums and defensive documentation requirements.
Strategic Opportunities
- Ambulatory surgical center penetration:Compact, mobile ultrasonic units address capital budget constraints in US outpatient facilities performing high-volume cholecystectomy and thyroidectomy procedures.
- EU AI Act algorithmic transparency:Real-time tissue feedback systems incorporating machine learning classification of vessel sealing quality can claim regulatory differentiation if decision pathways are auditable.
- Veterinary surgery crossover:Adaptation of human-scale ultrasonic instruments for companion animal soft-tissue procedures opens a channel with lower regulatory barriers and faster product iteration cycles.
Industry Challenges
- Notified body capacity bottlenecks:EU MDR designation shortages are extending technical documentation review timelines, delaying market authorization for iterative product improvements.
- Surgeon training standardization:Variability in tactile feedback interpretation across ultrasonic platforms requires device-specific credentialing that fragments hospital staff flexibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ultrasonic Dissection Devices Market |
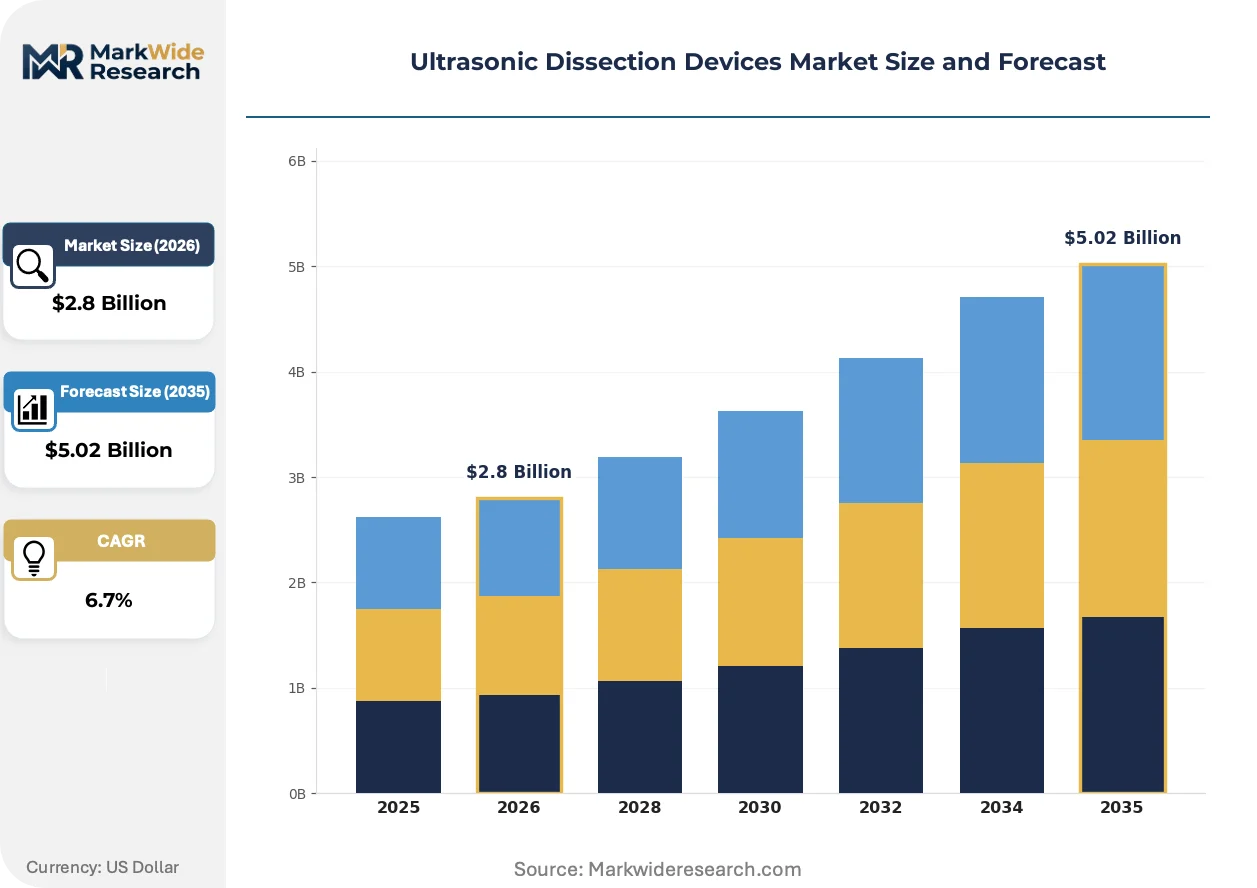
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ultrasonic Scalpel, Ultrasonic Aspirator, Ultrasonic Surgical Instruments, Combined Devices Application: Surgical Procedures, Tissue Dissection, Hemostasis, Tumor Resection End User: Hospitals, Surgical Centers, Research Institutions, ambulatory Surgical Centers Technology: Single-Use Devices, Reusable Instruments, Ultra-Frequency Devices, Handheld Devices |
| Companies Covered | Olympus Corporation, InnoSound Technologies, Inc., Ethicon (Johnson & Johnson), Söring GmbH, ConMed Corporation, Medtronic, BOWA-electronic GmbH & Co. KG, Misonix Inc., Stryker Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ultrasonic Dissection Devices Market Strategic Shifts & Innovations
Active feedback systems and material science advances are compressing the performance gap between premium and mid-tier ultrasonic platforms, while procurement organizations consolidate vendor relationships around integrated visualization-energy ecosystems.
Adaptive impedance monitoring is rewriting how ultrasonic generators modulate energy delivery during tissue transection. University hospitals in Germany and Japan are piloting these systems for real-time adjustment of vibration amplitude based on tissue density variation. The technology is compressing the learning curve for junior surgeons and reducing variation in vessel sealing outcomes across operator experience levels.
The EU AI Act's risk classification framework for software-as-a-medical-device is imposing documentation burdens on manufacturers embedding tissue recognition algorithms in next-generation generators. Firms must demonstrate decision transparency and post-deployment performance monitoring, with the highest scrutiny falling on systems claiming autonomous sealing parameter selection. Japanese PMDA is observing these European precedents for potential alignment in its software medical device guidance.
Hospital value analysis committees are unbundling service contracts from capital equipment purchases, negotiating preventive maintenance and training separately from generator and handpiece acquisition. This pattern is most pronounced in US integrated delivery networks consolidating procurement across multiple surgical sites, where standardization incentives override traditional distributor relationships.
Ultrasonic Dissection Devices Market Segmentation
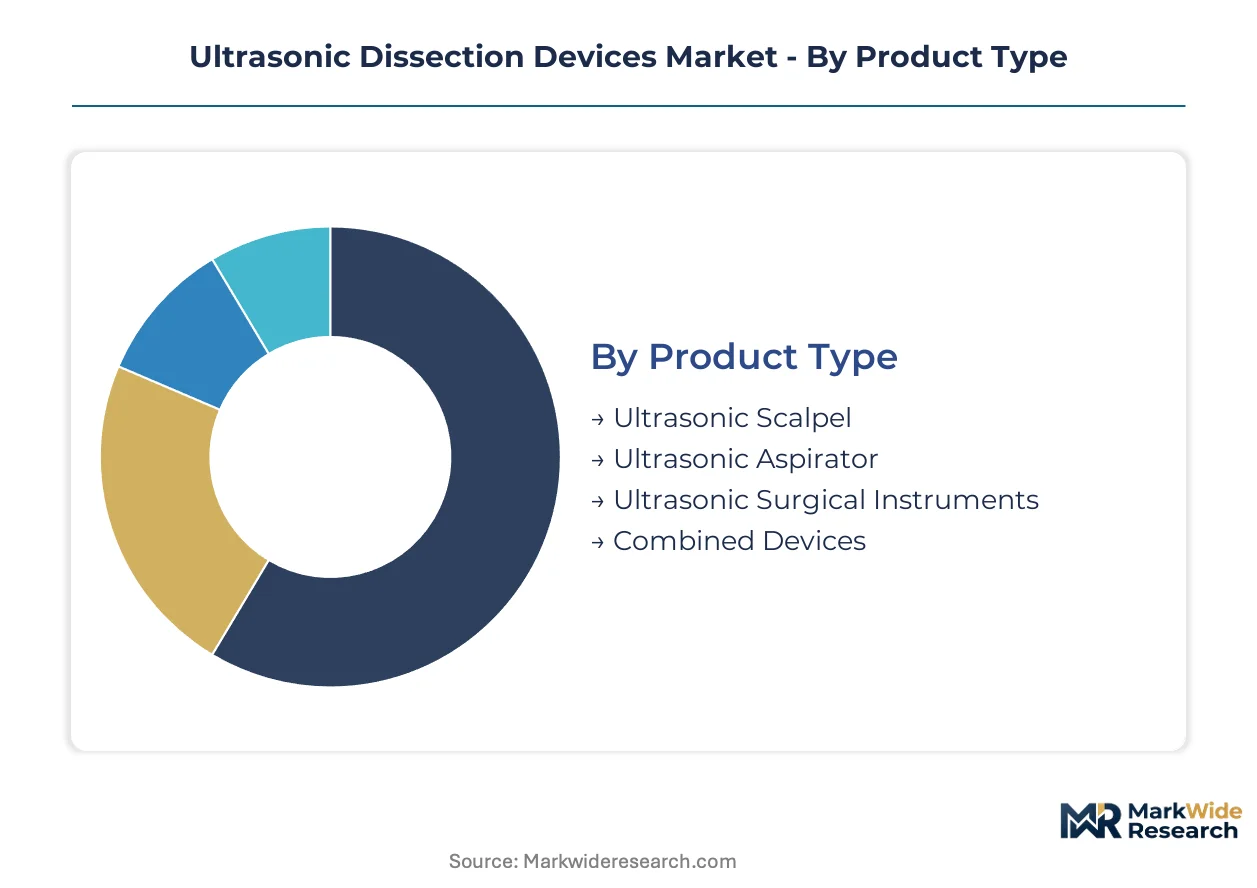
Segmentation in ultrasonic dissection devices reveals how procurement priorities diverge across surgical settings, from capital-intensive tertiary hospitals to budget-constrained outpatient facilities. Understanding these fault lines helps manufacturers align product portfolios with specific customer economics and regulatory exposure.
Product Type:
Hospital procurement committees differentiate platforms based on procedure volume, capital budget cycles, and the depth of existing generator ecosystems.
- Ultrasonic Scalpel:These instruments convert electrical energy into longitudinal mechanical vibrations at 55.5 kHz, enabling simultaneous cutting and coagulation with thermal spread limited to 1-2 mm. Demand concentrates in German university hospitals where integrated visualization suites drive bundled purchasing of generator-handpiece systems.
- Ultrasonic Aspirator:Devices combining fragmentation with suction evacuation operate at lower frequencies to preserve tissue architecture for pathological analysis. Neurosurgical departments in Japan's metropolitan medical centers prioritize these systems for tumor debulking where specimen integrity determines adjuvant therapy decisions.
- Ultrasonic Surgical Instruments:Specialized forceps and shears extend ultrasonic energy to grasping and dissecting functions in thoracic and hepatobiliary procedures.
- Combined Devices:Hybrid platforms integrating ultrasonic and radiofrequency modalities address cost-sensitive surgical centers seeking single-generator versatility.
Ultrasonic Scalpel leads volumes today; Combined Devices is gaining share fastest.
Application:
Procedure-specific requirements dictate energy delivery profiles, with vessel sealing quality standards varying across surgical disciplines and regulatory jurisdictions.
- Surgical Procedures:General surgery applications spanning cholecystectomy, colectomy, and gastrectomy represent the core installed base, with procedure volume in US academic medical centers driving standardized platform adoption.
- Tissue Dissection:Precision transection in anatomically confined spaces demands adaptive impedance monitoring, a capability university hospitals in Germany pilot for real-time feedback during hepatobiliary resection.
- Hemostasis:Vessel sealing up to 5 mm diameter anchors ultrasonic platform value propositions in gynecologic and urologic laparoscopy where blood loss quantifies outcomes.
- Tumor Resection:Oncologic margins and thermal damage thresholds impose distinct generator calibration requirements, with Japanese PMDA protocols extending validation timelines for cancer surgery claims.
Hemostasis commands the largest addressable base; Tumor Resection shows the steepest expansion trajectory.
End User:
Capital intensity and reprocessing infrastructure separate institutional buyers, with reimbursement pathways determining whether disposable or reusable economics prevail.
- Hospitals:Tertiary institutions with dedicated sterile processing departments amortize reusable instrument costs across high procedure volumes, though infection control protocols in US academic centers are shifting preference toward single-use handpieces.
- Surgical Centers:Freestanding facilities prioritize compact, mobile generators compatible with multi-specialty scheduling and limited storage footprints.
- Research Institutions:Preclinical and translational surgery programs drive demand for configurable platforms supporting protocol customization and data logging.
- Ambulatory Surgical Centers:Outpatient settings performing high-volume thyroidectomy and hernia repair favor generator-compatible disposable cartridges that eliminate reprocessing labor and liability exposure.
Hospitals retain volume leadership; Ambulatory Surgical Centers are climbing the fastest.
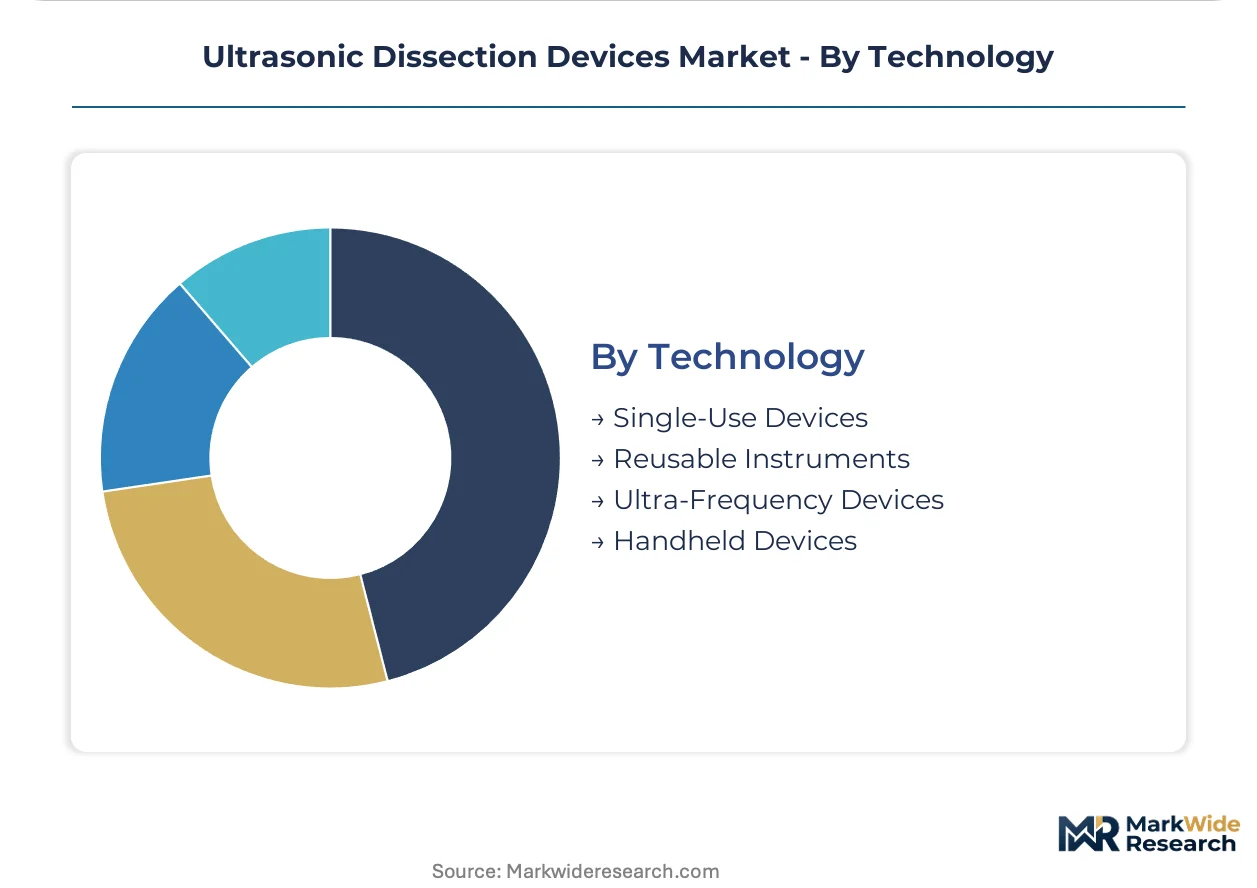
Technology:
Material science and regulatory classification frameworks differentiate technology tiers, with piezoelectric transducer specifications determining performance ceilings.
- Single-Use Devices:Disposable handpieces and generator cartridges eliminate cross-contamination risk and reprocessing validation burdens. US integrated delivery networks consolidating procurement across multiple sites are standardizing on single-use protocols to reduce sterilization department overhead.
- Reusable Instruments:Titanium alloy handpieces with ceramic transducer stacks withstand thousands of activation cycles, retaining footholds in cost-sensitive European markets where MDR documentation costs already strain capital budgets.
- Ultra-Frequency Devices:Extended frequency ranges above 60 kHz enable finer dissection control in ophthalmic and otologic microsurgery.
- Handheld Devices:Ergonomic pistol-grip and pencil-grip configurations dominate surgeon preference studies, with tactile feedback quality influencing platform loyalty and training investment.
Reusable Instruments leads current installed base; Single-Use Devices is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany pioneered ultrasonic surgical technology through university hospital research consortia in the 1990s, establishing the technical foundations that now diffuse across OECD surgical markets. The installed base of generator-handpiece systems concentrates where tertiary laparoscopic volumes justify capital investment and specialized training infrastructure.
United States
Academic medical centers in Boston, Houston, and the Research Triangle drive procurement of integrated ultrasonic platforms for minimally invasive fellowship training programs. FDA 510(k) premarket notification pathways shape product development timelines for energy-based surgical instruments targeting these institutions. The Cleveland Clinic and Mayo Clinic surgical networks standardize generator ecosystems across multi-site integrated delivery networks, consolidating vendor relationships and service contracts.
Germany
University hospitals in Munich, Heidelberg, and Berlin anchor European demand for adaptive impedance monitoring systems in hepatobiliary and thoracic procedures. EU MDR notified body conformity assessments extend technical documentation review timelines, compressing market entry windows for iterative product improvements. The Tübingen-Stuttgart surgical corridor hosts specialized training centers where device-specific credentialing programs reduce variation in vessel sealing outcomes across operator experience levels.
Japan
Metropolitan medical centers in Tokyo, Osaka, and Nagoya prioritize ultrasonic aspirator systems for neurosurgical tumor debulking where specimen integrity determines adjuvant therapy protocols. PMDA biological safety testing protocols extend registration cycles for foreign entrants, favoring domestic distributors with established quality management relationships. The Kobe-Kyoto medical device cluster supports translational surgery programs piloting real-time tissue feedback algorithms.
China
Provincial hospital networks in Shanghai, Beijing, and Guangzhou scale laparoscopic suite standardization as tiered healthcare reform expands surgical access beyond tertiary centers. NMPA medical device registration requirements for energy-based instruments tighten clinical evidence standards, aligning with international harmonization initiatives. The Suzhou industrial park concentrates piezoelectric transducer component manufacturing, exposing supply chains to export quota volatility in ceramic material refining.
United Kingdom
NHS foundation trusts in London, Manchester, and Birmingham negotiate value analysis frameworks that unbundle service contracts from capital equipment purchases for ultrasonic platforms. MHRA post-market surveillance requirements under retained EU MDR obligations elevate documentation burdens for manufacturers maintaining UK market access. The Oxford-Cambridge life sciences corridor supports early-stage ventures developing compact mobile units for ambulatory surgical center penetration.
Ultrasonic Dissection Devices Market Key Industry Players
The competitive structure tilts toward diversified medical technology conglomerates with backward integration into generator and visualization ecosystems. Tiered concentration separates integrated platform vendors from specialized component suppliers and regional service providers. Dominant archetypes include endoscopy-installed-base leveragers, energy-system pure-plays, and ambulatory-focused compact equipment specialists. Capacity expansion in ceramic transducer manufacturing and strategic partnerships for algorithmic tissue feedback represent the primary competitive vectors reshaping positioning.
Among diversified conglomerates, Ethicon and Olympus occupy positions exemplifying ecosystem bundling strategies that entrench procurement relationships through generator-handpiece interdependence. Söring GmbH represents the compact equipment archetype, anchoring a tier focused on capital-constrained surgical settings where mobility and reduced footprint address budget limitations. These three firms illustrate how geographic origin and corporate structure map onto divergent strategic postures across the premium-standard-economy spectrum.
| Leading Market Players |
|---|
| Olympus Corporation |
| InnoSound Technologies, Inc. |
| Ethicon (Johnson & Johnson) |
| Söring GmbH |
| ConMed Corporation |
| Medtronic |
| BOWA-electronic GmbH & Co. KG |
| Misonix Inc. |
| Stryker Corporation |
| Others |
Cost & Logistics Intelligence
Premium generator-handpiece ecosystems and compact mobile units diverge across a performance-capability gap that manifests in both procurement economics and component sourcing strategies. Bundled service contracts for integrated platforms command sustained premiums in German university hospitals, while unbundled capital purchases dominate US ambulatory surgical centers where disposable cartridge economics override long-term service relationships.
Pricing Analysis
Bundled-versus-unbundled service splits define pricing architecture across institutional buyer tiers. Three-tier pricing structure across premium, standard, and economy levels reflects generator compatibility depth, CE-MDR certification grade, and after-sales training inclusion. Pricing pressure stems from hospital value analysis committees negotiating preventive maintenance separately from equipment acquisition. Ambulatory surgical centers exhibit highest price sensitivity; integrated delivery networks standardizing across multi-site networks show lowest.
Supply Chain Analysis
CE-MDR and FDA 510(k) qualification gating concentrates qualified component supply among established transducer manufacturers. Ceramic piezoelectric materials draw from China, Japan, and Germany; titanium alloy handpiece fabrication centers on Switzerland and the United States. Palladium electrode supply rests on export quota volatility from Chinese refining concentration. Distribution runs through specialized surgical device distributors with generator-sterilization field service capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The ultrasonic dissection devices market compounds steadily as minimally invasive procedure volumes expand across OECD surgical markets. Laparoscopic suite standardization in tertiary hospitals provides durable demand visibility.
For Market Incumbents: Extend generator ecosystem lock-in through backward integration into transducer manufacturing and algorithmic tissue feedback R&D. Counter compact mobile entrants by unbundling service contracts to match ambulatory procurement flexibility. Prioritize notified body relationship investment to compress EU MDR documentation timelines. For New Entrants and Emerging Players: Freestanding ambulatory surgical centers in the United States represent the most penetrable buyer archetype with capital budget constraints and limited incumbent loyalty. Target compact mobile unit segments where generator portability and disposable cartridge economics displace reusable instrument reprocessing. Pursue veterinary surgery crossover applications for faster regulatory iteration cycles. For Investors and Strategic Acquirers: Consolidation pressure builds where EU MDR compliance costs fragment mid-tier manufacturers lacking notified body scale. Position for 5-10 year viability around algorithmic transparency capabilities under EU AI Act scrutiny. Monitor ceramic transducer supply quota announcements from Chinese export authorities as inflection indicators for input cost compression or spike.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway Acceleration | EU MDR notified body pre-submission reduces technical documentation review timelines for iterative generator improvements. |
| Hospital System Partnership | Integrated delivery network standardization contracts lock multi-site procurement across US academic medical centers. |
| Software Companion Development | Real-time tissue feedback algorithms under EU AI Act transparency requirements differentiate premium generator positioning. |
| Backward Integration into Transducers | Captive ceramic piezoelectric supply mitigates Chinese export quota exposure and stabilizes input cost profiles. |
| Reimbursement Strategy | CPT code alignment for ultrasonic vessel sealing in outpatient thyroidectomy expands ambulatory addressable volume. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary engagement with surgeons, hospital purchasing committee members, biomedical engineers, and GPO contracts managers informed demand-side validation. Secondary sources included FDA 510(k) premarket notification databases, EMA notified body conformity assessment records, CMS Medicare procedure volume data, and hospital procurement contract repositories. Bottom-up installed base modeling and top-down surgical procedure demand triangulation anchored volume estimates.
Comparable-period anchoring linked historical generator shipment data to forward projection assumptions across the modeling period. Segmentation dimensions spanned product type, application discipline, end-user facility tier, and technology configuration. CAGRs derived from logistic adoption curve fitting to laparoscopic suite penetration rates and single-use preference trajectories. Forecast inputs incorporated EU MDR implementation pace and PMDA software medical device guidance evolution.
Underlying measurement precision varies by segment; single-use device demand carries tighter precision than reusable instrument forecasting due to procurement contract visibility. Projections reflect documented assumptions regarding minimally invasive surgery adoption and regulatory harmonization timelines. A model refresh is warranted upon material change in EU notified body capacity or ceramic transducer export quota policy.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Arteriosclerosis Detector Market
Medical Devices
Global Auto-Injectors Market
Medical Devices
Radiofrequency-Based Aesthetic Devices Market
Medical Devices
Platelet Concentration Systems Market
Medical Devices
Epilepsy Treatment Devices Market
Medical Devices
Asia-Pacific Integrated Operating Room System Market
Medical Devices
Global Medical Laser Systems Market
Medical Devices
Orthokeratology Lens Market
Medical Devices
Intraoral Scanners Market
Medical Devices
Bone Power Tools Market
Medical Devices
Middle East and Africa Single-Use Medical Device Reprocessing Market
Medical Devices
Low Vision Aids Market
Medical Devices
Digital Body Thermometer Market
Medical Devices
Pen Needles Market
Medical Devices
Asia Pacific Apheresis Market
Medical Devices
External Nasal Dilator Market