
 Bone Power Tools Market | 2026-2036
Bone Power Tools Market Size, Share, and Industry Trends Forecast 2026-2036
Bone Power Tools Market Insights
A shift from single-source procurement to multi-source contracting is recalibrating how hospital systems evaluate bone power tool vendors. Stryker leverages its integrated surgical ecosystem to bundle power tools with implant systems. Zimmer Biomet anchors its position through deep specialization in orthopedic power systems for joint reconstruction. Medtronic competes by extending its navigated surgery platforms into powered instrument workflows.
Bone power tools are motorized surgical instruments designed to cut, drill, shape, or prepare bone tissue during operative procedures, typically operating at rotational speeds between 5,000 and 80,000 RPM depending on the specific osseous application. These instruments serve as critical enabling technology across orthopedic, trauma, and spinal surgeries where manual tools cannot achieve requisite precision or efficiency. Electromechanical technology leads the product landscape due to its torque consistency and battery portability, while pneumatic systems retain share in high-volume hospital settings where infrastructure supports compressed gas lines. Joint replacement applications command the largest share of procedure volume, though osteotomy applications are gaining traction as sports medicine and limb-alignment procedures expand.
FDA 510(k) premarket notification requirements govern device safety and electromagnetic compatibility for bone power tools sold in the United States, while the EU MDR imposes stricter clinical evidence and post-market surveillance obligations for European market access. ISO 13485 quality management certification has become a baseline expectation for supplier qualification by major hospital purchasing consortia. Stakeholders must monitor evolving battery chemistry standards and reusable-sterilization validation protocols as sustainability pressures intersect with surgical economics.
Market Dynamics
Hospital procurement consortia are consolidating vendor relationships, forcing bone power tool manufacturers to demonstrate total cost-of-ownership superiority across sterilization cycles, battery longevity, and instrument service life.
Growth Catalysts
- EU MDR compliance deadlines:Stricter post-market surveillance requirements are accelerating replacement cycles for legacy devices as hospitals preemptively upgrade to certified systems.
- Battery chemistry advances:Lithium-ion cell energy density improvements are extending cordless tool runtime, enabling ambulatory surgical centers to perform complex procedures without pneumatic infrastructure.
- Joint replacement volume concentration:Germany, the United States, and Japan are expanding orthopedic surgical suite capacity, directly lifting installed base demand for powered bone instruments.
Market Restraints
- Lithium and cobalt price volatility:Battery raw material cost swings compress margins for cordless tool portfolios and complicate long-term contract pricing.
- Pneumatic infrastructure lock-in:High-volume hospital systems with sunk investment in compressed gas lines face switching costs that slow electromechanical adoption despite portability advantages.
- FDA 510(k) electromagnetic compatibility testing:Pre-market notification requirements for radio-frequency emitting devices extend development timelines and raise regulatory compliance expenditure.
Strategic Opportunities
- Ambulatory surgery center expansion:United States outpatient joint replacement volume growth creates demand for compact, battery-powered systems that operate independent of hospital infrastructure.
- Reusable sterilization validation protocols:Sustainability mandates from hospital purchasing consortia favor manufacturers with validated multi-cycle instrument durability data.
- Navigated surgery platform integration:Convergence of robotic positioning systems with powered handpieces enables real-time bone cutting guidance, opening premium pricing tiers.
Industry Challenges
- Biomedical engineer specialization:Shortage of technicians trained in both electromechanical repair and sterile processing protocols complicates field service deployment.
- ISO 13485 certification timeline:Quality management system audits for supplier qualification create 12-18 month onboarding delays for new component vendors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bone Power Tools Market |
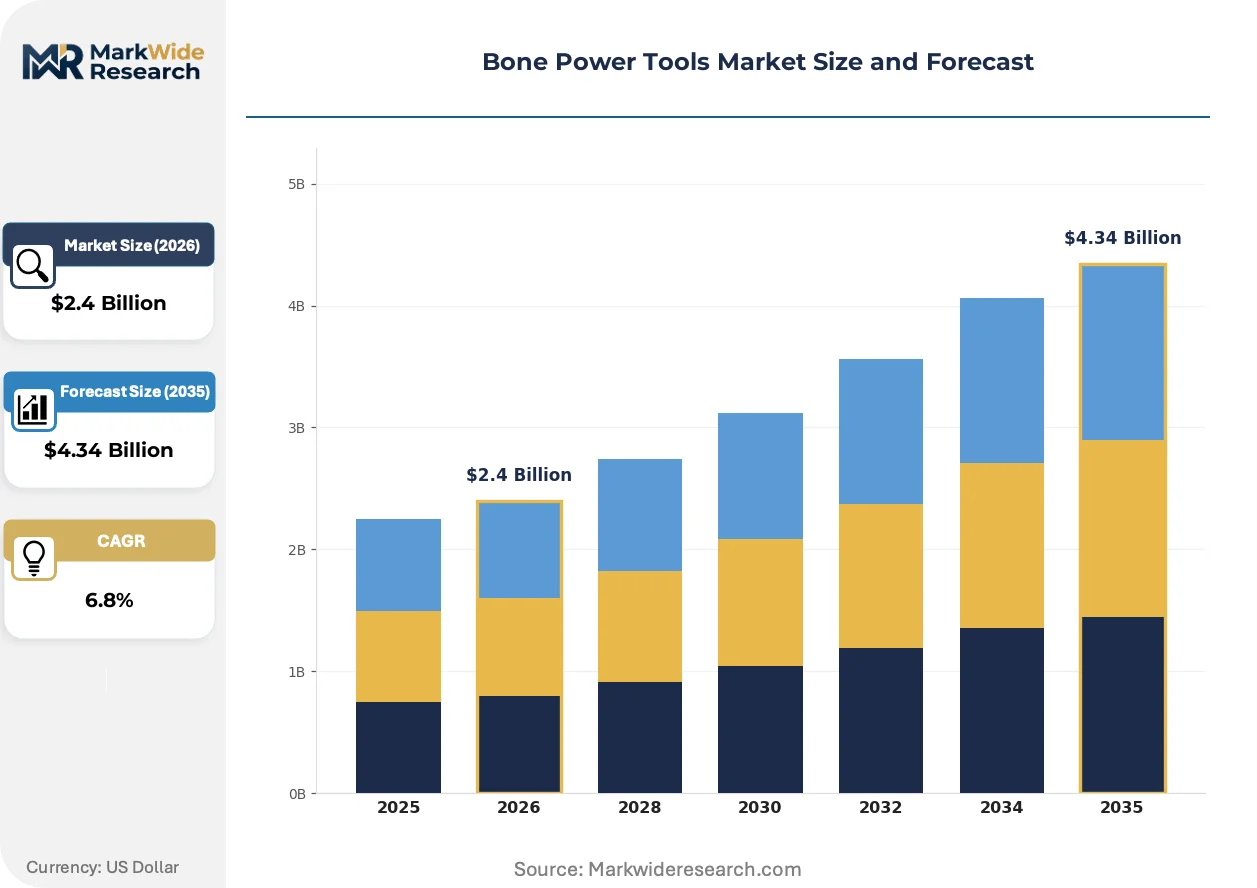
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.34 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hand Tools, Power Tools, Cutting Tools, Pneumatic Tools End User: Veterinary Practices, Research Labs, Bone Clinics, Hospitals Application: Fracture Repair, Bone Grafting, Osteotomy, Joint Replacement Technology: Electromechanical, Pneumatic, Hydraulic, Laser |
| Companies Covered | Stryker, Zimmer Biomet, Medtronic, Smith+Nephew, B. Braun Melsungen AG, CONMED Corporation, DePuy Synthes, Arthrex, NSK/Nakanishi Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bone Power Tools Market Trends and Innovations
Surgical workflow digitization is redefining how bone power tools integrate with broader operative ecosystems, from pre-operative planning software to post-procedure instrument tracking systems.
Brushless DC motor technology is converging with smart sensor arrays to enable real-time torque feedback and automatic speed modulation based on bone density detection. Tertiary care hospitals in the United States and Germany are piloting these intelligent handpieces for complex revision arthroplasty cases. This convergence is compressing the performance gap between high-end pneumatic systems and cordless electromechanical alternatives.
EU MDR Article 10 clinical evidence requirements are compelling manufacturers to generate post-market performance data through implant registries and patient follow-up studies. The regulatory burden falls heaviest on small-to-mid sized instrument suppliers lacking established clinical affairs infrastructure. European orthopedic consortia are responding by pooling procurement volume to favor vendors with demonstrated MDR technical documentation compliance.
Hospital value analysis committees are unbundling power tool acquisition from implant system contracts, creating standalone competitive bidding events for instrument fleets. This disintermediation of traditional bundled pricing is most pronounced in United States integrated delivery networks exceeding ten hospital facilities. Orthopedic service line directors now evaluate total cost per procedure across battery replacement cycles, sterilization throughput, and repair turnaround intervals rather than upfront capital expenditure alone.
Bone Power Tools Market Segmentation
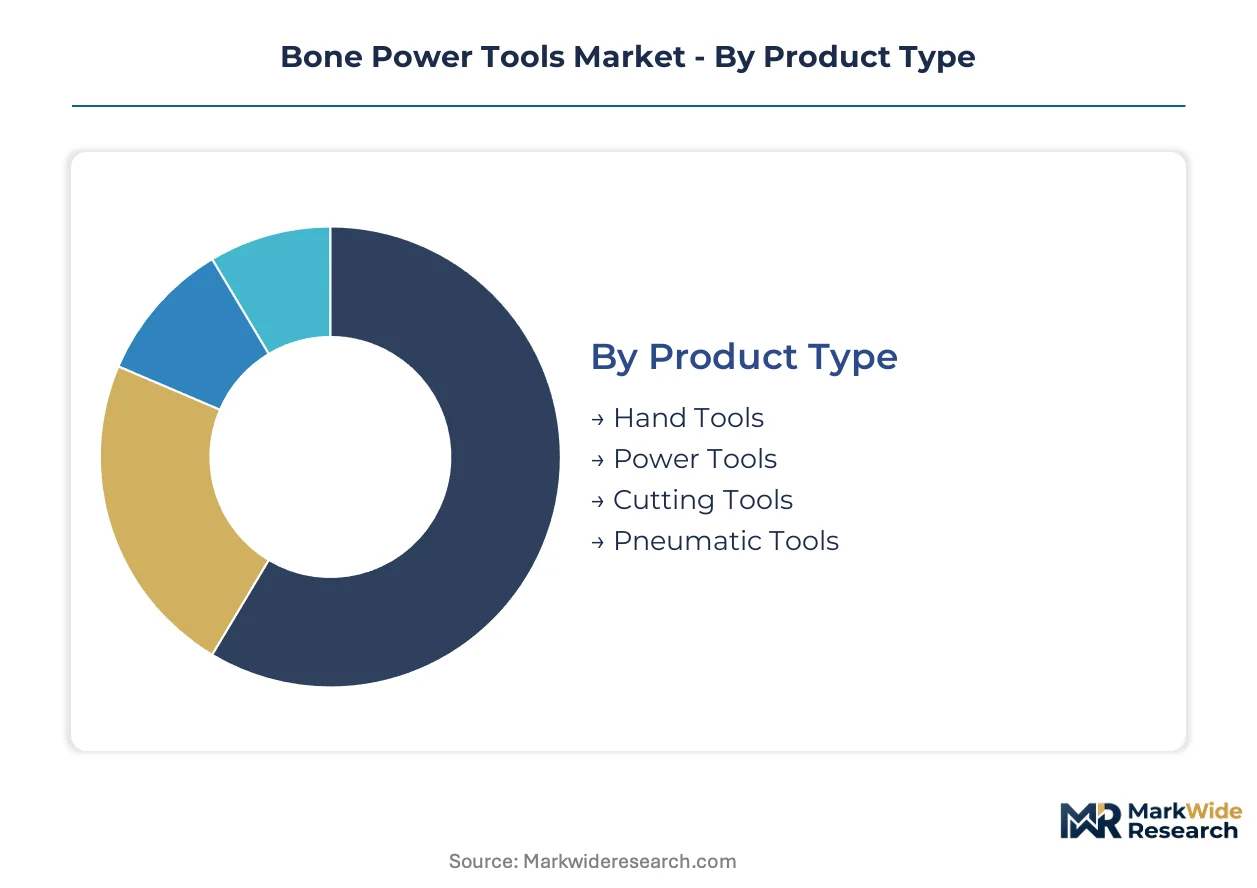
Bone power tools serve distinct clinical workflows requiring different performance specifications, sterilization protocols, and integration capabilities. Segmentation reveals where manufacturers must prioritize battery chemistry innovation versus pneumatic infrastructure compatibility.
Product Type:
Integration depth varies sharply across this category, with standalone handheld systems dominating ambulatory settings while console-integrated platforms anchor hospital surgical suites.
- Hand Tools:Manual instruments with mechanical advantage mechanisms for bone manipulation and preparation. Demand concentrates in veterinary practices and resource-constrained settings where capital equipment investment is limited by budget cycles.
- Power Tools:Motorized devices operating via battery packs or line power, delivering rotational force for cutting and drilling. United States ambulatory surgery centers are expanding procurement of cordless systems to enable outpatient joint procedures independent of hospital infrastructure.
- Cutting Tools:Specialized blades, saws, and burrs designed for precise osseous resection. German orthopedic consortia prioritize validated multi-cycle sterilization durability in vendor selection criteria.
- Pneumatic Tools:Compressed-gas-driven instruments offering sustained high-torque output for high-volume surgical environments. Japanese tertiary hospitals retain significant installed base due to sunk infrastructure investment in operating room gas delivery systems.
Power tools lead volumes today; pneumatic tools are gaining share fastest in emerging surgical hub expansions.
End User:
Customer type determines pricing tolerance, service contract structure, and regulatory documentation requirements across this market.
- Veterinary Practices:Animal orthopedic applications requiring scaled-down instrument specifications and simplified sterilization protocols. United States specialty veterinary hospitals are upgrading to battery-powered systems for mobility between surgical suites.
- Research Labs:Academic and commercial research facilities conducting biomechanical studies and device validation. ISO 13485 certification is mandatory for supplier qualification by major research institutions.
- Bone Clinics:Dedicated orthopedic outpatient facilities focused on fracture management and minor procedures. Ambulatory expansion in Germany is driving demand for compact, multi-procedure instrument sets.
- Hospitals:Integrated health systems with comprehensive surgical service lines and centralized sterile processing departments. United States hospital procurement consortia are unbundling power tool acquisition from implant contracts, creating standalone competitive bidding events.
Hospitals dominate current procurement value; bone clinics are expanding most quickly as outpatient migration accelerates.
Application:
Procedure complexity and reimbursement levels create tiered performance requirements across surgical indications.
- Fracture Repair:Trauma stabilization procedures requiring drilling, pinning, and fixation hardware placement. United States Level I trauma centers are standardizing on navigated drilling platforms to reduce iatrogenic complications.
- Bone Grafting:Harvesting and preparation of autograft or allograft material for skeletal reconstruction. Sports medicine practices in Japan are expanding bone grafting volumes for cartilage restoration procedures.
- Osteotomy:Controlled bone cutting for deformity correction and limb realignment. German orthopedic centers are piloting intelligent handpieces with real-time bone density feedback for complex revision cases.
- Joint Replacement:Arthroplasty procedures involving resection of articular surfaces and implant preparation. United States, Germany, and Japan account for concentrated demand as centers for aging-population hip and knee replacement volume.
Joint replacement anchors revenue today; osteotomy applications are climbing the fastest as limb-alignment procedures expand.
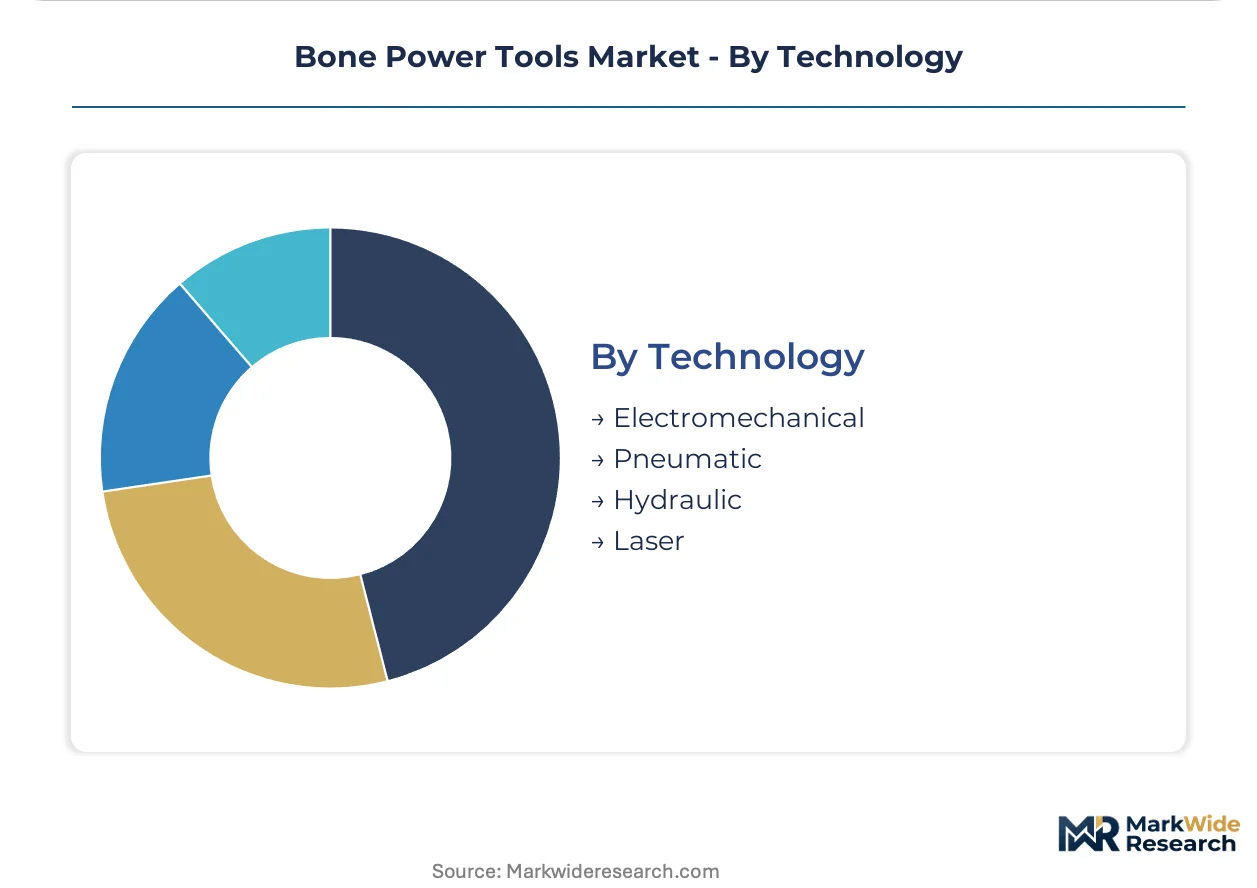
Technology:
Energy source selection determines infrastructure dependency, portability, and total cost-of-ownership profiles.
- Electromechanical:Battery-powered or line-powered motor systems with brushless DC technology and smart sensor integration. Lithium-ion energy density improvements are extending cordless runtime for complex multi-hour procedures.
- Pneumatic:Compressed air or nitrogen-driven turbines delivering consistent high-speed output. High-volume hospital systems face switching costs that slow displacement despite electromechanical portability advantages.
- Hydraulic:Fluid-pressure actuation systems for high-force applications in specialized trauma and spinal procedures. Limited adoption due to maintenance complexity and sterile processing challenges.
- Laser:Photonic ablation systems for precision bone cutting with minimal thermal necrosis. Experimental deployment in research settings pending clinical evidence generation for regulatory clearance pathways.
Electromechanical systems command the largest installed base; laser technology holds the steepest expansion trajectory contingent on clinical validation completion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhein-Ruhr metropolitan region anchors European orthopedic manufacturing, while demand concentrates in aging-population surgical hubs across three continents. Regulatory divergence between FDA pathways and EU MDR compliance timelines is fragmenting product launch sequencing. Hospital procurement consortia in each major market are rewriting vendor qualification standards.
United States
Ambulatory surgery centers in Florida and Texas are expanding outpatient joint replacement volume, driving cordless electromechanical system procurement. FDA 510(k) electromagnetic compatibility testing extends development timelines for radio-frequency emitting handpieces. The Greater Boston cluster hosts tertiary care pilots of intelligent handpieces with real-time bone density feedback.
Germany
Orthopedic consortia in Bavaria and North Rhine-Westphalia are pooling procurement volume to favor EU MDR-certified vendors with validated technical documentation. The country's national pharmaceutical regulator enforces stricter post-market surveillance obligations than legacy medical device directives. Stuttgart surgical hubs are standardizing on multi-cycle sterilization durability as a vendor selection criterion.
Japan
Tokyo and Osaka tertiary hospitals retain significant pneumatic installed base due to sunk infrastructure investment in operating room gas delivery systems. The country's national pharmaceutical regulator maintains PMDA clearance pathways that emphasize electromagnetic compatibility for powered instruments. Kobe medical device clusters are piloting navigated drilling platforms for complex revision arthroplasty.
United Kingdom
London integrated delivery networks exceeding ten hospital facilities are unbundling power tool acquisition from implant system contracts. The Medicines and Healthcare products Regulatory Agency aligns with EU MDR standards for post-market surveillance. Midlands orthopedic centers are expanding osteotomy volumes for limb-alignment procedures.
China
Yangtze River Delta hospital systems are upgrading surgical suite capacity for aging-population hip and knee replacement. The National Medical Products Administration governs device safety through pre-market notification requirements. Shanghai medical device clusters are developing domestic battery chemistry alternatives to reduce lithium and cobalt import dependency.
Bone Power Tools Market Competitive Landscape
Global majors compete with regional champions across integrated surgical ecosystems versus standalone instrument specialization. The vendor base stratifies into three tiers: diversified medtech conglomerates with implant bundling capability, pure-play orthopedic power system specialists, and regional fabricators serving cost-constrained settings. Dominant competitive moves include backward integration into battery cell sourcing and strategic partnerships with navigated surgery platform developers.
Within the diversified medtech tier, Stryker and Zimmer Biomet exemplify archetypes of ecosystem bundling versus deep orthopedic specialization. Stryker leverages its integrated surgical ecosystem to anchor hospital procurement relationships. Zimmer Biomet occupies a position defined by concentrated expertise in joint reconstruction power systems. Medtronic represents the navigated surgery convergence archetype, extending platform integration into powered instrument workflows.
| Leading Market Players |
|---|
| Stryker |
| Zimmer Biomet |
| Medtronic |
| Smith+Nephew |
| B. Braun Melsungen AG |
| CONMED Corporation |
| DePuy Synthes |
| Arthrex |
| NSK/Nakanishi Inc. |
| Others |
Pricing and Supply Chain Analysis
Hospital procurement consortia unbundling power tool acquisition from implant contracts are forcing manufacturers to absorb lithium and cobalt price volatility while validating multi-cycle sterilization durability. This demand-side restructuring compresses margins for cordless portfolios and elevates total cost-of-ownership documentation as a competitive gate.
Pricing Analysis
Input-cost pass-through from battery chemistry volatility feeds directly into contract pricing negotiations for cordless electromechanical systems. Pricing stratifies across premium navigated platforms, standard battery-powered handpieces, and economy-tier pneumatic alternatives, with differentiation anchored in ISO 13485 certification grade and validated sterilization cycle counts. Cost compression in mid-tier cordless portfolios is intensifying because raw material swings outpace contractual adjustment clauses. Ambulatory surgery centers exhibit highest price sensitivity due to capital constraints, while German orthopedic consortia prioritize certification compliance over unit economics.
Supply Chain Analysis
Lithium-ion cell supply rests on South Korean and Japanese specialty battery producers, with Chinese cathode material processors anchoring upstream chemical refining. Brushless DC motors and precision surgical-grade alloys draw from German and Japanese component specialists, while sterile packaging and single-use attachments feed from regional medical device converters. Single-source vulnerability concentrates in advanced battery cell chemistry, where qualified suppliers number fewer than five globally. Distribution runs through hospital procurement consortia and group purchasing organizations with consolidated vendor qualification protocols.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where EU MDR compliance deadlines and sustainability mandates are filtering demand toward premium-certified systems with validated technical documentation.
For Market Incumbents: Anticipate margin compression in legacy pneumatic portfolios as electromechanical alternatives displace installed base through portability advantages. Backward integration into battery cell sourcing secures supply continuity against cobalt price volatility, while accelerated EU MDR technical documentation investment preempts competitive exclusion from European orthopedic consortia pooling procurement volume. For New Entrants and Emerging Players: Enter via ambulatory surgery center expansion corridors in Florida and Texas, where outpatient joint replacement volume growth outpaces incumbent service coverage. Compact cordless systems with standalone sterilization validation offer the most penetrable entry point, with go-to-market execution anchored through direct contracting with multi-facility outpatient networks rather than hospital GPO channels. For Investors and Strategic Acquirers: Asymmetric upside sits with pure-play orthopedic power system specialists holding ISO 13485 certification and established EU MDR technical documentation, positioned for acquisition by diversified medtech conglomerates seeking implant bundling capability. Long-term viability hinges on navigated surgery platform integration and battery chemistry control. Watch FDA 510(k) clearance velocity for intelligent handpieces with real-time bone density feedback as the inflection indicator for premium tier expansion.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Technical Documentation Investment | Preemptive compliance secures access to German orthopedic consortia pooling procurement volume. |
| Battery Chemistry Backward Integration | Captive lithium-ion cell supply insulates margins against cobalt and lithium price volatility swings. |
| Navigated Surgery Platform Partnership | Integration with robotic positioning systems enables real-time bone cutting guidance premium pricing. |
| Ambulatory Surgery Center Direct Contracting | Bypassing hospital GPO channels captures outpatient joint replacement volume expansion in key states. |
| Multi-Cycle Sterilization Validation | Demonstrated instrument durability meets sustainability mandates from hospital purchasing consortia. |
Research Methodology
Bottom-up hospital and ambulatory surgical center modeling reconciled against top-down manufacturer shipment tracking forms the analytical core of this study. Primary interviews with orthopedic service line directors, biomedical engineers, hospital procurement committee members, and GPO contracts managers were validated against secondary sources including FDA 510(k) premarket notification filings, EU MDR technical documentation databases, hospital procurement records, and orthopedic implant registry data. Triangulation across these sources ensures segmentation integrity.
The input-output matrix framing connects procedure volume forecasts by application and end-user setting to instrument utilization rates and replacement cycles. Segmentation dimensions span product type, technology energy source, end-user facility type, and surgical application, with geographic clustering by regulatory framework. CAGRs were derived from installed base expansion, replacement cycle acceleration, and technology shift modeling. Forecast inputs incorporate EU MDR compliance deadline impacts, battery energy density improvement curves, and ambulatory surgery center capacity expansion trajectories.
Inputs from hospital procurement databases and manufacturer regulatory filings were available through the study window; gaps in real-time ambulatory surgery center capital expenditure plans introduce uncertainty bands around cordless system adoption velocity. Forecasts reflect assumptions regarding MDR enforcement consistency, battery chemistry cost stabilization, and navigated surgery platform penetration. A small set of named triggers—FDA electromagnetic compatibility testing delays, lithium supply chain disruptions, and EU MDR audit backlogs—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Asia-Pacific Ambulatory Infusion Pumps Market
Medical Devices
Bunion Correction Systems Market
Medical Devices
Asia-Pacific Wearable Medical Devices Market
Medical Devices
Oxygen Concentrators Market
Medical Devices
Global Cerebrospinal Fluid Drainage Catheter Market
Medical Devices
Accelerometers Medical Sensors Market
Medical Devices
Antibiotic-Loaded Bone Cement Market
Medical Devices
Endodontic Files Market
Medical Devices
Organ Transport Devices Market
Medical Devices
Global Oxygen Cylinders and Concentrators Market
Medical Devices
Wearable Blood Pressure Monitor Market
Medical Devices
Wearable Pulse Oximeters Market
Medical Devices
Veterinary Stereotactic Radiosurgery System Market
Medical Devices
Spinal Needles Market
Medical Devices
Pen Needles Market
Medical Devices
Medical Device and Accessories Market