
 Europe Medical Device Reprocessing Market | 2026-2036
Europe Medical Device Reprocessing Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Medical Device Reprocessing Market Foresight
Ambulatory surgical centers are redrawing procurement patterns across European healthcare, pulling demand away from traditional hospital-centric supply chains. Stryker Corporation leverages its end-to-end reprocessing infrastructure to dominate high-value device categories. Medtronic anchors its position through deep specialization in cardiac catheter reprocessing, while Steris competes aggressively on automated sterilization system placements.
Europe medical device reprocessing encompasses the cleaning, functional testing, repackaging, and relabeling of previously used medical devices to restore them to validated clinical performance standards, typically involving validated steam, ethylene oxide, or hydrogen peroxide plasma sterilization cycles with documented sterility assurance levels. The practice reduces per-procedure device costs by extending instrument lifecycles while maintaining compliance with EN ISO 17664 and EN 556 series standards for sterilization validation. Endoscopes command the largest product segment due to high unit costs and established reprocessing protocols, though catheters represent the fastest-expanding category as electrophysiology and interventional cardiology volumes rise across European cath labs. Steam sterilization leads technology adoption in on-site hospital settings, while ethylene oxide and plasma sterilization concentrate in off-site centralized facilities handling temperature-sensitive polymer and electronic components.
EMA coordination with notified bodies under the EU MDR framework is elevating clinical evidence requirements for reprocessed device equivalence, directly shaping market access timelines and reprocessor certification costs. Germany's Federal Institute for Drugs and Medical Devices and France's ANSM enforce national vigilance reporting that tightens post-market surveillance obligations on reprocessors. REACH chemical restrictions and the EU Green Deal circular economy targets are simultaneously pushing sterilization chemistry substitutions and device lifecycle extension mandates. Stakeholders must monitor notified body capacity bottlenecks and evolving MDR guidance documents to calibrate reprocessing portfolio investments against regulatory uncertainty.
Market Dynamics
The EU MDR framework is compressing market access timelines for reprocessors while elevating clinical evidence requirements, forcing consolidation among smaller operators unable to absorb notified body certification costs.
Growth Catalysts
- EU Green Deal circular economy mandates:France and Germany now embed device lifecycle extension targets into hospital procurement scoring, directly privileging reprocessed instruments over single-use alternatives.
- Ambulatory surgical center expansion:These facilities across Spain and Italy are adopting centralized reprocessing services to contain per-procedure costs without capital investment in on-site sterilization infrastructure.
- Catheter reprocessing protocol maturation:Validated cleaning cycles for electrophysiology catheters have crossed performance thresholds that satisfy cardiac cath lab quality committees.
Market Restraints
- Notified body capacity bottlenecks:EMA-coordinated MDR certification queues now stretch 18-24 months for reprocessor quality system approvals, freezing portfolio expansion for mid-tier operators.
- Polymer degradation limits:Repeated ethylene oxide exposure degrades catheter shaft polymers beyond validated cycle counts, constraining reprocessing yield rates for high-value electrophysiology devices.
- REACH chemical substitution costs:ECHA restrictions on legacy sterilization chemistries force capital retooling for hydrogen peroxide plasma systems at centralized facilities.
Strategic Opportunities
- Poland and Romania hospital consolidation:These underpenetrated markets are aggregating surgical volumes into regional networks that can sustain dedicated reprocessing contracts.
- AI-assisted visual inspection:Machine vision systems trained on endoscope defect libraries are converging with automated handling robotics to reduce manual quality labor.
- CSRD supply chain disclosure rules:Large EU hospital systems must now report Scope 3 emissions, creating procurement preference for reprocessed devices with verified carbon reduction documentation.
Industry Challenges
- Sterilization validation engineering talent scarcity:The specialized workforce capable of designing EN ISO 17664-compliant sterilization cycles is concentrated among aging practitioners with limited training pipeline replacement.
- Legacy hospital inventory system integration:Reprocessed device tracking requires bidirectional data exchange with hospital ERP platforms that lack standardized API architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Medical Device Reprocessing Market |
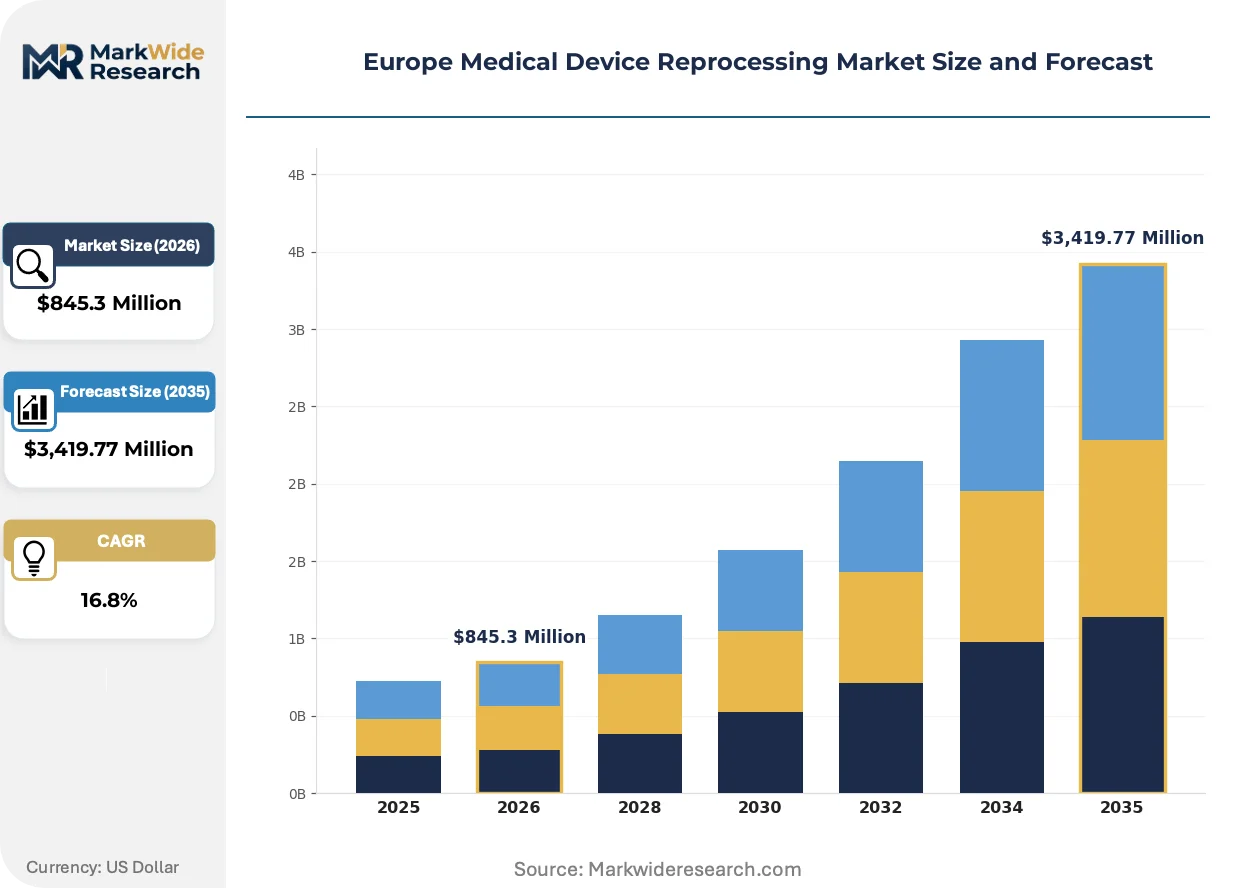
| Market Size in 2026 | $845.3 Million |
| Market Size in 2035 | $3,419.77 Million |
| CAGR (2026 – 2036) | 16.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Endoscopes, Surgical Instruments, Catheters, CRT Devices Technology: Steam Sterilization, Ethylene Oxide, Plasma Sterilization, Ozone Treatment End User: Hospitals, Ambulatory Surgical Centers, Clinics, Long-term Care Facilities Delivery Mode: On-site Processing, Off-site Processing, Reusable Systems, Disposable Systems |
| Companies Covered | Stryker Corporation, Medline Industries, Johnson & Johnson, Arjo, Steris, Cardinal Health, Vanguard AG, NEScientific, Medtronic, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Medical Device Reprocessing Market Shifts & Advancements
Reprocessing technology is pivoting from labor-intensive manual cleaning toward automated systems with embedded quality verification, while regulatory disclosure requirements reshape procurement evaluation criteria.
Low-temperature hydrogen peroxide plasma sterilization is supplanting ethylene oxide in centralized reprocessing facilities handling polymer-intensive cardiac catheters. German and Dutch hospital networks are adopting these systems at replacement cycle pace to eliminate toxic residue management burdens. This transition is compressing operational margins for reprocessors locked into legacy ethylene oxide infrastructure.
EMA-coordinated MDR guidance on reprocessed device equivalence is elevating clinical evidence submission requirements beyond pre-2021 benchmarks. Reprocessors must now generate performance data matching original manufacturer validation protocols, extending certification timelines by 12-18 months. Cardiac catheter categories face the steepest evidentiary burden, with several notified bodies suspending new applications pending clarified scope definitions.
Hospital procurement committees are unbundling device sourcing from sterilization service contracts, creating direct purchasing relationships with reprocessors that bypass traditional distributor markups. This pattern concentrates in the United Kingdom's NHS Supply Chain framework and French hospital group purchasing organizations. The shift pressures incumbent distributors to develop captive reprocessing capabilities or surrender high-margin catheter categories.
Europe Medical Device Reprocessing Market Segmentation
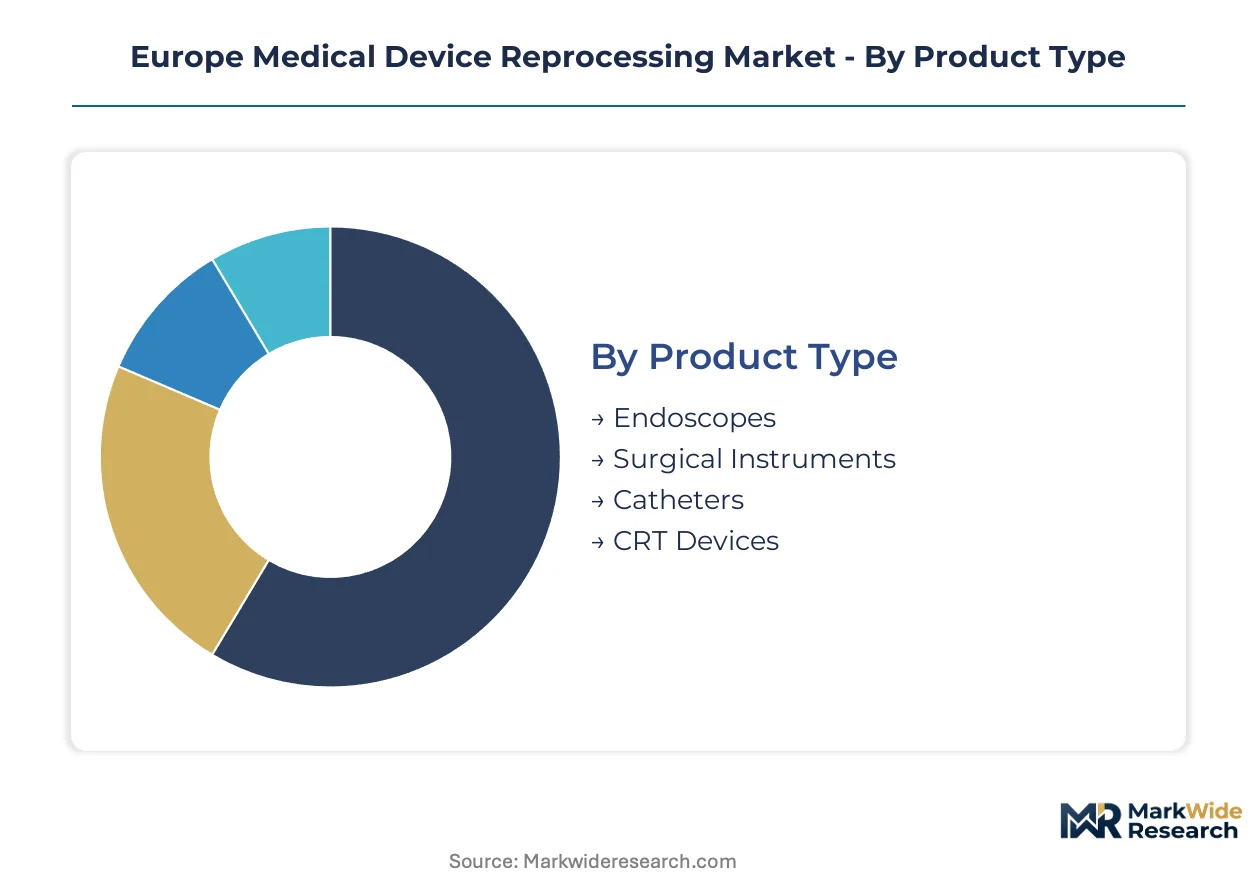
Segmentation in Europe medical device reprocessing reveals how procurement decisions split across capital intensity, regulatory burden, and clinical risk tolerance. Each dimension carries distinct margin profiles and certification requirements that reshape competitive positioning.
Product Type:
Domestic demand concentrates in Germany and France for capital-intensive categories, while export-oriented reprocessing services from the Netherlands and Belgium capture cross-border volume in standardized instruments.
- Endoscopes:Complex optical assemblies with narrow lumens require automated cleaning validation under EN ISO 17664. German university hospitals drive specification standards that propagate across EU procurement networks, though polymer fatigue limits reprocessing cycles for flexible gastroscopes.
- Catheters:Electrophysiology and interventional cardiology devices command premium reprocessing economics due to unit costs exceeding €800. French cardiac centers in Paris and Lyon are validating plasma sterilization protocols that extend polymer lifecycle performance beyond ethylene oxide baselines.
- Surgical Instruments:Metallic forceps, clamps, and retractors tolerate repeated steam sterilization with minimal degradation. Italian orthopedic networks in Lombardy aggregate sufficient volume to sustain dedicated reprocessing contracts.
- CRT Devices:Cardiac resynchronization therapy leads and generators face stringent electrical safety retesting. UK NHS trusts concentrate demand through centralized procurement frameworks that specify original manufacturer equivalence documentation.
Endoscopes command the established base. The steepest expansion runs through catheters.
Technology:
Cost tier differentiation separates capital-intensive plasma installations from operational-expense-heavy ethylene oxide chemistry management, with steam sterilization anchoring mid-market hospital budgets.
- Steam Sterilization:Saturated steam at 121-134°C penetrates metallic instrument lumens with validated sterility assurance levels. German Klinikum networks deploy these systems for same-day surgical instrument turnaround, though polymer incompatibility excludes cardiac catheters.
- Ethylene Oxide:Low-temperature gas penetration suits heat-sensitive polymers and electronic components. Dutch centralized facilities near Rotterdam manage toxic residue compliance under REACH restrictions that elevate operational overhead versus plasma alternatives.
- Plasma Sterilization:Hydrogen peroxide vapor plasma eliminates toxic byproduct burdens while processing temperature-sensitive devices. Belgian reprocessors in Flanders are converting ethylene oxide capacity to plasma systems to satisfy CSRD emission reporting requirements.
- Ozone Treatment:Aqueous ozone systems target endoscope channel disinfection with reduced cycle times. Spanish ASC clusters in Catalonia pilot these systems for ambulatory volume without centralized facility dependency.
Steam sterilization anchors hospital infrastructure. Plasma sterilization gains share fastest where REACH compliance costs bite deepest.
End User:
Customer type determines contract structure, with hospital systems demanding full quality documentation and ASCs prioritizing per-procedure cost containment over capital ownership.
- Hospitals:Tertiary centers in Germany, France, and the UK maintain captive reprocessing departments with dedicated sterilization engineering staff. EU MDR vigilance reporting obligations concentrate compliance investment at this tier.
- Ambulatory Surgical Centers:Spanish and Italian day-surgery facilities outsource reprocessing to regional centralized services. These operators avoid sterilization capital expenditure while meeting per-procedure cost targets through volume-based service contracts.
- Clinics:Independent diagnostic and minor procedure centers in Poland and Romania represent fragmented demand that regional reprocessing networks are aggregating through mobile collection logistics.
- Long-term Care Facilities:Nursing homes and rehabilitation centers generate lower-margin instrument volumes for basic surgical and wound care procedures. French EHPAD networks are standardizing procurement through regional hospital group purchasing organizations.
Hospitals anchor quality standards and certification investment. ASCs represent the volume expansion frontier.
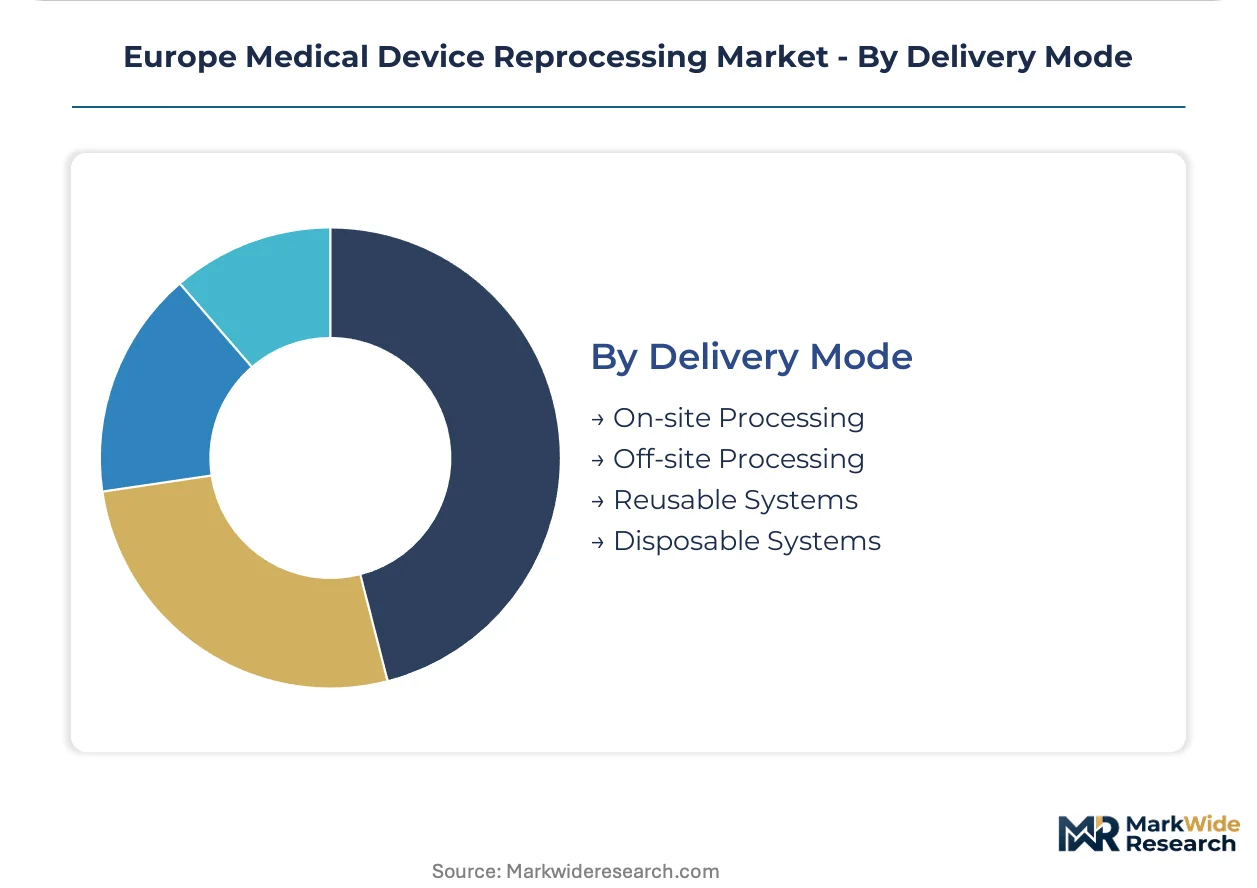
Delivery Mode:
Supply concentration versus geographic dispersion shapes whether reprocessing occurs within hospital walls or at regional facilities serving multiple customers.
- On-site Processing:Hospital-integrated sterilization departments control instrument turnaround times for emergency surgical schedules. German maximum-care hospitals defend this model against outsourcing pressure through integrated ERP tracking systems.
- Off-site Processing:Centralized facilities in the Netherlands and Belgium achieve scale economies serving multiple hospital systems. These operators absorb EU MDR certification costs across customer bases that individual hospitals cannot justify.
- Reusable Systems:Instrument sets designed for validated reprocessing cycles align with EU Green Deal circular economy procurement scoring. UK NHS Supply Chain frameworks now weight lifecycle extension metrics in vendor selection.
- Disposable Systems:Single-use alternatives retain share in high-risk implantable categories where reprocessing equivalence documentation remains under EMA review. Cardiac catheter original manufacturers defend this position through clinical evidence requirements.
Off-site processing captures consolidation-driven volume. Reusable systems align with tightening circular economy mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement committees in Germany, France, and the United Kingdom drive specification standards that cascade across neighboring markets. Ambulatory surgical centers in Southern Europe accelerate outsourcing contracts to centralized reprocessing facilities.
Germany
Maximum-care hospitals in Berlin and Munich maintain captive sterilization departments with dedicated engineering staff. The Federal Institute for Drugs and Medical Devices enforces national vigilance reporting that tightens post-market surveillance obligations on reprocessors. The Rhine-Ruhr industrial corridor hosts specialized ethylene oxide facilities serving cross-border hospital networks.
France
Cardiac centers in Paris and Lyon validate plasma sterilization protocols for high-value electrophysiology catheters. ANSM coordinates with EMA on MDR equivalence documentation requirements that extend certification timelines. The Île-de-France region concentrates day-surgery facilities adopting centralized reprocessing services to avoid capital expenditure.
United Kingdom
NHS Supply Chain frameworks unbundle device sourcing from sterilization contracts, creating direct purchasing relationships with reprocessors. The Medicines and Healthcare products Regulatory Agency enforces UKCA marking transitions parallel to EU MDR compliance. London and the Southeast anchor demand through tertiary center consolidation into regional procurement networks.
Netherlands
Centralized facilities near Rotterdam achieve scale economies serving multiple hospital systems across Benelux borders. REACH restrictions on legacy sterilization chemistries elevate operational overhead versus hydrogen peroxide plasma alternatives. The Randstad urban corridor integrates mobile collection logistics for fragmented clinic demand in surrounding provinces.
Spain
Ambulatory surgical centers in Catalonia pilot aqueous ozone systems for endoscope channel disinfection without centralized facility dependency. Regional health ministries embed circular economy scoring into hospital procurement frameworks. Barcelona and Madrid clusters aggregate sufficient surgical volume to sustain dedicated reprocessing contracts.
Europe Medical Device Reprocessing Market Competitive Landscape
Player mix skews toward diversified medical technology conglomerates with captive reprocessing divisions alongside specialized sterilization service operators. Tiered competitive positioning separates premium-tier original manufacturers from mid-market third-party reprocessors and regional service contractors. Two dominant strategic archetypes emerge: integrated device-reprocessing hybrids leveraging end-to-end control, and pure-play sterilization specialists competing on automated system placements. Consolidation pressure intensifies through M&A activity targeting notified body certification capabilities, while capacity expansion concentrates in hydrogen peroxide plasma installations.
Among diversified medical technology conglomerates, Stryker Corporation and Medtronic occupy positions exemplifying the integrated hybrid archetype, combining original device manufacturing with captive reprocessing infrastructure. Steris represents the pure-play sterilization specialist model, competing aggressively on automated system placements. Vanguard AG and NEScientific sit within the regional specialist tier, serving fragmented clinic demand through mobile logistics networks. Cardinal Health and Medline Industries exemplify distributor incumbents developing captive reprocessing capabilities to defend high-margin catheter categories against direct hospital-processor relationships.
| Leading Market Players |
|---|
| Stryker Corporation |
| Medline Industries |
| Johnson & Johnson |
| Arjo |
| Steris |
| Cardinal Health |
| Vanguard AG |
| NEScientific |
| Medtronic |
| Others |
Supply & Pricing Matrix
Hydrogen peroxide plasma sterilization chemistry displacing ethylene oxide across Benelux and German reprocessing clusters simultaneously redistributes supply geography toward Belgian and Dutch centralized facilities while compressing pricing economics for operators locked into legacy toxic residue management infrastructure.
Pricing Analysis
Cost-plus contracts with ethylene oxide feedstock indexation dominate third-party reprocessor agreements with German hospital networks, though plasma sterilization adopters in Belgium and the Netherlands are migrating toward fixed-fee per-procedure structures that transfer polymer degradation risk. Price differentiation hinges on EU MDR certification tier and volume scale, with notified body-endorsed operators commanding premiums over uncertified regional contractors. Pricing pressure stems from REACH compliance cost pass-through requirements that erode margins for ethylene oxide-dependent facilities. Ambulatory surgical centers in Spain and Italy exhibit highest price sensitivity, while UK NHS trusts prioritize quality documentation over per-unit cost minimization.
Supply Chain Analysis
Just-in-time instrument tracking through hospital ERP integration dominates German maximum-care hospital procurement, whereas centralized reprocessors in the Netherlands and Belgium maintain strategic stockpiles of polymer-intensive cardiac catheters to buffer against REACH chemical substitution disruptions. Geographic supply concentration centers on Germany, Belgium, and the Netherlands for sterilization equipment manufacturing, with hydrogen peroxide precursor chemicals sourced from German industrial chemical producers. Raw material dependencies include ethylene oxide gas, hydrogen peroxide solutions, and medical-grade polymer components for catheter shafts. Single-source vulnerability characterizes notified body certification capacity for EU MDR quality system approvals. Distribution runs through regional hospital group purchasing organizations in France and NHS Supply Chain frameworks in the United Kingdom.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across Europe's reprocessing market creates consolidation opportunities as EU MDR certification costs disproportionately burden mid-tier operators, while ambulatory surgical center expansion generates demand for outsourced sterilization services that bypass capital ownership requirements.
For Market Incumbents: Fortify notified body certification portfolios against EMA-coordinated MDR equivalence documentation requirements that extend cardiac catheter reprocessing approval timelines. Acquire sterilization validation engineering capabilities in Germany and France where workforce scarcity constrains cycle development throughput. Prioritize hydrogen peroxide plasma capacity conversion in Benelux facilities to eliminate REACH toxic residue compliance burdens that compress competitor margins. For New Entrants and Emerging Players: Differentiate on AI-assisted visual inspection integration for endoscope quality verification, targeting Polish and Romanian hospital consolidation networks where surgical volume aggregation sustains dedicated reprocessing contracts. Penetrate ambulatory surgical center clusters in Catalonia and Lombardy through mobile collection logistics that eliminate on-site sterilization capital requirements. Pursue direct procurement relationships with NHS Supply Chain frameworks that unbundle device sourcing from sterilization service contracts. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional sterilization specialists in the Netherlands and Belgium that have accumulated notified body certification capabilities but lack scale to absorb EU MDR vigilance reporting infrastructure costs. Long-term viability over a five-to-ten year horizon rests on hydrogen peroxide plasma technology adoption curves and REACH chemical restriction enforcement intensity. Monitor EMA guidance document releases on reprocessed device equivalence scope definitions as the critical inflection signal for cardiac catheter category market access timelines.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | Notified body queue positioning under EMA MDR coordination determines cardiac catheter reprocessing market access sequencing. |
| Hospital System Partnership | Direct procurement relationships with NHS Supply Chain and French GPOs bypass distributor markups in high-value categories. |
| Capacity Expansion | Plasma sterilization installations in Belgium and Netherlands capture REACH-driven ethylene oxide substitution demand. |
| Backward Integration | In-house hydrogen peroxide precursor production insulates Belgian reprocessors from German chemical supplier pricing volatility. |
| Software Companion Development | AI-assisted visual inspection platforms reduce manual quality labor in endoscope reprocessing workflows. |
Research Methodology
A spread of perspectives from sterilization engineering directors, hospital purchasing committee chairs, biomedical equipment specialists, and GPO contracts managers converged on the working assumptions underlying demand forecasts. Primary fieldwork across German university hospitals, French cardiac centers, and Dutch centralized reprocessing facilities combined with secondary validation from EMA guidance documents, notified body certification databases, EU Green Deal circular economy procurement frameworks, and REACH chemical restriction filings. Bottom-up surgical volume modeling and top-down healthcare expenditure allocation triangulated market sizing across the analysis window.
Segmentation dimensions modeled include product type, sterilization technology, end-user facility category, and delivery mode across the projection horizon. CAGRs derive from surgical procedure volume trajectories, ambulatory surgical center expansion rates, and EU MDR implementation pace assumptions. Industry-specific forecast inputs incorporate cardiac catheter reprocessing protocol maturation thresholds and hydrogen peroxide plasma sterilization adoption curves in centralized facilities.
Material uncertainties — EMA equivalence documentation scope clarifications, notified body capacity bottlenecks, and REACH chemical substitution enforcement intensity — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory implementation timelines and technology substitution economics. Revision becomes warranted when EMA guidance on reprocessed device equivalence crosses thresholds that alter cardiac catheter category certification feasibility.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Equipment
Tissue Processing Systems Market
Medical Equipment
India Massage Equipment Market
Medical Equipment
Medical Equipment Maintenance Market
Medical Equipment
Global Stereotactic Radiosurgery (Gamma Knife) Market
Medical Equipment
Medical Oxygen Gas Cylinder Market
Medical Equipment
Operating Table Parts Market
Medical Equipment
Medical Equipment Calibration Services Market
Medical Equipment
North America Medical Carts Market
Medical Equipment
Air Fluidized Therapy Beds Market
Medical Equipment
Apheresis Equipment Market
Medical Equipment
Global Platelet Agitator Market
Medical Equipment
Global Single-Arm Medical Pendant Market
Medical Equipment
Global Medical Lighting Technologies Market
Medical Equipment
Medical Oxygen Cylinders Market
Medical Equipment
North America Radiotherapy Market
Medical Equipment
Medical Gas Equipment Market