
 Arteriosclerosis Detector Market | 2026-2036
Arteriosclerosis Detector Market Size, Share, and Industry Trends Forecast 2026-2036
Arteriosclerosis Detector Market Analysis
Hospital procurement channels for cardiovascular diagnostics is reshaping vendor relationships across North America and Western Europe. Siemens Healthineers leverages its installed imaging base to anchor long-term service contracts. Abbott Laboratories differentiates through point-of-care blood pressure monitoring platforms that bypass centralized radiology workflows. GE Healthcare controls premium CT scanner placements through bundled financing arrangements with integrated delivery networks.
An arteriosclerosis detector identifies and quantifies arterial wall thickening, calcification, and endothelial dysfunction through non-invasive or minimally invasive measurement modalities, typically operating at spatial resolutions below one millimeter for intima-media thickness assessment. These devices serve the primary commercial purpose of enabling early cardiovascular risk stratification before symptomatic disease manifests. Ultrasound devices occupy the largest installed base due to lower capital requirements and established clinical training pathways, while CT scanners command the highest per-procedure revenue and dominate where coronary calcium scoring drives reimbursement. Advanced algorithm technology is displacing conventional image interpretation in research institutions, though regulatory validation lags behind technical capability.
FDA 510(k) pathways and EMA Medical Device Regulation (MDR) conformity assessments govern market access for algorithm-enhanced detectors in the United States and European Union respectively, with both frameworks intensifying scrutiny of clinical validation datasets. Japan's PMDA imposes additional localization requirements that delay foreign entrants by twelve to eighteen months relative to domestic manufacturers. Stakeholders must monitor evolving reimbursement codes for AI-assisted reads and decide whether to pursue parallel regulatory submissions or sequential geographic rollout.
Market Dynamics
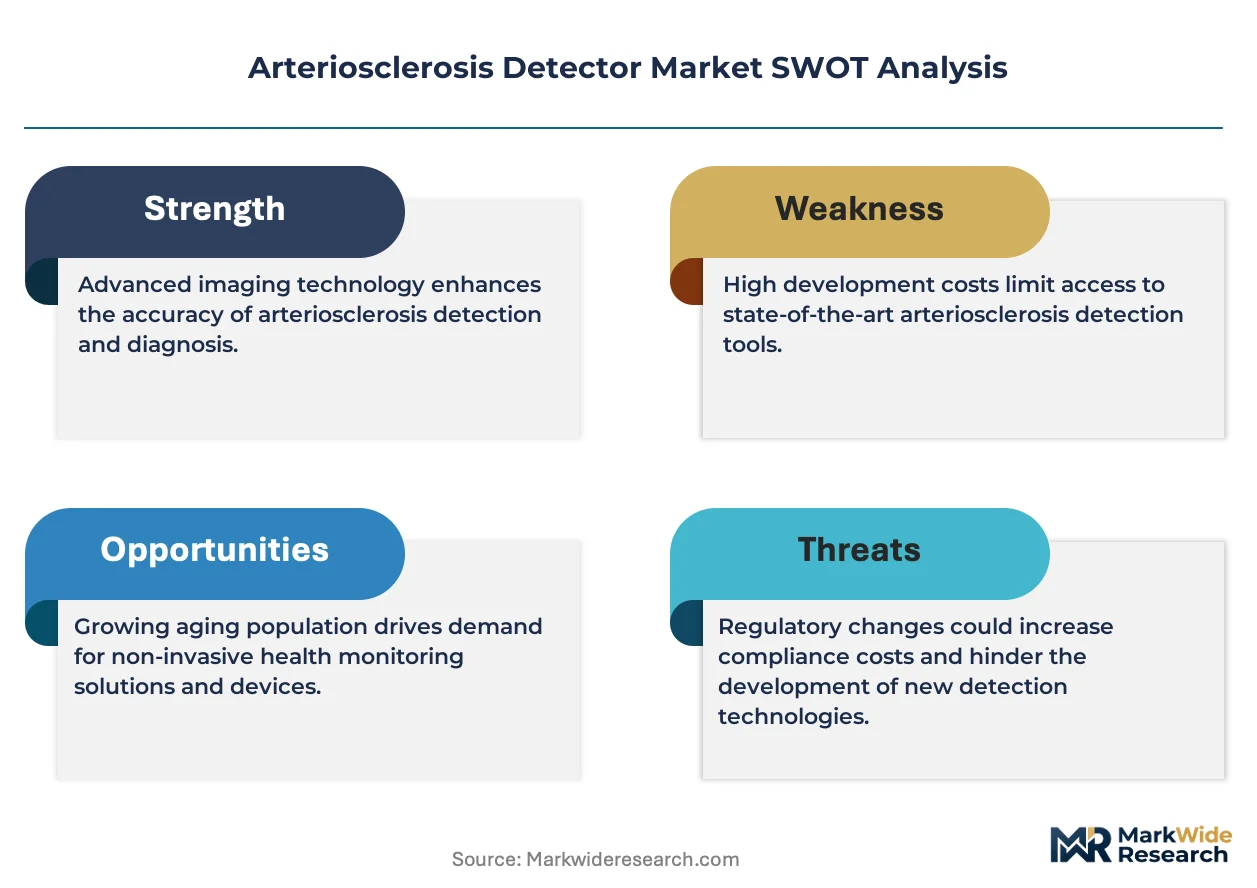
AI-enhanced diagnostic algorithms are compressing product development timelines and reshaping competitive positioning across cardiovascular screening markets. FDA and EMA clearance pathways now prioritize clinical validation datasets, forcing vendors to restructure R&D pipelines around algorithmic performance rather than hardware specifications.
Growth Catalysts
- Hospital Screening Program Expansion:Cardiovascular departments in Germany, Japan, and the United States are installing ultrasound and CT-based arteriosclerosis detection systems as standard preventive care infrastructure.
- AI-Assisted Reimbursement Codes:Emerging reimbursement frameworks for algorithm-enhanced diagnostic reads in the United States and European Union are creating direct revenue pathways for software-integrated detection platforms.
- CT Coronary Calcium Scoring:Preventive cardiology guidelines emphasizing early calcification assessment are driving demand for high-resolution CT installations in integrated delivery networks.
Market Restraints
- Regulatory Localization Burden:Japan's PMDA imposes twelve-to-eighteen-month localization requirements that delay foreign market entry relative to domestic manufacturers.
- Capital Equipment Concentration:Premium CT scanner procurement depends on bundled financing arrangements with large hospital systems, excluding smaller diagnostic centers.
- Training Pathway Inertia:Established clinical workflows around conventional ultrasound interpretation create adoption friction for algorithm-enhanced diagnostic platforms.
Strategic Opportunities
- Point-of-Care Blood Pressure Integration:Ambulatory monitoring platforms that bypass centralized radiology workflows offer expansion into primary care and retail clinic channels.
- Preventive Cardiology Guidelines:Updated clinical practice standards emphasizing early risk stratification create demand for non-invasive intima-media thickness assessment in asymptomatic populations.
- Service Contract Anchoring:Long-term maintenance and software update agreements tied to installed imaging bases generate recurring revenue streams independent of new hardware sales.
Industry Challenges
- Algorithm Validation Dataset Requirements:FDA 510(k) and EMA MDR frameworks intensify scrutiny of clinical evidence packages, extending pre-market submission preparation cycles.
- Legacy System Interoperability:Integration of AI-enhanced detection modules with existing PACS and EMR infrastructure requires specialized IT coordination and workflow redesign.
- Radiologist Training Compression:Accelerated adoption of automated interpretation tools outpaces formal education programs, creating competency gaps in algorithm-assisted diagnostic verification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Arteriosclerosis Detector Market |
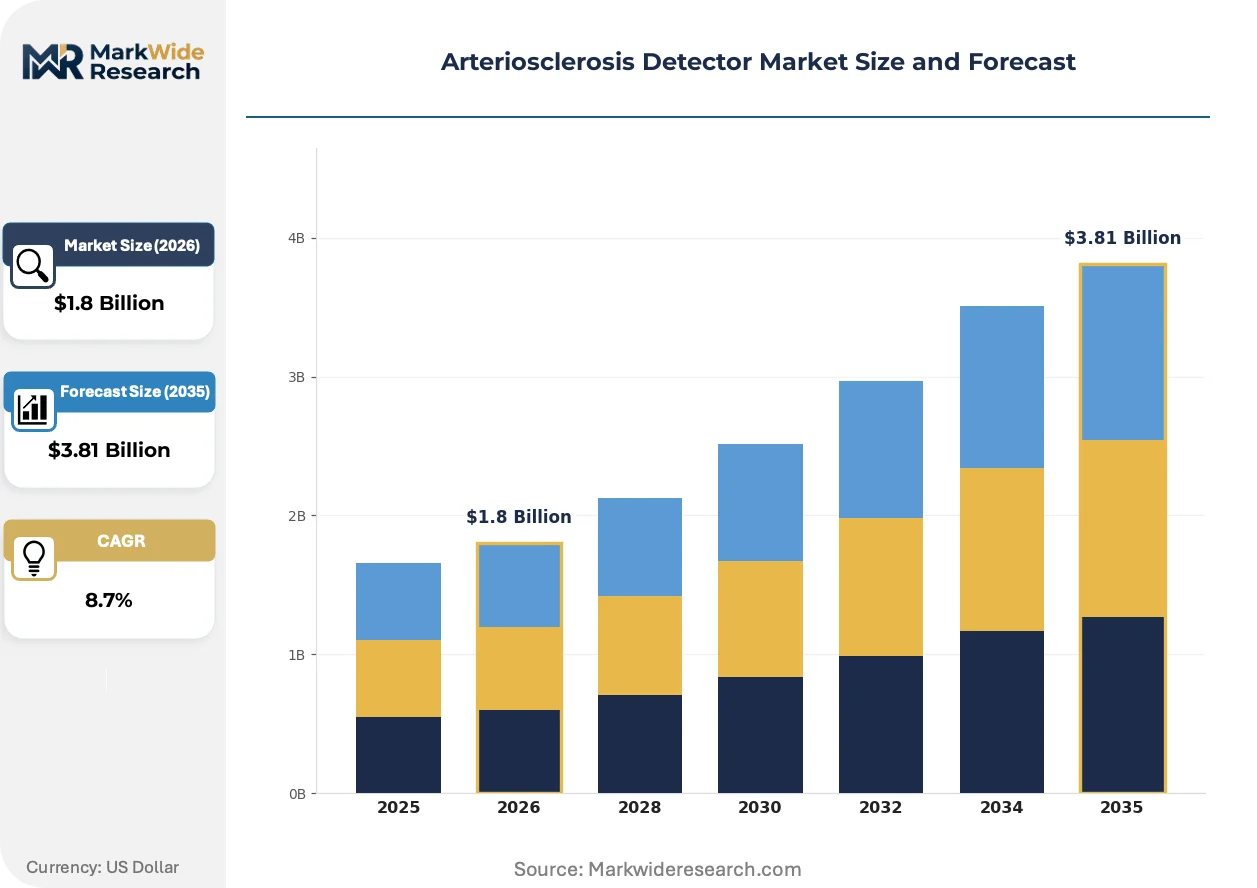
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ultrasound Devices, MRI Scanners, CT Scanners, Blood Pressure Monitors Technology: Digital Imaging, Wireless Monitoring, Wearable Sensors, Advanced Algorithm End User: Hospitals, Diagnostic Labs, Research Institutions, Outpatient Centers Application: Cardiovascular Screening, Clinical Research, Patient Monitoring, Health Management |
| Companies Covered | Abbott Laboratories, Siemens Healthineers, Koninklijke Philips, GE Healthcare, Roche Diagnostics, Medtronic, Boston Scientific Corporation, Edwards Lifesciences Corporation, F. Hoffmann-La Roche, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Arteriosclerosis Detector Market Emerging Trajectories
Deep learning architectures are collapsing traditional boundaries between hardware manufacturers and software vendors across cardiovascular diagnostics. Algorithmic interpretation now determines purchasing criteria as much as imaging resolution specifications.
Convolutional neural networks trained on multi-center arterial imaging datasets are collapsing the diagnostic accuracy gap between specialist radiologists and general practitioners. Community hospitals in the United States and Germany are deploying these tools to standardize intima-media thickness measurements without dedicated vascular sonographers. The structural consequence is collapsing referral volumes from primary care to tertiary cardiovascular centers as point-of-care confidence improves.
EMA Medical Device Regulation conformity assessments for algorithm-enhanced detectors now mandate prospective clinical validation across diverse patient populations. This regulatory tightening forces vendors to maintain separate evidence packages for European and United States submissions. CT-based coronary calcium scoring platforms face the steepest compliance burden due to radiation exposure risk classifications.
Integrated delivery networks are consolidating procurement authority for cardiovascular diagnostics into centralized supply chain functions. Individual hospital radiology departments lose autonomy over detector selection as system-wide standardization agreements take precedence. This concentration is most visible in United States metropolitan markets where three-to-five hospital systems control regional imaging capacity.
Arteriosclerosis Detector Market Segmentation
Segmentation reveals how procurement authority and clinical workflow requirements fragment demand across hardware modalities and software capabilities. Vendors must align product architecture with specific reimbursement pathways and end-user technical capacity.
Product Type:
Cost tiers separate capital-intensive imaging platforms from accessible point-of-care instruments, with financing structures determining addressable customer pools.
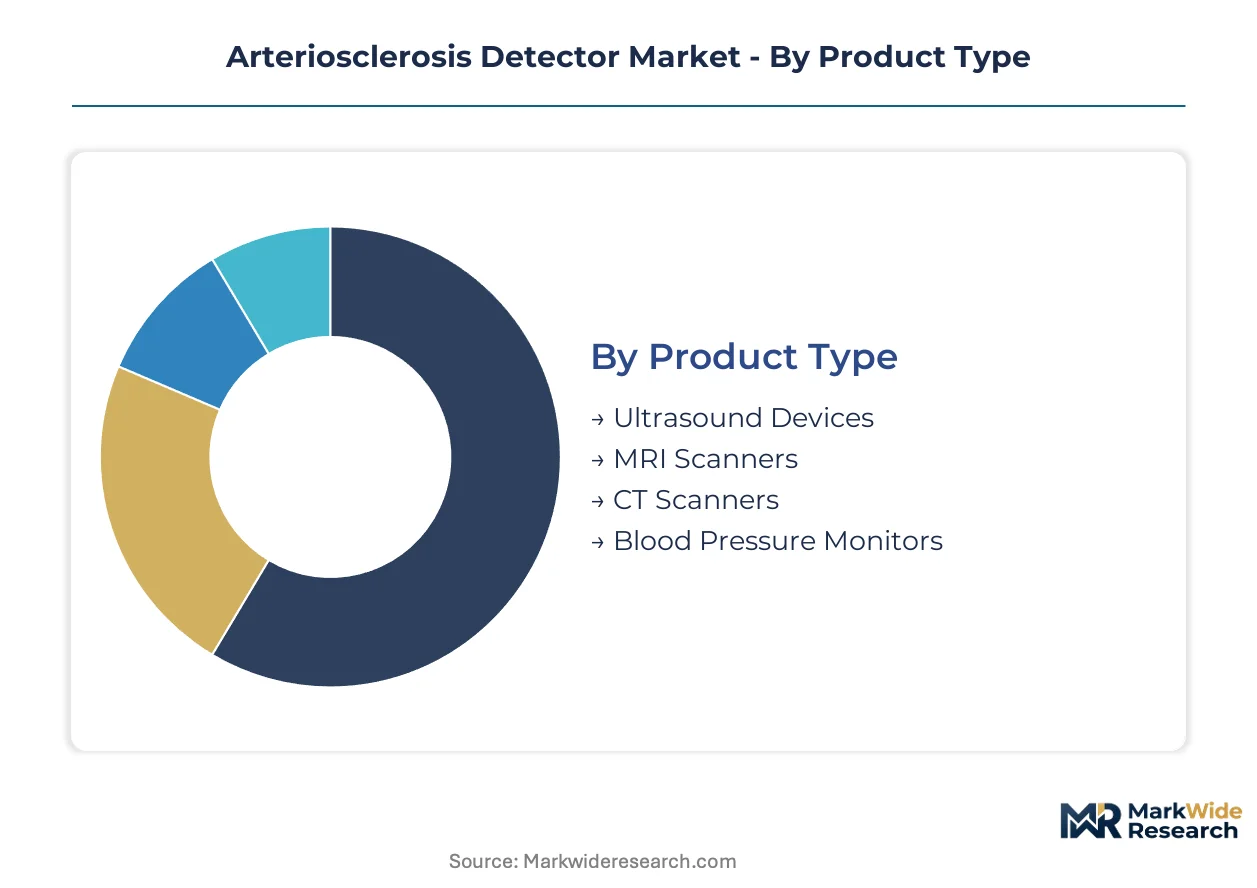
- Ultrasound Devices:These systems employ high-frequency sound waves to measure intima-media thickness at sub-millimeter resolution without ionizing radiation. Demand concentrates in German and Japanese outpatient clinics where preventive screening programs reimburse non-invasive arterial assessment. Lower capital requirements and established sonographer training pathways sustain installed base dominance.
- CT Scanners:Computed tomography platforms generate coronary calcium scores through rapid cardiac gating protocols. United States integrated delivery networks drive procurement through bundled financing arrangements tied to preventive cardiology service lines. Radiation exposure risk classifications elevate regulatory compliance burdens relative to ultrasound alternatives.
- MRI Scanners:Magnetic resonance systems enable plaque characterization without contrast agents in research-intensive settings.
- Blood Pressure Monitors:Ambulatory cuff-based devices provide vascular stiffness indices through pulse wave velocity analysis in primary care channels.
Ultrasound devices command the established base. The steepest expansion runs through CT scanners.
Technology:
Application maturity distinguishes regulatory-cleared diagnostic algorithms from emerging wearable form factors still seeking clinical validation.
- Digital Imaging:Conventional grayscale and Doppler processing architectures support standardized measurement protocols across hospital radiology departments. United States facilities prioritize FDA 510(k)-cleared image acquisition modules that integrate with existing PACS infrastructure. Hardware-software bundling in procurement contracts limits standalone software penetration.
- Advanced Algorithm:Convolutional neural networks automate intima-media thickness measurement and plaque classification without specialist interpretation. EMA MDR conformity assessments now mandate prospective validation across diverse European patient populations, compressing development timelines for compliant vendors. Research institutions in Germany and Japan deploy these tools to standardize community hospital screening accuracy.
- Wireless Monitoring:Bluetooth-enabled devices transmit arterial stiffness data to centralized EMR systems for longitudinal tracking.
- Wearable Sensors:Photoplethysmography-based wrist and finger devices estimate vascular age through pulse waveform analysis in consumer wellness segments.
Digital imaging retains the largest installed footprint. Advanced algorithm capabilities are gaining share fastest through reimbursement code expansion.
End User:
Customer type determines purchasing authority concentration, with centralized supply chain functions displacing departmental autonomy in large health systems.
- Hospitals:Acute care facilities maintain cardiovascular departments with dedicated vascular laboratories and catheterization suites. United States metropolitan markets concentrate procurement through three-to-five hospital systems controlling regional imaging capacity. Service contract anchoring strategies by major vendors lock in long-term maintenance and software update revenue.
- Diagnostic Labs:Independent testing facilities process referral-based arterial assessments for primary care networks. German outpatient laboratory chains expand cardiovascular screening menus to capture preventive care reimbursement. Workflow separation from hospital radiology departments enables faster algorithm adoption without legacy PACS integration constraints.
- Research Institutions:Academic medical centers validate novel biomarkers and imaging protocols for regulatory submission packages.
- Outpatient Centers:Freestanding clinics deliver point-of-care vascular assessment in retail and employer-based health settings.
Hospitals command the established base. Diagnostic labs present the steepest expansion trajectory through decentralized screening program growth.
Application:
Volume distribution reflects reimbursement code availability, with preventive screening generating procedure volume and clinical research commanding premium pricing.
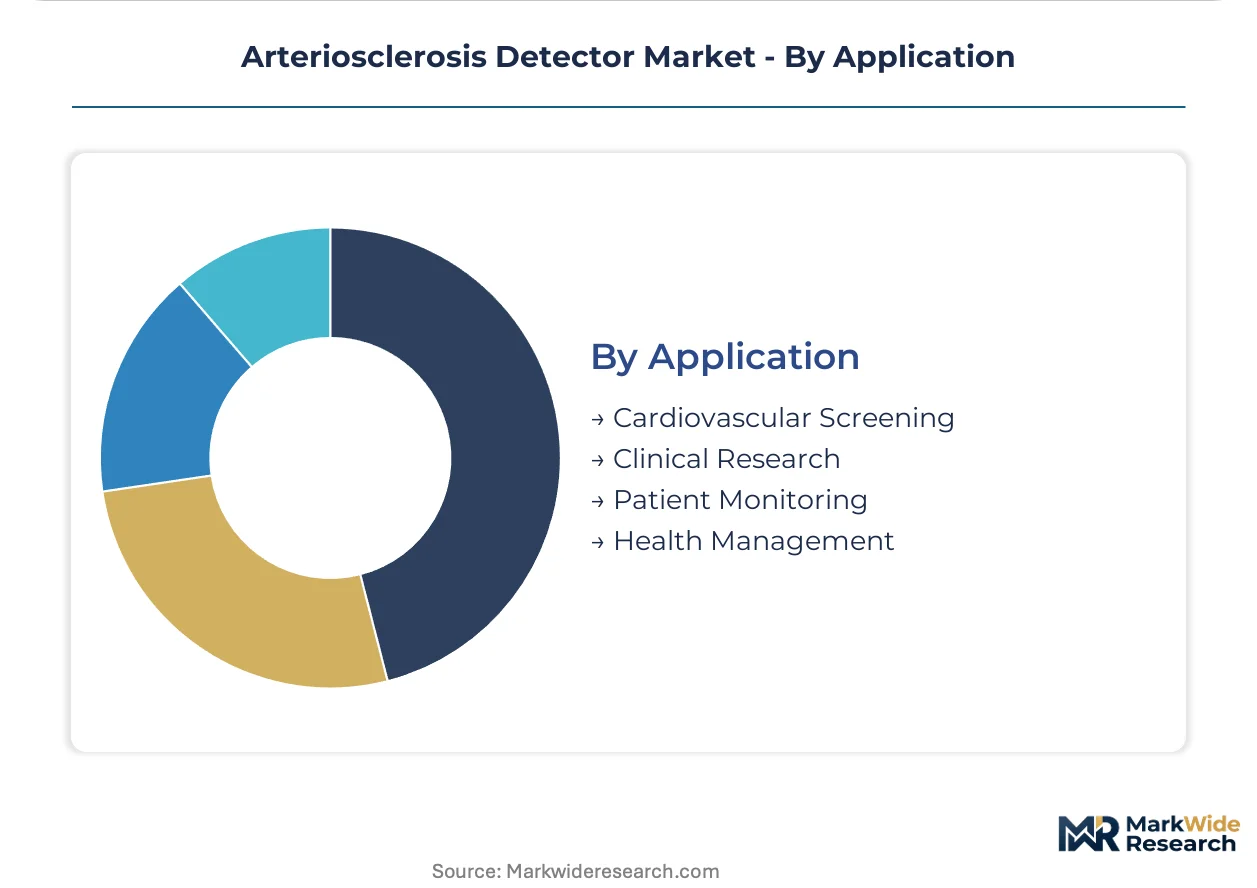
- Cardiovascular Screening:Asymptomatic risk stratification protocols drive bulk procedure volume in health system preventive care lines. Japanese health ministry screening mandates and United States Medicare preventive service coverage sustain demand for non-invasive arterial assessment. CT coronary calcium scoring guidelines from cardiology societies accelerate scanner placement in integrated networks.
- Clinical Research:Pharmaceutical trials and device validation studies require standardized arterial imaging endpoints with audit trails. EMA and FDA intensified scrutiny of algorithm training datasets elevates demand for protocol-compliant imaging cores. Contract research organizations in Germany and the United States consolidate preferred vendor relationships with validated platform operators.
- Patient Monitoring:Longitudinal tracking of arterial stiffness progression supports therapeutic intervention timing in chronic disease management.
- Health Management:Corporate wellness and insurance risk assessment programs incorporate vascular age metrics into population health stratification.
Cardiovascular screening commands the established base. Clinical research delivers the steepest expansion through regulatory validation service demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Cleveland Clinic cardiovascular corridor anchors United States demand for CT-based coronary calcium scoring installations. German university hospital networks drive ultrasound screening standardization across outpatient channels. Japanese metropolitan screening mandates compress procurement cycles for diagnostic equipment vendors.
United States
Integrated delivery networks in Texas and Florida consolidate cardiovascular imaging procurement through centralized supply chain functions. FDA 510(k) clearance pathways for AI-enhanced algorithms compress product validation timelines relative to European submissions. The Cleveland Clinic and Mayo Clinic anchor multi-site screening standardization agreements that lock in long-term service contracts.
Germany
Outpatient laboratory chains in Bavaria and North Rhine-Westphalia expand preventive cardiovascular screening menus to capture statutory health insurance reimbursement. EMA Medical Device Regulation conformity assessments mandate prospective clinical validation across diverse patient populations. The Munich medical technology cluster concentrates algorithm development talent for intima-media thickness automation tools.
Japan
Metropolitan prefectures enforce health ministry mandates for asymptomatic cardiovascular risk assessment in working-age populations. PMDA localization requirements impose twelve-to-eighteen-month delays on foreign detector manufacturers relative to domestic entrants. Tokyo and Osaka academic medical centers validate novel arterial stiffness biomarkers for regulatory submission packages.
United Kingdom
NHS England long-term plan targets expand community-based cardiovascular risk stratification outside hospital radiology departments. MHRA post-Brexit regulatory divergence from EMA MDR creates parallel submission requirements for algorithm-enhanced platforms. London and Manchester integrated care systems pilot point-of-care arterial assessment in primary care networks.
China
Tier-one hospital cardiovascular departments in Beijing and Shanghai install premium CT scanners through municipal health commission procurement tenders. NMPA medical device registration requirements intensify clinical evidence scrutiny for foreign-manufactured detection systems. The Yangtze River Delta medical device manufacturing base supplies cost-optimized ultrasound platforms for county-level hospital expansion.
Arteriosclerosis Detector Market Vendor Landscape
On the supply side, the industry is consolidating around imaging hardware manufacturers with established installed bases and long-term service contract portfolios. Three strategic archetypes dominate: diversified medical technology conglomerates with radiology workflow integration capabilities, specialized cardiovascular diagnostic firms with algorithm-centric R&D pipelines, and point-of-care monitoring specialists bypassing centralized hospital procurement. Competitive moves concentrate on M&A for AI algorithm assets and strategic partnerships with integrated delivery networks for exclusive equipment placement.
Among diversified health technology conglomerates, Siemens Healthineers and GE Healthcare exemplify the installed-base anchoring archetype through bundled financing arrangements with hospital systems. Abbott Laboratories occupies a distinct position in ambulatory monitoring channels that circumvent traditional radiology department procurement workflows. Koninklijke Philips represents the hybrid positioning of hardware-software integration across both hospital and outpatient settings.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Siemens Healthineers |
| Koninklijke Philips |
| GE Healthcare |
| Roche Diagnostics |
| Medtronic |
| Boston Scientific Corporation |
| Edwards Lifesciences Corporation |
| F. Hoffmann-La Roche |
| Others |
Supply Flow & Price Mechanics
The Yangtze River Delta manufacturing base anchors ultrasound transducer and CT detector module production, concentrating component supply leverage among three domestic champions whose capacity decisions cascade through downstream pricing tiers for hospital procurement contracts.
Pricing Analysis
Volume-discount tiering structures separate premium CT scanner placements with bundled software service agreements from standard ultrasound systems and economy-class blood pressure monitoring platforms. Pricing stratifies across premium, standard, and economy tiers based on FDA 510(k) certification grade and after-sales service bundling intensity. Cost compression in the economy tier intensifies because domestic Chinese manufacturers are expanding county-level hospital penetration. Diagnostic laboratories exhibit the highest price sensitivity due to thin preventive screening reimbursement margins, while integrated delivery networks demonstrate the lowest sensitivity given bundled financing access.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities from Siemens Healthineers and GE Healthcare lock in component allocation priority during semiconductor shortages. Manufacturing concentrates in Germany, Japan, and the United States for high-frequency ultrasound transducers, precision CT detector arrays, and AI inference chips. Raw material dependencies include rare earth elements for MRI magnets, silicon photomultipliers for CT detectors, and specialized acoustic lenses for vascular ultrasound. Single-source vulnerability in AI training chip supply from Taiwan Semiconductor creates procurement risk. Distribution runs through hospital GPO contracts and regional medical device distributors with exclusive territory agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The arteriosclerosis detector market is entering a cyclical recovery phase as hospital capital expenditure budgets rebound from pandemic-era deferrals and cardiovascular screening mandates expand across German and Japanese health systems.
For Market Incumbents: Insulate installed base revenue through long-term algorithm update subscriptions that tether hospital radiology departments to proprietary PACS integration layers. Consolidate service contract portfolios by acquiring independent maintenance providers in United States metropolitan markets where three-to-five hospital systems control regional imaging capacity. Vertical integration into AI training dataset curation defends against algorithm-centric entrants threatening conventional hardware-software bundling.
For New Entrants and Emerging Players: Establish a beachhead in German outpatient laboratory chains where statutory health insurance reimbursement for preventive cardiovascular screening is expanding fastest. Target point-of-care blood pressure monitoring integration in United Kingdom primary care networks piloting community-based risk stratification outside hospital radiology departments. Pursue regulatory sandbox pathways with MHRA post-Brexit divergence to accelerate algorithm validation timelines relative to EMA MDR conformity assessments.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized cardiovascular diagnostic firms with algorithm-centric R&D pipelines over diversified conglomerates with legacy hardware dependencies. Acquisition targets should demonstrate validated training datasets across diverse European and Asian patient populations with regulatory submission packages nearing completion. The signal to watch is FDA 510(k) clearance velocity for AI-assisted reimbursement codes, which would inflect software-integrated platform valuations.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Pathway | Accelerates market access for AI-enhanced intima-media thickness algorithms in United States hospital systems. |
| CE Marking Pathway | Unlocks EMA MDR-compliant placements across German outpatient laboratory expansion programs. |
| Hospital System Partnership | Secures bundled financing arrangements with integrated delivery networks in Texas and Florida metropolitan markets. |
| Software Companion Development | Enables PACS-integrated algorithm updates that tether long-term service revenue to installed CT scanner bases. |
| Reimbursement Strategy | Captures emerging AI-assisted diagnostic read codes from CMS and statutory health insurance frameworks. |
Methodological Framework
Initial hypotheses were tested against primary input from hospital purchasing committee members, biomedical engineers, GPO contracts managers, and vascular sonographers and refined through secondary validation against FDA 510(k) filings, EMA MDR submission databases, hospital procurement records, and CMS Medicare reimbursement code updates. Bottom-up segmentation modeling across product type, technology tier, end-user channel, and application area was triangulated against top-down market sizing from manufacturer revenue disclosures and regional health expenditure data.
Demand-supply-balance framing anchored the forecast framework, with procedure volume projections for cardiovascular screening and clinical research applications cross-referenced against installed base capacity and replacement cycles across the analysis window. Segmentation dimensions modeled include hardware modality, algorithm integration level, purchasing authority concentration, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted adoption curves and reimbursement code expansion timelines, incorporating PMDA localization delays and AI validation dataset requirements as industry-specific forecast inputs.
Stress conditions across hospital capital expenditure volatility, algorithm regulatory rejection rates, and semiconductor supply disruptions were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about reimbursement code adoption velocity and screening mandate enforcement intensity. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Clinical Trinocular Microscopes Market
Medical Devices
Robotic Biopsy Devices Market
Medical Devices
Cardiac Implants Market
Medical Devices
Global Pessary Market
Medical Devices
Middle East and Africa Orthotic Devices Market
Medical Devices
Germany Contraceptive Devices Market
Medical Devices
Laser Resurfacing Market
Medical Devices
Europe Breast Pumps Market
Medical Devices
External Defibrillator Market
Medical Devices
Global Cataract Surgery Devices Market
Medical Devices
Occlusion Microcatheter Market
Medical Devices
Cervical Retractors Market
Medical Devices
United Kingdom Spinal Surgery Devices Market
Medical Devices
South Korea Aesthetic Devices Market
Medical Devices
Global Intraoral Cameras Market
Medical Devices
Organ Transport Devices Market