
 Asia-Pacific Integrated Operating Room System Market | 2026-2036
Asia-Pacific Integrated Operating Room System Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Integrated Operating Room System Market Outlook
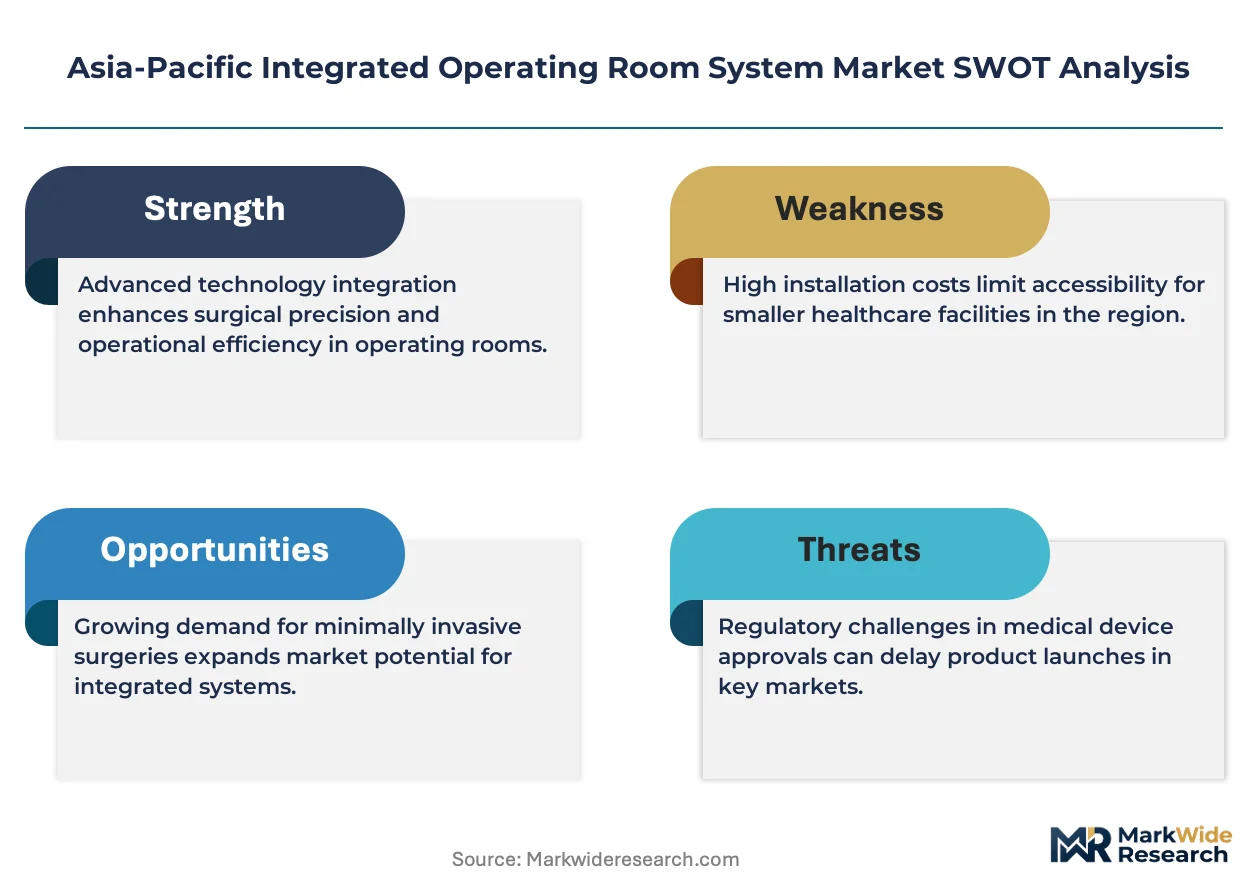
Modular system bundling is repositioning procurement decisions across the Asia-Pacific Integrated Operating Room System Market. Siemens Healthineers leverages its imaging-to-integration pipeline to anchor large hospital contracts in Japan and South Korea. GE Healthcare sustains competitive pressure through deep R&D investment in digital imaging architectures. Philips Healthcare differentiates via video integration ecosystems that unify surgical displays with real-time patient data streams.
An integrated operating room system combines surgical lights, tables, display systems, and video integration hardware with centralized control software to orchestrate multiple devices during procedures. LED surgical lights dominate product type demand due to energy efficiency and color rendering precision exceeding halogen predecessors. Robotics technology represents the fastest-expanding segment as hospitals invest in platforms enabling remote-assisted and precision-guided interventions. Hospitals remain the primary end user, though ambulatory surgery centers are gaining share as outpatient procedure volumes rise across Australia and Singapore.
Japan's PMDA, China's NMPA, and Australia's TGA collectively shape device approval pathways and interoperability standards across the region. These regulators enforce electromagnetic compatibility and cybersecurity protocols that extend development cycles but elevate barrier to entry for non-compliant suppliers. Stakeholders must monitor harmonization progress between national medical device databases to anticipate streamlined cross-border registration opportunities.
Market Dynamics
Japan's PMDA accelerated approval pathways for integrated OR platforms are compressing product registration timelines across the Asia-Pacific region, forcing competitors to restructure regional go-to-market operations around centralized regulatory hubs.
Growth Catalysts
- China's tertiary hospital construction:Public hospital expansion programs in provinces such as Guangdong and Sichuan are mandating integrated surgical infrastructure in new facilities, creating immediate procurement pipelines for OR system vendors.
- Robotics platform integration:Da Vinci and domestic surgical robot installations in South Korean university hospitals are requiring compatible video integration and centralized control architectures, pulling bundled OR system sales.
- Australia's TGA interoperability standards:Updated electromagnetic compatibility and cybersecurity protocols for connected medical devices are elevating compliance requirements that favor established integrated system suppliers over point-product vendors.
Market Restraints
- Semiconductor supply concentration:Taiwan-based foundry capacity constraints for high-resolution display controllers and FPGA chips are extending lead times for video integration hardware by 8-14 weeks.
- Japan's JIS certification complexity:Surgical light and table manufacturers face redundant electromagnetic testing requirements under both PMDA medical device rules and METI industrial safety standards, inflating development costs.
- Halogen-to-LED transition completion:Replacement demand for surgical lighting is plateauing as China's top-tier hospitals finish infrastructure upgrades, narrowing the addressable market for standalone lighting vendors.
Strategic Opportunities
- Vietnam's underpenetrated provincial hospitals:Ho Chi Minh City and Hanoi medical device distributors report rising inquiries for modular OR configurations from second-tier cities previously reliant on refurbished equipment.
- Remote surgical assistance networks:5G-enabled telesurgery pilot programs in Singapore's National University Hospital are creating demand for video integration systems with sub-20 millisecond latency specifications.
- India's PLI scheme for medical electronics:Production-linked incentives for domestic manufacturing of high-value medical devices are attracting component suppliers to establish captive production near Bengaluru and Hyderabad clusters.
Industry Challenges
- Biomedical engineer shortages:Australia's TGA reports a 34% vacancy rate for OR system commissioning specialists, delaying hospital activation timelines and straining vendor field service teams.
- Legacy PACS integration complexity:Japanese hospitals running 2015-era picture archiving systems face data format incompatibilities with modern video integration platforms, requiring costly middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Integrated Operating Room System Market |
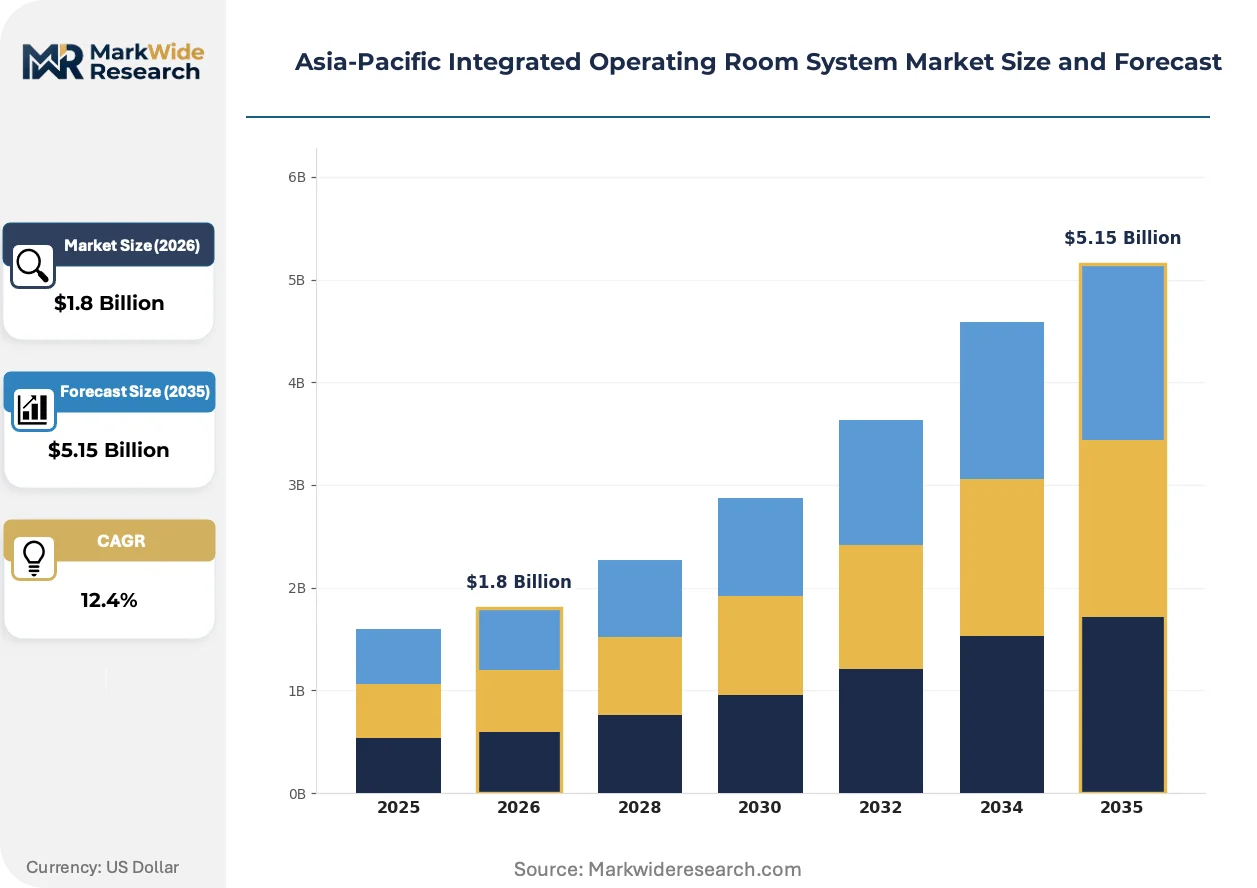
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $5.15 Billion |
| CAGR (2026 – 2036) | 12.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Surgical Lights, Surgical Tables, Display Systems, Video Integration Systems Technology: LED, OLED, Digital Imaging, Robotics End User: Hospitals, Ambulatory Surgery Centers, Surgical Clinics, Research Institutions Application: General Surgery, Orthopedic Surgery, Neurosurgery, Cardiovascular Surgery |
| Companies Covered | Siemens Healthineers, GE Healthcare, Philips Healthcare, Stryker Corporation, Medtronic, Johnson & Johnson, Olympus Corporation, Fujifilm Holdings Corporation, Getinge AB, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Integrated Operating Room System Market Strategic Shifts
Digital twin technology and AI-assisted surgical planning are restructuring how Asia-Pacific hospitals evaluate integrated OR investments, shifting procurement criteria from hardware specifications to ecosystem interoperability and data liquidity.
LED surgical lighting with spectral tunability is overtaking fixed-spectrum installations in Japan's cancer centers and South Korea's cardiovascular institutes, enabling procedure-specific illumination profiles that reduce surgeon eye strain and tissue recognition errors during lengthy interventions.
China's NMPA revised cybersecurity guidelines for connected medical devices now mandate encrypted data transmission and localized storage for patient video streams, compelling OR system vendors to rearchitect cloud-dependent platforms for on-premise deployment or risk registration rejection.
Hospital procurement committees in Singapore and Australia are unbundling after-sales service contracts from initial capital purchases, creating standalone multi-vendor maintenance agreements that fragment supplier revenue streams and intensify competition on technical support response metrics.
Asia-Pacific Integrated Operating Room System Market Segmentation
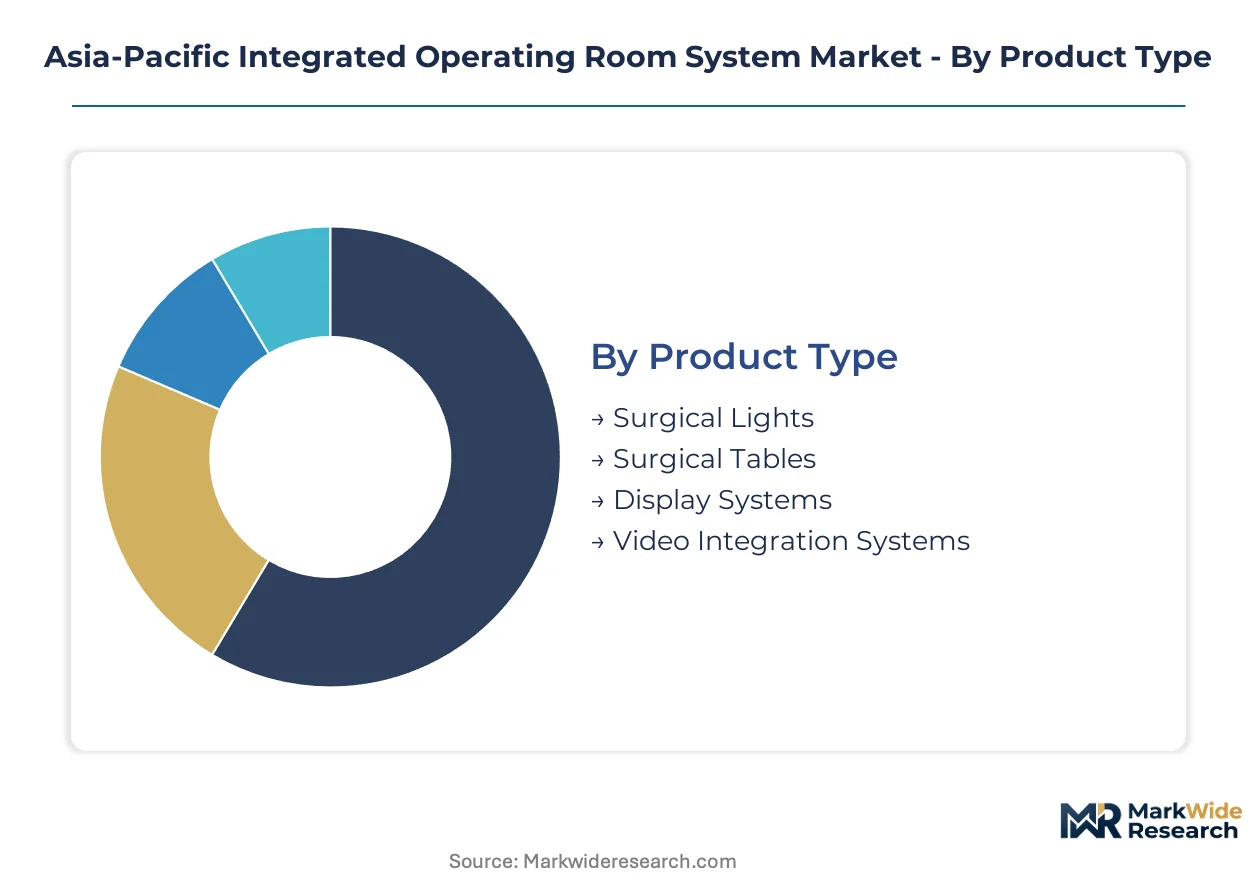
Integrated OR system procurement in the Asia-Pacific region fragments across hardware specifications, surgical applications, and facility tiers. Vendors must align product configurations with divergent infrastructure maturity across Japan's tertiary centers and Vietnam's provincial hospitals.
Product Type:
LED spectral tunability and 4K video distribution architectures are redefining capital allocation priorities for hospital procurement committees.
- Surgical Lights:LED platforms with CRI exceeding 95 now dominate new installations across Japan's cancer centers. China's top-tier hospitals have largely completed halogen-to-LED conversions, shifting demand toward spectral-tunable units for procedure-specific illumination profiles.
- Video Integration Systems:Centralized control software orchestrating multiple surgical displays represents the highest-margin hardware category. South Korean university hospitals installing Da Vinci platforms are mandating compatible video architectures, pulling bundled system sales.
- Surgical Tables:Motorized positioning systems with load capacities exceeding 450kg serve bariatric and orthopedic procedures. Australia's TGA electromagnetic compatibility requirements extend development cycles for table-integrated electronics.
- Display Systems:4K and 8K surgical monitors with near-zero latency specifications anchor telesurgery pilot programs in Singapore's National University Hospital.
Mature deployment sits with Surgical Lights. Newer deployment is concentrated in Video Integration Systems.
Technology:
Cost tier stratification separates premium robotics platforms from commoditized LED lighting infrastructure.
- LED:Energy efficiency gains exceeding 60% versus halogen predecessors drive replacement cycles across China's public hospital construction programs. Color rendering precision reduces tissue recognition errors during lengthy cardiovascular interventions.
- Robotics:Remote-assisted surgical platforms require sub-20 millisecond latency video integration and centralized device control. China's NMPA cybersecurity guidelines mandate encrypted data transmission and localized storage for patient video streams, compelling architecture redesigns.
- Digital Imaging:Real-time patient data streams unified with surgical displays differentiate Philips Healthcare's ecosystem approach in Australia and Singapore.
- OLED:Premium display technology with self-illuminating pixels serves niche applications in Japan's ophthalmic surgery suites where contrast precision is critical.
Volume concentration rests with LED. Margin expansion is climbing the fastest in Robotics.
End User:
Customer type determines service contract structures and technical support response requirements.
- Hospitals:Tertiary care centers in Guangdong and Sichuan provinces mandate integrated surgical infrastructure in new facilities. Japan's PMDA accelerated approval pathways compress procurement timelines for large hospital contracts.
- Ambulatory Surgery Centers:Outpatient procedure volumes rise across Australia and Singapore, driving demand for compact OR configurations with streamlined commissioning requirements.
- Surgical Clinics:Private specialty facilities in Ho Chi Minh City and Hanoi report rising inquiries for modular systems previously reliant on refurbished equipment.
- Research Institutions:Academic medical centers in South Korea require platforms enabling precision-guided interventions and surgical training simulations.
Capital deployment dominates in Hospitals. Capacity expansion is gaining share fastest in Ambulatory Surgery Centers.
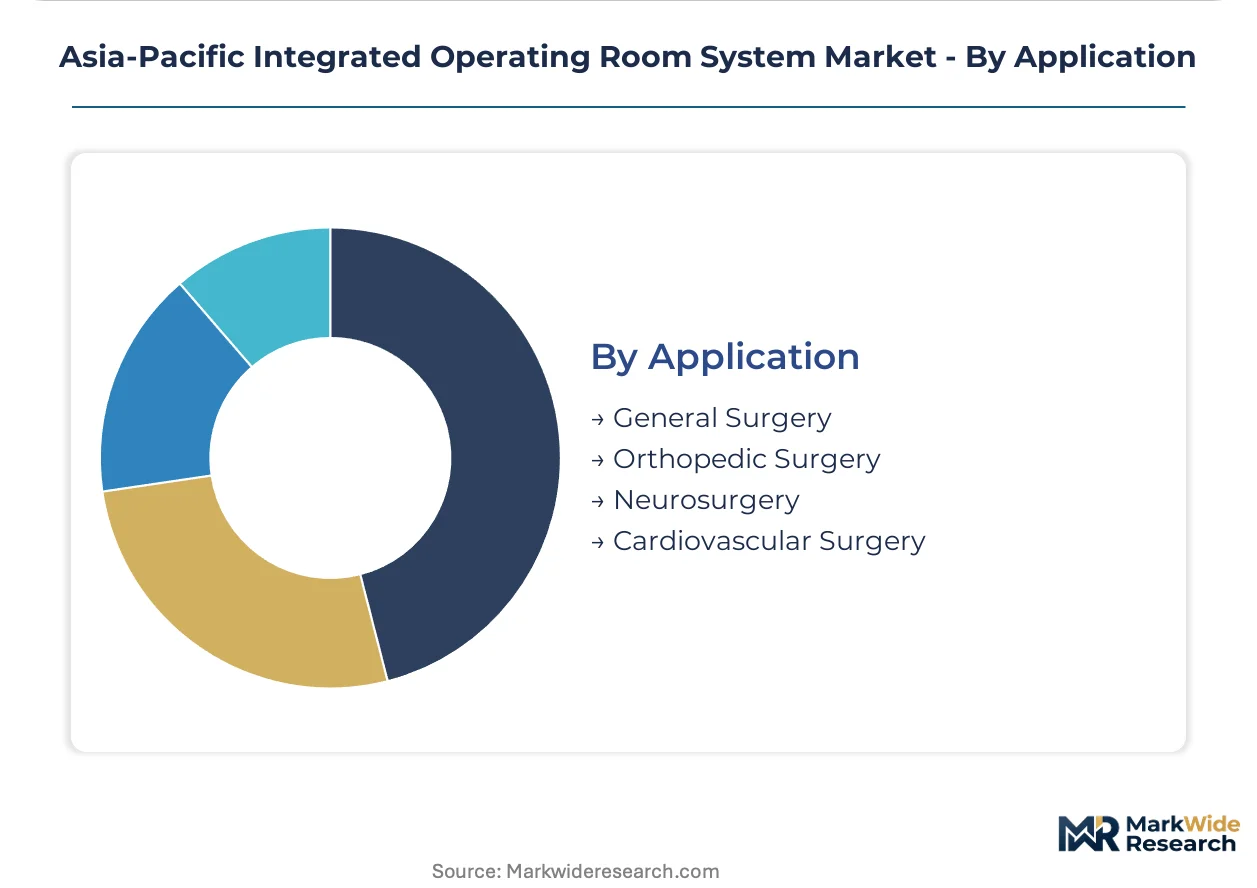
Application:
Procedure complexity dictates integration depth and device interoperability requirements.
- General Surgery:High-volume procedures across China's provincial hospitals prioritize cost-efficient modular configurations over fully integrated platforms.
- Cardiovascular Surgery:Lengthy interventions in Japan's cardiovascular institutes demand spectral-tunable LED lighting to reduce surgeon eye strain and fatigue-related errors.
- Neurosurgery:Precision requirements drive adoption of robotics platforms with real-time imaging fusion and navigation capabilities.
- Orthopedic Surgery:Motorized table positioning and high-definition arthroscopic video integration serve joint replacement volumes in Australia's aging demographic.
Procedure volume concentrates in General Surgery. Technology intensity is expanding most quickly in Neurosurgery.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of integrated OR system components concentrates in Japan and South Korea, while consumption demand spreads across China's hospital construction pipeline and Southeast Asia's upgrade cycles. This geographic mismatch creates supply chain coordination challenges for vendors managing cross-border installation and service logistics.
China
Provincial hospital construction in Guangdong and Sichuan mandates integrated surgical infrastructure in new tertiary facilities. NMPA cybersecurity guidelines now require encrypted data transmission and localized storage for patient video streams. Shanghai and Beijing medical device distributors report accelerating procurement timelines for bundled OR configurations.
Japan
Cancer centers and cardiovascular institutes drive replacement demand for spectral-tunable LED surgical lighting. PMDA accelerated approval pathways compress product registration timelines for integrated OR platforms. Tokyo and Osaka hospital networks anchor large-scale contracts for imaging-to-integration system bundles.
South Korea
University hospitals installing Da Vinci platforms require compatible video integration and centralized control architectures. MFDS enforces electromagnetic compatibility protocols that extend development cycles for table-integrated electronics. Seoul Capital Area medical centers concentrate robotics platform procurement and precision-guided intervention investments.
Australia
Ambulatory surgery centers gain share as outpatient procedure volumes rise across Sydney and Melbourne metropolitan areas. TGA interoperability standards elevate compliance requirements for connected medical devices. New South Wales and Victoria report 34% vacancy rates for OR system commissioning specialists, straining vendor field service capacity.
Vietnam
Provincial hospitals in second-tier cities shift from refurbished equipment to modular OR configurations. The national pharmaceutical regulator enforces medical device registration requirements that favor established suppliers with regional service networks. Ho Chi Minh City and Hanoi medical device distributors report rising inquiries for compact surgical infrastructure.
Asia-Pacific Integrated Operating Room System Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across the Asia-Pacific Integrated Operating Room System Market. Siemens Healthineers, GE Healthcare, and Philips Healthcare anchor the consolidated top tier through imaging-to-integration pipelines and deep R&D investment. Mid-tier vendors concentrate on point-product excellence in surgical lighting or video distribution. Competitive moves center on strategic partnerships with robotics platform manufacturers and geographic expansion into Vietnam's underpenetrated provincial markets.
Among diversified healthcare conglomerates, Siemens Healthineers and GE Healthcare occupy positions defined by vertical integration from imaging hardware through control software. Philips Healthcare exemplifies the ecosystem-focused archetype through video integration platforms that unify surgical displays with real-time patient data streams. Stryker Corporation represents the surgical infrastructure pure-play model, anchoring competitive positioning around motorized table systems and integrated lighting architectures. These three archetypes structure procurement committee evaluations across Japan's tertiary centers and China's public hospital construction programs.
| Leading Market Players |
|---|
| Siemens Healthineers |
| GE Healthcare |
| Philips Healthcare |
| Stryker Corporation |
| Medtronic |
| Johnson & Johnson |
| Olympus Corporation |
| Fujifilm Holdings Corporation |
| Getinge AB |
| Others |
Value Chain & Pricing Dynamics
Family-owned mid-cap lighting specialists across Taiwan and South Korea anchor component supply for LED surgical modules, their concentrated ownership patterns reinforcing pricing discipline through long-term foundry relationships rather than spot-market sourcing. This supply structure permits premium-tier vendors to maintain margin buffers against semiconductor volatility while forcing economy-tier assemblers into cost-down negotiations with Chinese display controller distributors.
Pricing Analysis
Margin tightening in economy-tier OR configurations traces to NMPA cybersecurity compliance costs that Chinese assemblers must absorb without brand premium offset. Three-tier pricing structure across premium, standard, and economy levels separates Siemens-Philips-GE bundled ecosystems from mid-tier video integrators and unbranded component suppliers. Price differentiation rests on CE-MDR certification tier and after-sales service bundling. Public hospital procurement committees in Guangdong demonstrate highest price sensitivity, while Japan's cancer centers prioritize spectral-tunable LED specifications over unit cost.
Supply Chain Analysis
Freight cost escalation from Taiwan-based FPGA foundries to Japanese OEM assembly plants is reshaping regional inventory positioning, with vendors holding 8-10 week safety stocks near Yokohama and Busan. Component supply concentrates in Taiwan, South Korea, and Japan for high-resolution display controllers, surgical-grade LEDs, and motorized table actuators. Raw material dependencies span gallium nitride substrates, medical-grade aluminum alloys, and fluoropolymer cable sheathing. Single-source vulnerability sits with Taiwan semiconductor foundry capacity. Distribution runs through hospital GPO contracts in Australia and direct-to-facility commissioning in Vietnam's provincial markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a consolidation play where NMPA cybersecurity mandates and PMDA accelerated approval pathways are forcing undercapitalized component vendors toward acquisition or exit.
For Market Incumbents: Anticipate margin compression from domestic Chinese robotics platforms requiring compatible video architectures by deepening backward integration into LED driver semiconductor sourcing. Secure JIS certification pre-approval for spectral-tunable lighting modules before METI revises industrial safety standards. Channel control through exclusive biomedical engineer training programs in Sydney and Melbourne defends service contract renewal rates against emerging Korean entrants. For New Entrants and Emerging Players: The premium-to-economy price gap in Vietnam's provincial hospital segment permits modular OR configuration entry without imaging-to-integration ecosystem investment. Target Ho Chi Minh City distributors serving second-tier cities previously dependent on refurbished halogen installations. Telesurgery-ready video integration with sub-20 millisecond latency specifications offers the most penetrable application wedge in Singapore's 5G pilot programs. For Investors and Strategic Acquirers: Distressed-cycle entries favor surgical lighting pure-plays with JIS-PMDA dual certification stranded by semiconductor working capital constraints in Japan's Kansai region. Long-term viability over a decade horizon hinges on robotics platform compatibility rather than standalone LED replacement cycles. Watch MFDS electromagnetic compatibility enforcement intensity as the inflection signal for Korean university hospital procurement acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Anchor contracts with Guangdong provincial construction programs secure multi-year bundled OR system deployment pipelines. |
| CE Marking Pathway | Accelerates Australian TGA mutual recognition and unlocks Singapore private hospital procurement committee access. |
| Software Companion Development | AI-assisted surgical planning modules differentiate Philips Healthcare's video integration ecosystem in Japan's cancer centers. |
| Backward Integration | Captive LED driver production near Seoul insulates against Taiwan foundry lead time volatility for Korean university hospital contracts. |
| Reimbursement Strategy | Alignment with Australia's MBS schedule for telesurgery procedures accelerates 5G-enabled OR system adoption in Sydney metropolitan networks. |
Study Parameters
Document review covered NMPA cybersecurity guideline filings, PMDA accelerated approval pathway records, and Australian TGA interoperability standards, complemented by interviews with hospital procurement committee chairs, biomedical engineering directors, and medical device distributor principals across Ho Chi Minh City, Shanghai, and Sydney. Secondary validation drew from hospital construction program announcements, GPO contract databases, and semiconductor trade flow data. Bottom-up installation forecasts triangulated against top-down tertiary care capacity expansion targets.
Cross-referencing historical procurement cycle patterns with panel input from OR system commissioning specialists shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, technology tier, end-user facility class, and surgical application complexity. CAGRs derived from weighted average of facility construction pipelines and replacement cycle assumptions. Industry-specific inputs incorporated Da Vinci platform installation trajectories and 5G telesurgery pilot program expansion timelines.
Underlying measurement precision varies by segment; LED surgical lighting carries tighter precision than emerging robotics platform integration due to mature installation databases. Forecasts reflect assumptions about regulatory harmonization progress and semiconductor supply normalization. Stakeholders should weight assumptions against their own operating context and regional procurement committee composition.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Intrauterine Contraceptive Devices (IUD) Market
Medical Devices
Digital Slit Lamp Market
Medical Devices
Vaginal Specula Market
Medical Devices
Global Laparoscopic and Open Hernia Mesh Repair Surgery Market
Medical Devices
Bone Conduction Hearing Devices Market
Medical Devices
Japan Contraceptive Devices Market
Medical Devices
Nitinol-Based Guide Wire Market
Medical Devices
Spinal Non-Fusion Technologies Market
Medical Devices
Home Sleep Apnea Testing Devices Market
Medical Devices
United States Aesthetic Devices Market
Medical Devices
Cardioscope Market
Medical Devices
Embolization Plugs Market
Medical Devices
Middle East and Africa Medical Devices Market
Medical Devices
Global Thermoelectric Devices in Medical and Laboratory Offering Market
Medical Devices
Americas Wearable Medical Device Market
Medical Devices
Cholesterol Monitors Market